
 Die-Cutter Market | 2026-2036
Die-Cutter Market Size, Share, and Industry Trends Forecast 2026-2036
Die-Cutter Market Outlook
Buyer concentration across the packaging supply chain is broadening as mid-sized corrugated converters and specialty label producers gain purchasing power alongside established multinational converters. BOBST leverages its rotary die-cutter installed base to sustain aftermarket service revenues across Europe. Heidelberger Druckmaschinen AG anchors its position through precision flat-bed engineering for folding carton applications. Masterwork Machinery Co., Ltd. competes on cost-optimized mechanical configurations for emerging Asian converter networks.
A die-cutter is a machine that uses hardened steel cutting dies or laser beams to sever sheet-fed substrates—paper, corrugated board, film, or textile—into precise shapes at speeds reaching thousands of impressions per hour, serving primary functions in packaging production, commercial printing finishing, and industrial material conversion. Rotary die-cutters occupy the highest volume tier in corrugated board processing due to continuous web compatibility and throughput economics, while digital die-cutting segments are expanding fastest among short-run label and prototype packaging workflows where tooling elimination compresses job changeover intervals. Hydraulic technology retains dominance in heavy-gauge embossing and tipping applications where tonnage consistency protects material integrity.
OSHA machine guarding standards in the United States, CE marking requirements under the EU Machinery Directive, and China's GB standards enforced by SAMR collectively dictate safety interlock specifications and electromagnetic compatibility thresholds for die-cutter imports and domestic sales. India's BIS certification mandates for industrial machinery are tightening market access conditions for non-compliant equipment suppliers. Stakeholders must monitor regulatory divergence between carbon-intensive hydraulic systems and electrified alternatives as energy efficiency standards harden across major manufacturing jurisdictions.
Market Dynamics
Automation investments across corrugated converter networks are compressing job changeover intervals and forcing equipment suppliers to embed predictive maintenance architectures into standard machine configurations.
Growth Catalysts
- E-commerce corrugated packaging:Direct-to-consumer fulfillment networks in the United States and China are pulling high-speed rotary systems into mid-sized converter facilities previously served by manual blanking operations.
- EU Machinery Directive CE marking:Harmonized safety interlock specifications are enabling cross-border equipment resale and reducing certification duplication costs for manufacturers exporting across European Union member states.
- Laser die-cutting:Tooling elimination for short-run label workflows is expanding addressable volume into prototype packaging and personalized SKU production.
Market Restraints
- Hardened steel die supply concentration:Specialty tool steel sourcing from German and Japanese metallurgical suppliers creates input cost volatility and extended lead times during alloy allocation cycles.
- Hydraulic system energy intensity:Carbon-intensive hydraulic power units face escalating compliance costs under China's dual carbon goals and EU F-Gas Regulation phase-down schedules.
- Digital substitution in prototyping:Inkjet-based direct-to-shape printing for mock-up validation is displacing physical die-cut samples in early-stage packaging development workflows.
Strategic Opportunities
- India BIS certification pathway:Industrial machinery safety mandates under Bureau of Indian Standards are creating first-mover advantage for compliant suppliers as domestic converter automation accelerates.
- Converged servo-electronic and vision systems:Real-time registration correction and automated die wear detection are opening premium pricing tiers in pharmaceutical folding carton applications.
- Aftermarket service unbundling:Remote diagnostics subscriptions and predictive spare parts logistics represent recurring revenue streams separate from initial equipment sales.
Industry Challenges
- Mechatronics technician scarcity:Servo drive programming and precision mechanical alignment skills are in short supply across converter maintenance departments in Germany and the United States.
- Legacy PLC integration complexity:Retrofitting Industry 4.0 data architectures into 1990s-era flat-bed die-cutter control systems requires custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Die-Cutter Market |
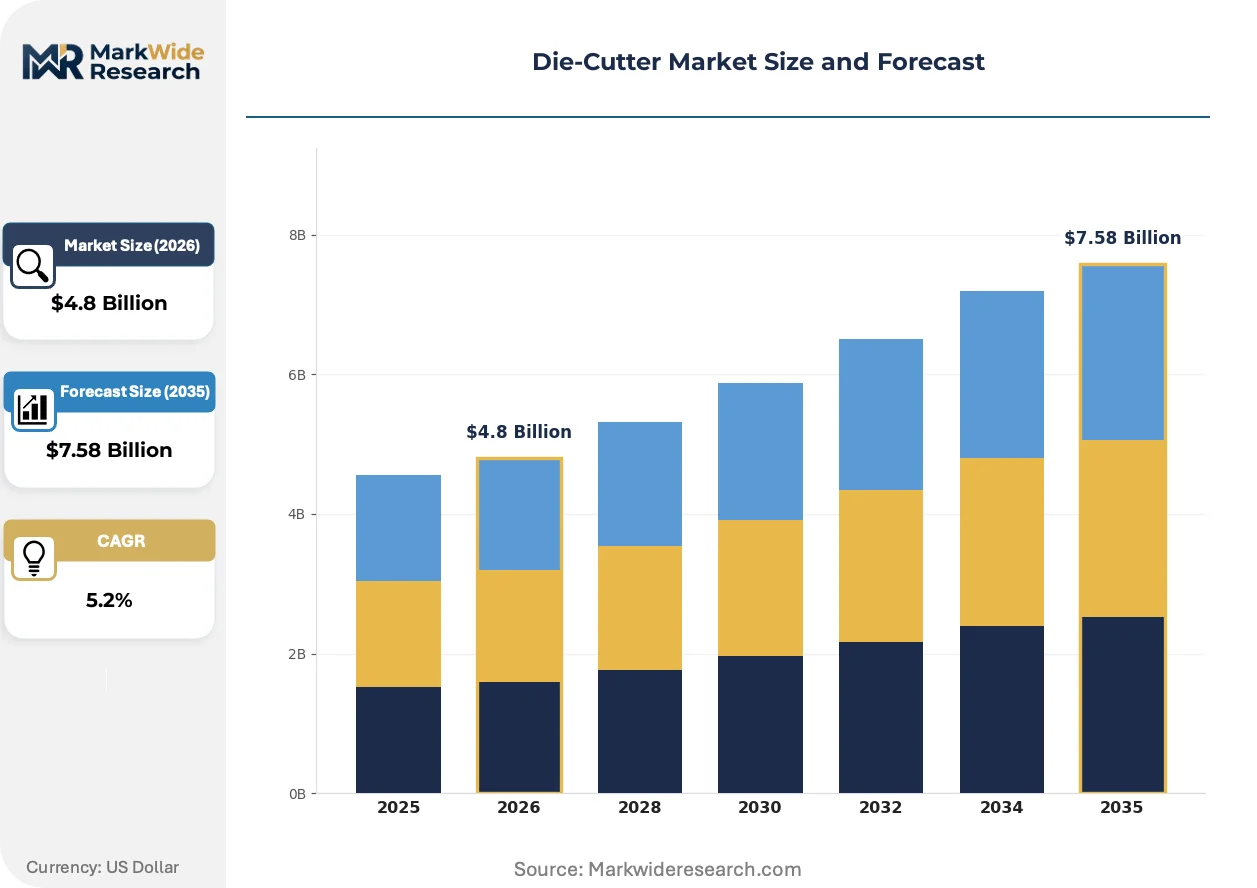
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.58 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Bed, Rotary, Digital, Laser Technology: Mechanical, Hydraulic, Pneumatic, Electrical End User: Packaging, Textile, Automotive, Electronics Application: Labeling, Cardboard, Embossing, Tipping |
| Companies Covered | Heidelberger Druckmaschinen AG, BOBST, Komori Corporation, Koenig & Bauer AG, Masterwork Machinery Co., Ltd., SANWA Co., Ltd., Duplo International, Yawa Printing Machinery Co., Ltd., Hunkeler AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Die-Cutter Market Strategic Shifts
Equipment architectures are converging around data-enabled uptime guarantees and energy recovery systems that reshape competitive differentiation beyond mechanical throughput specifications.
Servo-electronic press drives are integrating regenerative braking modules that return deceleration energy to facility power grids. Folding carton converters in Germany and Switzerland are adopting these configurations to meet corporate science-based emissions targets. The technology is integrating energy consumption monitoring into standard equipment quotations, compressing price competition toward total cost of ownership metrics rather than capital expenditure alone.
China's GB standards enforced by SAMR are tightening electromagnetic compatibility thresholds for imported die-cutting equipment. Manufacturers must redesign control cabinet shielding and motor cable routing to satisfy updated testing protocols. Packaging machinery importers are responding by establishing pre-shipment certification laboratories in Shanghai to accelerate customs clearance timelines.
Converter procurement departments are consolidating vendor relationships around full-lifecycle service agreements that bundle maintenance, spare parts, and productivity consulting. This behavior is displacing transactional equipment purchasing in mid-sized corrugated networks across the United States. The shift is most visible among e-commerce packaging specialists seeking guaranteed uptime commitments during peak seasonal fulfillment windows.
Die-Cutter Market Segmentation
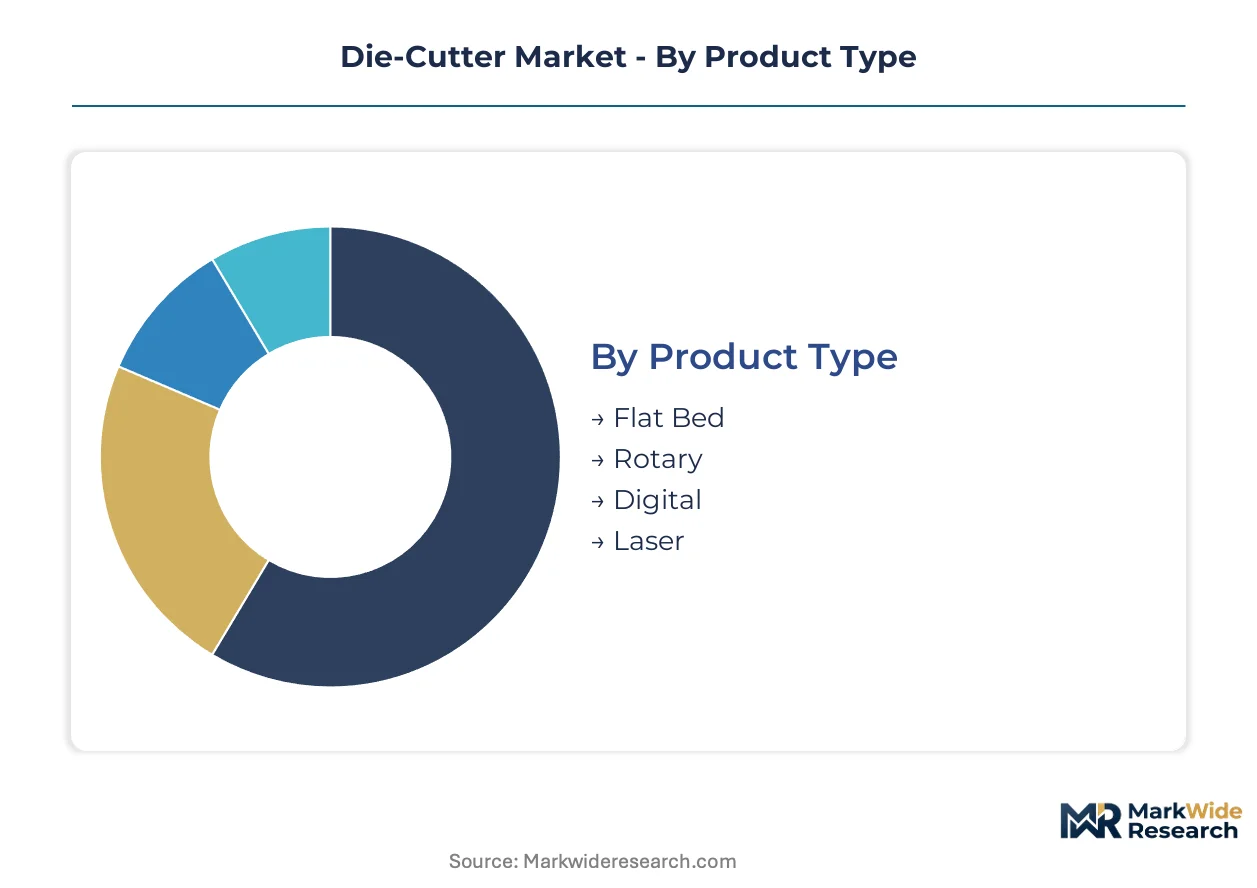
Die-cutter procurement patterns diverge sharply across substrate thickness, production volume, and tooling flexibility requirements. Equipment specifications that dominate corrugated fulfillment networks differ materially from those serving pharmaceutical label workflows or automotive gasket production.
Product Type:
Standardization dominates high-volume corrugated installations while customization pressures mount in short-run packaging and prototyping segments.
- Flat Bed:Rigid platen configuration delivers precise kiss-cutting for folding carton and thick board applications. Demand concentrates in Germany and Switzerland where pharmaceutical packaging converters prioritize registration accuracy over raw speed.
- Rotary:Continuous web processing enables throughput economics unmatched by intermittent formats. E-commerce corrugated specialists in the United States and China are pulling these systems into mid-tier converter facilities previously served by manual blanking.
- Digital:Tooling elimination compresses job changeover to minutes for prototype validation and personalized SKU production.
- Laser:Beam-based severing handles delicate films and non-woven textiles without mechanical die wear.
Most installed capacity flows through Rotary systems. Expansion is steepest in Digital configurations.
Technology:
Energy intensity and tonnage consistency define the cost-performance trade-offs across power transmission architectures.
- Mechanical:Crank-driven flywheel systems offer capital efficiency and maintenance simplicity for stable, long-run production. Asian converter networks favor these configurations for cost-optimized entry-level installations.
- Hydraulic:Fluid power units maintain uniform pressure across irregular substrates and deep embossing operations. Heavy-gauge tipping applications in European luxury packaging rely on hydraulic tonnage consistency despite escalating compliance costs under EU F-Gas Regulation phase-down schedules.
- Pneumatic:Compressed air actuation serves light-duty kiss-cutting and perforation tasks with minimal infrastructure requirements.
- Electrical:Servo-electronic drives with regenerative braking return deceleration energy to facility grids, satisfying corporate emissions targets in Swiss and German folding carton operations.
Mechanical systems retain the largest installed base. Electrical configurations are gaining share fastest among sustainability-mandated procurement.
End User:
End-use specifications range from food-contact compliance in packaging to dimensional tolerances in electronics lamination.
- Packaging:Corrugated, folding carton, and flexible film conversion represent the dominant demand pool. E-commerce fulfillment networks in the United States and China are accelerating automation investments across mid-sized converter tiers.
- Textile:Non-woven and technical fabric cutting requires blade or laser configurations that minimize fiber fraying. Automotive interior suppliers in Germany specify rotary systems for seat and insulation material processing.
- Automotive:Gasket, shim, and acoustic damping material production demands thickness consistency across high-strength elastomers.
- Electronics:Flexible circuit and display film severing requires micron-level registration precision and clean-edge quality.
Packaging absorbs the majority of annual equipment shipments. Electronics applications are expanding most quickly as display manufacturing concentrates in East Asian clusters.
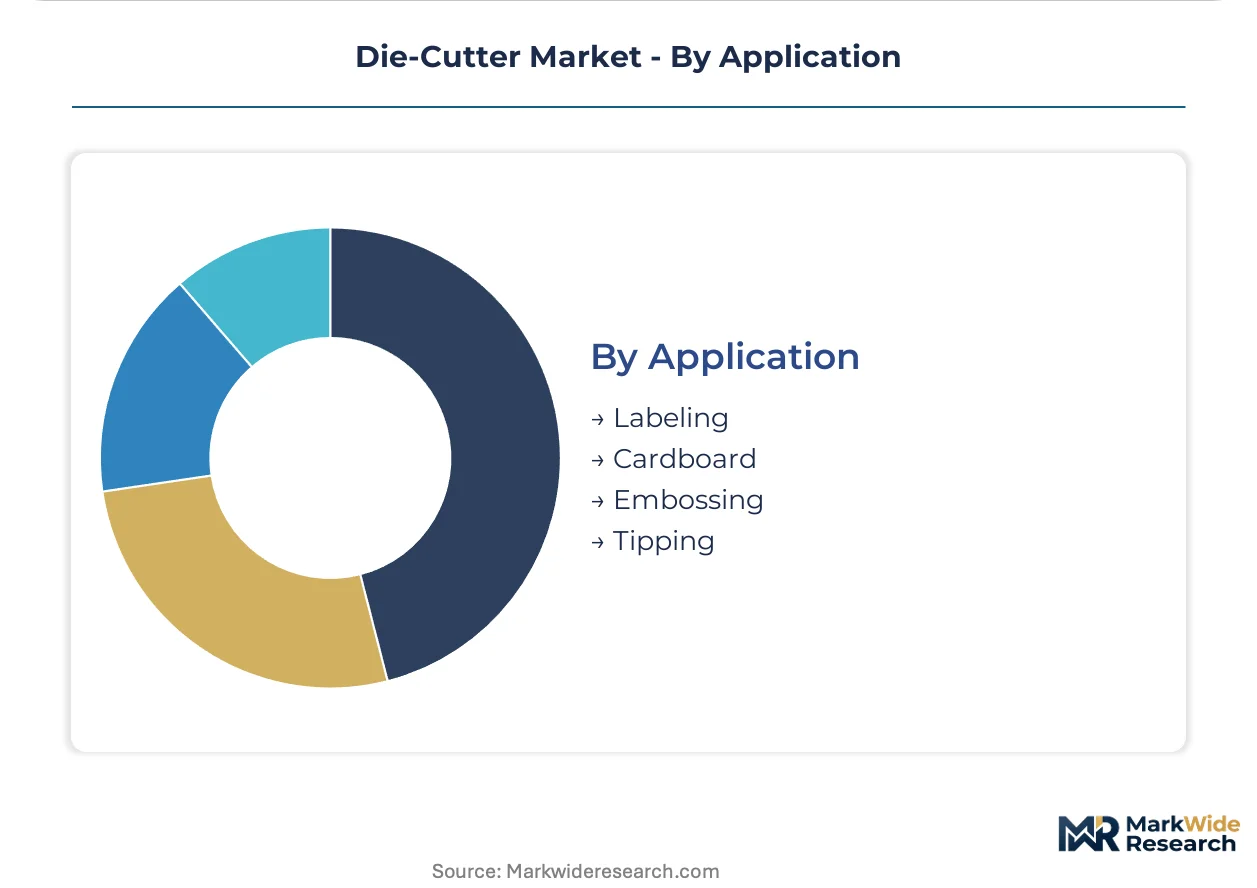
Application:
Functional requirements span surface decoration, structural forming, and adhesive assembly preparation.
- Labeling:Pressure-sensitive and shrink-sleeve label production favors rotary or digital formats for rapid job changeover. Pharmaceutical serialization mandates in the United States and EU are driving investment in vision-integrated die-cutting lines.
- Cardboard:Corrugated board blanking and creasing for box and display production. High-speed rotary systems dominate volume throughput for e-commerce shipping containers.
- Embossing:Raised surface texture creation for premium folding carton and luxury packaging applications.
- Tipping:Cigarette and specialty filter rod wrapping paper cutting requires precision alignment with high-speed packing lines.
Cardboard processing commands the greatest installed equipment base. Labeling applications are climbing the fastest as SKU proliferation accelerates across consumer goods.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German folding carton converters prioritize registration precision while Chinese e-commerce networks drive rotary system volume, revealing how regional industrial specialization shapes equipment procurement patterns.
United States
Direct-to-consumer fulfillment networks pull high-speed rotary die-cutters into mid-sized corrugated converter facilities previously served by manual blanking operations. OSHA machine guarding standards dictate safety interlock specifications for domestic sales and imports. Converter automation investments concentrate in the Midwest and Southeast, where seasonal peak fulfillment windows demand guaranteed uptime commitments.
Germany
Pharmaceutical packaging converters prioritize flat-bed systems delivering kiss-cutting accuracy for folding carton applications. CE marking requirements under the EU Machinery Directive enable cross-border equipment resale across member states. Industrial clusters in Baden-Württemberg and Bavaria anchor precision engineering demand, with servo-electronic drives integrating regenerative braking to meet corporate science-based emissions targets.
China
E-commerce corrugated packaging specialists accelerate automation investments across mid-tier converter networks. GB standards enforced by SAMR tighten electromagnetic compatibility thresholds for imported equipment, forcing redesign of control cabinet shielding and motor cable routing. Manufacturing concentration in the Yangtze River Delta and Pearl River Delta drives cost-optimized mechanical configurations for emerging converter networks.
India
Domestic converter automation accelerates as mid-sized facilities gain purchasing power alongside established multinational operators. BIS certification mandates for industrial machinery tighten market access conditions for non-compliant equipment suppliers. Industrial corridors in Maharashtra and Gujarat attract first-mover suppliers establishing pre-shipment certification partnerships to accelerate customs clearance timelines.
Switzerland
Luxury packaging applications rely on hydraulic tonnage consistency for heavy-gauge embossing despite escalating compliance costs. Corporate emissions targets drive adoption of servo-electronic configurations with energy recovery systems. Precision manufacturing clusters around Zurich and Basel prioritize total cost of ownership metrics over capital expenditure alone in equipment procurement decisions.
Die-Cutter Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the die-cutter market, creating a tiered structure where scale-driven aftermarket service networks coexist with cost-optimized mechanical engineering. The vendor base spans Swiss precision engineering conglomerates, Japanese printing machinery specialists, and Chinese fabrication networks. Three archetypes dominate: diversified printing machinery groups with rotary installed bases, flat-bed precision engineering specialists, and emerging Asian cost-optimized fabricators. Competitive moves concentrate on predictive maintenance service unbundling and converged servo-electronic vision system development.
Among diversified printing machinery groups, BOBST and Heidelberger Druckmaschinen AG exemplify archetypes anchored in rotary installed base leverage and flat-bed precision engineering respectively. Masterwork Machinery Co., Ltd. occupies a position within the cost-optimized fabrication tier serving emerging Asian converter networks. These three entities represent the strategic positioning spectrum from aftermarket service revenue sustainment through precision registration accuracy to capital-efficient mechanical configuration.
| Leading Market Players |
|---|
| Heidelberger Druckmaschinen AG |
| BOBST |
| Komori Corporation |
| Koenig & Bauer AG |
| Masterwork Machinery Co., Ltd. |
| SANWA Co., Ltd. |
| Duplo International |
| Yawa Printing Machinery Co., Ltd. |
| Hunkeler AG |
| Others |
Value Chain & Pricing Dynamics
Mechatronics technician scarcity in Baden-Württemberg and Bavaria widens labor-cost differentials between German precision engineering clusters and Asian fabrication networks, compressing pricing-tier spreads as servo-electronic configurations command premiums against cost-optimized mechanical alternatives.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for entry-level rotary die-cutters. Three-tier pricing structure across premium, standard, and economy levels stratifies by CE marking compliance and predictive maintenance bundling. Pricing pressure stems from digital substitution in prototyping workflows. Mid-sized corrugated converters exhibit highest price sensitivity, while pharmaceutical packaging specialists prioritize registration accuracy over capital expenditure.
Supply Chain Analysis
CE marking and BIS certification gating restricts market access for non-compliant equipment suppliers, forcing pre-shipment laboratory investments. Specialty tool steel sourcing draws from German and Japanese metallurgical suppliers, while servo drive manufacturing rests on Taiwanese and South Korean electronics clusters. Single-source vulnerability concentrates in hardened steel die supply. Distribution runs through OEM-direct channels for large converters and machinery distributors for mid-tier networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The die-cutter market reads as a late-cycle quality story where pharmaceutical serialization mandates and corporate emissions targets are redirecting procurement toward servo-electronic precision and energy recovery systems.
For Market Incumbents: Acquire predictive maintenance software capabilities to unbundle aftermarket service revenues from equipment sales. Defend against Asian cost-optimized fabricators by embedding vision-integrated registration systems into standard pharmaceutical folding carton configurations. Certification investment in India's BIS pathway secures first-mover positioning as domestic converter automation accelerates. For New Entrants and Emerging Players: Launch via remote diagnostics subscription models targeting mid-sized e-commerce corrugated converters in India's Maharashtra and Gujarat corridors. White-space exists in converged servo-electronic and vision systems for pharmaceutical applications. Underpenetrated segments include laser die-cutting for flexible electronics lamination in East Asian display manufacturing clusters. For Investors and Strategic Acquirers: Diversified printing machinery groups are the most active acquirer in this space, seeking aftermarket service network scale. Long-term viability hinges on recurring revenue streams decoupled from capital expenditure cycles. Target acquisition archetype: pure-play predictive maintenance platforms with established converter relationships. Monitor e-commerce fulfillment network automation announcements as inflection indicator for rotary system demand.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Acquisition | Captures recurring revenue streams beyond initial equipment sales in converter networks. |
| CE Marking Pre-Certification Laboratory Investment | Accelerates customs clearance for imported equipment under SAMR-enforced GB standards. |
| Servo-Electronic Regenerative Braking Integration | Satisfies corporate science-based emissions targets in Swiss and German pharmaceutical packaging. |
| India BIS Certification Partnership | Establishes compliant supply position ahead of accelerating domestic converter automation. |
| Vision-Integrated Registration System Development | Opens premium pricing tiers for pharmaceutical serialization mandates in US and EU markets. |
Study Parameters
Direct dialogue with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads across corrugated converter networks and pharmaceutical packaging operations grounded qualitative findings. Secondary validation drew from SEC filings of listed machinery manufacturers, EU Machinery Directive documentation, SAMR GB standard publications, and trade customs data for die-cutting equipment imports. Bottom-up equipment shipment estimates triangulated against top-down converter automation investment surveys.
Segment-level outputs across the projection horizon reflect modeled interactions between substrate thickness requirements, production volume tiers, and tooling flexibility specifications. CAGRs derived from regression analysis against e-commerce fulfillment network expansion, regulatory compliance cost trajectories, and energy efficiency standard adoption curves. Industry-specific inputs included servo-electronic drive penetration rates and predictive maintenance subscription attach rates.
Several conditions sit outside the modeled scope, including abrupt tariff reconfigurations affecting German-Japanese tool steel supply corridors and unanticipated digital printing substitutions in corrugated prototyping workflows. Forecasts reflect documented assumptions regarding converter automation timelines and emissions regulation enforcement intensity. A model refresh is warranted upon material change in EU F-Gas Regulation phase-down schedules or China's dual carbon goal implementation pace.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Nitrogen Filling Systems Market
Packaging Equipment
Airless Pumps Market
Packaging Equipment
Global Cap Applicators Market
Packaging Equipment
Hydrapulper Market
Packaging Equipment
Powder Filling Equipment Market
Packaging Equipment
Powder Dispenser Market
Packaging Equipment
Loading Spout Market
Packaging Equipment
Bottle-Capping Equipment Market
Packaging Equipment
Bespoke Dispenser Market
Packaging Equipment
Strapping and Banding Equipment Market
Packaging Equipment
Table Top Band Sealer Market
Packaging Equipment
Dispensing Booth Market
Packaging Equipment
Skin Packaging Equipment Market
Packaging Equipment
Can Seamers Market
Packaging Equipment
Dispensing Sprayers Market
Packaging Equipment
Global Reverse Vending Machine Market