
 Packaging Tensioner Market | 2026-2036
Packaging Tensioner Market Size, Share, and Industry Trends Forecast 2026-2036
Packaging Tensioner Market Analytics
REACH compliance is repositioning material sourcing and surface treatment costs for European suppliers. FROMM Packaging Systems leverages its Swiss engineering heritage to sustain premium positioning in automated strapping systems. Samuel Strapping Systems anchors North American distribution through extensive dealer networks and steel strapping specialization. Mosca GmbH dominates the German home market with integrated strapping head and tensioner technology.
A packaging tensioner is a mechanical or electromechanical device that applies calibrated force to strapping bands, typically achieving tension ranges from 500 to 5,000 Newtons depending on band material and width, to secure palletized goods, corrugated bundles, or individual packages for transport and storage. The device engages with polypropylene, polyester, or steel strapping through gripping wheels, feed mechanisms, and sealing systems to create uniform load containment. Electric tensioners command the widest margin pools in high-volume beverage and food operations where line speed consistency justifies capital investment. Battery-powered tensioners represent the fastest-expanding category as warehouse operators eliminate pneumatic infrastructure and gain portability across dock and floor operations. Manual tensioners remain entrenched in small-batch consumer goods and pharmaceutical packaging where low throughput and frequent changeovers limit automation returns.
EMA guidelines on medical device packaging integrity and FDA quality system regulations for pharmaceutical distribution shape validation requirements for tensioner equipment in healthcare supply chains. OSHA ergonomic standards in the United States and EU machinery safety directives under CE marking constrain manual tensioner designs and accelerate electric substitution in repetitive-use environments. Stakeholders must monitor how carbon border adjustments and extended producer responsibility frameworks alter total cost of ownership calculations across material and power source categories.
Market Dynamics
Automated packaging line integration is displacing manual strapping operations across food and beverage distribution centers, compressing equipment replacement cycles and elevating electric tensioner specifications as the default procurement standard.
Growth Catalysts
- EU F-Gas Regulation:Phase-down mandates for fluorinated greenhouse gases are accelerating warehouse electrification, pushing pneumatic infrastructure replacement with battery-powered tensioner systems in cold-chain logistics facilities.
- Food industry automation:High-volume beverage bottlers and prepared meal distributors are consolidating strapping operations into continuous-motion packaging lines that demand precision tension control and sealed cycle consistency.
- German precision engineering clusters:Stuttgart and Munich manufacturing corridors sustain premium equipment procurement through export-oriented automotive parts and machinery logistics hubs requiring validated load containment.
Market Restraints
- Lithium-ion cell supply concentration:Battery-powered tensioner production depends on cylindrical cell supply chains concentrated in East Asian manufacturing zones, exposing European assemblers to input volatility and extended lead times.
- Steel strapping price volatility:Cold-rolled steel input costs fluctuate with energy-intensive European smelter operations, compressing margin pools for manual tensioner suppliers serving construction and heavy machinery sectors.
- REACH surface treatment compliance:Hexavalent chromium restrictions on corrosion-resistant coatings force reformulation of gripping wheel materials, extending qualification timelines for equipment destined for pharmaceutical packaging lines.
Strategic Opportunities
- India warehouse modernization:PLI scheme incentives for cold-chain infrastructure and organized retail distribution are creating first-mover advantages for electric tensioner suppliers establishing local assembly operations.
- Pharmaceutical serialization integration:EMA guidelines on medical device packaging integrity are elevating tensioner validation requirements, opening specification-driven procurement channels for equipment with integrated force monitoring and data logging.
- Retrofit cordless conversion kits:Battery-powered drive modules are converging with existing pneumatic tensioner chassis designs, enabling fleet conversion without full equipment replacement in North American third-party logistics operations.
Industry Challenges
- CE machinery safety directive certification:Revised guard interlock and emergency stop requirements for automated strapping heads are extending type-approval timelines and complicating multi-country product launches.
- Legacy ERP integration:Electric tensioner data outputs for line monitoring require custom middleware development to interface with decades-old manufacturing execution systems prevalent in mid-sized consumer goods plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaging Tensioner Market |
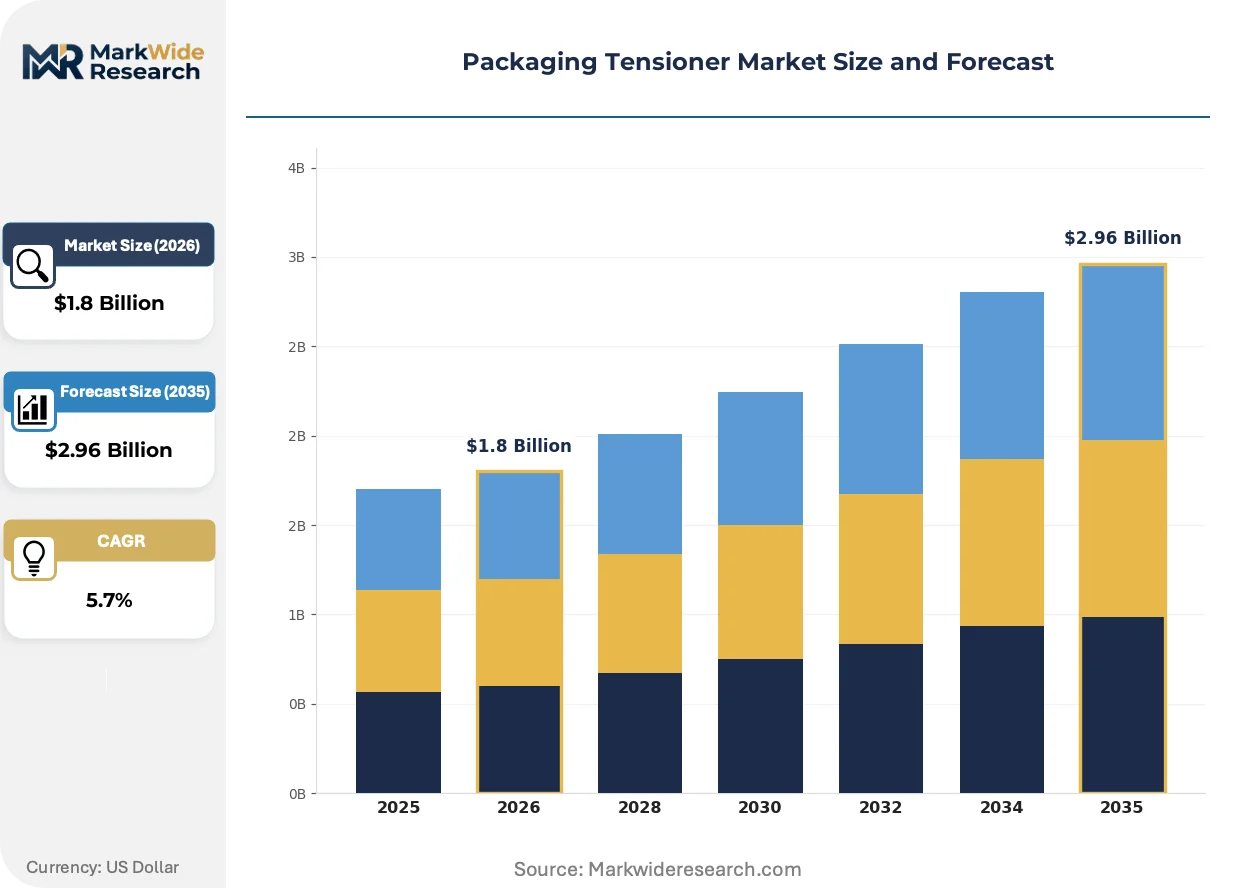
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
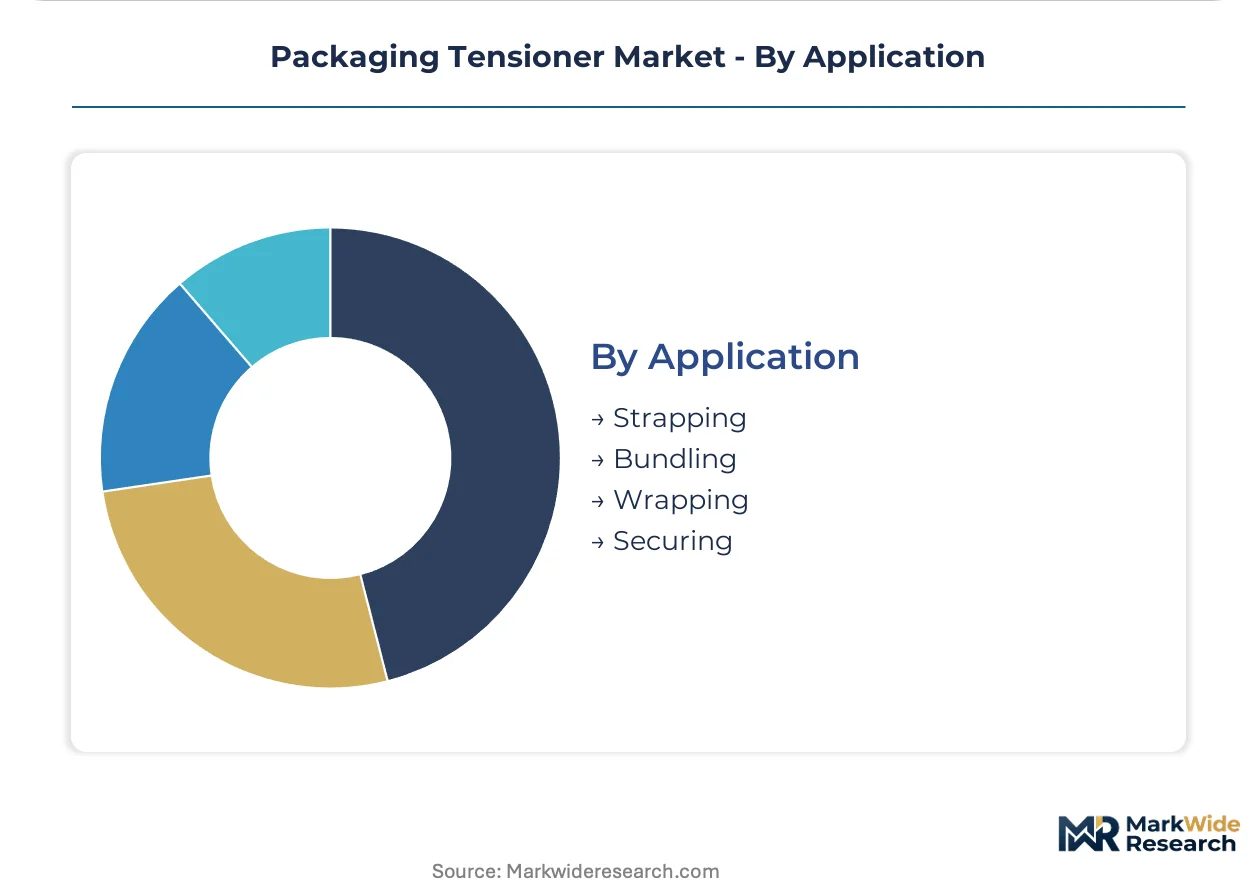
| Segmentation | Product Type: Manual Tensioners, Electric Tensioners, Pneumatic Tensioners, Battery-Powered Tensioners Material: Plastic, Steel, Aluminum, Composite End User: Food Industry, Beverage Industry, Consumer Goods, Pharmaceutical Application: Strapping, Bundling, Wrapping, Securing |
| Companies Covered | Signode Industrial Group, FROMM Packaging Systems, Samuel Strapping Systems, Dynaric, Inc., Mosca GmbH, Polychem Corporation, Orgapack, Strapex, Carolina Strapping and Buckles Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaging Tensioner Market Evolving Landscape
Digital force monitoring and predictive maintenance capabilities are repositioning tensioner equipment from commodity peripherals to data-integrated packaging line components, altering supplier value capture and buyer procurement evaluation criteria.
Brushless DC motor technology is converging with precision load cell feedback systems in next-generation electric tensioners, enabling real-time tension adjustment within 50-millisecond response windows. High-speed beverage canning operations in Germany and the Netherlands are adopting these systems to eliminate strap breakage on accelerated palletizing lines. The technology is converging with cloud-based equipment monitoring platforms, compressing maintenance intervals from calendar-based to condition-based service models.
REACH authorization requirements for cobalt compounds in battery cathodes are forcing European tensioner manufacturers to redesign power pack architectures around nickel-manganese alternatives. Industrial consequence includes extended qualification testing for cycle life and thermal stability in warehouse temperature extremes. Medical device packaging suppliers in Ireland and Switzerland are most affected, responding with accelerated supplier audits and dual-source battery procurement strategies.
Equipment-as-a-service contracting is displacing capital purchase models among North American third-party logistics operators managing seasonal volume volatility. The segment being disrupted is traditional distributor sales channels, replaced by manufacturer-direct fleet management agreements bundling hardware, maintenance, and consumables. This pattern is most visible in California and Texas e-commerce fulfillment hubs where strap consumption scales directly with shipment velocity.
Packaging Tensioner Market Segmentation
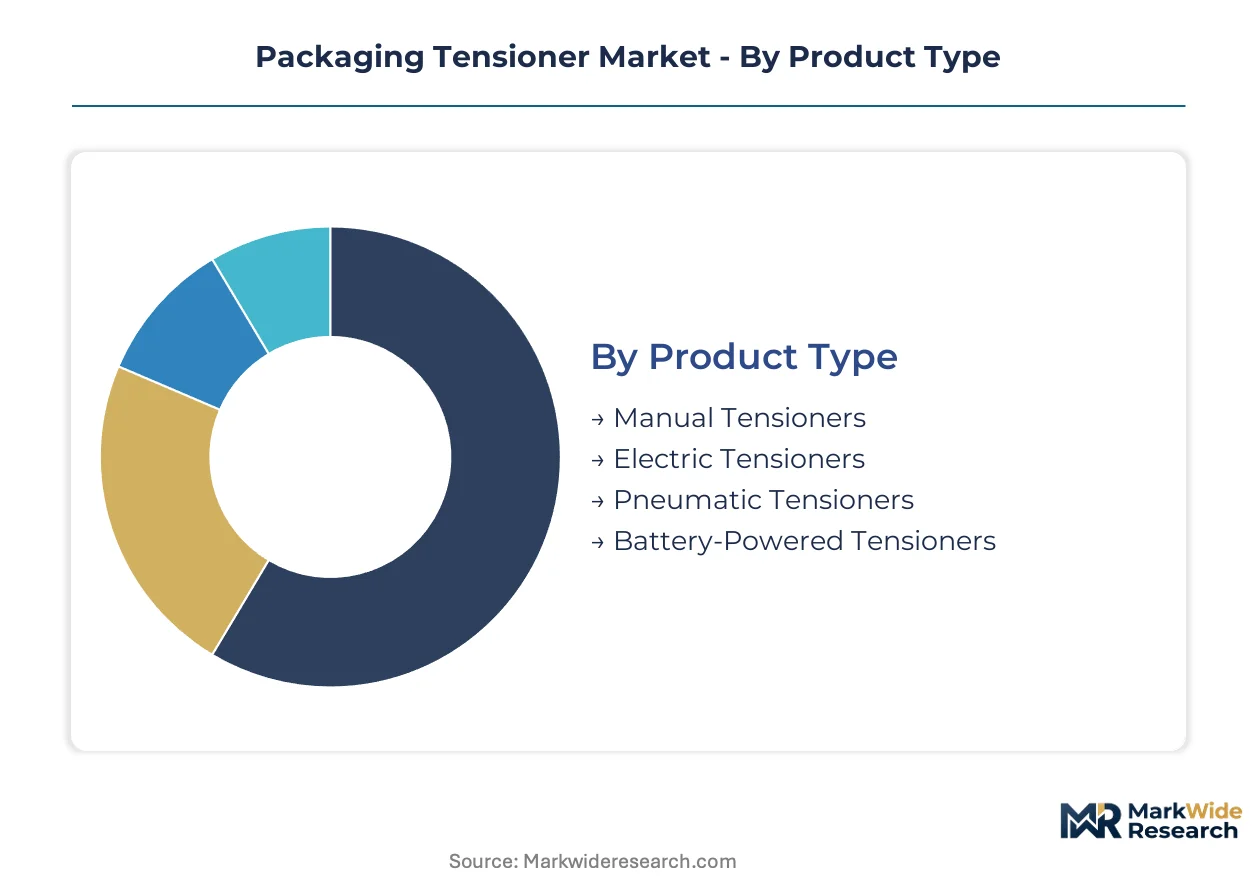
Segmentation in the packaging tensioner market reveals how power source selection, material compatibility, and end-use validation requirements reshape procurement patterns across automated and manual operations. Equipment specifications diverge sharply between high-volume beverage lines demanding sealed-cycle consistency and pharmaceutical packaging requiring force-documentation compliance.
Product Type:
Supply concentration in motor and battery cell manufacturing is tilting competitive advantage toward electrified tensioner categories while constraining pneumatic system availability in regulated environments.
- Electric Tensioners:Brushless DC motor systems with precision load cell feedback achieve real-time tension adjustment within 50-millisecond response windows. Demand concentrates in German and Dutch beverage canning operations where accelerated palletizing lines require sealed-cycle consistency and minimal strap breakage.
- Battery-Powered Tensioners:Lithium-ion cylindrical cell architectures eliminate pneumatic infrastructure dependency while enabling portability across dock and floor operations. Warehouse operators in California and Texas e-commerce fulfillment hubs are consolidating procurement around cordless fleets to manage seasonal volume volatility.
- Manual Tensioners:Ratchet and pawl mechanisms for low-throughput applications where capital constraints outweigh labor cost considerations.
- Pneumatic Tensioners:Compressed-air systems facing displacement in EU cold-chain logistics under F-Gas Regulation phase-down mandates for fluorinated greenhouse gases.
Electric tensioners absorb the bulk of installed capacity in high-volume automated lines; battery-powered tensioners are expanding most quickly as warehouse operators eliminate pneumatic infrastructure.
Material:
Raw material sourcing geography and REACH surface treatment compliance are repositioning cost structures and qualification timelines across corrosion-resistant gripping wheel production.
- Steel:Cold-rolled carbon and stainless grades dominate heavy machinery and construction sector strapping where ultimate tensile strength exceeds 1,000 Newtons. European smelter energy costs are compressing margin pools for manual tensioner suppliers serving these sectors.
- Plastic:Polypropylene and polyester bands capture high-volume food and consumer goods bundling where elasticity and cost efficiency outweigh metallic strength requirements.
- Aluminum:Lightweight corrosion-resistant strapping for aerospace components and export-sensitive cargo weight optimization.
- Composite:Fiber-reinforced polymer bands emerging in specialized pharmaceutical and medical device packaging requiring radiolucency and non-magnetic properties.
Steel maintains the largest installed base for heavy-load containment; composite materials are climbing the fastest as medical device packaging specifications tighten.
End User:
Regulatory validation requirements and line speed specifications are fragmenting procurement criteria across food safety, pharmaceutical integrity, and consumer goods throughput priorities.
- Food Industry:Automated packaging lines with continuous-motion strapping operations demanding precision tension control and stainless steel construction for washdown compliance. Prepared meal distributors and high-volume bottlers are consolidating equipment specifications around electric tensioner platforms.
- Pharmaceutical:EMA guidelines on medical device packaging integrity and FDA quality system regulations mandate force monitoring, data logging, and qualification documentation. Tensioner equipment requires integrated validation protocols for healthcare supply chain deployment.
- Beverage Industry:High-speed canning and bottling operations with accelerated palletizing lines requiring real-time tension adjustment to eliminate strap breakage.
- Consumer Goods:Mixed batch sizes and frequent changeovers limiting automation returns, sustaining manual tensioner entrenchment in mid-sized plants with legacy manufacturing execution systems.
Food industry applications command the largest equipment installed base; pharmaceutical end users are gaining share fastest as serialization and integrity requirements elevate specification-driven procurement.
Application:
Functional differentiation in force application methods is aligning equipment selection with load geometry, transport mode, and containment duration requirements.
- Strapping:Circumferential band tensioning around palletized units or corrugated bundles for unitized transport. German automotive parts logistics hubs require validated load containment specifications for export-oriented distribution.
- Bundling:Multi-unit compression of identical products into handling-efficient configurations for retail distribution and e-commerce fulfillment.
- Wrapping:Tensioned film or band application for weather protection and tamper evidence in extended outdoor storage scenarios.
- Securing:Point-specific tensioning for irregular geometries and mixed-load stabilization in intermodal container transport.
Strapping applications dominate equipment deployment by volume; bundling operations are expanding most quickly with organized retail and e-commerce distribution growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany, where precision engineering clusters and export-oriented logistics hubs sustain premium equipment procurement. Warehouse electrification mandates across the EU are accelerating battery-powered tensioner adoption in cold-chain facilities. Asian markets are modernizing distribution infrastructure, creating specification-driven procurement channels for automated strapping systems.
Germany
Stuttgart and Munich manufacturing corridors drive demand for validated load containment in automotive parts logistics. The F-Gas Regulation accelerates pneumatic infrastructure replacement with battery-powered systems in cold-chain warehouses. German precision engineering clusters sustain premium equipment procurement through export-oriented machinery distribution hubs requiring sealed-cycle consistency.
United States
California and Texas e-commerce fulfillment hubs consolidate procurement around cordless tensioner fleets for seasonal volume management. OSHA ergonomic standards accelerate electric substitution in repetitive-use warehouse environments. Midwest automotive parts distribution centers adopt precision tension control for validated export packaging.
China
Yangtze River Delta beverage bottlers integrate continuous-motion strapping lines demanding real-time tension adjustment. GB standards and dual carbon goals push warehouse operators toward electrified equipment. Pearl River Delta consumer goods manufacturers balance automation returns against legacy manufacturing execution system constraints.
India
Maharashtra and Gujarat organized retail distribution networks modernize cold-chain infrastructure under PLI scheme incentives. The country's national logistics regulator enforces packaging integrity standards for pharmaceutical exports. Karnataka warehouse clusters create first-mover advantages for electric tensioner suppliers establishing local assembly.
Netherlands
Randstad logistics hubs demand precision tension control for high-speed beverage canning operations. REACH compliance repositions material sourcing costs for European suppliers serving pharmaceutical packaging lines. Rotterdam port-centric distribution centers adopt battery-powered fleets to eliminate pneumatic infrastructure dependency.
Packaging Tensioner Market Competitive Landscape
German producers anchor the premium tier through precision engineering heritage; Swiss specialists hold specification-driven positions in pharmaceutical validation markets. The vendor base clusters around three strategic archetypes: integrated strapping system providers, component specialists focused on gripping wheel and feed mechanisms, and regional fabricators serving construction and heavy machinery sectors. Competitive moves center on equipment-as-a-service contracting models and retrofit cordless conversion kits for existing pneumatic fleets.
Within the integrated systems tier, FROMM Packaging Systems and Mosca GmbH exemplify European engineering-centric positioning. Samuel Strapping Systems occupies a position among North American distributors with steel strapping specialization. Signode Industrial Group anchors the scale-driven segment with broad industrial coverage across multiple material categories.
| Leading Market Players |
|---|
| Signode Industrial Group |
| FROMM Packaging Systems |
| Samuel Strapping Systems |
| Dynaric, Inc. |
| Mosca GmbH |
| Polychem Corporation |
| Orgapack |
| Strapex |
| Carolina Strapping and Buckles Company |
| Others |
Value Network & Pricing Analysis
Swiss precision engineering talent pools anchor premium-tier labor costs that widen the spread between battery-powered electric systems and entry-level manual equipment. German automation specialists command wage premiums that feed into sealed-cycle tensioner pricing, while East Asian battery cell manufacturing clusters compress cordless unit costs at the standard tier.
Pricing Analysis
Volume absorption concentrates in mid-tier battery-powered equipment where margin pools are narrowing fastest due to lithium-ion cell supply competition. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked pharmaceutical-grade systems from warehouse cordless fleets and construction-sector manual tools. Pricing pressure stems from REACH surface treatment compliance extending European supplier qualification timelines. Beverage bottlers show least price sensitivity given line-speed consistency requirements; small-batch consumer goods plants remain most cost-constrained.
Supply Chain Analysis
Refurbishment flows for pneumatic tensioner chassis into cordless conversion kits are extending equipment lifecycles and compressing new-unit demand in North American third-party logistics. Manufacturing concentrates in Germany, China, and Switzerland for precision components; battery cell supply draws from South Korea and Japan. Cold-rolled steel inputs and cobalt-based cathode materials face commodity volatility and regulatory substitution mandates. Single-source vulnerability runs through cylindrical cell supply chains concentrated in East Asian zones. Distribution runs through manufacturer-direct fleet management agreements displacing traditional dealer networks in California and Texas e-commerce hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints in lithium-ion cell qualification for warehouse temperature extremes are propping pricing power for validated battery architectures. Capacity bottlenecks at European surface treatment facilities extend lead times for pharmaceutical-grade equipment.
For Market Incumbents: Cement premium positioning through backward integration into brushless DC motor production and captive supply of REACH-compliant gripping wheel coatings. FROMM Packaging Systems and Mosca GmbH demonstrate how Swiss and German engineering heritage defends margin pools against emerging Asian electric tensioner suppliers. CE machinery safety directive certification investments create switching costs for beverage industry buyers. For New Entrants and Emerging Players: Capture retrofit cordless conversion kit demand in North American pneumatic tensioner installed bases where full fleet replacement capital is constrained. India's PLI scheme cold-chain modernization offers the most penetrable geography for local assembly operations. Equipment-as-a-service contracting models bypass upfront capital barriers among seasonal third-party logistics operators. For Investors and Strategic Acquirers: Re-rating potential sits with precision load cell and force-monitoring technology specialists given pharmaceutical serialization integration requirements. Long-term viability favors targets with validated healthcare supply chain deployment records and dual-source battery procurement strategies. Monitor EMA guideline revisions on medical device packaging integrity for inflection signals in specification-driven procurement channels.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Architecture Redesign | REACH cobalt restrictions force nickel-manganese cathode pivots requiring extended thermal qualification. |
| Retrofit Cordless Conversion Kits | Pneumatic chassis reuse cuts capital barriers for warehouse fleet electrification in F-Gas regulated facilities. |
| Equipment-as-a-Service Contracting | Manufacturer-direct agreements bundle maintenance and consumables for seasonal e-commerce fulfillment operators. |
| Precision Load Cell Integration | Real-time tension adjustment meets German beverage canning line speed consistency requirements. |
| Local Assembly in India | Maharashtra and Gujarat PLI incentives create first-mover positioning for cold-chain infrastructure modernization. |
Research Methodology
Multi-period observation of battery cell supply lead times, REACH authorization timelines, and warehouse electrification capex flows anchored the trend analysis, supplemented by interviews with plant engineers at German beverage bottlers, maintenance directors at Texas e-commerce fulfillment hubs, procurement leads at pharmaceutical packaging suppliers, and aftermarket service heads at Swiss tensioner distributors. Secondary validation drew from ECHA substance restriction databases, EU F-Gas Regulation phase-down schedules, FDA quality system guidance documents, and customs trade data on strapping equipment imports. Bottom-up equipment shipment tallies and top-down industrial automation spending estimates were triangulated to constrain forecast variance.
Segment-weighting approaches applied differential growth assumptions across power source categories, material compatibility tiers, and end-use validation requirements. Power source segmentation—electric, battery-powered, manual, pneumatic—combined with end-use splits across food, pharmaceutical, beverage, and consumer goods shaped the analytical framework across the projection horizon. CAGRs were derived from installed base turnover rates and replacement cycle compression in automated packaging lines. Industry-specific inputs included F-Gas Regulation compliance deadlines and EMA medical device packaging integrity guideline implementation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to lithium-ion cell supply concentration, carbon border adjustment mechanisms, and extended producer responsibility framework implementation. Forecasts reflect documented assumptions on warehouse electrification capex trajectories and pharmaceutical serialization adoption curves. Practitioners should monitor EU battery regulation cell qualification requirements and cold-chain logistics PLI scheme disbursement rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
France Foam Pumps Market
Packaging Equipment
Powder Filling Equipment Market
Packaging Equipment
Retail Press Dispenser Pump Market
Packaging Equipment
Nitrogen Filling Systems Market
Packaging Equipment
Thermal Impulse Sealers Market
Packaging Equipment
Filling Equipment Market
Packaging Equipment
Packer Market
Packaging Equipment
Laser Coding Equipment Market
Packaging Equipment
Die-Cutter Market
Packaging Equipment
Skin Packaging Equipment Market
Packaging Equipment
Tray Loader Market
Packaging Equipment
Flexible End-Load Cartoner Market
Packaging Equipment
Global Reverse Vending Machine Market
Packaging Equipment
Single Use Mixer Market
Packaging Equipment
Vacuum Fillers Market
Packaging Equipment
Bag Re-Sealer Market