
 Packaging Equipment Market | 2026-2036
Packaging Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Packaging Equipment Market Analysis
Equipment leasing and pay-per-use financing is reconfiguring capital deployment for mid-sized processors that previously deferred automation investments. Krones AG leverages its integrated bottling and packaging lines to anchor large beverage contracts across Europe. Syntegon Technology GmbH specializes in pharmaceutical containment and aseptic systems, sustaining premium positioning in regulated environments. Coesia S.p.A. controls a diversified portfolio of specialty machinery brands, competing across multiple end-use verticals without single-category dependence.
Packaging equipment encompasses machinery engineered to form, fill, seal, label, and palletize containers with throughputs ranging from dozens to thousands of units per minute, depending on servo-driven precision and line synchronization architecture. Its primary commercial purpose is to preserve product integrity, extend shelf stability, and comply with serialized traceability mandates across supply chains. Automatic technology leads installed capacity but robotic systems represent the fastest-expanding segment as collaborative arms displace fixed automation in mixed-SKU environments. Flexible packaging equipment commands widening share as brand owners convert from rigid formats to reduce material intensity and shipping cube, though rigid systems still dominate margin pools in aseptic dairy and carbonated beverages.
The EU F-Gas Regulation and REACH compliance frameworks constrain refrigerant and coating choices in sealing systems sold across Europe, while FDA validation requirements govern pharmaceutical equipment destined for US markets. ISO 9001 and ISO 14001 certifications function as baseline qualification criteria for tenders from multinational food and beverage buyers, effectively filtering regional suppliers from global procurement lists. Stakeholders must monitor how Extended Producer Responsibility schemes in multiple jurisdictions reshape equipment specifications for recyclability and material recovery.
Market Dynamics
Automated packaging lines are reconfiguring capital allocation as food processors confront EU single-use plastics directives and serialized traceability mandates. Equipment suppliers must now engineer for material flexibility and regulatory compliance simultaneously.
Growth Catalysts
- EU Green Deal packaging rules:Mandatory recyclability targets are forcing brand owners to retrofit lines for paper-based and mono-material substrates, creating replacement demand across dairy and beverage plants.
- Pharmaceutical serialization:Track-and-trace mandates in regulated markets are driving investment in integrated vision systems and tamper-evident sealing equipment.
- German machinery clusters:Engineering concentration around Stuttgart and Munich supplies precision filling systems that set performance benchmarks for export markets.
Market Restraints
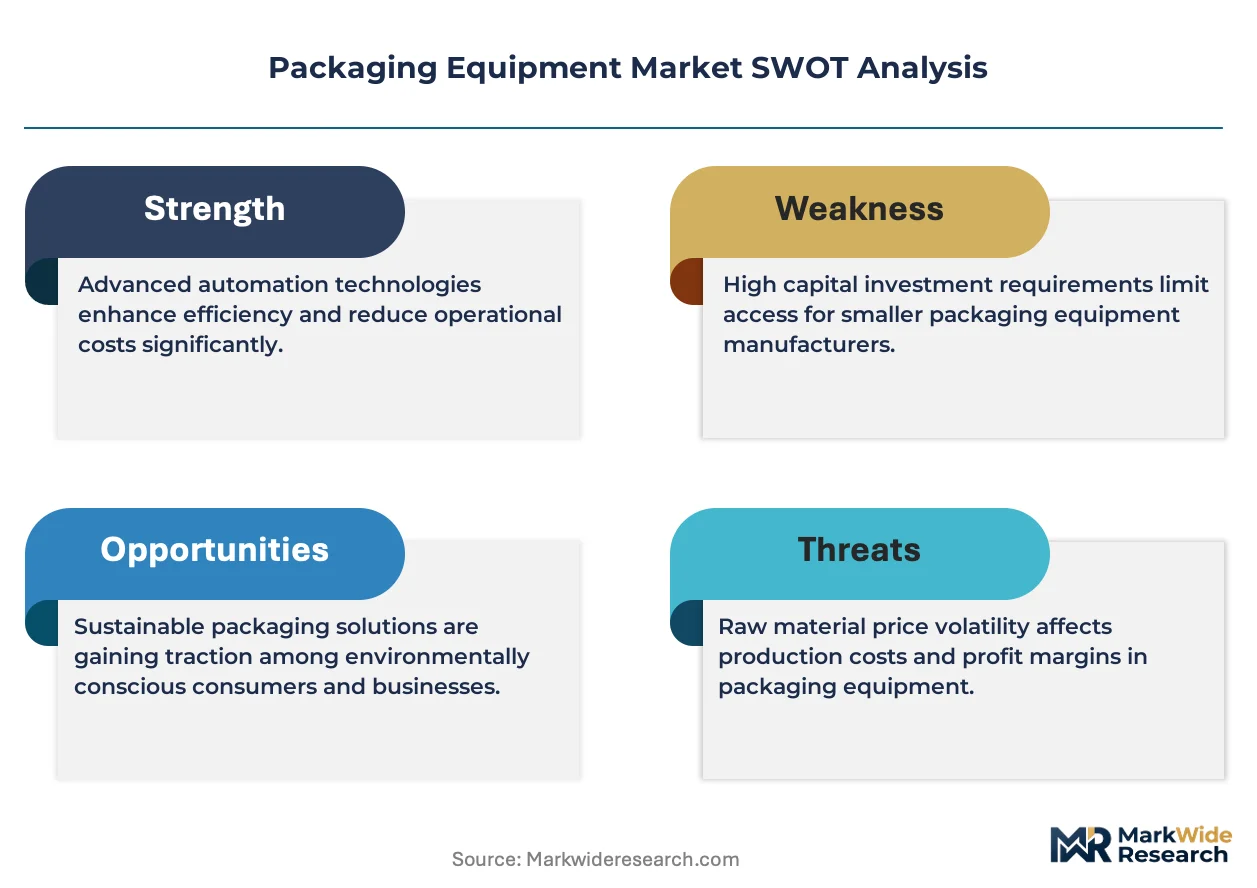
- Stainless steel price volatility:Equipment frames and contact surfaces depend on alloy grades whose commodity swings compress margin predictability for build-to-order manufacturers.
- Specialized servo motor supply:Precision motion control components concentrate with Japanese and German suppliers, exposing lead time risk for system integrators.
- F-Gas Regulation compliance costs:Sealing system refrigerant restrictions add engineering overhead for equipment sold across EU member states.
Strategic Opportunities
- India food processing expansion:Cold chain infrastructure investment under PLI schemes is creating first-time automation demand in dairy and ready-to-eat segments.
- Equipment-as-a-service models:Pay-per-output contracts reduce capital barriers for mid-sized processors in Southeast Asian markets.
- Digital twin convergence:Virtual commissioning tools are compressing installation timelines and enabling remote diagnostics for dispersed production networks.
Industry Challenges
- Mechatronics talent scarcity:Servo programming and line synchronization expertise pools thinly across OEM engineering departments.
- FDA validation timelines:Pharmaceutical equipment qualification protocols extend delivery cycles and tie up field service resources.
- Retrofit integration complexity:Legacy Allen-Bradley and Siemens control architectures resist seamless upgrade paths to IoT-enabled monitoring platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaging Equipment Market |
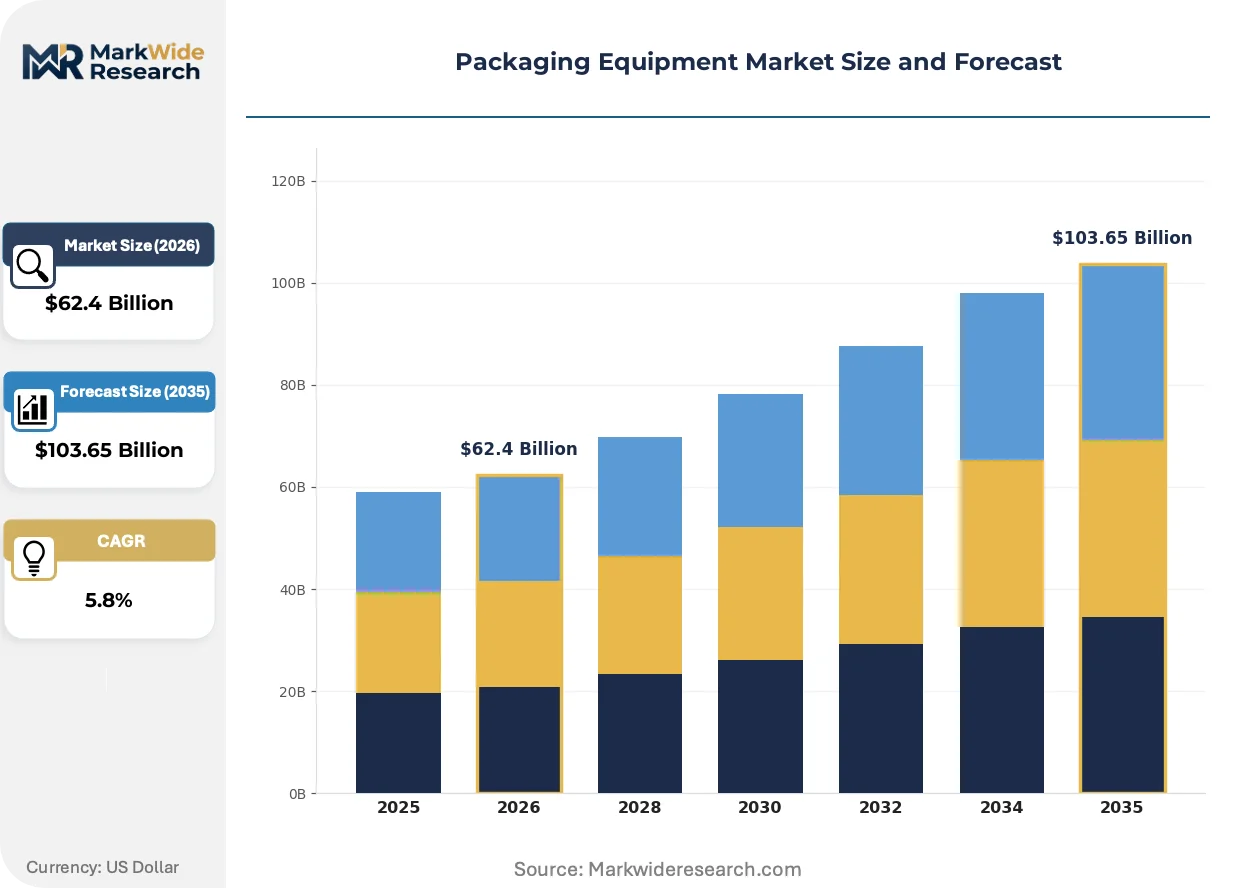
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $103.65 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Fillers, Horizontal Sealers, Case Packers, Labelers Technology: Automatic, Semi-Automatic, Manual, Robotic End User: Food & Beverage, Pharmaceuticals, Cosmetics, Electronics Packaging Type: Flexible, Rigid, Semi-Rigid, Others |
| Companies Covered | KHS Group, SIG Combibloc Group Ltd., Tetra Laval Group, Barry-Wehmiller Companies, Syntegon Technology GmbH, Krones AG, Coesia S.p.A., GEA Group Aktiengesellschaft, Sacmi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaging Equipment Market Emerging Trajectories
Packaging equipment architecture is pivoting from fixed automation toward adaptive systems that accommodate shorter production runs and material variability without mechanical changeover.
Collaborative robotic arms are hybridizing traditional fixed-automation lines by enabling mixed-SKU handling without dedicated tooling changeovers. Beverage co-packers and contract manufacturers are deploying these systems to absorb volatility in promotional packaging formats. The technology is hybridizing line economics by reducing minimum efficient scale thresholds for automated operation.
REACH chemical restrictions and EU F-Gas Regulation amendments are constraining adhesive and refrigerant selections in sealing equipment sold across member states. Manufacturers must now qualify alternative bonding chemistries and closed-loop cooling architectures. Pharmaceutical and aseptic dairy segments face the steepest reformulation burdens as they balance compliance against validation continuity.
Leasing structures and throughput-based contracting are displacing outright purchase for mid-capacity processors seeking to preserve balance sheet flexibility. Third-party equipment financiers and OEM captive finance arms are building subscription offerings that bundle maintenance and upgrade rights. This pattern concentrates in European and North American markets where capital discipline intersects with sustainability-driven line refresh cycles.
Packaging Equipment Market Segmentation
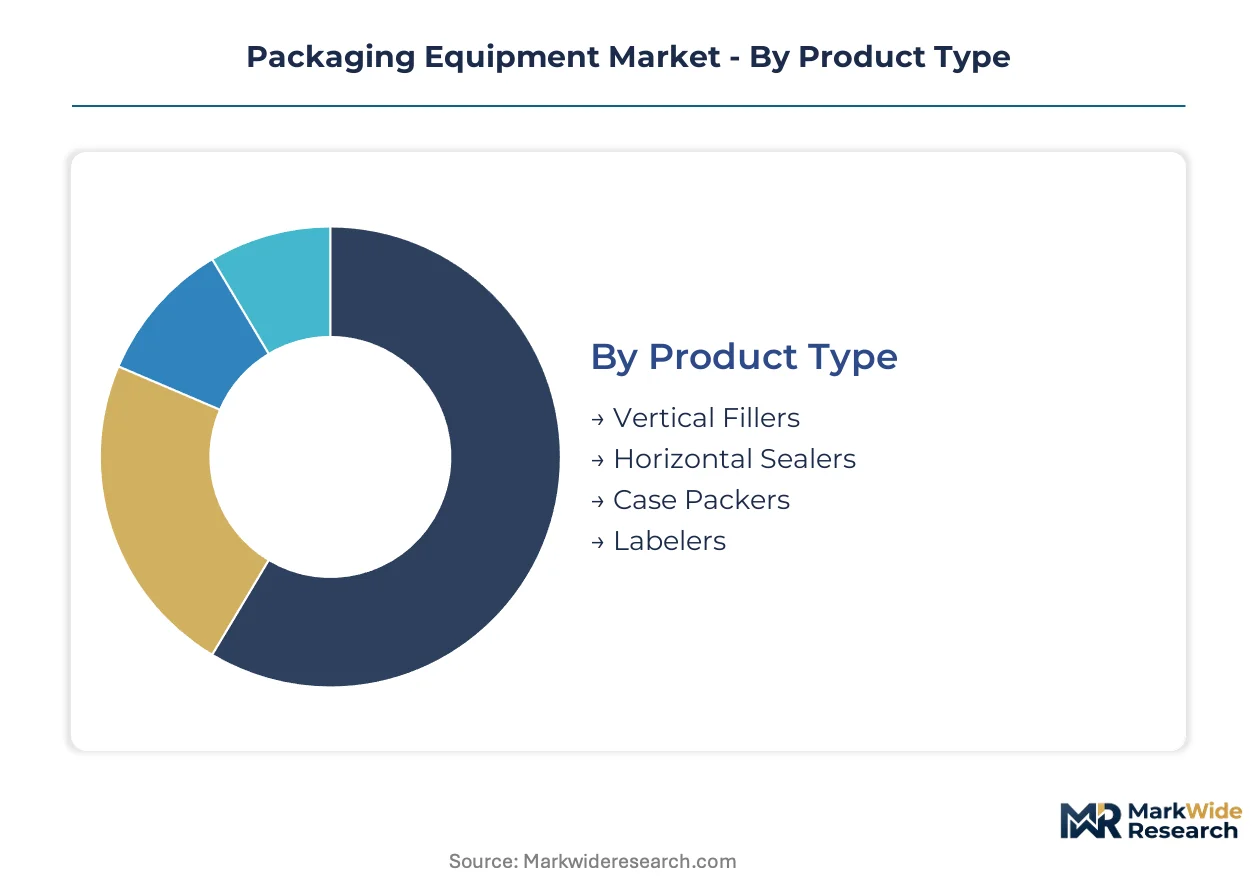
Packaging equipment segmentation reveals how capital deployment cycles vary dramatically across machine types and automation tiers. Equipment replacement timelines range from three-year refresh cycles for labelers to decade-long horizons for integrated bottling lines, creating distinct revenue recognition patterns for suppliers.
Product Type:
Cycle times diverge sharply across machine categories, with peripheral equipment turning over fastest and integrated systems anchoring decade-long capital planning horizons.
- Vertical Fillers:Gravity and auger-fed systems form, fill, and seal pouches and bags in continuous vertical motion. Dairy processors in Germany deploy these for milk powder and yogurt formats where hermetic seals govern shelf stability.
- Horizontal Sealers:Flow-wrap and thermoform systems process flat film stock into sealed trays and pillow packs. Ready-meal manufacturers in France favor horizontal formats for modified atmosphere packaging that extends chilled distribution windows.
- Case Packers:Robotic and mechanical systems erect corrugated containers and load finished goods for palletization. Beverage bottlers specify case packers with servo-driven changeover to accommodate promotional multi-packs without mechanical retooling.
- Labelers:Pressure-sensitive, sleeve, and glue-applied systems apply primary and secondary decoration. Craft beverage producers cycle through labeler upgrades fastest as SKU proliferation and regulatory mark-up requirements accelerate refresh timelines.
Vertical Fillers anchor the volume base while Labelers gain share at the steepest rate.
Technology:
Capital intensity stratifies cleanly across automation tiers, with manual equipment occupying entry price points and robotic systems commanding premium positioning through labor substitution economics.
- Automatic:Fully integrated lines with programmable logic controllers synchronize forming, filling, and sealing at throughputs exceeding 600 units per minute. Carbonated beverage plants in Italy specify automatic systems where line efficiency governs unit economics.
- Semi-Automatic:Operator-fed machines automate core functions while requiring manual loading and changeover intervention. Mid-sized confectionery producers in Spain deploy semi-automatic equipment to bridge volume thresholds before full automation becomes viable.
- Manual:Hand-operated sealers and bench-top fillers serve micro-batch producers and pilot-scale operations. Artisan food startups in Portugal purchase manual equipment to validate product-market fit before scaling capital commitments.
- Robotic:Collaborative and articulated arms handle pick-and-place, palletizing, and mixed-SKU sorting without fixed tooling. Contract packagers in the Netherlands install robotic systems to absorb volatility in promotional format demand.
Automatic technology commands the installed base while Robotic installations expand most quickly as labor costs and SKU complexity escalate.
End User:
Regulatory burden and validation rigor create divergent procurement patterns, with pharmaceutical buyers demanding documentation depth that food processors rarely replicate.
- Food & Beverage:Equipment must comply with EU hygiene directives and national food contact material regulations across dairy, meat, bakery, and beverage sub-segments. German dairy cooperatives specify aseptic filling systems where extended shelf life reduces cold chain dependency.
- Pharmaceuticals:Containment and serialization equipment serves oral solid dose, parenteral, and biologics manufacturing under EMA and national competent authority oversight. Swiss pharmaceutical packaging lines integrate vision systems for track-and-trace compliance across EU distribution networks.
- Cosmetics:Filling and capping equipment handles creams, serums, and fragrances where viscosity variation and decoration precision govern specification. French luxury beauty brands specify servo-driven dosing to minimize giveaway and preserve margin.
- Electronics:Anti-static packaging and precision placement systems protect semiconductors and consumer devices from electrostatic discharge and mechanical damage. Dutch electronics assemblers deploy automated tape-and-reel equipment for component shipment to Asian contract manufacturers.
Food & Beverage anchors procurement volume while Pharmaceuticals drives premium pricing through validation and containment requirements.
Packaging Type:
Material transition dynamics reshape equipment specifications as brand owners migrate from rigid formats toward substrates that reduce shipping cube and improve recyclability profiles.
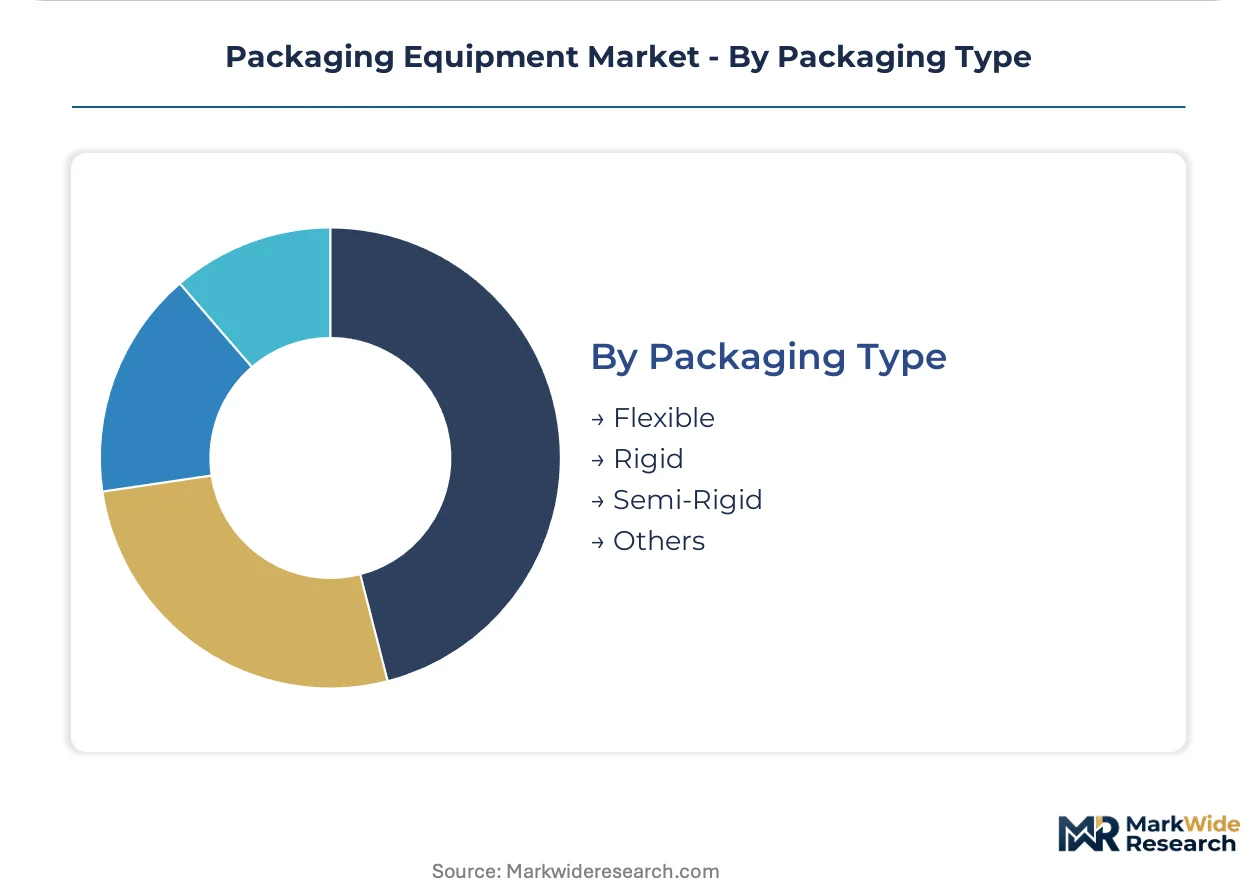
- Flexible:Film, pouch, and bag equipment processes polyethylene, polypropylene, and emerging paper-based barrier substrates. Italian pasta producers retrofit lines for mono-material flexible formats that satisfy EU single-use plastics directives.
- Rigid:Blow molding, thermoforming, and injection molding systems produce bottles, jars, and trays from PET, HDPE, and PP resins. German mineral water bottlers maintain rigid format dominance where carbonation retention and premium shelf presence outweigh material efficiency gains.
- Semi-Rigid:Carton, tray, and blister formats combine structural rigidity with reduced material mass versus fully rigid alternatives. Spanish fresh produce distributors specify semi-rigid trays with top-seal film to balance protection against breathable packaging requirements.
- Others:Specialized equipment handles biodegradable polymers, molded fiber, and hybrid material constructions at pilot and niche commercial scale. Belgian organic food brands test molded fiber equipment for takeaway containers ahead of anticipated regulatory bans on expanded polystyrene.
Rigid formats retain the largest installed base while Flexible equipment shows the steepest expansion trajectory as material substitution accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment trade flows concentrate in manufacturing economies with strong machinery engineering traditions and processing sector scale. Export-oriented fabricators in Germany and Italy supply filling and sealing systems throughout Europe and into emerging markets, while import demand surges in India and Southeast Asia where food processing automation accelerates.
Germany
Stuttgart and Munich engineering clusters produce precision filling systems for dairy and beverage exporters. The EU F-Gas Regulation drives refrigerant transition in sealing equipment sold across member states. Bavarian OEMs anchor European supply chains with integrated bottling lines serving carbonated and aseptic applications.
United States
Pharmaceutical serialization mandates under FDA 21 CFR Part 11 propel vision system and track-and-trace equipment investment. Craft beverage proliferation in the Pacific Northwest and Southeast generates labeler refresh demand as SKU counts expand. Midwest dairy cooperatives specify automated case packers to reduce labor dependency in high-volume cheese operations.
China
Domestic dairy processors under SAMR food safety oversight retrofit lines for extended shelf-life formats. Yangtze River Delta manufacturing bases produce mid-tier filling equipment for Southeast Asian export markets. NMPA pharmaceutical packaging regulations accelerate containment system localization for biologics manufacturing.
India
PLI scheme incentives for food processing cold chain infrastructure create first-time automation demand in dairy and ready-to-eat segments. FSSAI hygiene mandates push mid-sized processors toward semi-automatic equipment upgrades. Gujarat and Maharashtra industrial corridors attract European OEM joint ventures for localized assembly operations.
Italy
Emilia-Romagna packaging machinery districts supply flow-wrap and thermoform systems for European fresh produce and pasta producers. REACH chemical restrictions constrain adhesive selections in sealing equipment exported to EU markets. Venetian OEMs specialize in modified atmosphere packaging lines serving French and German retail distribution networks.
Packaging Equipment Market Vendor Landscape
On the supply side, the industry is consolidating around integrated system providers with captive control over critical motion control and software architectures. Tiered competitive positioning separates turnkey line integrators from component specialists and regional fabricators. Strategic archetypes include diversified machinery conglomerates, pure-play packaging specialists, and emerging Asian scale players. Dominant competitive moves encompass portfolio diversification into adjacent processing equipment and geographic expansion through distribution partnerships in underpenetrated markets.
Within the European engineering tier, Krones AG and Syntegon Technology GmbH exemplify divergent specialization strategies, with the former anchoring beverage system integration and the latter occupying pharmaceutical containment positioning. Coesia S.p.A. represents the diversified holding company archetype, controlling multiple specialty machinery brands across end-use verticals without single-category dependence. Among North American fabricators, Barry-Wehmiller Companies occupies the acquisition-driven consolidation position, while Tetra Laval Group exemplifies the vertically integrated packaging materials-to-machinery model.
| Leading Market Players |
|---|
| KHS Group |
| SIG Combibloc Group Ltd. |
| Tetra Laval Group |
| Barry-Wehmiller Companies |
| Syntegon Technology GmbH |
| Krones AG |
| Coesia S.p.A. |
| GEA Group Aktiengesellschaft |
| Sacmi |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese mid-tier filling equipment is compressing margin buffers for European OEMs while simultaneously forcing German and Italian suppliers toward premium positioning and extended service bundling.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels. Certification grade—particularly FDA validation and EU F-Gas compliance tiers—separates premium German systems from standardized Italian alternatives and economy Asian imports. Pricing pressure stems from stainless steel commodity swings and Japanese servo motor supply constraints. Mid-sized food processors exhibit highest price sensitivity, while pharmaceutical manufacturers absorb premium tiers for validation continuity.
Supply Chain Analysis
Extended payment terms from European OEMs to Japanese and German servo motor suppliers are lengthening working capital cycles across the equipment fabrication tier. Component sourcing concentrates in Germany, Italy, and China, with precision motion control systems drawing from Japanese suppliers. Stainless steel alloy grades and specialized refrigerants for sealing equipment rest on commodity and regulatory exposure. Distribution runs through regional machinery engineering clusters serving export markets with localized assembly partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Packaging equipment sits in early-cycle expansion as EU Green Deal mandates force material-flexibility retrofits across installed dairy and beverage bases, creating replacement demand independent of greenfield capacity.
For Market Incumbents: Build switching-cost moats through captive financing arms and predictive maintenance subscriptions that embed OEMs within customer operations. Consolidate regional service networks to defend against emerging Asian scale players. Deepen backward integration into servo control architectures to reduce exposure to Japanese supplier lead times. For New Entrants and Emerging Players: Mid-market processors in India's Gujarat and Maharashtra corridors represent the most penetrable entry point, where PLI scheme incentives intersect with first-time automation demand. Target semi-automatic equipment tiers for dairy cooperatives upgrading from manual operations. Deploy equipment-as-a-service contracting to bypass capital-constraint barriers. For Investors and Strategic Acquirers: Capital is best deployed toward pharmaceutical containment specialists with FDA validation track records and recurring aftermarket revenue streams. Long-term viability hinges on software-defined equipment architectures enabling remote diagnostics. Monitor EU Extended Producer Responsibility implementation timelines as inflection signals for recyclability-driven line refresh cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Equipment-as-a-Service Launch | Pay-per-output contracts reduce capital barriers for mid-sized Southeast Asian processors. |
| Backward Integration into Motion Control | In-house servo programming mitigates Japanese supplier concentration risk. |
| Digital Twin Platform Deployment | Virtual commissioning compresses installation timelines for dispersed beverage networks. |
| Pharmaceutical Containment Acquisition | FDA validation expertise commands premium positioning in biologics manufacturing. |
| Recyclable Substrate Line Retrofit | EU single-use plastics directives create replacement demand across dairy plants. |
Methodological Framework
Desk research of trade association filings, customs records, and machinery engineering publications preceded structured interviews with plant engineers, OEM procurement teams, aftermarket service heads, and food processing operations directors. Primary fieldwork with European packaging machinery OEMs and Indian dairy cooperative technical staff was cross-validated against SEC filings and EU regulatory impact assessments. Bottom-up equipment shipment analysis and top-down processing sector investment flows were triangulated to anchor volume estimates.
Assumptions around EU regulatory implementation timelines and stainless steel price normalization were held fixed across the projection horizon, while technology adoption curves and regional penetration rates were sensitivity-tested. Segmentation modeling spanned automation tier, end-use vertical, packaging material type, and geographic machinery cluster. CAGRs were derived from equipment replacement cycle analysis and greenfield capacity announcements. Forecast inputs incorporated F-Gas Regulation compliance cost trajectories and pharmaceutical serialization mandate expansion patterns.
Practitioners should monitor EU EPR scheme rollout velocity and Japanese servo motor supply allocation for early signals of demand or cost revision. Forecasts reflect documented assumptions around regulatory enforcement intensity and commodity price stabilization. Macroeconomic contraction, accelerated regulatory deviation, or breakthrough alternative packaging formats would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Airless Pumps Market
Packaging Equipment
Global End-Of-Line Packaging Market
Packaging Equipment
Diaper Packaging Machines Market
Packaging Equipment
Ancillary Packaging Equipment Market
Packaging Equipment
Heat Sealing Equipment Market
Packaging Equipment
Vacuum Sealers Market
Packaging Equipment
Die-Cutter Market
Packaging Equipment
High Resolution Dispensing Systems and Equipment Market
Packaging Equipment
Table Top Band Sealer Market
Packaging Equipment
Shrink Wrap Equipment Market
Packaging Equipment
Shrink Wrapper Market
Packaging Equipment
Inflatable Void Fill System Market
Packaging Equipment
Global Dispensing Systems Market
Packaging Equipment
Industrial Heat Sealers Market
Packaging Equipment
Sack Tip Stations Market
Packaging Equipment
Packer Market