
 Slitter Rewinder Machines Market | 2026-2036
Slitter Rewinder Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Slitter Rewinder Machines Market Outlook
China is tilting the supply landscape through aggressive capacity additions in precision converting equipment. Kampf leverages its German engineering heritage to sustain premium positioning in high-tension foil slitting. ASHE Converting Equipment anchors British manufacturing presence through specialized narrow-web systems for flexible packaging. Jennerjahn Machine dominates North American narrow-web tissue and toweling segments with dedicated slitter rewinders built for hygiene product converters.
A slitter rewinder machine unwinds master rolls of flexible material, slits them to specified widths using shear, score, or razor blades, and rewinds finished rolls at controlled tension and alignment. Modern units operate at line speeds exceeding 1,000 meters per minute with automatic knife positioning and defect detection systems integrated into the control architecture. Automatic machine types command the largest installed base as converters prioritize throughput consistency and reduced changeover downtime across plastic and film processing lines. PLC-based control systems retain broad adoption despite CNC penetration in premium segments, since ladder-logic familiarity lowers maintenance burdens for mid-tier operators.
Germany's Ecodesign for Sustainable Products Regulation pressures manufacturers to document energy consumption and material efficiency across machine lifecycles. China's GB standards for mechanical safety and the EU's CE marking requirements for electromagnetic compatibility both shape export qualification pathways for OEMs serving multiple jurisdictions. Stakeholders must weigh capital allocation between servo-electric automation upgrades and legacy pneumatic system support as regulatory thresholds tighten without uniform global timing.
Market Dynamics
Servo-electric automation architectures are displacing legacy pneumatic systems across film and foil converting lines, driven by energy efficiency mandates and precision tension control requirements.
Growth Catalysts
- EU Ecodesign Regulation:Germany's Ecodesign for Sustainable Products Regulation mandates documented lifecycle energy consumption, pushing converters toward servo-driven automatic slitter rewinders with regenerative drives and smart power management.
- Flexible packaging film demand:Food and pharmaceutical flexible packaging converters in China's coastal provinces are scaling precision converting capacity to serve export markets, requiring high-speed automatic units with defect detection integration.
- AI-powered edge computing:Machine vision systems with real-time defect classification are reducing material waste and enabling predictive maintenance, particularly attractive to narrow-web tissue processors seeking zero-defect output.
Market Restraints
- Specialized steel alloy supply:Precision-ground shear blades and hardened arbors depend on specialty tool steel grades concentrated among Japanese and German metallurgical suppliers, creating input cost volatility and extended lead times.
- CE marking electromagnetic compliance:The EU's electromagnetic compatibility directive imposes costly certification cycles on OEMs, particularly constraining mid-tier Asian manufacturers seeking European market entry.
- Digital printing substitution:Single-pass inkjet web presses with inline finishing are capturing short-run label and flexible packaging volumes, compressing demand for standalone slitting capacity in runs below 10,000 linear meters.
Strategic Opportunities
- India's PLI scheme for packaging:India's Production Linked Incentive scheme for specialty chemicals and packaging materials is attracting film extrusion investments, creating greenfield demand for integrated slitting and rewinding lines in Gujarat and Maharashtra.
- Battery separator film processing:Lithium-ion battery manufacturers require ultra-clean slitting environments for ceramic-coated polypropylene separators, a specification gap that OEMs with cleanroom-compatible architectures can exploit.
- Remote diagnostics convergence:Cloud-based condition monitoring fused with augmented reality technician support is enabling OEMs to unbundle after-sales service contracts and capture recurring revenue from distributed converter bases.
Industry Challenges
- Mechatronics technician scarcity:Servo system commissioning and PLC troubleshooting require cross-trained automation specialists, a skill profile in short supply across Midwestern US converting hubs where legacy mechanical expertise dominates.
- Legacy control integration:Retrofitting 1990s-era DC drive slitter rewinders with modern servo axes demands custom mechanical adapters and software bridges, extending project timelines and inflating integration costs for brownfield sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Slitter Rewinder Machines Market |
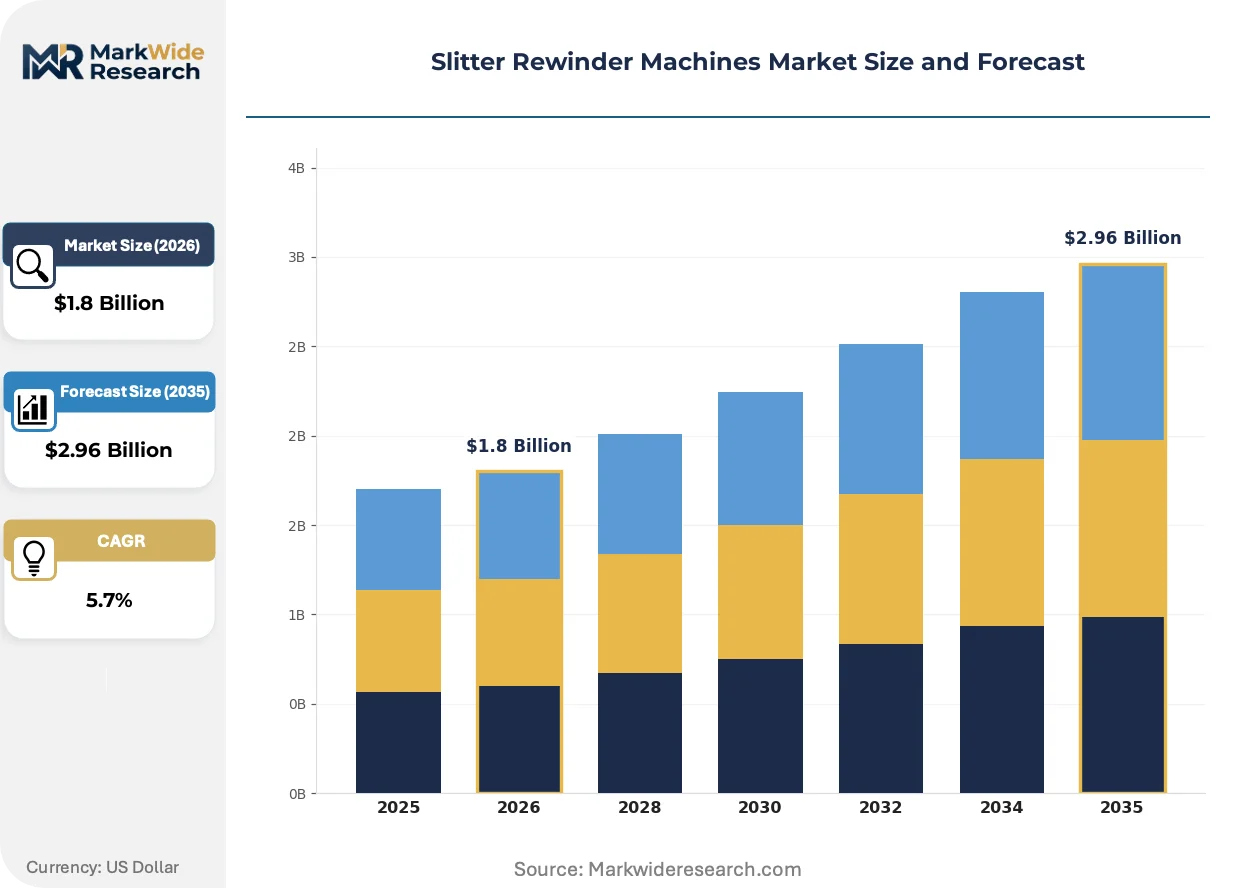
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Machine Type: Automatic, Semi-Automatic, Manual, Digital End User: Packaging, Retail, Textile, Electronics Material Type: Plastic, Paper, Film, Foil Control System: PLC, CNC, Pneumatic, Hydraulic |
| Companies Covered | Atlas Converting Equipment, Kampf, ASHE Converting Equipment, Euromac Costruzioni Meccaniche, Pasquato Cutting Machines, Jennerjahn Machine, GOEBEL IMS, Parkinson Technologies, Elite Cameron TS Converting Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Slitter Rewinder Machines Market Strategic Shifts
Digital thread technologies and sustainable materials processing are converging to redefine machine specifications, with regulatory compliance and operational transparency now embedded in core system architecture rather than treated as aftermarket additions.
Direct-drive torque motor technology is hybridizing with traditional gearbox and belt-drive unwinding systems, delivering precise tension control without mechanical backlash. High-end foil processors in Germany and Japan are adopting these architectures for aluminum battery foil and capacitor film applications where tension deviation below 0.5% prevents edge waviness. The technology is hybridizing market segmentation by enabling single machines to handle both delicate 6-micron films and heavy-gauge industrial laminates that previously required dedicated lines.
The EU's Corporate Sustainability Reporting Directive now requires large converters to disclose Scope 3 emissions including capital equipment energy profiles. This disclosure mandate is forcing OEMs to publish verified power consumption data across operating modes, with CE-marked machines now competing partly on kilowatt-hour per ton of finished product. German and Italian manufacturers with existing energy certification infrastructure are capturing specification advantage, while competitors face 12-18 month documentation gaps.
Converters are consolidating vendor relationships and demanding outcome-based performance guarantees rather than equipment-only transactions. Large North American flexible packaging groups now specify guaranteed uptime percentages and throughput-per-shift minimums, with payment terms tied to operational validation rather than delivery acceptance. This contracting evolution is most visible in California and Texas, where private equity-backed packaging roll-ups possess procurement leverage to impose service-level obligations on machine suppliers.
Slitter Rewinder Machines Market Segmentation
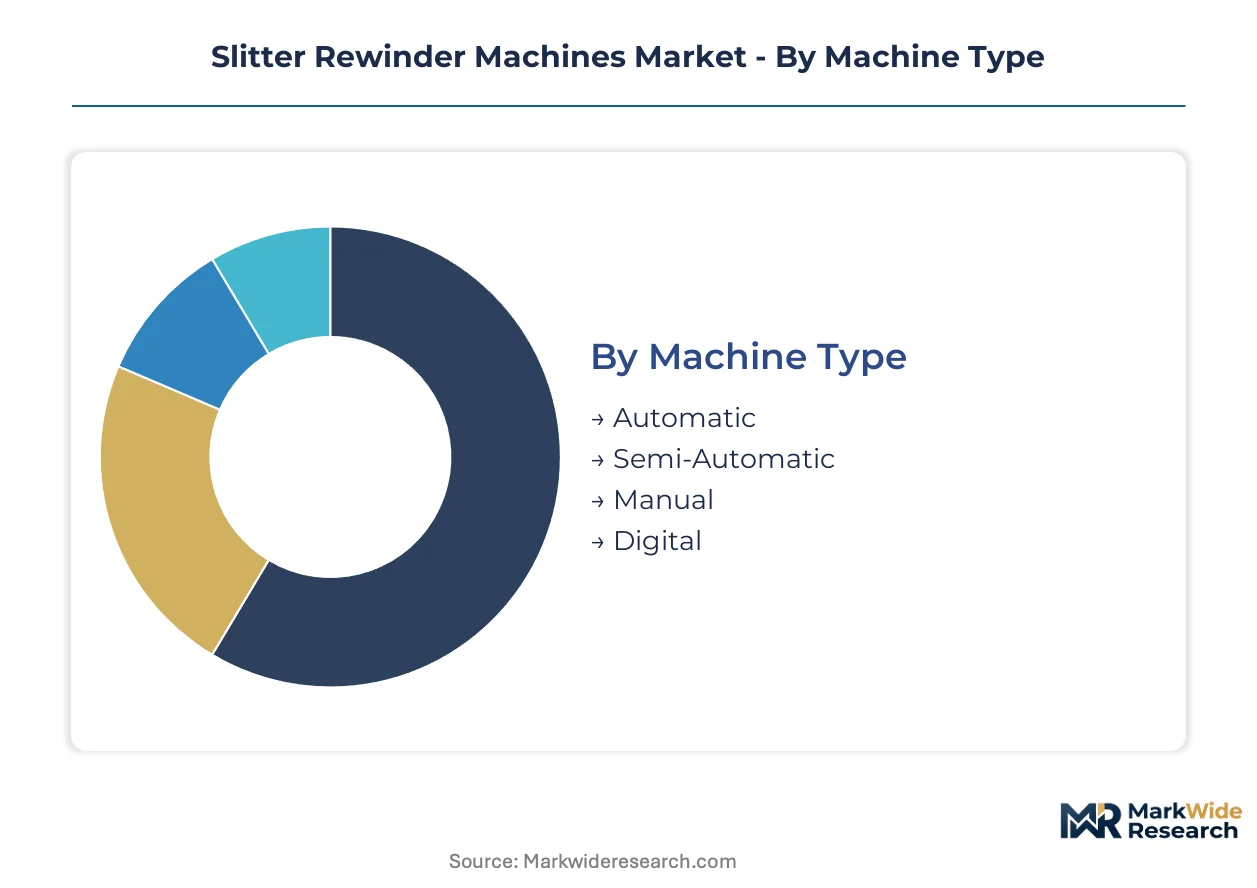
Slitter rewinder machine segmentation reveals how after-sales service intensity varies dramatically across automation tiers and material specifications. Converters operating high-speed film lines demand predictive maintenance contracts that OEMs monetize separately from hardware margins.
Machine Type:
After-sales service intensity escalates with automation complexity, as servo-driven automatic units require specialized technician networks that reshape vendor profitability models.
- Automatic:Servo-electric architectures with regenerative drives and automatic knife positioning dominate flexible packaging lines in China's coastal provinces. Food and pharmaceutical converters in Zhejiang and Jiangsu prioritize throughput consistency and defect detection integration. PLC-based control familiarity lowers maintenance burdens for mid-tier operators despite CNC penetration in premium segments.
- Semi-Automatic:Hybrid configurations bridge legacy pneumatic systems and modern servo axes, appealing to brownfield sites in Germany's converting belt where retrofit economics favor incremental automation. Tension control precision falls short of battery separator specifications but satisfies general industrial film processing.
- Manual:Mechanical score and razor blade systems persist in narrow-web tissue converting where low capital thresholds match hygiene product batch sizes.
- Digital:Inline machine vision and edge computing integration enable real-time defect classification for zero-defect output requirements in pharmaceutical packaging.
Automatic machines hold the largest share; momentum sits with Digital configurations as AI-powered edge computing expands.
End User:
Application-specific tension tolerances and cleanliness requirements fragment procurement specifications across verticals with diverging capital deployment cycles.
- Packaging:Flexible food and pharmaceutical film converters drive demand for high-speed units with electromagnetic compatibility certification under EU directives. California and Texas packaging roll-ups impose outcome-based performance guarantees with uptime percentages tied to payment terms.
- Retail:Label stock and point-of-sale material processors favor semi-automatic configurations with quick changeover capabilities for short-run digital printing substitution pressures.
- Textile:Narrow-web tissue and toweling segments in the US Midwest require dedicated slitter rewinders built for hygiene product converters with specific unwind tension profiles.
- Electronics:Lithium-ion battery manufacturers demand ultra-clean slitting environments for ceramic-coated polypropylene separators, a specification gap that cleanroom-compatible architectures exploit.
Packaging commands the dominant installed base; Electronics represents the steepest expansion trajectory as battery separator film processing scales.
Material Type:
Material thickness ranges and surface sensitivity dictate blade geometry, arbor design, and tension control architecture across converting lines.
- Plastic:Biaxially oriented polypropylene and polyethylene terephthalate films require precision-ground shear blades and hardened arbors dependent on specialty tool steel grades concentrated among Japanese and German metallurgical suppliers.
- Paper:Tissue and toweling grades tolerate score blade slitting with lower capital intensity, though dust extraction and static control add system complexity for hygiene product specifications.
- Film:Delicate 6-micron capacitor films and heavy-gauge industrial laminates increasingly run on hybrid direct-drive torque motor systems that eliminate mechanical backlash.
- Foil:Aluminum battery foil and capacitor applications in Germany and Japan demand tension deviation below 0.5% to prevent edge waviness, pushing adoption of direct-drive unwinding architectures.
Plastic films retain the broadest application base; Foil processing is gaining share fastest as battery manufacturing capacity expands.
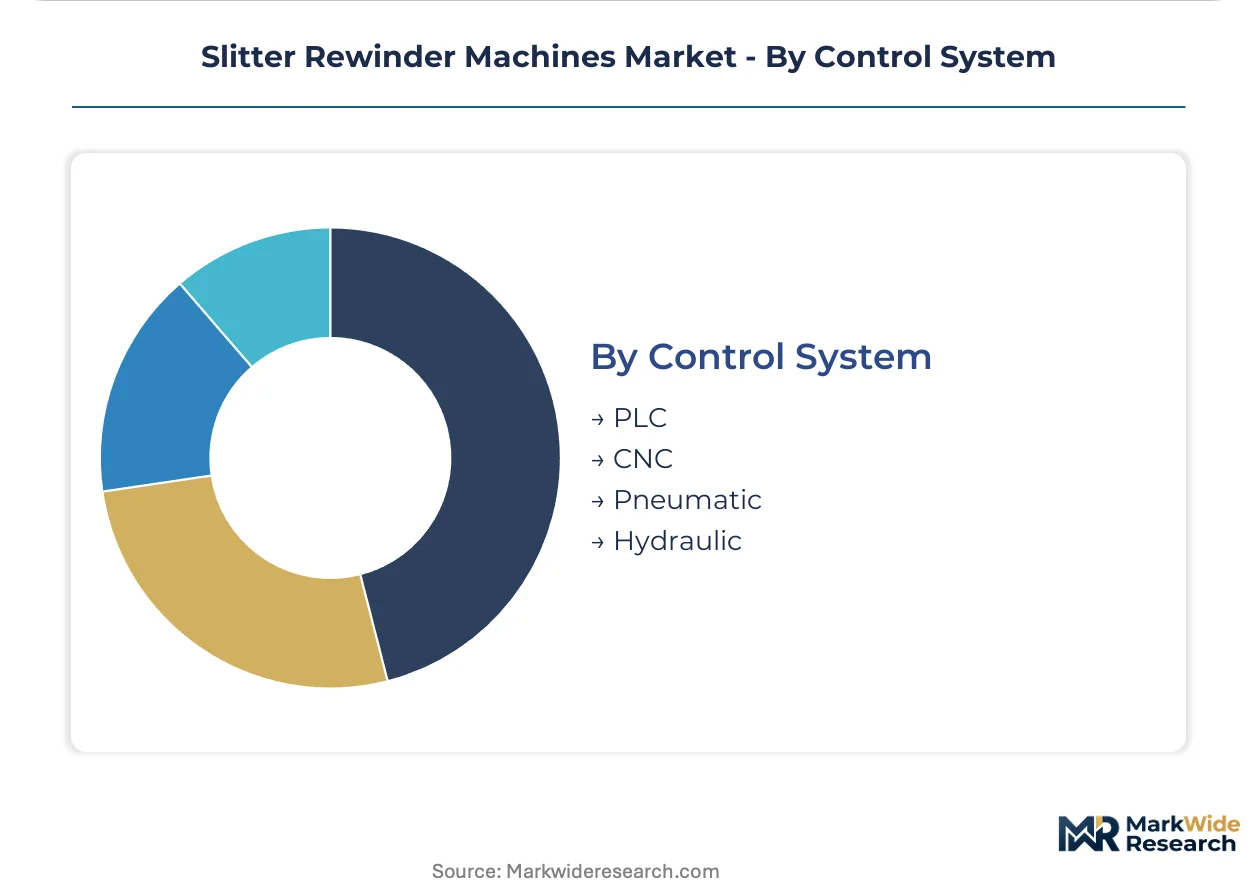
Control System:
Control architecture selection reflects trade-offs between precision, maintenance accessibility, and legacy integration burdens across operator skill profiles.
- PLC:Ladder-logic programming retains broad adoption across mid-tier film and foil converters where technician familiarity reduces commissioning costs and downtime response times.
- CNC:Computer numerical control dominates premium foil slitting where Kampf and other German engineering heritage manufacturers sustain positioning through high-tension precision.
- Pneumatic:Legacy systems face displacement by servo-electric architectures under Germany's Ecodesign for Sustainable Products Regulation mandating documented lifecycle energy consumption.
- Hydraulic:Heavy-gauge industrial laminate processing retains hydraulic tension control for extreme torque requirements where electric servo sizing becomes economically prohibitive.
PLC systems maintain the largest installed base; servo-electric architectures are displacing pneumatic and hydraulic alternatives fastest under energy efficiency mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's automated container handling infrastructure underwrites Europe's converting equipment distribution hub, while China's Yangtze River Delta ports process the densest concentration of film and foil slitting machinery imports globally.
United States
Flexible packaging roll-ups in California and Texas impose outcome-based performance guarantees on equipment suppliers. OSHA workplace safety standards and FDA food contact material regulations shape machine guarding and surface finish specifications. Midwestern converting hubs around Chicago and Milwaukee face acute mechatronics technician scarcity as servo system commissioning demands outpace legacy mechanical expertise.
Germany
Battery separator film processors in Baden-Württemberg demand tension deviation below 0.5% for aluminum battery foil applications. The Ecodesign for Sustainable Products Regulation mandates documented lifecycle energy consumption, accelerating displacement of pneumatic systems by servo-electric architectures. Stuttgart and Karlsruhe host precision converting clusters where direct-drive torque motor technology adoption concentrates.
China
Food and pharmaceutical film converters in Zhejiang and Jiangsu provinces scale precision converting capacity for export markets. GB standards for mechanical safety and MIIT industrial efficiency directives shape domestic equipment procurement. Shanghai and Ningbo port clusters process the highest volume of automatic slitter rewinder imports serving coastal manufacturing belts.
India
Specialty chemicals and packaging material investments under the PLI scheme attract film extrusion capacity to Gujarat and Maharashtra. BIS certification requirements and state-level industrial safety regulations govern equipment qualification. Ahmedabad and Mumbai industrial corridors generate greenfield demand for integrated slitting and rewinding lines.
Japan
Capacitor film and electronics material processors in Kansai and Chubu regions require ultra-clean slitting environments. METI energy efficiency standards and JIS mechanical safety specifications filter equipment procurement. Osaka and Nagoya manufacturing clusters sustain premium positioning for high-tension foil slitting applications.
Slitter Rewinder Machines Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying precision-ground shear blades and hardened arbors. The vendor base concentrates among German engineering heritage manufacturers, British narrow-web specialists, and North American hygiene-focused fabricators. Two strategic archetypes dominate: premium-tier OEMs leveraging energy certification infrastructure, and mid-tier Asian manufacturers constrained by CE marking documentation gaps. Competitive moves center on M&A consolidation among packaging roll-ups and capacity expansion into battery separator film specifications.
Among German-based platform integrators, Kampf GmbH and GOEBEL IMS occupy positions anchored by high-tension precision engineering heritage. ASHE Converting Equipment represents the British narrow-web specialization archetype, while Jennerjahn Machine exemplifies North American dominance in hygiene product converting segments. These three fabricators illustrate how geographic engineering traditions translate into distinct market positioning across automation tiers and material specifications.
| Leading Market Players |
|---|
| Atlas Converting Equipment |
| Kampf |
| ASHE Converting Equipment |
| Euromac Costruzioni Meccaniche |
| Pasquato Cutting Machines |
| Jennerjahn Machine |
| GOEBEL IMS |
| Parkinson Technologies |
| Elite Cameron TS Converting Equipment |
| Others |
Value Chain & Pricing Dynamics
Specialty tool steel supply concentration among Japanese and German metallurgical suppliers determines both tiered pricing spreads across automatic, semi-automatic, and manual machine configurations and the elongated supply chain architecture that converters must navigate. Procurement teams face simultaneous pressure from input cost volatility on precision-ground shear blades and hardened arbors alongside extended qualification timelines for alternative metallurgical sources.
Pricing Analysis
Volume-discount tiering structures separate premium servo-electric automatic units with regenerative drives and defect detection integration from mid-range PLC-based configurations and economy-grade pneumatic legacy systems. Price differentiation rests on CE marking certification status and after-sales service bundling intensity, with German and Italian OEMs commanding specification premiums through verified energy consumption documentation. Cost compression in mid-tier segments intensifies as Chinese coastal converters scale procurement volumes and negotiate outcome-based performance guarantees. Small-scale tissue converters in the US Midwest exhibit highest price sensitivity due to batch-size constraints, while lithium-ion battery manufacturers prioritize specification compliance over capital outlay.
Supply Chain Analysis
Upstream feedstock dependencies center on specialty tool steel grades from Japan and Germany, high-torque servo motors from German and Italian automation specialists, and precision bearings from Swedish and Japanese suppliers. Component sourcing draws from concentrated metallurgical clusters in Düsseldorf and Osaka, with alternative qualification pathways requiring 12-18 month validation cycles. Single-source vulnerability persists for ceramic-coated polypropylene separator specifications where cleanroom-compatible architectures face limited secondary sourcing. Distribution runs through Rotterdam's automated container infrastructure for European markets and Shanghai-Ningbo port clusters for Asia-Pacific deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits at a cyclical recovery phase driven by battery separator film capacity expansion, with capital equipment procurement accelerating as lithium-ion manufacturing investments reach commercial scale.
For Market Incumbents: Harden defensive positioning through backward integration into precision metallurgical component production, capturing margin that currently flows to Japanese and German tool steel suppliers. Invest aggressively in cleanroom-compatible machine architectures to anchor specification control as battery separator film processing scales. Prioritize certification infrastructure for EU Corporate Sustainability Reporting Directive compliance to maintain pricing power against mid-tier Asian competitors facing documentation gaps.
For New Entrants and Emerging Players: Pursue white-space capture in India's Gujarat and Maharashtra industrial corridors where PLI scheme incentives attract film extrusion investments without entrenched vendor relationships. Target battery separator film specifications where incumbent capacity constraints create procurement bottlenecks for lithium-ion manufacturers. Lead with remote diagnostics and augmented reality technician support as a service-unbundling wedge against legacy OEMs dependent on bundled after-sales contracts.
For Investors and Strategic Acquirers: The market sits at an early-expansion phase that favors platform integrators with energy certification infrastructure and established technician networks. Long-term viability over the coming decade hinges on exposure to battery manufacturing capital cycles and flexible packaging consolidation trends. Acquisition targets should demonstrate cleanroom-compatible architectures and documented power consumption verification. Monitor lithium-ion battery capacity announcement velocity as the primary inflection signal for equipment order flow acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Metallurgy | Captures margin from Japanese and German tool steel suppliers while reducing lead time volatility. |
| Cleanroom-Compatible Architecture Development | Exploits specification gaps for ceramic-coated polypropylene separator processing in battery manufacturing. |
| Remote Diagnostics Platform Deployment | Enables OEMs to unbundle after-sales service contracts and capture recurring revenue from distributed converter bases. |
| EU Energy Certification Investment | Defends specification advantage as Corporate Sustainability Reporting Directive mandates Scope 3 capital equipment disclosure. |
| India PLI Corridor Market Entry | Positions for greenfield demand in Gujarat and Maharashtra as specialty chemicals and packaging investments accelerate. |
Study Parameters
The analysis maps automatic, semi-automatic, manual, and digital machine configurations, each validated through maintenance directors at flexible packaging converters, plant engineers at battery separator film processors, OEM procurement teams, and aftermarket service heads. Primary interviews combined with secondary validation from SEC filings of listed packaging equipment manufacturers, MIIT industrial efficiency directives, EU Ecodesign regulatory documentation, and customs trade data for slitting machinery imports. Bottom-up installation base estimates triangulated against top-down capital expenditure flows across food, pharmaceutical, and electronics material processing verticals.
Assumption sets held regulatory implementation timelines and energy efficiency mandate stringency fixed across modeling scenarios while varying battery manufacturing capacity expansion rates and flexible packaging consolidation velocity. Segmentation dimensions modeled include automation tier, end-use vertical, material thickness range, and regional regulatory cluster. CAGRs derived from equipment replacement cycles, brownfield retrofit economics, and greenfield capacity announcement pipelines. Forecast inputs incorporated servo-electric adoption curves and cleanroom specification penetration rates.
Macroeconomic conditions sit as an overlay; deviation in industrial capital expenditure cycles, specialty steel alloy pricing, or lithium-ion demand trajectories would shift the trajectory. Forecasts reflect documented assumptions without guarantee of realization. Cross-checking against equipment order backlogs reported in OEM financial disclosures and battery manufacturing capacity development databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Corrugated Paper Machine Market
Packaging Machinery
Global Tissue Paper Converting Machines Market
Packaging Machinery
Automatic Liquid Filling Machines Market
Packaging Machinery
Wet Ink Coding Machines Market
Packaging Machinery
Pallet Strapping Machines Market
Packaging Machinery
Laminating Machines Market
Packaging Machinery
Side Load Case Packing Machines Market
Packaging Machinery
Sack Filling Machine Market
Packaging Machinery
Tablet Packing Machine Market
Packaging Machinery
Metal Banding Machine Market
Packaging Machinery
Envelope Sealing Machines Market
Packaging Machinery
Pallet Stretch Wrapping Machines Market
Packaging Machinery
Barcode Labeller Machine Market
Packaging Machinery
Cosmetic Filling Machines Market
Packaging Machinery
Stacking Machine Market
Packaging Machinery
Shrink Wrapping Machines Market