
 Confectionery Packaging Machine Market | 2026-2036
Confectionery Packaging Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Confectionery Packaging Machine Market Analysis
Modular packaging configurations is shifting how confectionery brands evaluate capital equipment, moving from standalone machines toward integrated lines that handle forming, filling, and sealing in synchronized sequences. Syntegon Technology leverages its pharmaceutical packaging heritage to engineer hygienic confectionery systems with washdown capabilities. GEA Group anchors its position through extensive aftermarket service networks spanning major candy production regions. IMA Group specializes in high-speed wrapping technologies for premium chocolate assortments requiring delicate handling protocols.
Confectionery packaging machines constitute electromechanical systems designed to enclose candy, chocolate, and snack products in protective formats using specified film gauges, heat-sealing temperatures, and throughput rates measured in units per minute. These systems employ servo-driven motion control, programmable logic controllers, and vision inspection to maintain seal integrity and weight accuracy across continuous production cycles. Flow wrappers occupy the largest installed base due to their versatility across bar and countline formats, while robotic technology segments are gaining traction for flexible handling of irregular premium shapes. Tray sealers command stronger margins in artisan and gift confectionery applications where presentation standards justify slower, precision-oriented equipment.
FDA food contact notification requirements govern laminate and film compositions used in US-bound confectionery packaging, while EU machinery safety directives mandate interlocked guarding and emergency stop protocols for equipment sold across European markets. ISO hygiene standards for food processing machinery influence design specifications for washdown compatibility and microbial control in wet-cleaning environments. Stakeholders must monitor evolving extended producer responsibility frameworks for packaging waste, as these regulations will increasingly determine acceptable material formats and recyclability thresholds for new equipment investments.
Market Dynamics
Modular line integration is compressing equipment replacement cycles as confectionery manufacturers abandon standalone machines for synchronized forming-filling-sealing sequences that reduce changeover downtime and labor touchpoints.
Growth Catalysts
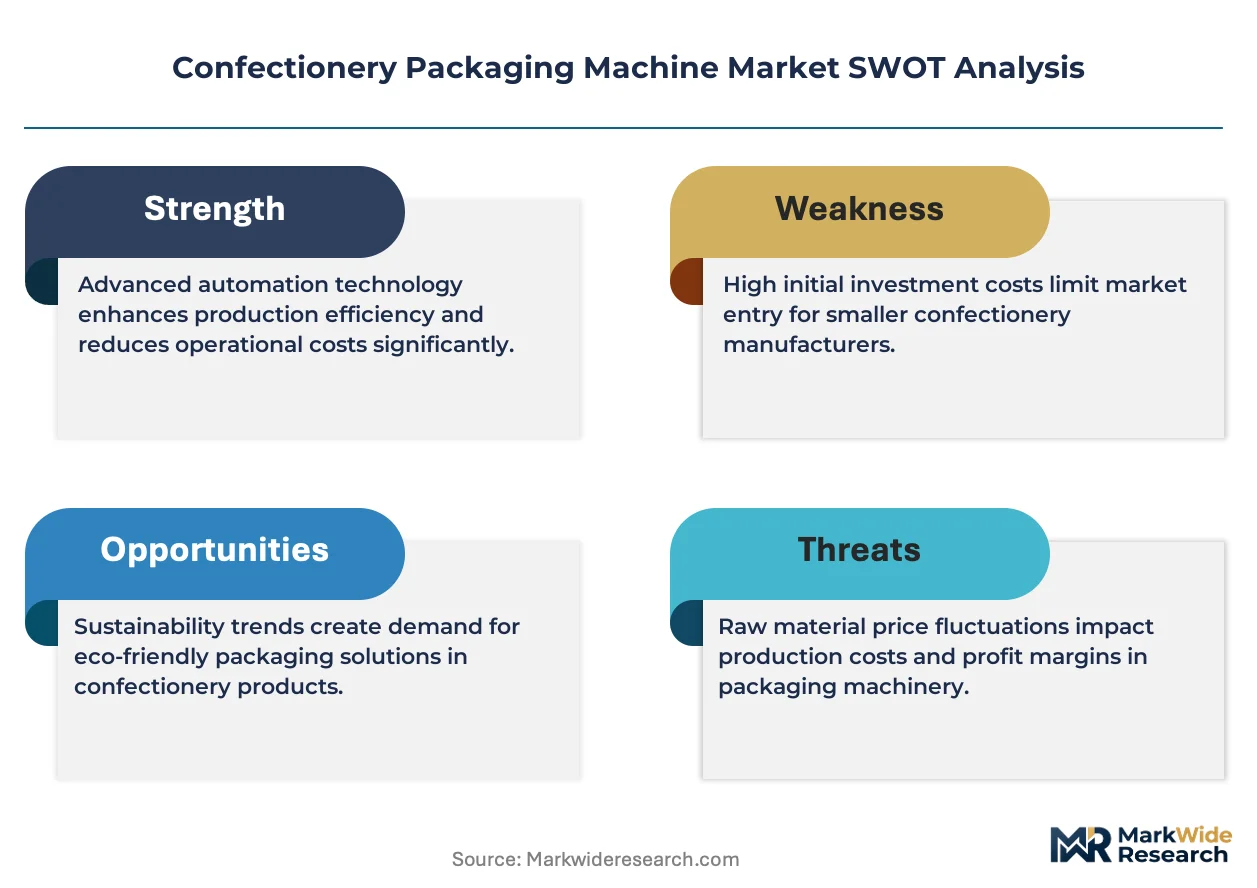
- EU Machinery Safety Directives:Mandated interlocked guarding and emergency stop protocols are accelerating replacement of legacy equipment across European export destinations, pulling forward capital expenditure timelines for compliance-bound producers.
- Robotic Handling Technology:Articulated arm systems with vision-guided pick-and-place capabilities are penetrating premium chocolate assortments where irregular shapes previously required manual loading.
- Germany:Precision engineering clusters around Stuttgart and Munich supply integrated packaging systems to multinational confectionery brands, anchoring regional equipment demand concentration.
Market Restraints
- Stainless Steel Input Volatility:Grade 304 and 316 stainless steel price swings directly compress margin structures for hygienic washdown-compatible equipment manufacturers.
- Servo Drive Supply Concentration:Japanese and German motion control component suppliers create single-source vulnerability for high-speed wrapping machine builders.
- Heat-Sealing Temperature Uniformity:Technical limitations in maintaining ±2°C tolerance across wide film webs constrain throughput scaling for biodegradable laminate formats.
Strategic Opportunities
- India:Domestic chocolate consumption expansion and FSSAI food safety enforcement create underpenetrated demand for automated flow wrapping among regional confectionery brands.
- Extended Producer Responsibility Frameworks:EU packaging waste regulations are mandating recyclable mono-material formats, creating equipment retrofit demand for heat-sealing systems compatible with thinner film gauges.
- Convergence of AI Vision and Predictive Maintenance:Machine learning-enabled defect detection integrated with IoT sensor networks is enabling outcome-based service contracts that unbundle hardware from uptime guarantees.
Industry Challenges
- Mechatronics Skill Scarcity:Shortage of technicians proficient in servo tuning, PLC programming, and hygienic design standards constrains field service expansion for aftermarket revenue capture.
- FDA Food Contact Notification Timelines:Six-to-eighteen-month approval cycles for novel laminate compositions delay commercialization of sustainable packaging equipment configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Confectionery Packaging Machine Market |
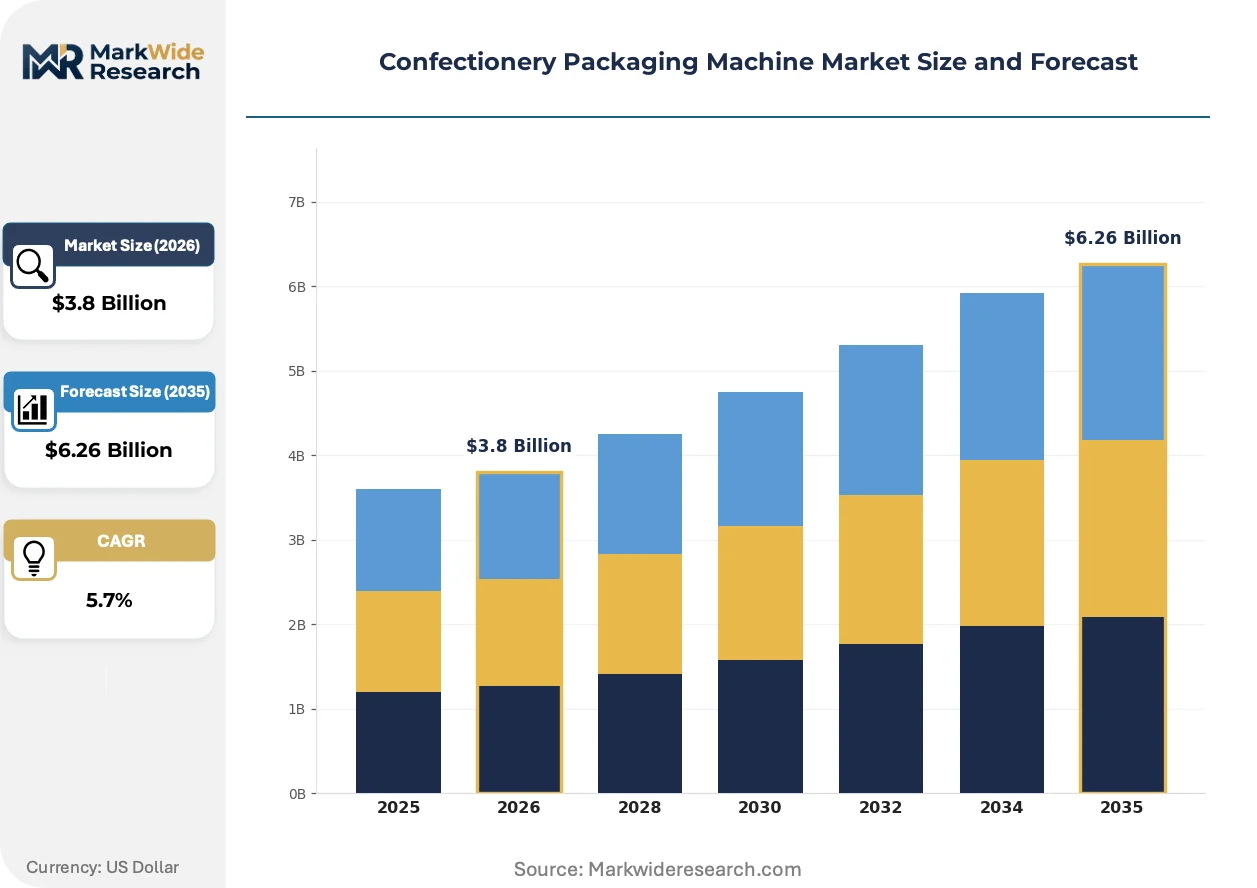
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flow Wrappers, Vertical Form Fill Seal, Stick Pack Machines, Tray Sealers End User: Chocolate Manufacturers, Candy Producers, Snack Food Companies, Bakery Product Lines Technology: Automatic, Semi-Automatic, Manual, Robotic Packaging Type: Box, Bag, Pouch, Wrapper |
| Companies Covered | Syntegon Technology, GEA Group, IMA Group, MULTIVAC, Cama 1 S.p.A., Coesia Group, FUJI Machinery, Tetra Pak, Krones AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Confectionery Packaging Machine Market Emerging Trajectories
Active alignment between equipment functionality and regulatory compliance requirements is reshaping R&D priorities, with manufacturers embedding certification-ready architectures rather than retrofitting after design completion.
Digital twin simulation is unifying machine commissioning protocols by enabling virtual validation of forming, filling, and sealing sequences before physical assembly. Mid-sized confectionery producers in Italy and Japan are adopting cloud-based twin platforms to compress startup timelines from months to weeks. This capability is unifying equipment specification processes around software-configurable parameters rather than mechanical customization.
REACH substance restrictions on per- and polyfluoroalkyl substances are eliminating fluoropolymer coatings from heat-sealing surfaces, forcing equipment redesigns toward ceramic and plasma-treated metal alternatives. European machinery builders face immediate compliance deadlines while US-bound exports anticipate analogous FDA guidance. Chocolate bar manufacturers with pan-European distribution are prioritizing PFAS-free seal jaw systems to preempt supply chain disruption.
Aftermarket service unbundling is disrupting traditional bundled maintenance contracts as end-users demand consumption-based spare parts provisioning and remote diagnostic subscriptions. Premium chocolate brands with seasonal production peaks are replacing fixed annual service agreements with on-demand technician dispatch models. This shift is most visible in Switzerland and Belgium where artisan producers operate lower utilization lines requiring flexible support structures.
Confectionery Packaging Machine Market Segmentation
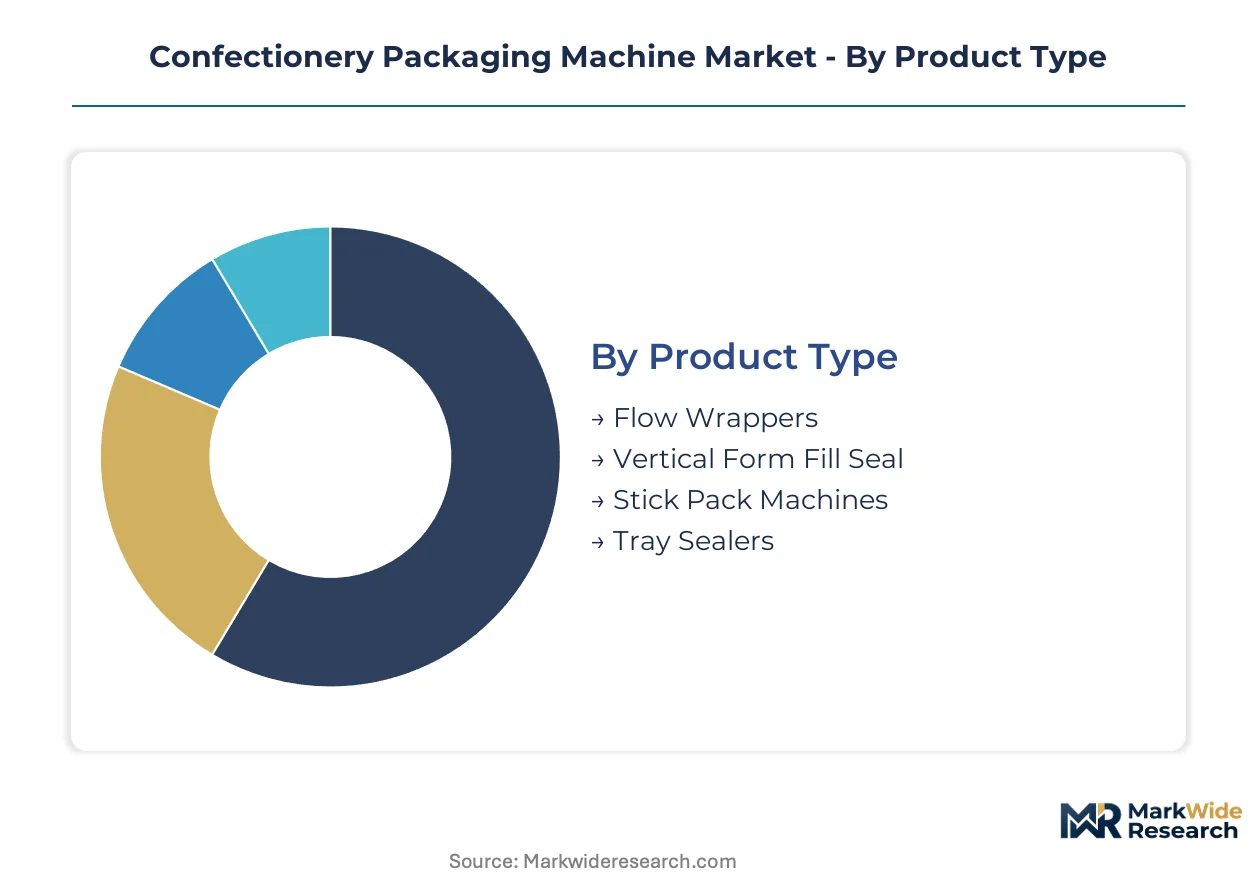
Packaging machine segmentation reveals distinct integration patterns across confectionery operations. Standalone units serve artisan producers with seasonal demand fluctuations, while synchronized line configurations dominate multinational chocolate brands seeking continuous throughput optimization.
Product Type:
Standalone machines predominate in small-batch artisan operations, whereas integrated forming-filling-sealing sequences anchor high-volume chocolate manufacturing facilities.
- Flow Wrappers:Electromechanical systems employing servo-driven motion control to enclose bar and countline formats in continuous film webs. German precision engineering clusters around Stuttgart supply these systems to multinational confectionery brands seeking synchronized line integration for reduced changeover downtime.
- Vertical Form Fill Seal:Systems that form bags from flat rollstock, fill with product, and seal in vertical orientation for granular or piece candy. Demand concentrates in Japan where high-speed wrapping technologies serve premium chocolate assortments requiring delicate handling protocols and minimal product damage.
- Stick Pack Machines:Narrow-format vertical systems producing single-serve sachets for powdered candy and drinking chocolate.
- Tray Sealers:Heat-sealing equipment for rigid containers in gift confectionery and artisan applications where presentation standards justify precision-oriented slower throughput.
Flow wrappers lead volumes today; vertical form fill seal configurations are gaining share fastest among regional candy producers scaling automated operations.
End User:
Capital deployment intensity varies sharply across end-user categories, with chocolate manufacturers outspending other segments on integrated line configurations.
- Chocolate Manufacturers:Producers of bar, countline, and premium assortment formats requiring hygienic washdown-compatible equipment with FDA food contact material compliance. Italy's packaging machinery builders specialize in high-speed wrapping for these manufacturers serving EU and export markets with stringent machinery safety directive requirements.
- Candy Producers:Manufacturers of hard candy, gummies, and chewy formats with diverse viscosity and temperature handling needs. Swiss and Belgian artisan producers drive aftermarket service unbundling here, replacing fixed annual contracts with on-demand technician dispatch for seasonal production peaks.
- Snack Food Companies:Cross-category producers requiring format flexibility across confectionery and savory applications.
- Bakery Product Lines:Integrated dessert and sweet baked goods operations with overlapping packaging specifications.
Chocolate manufacturers dominate capital expenditure; candy producers are expanding automated packaging most aggressively among mid-tier regional brands.
Technology:
Automation depth determines labor substitution economics and regulatory compliance architecture across installation bases.
- Automatic:Fully servo-driven systems with programmable logic controllers and vision inspection maintaining seal integrity across continuous production cycles. EU machinery safety directives mandating interlocked guarding and emergency stop protocols accelerate replacement of legacy equipment toward these configurations.
- Robotic:Articulated arm systems with vision-guided pick-and-place capabilities penetrating premium chocolate assortments where irregular shapes previously required manual loading.
- Semi-Automatic:Hybrid configurations requiring operator intervention for product loading or changeover sequences.
- Manual:Operator-dependent equipment surviving in micro-batch artisan operations with sub-thousand unit hourly throughput requirements.
Automatic systems anchor installed base volumes; robotic technology segments are climbing the fastest as vision capabilities mature for irregular premium shapes.
Packaging Type:
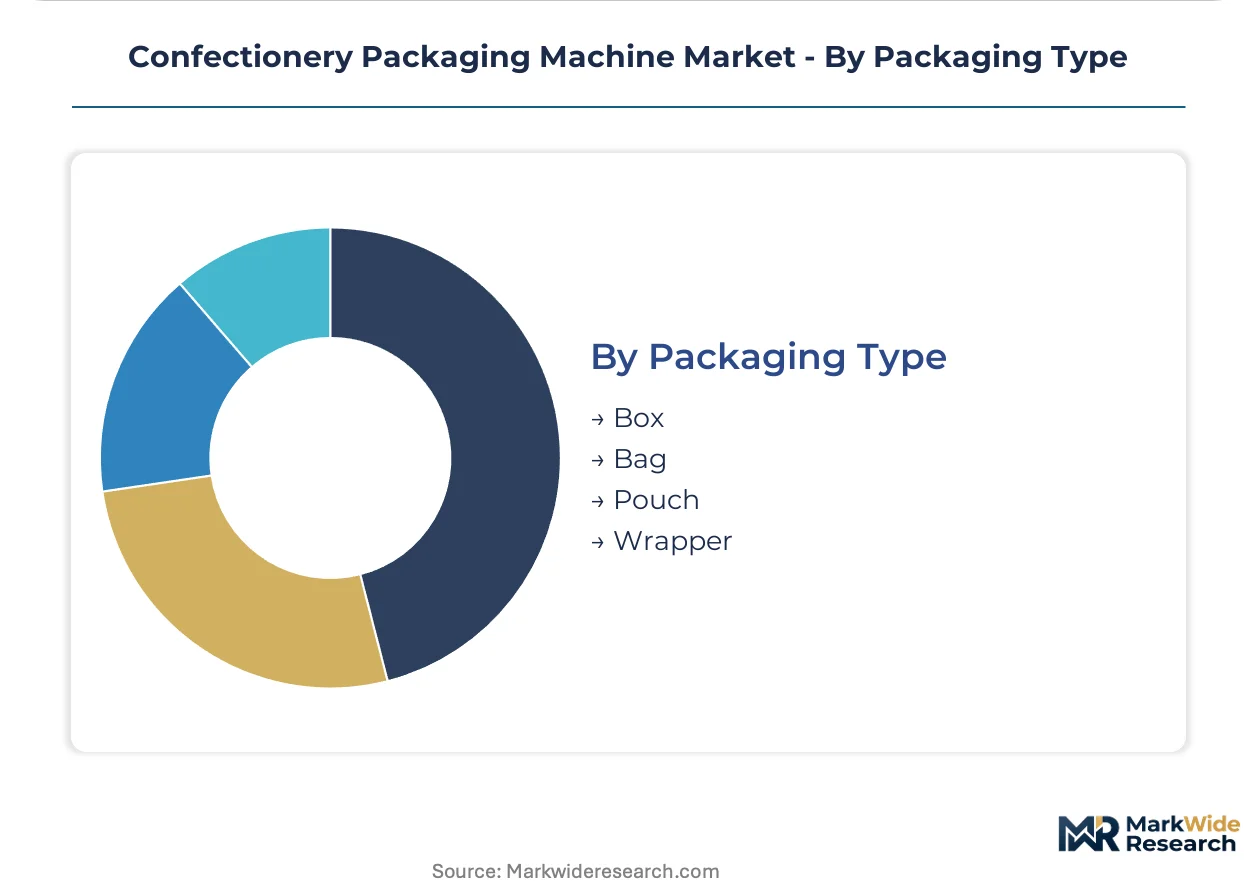
Material format selection increasingly reflects extended producer responsibility frameworks and recyclability thresholds rather than purely functional specifications.
- Wrapper:Primary film enclosures for individual confectionery units, with heat-sealing systems adapting to thinner film gauges mandated by EU packaging waste regulations. REACH substance restrictions on per- and polyfluoroalkyl substances are eliminating fluoropolymer coatings from seal jaw surfaces, forcing ceramic and plasma-treated metal redesigns.
- Pouch:Flexible stand-up or flat formats for multi-serve and resealable applications. Mono-material pouch demand is expanding most quickly as confectionery brands preempt supply chain disruption from evolving recyclability mandates.
- Bag:Larger-format flexible containers for bulk and club retail channels.
- Box:Rigid paperboard formats for gift assortments and premium presentation requirements.
Wrapper formats dominate unit volumes today; pouch configurations are expanding most quickly as brands transition toward recyclable mono-material structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Confectionery packaging machinery traces its industrial lineage to nineteenth-century Swiss and German chocolate houses that mechanized foil wrapping for mass-produced tablet bars. Equipment manufacturing subsequently clustered around precision engineering centers in Central Europe and Japan, with contemporary demand patterns reflecting these historical production geographies.
Germany
Stuttgart and Munich anchor Europe's densest concentration of packaging systems integrators, supplying multinational chocolate brands with synchronized forming-filling-sealing lines. EU machinery safety directives mandating interlocked guarding and emergency stop protocols accelerate replacement cycles among export-oriented fabricators. Baden-Württemberg's precision engineering corridor hosts specialized servo-drive component suppliers that feed regional machine builders.
Italy
Emilia-Romagna's packaging machinery district specializes in high-speed wrapping technologies for premium chocolate assortments requiring delicate handling protocols. REACH substance restrictions on per- and polyfluoroalkyl substances force immediate redesigns of heat-sealing surfaces toward ceramic alternatives among Bologna-area equipment manufacturers. Parma's food technology cluster converges confectionery processing and packaging expertise within tight geographic proximity.
Japan
Kanto region demand concentrates around Tokyo-Osaka industrial corridors where domestic chocolate brands deploy automated lines for seasonal gift production peaks. METI industrial standards for food processing machinery influence hygienic design specifications across regional equipment output. Nagoya's automation engineering base supplies vision-guided robotic handling systems for irregular premium shapes.
United States
Midwestern confectionery manufacturers expand automated packaging capacity to meet FDA food contact notification requirements for laminate compositions in US-bound production. Chicago-area systems integrators retrofit legacy equipment with washdown-compatible architectures for allergen control compliance. Pennsylvania's historic chocolate production belt drives aftermarket service demand for seasonal capacity scaling.
India
Maharashtra and Gujarat host the fastest-expanding regional demand as domestic chocolate consumption growth intersects with FSSAI food safety enforcement among mid-tier confectionery brands. Mumbai-Pune industrial corridor attracts European packaging machinery vendors establishing localized service presence. Regional equipment procurement concentrates on entry-level flow wrapping systems for countline format scaling.
Confectionery Packaging Machine Market Vendor Landscape
The competitive structure tilts toward diversified industrial conglomerates with cross-sector packaging expertise. Equipment manufacturing exhibits moderate concentration, with top-tier players commanding integrated line contracts while mid-market specialists capture standalone machine segments. Two strategic archetypes dominate: precision-engineering heritage firms leveraging pharmaceutical packaging DNA, and diversified process technology groups anchoring positions through aftermarket service networks. Competitive moves center on modular platform standardization and geographic service density expansion rather than pure capacity races.
Among diversified process technology groups, GEA Group and Krones AG exemplify the aftermarket-anchored archetype, occupying positions where extensive service networks spanning major candy production regions reinforce equipment specification decisions. Syntegon Technology represents the precision-engineering heritage model, sitting within a competitive tier where pharmaceutical packaging DNA transfers to hygienic confectionery system design. These three entities anchor the competitive landscape without exhausting its structural variety.
| Leading Market Players |
|---|
| Syntegon Technology |
| GEA Group |
| IMA Group |
| MULTIVAC |
| Cama 1 S.p.A. |
| Coesia Group |
| FUJI Machinery |
| Tetra Pak |
| Krones AG |
| Others |
Supply Flow & Price Mechanics
EU machinery safety directives mandating interlocked guarding and emergency stop protocols force confectionery manufacturers toward certified equipment configurations, compelling supply chains to absorb compliance engineering costs and compressing margin structures for non-certified fabricators.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates equipment procurement, with premium tiers commanding substantial markups for FDA-validated washdown architectures and integrated line synchronization. Price differentiation hinges on certification grade and after-sales service bundling, with EU CE-marked and US FDA-compliant systems sitting at the premium extreme. Cost compression in mid-tier configurations is intensifying because regional manufacturers in India and Southeast Asia are scaling automated flow wrapping capacity. Artisan chocolate producers in Switzerland and Belgium exhibit highest price sensitivity due to seasonal utilization patterns, while multinational brands in Germany and Japan demonstrate lowest sensitivity given continuous throughput requirements.
Supply Chain Analysis
Grade 304 and 316 stainless steel supply rests on German and Japanese specialty metal producers, while servo-drive motion control components draw from concentrated Japanese and German automation engineering clusters. Ceramic seal jaw materials and plasma-treated metal surfaces are gaining share as REACH substance restrictions eliminate fluoropolymer alternatives. Single-source vulnerability in precision motion control components creates structural supply chain risk for high-speed wrapping machine builders. Distribution runs through direct OEM sales for integrated line contracts and specialized distributor networks for standalone equipment serving mid-tier regional producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Confectionery packaging machinery functions as a regulatory compounder where EU extended producer responsibility frameworks for packaging waste are accelerating equipment replacement cycles across export-bound production facilities.
For Market Incumbents: Lock in aftermarket service density by expanding on-demand technician dispatch networks across seasonal production peaks in Belgium and Switzerland. Prioritize backward integration into ceramic seal jaw manufacturing to preempt PFAS coating supply disruption. Defensive positioning against emerging robotic handling entrants requires embedding AI vision inspection as standard configuration rather than premium upgrade.
For New Entrants and Emerging Players: Begin with entry-level flow wrapping systems targeting Maharashtra and Gujarat confectionery brands scaling automated operations under FSSAI enforcement pressure. India's underpenetrated mid-tier segment offers white-space opportunity for standardized equipment configurations with localized service presence. Direct sales partnerships with Mumbai-Pune industrial corridor distributors provide lowest-friction go-to-market pathway.
For Investors and Strategic Acquirers: Asymmetric upside sits with precision-engineering heritage firms possessing pharmaceutical packaging DNA transferable to hygienic confectionery applications. Five-to-ten year viability favors equipment manufacturers with embedded regulatory certification capabilities and software-configurable platform architectures. Watch for inflection signals in biodegradable laminate heat-sealing temperature uniformity breakthroughs that would unlock throughput scaling for sustainable packaging formats.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Platform Standardization | Reduces changeover downtime for multinational chocolate brands operating synchronized forming-filling-sealing lines. |
| Backward Integration into Servo Components | Mitigates single-source vulnerability from Japanese and German motion control suppliers. |
| PFAS-Free Seal Jaw Redesign | Ensures REACH compliance for European machinery exports while anticipating analogous FDA guidance. |
| Cloud-Based Digital Twin Deployment | Compresses commissioning timelines for mid-sized Italian and Japanese confectionery producers. |
| Localized Service Network Expansion | Captures aftermarket revenue from seasonal capacity scaling in Swiss and Belgian artisan operations. |
Methodological Framework
Bottom-up chocolate manufacturer and candy producer modeling reconciled against top-down packaging machinery production tracking forms the analytical core. Primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and regulatory compliance officers intersect with secondary validation through EU machinery safety directive filings, FDA food contact notifications, customs trade data, and SEC equipment manufacturer disclosures. Triangulation between demand-side capital expenditure patterns and supply-side production capacity ensures consistency across estimation procedures.
Input-output matrices map equipment shipments by product type, automation depth, end-user category, and regional production cluster across the projection horizon. CAGRs derive from segmented growth rate reconciliation against aggregate market expansion. Forecast inputs incorporate stainless steel price volatility indices, servo-drive component lead time fluctuations, and regulatory compliance timeline assumptions for laminate material approvals.
Several conditions sit outside the modeled scope, including geopolitical trade disruption scenarios, abrupt REACH substance restriction expansions, and breakthroughs in biodegradable film heat-sealing technology. Forecasts reflect documented assumptions about regulatory enforcement intensity and substitution elasticity between equipment tiers. A small set of named triggers warrants ongoing watch: Japanese servo-drive export restrictions, EU extended producer responsibility framework implementation timelines, and FSSAI inspection capacity expansion in India.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Liquid Capsule Filling Machines Market
Packaging Machinery
Global Tissue Paper Converting Machines Market
Packaging Machinery
Global Filling Machines Market
Packaging Machinery
Vertical Bagging Machine Market
Packaging Machinery
Paper Napkin Converting Lines Market
Packaging Machinery
Vacuum Chamber Packaging Machines Market
Packaging Machinery
Bagging Machine Market
Packaging Machinery
Blown Film Extrusion Machine Market
Packaging Machinery
Pallet Strapping Machines Market
Packaging Machinery
Sleeve Wrapping Machine Market
Packaging Machinery
Food Powder Packaging Machine Market
Packaging Machinery
Folding Gluing Machines Market
Packaging Machinery
Shrink - Sleeve Wrapping Machinery Market
Packaging Machinery
Asia-Pacific Pharmaceutical Packaging Machinery Market
Packaging Machinery
Corrugated Box Machines Market
Packaging Machinery
Package Closing Machines Market