
 Beverage Can Seamers Market | 2026-2036
Beverage Can Seamers Market Size, Share, and Industry Trends Forecast 2026-2036
Beverage Can Seamers Market Outlook
Contract packagers is unwinding share from captive beverage manufacturer installations as craft and regional brands outsource canning operations. Krones leverages its integrated line engineering to dominate European high-speed installations. JBT anchors North American aftermarket service networks for legacy seamer fleets. Pneumatic Scale Angelus specializes in rotary seamer architectures for carbonated soft drink producers.
Beverage can seamers are precision closing machines that form hermetic double seams between can bodies and ends, typically operating at speeds from 100 to 3,000 cans per minute using rotary or inline mechanical action. The equipment ensures internal pressure retention for carbonated products and oxygen exclusion for shelf-stable beverages through controlled chuck and roller geometries. Mechanical sealers occupy the largest installed base due to proven reliability in high-volume aluminum lines, while ultrasonic sealers represent the fastest-growing technology segment as thin-wall can designs demand non-contact sealing. Retrofits and upgrades command concentrated margin pools as OEMs seek to extend asset life without greenfield capital deployment.
FDA regulates food-contact surfaces and lubricant migration limits for seamers handling alcoholic and non-alcoholic beverages in the United States. EPA aluminum recycling mandates and OSHA mechanical guarding standards shape equipment specification sheets and factory acceptance protocols. Stakeholders must monitor seamer technology roadmaps against evolving can lightweighting targets and deposit-return scheme expansions across multiple jurisdictions.
Market Dynamics
Aluminum can lightweighting programs are forcing seamer manufacturers to recalibrate chuck and roller geometries for thinner wall specifications while maintaining hermetic integrity at high speeds.
Growth Catalysts
- Deposit-return scheme expansion:Germany's DRS implementation and similar frameworks across Scandinavia are accelerating aluminum can circulation rates. This mandates higher-throughput seamer installations to handle return-loop volumes.
- Craft brewery automation:Small-scale beverage producers in the United States are purchasing compact rotary seamers to bring canning in-house rather than relying on mobile canning services.
- EPA recycling mandates:Aluminum recovery targets are tightening scrap quality specifications, pushing beverage manufacturers toward precision seamers that minimize leaker rates and contamination.
Market Restraints
- Stainless steel input volatility:Seamer frame and tooling fabrication depends on austenitic grades subject to nickel price swings, compressing OEM margin predictability.
- German supply concentration:Precision machining capabilities for high-speed seamer chucks cluster in Baden-Württemberg, creating single-source vulnerability for European line builders.
- Ultrasonic sealing technical limits:Non-contact seam formation remains incompatible with embossed can end designs used in premium beverage segments, constraining technology migration.
Strategic Opportunities
- India beverage packaging:FSSAI food-contact regulations are formalizing, creating first-mover advantage for seamer OEMs establishing local assembly and service infrastructure.
- Aseptic canning convergence:Integration of hydrogen peroxide sterilization tunnels with rotary seamers opens shelf-stable dairy and functional beverage applications previously bottled.
- Outcome-based service contracts:Fleet operators are unbundling seamer maintenance from capital purchases, enabling recurring revenue streams for technical service providers.
Industry Challenges
- Double-seam inspection technician scarcity:Visual and teardown-based quality verification requires specialized training that vocational programs have not scaled to meet installation growth.
- Legacy mechanical control retrofit complexity:Analog seamer fleets with cam-driven timing systems resist Industry 4.0 sensor integration without extensive mechanical redesign.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beverage Can Seamers Market |
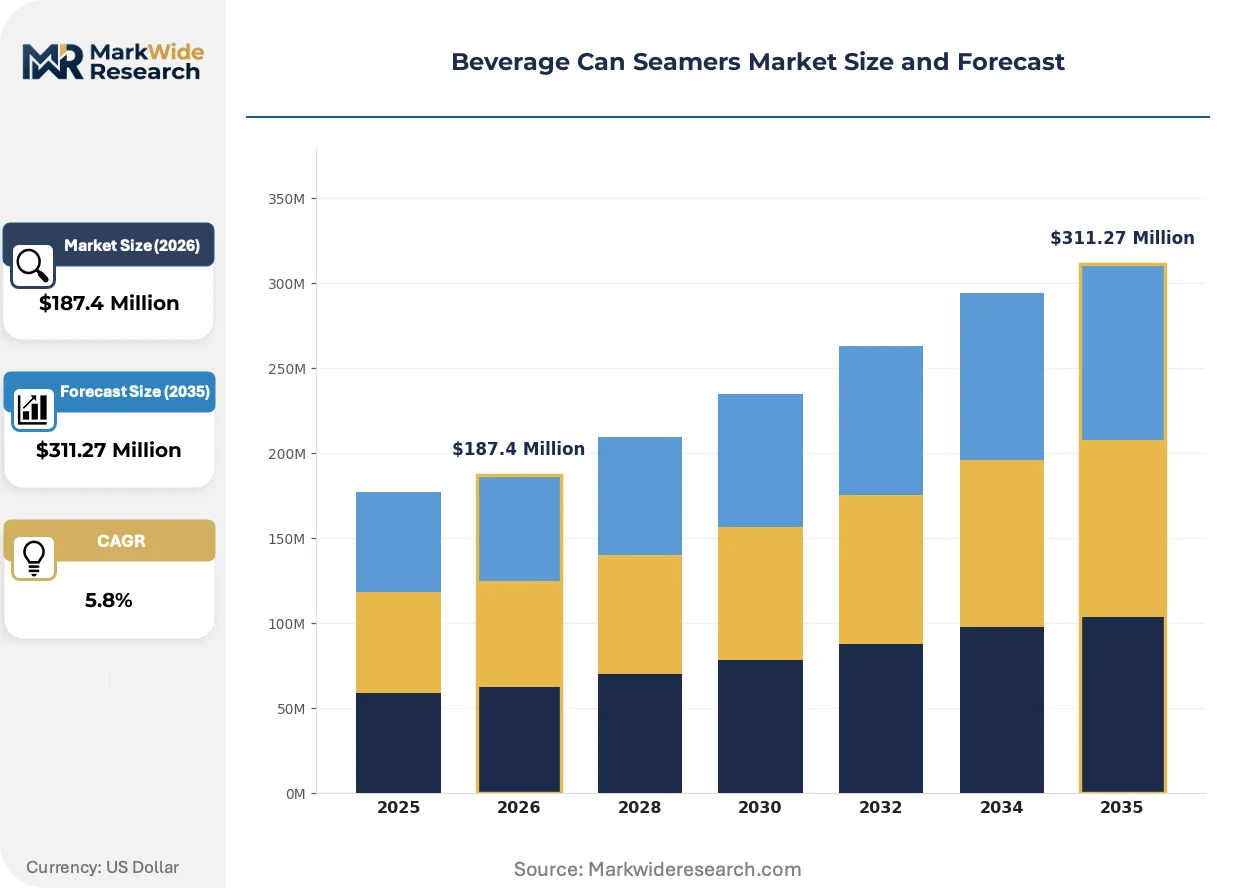
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aerosol Can Seamers, Beverage Can Seamers, Food Can Seamers, Specialty Can Seamers Technology: Mechanical Sealers, Ultrasonic Sealers, Pneumatic Sealers, Manual Sealers End User: Beverage Manufacturers, Food Processors, Contract Packagers, OEMs Installation: On-site Installation, Off-site Installation, Retrofits, Upgrades |
| Companies Covered | Krones, ZACMI, Ferrum Canning Technology, Toyo Seikan, Ezquerra Group, Pneumatic Scale Angelus, JBT, Swiss Can Machinery AG, CFT Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beverage Can Seamers Market Strategic Shifts
Seamer architecture is pivoting from purely mechanical systems toward hybrid electromechanical platforms that enable real-time parameter adjustment without tooling changeovers.
Ultrasonic sealing technology is displacing mechanical double-seam formation in thin-wall aluminum applications below 0.008 inch body stock. Japanese beverage producers are piloting these systems for sensitive flavor profiles where metal-to-metal contact risks contamination. The technology is displacing traditional roller-based seamers in premium segments where can integrity margins are widest.
REACH substance restrictions on chromium-based surface treatments are forcing European seamer manufacturers to adopt tungsten carbide coatings and plasma-nitrided tooling. Ferrum Canning Technology and Krones have reformulated their roller metallurgy to eliminate hexavalent chrome passivation. German OEMs are now exporting this compliant tooling specification to North American craft brewery installations.
Contract packager procurement now dominates mid-speed seamer demand as brand owners shed captive canning assets. Regional beverage companies in Texas and Colorado are outsourcing to third-party canning lines rather than depreciating owned equipment. This concentration is visible most acutely in the Rocky Mountain corridor where mobile canning fleets have given way to permanent contract facilities.
Beverage Can Seamers Market Segmentation
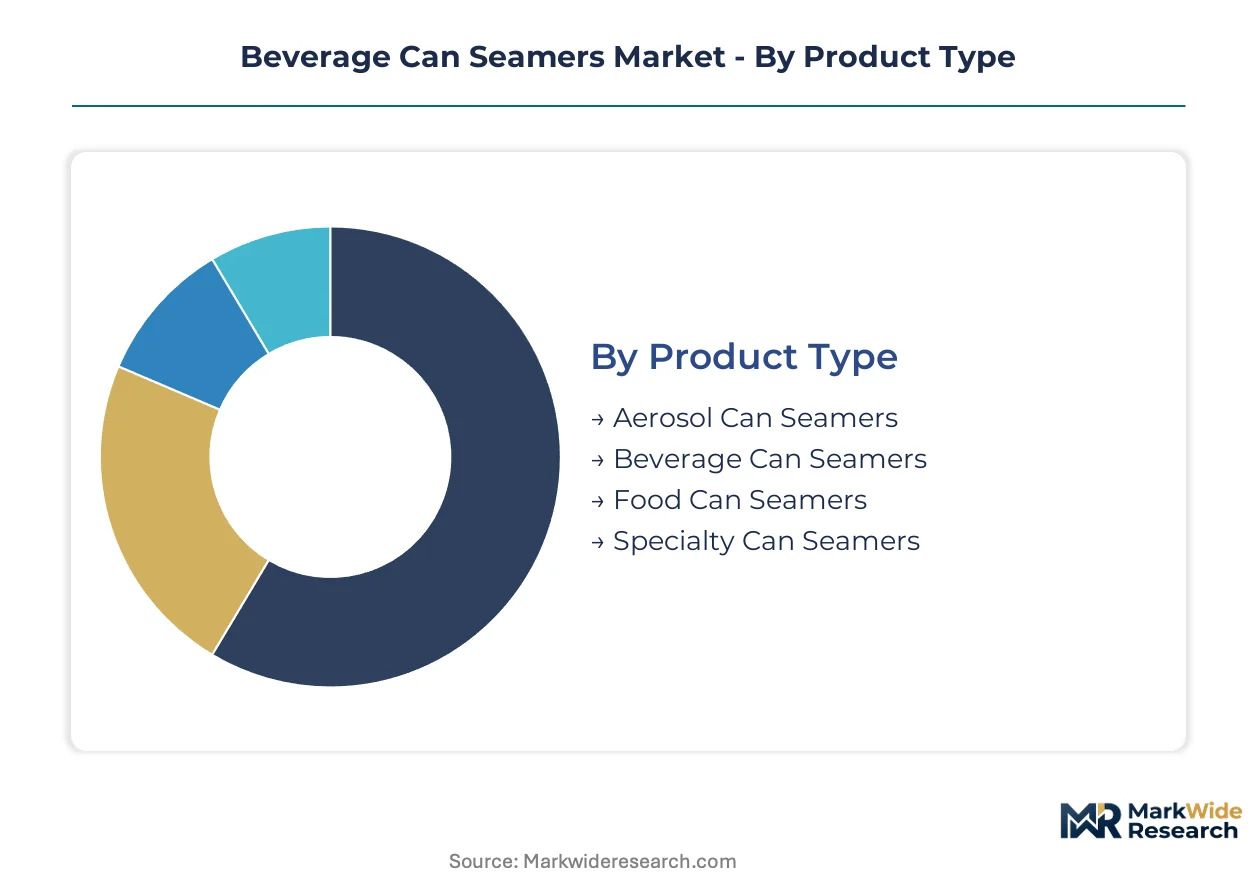
Seamer procurement patterns diverge sharply across customer types and installation contexts. Contract packagers prioritize throughput flexibility over brand-specific customization, while beverage manufacturers optimize for line integration. Technology choice increasingly hinges on can lightweighting compatibility rather than legacy reliability metrics.
Product Type:
Aerosol can seamers face acute substitution pressure from bag-on-valve systems in personal care applications, forcing equipment suppliers to defend their installed base through aftermarket service bundling.
- Beverage Can Seamers:Rotary and inline architectures seal aluminum bodies to ends at speeds from 100 to 3,000 cans per minute. Demand concentrates in Germany and the United States where craft brewery automation and deposit-return scheme expansions drive capacity additions.
- Food Can Seamers:Heavier-gauge steel handling distinguishes these units from beverage variants, with chuck geometries calibrated for thicker wall specifications. Procurement clusters among vegetable and soup processors in the Midwestern United States facing FDA food-contact surface compliance deadlines.
- Aerosol Can Seamers:Pressure-rated double-seam formation for propellant containment. European cosmetic brands are migrating toward alternative dispensing formats.
- Specialty Can Seamers:Configured for irregular geometries including tapered and shaped containers. Premium spirits producers in Scotland and Kentucky represent the primary demand pocket.
Beverage can seamers retain volume leadership; ultrasonic-enabled beverage seamers hold the steepest expansion curve.
Technology:
Cost tier stratification separates capital-intensive rotary systems from entry-level manual units, with pneumatic architectures occupying the contested mid-market where contract packagers optimize for throughput per square foot.
- Mechanical Sealers:Cam-driven roller systems dominate high-volume aluminum lines through proven hermetic integrity at sustained operating speeds. Germany's Baden-Württemberg machining cluster supplies precision chucks to Krones and Ferrum Canning Technology installations across European beverage corridors.
- Ultrasonic Sealers:Non-contact seam formation via high-frequency vibration eliminates metal-to-metal contamination risks. Japanese beverage producers pilot these systems for flavor-sensitive applications where traditional roller contact alters product chemistry.
- Pneumatic Sealers:Compressed-air actuation enables rapid format changeovers without mechanical retooling. Regional contract packagers in Texas and Colorado favor these units for multi-SKU flexibility.
- Manual Sealers:Hand-cranked or foot-pedal operation for prototyping and micro-batch production. Craft brewery startups in the Rocky Mountain corridor purchase these as bridge equipment before scaling to automated lines.
Mechanical sealers command the largest installed base; ultrasonic sealers are gaining share fastest in thin-wall aluminum applications.
End User:
Customer type determines procurement cadence and service contract structure, with OEMs purchasing for integration into complete line sales while contract packagers unbundle maintenance from capital acquisition.
- Beverage Manufacturers:Captive canning operations at multinational soft drink and brewing conglomerates. These buyers specify integrated line engineering from Krones and JBT with multi-year aftermarket agreements.
- Contract Packagers:Third-party canning service providers serving craft and regional brands without owned assets. Rocky Mountain corridor facilities are displacing mobile canning fleets with permanent high-speed installations.
- Food Processors:Canned vegetable, soup, and ready-meal producers with seasonal production peaks. These users prioritize retort compatibility and extended shelf-life validation protocols.
- OEMs:Line integrators purchasing seamers for incorporation into complete packaging systems. German and Italian engineering houses dominate this procurement channel for export to emerging markets.
Contract packagers are expanding procurement most rapidly; beverage manufacturers retain the largest cumulative fleet value.
Installation:
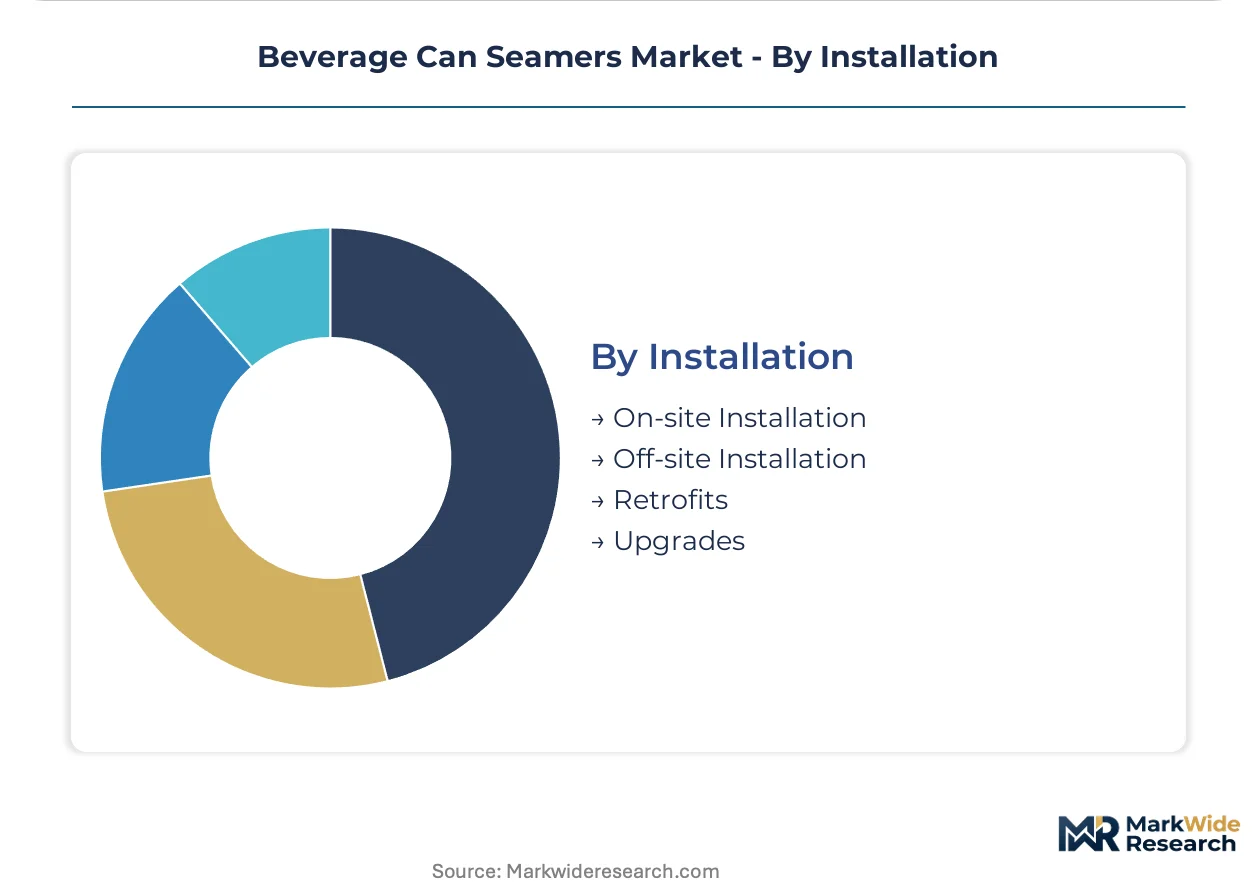
Volume trajectory favors retrofits over greenfield deployment as capital constraints extend asset life cycles and OEMs develop modular upgrade kits for legacy mechanical control systems.
- On-site Installation:New equipment commissioning at greenfield or expansion facilities. German beverage producers favor this approach for integrated line synchronization with Krones engineering.
- Off-site Installation:Pre-commissioning at OEM or integrator facilities before shipment. This method reduces production downtime for brownfield replacements in high-utilization plants.
- Retrofits:Control system and tooling upgrades to analog seamer fleets. JBT anchors North American aftermarket networks for legacy mechanical installations resisting Industry 4.0 sensor integration.
- Upgrades:Speed enhancement kits and lightweighting compatibility modifications. EPA aluminum recycling mandates are tightening scrap quality specifications, pushing precision seamer investments that minimize leaker rates.
Retrofits represent the largest revenue pool; upgrades are climbing fastest as lightweighting programs force chuck and roller geometry recalibration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German seamer OEMs export precision tooling to craft brewery installations across the United States and Japan. This transatlantic equipment corridor channels Baden-Württemberg machining expertise into North American aluminum canning lines. Japanese beverage producers simultaneously import European ultrasonic sealing technology for thin-wall applications.
United States
Craft brewery automation in Colorado and Texas drives compact rotary seamer procurement as regional brands abandon mobile canning services. EPA aluminum recycling mandates tighten scrap quality specifications, pushing manufacturers toward precision equipment that minimizes leaker rates. The Rocky Mountain corridor hosts permanent contract packager facilities displacing temporary canning fleets.
Germany
Deposit-return scheme implementation accelerates aluminum can circulation rates, mandating higher-throughput seamer installations for return-loop volumes. REACH substance restrictions on chromium-based surface treatments force roller metallurgy reformulation toward tungsten carbide coatings. Baden-Württemberg's precision machining cluster supplies chuck components to Krones and Ferrum Canning Technology installations.
Japan
Flavor-sensitive beverage producers pilot ultrasonic sealing systems where traditional roller contact risks product chemistry alteration. METI industrial standards guide food-contact surface specifications for alcoholic and non-alcoholic canning operations. Tokyo-Osaka manufacturing corridors integrate these non-contact seamers into premium packaging lines for sensitive flavor profiles.
India
FSSAI food-contact regulations formalization creates first-mover positioning for seamer OEMs establishing local assembly infrastructure. Central government PLI scheme incentives support domestic packaging machinery manufacturing scale-up. Maharashtra and Gujarat industrial zones attract technical service providers targeting outbound beverage export capacity.
United Kingdom
Scotch whisky and premium spirits producers in Scotland commission specialty seamers for irregular tapered can geometries. UK Environment Agency packaging waste regulations align with EU deposit-return frameworks post-Brexit transition. London contract packagers serve craft beverage startups scaling beyond manual seamer prototyping.
Beverage Can Seamers Market Competitive Environment
Listed leaders compete with private specialists across engineering depth and aftermarket service reach. The vendor base stratifies into integrated line engineers, standalone seamer fabricators, and regional service networks. Three archetypes dominate: German precision machiners with captive tooling supply, North American aftermarket service anchors for legacy fleets, and Japanese technology licensors for ultrasonic sealing. Competitive moves concentrate on modular retrofit kits for analog control systems and outcome-based maintenance contracts unbundled from capital sales.
Among German-based precision engineers, Krones AG and Ferrum Canning Technology GmbH exemplify the integrated tooling-and-equipment archetype. JBT Corporation represents North American aftermarket service concentration. These three occupy positions spanning high-speed line integration, precision chuck fabrication, and legacy fleet technical support respectively.
| Leading Market Players |
|---|
| Krones |
| ZACMI |
| Ferrum Canning Technology |
| Toyo Seikan |
| Ezquerra Group |
| Pneumatic Scale Angelus |
| JBT |
| Swiss Can Machinery AG |
| CFT Group |
| Others |
Value Chain & Pricing Dynamics
REACH substance restrictions on chromium-based surface treatments gate both European seamer tooling qualification and price differentiation between compliant and legacy metallurgy tiers. OEMs bearing tungsten carbide coating certification capture margin premiums while uncertified fabricators face buyer disqualification from German beverage line procurement.
Pricing Analysis
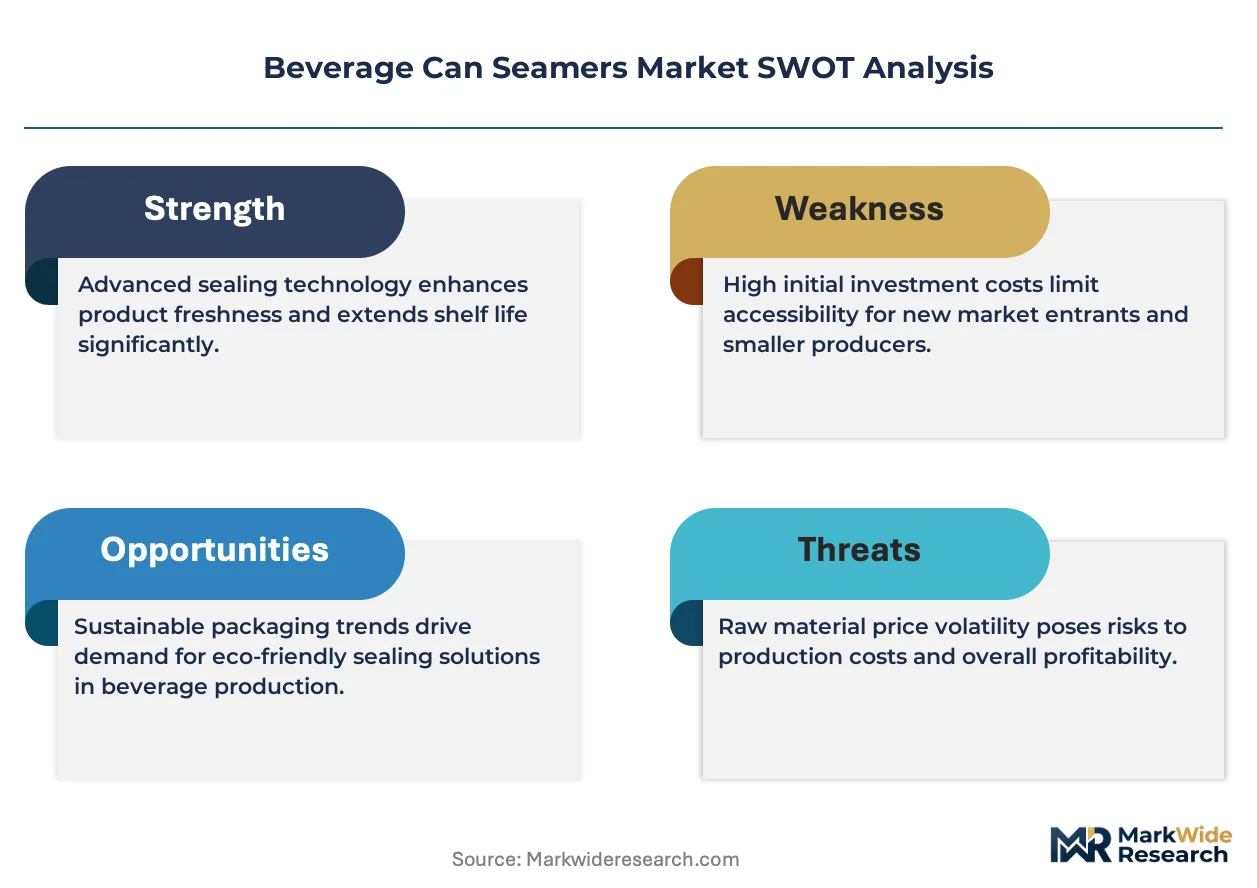
Current-generation ultrasonic sealers command substantial premiums over mechanical roller systems, while prior-generation pneumatic architectures face price erosion in the contract packager segment. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated high-speed rotary units from mid-tier pneumatic flex-lines and entry-level manual seamers. Price differentiation hinges on certification tier and after-sales service bundling. Cost compression in standard-tier pneumatic equipment is intensifying because regional contract packagers in Texas and Colorado prioritize throughput-per-square-foot metrics over brand heritage.
Supply Chain Analysis
Container availability constraints on Hamburg-to-Houston trade lanes inflate inbound logistics costs for German precision chuck components. Manufacturing concentration centers on Germany, Japan, and the United States, with Baden-Württemberg's machining cluster feeding Krones and Ferrum Canning Technology. Raw material dependencies draw from austenitic stainless steel grades, tungsten carbide feedstock, and plasma-nitriding gas supplies. Single-source vulnerability in German precision machining creates structural risk for European line builders. Distribution runs through OEM-direct channels for integrated line sales and regional service networks for aftermarket retrofit kits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Seamer technology platforms are approaching an interoperability inflection where hybrid electromechanical architectures enable real-time parameter adjustment without mechanical retooling, reshaping competitive moats around software-enabled service contracts rather than hardware fabrication scale.
For Market Incumbents: Shield installed base value by embedding predictive maintenance algorithms into legacy mechanical fleets before ultrasonic sealing displaces roller-based architectures in thin-wall applications. Deepen backward integration into Baden-Württemberg precision machining capabilities to secure chuck supply against single-source vulnerability. Prioritize certification investment for REACH-compliant tungsten carbide tooling to maintain German beverage line access. For New Entrants and Emerging Players: Differentiate on outcome-based service contracts unbundled from capital sales, targeting contract packagers in the Rocky Mountain corridor where permanent facilities are displacing mobile canning fleets. Penetrate India's Maharashtra and Gujarat industrial zones before FSSAI food-contact regulations fully formalize, establishing local assembly infrastructure ahead of multinational OEM lock-in. Pursue licensing arrangements with Japanese ultrasonic technology holders rather than mechanical roller replication. For Investors and Strategic Acquirers: EPA aluminum recycling mandate implementation reshapes the acquisition landscape toward precision seamer OEMs with demonstrable leaker-rate minimization capabilities. Long-term viability favors vendors with hybrid electromechanical platforms capable of spanning current mechanical reliability demands and future ultrasonic migration. Target acquisition archetypes include regional service networks with captive retrofit kit distribution and ultrasonic technology licensors with flavor-sensitive beverage validation. Watch for deposit-return scheme expansion announcements across Scandinavian jurisdictions as volume inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Retrofit Kit Development | Extends asset life for JBT-served North American legacy fleets without greenfield capital deployment. |
| Ultrasonic Technology Licensing | Enables Japanese beverage producers to pilot non-contact sealing for flavor-sensitive premium applications. |
| Local Assembly Infrastructure | Positions first-mover advantage in India before FSSAI regulations fully formalize compliance requirements. |
| Outcome-Based Service Contracts | Unbundles maintenance from capital purchases for contract packagers prioritizing throughput flexibility. |
| REACH-Compliant Tooling Reformulation | Eliminates hexavalent chrome passivation for continued German beverage line OEM qualification. |
Study Parameters
A spread of perspectives from plant engineers at beverage manufacturers, procurement leads at contract packagers, aftermarket service directors, and precision machining specialists converged on the working assumptions. Primary interviews combined with secondary validation from FDA food-contact surface guidance documents, EPA aluminum recycling mandate filings, and SEC equipment manufacturer disclosures. Bottom-up installation data triangulated against top-down beverage production volume projections.
Segmentation dimensions modeled span product type, technology generation, end-user archetype, and installation context across the analysis window. CAGRs derived from equipment procurement trajectories correlated with aluminum can lightweighting program timelines and deposit-return scheme implementation schedules. Forecast inputs incorporated chuck geometry recalibration cycles and ultrasonic sealing pilot program expansion patterns.
Forecasts assume regulatory continuity in FDA food-contact surface regimes and EPA recycling mandates; material policy shifts would require re-modeling. Specific risk factors include nickel price volatility affecting stainless steel input costs and REACH substance restriction expansion beyond chromium-based treatments. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Paper Embossing Machine Market
Packaging Machinery
Oil Packing Machine Market
Packaging Machinery
Clamshell Labeling Machines Market
Packaging Machinery
Global Pet Stretch Blow Molding Machines Market
Packaging Machinery
Powder Auger Fillers Market
Packaging Machinery
Box Sealing Machines Market
Packaging Machinery
Global Filling Machines Market
Packaging Machinery
Cling Wrap Machine Market
Packaging Machinery
Cutter-Box Packaging Market
Packaging Machinery
Global Tissue Paper Converting Machines Market
Packaging Machinery
Global Blow Fill Seal Equipment Market
Packaging Machinery
Wicketed Bagging Machines Market
Packaging Machinery
Global Hand Wrapping Machine Market
Packaging Machinery
Tablet Packing Machine Market
Packaging Machinery
Corrugated Box Printer Slotter Machine Market
Packaging Machinery
Corrugated Box Machines Market