
 Straw Machine Market | 2026-2036
Straw Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Straw Machine Market Insights
Buyer concentration across the beverage industry is broadening as regional bottlers and private-label drink manufacturers invest in in-house straw production, fragmenting demand that once flowed to a handful of multinational suppliers. Anhui Wenying Machinery Technology Co., Ltd. leverages its Jiangsu engineering base to dominate domestic fully-automatic lines for paper substrate conversion. Miyazaki Machinery anchors premium precision segments in Japan through tight tolerances on high-speed cutting modules. Tembo Paper competes across European hospitality supply chains with equipment optimized for thin-wall paper straws.
A straw machine forms, cuts, and optionally packages drinking straws from paper webs, biopolymer resins, or alternative compostable substrates, typically operating at speeds between 200 and 800 pieces per minute depending on gauge and material stiffness. The equipment serves beverage packaging converters and foodservice distributors seeking to replace plastic straws with compliant single-use alternatives. Fully automatic systems lead capital deployment among volume beverage producers seeking labor reduction, while high-speed lines capture the fastest expansion as QSR chains tighten throughput requirements. Extrusion technology dominates biopolymer processing, though thermoforming equipment for molded paper pulp straws is gaining traction where fiber-based products must meet hot-liquid durability standards.
FDA food-contact substance notifications shape material approval pathways for U.S. equipment buyers, while the EU's Single-Use Plastics Directive and REACH compliance on additives constrain substrate choices and machine configuration across European sales. China's GB standards for paper products and SAMR food-contact regulations add certification layers for domestic and export-bound machinery. Stakeholders must monitor evolving compostability certification requirements from BPI and TÜV Austria, as these third-party standards increasingly gate procurement decisions by major beverage brands and hospitality distributors.
Market Dynamics
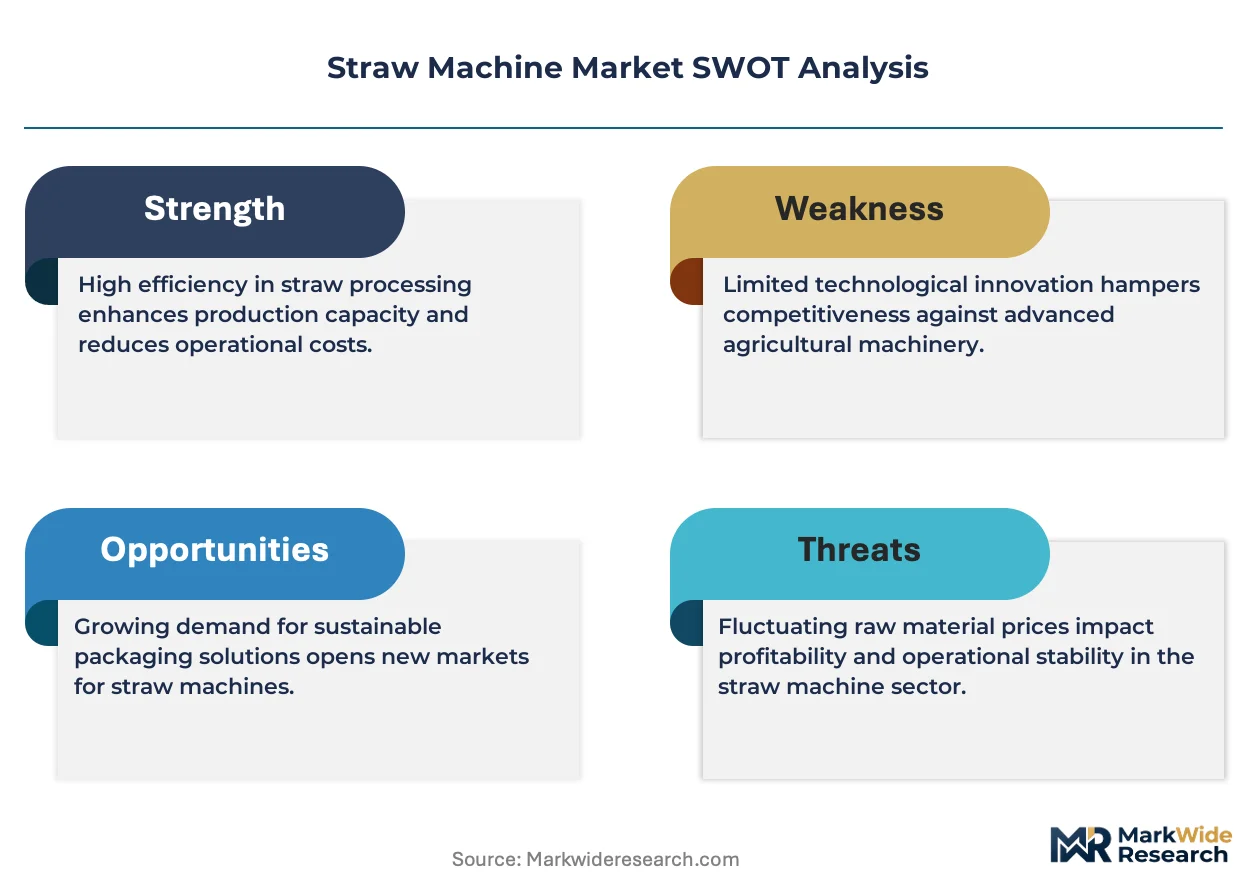
The straw machine sector is reconfiguring around substrate versatility as beverage brands demand equipment capable of switching between paper webs and biopolymer resins without line changeover delays. This technical imperative is compressing supplier lead times and reshaping R&D allocation across machine builders.
Growth Catalysts
- EU Single-Use Plastics Directive:Mandates on single-use plastic elimination are forcing hospitality distributors to retrofit or replace legacy extrusion lines with compostable-substrate systems.
- Hot-liquid durability standards:QSR chains serving coffee and tea are specifying molded paper pulp straw equipment to meet performance thresholds that conventional paper tubes cannot satisfy.
- Jiangsu-Zhejiang cluster concentration:Domestic Chinese machine builders are capturing export orders from Southeast Asian beverage converters seeking lower capital intensity than European or Japanese alternatives.
Market Restraints
- Biopolymer resin price volatility:PLA and PHA feedstock costs fluctuate with corn starch and sugarcane commodity markets, complicating equipment ROI calculations for mid-sized converters.
- Cutting module precision bottlenecks:High-speed lines above 600 pieces per minute require imported servo systems from Japan or Germany, creating supply concentration risk.
- Compostability certification fragmentation:Divergent BPI, TÜV Austria, and OK Compost HOME standards force machine builders to engineer modular certification pathways rather than universal solutions.
Strategic Opportunities
- India beverage packaging expansion:FSSAI plastic phase-out timelines and domestic PLA production scale-up are creating first-mover openings for equipment vendors establishing local service networks.
- Aftermarket retrofit kits:Paper straw conversion modules for existing plastic straw extrusion lines represent a lower-capex entry point for regional bottlers with constrained capital budgets.
- Automated quality inspection integration:Machine vision systems for real-time defect detection in paper straw walls are unifying with forming equipment to reduce downstream rejection rates.
Industry Challenges
- Cross-material process engineering talent:Equipment designers must bridge paper web handling expertise with biopolymer extrusion thermodynamics, a skill intersection rarely found in single-discipline engineering pools.
- Legacy line integration complexity:Beverage packaging converters operating 15-20 year old forming equipment face control system incompatibility when attempting to graft modern servo-driven cutting modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Straw Machine Market |
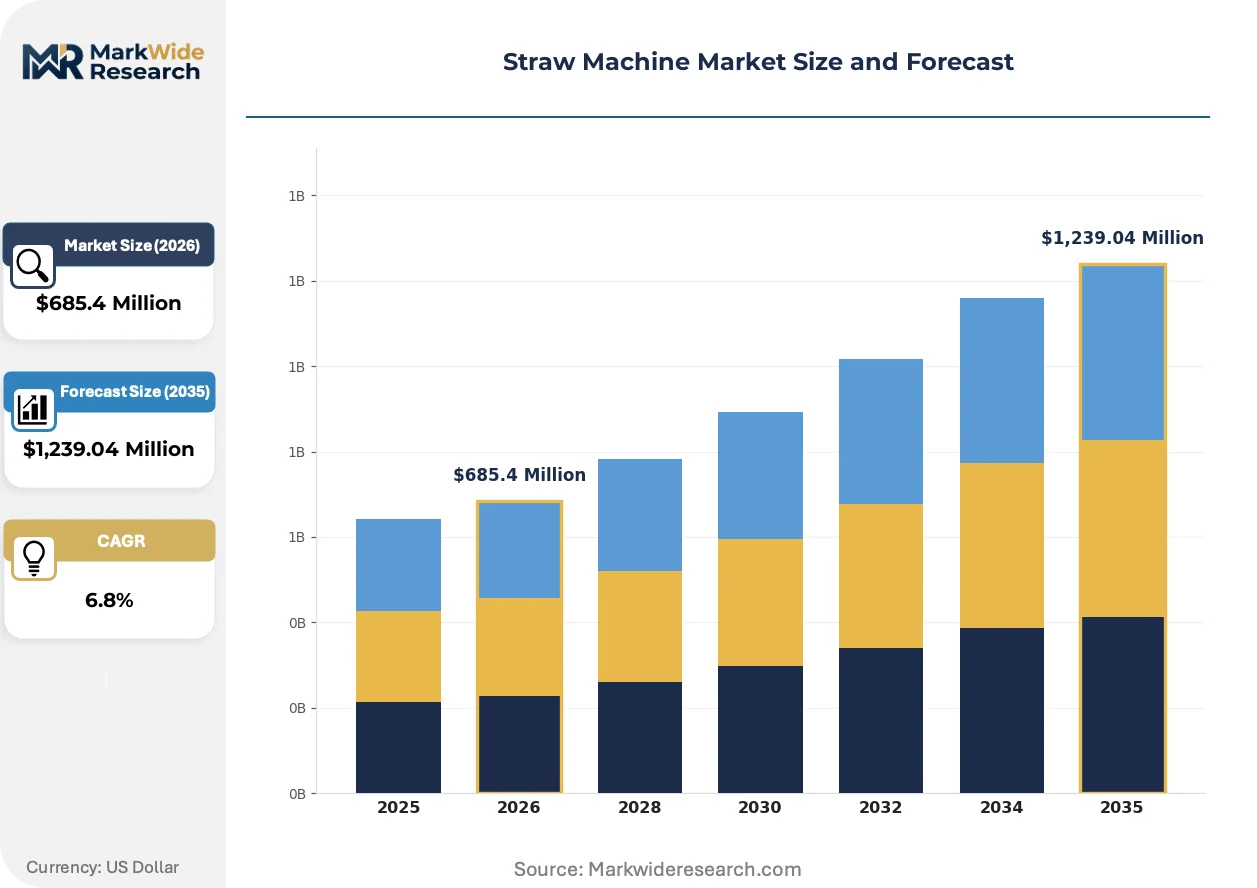
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fully Automatic, Semi Automatic, Manual, High-Speed, Multi-Function Technology: Extrusion, Injection Molding, Thermoforming, Blow Molding, Compression Molding Application: Beverage Industry, Food Packaging, Hospitality Chains, Event Management End User: Manufacturing Units, Packaging Companies, Catering Services, Distributors |
| Companies Covered | Anhui Wenying Machinery Technology Co., Ltd., Unitely Machinery, Henan Top Packing Machinery Co., Ltd., Kunshan Zhiyang Machinery, Kally Machinery, Jain Industries, Miyazaki Machinery, Sankyo Seisakusho, Tembo Paper, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Straw Machine Market Trends and Innovations
Equipment architecture is pivoting from single-substrate specialization toward rapid-changeover platforms. This evolution is compressing product development cycles and forcing component suppliers to standardize interfaces across material categories.
Servo-driven tension control systems are unifying paper web feeding with biopolymer film handling within shared machine frames. Mid-sized regional bottlers in Germany and the United States are piloting these hybrid lines to hedge against substrate cost swings. The technology is unifying what were previously separate equipment categories, reducing floor space requirements and technician training burdens.
REACH compliance on additives and colorants is constraining substrate formulations permitted in EU-bound equipment configurations. Machine builders must now validate entire material-feed pathways rather than isolated contact surfaces. Paper straw producers serving McDonald's and Starbucks European supply chains are responding by specifying additive-free natural fiber grades that simplify compliance documentation.
Regional bottlers are fragmenting procurement patterns that previously consolidated through multinational equipment lessors. Direct purchasing from Chinese and Turkish machine builders is displacing distributor-mediated sourcing in Eastern Europe and Latin America. This channel shift is most visible among private-label beverage manufacturers in Poland and Mexico seeking 25-30% capital cost reductions.
Straw Machine Market Segmentation
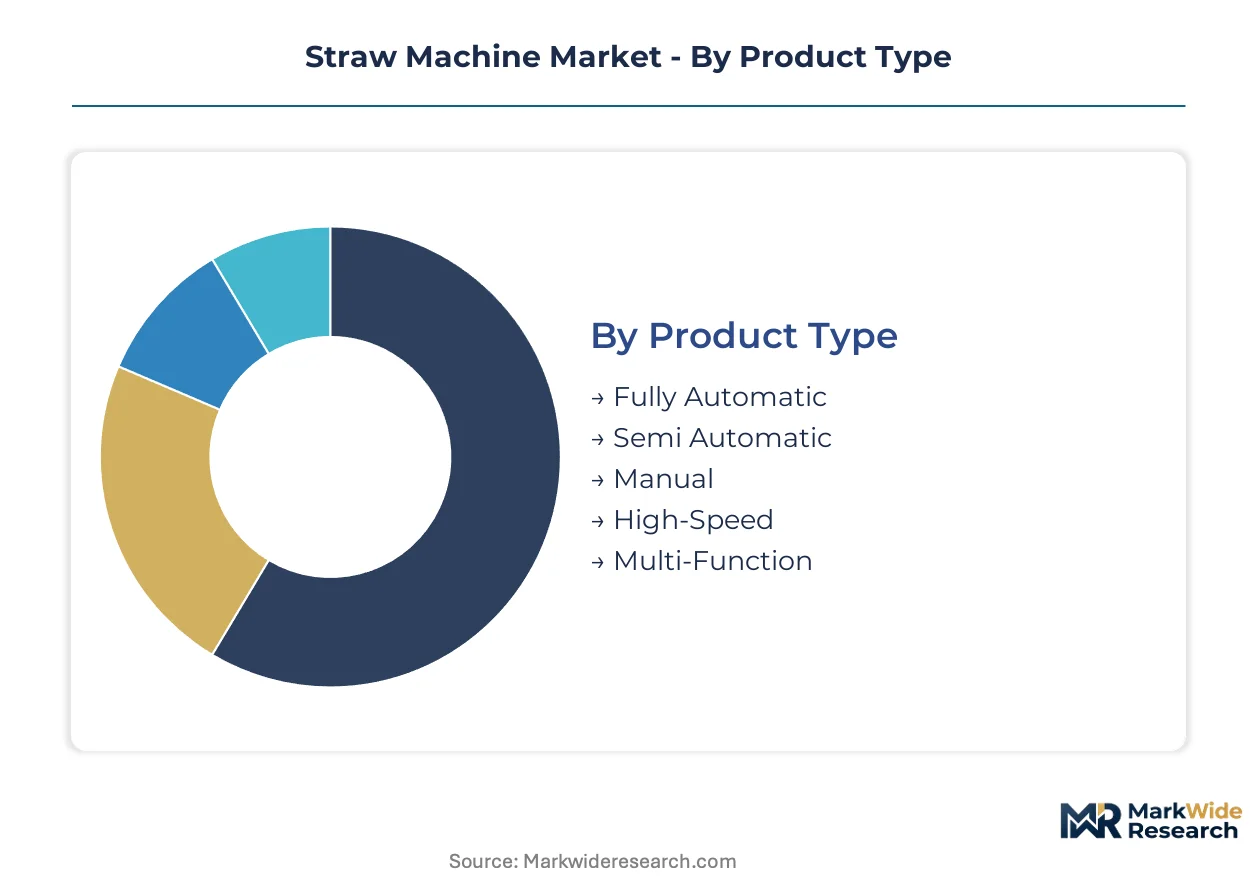
Straw machine procurement decisions fragment across substrate compatibility requirements, throughput specifications, and compliance documentation burdens. Equipment buyers weigh certification pathways against capital intensity and line flexibility needs.
Product Type:
FDA food-contact substance notifications and EU REACH additive constraints shape which automation tiers beverage brands can deploy. Fully automatic systems face the steepest certification documentation requirements for servo-driven cutting modules.
- Fully Automatic:Systems integrate forming, cutting, and packaging at speeds of 400-800 pieces per minute with minimal operator intervention. Demand concentrates among multinational beverage brands in Germany and the United States seeking labor reduction and BPI compostability certification alignment.
- High-Speed:Lines exceeding 600 pieces per minute require precision servo systems typically sourced from Japanese or German component suppliers. QSR chains serving hot beverages in Japan and South Korea specify these systems to meet molded paper pulp durability standards.
- Semi Automatic:Mid-sized regional bottlers in Poland and Mexico favor these units for 200-400 piece per minute output with partial manual feeding.
- Manual:Entry-level equipment serves small catering operations and event management companies with minimal regulatory exposure.
- Multi-Function:Hybrid platforms switch between paper web and biopolymer resin handling without extended changeover downtime.
Leading the category by volume: Fully Automatic. Growing fastest: High-Speed.
Technology:
Cost tiers separate equipment categories, with thermoforming commanding premium positioning for molded fiber applications while extrusion dominates volume deployment.
- Extrusion:Dominates biopolymer processing for PLA and PHA resins, operating through heated barrel and screw mechanisms. China's Jiangsu manufacturing cluster anchors global supply of mid-range extrusion lines serving Southeast Asian beverage converters.
- Thermoforming:Molds paper pulp slurry into rigid straw geometries capable of withstanding hot liquids above 60°C. Starbucks and McDonald's European supply chains specify thermoformed equipment to meet performance thresholds unreachable by rolled paper tubes.
- Injection Molding:Precision cavity-based forming for complex biopolymer geometries with tight dimensional tolerances.
- Blow Molding:Limited deployment for hollow biopolymer straw variants requiring internal pressure forming.
- Compression Molding:Lower capital intensity option for fiber-based substrates in emerging markets with constrained equipment budgets.
Highest capital intensity: Thermoforming. Widest installed base: Extrusion.
Application:
Customer type determines throughput requirements and compliance stringency, with hospitality chains facing the most fragmented certification demands across operating geographies.
- Beverage Industry:Encompasses bottled water, soft drinks, and ready-to-drink tea producers requiring high-volume continuous operation. Coca-Cola and PepsiCo bottling partners in the United States and Mexico drive specification of servo-driven quality inspection integration.
- Hospitality Chains:McDonald's, Starbucks, and regional hotel groups demand equipment capable of producing both standard and jumbo straw formats with full compostability documentation. EU Single-Use Plastics Directive compliance forces these buyers toward modular certification pathways covering BPI, TÜV Austria, and OK Compost HOME standards.
- Food Packaging:Converters serving yogurt, pudding, and single-serve condiment markets with smaller diameter straw requirements.
- Event Management:Seasonal and temporary demand characterized by lower durability specifications and minimal regulatory oversight.
Steepest compliance burden: Hospitality Chains. Most price-sensitive procurement: Event Management.
End User:
Geography shapes supplier relationships, with packaging companies in Eastern Europe and Latin America increasingly sourcing direct from Chinese and Turkish machine builders.
- Packaging Companies:Dedicated converters such as Huhtamaki and Transcend Packaging operate multiple substrate lines to hedge against PLA and PHA resin price volatility. These buyers prioritize rapid-changeover platforms allowing same-day switches between paper and biopolymer production.
- Manufacturing Units:In-house straw production at beverage bottling facilities in India's Maharashtra and Karnataka states is expanding following FSSAI plastic phase-out timelines.
- Catering Services:Fragmented demand from institutional foodservice operators with limited capital budgets and basic compliance needs.
- Distributors:Intermediate procurement channels consolidating orders from smaller hospitality and foodservice accounts.
Fastest equipment upgrade cycles: Packaging Companies. Emerging demand concentration: Manufacturing Units.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biopolymer resin feedstock availability in Thailand's cassava belt and China's corn starch regions anchors equipment demand concentration. Jiangsu and Zhejiang manufacturing clusters supply domestic converters and Southeast Asian export markets. India's FSSAI plastic phase-out creates new procurement nodes in Maharashtra and Karnataka.
United States
Beverage bottlers in Texas and Georgia retrofit legacy extrusion lines for PLA compatibility. FDA food-contact substance notifications govern servo-driven cutting module approvals. Dallas-Fort Worth packaging corridors concentrate demand for fully-automatic systems with BPI compostability alignment.
Germany
QSR supply chains specify thermoforming equipment for hot-liquid molded paper pulp straws. REACH additive constraints on colorants constrain substrate formulations permitted in EU-bound configurations. Bavarian industrial zones host precision component suppliers for high-speed servo systems.
China
NMPA guidelines on food-contact materials accelerate equipment upgrades toward compostable substrate handling. SAMR regulations add certification layers for domestic machinery and export-bound lines. Jiangsu and Zhejiang manufacturing clusters serve both local converters and Southeast Asian beverage markets.
India
FSSAI plastic phase-out timelines drive in-house straw production at Maharashtra and Karnataka bottling facilities. Domestic PLA production scale-up reduces resin import dependency for regional converters. Pune and Bengaluru industrial corridors attract first-mover equipment vendors establishing local service networks.
Japan
METI efficiency standards push hospitality distributors toward rapid-changeover hybrid platforms. Premium precision segments demand tight tolerances on high-speed cutting modules above 600 pieces per minute. Nagoya engineering bases anchor servo system integration for molded paper pulp durability specifications.
Straw Machine Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue aftermarket retrofit kits and automated quality inspection integration. The vendor base spans Chinese manufacturing clusters, Japanese precision engineering centers, and European hospitality supply specialists. Three archetypes dominate: domestic volume fabricators leveraging Jiangsu-Zhejiang engineering bases, premium precision specialists from Japanese industrial zones, and European compliance-focused builders serving McDonald's and Starbucks supply chains. Capacity expansion and geographic direct-selling displace distributor-mediated sourcing as primary competitive moves.
Among Chinese fabricators, Anhui Wenying Machinery Technology Co., Ltd. and Henan Top Packing Machinery Co., Ltd. exemplify the domestic volume archetype serving Southeast Asian export markets. Miyazaki Machinery occupies a position within the premium precision tier anchored in Japanese engineering standards. Tembo Paper represents the European compliance-focused builder archetype optimized for thin-wall paper straw production.
| Leading Market Players |
|---|
| Anhui Wenying Machinery Technology Co., Ltd. |
| Unitely Machinery |
| Henan Top Packing Machinery Co., Ltd. |
| Kunshan Zhiyang Machinery |
| Kally Machinery |
| Jain Industries |
| Miyazaki Machinery |
| Sankyo Seisakusho |
| Tembo Paper |
| Others |
Pricing and Supply Chain Analysis
Captive integration of servo-driven cutting modules by Japanese and German component suppliers anchors both supply security and premium pricing power for high-speed straw machine lines above 600 pieces per minute. This upstream control over precision motion systems allows Miyazaki Machinery and Bavarian engineering zones to command substantial margins while constraining cost-competitive alternatives for mid-tier buyers.
Pricing Analysis
Warranty and field service bundling separates premium Japanese and European equipment from unbundled Chinese alternatives, with Miyazaki Machinery and Tembo Paper including multi-year maintenance contracts while Jiangsu-Zhejiang fabricators price hardware-only. Three-tier pricing structure across premium, standard, and economy levels correlates with servo system origin, BPI certification documentation, and hot-liquid durability testing. Cost compression in the standard tier is intensifying because regional bottlers in Poland and Mexico are sourcing direct from Chinese builders, bypassing distributor markups. Event management and small catering operations exhibit the highest price sensitivity, while QSR chains serving Starbucks and McDonald's European supply chains prioritize certification alignment over capital cost.
Supply Chain Analysis
REACH compliance on additives and FDA food-contact substance notifications gate component qualification, forcing machine builders to validate entire material-feed pathways rather than isolated contact surfaces. Manufacturing concentrates in China's Jiangsu and Zhejiang clusters, with precision servo systems drawn from Japan's Nagoya engineering bases and Bavarian industrial zones. Biopolymer resin feedstock rests on corn starch and sugarcane commodity markets, creating price volatility that complicates equipment ROI calculations. Single-source vulnerability concentrates in Japanese servo motor suppliers for high-speed cutting modules above 600 pieces per minute. Distribution runs through direct manufacturer-to-converter relationships, displacing distributor-mediated sourcing in Eastern Europe and Latin America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The straw machine sector sits in a substrate-transition phase, with rapid-changeover hybrid platforms replacing single-substrate legacy lines as beverage brands demand same-day switches between paper webs and biopolymer resins.
For Market Incumbents: Deepen backward integration into servo system repair capabilities and regional spare parts warehousing to defend against supply concentration risk from Japanese and German component suppliers. Add capacity in India's Maharashtra and Karnataka industrial corridors to capture FSSAI plastic phase-out procurement waves before first-mover equipment vendors establish entrenched service networks. Certification investment in modular BPI, TÜV Austria, and OK Compost HOME pathways preserves specification access to McDonald's and Starbucks European supply chains. For New Entrants and Emerging Players: The EU Single-Use Plastics Directive in Germany and France opens a window for aftermarket retrofit kits targeting legacy plastic straw extrusion lines, a lower-capex entry point for regional bottlers with constrained capital budgets. India's FSSAI plastic phase-out timelines represent the most penetrable geography, with domestic PLA production scale-up reducing resin import dependency for converters in Pune and Bengaluru. A go-to-market angle anchored in automated quality inspection integration—machine vision systems for real-time defect detection—differentiates against established hardware-only vendors. For Investors and Strategic Acquirers: Exit pathways concentrate in precision component specialists with captive servo system technology and established certification documentation libraries. Long-term viability favors equipment builders capable of spanning both paper web handling and biopolymer extrusion thermodynamics, a skill intersection rarely found in single-discipline engineering pools. The signal to watch is compostability certification harmonization between BPI and TÜV Austria standards, which would reduce modular engineering overhead and expand addressable market for unified-platform builders.| Strategic Initiative | Industry Significance |
|---|---|
| Rapid-Changeover Platform Development | Enables same-day substrate switching for packaging companies hedging against PLA price volatility. |
| Aftermarket Retrofit Kit Expansion | Captures regional bottler demand for lower-capex paper straw conversion without full line replacement. |
| Automated Quality Inspection Integration | Reduces downstream rejection rates for thin-wall paper straws serving McDonald's European supply chains. |
| India Service Network Establishment | Secures first-mover position in Maharashtra and Karnataka ahead of FSSAI plastic phase-out enforcement. |
| Modular Certification Pathway Engineering | Preserves specification access across divergent BPI, TÜV Austria, and OK Compost HOME standards. |
Research Methodology
Multi-period observation of equipment procurement patterns, substrate switching frequencies, and certification documentation burdens anchored the trend analysis, supplemented by interviews with plant engineers at beverage bottling facilities, procurement leads at packaging converters, aftermarket service heads, and technical R&D directors at machine builders. Secondary validation drew from SAMR food-contact regulations, FDA food-contact substance notification databases, EU Single-Use Plastics Directive implementation timelines, and BPI compostability certification registries. Bottom-up triangulation across individual equipment transactions and top-down cross-checks against regional production capacity estimates ensured consistency.
Input-output matrices modeled straw machine deployment across substrate compatibility, throughput specification, automation tier, and end-user geography dimensions throughout the forecast period. CAGRs derived from fitted growth curves applied to baseline installation data, with cross-segment reconciliation ensuring internal consistency. Industry-specific forecast inputs included biopolymer resin price volatility indices and QSR chain throughput requirement trajectories.
The model assumes a particular technology adoption path; alternative pathways for molded paper pulp thermoforming versus rolled paper tube extrusion would alter the outlook for hot-liquid durability specifications. Forecasts reflect assumptions about regulatory enforcement timing and certification harmonization that may shift with political or administrative changes. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Laminating Machines Market
Packaging Machinery
Automatic Liquid Filling Machines Market
Packaging Machinery
Cosmetic Packaging Machinery Market
Packaging Machinery
Tray and Sleeve Packing Machines Market
Packaging Machinery
Bundling Machine Market
Packaging Machinery
North America Printing Machinery Market
Packaging Machinery
Corrugated Box Machines Market
Packaging Machinery
Hand-Held Capping Machines Market
Packaging Machinery
Tablet Packing Machine Market
Packaging Machinery
Wet Ink Coding Machines Market
Packaging Machinery
Shrink - Sleeve Wrapping Machinery Market
Packaging Machinery
Tray Sealing Machines Market
Packaging Machinery
Liquid Capsule Filling Machines Market
Packaging Machinery
Vertical Injection Molding Machine Market
Packaging Machinery
Global Paper Napkin Making Machine Market
Packaging Machinery
Blown Film Extrusion Machine Market