
 Laminating Machines Market | 2026-2036
Laminating Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Laminating Machines Market Outlook
Modular equipment configurations are shifting buyer choice in laminating machinery as converters seek lines that integrate printing, coating, and slitting in single footprints. BOBST Group SA leverages its rotary die-cutting heritage to anchor high-speed web processing ecosystems across Europe and Asia-Pacific. Nordmeccanica Group S.p.A. specializes in solventless and water-based adhesive laminators that sustain premium positioning in food packaging compliance segments. Comexi Group Industries S.A.U. competes through narrow-web flexo-lamination hybrids that dominate Latin American and Iberian converter markets.
Laminating machines bond multi-layer substrates through thermal, pressure-sensitive, or UV-cured adhesive systems to create protective or barrier-enhanced composites, typically operating at web speeds from 100 to 600 meters per minute depending on substrate complexity. Their primary purpose spans document preservation, flexible food packaging, and industrial label protection where moisture or oxygen ingress must be blocked. Hot laminators lead the product type landscape due to entrenched use in commercial print finishing and educational supply chains, while UV-cured technology segments are expanding fastest as energy-cured adhesives eliminate thermal damage to heat-sensitive films. The packaging industry end-user channel concentrates margin pools because pharmaceutical and snack food converters demand validated, traceable lamination processes with lot-controlled adhesive deposition.
FDA food-contact substance notifications and EPA volatile organic compound rules in the United States shape adhesive chemistry selection and equipment ventilation design, while REACH and the EU F-Gas Regulation in Europe restrict solvent-based systems and fluorinated barrier films that laminators must process. OSHA machine guarding standards and CE marking mechanical safety directives further dictate roll-handling automation and interlock investments. Stakeholders must monitor how evolving extended producer responsibility frameworks in multiple jurisdictions redirect capital toward recyclable mono-material lamination architectures.
Market Dynamics
Packaging converters are consolidating lamination, printing, and slitting into single-footprint production lines to reduce capital intensity and floor-space requirements. This equipment integration wave is compressing vendor margins while favoring suppliers with rotary die-cutting and web-handling heritage.
Growth Catalysts
- Solvent-free adhesive mandates:REACH and the EU Green Deal are accelerating converter investment in water-based and solventless lamination systems across European food packaging operations.
- Pharmaceutical barrier validation:FDA food-contact substance notifications require traceable adhesive deposition and lot-controlled processes, pulling validated laminator demand from US drug packaging converters.
- Flexible packaging investment clusters:Germany, China, and the United States concentrate new lamination capacity as snack food and ready-meal producers expand shelf-stable product lines.
Market Restraints
- Fluorinated film processing constraints:The EU F-Gas Regulation restricts high-barrier fluoropolymer films that laminators must substitute with multi-layer adhesive alternatives at higher unit cost.
- Capital equipment intensity:Integrated print-laminate-slit lines require seven-figure capital commitments that freeze mid-tier converters in spot-contractor relationships.
- Skilled technician scarcity:Web tension control and adhesive rheology expertise concentrates in aging workforces across Midwestern US and Northern Italian machine districts.
Strategic Opportunities
- Mono-material lamination architectures:Extended producer responsibility frameworks in Germany and France are redirecting converter capital toward recyclable single-substrate barrier films.
- Narrow-web hybrid penetration:Latin American and Iberian markets remain underpenetrated by flexo-lamination combination equipment serving regional label converters.
- UV-cured adhesive expansion:Energy-cured systems eliminate thermal damage to heat-sensitive films, opening pharmaceutical blister and medical device packaging segments previously closed to hot lamination.
Industry Challenges
- CE marking mechanical safety compliance:Roll-handling automation and interlock investments extend equipment commissioning timelines by four to six months for European installations.
- Legacy ERP integration friction:New laminator control systems require custom middleware to connect with converter inventory and scheduling platforms, inflating implementation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laminating Machines Market |
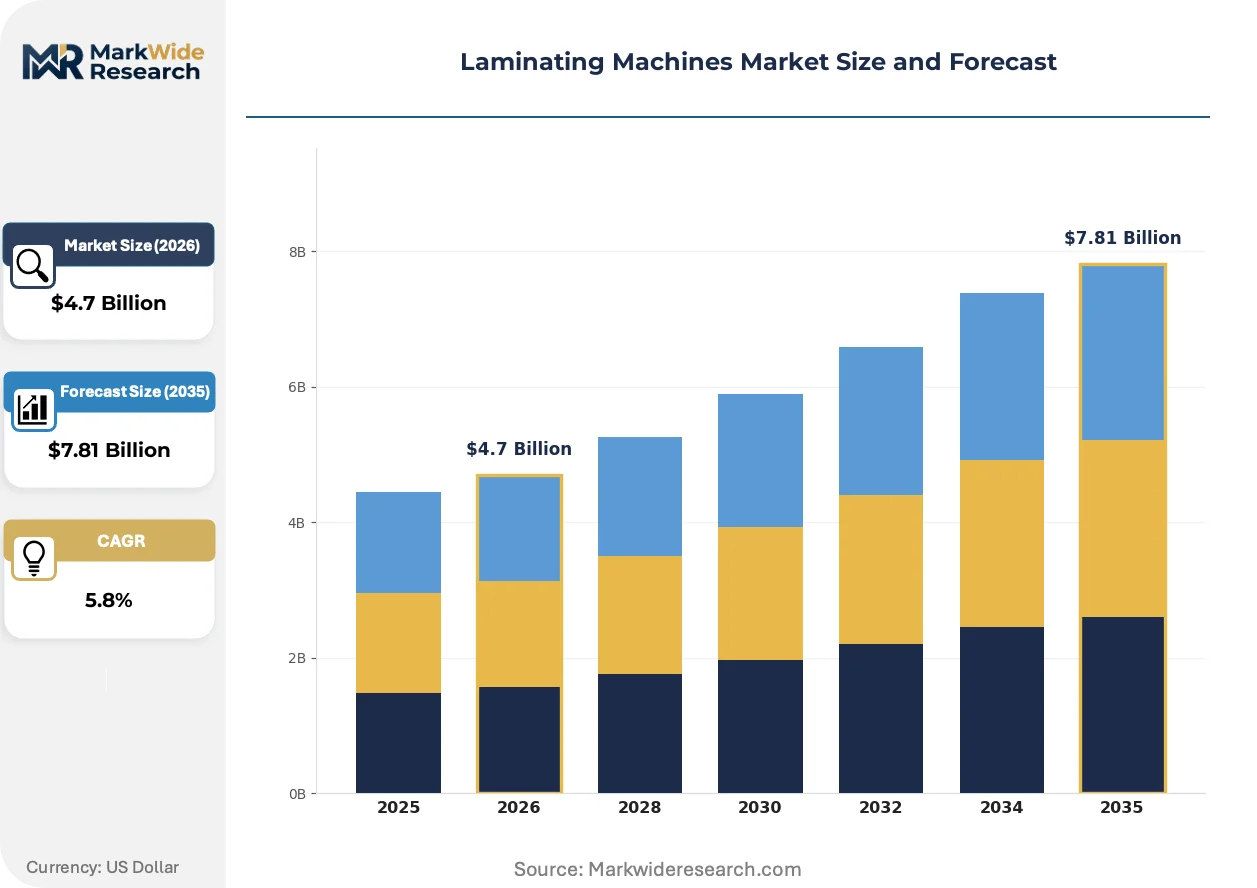
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $7.81 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cold Laminators, Hot Laminators, Roll Laminators, Pouch Laminators End User: Printing Companies, Educational Institutions, Offices, Packaging Industry Technology: Thermal, Pressure Sensitive, UV, Electric Application: Document Protection, Product Packaging, Photo Finishing, Card Making |
| Companies Covered | Uteco Converting S.p.A., Comexi Group Industries S.A.U., Nordson Corporation, Global Web Finishing Inc., Karlville Development LLC, BOBST Group SA, Nordmeccanica Group S.p.A., KENMEC Mechanical Engineering Co., Ltd., FRIMO Group GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laminating Machines Market Strategic Shifts
Equipment architecture and adhesive chemistry are converging to eliminate thermal processing steps while enabling faster substrate changeovers. These shifts are compressing production batch sizes and rewarding converters with multi-product flexibility.
Digital print-to-laminate workflow integration is modularizing equipment purchasing decisions. Narrow-web converters in Latin America and Iberia are acquiring combination flexo-lamination units that merge pre-press, coating, and finishing in single footprints. This architecture collapses make-ready time from hours to minutes while reducing skilled operator headcount.
REACH and the EU F-Gas Regulation are forcing solvent-based adhesive phase-outs across European flexible packaging operations. Converters are retrofitting existing laminators with water-based and solventless coating heads or replacing thermal drying sections with UV-cured deposition systems. German pharmaceutical and snack food packaging producers face the steepest compliance timelines.
Certification-driven procurement is shortening equipment replacement cycles. US pharmaceutical converters now require FDA-validated adhesive traceability systems that obsolete laminators installed before 2018. After-sales service contracts are unbundling from equipment sales as converters seek independent maintenance providers with multi-brand expertise.
Laminating Machines Market Segmentation
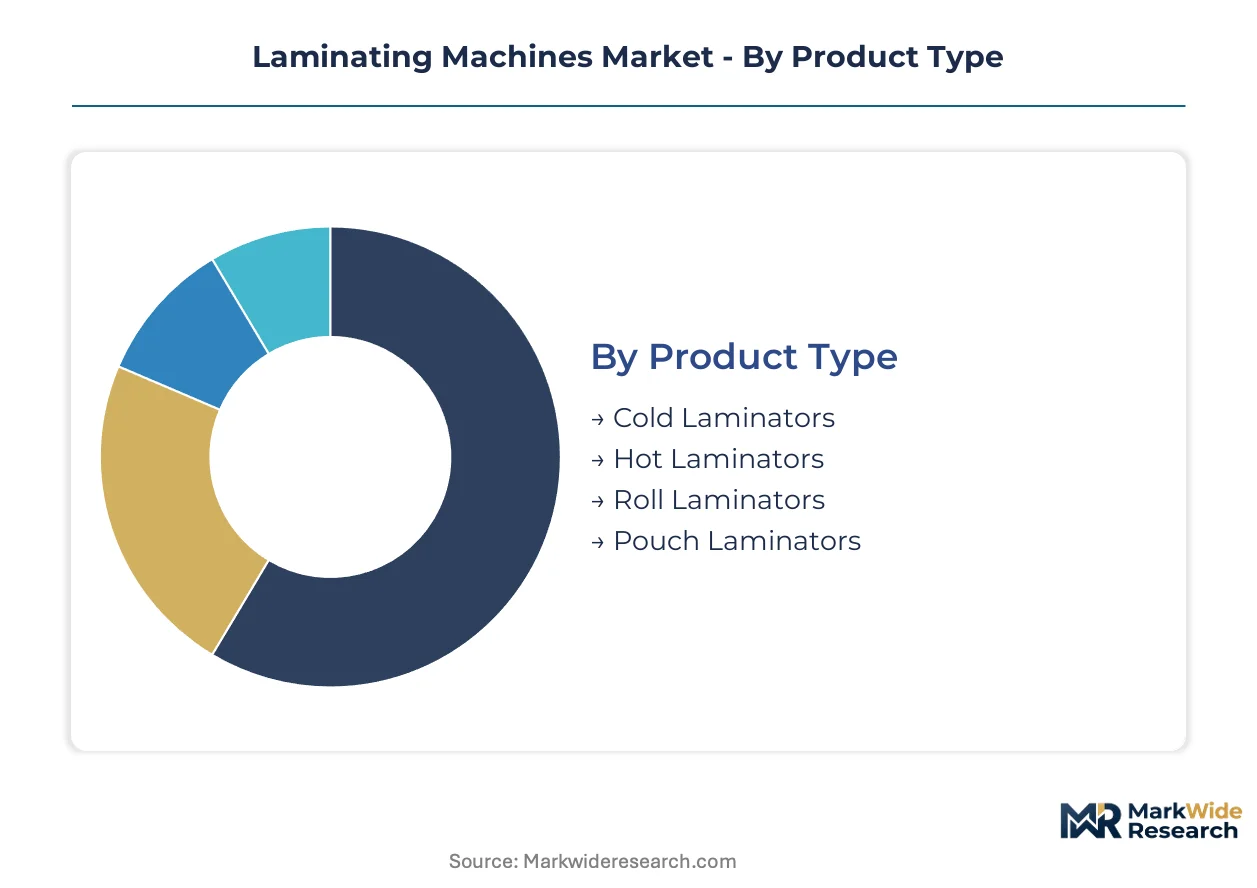
Segmentation in laminating machinery reveals how adhesive chemistry, substrate handling, and end-use validation requirements split procurement budgets across converter types. Equipment specifications diverge sharply between food-grade barrier producers and commercial print finishers.
Product Type:
Buyers in this category differentiate primarily by thermal processing requirements and throughput scale rather than capital budget alone.
- Hot Laminators:These systems apply heat-activated adhesives through thermal rollers operating at controlled temperatures to bond films to paper or board substrates. Demand concentrates in commercial print finishing operations across Germany and the United States where document preservation and educational supply contracts require proven reliability. Entrenched supply chains and familiar maintenance protocols slow displacement despite energy efficiency drawbacks.
- Cold Laminators:Pressure-sensitive adhesive systems eliminate thermal damage to heat-sensitive substrates through mechanical pressure alone. Pharmaceutical blister packaging converters in Switzerland and medical device manufacturers in the United States are expanding capacity here as FDA validation requirements tighten around temperature-sensitive barrier films.
- Roll Laminators:Continuous web systems process substrate rolls at speeds from 100 to 600 meters per minute for high-volume flexible packaging lines.
- Pouch Laminators:Entry-level desktop and floor-standing units seal individual documents in pre-formed adhesive pouches for small-batch office and school use.
Volume sits with Hot Laminators; growth tilts toward Cold Laminators.
End User:
Margin capture varies dramatically by validation burden, with regulated industries paying premiums for traceable adhesive deposition systems.
- Packaging Industry:Flexible food packaging and pharmaceutical barrier producers operate the most capital-intensive installations, requiring validated lot-controlled processes with full adhesive traceability. German snack food converters and US drug packaging specialists are expanding solventless lamination capacity to meet REACH and FDA compliance timelines.
- Printing Companies:Commercial print finishers prioritize equipment uptime and fast substrate changeovers over barrier validation. Latin American and Iberian narrow-web converters are acquiring combination flexo-lamination units that collapse make-ready time from hours to minutes.
- Educational Institutions:Schools and universities purchase pouch and entry-level roll systems for document preservation and teaching material protection.
- Offices:Corporate procurement favors compact cold laminators for presentation materials and ID badge production with minimal operator training.
Revenue concentrates in Packaging Industry; fastest expansion occurs in Printing Companies.
Technology:
Regulatory chemistry mandates are forcing technology transitions faster than equipment depreciation cycles can absorb.
- Thermal:Heat-activated adhesive systems dominate installed base through mechanical simplicity and broad substrate compatibility. European converters face retrofit pressure as REACH solvent restrictions and EU F-Gas Regulation fluoropolymer limits compound compliance costs.
- UV:Energy-cured adhesives polymerize instantly under ultraviolet exposure, eliminating thermal damage and enabling faster line speeds. Medical device packaging specialists in the United States and pharmaceutical blister producers in Germany are expanding UV capacity as heat-sensitive film adoption accelerates.
- Pressure Sensitive:Self-adhesive systems require no curing or drying, suiting short-run label and card production with minimal setup.
- Electric:Precision temperature control systems serve niche applications requiring exact thermal profiles for specialty substrates.
Installed base favors Thermal; steepest expansion trajectory belongs to UV.
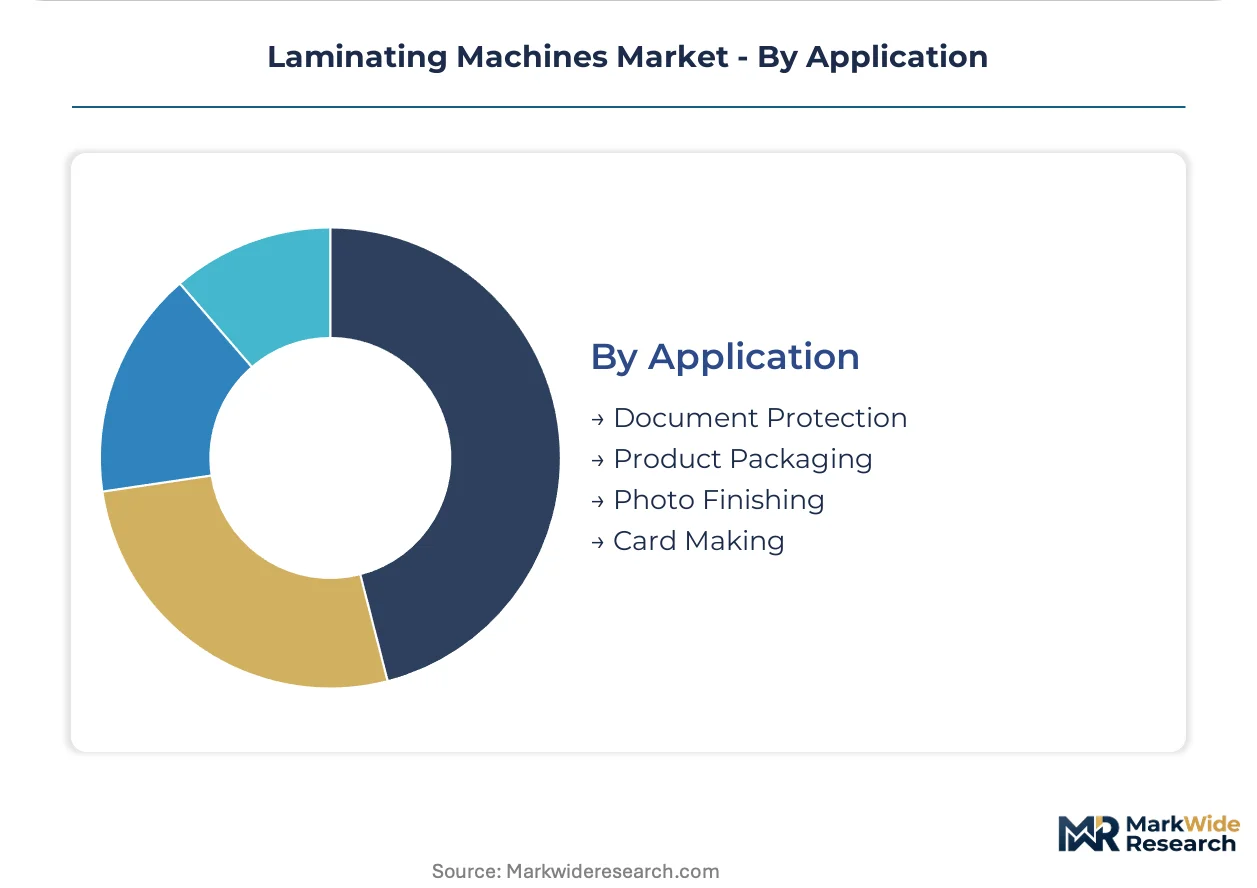
Application:
Barrier performance requirements split the market between commodity protection and validated ingress prevention.
- Product Packaging:Multi-layer barrier films for snack foods, ready-meals, and pharmaceuticals demand validated oxygen and moisture ingress prevention. German and Chinese converters are expanding solvent-free capacity to meet shelf-stable product line growth.
- Document Protection:Commercial print and educational laminating prioritizes cost-per-sheet and equipment reliability over barrier metrics. US school districts and corporate print centers maintain steady replacement demand for proven thermal systems.
- Photo Finishing:Professional photography labs and retail minilabs require UV-stable, non-yellowing films with precise gloss control.
- Card Making:Loyalty card, ID badge, and gaming card producers use specialized pouch and roll systems for dimensional stability and edge seal integrity.
Capital deployment concentrates in Product Packaging; Document Protection sustains volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany manufactures the most sophisticated laminating equipment while China and the United States absorb the majority of new capacity installations. Production clusters concentrate in Northern Italy and Baden-Württemberg, but demand growth outpaces domestic supply in Asia-Pacific and North American flexible packaging corridors.
United States
Pharmaceutical barrier validation and snack food shelf-stable lines drive laminator procurement from New Jersey to Wisconsin converters. FDA food-contact substance notifications and EPA volatile organic compound rules shape adhesive chemistry selection and ventilation design investments. Chicago and Minneapolis machine districts face skilled technician scarcity for web tension control and adhesive rheology expertise.
Germany
Snack food producers and pharmaceutical packers expand solventless lamination capacity to meet EU Green Deal compliance timelines. REACH restrictions and the EU F-Gas Regulation force fluoropolymer film substitution with multi-layer adhesive alternatives at higher unit cost. The Düsseldorf-Cologne corridor anchors high-speed web processing ecosystems serving export markets.
China
Flexible packaging investment accelerates in Yangtze River Delta and Pearl River Delta manufacturing zones for ready-meal and export snack production. The country's national environmental regulator enforces volatile organic compound emission standards that push converters toward water-based adhesive systems. Shenzhen and Suzhou clusters concentrate new lamination capacity with integrated print-coat-slit line configurations.
Italy
Narrow-web flexo-lamination hybrids dominate converter procurement across Lombardy and Emilia-Romagna label production centers. CE marking mechanical safety directives extend equipment commissioning timelines by four to six months for roll-handling automation compliance. Bologna and Milan districts specialize in solventless adhesive laminators for premium food packaging segments.
Switzerland
Pharmaceutical blister packaging converters expand cold laminator capacity as FDA validation requirements tighten around temperature-sensitive barrier films. Swissmedic and EMA alignment on medical device packaging standards pulls traceable adhesive deposition system demand. Basel and Zurich pharmaceutical clusters require lot-controlled processes with full adhesive traceability.
Laminating Machines Market Competitive Environment
The competitive structure tilts toward integrated web-handling specialists with rotary die-cutting heritage. Equipment vendors consolidate around three tiers: multinational conglomerates with full finishing line portfolios, mid-cap regional specialists in solvent-free adhesive systems, and narrow-web hybrid fabricators serving Latin American and Iberian markets. Dominant competitive moves include geographic expansion through distribution partnerships and technology licensing for UV-cured adhesive retrofit kits.
Among European-based integrated specialists, BOBST Group SA exemplifies the multinational conglomerate archetype with rotary die-cutting heritage anchoring high-speed web processing ecosystems. Nordmeccanica Group S.p.A. and Comexi Group Industries S.A.U. occupy positions within the mid-cap specialist tier, with the former representing solventless adhesive expertise and the latter exemplifying narrow-web flexo-lamination hybrid penetration in underdeveloped regional converter markets.
| Leading Market Players |
|---|
| Uteco Converting S.p.A. |
| Comexi Group Industries S.A.U. |
| Nordson Corporation |
| Global Web Finishing Inc. |
| Karlville Development LLC |
| BOBST Group SA |
| Nordmeccanica Group S.p.A. |
| KENMEC Mechanical Engineering Co., Ltd. |
| FRIMO Group GmbH |
| Others |
Value Chain & Pricing Dynamics
UV-cured adhesive retrofit adoption across European flexible packaging converters is compressing equipment depreciation cycles while simultaneously concentrating procurement leverage among solventless technology specialists in Northern Italy and Baden-Württemberg. This chemistry transition forces mid-tier converters into extended spot-contractor relationships, amplifying pricing power asymmetries between integrated line suppliers and fragmented component vendors.
Pricing Analysis
Margin tightening in mid-tier equipment reflects the capital intensity of integrated print-laminate-slit configurations. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated pharmaceutical systems from commercial print finishers and entry-level pouch units. Price differentiation hinges on CE marking compliance grade and after-sales service bundling. Cost-down pressure on standard-tier equipment accelerates because Chinese manufacturers in Suzhou and Shenzhen are expanding water-based adhesive system output. Commercial print finishers exhibit highest price sensitivity; pharmaceutical barrier producers accept premiums for lot-controlled traceability.
Supply Chain Analysis
Dual-sourcing mandates from German snack food converters and US pharmaceutical packers require qualified suppliers for both solventless coating heads and UV-cured deposition systems. Component manufacturing concentrates in Italy, Germany, and China. Precision web tension control systems and adhesive rheology modules draw from specialized machine districts around Bologna, Stuttgart, and Shanghai. Single-source vulnerability persists in high-speed rotary die-cutting assemblies. Distribution runs through OEM direct sales for large installations and regional distributor networks for narrow-web hybrid units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as converters seek captive control over adhesive chemistry validation and after-sales service capabilities to lock in compliance-advantaged positioning.
For Market Incumbents: Acquire solventless adhesive formulation expertise to anchor recurring revenue streams beyond equipment sales. Consolidate aftermarket service capabilities in Midwestern US and Northern Italian districts where aging technician workforces threaten maintenance quality. Defend against emerging Chinese competitors by embedding FDA and REACH validation protocols into control system architectures. For New Entrants and Emerging Players: Enter via narrow-web flexo-lamination hybrid penetration in underdeveloped Latin American and Iberian converter markets. Target regional label producers in São Paulo and Barcelona corridors seeking collapsed make-ready times. Pursue technology licensing arrangements with established UV-cured adhesive suppliers rather than greenfield R&D investment. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to multinational conglomerates seeking rotary die-cutting heritage and web-handling ecosystems. Long-term viability favors mid-cap specialists with demonstrated solvent-free compliance trajectories in German pharmaceutical and snack food segments. Watch for inflection in extended producer responsibility framework enforcement across France and Germany as a signal for mono-material lamination architecture capital redeployment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adhesive Chemistry | Captures REACH and FDA compliance margin pools previously ceded to chemical suppliers. |
| UV-Cured Retrofit Kit Licensing | Enables incumbent equipment installed base extension without full line replacement capex. |
| Narrow-Web Hybrid Geographic Expansion | Penetrates Latin American and Iberian markets with flexo-lamination combination units. |
| Aftermarket Service Unbundling | Addresses converter demand for independent multi-brand maintenance expertise. |
| Mono-Material Architecture R&D Partnership | Aligns equipment development with German and French extended producer responsibility timelines. |
Study Parameters
Multi-period observation of lamination capacity installations, adhesive chemistry transitions, and regulatory compliance timelines anchored the trend analysis, supplemented by interviews with packaging converter operations directors, OEM procurement managers, aftermarket service technicians, and adhesive formulation specialists. Secondary validation drew from REACH substance restriction updates, FDA food-contact substance notification databases, EU F-Gas Regulation amendments, and flexible packaging trade association capacity surveys. Bottom-up equipment shipment tracking and top-down converter capex analysis were triangulated against adhesive raw material consumption patterns.
Input-output matrices modeled unit shipments and revenue flows across product type, technology, end user, and application dimensions throughout the forecast period. CAGRs were derived from regression analysis of historical installation data against projected compliance-driven replacement cycles. Industry-specific forecast inputs included solvent-free adhesive mandate enforcement schedules in Germany and volatile organic compound emission standard tightening in China.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU Green Deal implementation or abrupt fluoropolymer film substitution deadlines. Deviation in FDA validation requirement stringency for pharmaceutical barrier applications would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Blown Film Extrusion Machine Market
Packaging Machinery
Global Blister Packaging Machinery Market
Packaging Machinery
Tea Packing Machine Market
Packaging Machinery
Tray and Sleeve Packing Machines Market
Packaging Machinery
Injectable Liquid Filling Machines Market
Packaging Machinery
Shrink Wrapping Machines Market
Packaging Machinery
Global Food and Beverage Packaging Machinery Market
Packaging Machinery
Beverage Can Seamers Market
Packaging Machinery
Hand-Held Capping Machines Market
Packaging Machinery
Side Load Case Packing Machines Market
Packaging Machinery
Bakery Packaging Machine Market
Packaging Machinery
Vacuum Chamber Packaging Machines Market
Packaging Machinery
Granule Filling Machine Market
Packaging Machinery
Molded Pulp Packaging Machines Market
Packaging Machinery
Product Dispensing Machinery Market
Packaging Machinery
Packaging Conveyors Market