
 Global Pet Stretch Blow Molding Machines Market | 2026-2036
Global Pet Stretch Blow Molding Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pet Stretch Blow Molding Machines Market Foresight
China is tilting the competitive map through massive PET packaging machinery capacity additions serving both domestic beverage bottlers and export markets. Krones AG leverages its integrated filling-line architecture to anchor premium positioning across European and Asian bottling corridors. SMI competes aggressively on throughput economics for high-volume carbonated soft drink operations. Nissei ASB Machine specializes in precision stretch blow molding for pharmaceutical-grade containers, occupying a defensible niche where cavity-to-cavity consistency commands pricing power.
Pet stretch blow molding machines thermoform polyethylene terephthalate preforms into oriented containers using pressurized air at 25-40 bar, with biaxial orientation improving barrier properties and drop resistance for carbonated beverages and personal care products. The equipment serves as the critical conversion node between resin injection and filled-product distribution. Servo electric and hybrid systems are capturing disproportionate growth as energy efficiency mandates tighten operational cost structures for bottlers running 24/7 production schedules. Inline machines dominate beverage applications where speed and footprint optimization matter, while multi-station configurations serve cosmetic manufacturers and drug formulators requiring rapid mold changeovers for shorter production runs.
FDA food-contact regulations, EU F-Gas restrictions on high-GWP refrigerants, and China's GB standards for packaging machinery safety collectively shape equipment specification requirements and market access conditions across major manufacturing zones. Bottlers in regulated jurisdictions now specify energy consumption and emissions documentation as standard procurement criteria alongside throughput and cavitation metrics. Stakeholders must monitor how carbon-border adjustment mechanisms and extended producer responsibility frameworks recalibrate total cost of ownership calculations for PET packaging investments.
Market Dynamics
Electric servo drives are displacing hydraulic systems across beverage bottling corridors, compressing energy footprints while EU F-Gas Regulation deadlines accelerate refrigerant phase-out timelines for cooling-dependent machinery architectures.
Growth Catalysts
- EU F-Gas Regulation:Mandatory hydrofluorocarbon phase-downs are forcing converters toward electric and hybrid blow molding platforms that eliminate refrigerant-based mold cooling circuits entirely.
- Pharmaceutical packaging:Injectable drug manufacturers demand cavity-to-cavity weight consistency below 0.3 grams, pulling precision stretch blow molding capacity into sterile fill-finish supply chains.
- India:Domestic preform production capacity is scaling 40% year-over-year as bottlers backward-integrate to reduce import exposure on finished containers from Southeast Asian suppliers.
Market Restraints
- Copper and rare-earth magnet costs:Servo motor bill-of-materials volatility is compressing margins on electric machine configurations just as regulatory deadlines mandate their adoption.
- German precision component suppliers:Concentration of high-tolerance screw and barrel manufacturers in Baden-Württemberg creates single-source vulnerability for Asian machine builders.
- Polypropylene substitution:Hot-fill dairy and ready-to-drink tea brands are trialing clarified PP bottles that bypass stretch blow molding entirely for temperature-stable applications.
Strategic Opportunities
- Brazil:ANVISA pharmaceutical packaging regulations are tightening traceability requirements, opening demand for integrated vision-inspection blow molding cells that Western suppliers dominate.
- Carbonated soft drink lightweighting:0.5-liter bottle weights below 8.5 grams require biaxial orientation control algorithms that only next-generation electric machines deliver reliably.
- Japan METI Green Transformation bonds:Subsidized financing for energy-efficient manufacturing equipment is accelerating replacement cycles for aging hydraulic blow molding lines.
Industry Challenges
- Multi-physics simulation expertise:Predictive modeling of PET strain-hardening behavior requires polymer rheology specialists that machine builders struggle to recruit against automotive and aerospace employers.
- Legacy Allen-Bradley integration:Brownfield bottling halls running 1990s-era PLC architectures face protocol translation complexity when retrofitting Industry 4.0 data acquisition modules onto existing blow molding cells.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pet Stretch Blow Molding Machines Market |
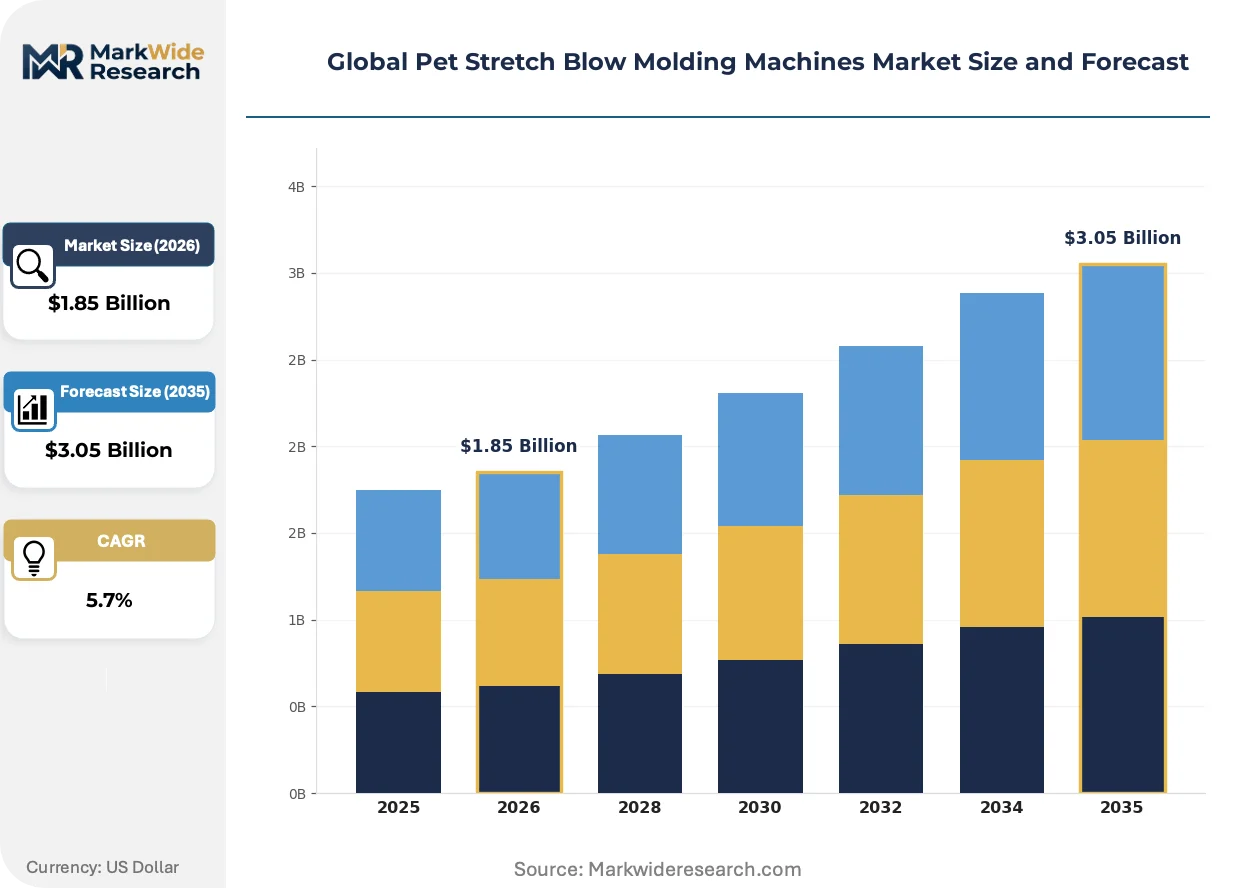
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.05 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Station, Double Station, Multi Station, Inline Machines Technology: Hydraulic, Servo Electric, Pneumatic, Hybrid Systems Application: Beverages, Personal Care, Pharmaceuticals, Chemical Packaging End User Industry: Bottlers, Cosmetic Manufacturers, Drug Formulators, Specialty Chemical Producers |
| Companies Covered | SMI, AOKI, Krones AG, W. Amsler Equipment, Sipa, Sacmi Imola, Guangzhou Tech-Long Packaging Machinery, Zhejiang Huangyan Lingma Plastic Machinery, Nissei ASB Machine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pet Stretch Blow Molding Machines Market Shifts & Advancements
Digital twin architectures are compressing mold commissioning timelines from weeks to days, while regulatory pressure on refrigerant emissions accelerates thermal management innovation. Machine builders now compete on simulation fidelity as much as mechanical throughput.
Virtual mold-tuning software is virtualizing the traditional trial-and-error process of stretch rod speed profiling and preform temperature mapping. Beverage bottlers in Germany and the Netherlands are deploying these tools to reduce startup scrap rates by half. The technology is virtualizing the role of veteran process engineers, collapsing decades of heuristic knowledge into parameterized simulation models that junior technicians can execute.
China's GB standards for packaging machinery safety are mandating redundant safety circuits and lockout-tagout compatibility that exceed baseline CE requirements. Domestic machine builders in Guangdong and Zhejiang are redesigning guard enclosures and control architectures to capture export certifications. European incumbents face compliance cost inflation as they dual-certify platforms for both EU machinery directives and evolving Chinese national standards.
After-sales service unbundling is fragmenting traditional bundled maintenance contracts into performance-based subscriptions tied to availability guarantees. Indian bottling cooperatives and Southeast Asian contract manufacturers are resisting multi-year service lock-ins, instead procuring spare parts through Alibaba Industrial and third-party automation integrators. This shift is most pronounced in Vietnam and Indonesia, where local engineering firms now rebuild servo drives independently of original equipment manufacturers.
Global Pet Stretch Blow Molding Machines Market Segmentation
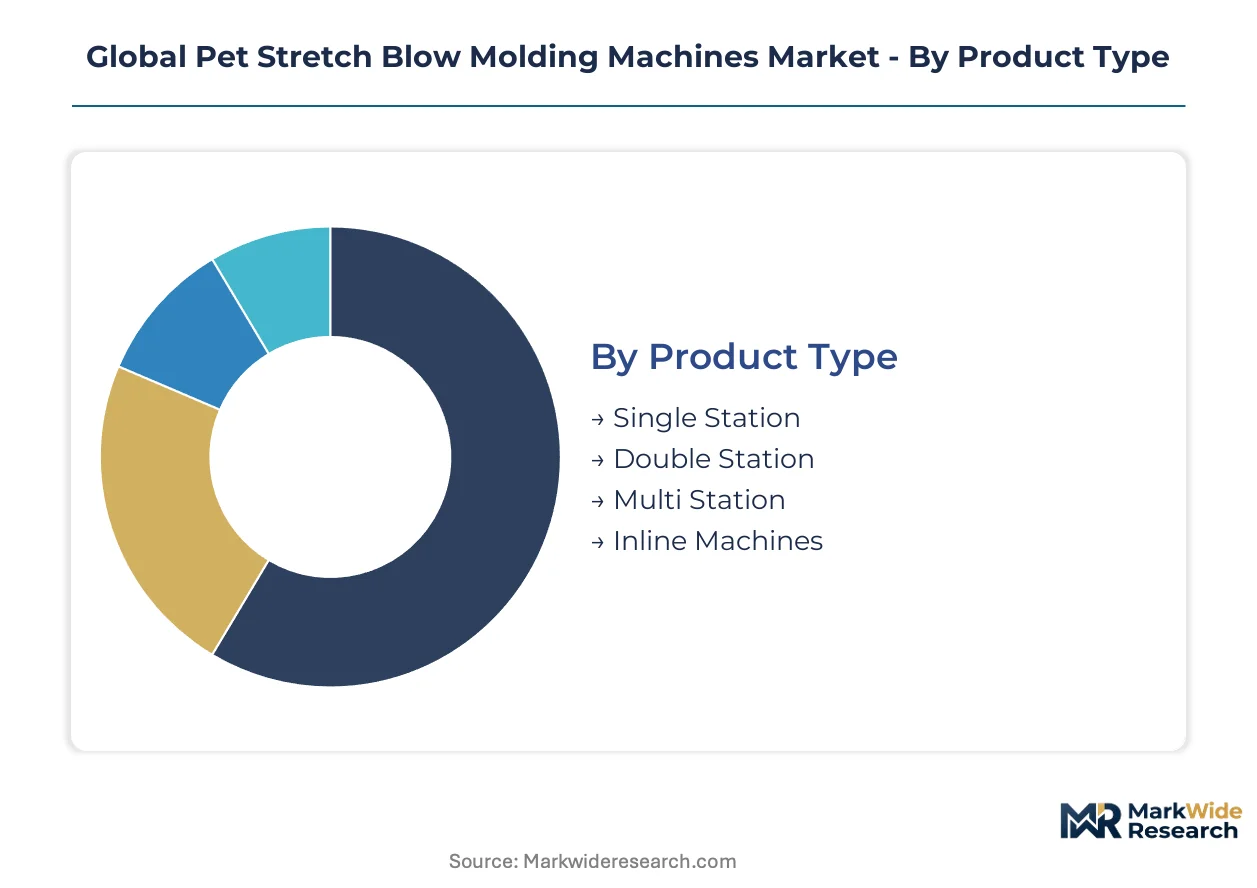
Segmentation in PET stretch blow molding machines reveals how equipment specifications map to operational intensity and service dependencies. Bottlers running carbonated beverage lines prioritize uptime guarantees and rapid spare parts availability over initial capital outlay, while pharmaceutical formulators demand precision calibration support that fragments vendor economics across customer tiers.
Product Type:
After-sales service intensity varies dramatically by station configuration, with multi-station architectures requiring specialized technicians for mold changeover optimization and inline machines demanding continuous availability contracts to protect throughput.
- Inline Machines:Continuous rotary architectures integrate directly with filling lines at speeds exceeding 80,000 bottles per hour. Beverage bottlers in Germany and the Netherlands specify these for mineral water and carbonated soft drink operations where footprint efficiency and energy recovery systems justify premium service contracts. The EU F-Gas Regulation accelerates electric inline adoption as hydraulic cooling circuits face refrigerant phase-out deadlines.
- Multi Station:Indexing turret designs enable rapid mold swaps for cosmetic manufacturers and drug formulators running shorter production campaigns. Personal care brands in France and Switzerland leverage these for SKU proliferation in premium shampoo and serum packaging where cavity-specific quality documentation is mandatory.
- Single Station:Compact semi-automatic units serve specialty chemical producers and regional bottlers with batch-scale requirements.
- Double Station:Parallel-cavity configurations balance throughput with changeover flexibility for mid-volume pharmaceutical contractors.
By volume, inline machines lead. By growth pace, multi-station configurations are climbing the fastest as cosmetics brands fragment SKUs.
Technology:
Technology selection now hinges on total cost of ownership calculations where energy tariffs and carbon border exposure reshape payback periods for bottlers operating across multiple regulatory jurisdictions.
- Servo Electric:Permanent magnet synchronous motors eliminate hydraulic fluid maintenance while delivering precision stretch rod control within 0.1 millimeter repeatability. Japanese bottlers accessing METI Green Transformation bond financing are replacing aging hydraulic fleets, while Indian cooperatives specify these for 24/7 mineral water operations where grid stability concerns favor regenerative braking architectures.
- Hybrid Systems:Combined electric servo and pneumatic clamping units optimize capital efficiency for mid-tier beverage producers. Brazilian bottlers serving ANVISA-regulated pharmaceutical packaging leverage hybrid platforms to balance precision requirements against import tariff exposure on fully electric European equipment.
- Hydraulic:Legacy architectures persist in price-sensitive Southeast Asian markets with established maintenance ecosystems.
- Pneumatic:Compressed-air-dependent systems retain niche positioning for explosive-atmosphere chemical packaging where electrical spark risks dominate specification.
By installed base, hydraulic systems still dominate. By replacement velocity, servo electric platforms are gaining share fastest as energy efficiency mandates tighten.
Application:
Application-driven segmentation exposes divergent tolerance for machine complexity, with pharmaceutical packaging demanding cavity-to-cavity validation protocols that pharmaceutical-grade blow molding cells must document for FDA and EMA submission.
- Beverages:Carbonated soft drink and bottled water operations consume the majority of installed capacity, with lightweighting targets below 8.5 grams for 0.5-liter bottles requiring biaxial orientation algorithms. Chinese bottlers backward-integrating preform production specify high-cavitation electric machines to serve domestic demand and export markets.
- Pharmaceuticals:Injectable drug packaging demands weight consistency below 0.3 grams cavity-to-cavity, with sterile fill-finish integration requiring isolator-compatible machine architectures. German and Swiss drug formulators specify integrated vision-inspection cells for traceability compliance.
- Personal Care:Premium cosmetic bottles for skincare and fragrance applications prioritize surface finish quality and color consistency over speed.
- Chemical Packaging:Agrochemical and solvent containers emphasize barrier layer co-injection and UN certification compliance for hazardous material transport.
By revenue concentration, beverages leads. By specification intensity, pharmaceuticals is expanding most quickly as biologics packaging requirements proliferate.
End User Industry:
End user procurement patterns fragment by scale and integration depth, with multinational bottlers demanding global spare parts networks and regional cooperatives sourcing through Alibaba Industrial for cost containment.
- Bottlers:Carbonated soft drink and water bottlers represent the volume anchor, with Coca-Cola and Pepsi system suppliers in India scaling domestic preform capacity 40% annually to reduce Southeast Asian import dependence. These operators specify machines with 10-year availability guarantees and remote diagnostics integration.
- Drug Formulators:Sterile pharmaceutical manufacturers impose the most stringent qualification protocols, with FDA 21 CFR Part 11 compliance for electronic records driving specification. European injectables specialists require thermal mapping documentation and IQ/OQ/PQ validation packages that extend procurement cycles.
- Cosmetic Manufacturers:L'Oréal and Estée Lauder supply chain partners prioritize rapid mold changeover for seasonal SKU launches.
- Specialty Chemical Producers:Agrochemical and industrial solvent packagers emphasize UN-certified barrier performance and chemical resistance testing.
By unit shipments, bottlers leads. By margin expansion, drug formulators is ahead as validation-intensive procurement reduces price sensitivity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU F-Gas Regulation deadlines are compressing equipment replacement cycles across German and Dutch bottling corridors. Chinese machinery capacity additions are reshaping export competition. Indian domestic preform production is scaling rapidly.
China
Guangdong and Zhejiang machinery builders are adding PET packaging equipment capacity to serve both domestic beverage bottlers and Southeast Asian export markets. GB standards for packaging machinery safety mandate redundant safety circuits that exceed baseline CE requirements. The Pearl River Delta hosts the densest concentration of blow molding machine manufacturing, with domestic producers redesigning guard enclosures to capture dual certifications.
Germany
Baden-Württemberg precision component suppliers dominate high-tolerance screw and barrel manufacturing for electric servo systems. The EU F-Gas Regulation accelerates refrigerant phase-out timelines, forcing converters toward electric platforms. Bottling clusters in Bavaria and North Rhine-Westphalia specify integrated filling-line architectures with energy recovery systems.
India
Maharashtra and Gujarat bottling cooperatives are backward-integrating preform production at 40% annual capacity growth to reduce import exposure. Central Electricity Authority grid stability concerns favor regenerative braking architectures for 24/7 mineral water operations. The Delhi-Mumbai Industrial Corridor anchors domestic machinery demand as Pepsi and Coca-Cola system suppliers scale captive preform capacity.
Japan
METI Green Transformation bonds subsidize energy-efficient manufacturing equipment, accelerating replacement cycles for aging hydraulic blow molding lines in Kanto and Kansai regions. Pharmaceutical packaging demand in Osaka-Tokyo corridors pulls precision stretch blow molding capacity into sterile fill-finish supply chains. Japanese bottlers specify permanent magnet synchronous motors for precision stretch rod control within 0.1 millimeter repeatability.
Brazil
ANVISA pharmaceutical packaging regulations are tightening traceability requirements in São Paulo and Rio de Janeiro pharmaceutical corridors. Brazilian bottlers leverage hybrid platforms to balance precision requirements against import tariff exposure on fully electric European equipment. The Southeast industrial belt dominates demand for integrated vision-inspection blow molding cells.
Global Pet Stretch Blow Molding Machines Market Competitive Landscape
Integrated filling-line architects and precision component specialists split the market between premium-tier system integration and mid-tier throughput economics. The vendor base concentrates around three strategic archetypes: European incumbents with validated pharmaceutical-grade platforms, Asian scale producers competing on capital efficiency, and Japanese precision specialists occupying sterile packaging niches. Competitive moves center on digital twin service unbundling and METI-subsidized fleet replacement programs.
Among European integrated system architects, Krones AG and Sacmi Imola represent the premium-tier positioning anchored by filling-line architecture dominance. SMI exemplifies aggressive throughput economics for high-volume carbonated soft drink operations. Nissei ASB Machine occupies the precision pharmaceutical niche where cavity-to-cavity consistency commands pricing power in sterile fill-finish supply chains.
| Leading Market Players |
|---|
| SMI |
| AOKI |
| Krones AG |
| W. Amsler Equipment |
| Sipa |
| Sacmi Imola |
| Guangzhou Tech-Long Packaging Machinery |
| Zhejiang Huangyan Lingma Plastic Machinery |
| Nissei ASB Machine |
| Others |
Supply & Pricing Matrix
Shanghai-Rotterdam container freight corridors transmit cost volatility from Baden-Württemberg precision component clusters to Indian bottling cooperatives, compressing margins on servo electric configurations while amplifying price spreads between CE-certified European systems and GB-standard Chinese alternatives.
Pricing Analysis
Geographic price spreads between German electric servo platforms and Guangdong hybrid alternatives now exceed the freight differential alone, reflecting certification tier premiums. Pricing stratifies across pharmaceutical-grade validation packages, beverage-grade throughput contracts, and economy-tier pneumatic units for chemical packaging. Cost compression in mid-tier servo configurations is intensifying because rare-earth magnet supply volatility feeds into permanent magnet motor bills of materials. Indian mineral water cooperatives exhibit highest price sensitivity, while sterile pharmaceutical formulators in Osaka-Tokyo corridors absorb premium positioning for cavity-to-cavity documentation.
Supply Chain Analysis
Tariff exposure between Germany and Brazil dominates procurement risk for ANVISA-regulated pharmaceutical packaging lines. Component sourcing draws from Baden-Württemberg for high-tolerance screws and barrels, Guangdong for frame fabrications, and Japan for permanent magnet synchronous motors. Single-source vulnerability concentrates in German precision component suppliers serving Asian machine builders. Distribution runs through OEM-direct channels for multinational bottlers, Alibaba Industrial for Southeast Asian spare parts, and third-party automation integrators in Vietnam and Indonesia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from performance-based availability subscriptions and virtual mold-tuning software licenses is expanding faster than hardware shipments, restructuring vendor economics toward recurring revenue architectures.
For Market Incumbents: Insulate premium positioning by embedding digital twin architectures into long-term service contracts that lock in beverage bottlers with 10-year availability guarantees. Deepen upstream control over precision screw and barrel manufacturing to offset Baden-Württemberg supplier concentration risk. Capture METI Green Transformation bond-funded replacement cycles in Japan with subsidized financing packages. For New Entrants and Emerging Players: Mid-market hybrid platforms for Brazilian pharmaceutical contractors facing ANVISA traceability mandates represent the most penetrable entry point. Vietnamese and Indonesian contract manufacturers resisting multi-year service lock-ins offer white-space for third-party rebuild services on servo drives. Lead with unbundled spare parts availability through Alibaba Industrial channels against OEM maintenance bundling. For Investors and Strategic Acquirers: EU F-Gas Regulation refrigerant phase-down deadlines reshape the acquisition landscape toward electric and hybrid platform specialists with validated pharmaceutical-grade architectures. Target precision component suppliers with polymer rheology simulation capabilities that machine builders struggle to recruit organically. Watch Japan METI bond disbursement velocity as the signal for fleet replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Service Unbundling | Virtual mold-tuning software collapses commissioning timelines for German bottlers. |
| Backward Integration into Preform Production | Indian bottlers scaling captive capacity reduce Southeast Asian import exposure. |
| Hybrid Platform Certification | ANVISA-compliant architectures balance precision against Brazilian import tariffs. |
| Regenerative Braking Architecture Deployment | Grid stability concerns in Maharashtra favor energy recovery for 24/7 operations. |
| Precision Component Supplier Acquisition | Baden-Württemberg screw and barrel expertise anchors servo electric reliability. |
Research Methodology
Desk research of EU F-Gas regulatory filings, METI Green Transformation bond disbursement records, and ANVISA pharmaceutical packaging guidelines preceded structured interviews with plant engineers at beverage bottlers, aftermarket service heads at OEMs, procurement leads at pharmaceutical formulators, and automation integrators in Southeast Asia. Secondary validation drew from customs trade data on PET machinery imports, SEC filings of listed packaging equipment manufacturers, and industrial energy consumption disclosures. Bottom-up unit shipment estimates triangulated against top-down market sizing from macroeconomic production indicators.
Assumptions held fixed include EU F-Gas refrigerant phase-down timelines, China GB standards enforcement trajectories, and India grid stability conditions; variables tested included copper and rare-earth magnet price corridors, carbon border adjustment mechanism coverage expansion, and polypropylene substitution rates in hot-fill applications. Segmentation modeling spanned machine architecture, drive technology, end-use application, and regional regulatory cluster. CAGRs derived from logistic curve fitting to replacement cycle data and capacity expansion announcements across the projection horizon. Industry-specific inputs incorporated pharmaceutical validation protocol complexity indices and beverage lightweighting target trajectories.
Macroeconomic conditions sit as an overlay; deviation in energy tariff trajectories, freight rate corridors, or central bank financing costs would shift the trajectory of capital equipment replacement cycles. Forecasts reflect documented assumptions on regulatory enforcement intensity and technology substitution elasticities. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Overwrapping Machines Market
Packaging Machinery
Poly Bagging Machines Market
Packaging Machinery
EPS Pre-Expander Machines Market
Packaging Machinery
Global Film Coating Machine Market
Packaging Machinery
Labeling Machines Market
Packaging Machinery
Side Load Case Packing Machines Market
Packaging Machinery
Die Cutting Machine Market
Packaging Machinery
Meter-Mix Dispensing Machine Market
Packaging Machinery
Vertical Strapping Machines Market
Packaging Machinery
Lid Applicator Machine Market
Packaging Machinery
Horizontal Flow Wrapping Machines Market
Packaging Machinery
Paper Embossing Machine Market
Packaging Machinery
Tray Sealer Machines Market
Packaging Machinery
Carton Folding and Gluing Machine Market
Packaging Machinery
Automatic Filling Machine Market
Packaging Machinery
Wet Ink Coding Machines Market