
 Autofill Drums & Totes Machines Market | 2026-2036
Autofill Drums & Totes Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Autofill Drums & Totes Machines Market Analytics
Modular filling configurations is rebalancing buyer preference away from monolithic drum lines toward interchangeable tote-and-bulk modules. Krones AG leverages its rotary filler architecture to anchor large-format chemical contracts. Tetra Pak competes through aseptic integration expertise that extends from carton to bulk liquid handling. Scholle IPN specializes in bag-in-box transitions that occupy niche pharmaceutical and food-grade tote applications.
Autofill drums and totes machines are automated liquid dispensing systems engineered to fill containers ranging from 55-gallon drums to intermediate bulk containers (IBCs) up to 550 gallons, utilizing precision pump mechanisms, level sensors, and programmable logic controllers to achieve fill accuracies within plus or minus 0.1 percent by volume. These systems serve chemical, food, pharmaceutical, and industrial packaging operations where containment integrity, batch traceability, and throughput speed determine operational economics. Automatic drums command the largest installed base due to sustained demand from high-volume chemical manufacturing, though totes represent the fastest-expanding configuration as just-in-time logistics and reduced material handling costs reshape downstream distribution. Pressure fill technology leads in viscous and foam-prone applications, while flow meter systems capture margin pools in pharmaceutical production where in-line verification eliminates manual sampling.
EPA spill prevention regulations and OSHA process safety management standards mandate secondary containment and automated shutoff systems for hazardous liquid filling operations in the United States. REACH compliance and CE marking requirements across Europe enforce material compatibility documentation and electromagnetic safety certification for equipment deployed in chemical and food processing environments. India's BIS machinery safety standards and China's GB standards for packaging equipment add parallel conformity layers for suppliers targeting Asia-Pacific expansion. Stakeholders must monitor evolving carbon border adjustment mechanisms and solvent emission thresholds that will reshape equipment specification criteria and regional sourcing decisions.
Market Dynamics
Modular filling configurations are rebalancing buyer preference away from monolithic drum lines toward interchangeable tote-and-bulk modules that reduce capital lock-in and accommodate batch-size volatility. Chemical manufacturers in Germany and the United States are expanding procurement of pressure-fill systems to meet EPA and OSHA containment standards.
Growth Catalysts
- REACH compliance mandates:European chemical processors must document material compatibility and electromagnetic safety certification, forcing equipment upgrades across filling operations.
- India's BIS machinery safety standards:Domestic pharmaceutical and food packaging lines require certified autofill systems, creating localized demand pull for compliant machinery.
- Just-in-time logistics adoption:Downstream distributors are consolidating toward intermediate bulk containers to cut material handling costs and warehouse footprint.
Market Restraints
- Stainless steel input volatility:Grade 316L price swings compress margins for equipment fabricators serving pharmaceutical-grade specifications.
- Pump mechanism supply concentration:Precision positive-displacement pump assemblies concentrate among German and Japanese suppliers, creating single-source vulnerability.
- Pressure-fill technical ceiling:Highly aerated or shear-sensitive formulations remain difficult to handle without foam suppression additives that complicate clean-in-place protocols.
Strategic Opportunities
- China's dual carbon goals:Energy-efficient filling systems with regenerative drives qualify for provincial green manufacturing incentives.
- Aseptic tote integration:Convergence of isolator technology with bulk liquid handling opens pharmaceutical biologics applications previously served by disposable bag systems.
- Remote diagnostics channels:Equipment-as-a-service models with predictive maintenance subscriptions penetrate mid-tier chemical processors seeking to avoid capital expenditure.
Industry Challenges
- PLC programming specialization:Shortage of technicians fluent in IEC 61131-3 standards delays commissioning and retrofit timelines.
- CE-MDR dual certification burden:European pharmaceutical equipment must satisfy machinery directive and medical device regulation simultaneously, extending approval cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autofill Drums & Totes Machines Market |
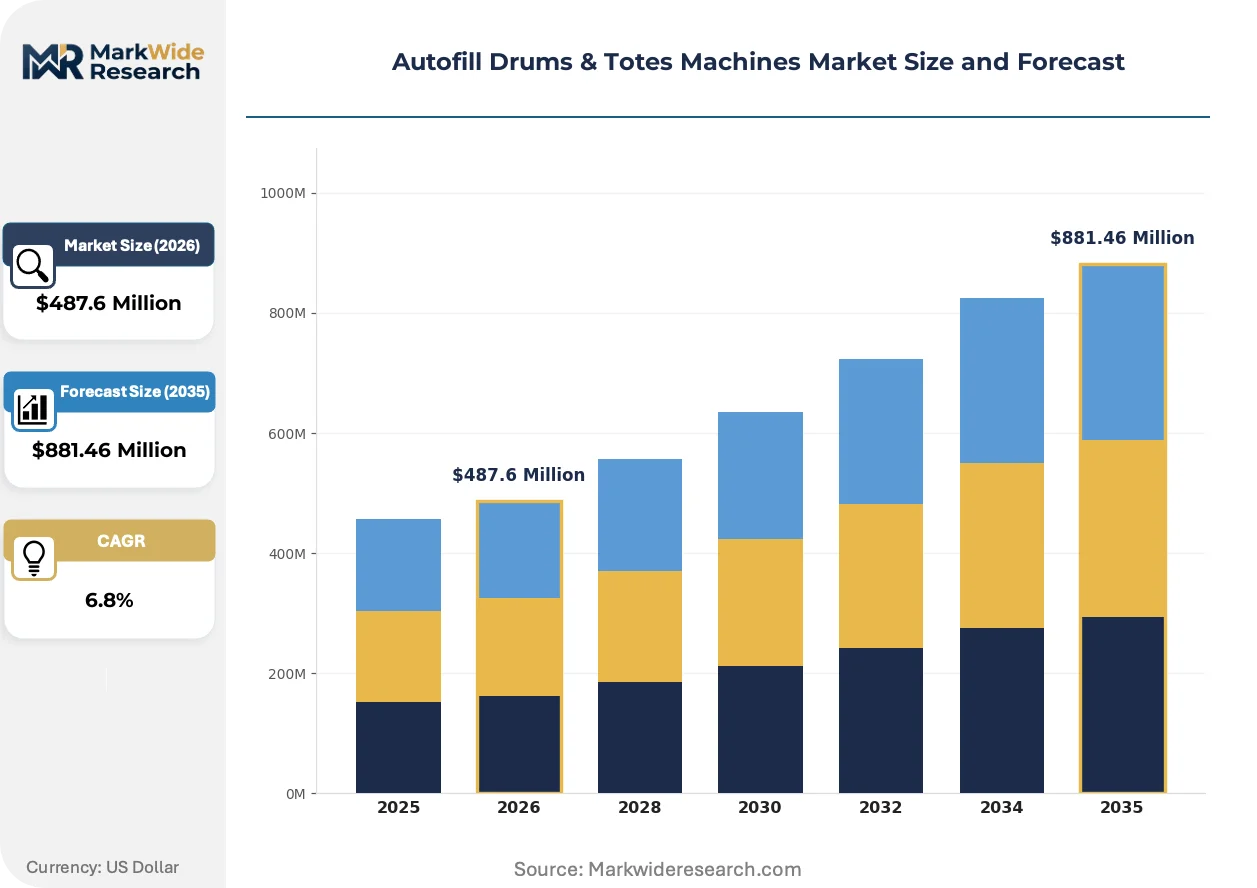
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Drums, Semi-Automatic Drums, Totes, Bulk Containers Application: Food Processing, Chemical Manufacturing, Pharmaceutical Production, Industrial Packaging End User: Manufacturers, Distributors, Retailers, Service Providers Technology: Gravity Fill, Pressure Fill, Volumetric Fill, Flow Meter |
| Companies Covered | Sidel, Krones AG, Tetra Pak, Scholle IPN, PASE Group, Ronchi Mario, Comac, Specialty Equipment, Eascan Automation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autofill Drums & Totes Machines Market Evolving Landscape
Precision pump mechanisms with in-line verification are displacing gravimetric sampling across pharmaceutical batch operations, while connectivity architectures enable real-time fill accuracy monitoring. These shifts compress quality assurance cycles and reduce manual intervention.
Coriolis mass flow meters are expanding into high-viscosity chemical filling applications previously dominated by volumetric piston pumps. Specialty chemical manufacturers in the United States are adopting these systems to eliminate density compensation errors in multi-product lines. This technology is expanding into foam-prone formulations by enabling shear-rate control that preserves product integrity.
EPA spill prevention regulations now mandate automated shutoff systems and secondary containment for hazardous liquid filling operations in the United States. Chemical processors must retrofit existing lines or specify new equipment with integrated containment sumps and leak detection sensors. Pressure-fill system suppliers are responding with modular containment modules that simplify compliance without full line replacement.
Buyer procurement is consolidating toward outcome-based performance contracts that tie payment to verified fill accuracy and uptime metrics. Mid-tier food processors in India and China are bypassing traditional distributor channels to engage directly with equipment manufacturers for specification and commissioning support. This pattern is most visible in pharmaceutical contract manufacturing organizations seeking to unbundle after-sales service from initial capital purchase.
Autofill Drums & Totes Machines Market Segmentation
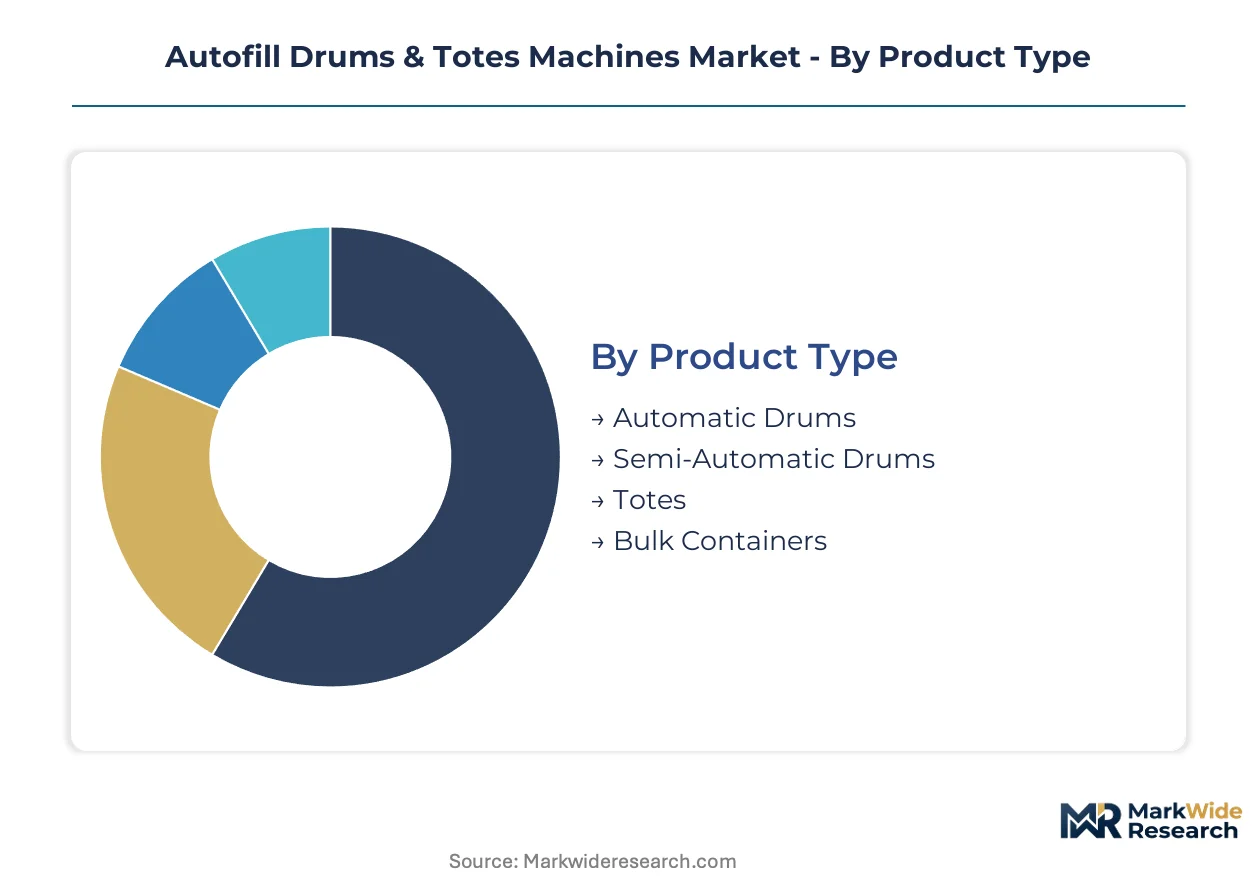
Autofill drums and totes machines serve divergent compliance regimes across chemical, pharmaceutical, and food sectors, making segmentation essential for matching equipment specifications to regulatory thresholds. Each category carries distinct certification burdens that determine procurement priorities and supplier qualification pathways.
Product Type:
CE marking and EPA spill prevention regulations impose divergent hardware requirements across drum versus tote configurations, with stainless steel grade specifications varying by containment volume and hazard classification.
- Automatic Drums:Fully automated 55-gallon drum lines integrate programmable logic controllers with level sensors and automated shutoff systems to meet OSHA process safety management standards. Chemical manufacturers in Germany and the United States anchor demand here, driven by high-volume production lines requiring containment integrity documentation for EPA compliance.
- Totes:Intermediate bulk container systems accommodate 275-550 gallon volumes with modular filling architectures that reduce material handling costs in just-in-time logistics networks. Pharmaceutical contract manufacturers in India are expanding procurement of these systems as BIS machinery safety standards tighten certification requirements for domestic packaging lines.
- Semi-Automatic Drums:Hybrid configurations blend manual loading with automated dispensing for mid-tier processors seeking capital expenditure flexibility.
- Bulk Containers:Large-format systems exceed standard tote capacities for specialty chemical and industrial fluid handling applications.
Automatic drums sits at the top of the volume ranking, with totes climbing the fastest.
Application:
End-use concentration determines margin structure, with pharmaceutical and chemical segments commanding premium pricing for validated systems while food processing operates on throughput efficiency metrics.
- Chemical Manufacturing:Pressure-fill systems dominate this segment for viscous and foam-prone formulations, with secondary containment and leak detection sensors mandated under EPA regulations. Producers in the United States retrofit existing lines or specify new equipment with integrated containment sumps to satisfy spill prevention requirements.
- Pharmaceutical Production:Volumetric and flow meter technologies capture this segment through in-line verification capabilities that eliminate manual sampling. Batch operations across India and China are driving adoption as these systems compress quality assurance cycles and support batch traceability requirements.
- Food Processing:Gravity fill technology anchors this segment for liquid food products where shear sensitivity and foam control determine equipment selection.
- Industrial Packaging:General-purpose filling systems serve lubricants, coatings, and non-hazardous industrial fluids with standardized configurations.
Chemical manufacturing commands the largest installed base, while pharmaceutical production gains share fastest.
End User:
Procurement authority varies sharply across the value chain, with manufacturers specifying technical requirements while distributors prioritize interchangeability and service providers focus on commissioning support.
- Manufacturers:Chemical and pharmaceutical producers with captive filling operations specify equipment directly, engaging suppliers for specification and commissioning support rather than distributor channels. These buyers tie payment to verified fill accuracy and uptime metrics under outcome-based performance contracts.
- Distributors:Third-party logistics operators consolidate toward intermediate bulk containers to cut warehouse footprint, driving demand for modular tote systems with rapid changeover capabilities.
- Retailers:Private-label food and chemical brand owners contract filling services rather than owning equipment assets.
- Service Providers:Contract manufacturing organizations and toll processors seek equipment-as-a-service models with predictive maintenance subscriptions to avoid capital expenditure.
Manufacturers anchor procurement volume, with service providers expanding most quickly through subscription-based acquisition models.
Technology:
Fill mechanism selection hinges on fluid properties and verification requirements, with gravimetric methods yielding to in-line mass flow measurement in precision applications.
- Pressure Fill:Positive-displacement pump systems with automated shutoff dominate viscous, foam-prone, and hazardous chemical applications. German and Japanese suppliers concentrate precision pump mechanism production, creating single-source vulnerability for fabricators serving this segment.
- Flow Meter:Coriolis mass flow meters are displacing gravimetric sampling across pharmaceutical batch operations, enabling real-time fill accuracy monitoring and density compensation for multi-product lines. Specialty chemical manufacturers in the United States adopt these systems to eliminate density errors.
- Gravity Fill:Passive dispensing systems serve food processing lines where product integrity depends on minimal shear exposure.
- Volumetric Fill:Piston and pump-based volume measurement systems serve mid-tier applications with moderate accuracy requirements.
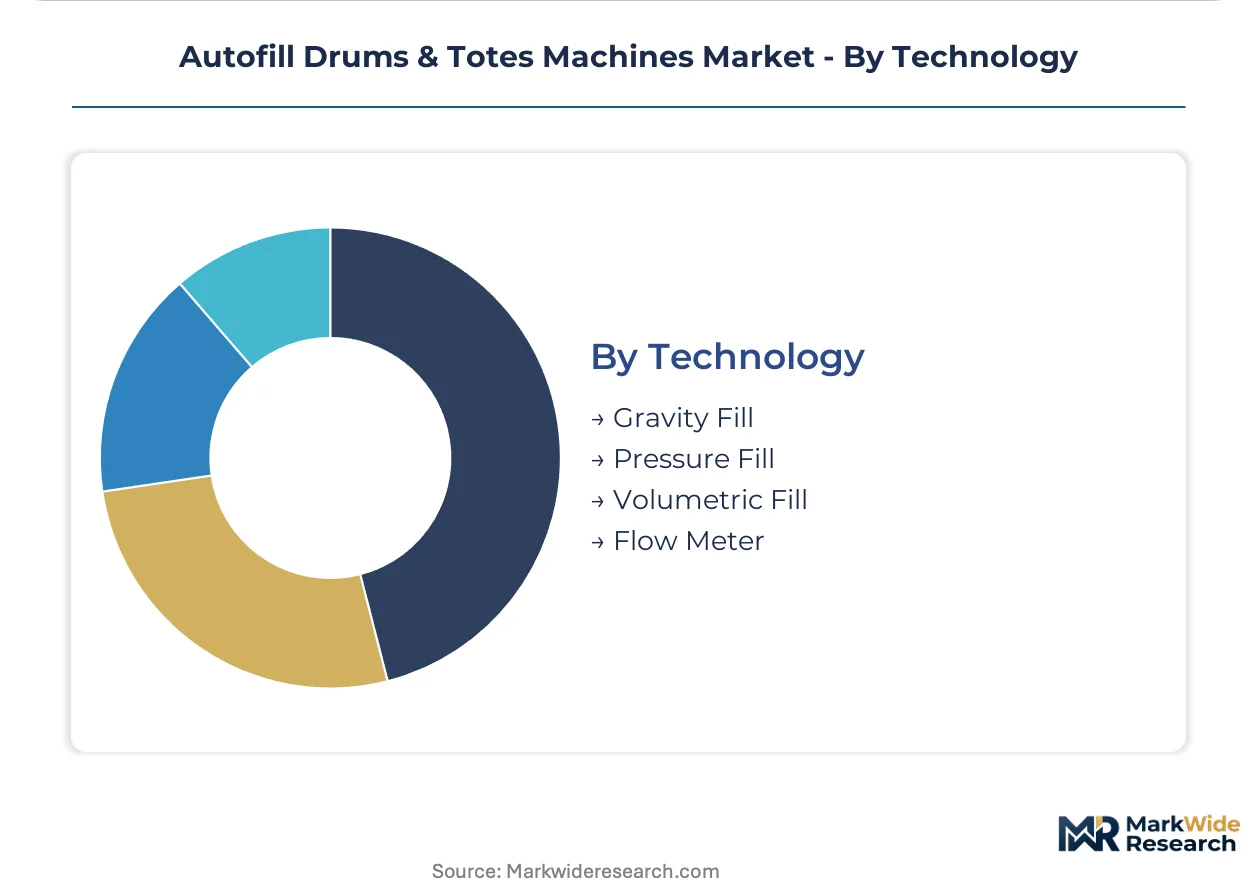
Pressure fill holds the largest installed base, with flow meter systems ascending fastest on pharmaceutical validation demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial liquid filling technology first scaled in post-war Germany and the United States, where chemical manufacturing density demanded automated containment systems. Today's procurement patterns still trace these origins, though capacity expansion now concentrates in Asia-Pacific pharmaceutical clusters and Middle Eastern petrochemical zones.
United States
Chemical manufacturers in Texas and Louisiana are retrofitting pressure-fill lines to satisfy EPA spill prevention mandates. OSHA process safety management standards now require automated shutoff systems and secondary containment sumps for hazardous liquid operations. Houston's petrochemical corridor anchors North American demand, with specialty chemical producers adopting Coriolis mass flow meters to eliminate density compensation errors across multi-product lines.
Germany
REACH compliance documentation and CE machinery directive certification force equipment upgrades across Rhineland chemical processing zones. Precision pump mechanism suppliers concentrate in Baden-Württemberg, creating single-source vulnerability for fabricators serving pharmaceutical-grade specifications. Bavaria's industrial machinery cluster drives modular filling architecture development, with rotary filler systems capturing large-format chemical contracts.
China
Provincial green manufacturing incentives under dual carbon goals accelerate procurement of energy-efficient filling systems with regenerative drives. GB standards for packaging equipment add conformity layers for domestic and export-bound machinery. Yangtze River Delta pharmaceutical contract manufacturers expand volumetric system adoption as batch traceability requirements tighten under NMPA oversight.
India
BIS machinery safety standards tighten certification requirements for domestic pharmaceutical and food packaging lines. Maharashtra and Gujarat chemical processors drive automatic drum system procurement for high-volume production. Bangalore's biologics manufacturing cluster experiments with aseptic tote integration, converging isolator technology with bulk liquid handling previously served by disposable bag systems.
Japan
METI industrial efficiency programs promote predictive maintenance subscriptions and equipment-as-a-service models among mid-tier processors. JIS standards compatibility remains essential for machinery exports across ASEAN markets. Osaka-Kobe industrial zone maintains precision positive-displacement pump assembly concentration, though supply chain vulnerability concerns push fabricators toward dual-sourcing strategies.
Autofill Drums & Totes Machines Market Competitive Landscape
The competitive structure tilts toward diversified packaging machinery conglomerates with cross-sector liquid handling expertise. Three archetypes dominate: rotary filler specialists leveraging architectural modularity, aseptic integration experts extending carton expertise into bulk formats, and bag-in-box transition specialists occupying niche pharmaceutical applications. Capacity expansion and technology licensing represent the dominant competitive moves, with fabricators seeking to unbundle after-sales service from initial capital purchase.
Among European-headquartered conglomerates, Krones AG exemplifies the rotary filler architecture archetype, while Tetra Pak occupies a position bridging aseptic carton and bulk liquid handling expertise. Scholle IPN represents the bag-in-box transition specialist tier, with Sidel anchoring the diversified packaging systems archetype across multiple liquid filling modalities.
| Leading Market Players |
|---|
| Sidel |
| Krones AG |
| Tetra Pak |
| Scholle IPN |
| PASE Group |
| Ronchi Mario |
| Comac |
| Specialty Equipment |
| Eascan Automation |
| Others |
Value Network & Pricing Analysis
Procurement consolidation among mid-tier chemical processors in India and China toward outcome-based performance contracts is forcing equipment fabricators to unbundle after-sales service from capital purchase, compressing upfront pricing while extending revenue recognition timelines. This shift rewards suppliers with captive service networks and penalizes those dependent on third-party commissioning support.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates equipment transactions, with differentiation driven by stainless steel grade certification and after-sales service bundling. Cost compression in the economy tier is intensifying because Grade 316L price volatility erodes fabricator margins. Contract manufacturing organizations exhibit highest price sensitivity due to capital constraints, while multinational chemical producers in Germany and the United States prioritize validated system performance over unit cost.
Supply Chain Analysis
Refurbishment flows for precision positive-displacement pump assemblies concentrate in Baden-Württemberg and Osaka-Kobe industrial zones, creating circular supply channels that extend component lifecycle. Equipment fabrication draws from German and Japanese pump mechanism suppliers, stainless steel feedstock from Chinese mills, and programmable logic controller modules from Taiwanese semiconductor fabricators. Single-source vulnerability in precision pump assemblies represents the dominant structural risk. Distribution runs through direct manufacturer engagement for specification and commissioning, bypassing traditional distributor channels in pharmaceutical and food processing verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where procurement of EPA-compliant pressure-fill systems in the United States carries 15-20% cost premiums versus functionally equivalent CE-marked equipment manufactured for European REACH compliance, creating margin expansion opportunities for dual-certified fabricators.
For Market Incumbents: Deepen backward integration into precision pump mechanism production to offset single-source vulnerability from German and Japanese suppliers. Anchor large-format chemical contracts through rotary filler architecture modularity while defending against aseptic integration specialists encroaching from carton expertise into bulk liquid handling. For New Entrants and Emerging Players: Mid-tier food processors in India seeking capital expenditure flexibility represent an underserved buyer archetype bypassing traditional distributor channels. Penetrate this segment through equipment-as-a-service models with predictive maintenance subscriptions, leveraging BIS machinery safety standard certification as entry qualification. For Investors and Strategic Acquirers: Asymmetric upside sits with modular filling architecture specialists possessing isolator technology integration capabilities for pharmaceutical biologics applications. Long-term viability centers on convergence with disposable bag system replacement cycles. Monitor NMPA batch traceability requirement tightening in China as inflection indicator for volumetric system demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pump Mechanisms | Mitigates single-source dependency on Baden-Württemberg and Osaka-Kobe suppliers for precision assemblies. |
| Aseptic Tote Integration Development | Converges isolator technology with bulk liquid handling to capture pharmaceutical biologics contracts from disposable bag systems. |
| Equipment-as-a-Service Launch | Penetrates mid-tier chemical processors seeking to avoid capital expenditure through predictive maintenance subscriptions. |
| Dual Certification Investment | Captures margin arbitrage between EPA-compliant and CE-marked equipment specifications across Atlantic procurement bases. |
| Provincial Green Manufacturing Alignment | Qualifies energy-efficient systems with regenerative drives for China's dual carbon goal incentives in Yangtze River Delta clusters. |
Research Methodology
Bottom-up pharmaceutical and chemical processor demand modeling reconciled against top-down precision pump mechanism supplier tracking forms the analytical core of this study. Primary interviews with plant managers, OEM procurement teams, aftermarket service heads, and technical R&D directors at equipment fabricators cross-validated against customs and trade data, SEC filings from diversified packaging machinery conglomerates, and machinery safety certification databases from BIS and notified bodies.
Historical trendline analysis across automatic drum, tote, and semi-automatic configurations established baseline penetration patterns, with projection modeling segmented by fill technology, end-use industry, containment volume tier, and regional regulatory cluster. CAGRs were derived from equipment shipment tracking and capacity expansion announcements across the analysis window, incorporating stainless steel input cost indices and provincial green manufacturing incentive qualification criteria as industry-specific forecast inputs.
Underlying measurement precision varies by segment; pharmaceutical production and chemical manufacturing carry tighter precision than industrial packaging due to validated system documentation requirements. Forecasts incorporate assumptions regarding REACH compliance enforcement continuity, BIS machinery safety standard implementation timelines, and Grade 316L price trajectory stability. Practitioners should monitor EPA spill prevention regulation amendment cycles and carbon border adjustment mechanism rollout for early signals of equipment specification criteria shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
In-Line Thermoforming Machine Market
Packaging Machinery
Bagging Machine Market
Packaging Machinery
Beverage Can Seamers Market
Packaging Machinery
Oil Packing Machine Market
Packaging Machinery
Granule Filling Machine Market
Packaging Machinery
Bundling Machine Market
Packaging Machinery
Global Food and Beverage Packaging Machinery Market
Packaging Machinery
Metal Banding Machine Market
Packaging Machinery
Tamper Evidence Machinery Market
Packaging Machinery
Blow Fill Seal (BFS) Technology Market
Packaging Machinery
Pouch Packaging Machine Market
Packaging Machinery
Overwrapping Machines Market
Packaging Machinery
Cling Wrap Machine Market
Packaging Machinery
Stretch Blow Molding Machines Market
Packaging Machinery
Corrugated Box Making Machine Market
Packaging Machinery
Liquid Pouch Filling and Sealing Machine Market