
 Ruthenium Tetroxide Market | 2026-2036
Ruthenium Tetroxide Market Size, Share, and Industry Trends Forecast 2026-2036
Ruthenium Tetroxide Market Outlook
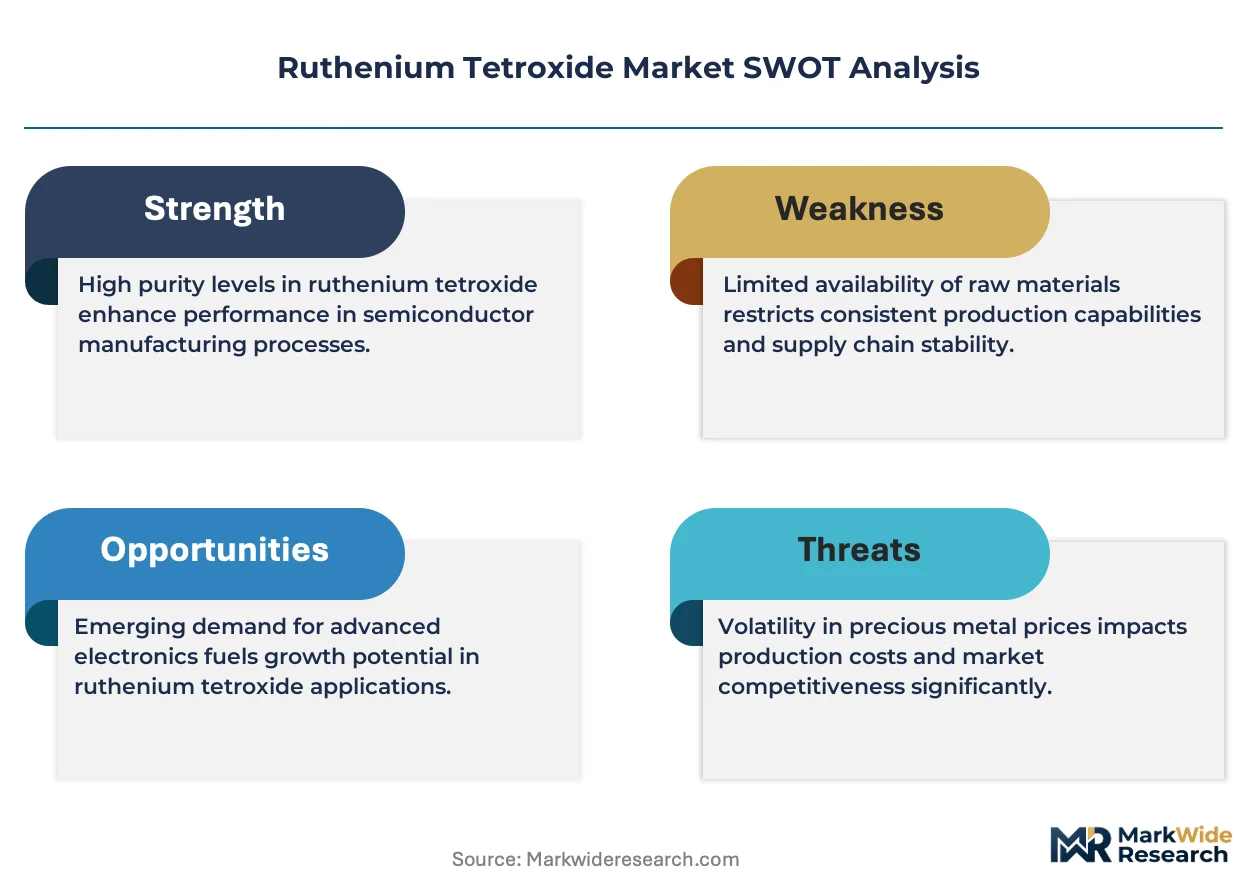
High-purity grade specifications are reorganizing competitive dynamics across the ruthenium tetroxide landscape. Johnson Matthey leverages its integrated precious metal refining network to secure feedstock continuity for electronic-grade output. PJSC MMC Norilsk Nickel anchors global primary ruthenium supply through its Arctic mining and smelting complex. American Elements differentiates via specialized packaging and lot-traceability protocols serving research-intensive buyers.
Ruthenium tetroxide is a volatile, yellow crystalline solid (RuO₄, molecular weight 165.07 g/mol) produced by oxidation of ruthenium metal or compounds, functioning primarily as a powerful oxidizing agent and specialized thin-film precursor in semiconductor fabrication. High-purity product grades command premium positioning as extreme ultraviolet lithography nodes advance below 7 nanometers, while analytical grade segments sustain steady volume through materials characterization laboratories. Semiconductor manufacturing applications represent the fastest-expanding demand pool, whereas electroplating end-uses maintain mature, volume-stable consumption patterns in connector and contact manufacturing.
EPA hazardous air pollutant standards and OSHA permissible exposure limits constrain domestic manufacturing and handling protocols, while REACH registration requirements in Europe govern import volumes and downstream user obligations. South Korea's MFDS chemical control regulations and China's MEE hazardous chemical management framework are tightening storage and transport compliance for cross-border specialty chemical trade. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions that could displace competing chemistries and redirect demand toward ruthenium-based alternatives.
Market Dynamics
Semiconductor node advancement below 3 nanometers is concentrating ruthenium tetroxide demand among a handful of advanced foundry operators, compressing supplier qualification timelines and tightening purity specifications.
Growth Catalysts
- Extreme ultraviolet lithography scaling:Sub-7nm patterning requirements are pulling electronic-grade ruthenium tetroxide into front-end-of-line processes at Taiwan Semiconductor Manufacturing and Samsung Foundry.
- China's dual carbon framework:MEE hazardous chemical management rules are filtering out lower-tier suppliers, redirecting procurement toward certified high-purity producers.
- Per- and polyfluoroalkyl substance restrictions:REACH and state-level US bans on PFAS chemistries are opening substitution pathways for ruthenium-based oxidation in specialized etching applications.
Market Restraints
- Primary supply concentration:Arctic smelting complexes in Russia anchor 40% of global ruthenium feedstock, exposing downstream processors to geopolitical transit friction.
- Volatile precursor costs:Sponge ruthenium price swings from 2022-2024 compressed formulator margins and delayed capacity expansion commitments.
- OSHA exposure thresholds:Permissible limits of 0.1 mg/m³ constrain US-based synthesis scale-up and necessitate costly containment infrastructure.
Strategic Opportunities
- Indian specialty chemical manufacturing:PLI scheme incentives for electronic materials are drawing packaging and formulation investment away from traditional East Asian hubs.
- Atomic layer deposition convergence:Ruthenium tetroxide precursor chemistry is intersecting with ALD tool advances to enable conformal seed layers in 3D NAND stacking.
- Research-grade channel expansion:Direct-to-laboratory distribution via specialized chemical marketplaces is bypassing traditional distributor markups for analytical-grade volumes.
Industry Challenges
- Cleanroom-qualified logistics:Cross-border transport of pyrophoric precursors requires MFDS, MEE, and EPA-aligned documentation that extends delivery lead times.
- Patent thickets around purification:Disputes over zone-refining methods for electronic-grade material are complicating new entrant licensing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ruthenium Tetroxide Market |
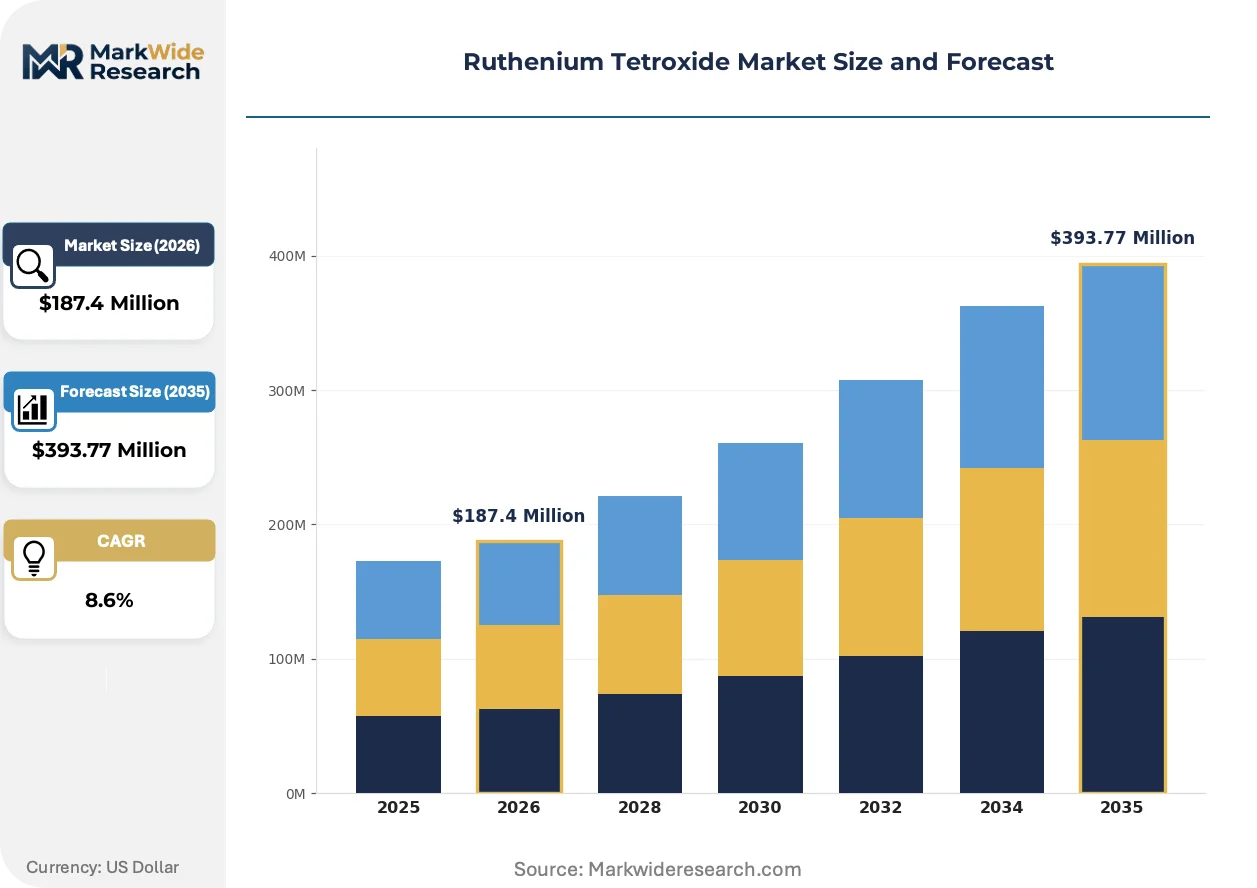
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Purity, Analytical Grade, Technical Grade, Industrial Grade Application: Catalyst, Chemical Synthesis, Semiconductor Manufacturing, Electroplating End User: Pharmaceuticals, Electronics, Chemical Industry, Research Institutions Packaging Type: Drum, Bottle, Canister, Bulk |
| Companies Covered | Johnson Matthey, American Elements, ESPI Metals, PJSC MMC Norilsk Nickel, Aspira Scientific, FURUYA METAL Co., Ltd, Reade International Corp., Metakem GmbH, J&K Scientific Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ruthenium Tetroxide Market Strategic Shifts
Process chemistry and regulatory compliance are diverging sharply between legacy semiconductor nodes and leading-edge fabrication, forcing suppliers to maintain dual product architectures.
Electronic-grade ruthenium tetroxide is bifurcating into distinct specification tiers: legacy 99.9% purity serving mature node electroplating versus 99.999% material qualified for EUV resists and atomic layer deposition. Samsung Foundry and Intel are accelerating qualification of the higher grade, compressing the window for mid-tier suppliers to upgrade. This split is fragmenting the supplier base into integrated precious metal refiners versus specialized gas/chemical formulators.
REACH authorization requirements for Substances of Very High Concern are tightening downstream user obligations for ruthenium compound importers into the European Economic Area. ECHA's 2023-2024 dossier updates have reclassified certain ruthenium salts, forcing reformulation of analytical reagents and extended safety data sheet revision cycles. German and French chemical distributors are consolidating supplier panels to reduce compliance audit burden.
Long-term supply agreements are displacing spot market purchasing among South Korean memory manufacturers confronting volatile sponge metal pricing. SK Hynix and Samsung Electronics have shifted toward 24-36 month offtake contracts with fixed purity escalators, compressing working capital flexibility for smaller formulators. This contractual pivot is most pronounced in Pyeongtaek and Yongin manufacturing clusters where just-in-time precursor delivery remains critical.
Ruthenium Tetroxide Market Segmentation
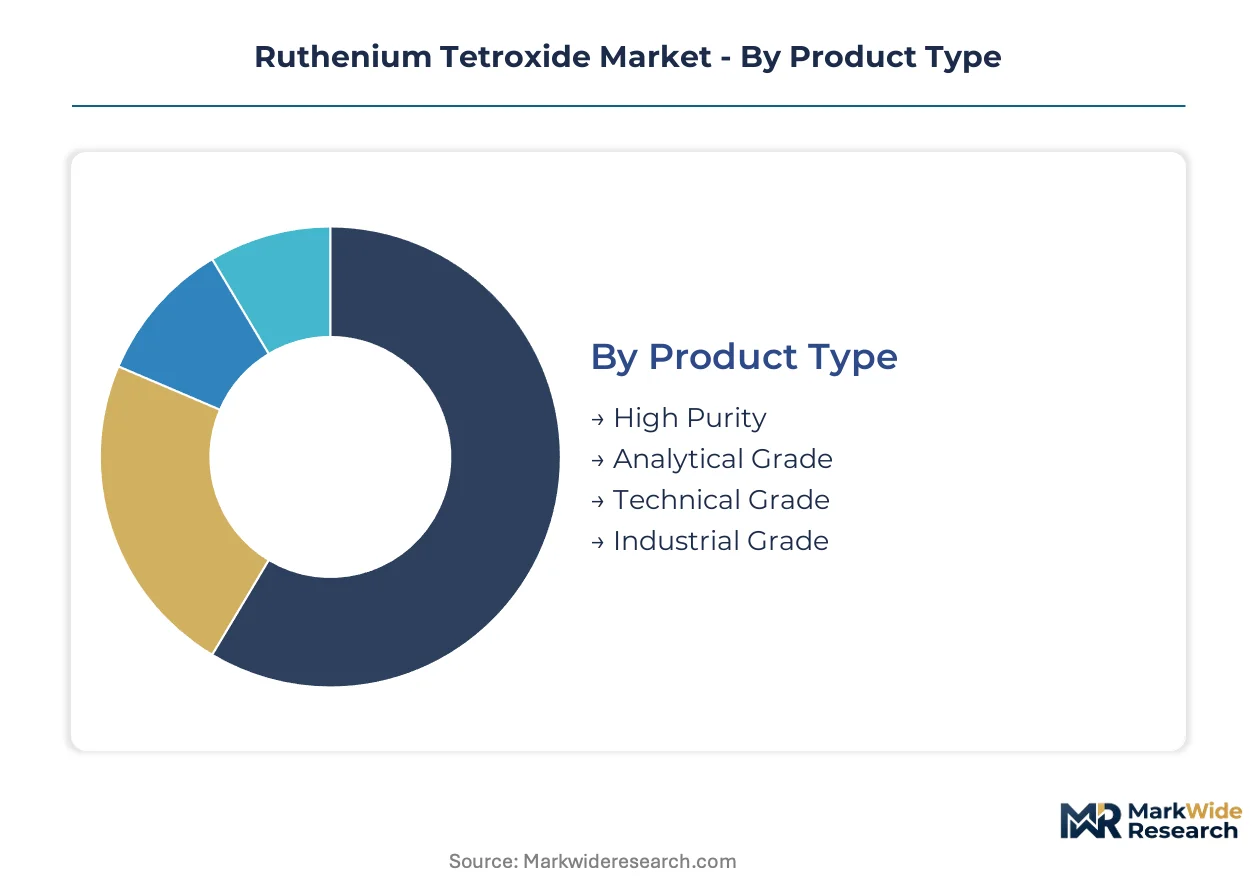
Ruthenium tetroxide procurement channels diverge sharply between bulk industrial buyers and precision-driven semiconductor fabs. Channel specialization dictates packaging, documentation, and purity validation requirements across each segment tier.
Product Type:
Channel-mix patterns split electronic-grade material through direct refiner relationships while analytical grades flow via specialized chemical distributors.
- High Purity:Electronic-grade specifications at 99.999% purity serve EUV lithography and atomic layer deposition processes. Samsung Foundry and TSMC procurement contracts specify lot-traceable material with sub-ppb metallic contamination limits.
- Analytical Grade:Standardized at 99.9% purity for materials characterization laboratories and quality control applications. Research institutions in Germany and Japan drive steady volume through certified chemical marketplaces with full SDS documentation packages.
- Technical Grade:Intermediate purity tier serves electroplating formulators requiring consistent oxidation potential without semiconductor-grade certification overhead.
- Industrial Grade:Bulk volumes for chemical synthesis operations prioritize unit cost over traceability, moving through commodity chemical distributors.
By volume, Industrial Grade leads. By growth pace, High Purity is climbing the fastest.
Application:
Cost-tier stratification separates premium-priced semiconductor precursors from mature electroplating chemistries with compressed margins.
- Semiconductor Manufacturing:Front-end-of-line patterning and seed layer deposition at sub-7nm nodes. South Korean foundry operations in Pyeongtaek and Yongin clusters anchor demand concentration as EUV scaling accelerates.
- Electroplating:Connector and contact manufacturing for automotive and telecommunications hardware. Mature demand profile with volume-stable consumption patterns across German and Chinese plating facilities.
- Catalyst:Specialized oxidation chemistry for fine chemical synthesis, particularly pharmaceutical intermediate production.
- Chemical Synthesis:Broad-spectrum oxidizing agent applications in organic chemistry transformation protocols.
Semiconductor Manufacturing commands the steepest expansion trajectory. Electroplating retains the largest installed demand base.
End User:
Customer-type segmentation separates capital-intensive electronics manufacturers from grant-funded research operations with divergent procurement cycles.
- Electronics:Memory and logic device manufacturers requiring just-in-time precursor delivery with cleanroom-qualified logistics. SK Hynix and Samsung Electronics long-term offtake contracts now span 24-36 month horizons.
- Research Institutions:University and national laboratory buyers prioritizing small-lot flexibility and technical documentation over unit economics. Direct-to-laboratory distribution channels are displacing traditional distributor markups.
- Chemical Industry:Specialty and commodity chemical producers integrating ruthenium tetroxide into formulated product lines.
- Pharmaceuticals:API manufacturers employing selective oxidation in complex molecule synthesis pathways.
Electronics generates the highest revenue per kilogram. Research Institutions show the most volatile demand pattern.
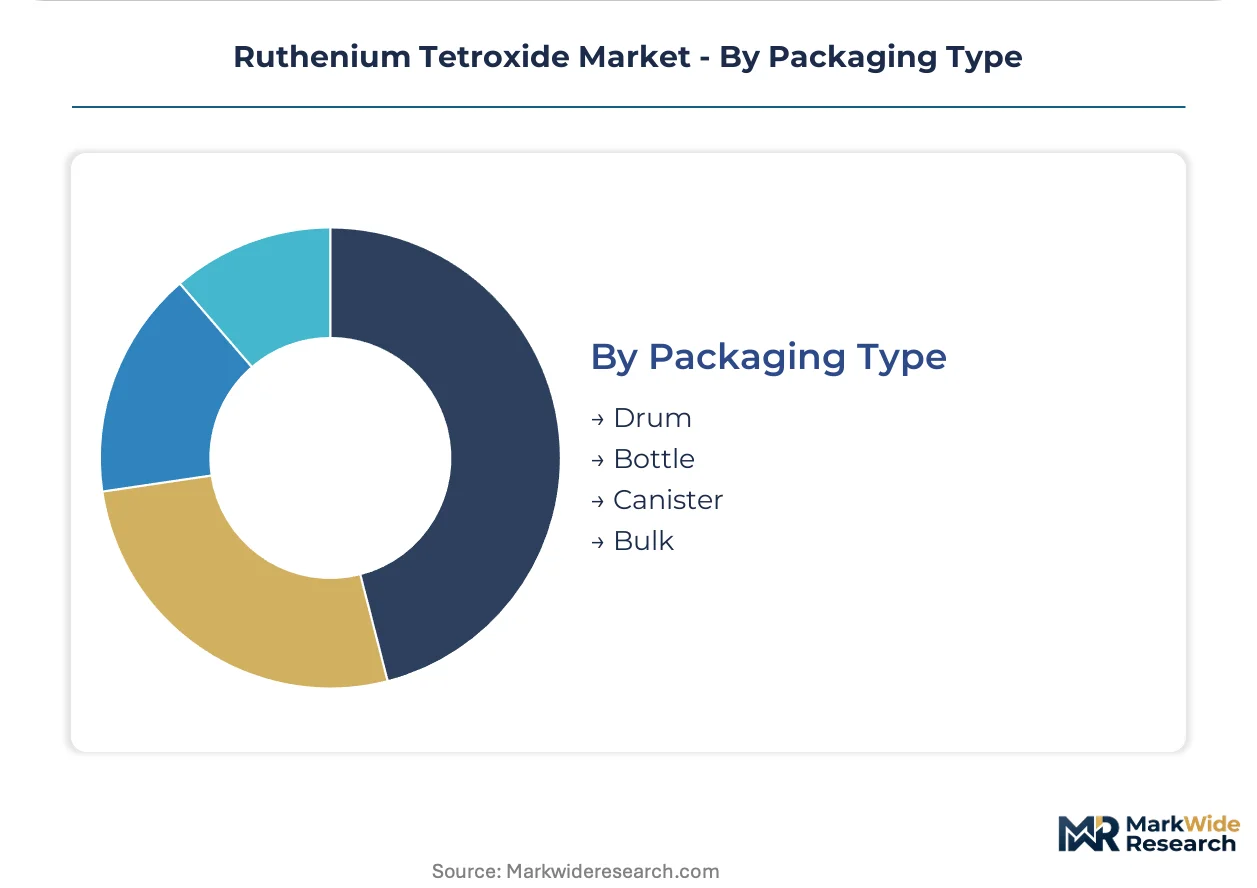
Packaging Type:
Supply concentration in pyrophoric precursor handling shapes packaging specification divergence between bulk industrial users and precision electronics customers.
- Bottle:Amber glass containers with inert atmosphere seals for analytical and research-grade volumes. American Elements and specialized distributors dominate this channel with lot-traceability protocols.
- Canister:Stainless steel pressure vessels for semiconductor fab delivery systems. Samsung Foundry and Intel qualification requirements mandate specific surface finish and cleaning certification.
- Drum:Standard industrial packaging for technical and industrial grade chemical synthesis applications.
- Bulk:Tanker and tote configurations for large-scale electroplating bath formulation and catalyst manufacturing.
Drum shipments dominate total volume. Canister packaging is gaining share fastest on semiconductor demand pull.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances in ruthenium tetroxide concentrate supply risk in Russian Arctic mining complexes while demand clusters in East Asian semiconductor fabrication. The United States maintains a structural deficit in primary ruthenium feedstock, relying on refined imports for electronic-grade precursor manufacturing.
United States
Domestic semiconductor fabs in Arizona and Oregon drive electronic-grade precursor consumption. EPA hazardous air pollutant standards and OSHA permissible exposure limits of 0.1 mg/m³ constrain synthesis scale-up and necessitate costly containment infrastructure. Intel's expanding operations in Hillsboro anchor Pacific Northwest demand concentration.
South Korea
Samsung Foundry and SK Hynix operations in Pyeongtaek and Yongin clusters anchor front-end-of-line precursor demand. MFDS chemical control regulations tighten storage and transport compliance for cross-border specialty chemical trade. Long-term offtake contracts now span 24-36 month horizons with fixed purity escalators.
China
Dual carbon goals and MEE hazardous chemical management rules filter out lower-tier suppliers, redirecting procurement toward certified high-purity producers. Yangtze River Delta electronics manufacturing clusters concentrate demand for EUV-grade material. Domestic refining capacity expansion lags behind semiconductor fabrication investment.
Japan
Materials characterization laboratories and national research institutions sustain steady analytical-grade volume. METI industrial policy supports domestic precursor supply chain resilience for advanced node manufacturing. Tokyo-Yokohama chemical distribution hubs maintain specialized packaging and lot-traceability protocols.
Germany
REACH registration requirements and ECHA dossier updates govern import volumes and downstream user obligations for ruthenium compound handlers. Industrial electroplating facilities in North Rhine-Westphalia maintain mature, volume-stable consumption patterns. German chemical distributors consolidate supplier panels to reduce compliance audit burden.
Ruthenium Tetroxide Market Competitive Environment
Listed leaders compete with private specialists across feedstock security and purification technology dimensions. The supplier base fragments between integrated precious metal refiners with captive mining access and specialized chemical formulators serving niche purity tiers. Three archetypes dominate: Arctic-anchored primary producers, Anglo-American integrated refiners, and research-grade packaging specialists. Competitive moves concentrate on long-term offtake contracting and geographic diversification of formulation capacity.
Among integrated precious metal refiners, Johnson Matthey and PJSC MMC Norilsk Nickel occupy positions at opposite ends of the supply chain. Johnson Matthey exemplifies the Anglo-American refiner archetype with electronic-grade output capabilities. PJSC MMC Norilsk Nickel anchors primary feedstock supply through Arctic mining and smelting operations. American Elements represents the specialized packaging tier, serving research-intensive buyers with lot-traceability protocols.
| Leading Market Players |
|---|
| Johnson Matthey |
| American Elements |
| ESPI Metals |
| PJSC MMC Norilsk Nickel |
| Aspira Scientific |
| FURUYA METAL Co., Ltd |
| Reade International Corp. |
| Metakem GmbH |
| J&K Scientific Ltd |
| Others |
Value Chain & Pricing Dynamics
REACH authorization requirements for Substances of Very High Concern simultaneously gate supplier qualification and enable price differentiation between certified and non-certified material tiers. Electronic-grade producers command premiums through documented compliance with ECHA dossier updates, while uncertified technical grades compete on unit cost in commoditized electroplating channels.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing as the dominant structure, with Samsung Foundry and SK Hynix locking 24-36 month horizons with fixed purity escalators. Price differentiation hinges on certification grade—99.999% EUV-qualified material versus 99.9% analytical grade—and volume scale commitments. Cost compression in technical-grade tiers is intensifying because sponge ruthenium price volatility from 2022-2024 compressed formulator margins. Research institutions exhibit highest price sensitivity due to grant-funded procurement cycles, whereas semiconductor fabs prioritize supply security over unit economics.
Supply Chain Analysis
Just-in-time delivery preferences among South Korean memory manufacturers clash with strategic stockpile tendencies at integrated precious metal refiners managing Arctic feedstock exposure. Primary ruthenium concentrate originates from Russia, South Africa, and Zimbabwe, with downstream electronic-grade synthesis concentrated in the United States, Germany, and Japan. Formulation rests on sponge ruthenium feedstock, high-purity oxidation reagents, and cleanroom-qualified packaging materials. Single-source vulnerability around Russian Arctic smelting complexes—anchoring 40% of global primary supply—exposes downstream processors to geopolitical transit friction. Distribution runs through direct refiner relationships for electronic-grade volumes and specialized chemical distributors for analytical grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ruthenium tetroxide market is navigating a cyclical recovery driven by semiconductor capital expenditure rebounds following node advancement pauses. Extreme ultraviolet lithography scaling at sub-7nm geometries provides the cyclical justification for demand normalization.
For Market Incumbents: Fortify feedstock security through captive supply arrangements or long-term offtake contracts with Arctic-anchored primary producers, insulating against geopolitical transit disruptions. Deepen certification investment in ECHA REACH dossier maintenance and MFDS-aligned documentation to defend electronic-grade positioning against emerging Asian formulators. Priority levers include backward integration into sponge ruthenium refining and capacity addition in Indian PLI scheme jurisdictions.
For New Entrants and Emerging Players: Direct-to-laboratory distribution channels represent a service-layer gap where incumbents under-serve research-intensive buyers with inflexible minimum order quantities and distributor markups. Target analytical-grade segments in German and Japanese materials characterization laboratories through specialized packaging and lot-traceability protocols. The most penetrable geography is India, where PLI scheme incentives for electronic materials are drawing packaging investment away from traditional East Asian hubs.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electronic-grade purification infrastructure as zone-refining patent disputes complicate new entrant licensing. Long-term viability favors integrated precious metal refiners with captive mining access over standalone formulators exposed to feedstock volatility. Acquisition target archetype: mid-cap specialists with qualified canister packaging capabilities and existing Samsung Foundry or Intel supplier status. The signal to watch is qualification timeline compression below 12 months for advanced node material.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | SK Hynix and Samsung Electronics contracts spanning 24-36 months reduce sponge metal price exposure. |
| Backward Integration | Johnson Matthey's precious metal refining network secures feedstock continuity for electronic-grade output. |
| Capacity Expansion | Indian PLI scheme incentives draw packaging and formulation investment toward specialty chemical manufacturing. |
| Green Manufacturing Transition | China's dual carbon goals filter procurement toward certified high-purity producers with documented emissions profiles. |
| Joint Venture | ALD tool convergence with ruthenium tetroxide precursor chemistry enables conformal seed layers in 3D NAND stacking. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with semiconductor procurement directors, precious metal refinery operations managers, specialty chemical distributors, and ECHA regulatory affairs specialists; and secondary validation through customs/trade data, SEC 10-K filings from listed refiners, ECHA dossier updates, and MFDS chemical control regulation filings. Bottom-up triangulation across product-grade volume estimates and top-down cross-checks against semiconductor capital expenditure disclosures ensured convergence.
Across the projection horizon, the analytical framework modeled segmentation dimensions including purity grade tier, end-use application, packaging format, and regional production hub. CAGRs were derived through trend extrapolation of sponge ruthenium price cycles, node advancement timelines, and regulatory compliance cost trajectories. Forecast inputs incorporated EUV lithography adoption curves and atomic layer deposition tool deployment patterns.
Forecasts assume regulatory continuity in REACH authorization requirements and MFDS hazardous chemical management frameworks; material policy shifts would require re-modeling. Specific risk factors include per- and polyfluoroalkyl substance restriction expansions redirecting demand unexpectedly, and Arctic supply route disruptions. Revision becomes warranted when semiconductor node advancement timelines cross below 3 nanometers at scale.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Photographic Chemicals Market
Chemicals
Lauryl Dimethyl Amine Oxide Market
Chemicals
Germany Methanol Market
Chemicals
Isoamyl Acetate Market
Chemicals
Aluminum Phosphide Market
Chemicals
South America Surface Treatment Chemicals Market
Chemicals
Sulfur Chemicals Market
Chemicals
CHPTAC Market
Chemicals
Dimethyl Phosphate Market
Chemicals
Ethanolamine Market
Chemicals
Europe Calcium Peroxide Market
Chemicals
Hypophosphorous Acid Market
Chemicals
Southeast Asia Construction Chemicals Market
Chemicals
Indonesia Nitric Acid Market
Chemicals
Asia-Pacific Methanol Market
Chemicals
Heptaldehyde Market