
 United Arab Emirates Plastic Caps and Closures Market | 2026-2036
United Arab Emirates Plastic Caps and Closures Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Plastic Caps and Closures Market Insights
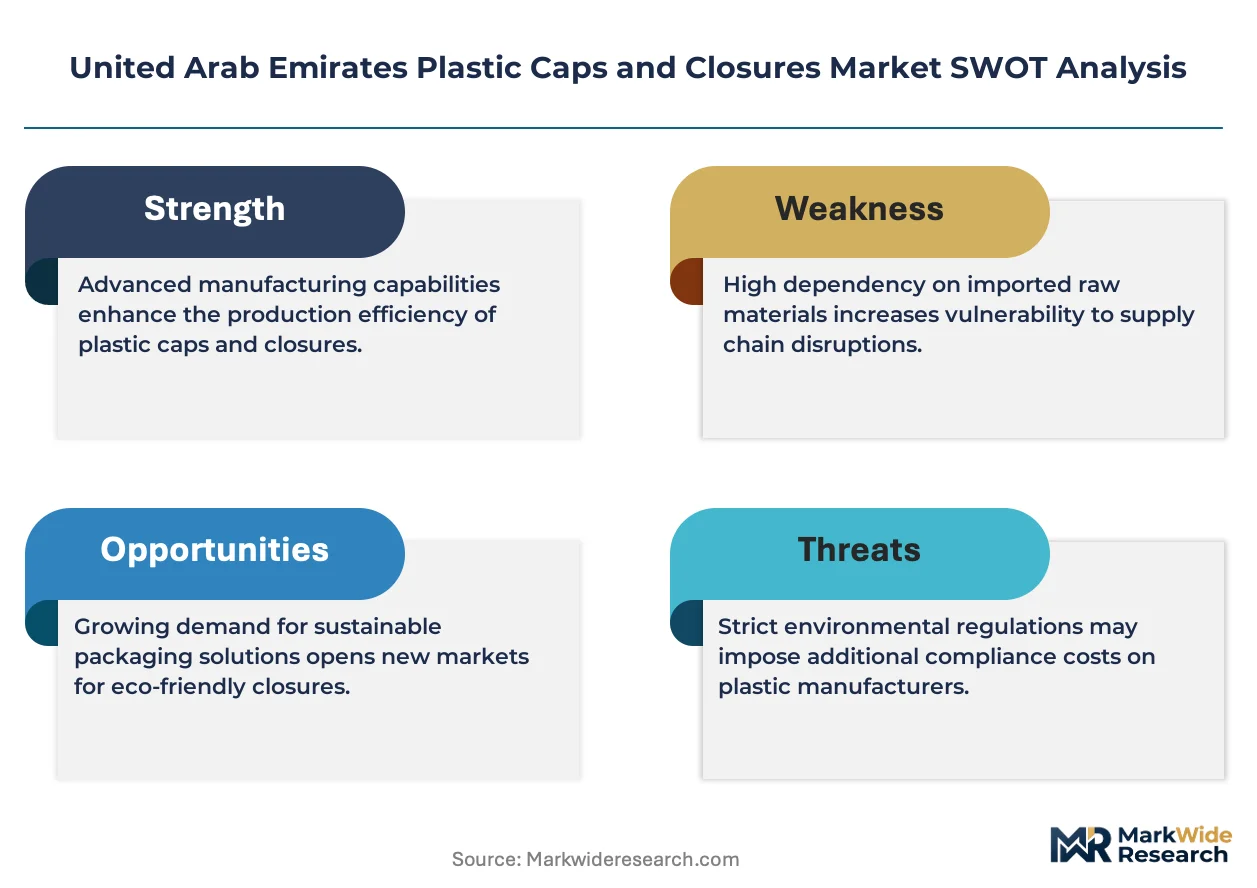
ISO 15378 certification for pharmaceutical packaging materials is reorganizing competitive access across the United Arab Emirates plastic caps and closures landscape. Bericap Middle East FZE leverages its regional manufacturing footprint to serve beverage bottlers with standardized closure lines. ALPLA Plastic Middle East Industries LLC anchors supply through backward integration into resin conversion and mold fabrication. Emirates Plastic Industries Factory competes on rapid tooling turnaround for custom cap geometries.
Plastic caps and closures are threaded or snap-fit dispensing devices, typically injection-molded from polyolefin resins with tamper-evident bands and sealing liners, designed to preserve contents, enable controlled dispensing, and confirm package integrity across liquid and semi-solid products. Polypropylene dominates material selection for hot-fill and carbonated applications due to thermal stability and hinge-flex performance. Screw caps occupy the largest volume share across beverage and pharmaceutical formats, while push-pull closures represent the fastest-growing closure type in sports drink and on-the-go personal care segments where single-handed dispensing commands premium placement.
MOHAP pharmaceutical packaging rules, ESMA product conformity schemes, and Dubai Municipality food-contact material standards collectively shape material selection, migration testing protocols, and market entry requirements for domestic and imported closure systems. The UAE's mandatory halal certification pathways for food-contact materials add a compliance layer distinct from European or North American frameworks. Stakeholders must monitor evolving extended producer responsibility consultations and recyclate-content mandates that will reshape resin sourcing strategies and tooling investments.
Market Dynamics
MOHAP pharmaceutical packaging regulations and Dubai Municipality food-contact standards are compressing material approval timelines and forcing resin qualification investments across UAE closure manufacturing. These compliance pressures intersect with rising beverage bottling capacity in Jebel Ali and Kizad industrial zones to reshape competitive positioning.
Growth Catalysts
- Hot-fill beverage expansion:Polypropylene screw cap demand accelerates as UAE-based dairy and juice processors expand aseptic filling lines for export markets. Thermal stability requirements favor domestic PP compounders.
- ESMA product conformity enforcement:Mandatory pre-shipment testing for imported closures is redirecting procurement toward UAE-certified molders with in-house migration labs.
- Halal certification pathways:Food-contact material halal standards create procurement preference for UAE-based suppliers with Sharia-compliant supply chain documentation.
Market Restraints
- Polypropylene resin import dependence:Over 80% of feedstock arrives through Jebel Ali port, exposing molders to freight rate volatility and Red Sea route disruptions.
- ISO 15378 certification scarcity:Limited UAE testing facilities extend pharmaceutical closure approval timelines to 14-18 months, freezing new entrant access.
- Aluminum closure substitution:Premium water and wine segments are migrating to metal ROPP closures for perceived sustainability and oxygen barrier performance.
Strategic Opportunities
- Abu Dhabi polymer cluster development:Borouge's Ruwais expansion enables localized PP and HDPE supply, reducing resin landed cost for Kizad-based molders.
- Extended producer responsibility pre-positioning:Early investment in post-consumer recyclate processing aligns with anticipated 2026-2027 UAE packaging waste regulations.
- Sports nutrition push-pull formats:Functional beverage startups in Dubai Science Park seek custom hinge-flex closures for protein shake bottles.
Industry Challenges
- Multi-cavity mold design expertise gap:UAE technical institutes produce insufficient injection molding engineers for 32-64 cavity high-speed tooling deployment.
- Tamper-evident band integration complexity:Pharmaceutical clients demand break-force consistency within 2N variance, requiring statistical process control investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Plastic Caps and Closures Market |
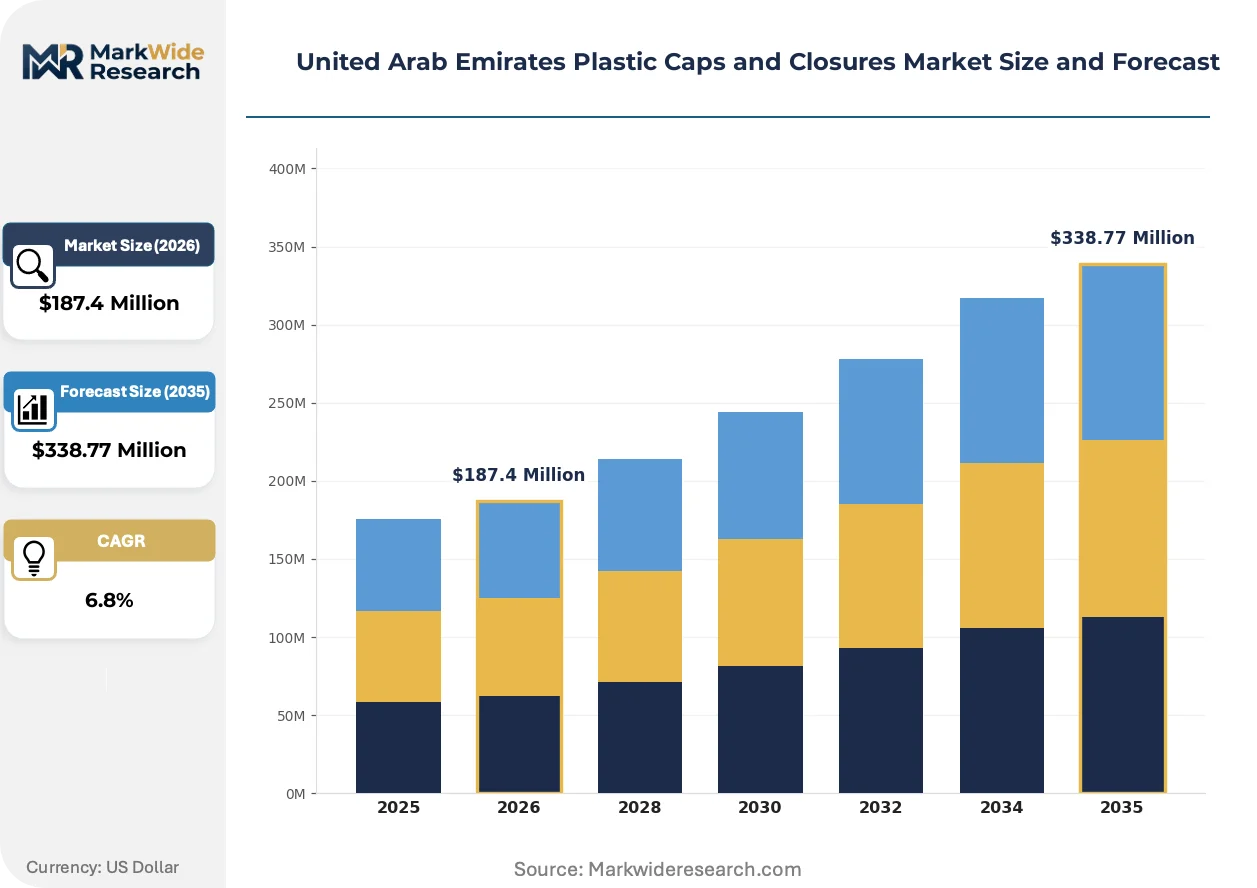
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Caps, Closures, Lids, Seals Material: Polyethylene, Polypropylene, PVC, PET End User: Food & Beverage, Personal Care, Pharmaceuticals, Household Closure Type: Screw Caps, Snap-On Caps, Push-Pull Caps, Biodynamic Caps |
| Companies Covered | Amcor PLC, Aptar Group, Bericap Middle East FZE, ALPLA Plastic Middle East Industries LLC, Emirates Plastic Industries Factory, Modern Plastic Industry, ENPI Group, Polycos Plastic Industries, Alamir Plastic Industries, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Plastic Caps and Closures Market Trends and Innovations
Digital thread technologies and bio-based material pilots are converging with tightening Gulf regulatory frameworks to redefine how UAE closure manufacturers qualify products and secure long-term supply contracts with multinational bottlers.
Biobased polypropylene derived from camelina oil feedstock is supplanting conventional fossil-based resin in pilot pharmaceutical closure lines. Dubai-based contract manufacturers are trialing these materials for European export orders where brand owners face Scope 3 pressure. The structural consequence is a bifurcation in UAE resin sourcing strategies between premium certified bio-streams and cost-optimized conventional grades.
MOHAP's 2024 updated pharmaceutical packaging guidelines now mandate extractables testing for all elastomeric liner materials used in child-resistant closures. This regulatory tightening is forcing UAE molders to abandon generic TPE suppliers and qualify dedicated pharmaceutical-grade compounders. The compliance burden falls heaviest on mid-cap generic producers lacking in-house analytical chemistry capabilities.
Beverage bottlers in Dubai Industrial City are consolidating closure procurement through direct mold-lease arrangements rather than spot purchasing. This contractual shift transfers cavity maintenance and inventory risk to molder balance sheets while locking in volume commitments. The transformation is most visible among regional water brands seeking supply security amid resin price volatility.
United Arab Emirates Plastic Caps and Closures Market Segmentation
Closure specifications diverge sharply across UAE end-use channels. Pharmaceutical mandates from MOHAP, beverage hot-fill requirements in Jebel Ali, and halal certification pathways each demand distinct material grades and dimensional tolerances that reshape supplier qualification priorities.
Product Type:
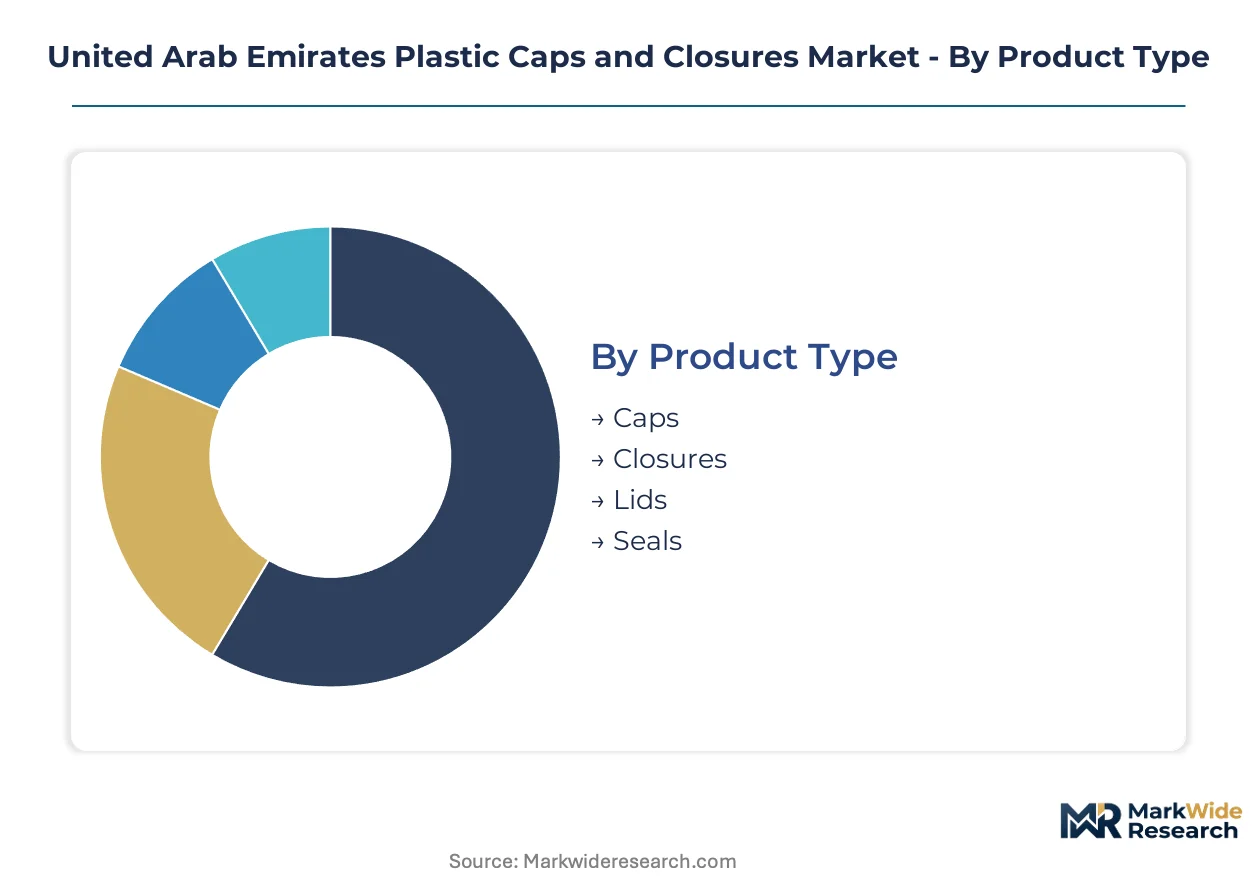
Channel flow concentrates caps and closures through beverage bottlers in Dubai Industrial City, while pharmaceutical lids route through MOHAP-certified compounders in Abu Dhabi's Kizad corridor. Seals for food-contact applications face dual ESMA and Dubai Municipality compliance checkpoints.
- Caps:Threaded polyolefin dispensers with tamper-evident bands dominate beverage bottling lines. Dubai-based water and dairy processors drive volume through standardized 28mm and 38mm neck finishes for export-bound PET bottles.
- Closures:Child-resistant and senior-friendly formats carry the steepest pharmaceutical compliance burden. MOHAP's 2024 extractables testing mandate forces molders to abandon generic TPE liners and qualify dedicated pharmaceutical-grade compounders.
- Lids:Snap-fit designs for dairy cups and ready-meal trays serve UAE food processors expanding aseptic filling capacity.
- Seals:Induction-sealed foil laminates protect pharmaceutical and personal care contents from moisture ingress. Migration testing protocols under ESMA conformity schemes extend approval timelines for imported seal systems.
Caps dominate installed base. Closures are where expansion concentrates.
Material:
Cost tiers separate commodity resin grades from certified pharmaceutical streams. Borouge's Ruwais expansion is compressing landed polypropylene costs for Kizad-based molders while bio-based pilot lines command premium positioning for European export orders.
- Polyethylene:HDPE resin supplies screw caps for household and personal care segments where chemical resistance and moderate heat tolerance suffice. UAE molders source primarily through Jebel Ali port, exposing operations to Red Sea freight volatility.
- Polypropylene:Homopolymer and random copolymer grades serve hot-fill beverage and hinge-flex push-pull applications. Thermal stability above 85°C positions PP as the default for aseptic dairy and juice processing lines.
- PVC:Rigid formulations persist in specific pharmaceutical blister pack lidding despite environmental pressure. Migration control requirements under Dubai Municipality standards constrain supplier pools.
- PET:Crystallized grades form threaded closures for carbonated soft drinks and edible oil bottles. Compatibility with bottle resin streamlines recycling sortation under anticipated UAE extended producer responsibility frameworks.
Polypropylene anchors volume share. Polyethylene is where cost optimization concentrates.
End User:
Application requirements fragment procurement specifications. Pharmaceutical clients demand ISO 15378 certification and 14-18 month qualification timelines, while beverage bottlers prioritize mold-lease arrangements that transfer inventory risk to suppliers.
- Food & Beverage:Hot-fill dairy, aseptic juice, and bottled water segments consume the majority of UAE closure output. Halal certification pathways for food-contact materials create procurement preference for suppliers with Sharia-compliant supply chain documentation.
- Personal Care:Flip-top and disc-top formats for shampoo and lotion bottles emphasize ergonomic dispensing. Dubai Science Park functional beverage startups are pulling hinge-flex closure expertise into adjacent nutrition categories.
- Pharmaceuticals:Child-resistant and tamper-evident designs face MOHAP's tightened extractables testing for elastomeric liners. Limited UAE analytical chemistry capacity extends new entrant approval cycles.
- Household:Trigger sprayers and screw caps for cleaning chemicals prioritize chemical resistance over precision tolerance. Standardized geometries enable multi-customer mold utilization.
Food & Beverage dominates installed base. Pharmaceuticals are where margin expansion concentrates.
Closure Type:
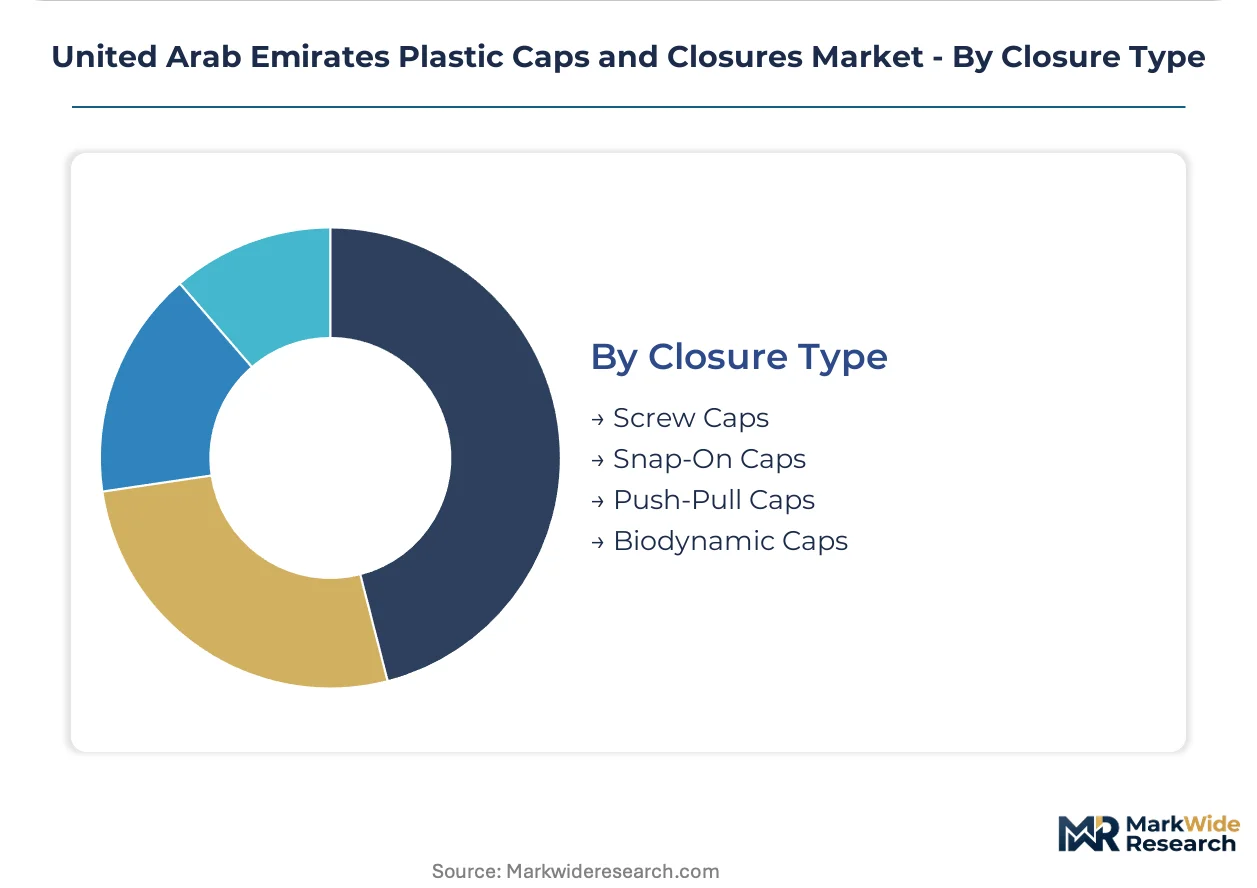
Volume scale separates high-cavity screw cap production from specialized biodynamic formats. Multi-cavity mold design expertise gaps at UAE technical institutes constrain deployment of 32-64 cavity tooling for mass-market beverage applications.
- Screw Caps:Continuous thread designs with induction seal liners serve carbonated and still beverages across 28mm through 48mm neck finishes. Jebel Ali bottlers consolidate procurement through direct mold-lease contracts.
- Snap-On Caps:Press-fit closures for dairy cups and single-serve condiments enable high-speed filling line throughput. Tooling turnaround speed differentiates domestic molders against imported alternatives.
- Push-Pull Caps:Hinge-flex sports closures command premium placement in protein shakes and isotonic drinks. Single-handed dispensing functionality drives placement in Dubai's on-the-go consumption channels.
- Biodynamic Caps:Pressure-activated and motion-responsive formats remain niche in UAE pharmaceutical pilot lines. Development partnerships with European brand owners test local manufacturing feasibility.
Screw Caps dominate installed base. Push-Pull Caps are where application innovation concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jebel Ali Port anchors the United Arab Emirates plastic caps and closures trade, processing over 80% of polypropylene resin imports that feed molders across Dubai and Abu Dhabi industrial corridors.
Dubai
Hot-fill beverage bottlers in Dubai Industrial City drive polypropylene screw cap demand for dairy and juice export lines. Dubai Municipality food-contact material standards enforce migration testing protocols that favor domestic molders with in-house laboratories. Jebel Ali Free Zone concentrates Bericap Middle East FZE and ALPLA Plastic Middle East Industries LLC operations serving regional water brands.
Abu Dhabi
Kizad industrial corridor houses pharmaceutical-focused molders navigating MOHAP's 2024 extractables testing mandates for elastomeric liners. Borouge's Ruwais polypropylene expansion reduces resin landed costs for Abu Dhabi-based compounders. Emirates Plastic Industries Factory competes on rapid tooling turnaround for custom cap geometries serving local pharmaceutical clients.
Sharjah
Mid-cap molders in Sharjah's industrial zones supply standardized closures for household and personal care segments where chemical resistance trumps precision tolerance. ESMA product conformity enforcement redirects procurement toward UAE-certified suppliers with pre-shipment testing capabilities. Sharjah's technical institutes struggle to produce sufficient injection molding engineers for high-cavity tooling deployment.
Northern Emirates
Ras Al Khaimah and Fujairah host emerging packaging converters targeting cost-optimized polyethylene screw caps for regional cleaning chemical brands. Limited ISO 15378 certification access extends pharmaceutical closure approval timelines, freezing premium segment participation. These emirates compete on labor arbitrage rather than technical specialization.
United Arab Emirates Plastic Caps and Closures Market Competitive Landscape
Listed multinationals compete with private specialists across certification tiers and resin integration depth. The vendor base clusters around three strategic archetypes: global packaging conglomerates with regional manufacturing footprints, Middle East-focused molders with backward integration into resin conversion, and domestic fabricators competing on tooling speed and custom geometry capabilities. Dominant competitive moves include direct mold-lease arrangements that transfer inventory risk to suppliers, and early investment in post-consumer recyclate processing to align with anticipated UAE extended producer responsibility frameworks.
Among UAE-based specialists, Bericap Middle East FZE and ALPLA Plastic Middle East Industries LLC occupy positions within the integrated manufacturing tier, while Emirates Plastic Industries Factory exemplifies the rapid-turnover custom tooling archetype. These three entities anchor the competitive landscape through distinct capability positioning rather than overlapping segment coverage.
| Leading Market Players |
|---|
| Amcor PLC |
| Aptar Group |
| Bericap Middle East FZE |
| ALPLA Plastic Middle East Industries LLC |
| Emirates Plastic Industries Factory |
| Modern Plastic Industry |
| ENPI Group |
| Polycos Plastic Industries |
| Alamir Plastic Industries |
| Others |
Pricing and Supply Chain Analysis
Aluminum closure substitution in premium water and wine segments simultaneously compresses polypropylene screw cap pricing power and redirects procurement geography toward European metal closure suppliers. This input displacement forces UAE molders to defend volume share through aggressive mold-lease terms while absorbing resin freight volatility through Jebel Ali.
Pricing Analysis
Volume-discount tiering separates pharmaceutical-grade closures with ISO 15378 certification from commodity beverage caps. Price differentiation hinges on migration testing documentation and hot-fill thermal stability ratings. Pricing pressure stems from Borouge's Ruwais expansion compressing domestic PP landed costs. Beverage bottlers exhibit highest price sensitivity due to consolidated procurement through direct mold-lease contracts, while pharmaceutical clients prioritize compliance over unit cost.
Supply Chain Analysis
Inventory lead times for pharmaceutical-grade elastomeric liners now stretch 14-18 months due to limited UAE analytical chemistry capacity. Geographic supply concentrates in Saudi Arabia, India, and Germany for certified TPE compounds. Raw material dependencies span polypropylene resin, pharmaceutical-grade elastomers, and induction seal laminates. Single-source vulnerability sits with Jebel Ali port handling over 80% of PP feedstock imports. Distribution runs through mold-lease arrangements transferring cavity maintenance risk to suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE plastic caps and closures market approaches a platform-economics inflection as mold-lease contracts and direct procurement consolidation create winner-take-most dynamics. Interoperability between closure specifications and bottling line automation standards is locking in supplier ecosystems.
For Market Incumbents: Shield market position by deepening backward integration into Borouge's Ruwais polymer stream and accelerating ISO 15378 certification coverage. Aluminum closure substitution in premium segments demands defensive capacity in hinge-flex push-pull formats. Channel control through mold-lease inventory absorption remains the critical retention lever against mid-cap competitors. For New Entrants and Emerging Players: Lead with sports nutrition push-pull closures targeting Dubai Science Park functional beverage startups. White-space concentrates in custom hinge-flex geometries for protein shake bottles where incumbent tooling turnaround lags. Go-to-market should emphasize rapid prototyping partnerships with contract manufacturers lacking in-house closure design. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European packaging conglomerates seeking Gulf manufacturing footprint expansion. Long-term viability favors molders with captive resin conversion and pharmaceutical certification infrastructure. Watch for MOHAP extractables testing mandate enforcement as the signal indicating compliance-capability scarcity premium expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Conversion | Borouge's Ruwais expansion enables captive PP supply, compressing landed costs for Kizad-based molders. |
| ISO 15378 Certification Investment | Pharmaceutical closure approval timelines freeze generic competitors lacking dedicated analytical chemistry capabilities. |
| Post-Consumer Recyclate Processing Buildout | Early positioning aligns with anticipated UAE extended producer responsibility packaging waste regulations. |
| Mold-Lease Contract Expansion | Direct arrangements with Jebel Ali bottlers transfer inventory risk while locking volume commitments. |
| Custom Push-Pull Closure Development | Hinge-flex expertise serves Dubai Science Park functional beverage startups seeking differentiated dispensing formats. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with beverage procurement directors, pharmaceutical packaging managers, mold fabrication engineers, and resin compounder technical leads. Secondary validation drew from ESMA conformity scheme filings, Dubai Municipality food-contact material registrations, MOHAP pharmaceutical packaging guidelines, and customs import data through Jebel Ali port. Bottom-up volume triangulation against top-down value estimates anchored segmentation outputs.
Across the analysis window, forecasts model closure type, material grade, end-use channel, and emirate-level manufacturing concentration. CAGRs derive from elasticity-adjusted demand projections incorporating hot-fill beverage capacity expansion and pharmaceutical regulatory tightening. Industry-specific inputs include Borouge resin supply schedules, MOHAP certification pipeline data, and mold-lease contract coverage ratios.
Underlying assumptions cover sustained Red Sea shipping route stability and MOHAP enforcement continuity, with deviation risk concentrated in resin import disruption and extended producer responsibility implementation timing. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Tube Closures Market
Caps and Closures
Non-Aerosol Overcaps Market
Caps and Closures
Japan Plastic Caps and Closures Market
Caps and Closures
Foam Cap Liners Market
Caps and Closures
Side Pour Caps Market
Caps and Closures
Metal Caps and Closures Market
Caps and Closures
Ring Pull Caps Market
Caps and Closures
Beverage Caps and Closures Market
Caps and Closures
PVC-Free Cap Liners Market
Caps and Closures
Latin America Metal Caps and Closures Market
Caps and Closures
Lug Caps Market
Caps and Closures
Bag Closure Clips Market
Caps and Closures
Spouted Dispensing Closures Market
Caps and Closures
Heat Shrink Bands Market
Caps and Closures
Flip Top Caps and Closures Market
Caps and Closures
Case Closures and Sealers Market