
 Tear Tab Cap Market | 2026-2036
Tear Tab Cap Market Size, Share, and Industry Trends Forecast 2026-2036
Tear Tab Cap Market Analytics
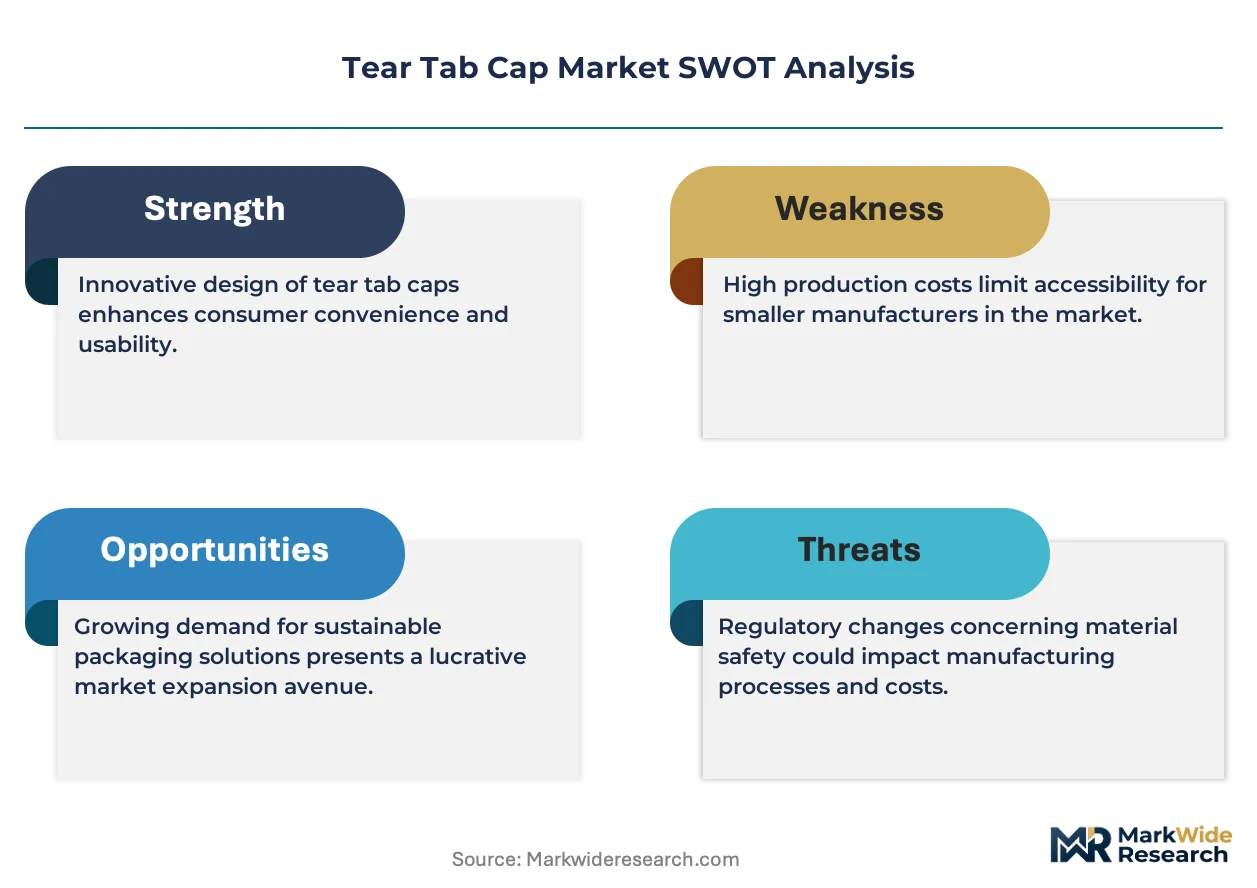
Aftermarket closure customization revenue is tilting toward value-added tamper-evident configurations as brand owners seek differentiation at the point of opening. Amcor leverages its global film and closure platform to sustain multi-material tear tab programs across beverage and pharmaceutical lines. Crown Holdings anchors North American metal closure capacity with in-house coating and forming operations that compete on speed-to-tooling for seasonal beverage launches.
A tear tab cap is a single-use closure featuring a pre-scored membrane or ring that fractures along a defined path when pulled, typically manufactured through injection molding of polypropylene or polyethylene with integrated living-hinge geometry, and functions to provide visible evidence of first opening while enabling tool-free access. Plastic variants dominate unit volume across beverage bottling given cost parity and color-match flexibility, yet composite laminates with aluminum foil layers are gaining fastest in pharmaceutical applications where oxygen barrier performance commands premium positioning. Metal tear tabs retain structural share in carbonated can formats where internal pressure demands rigid retention geometry.
FDA 21 CFR tamper-evident packaging requirements and EU MDR device labeling standards shape material selection and validation protocols for pharmaceutical-bound tear tab caps, while ISO 8317 child-resistant specifications constrain hinge-force tolerances across consumer product segments. EMA's evolving serialization mandates further tighten traceability expectations for European-distributed pharmaceutical closures. Stakeholders must monitor regulatory divergence between US and European tamper-evident testing protocols when configuring regional supply footprints.
Market Dynamics
Pharmaceutical serialization mandates and oxygen-barrier material specifications are compressing supplier qualification timelines while expanding validation documentation burdens across contract packaging networks.
Growth Catalysts
- FDA 21 CFR tamper-evident mandates:Pharmaceutical container standards now require visible fracture evidence at first opening, forcing format conversions across oral solid dose packaging lines in the United States.
- Polypropylene living-hinge advances:Injection molding precision improvements enable thinner pre-scored membranes without sacrificing pull-force consistency, reducing unit material consumption in high-volume beverage applications.
- German pharmaceutical cluster concentration:Contract packaging hubs around Frankfurt and Stuttgart generate concentrated demand for composite laminate tear tabs with aluminum foil oxygen barriers.
Market Restraints
- Polypropylene resin price volatility:Feedstock cost swings tied to propylene supply disruptions compress margin stability for injection-molded cap producers serving price-sensitive beverage segments.
- Tooling lead time elongation:Precision mold fabrication for living-hinge geometry now stretches 14-18 weeks at qualified suppliers, constraining speed-to-market for seasonal product launches.
- Aluminum foil supply concentration:Pharmaceutical-grade foil sourcing depends on a limited qualified supplier base in Western Europe, creating single-source vulnerability for barrier-layer tear tab production.
Strategic Opportunities
- EMA serialization mandate expansion:European traceability requirements for pharmaceutical closures create certified supplier scarcity that rewards early compliance investment with multi-year contract lock-in.
- Biologic drug container migration:Temperature-sensitive biologics packaging is converting from screw-cap to tear-tab formats for single-use sterility assurance, opening high-margin specialty segments.
- Direct-to-pharmacy distribution:E-commerce channel development for OTC medications enables private-label tear tab specification bypassing traditional wholesaler gatekeepers.
Industry Challenges
- Validation documentation burdens:FDA process validation and EU MDR technical file requirements demand 18-24 month qualification cycles for new tear tab geometries, freezing design iteration speed.
- Multi-material recycling complexity:Composite tear tabs combining polypropylene, aluminum, and adhesive layers fall outside existing mechanical recycling streams, exposing brand owners to extended producer responsibility penalties under EU packaging regulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tear Tab Cap Market |
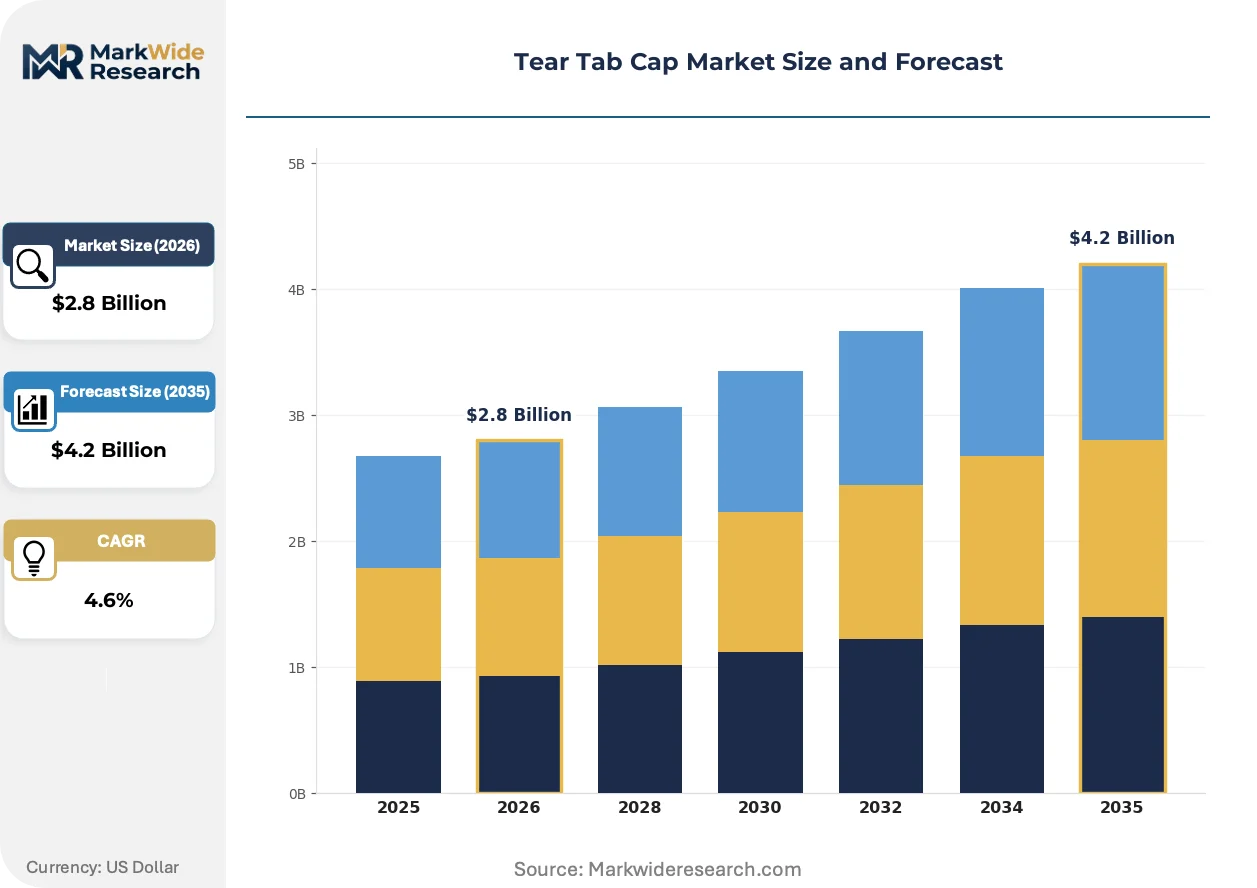
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Metal, Paper, Composite Application: Beverage Packaging, Pharmaceutical Containers, Food Sealing, Consumer Products End User: Manufacturers, Distributors, Retailers, Consumers Packaging Type: Bottles, Cans, Cartons, Jars |
| Companies Covered | Amcor, Sonoco Products Company, Crown Holdings, Silgan Holdings, Constantia Flexibles, Berry Global, StockCap, Daemar Inc., CL Smith Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tear Tab Cap Market Evolving Landscape
Material science convergence and regulatory documentation automation are compressing traditional supplier qualification barriers while opening specification windows for novel barrier technologies.
Mono-material polypropylene tear tabs with plasma-enhanced barrier coatings are collapsing the cost-performance tradeoff that previously forced pharmaceutical applications toward aluminum-laminate constructions. German and Swiss packaging converters are piloting these formulations for oral solid dose containers, eliminating delamination risk while maintaining oxygen transmission rates below 0.5 cc per day. The structural consequence is a compression of the premium pricing tier for barrier-grade tear tabs as coated mono-material alternatives achieve functional parity at 15-20 percent lower unit cost.
REACH SVHC disclosure requirements and EU MDR technical documentation standards are forcing material composition transparency down to the additive level across European pharmaceutical supply chains. Suppliers must now provide full substance declarations for colorants, slip agents, and nucleating compounds used in living-hinge formulations. The segment most affected is contract packaging organizations serving pan-European drug distribution, which are consolidating supplier bases to reduce documentation fragmentation and audit burden.
Brand owners are unbundling closure supply from primary container contracts, creating direct procurement relationships with specialized tear tab manufacturers that bypass traditional one-stop packaging integrators. This disintermediation is most visible among mid-sized pharmaceutical companies in the United States seeking differentiated opening experiences for patient adherence programs. The shift enables faster design iteration and color-matching flexibility but requires buyers to internalize specification validation expertise previously handled by integrator quality teams.
Tear Tab Cap Market Segmentation
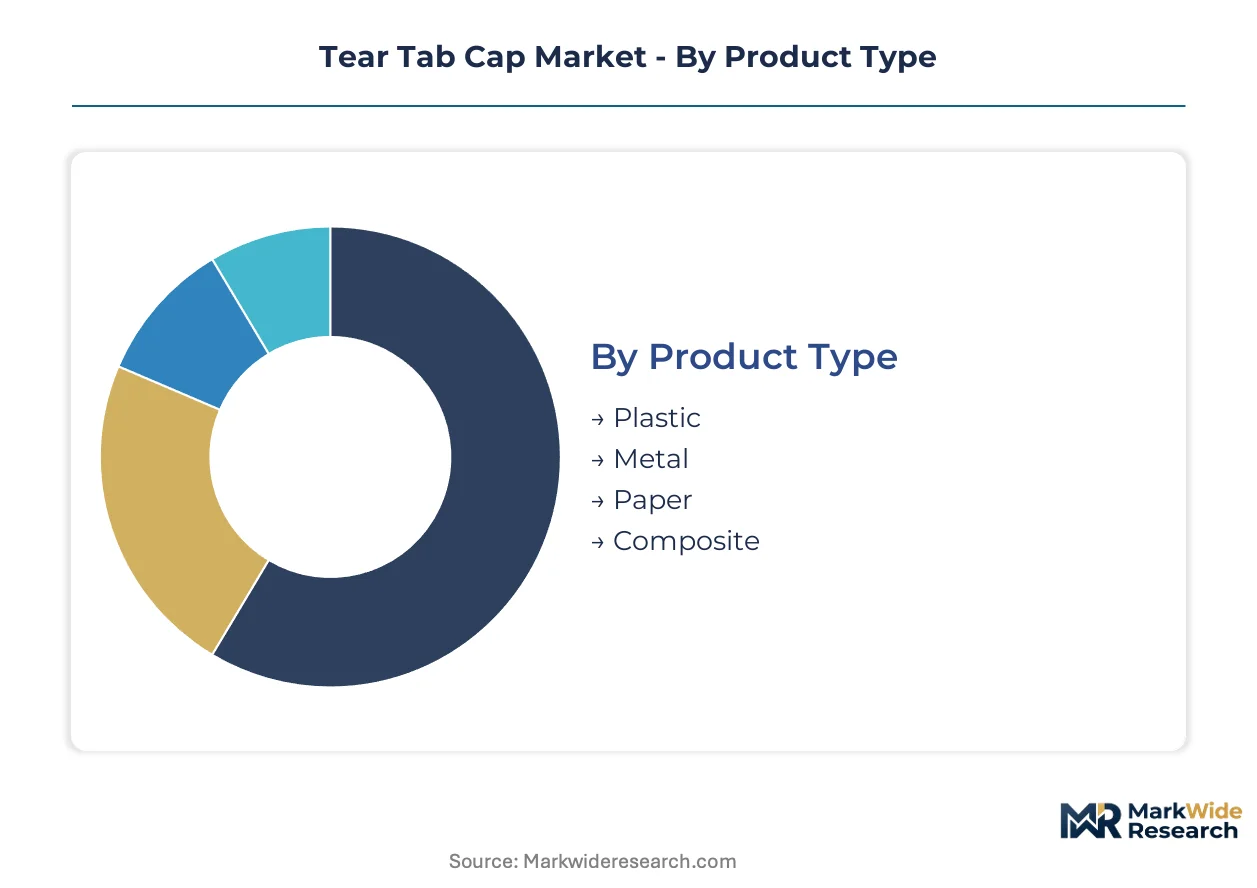
Tear tab cap segmentation reveals how material science and regulatory requirements fragment supply strategies across end-use verticals. Pharmaceutical oxygen-barrier specifications and beverage cost-minimization pressures pull converters toward divergent technical competencies.
Product Type:
Mature injection-molding platforms dominate high-volume segments while emerging barrier technologies reshape premium pharmaceutical applications.
- Plastic:Polypropylene living-hinge constructions account for the majority of beverage bottling deployments. FDA 21 CFR compliance for pharmaceutical oral solid doses now demands pull-force consistency validation that compresses qualified supplier pools in the United States.
- Metal:Aluminum tear tabs retain structural rigidity for carbonated can formats where internal pressure exceeds 90 psi. German beverage canning lines favor tinplate variants with epoxy-phenolic internal coatings for acidic product compatibility.
- Paper:Fiber-based tear tabs serve ambient-stable dry goods with limited moisture exposure requirements.
- Composite:Polypropylene-aluminum laminates command pharmaceutical oxygen-barrier specifications below 0.5 cc per day.
Plastic retains volume leadership; composite holds the steepest expansion curve.
Application:
Cost tier stratification separates commodity beverage specifications from validated pharmaceutical documentation burdens.
- Beverage Packaging:Carbonated soft drink and bottled water bottlers prioritize polypropylene unit economics and color-match flexibility across seasonal SKUs. Crown Holdings and Amcor compete on 14-week tooling velocity for promotional launches.
- Pharmaceutical Containers:Oral solid dose and biologic single-use formats demand EMA serialization-ready traceability and EU MDR technical file compliance. Frankfurt-area contract packaging hubs concentrate demand for barrier-grade composite constructions.
- Food Sealing:Shelf-stable dairy and ready-to-eat segments specify peel-force ranges compatible with automated filling lines.
- Consumer Products:Household chemical and personal care applications balance child-resistance torque requirements with senior-friendly opening geometry.
Beverage packaging retains volume leadership; pharmaceutical containers hold the steepest expansion curve.
End User:
Customer type determines specification authority and validation burden distribution across the value chain.
- Manufacturers:Brand-owning pharmaceutical companies and beverage bottlers direct material selection and living-hinge geometry design. Mid-sized US drug companies increasingly bypass packaging integrators for direct tear tab procurement.
- Distributors:Wholesale pharmaceutical and beverage supply intermediaries influence private-label specification standardization.
- Retailers:Pharmacy chains and mass merchandisers specify opening experience requirements for private-label OTC medications.
- Consumers:End-user adherence feedback loops inform patient-centric pull-force optimization for geriatric populations.
Manufacturers retain volume leadership; retailers hold the steepest expansion curve.
Packaging Type:
Volume concentration varies by container geometry and closure integration complexity.
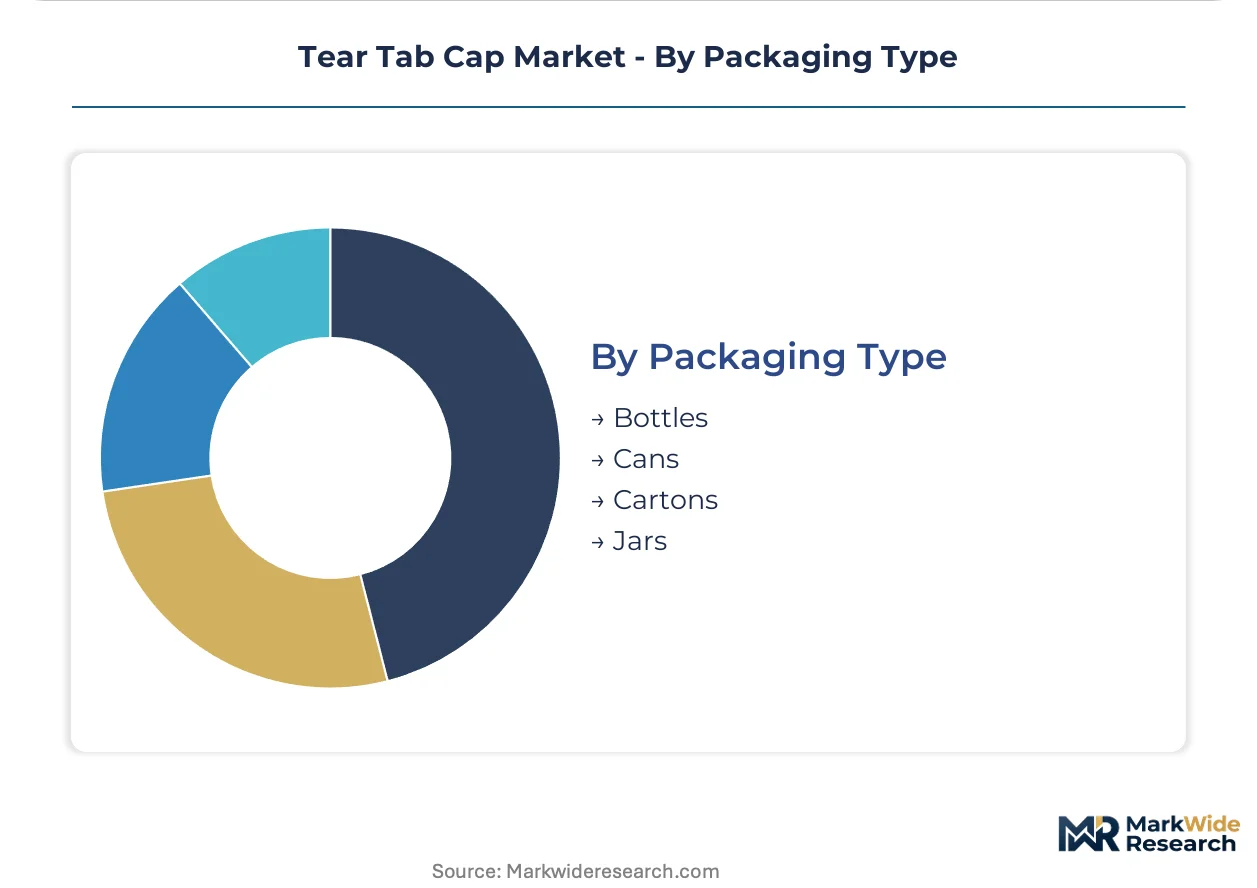
- Bottles:Polypropylene tear tabs integrate with HDPE and PET neck finishes across beverage and pharmaceutical liquid formats. German converters pilot plasma-coated mono-material alternatives to aluminum-laminate constructions.
- Cans:Metal tear tabs for aluminum beverage cans require precision scoring to balance opening force with structural integrity under pressure.
- Cartons:Aseptic liquid packaging employs composite tear strips with aluminum foil barriers for extended shelf stability.
- Jars:Wide-mouth food and pharmaceutical containers specify hinge geometries accommodating vacuum seal retention.
Bottles retain volume leadership; cartons hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity in beverage bottling concentrates in Asian export manufacturing zones, while pharmaceutical-grade specifications command premium tolerance in German and Swiss contract packaging clusters.
United States
FDA 21 CFR tamper-evident mandates drive format conversions across oral solid dose packaging lines in New Jersey and Pennsylvania pharmaceutical corridors. The FDA's evolving guidance on visible fracture evidence tightens validation protocols for domestic suppliers. Chicago-area contract packaging hubs concentrate demand for high-speed beverage bottling configurations.
Germany
EMA serialization mandates and EU MDR technical documentation standards compress supplier qualification timelines for Frankfurt and Stuttgart pharmaceutical clusters. REACH SVHC disclosure requirements force material composition transparency down to additive levels. Bavarian packaging converters pilot plasma-enhanced mono-material barrier coatings for oral solid dose containers.
China
NMPA pharmaceutical container standards and dual carbon goals reshape material selection for Yangtze River Delta injection-molding operations. GB standards compliance for food-contact applications constrains living-hinge geometry design. Zhejiang and Jiangsu provinces dominate polypropylene living-hinge production for export beverage markets.
India
CDSCO pharmaceutical packaging regulations and PLI scheme incentives attract contract manufacturing investment to Maharashtra and Gujarat pharmaceutical zones. BIS standards for food-grade closures constrain domestic supplier pools. Hyderabad and Bangalore clusters specialize in barrier-grade tear tabs for temperature-sensitive biologics.
Switzerland
Swissmedic device labeling standards and EU MDR alignment create certified supplier scarcity for Basel-area pharmaceutical packaging operations. Precision molding expertise concentrates in Zurich and Geneva industrial corridors. Swiss converters lead pilot programs for plasma-coated mono-material alternatives to aluminum-laminate constructions.
Tear Tab Cap Market Competitive Landscape
Capability concentration sits with specialized pharmaceutical-grade suppliers; scale advantage sits with diversified packaging conglomerates. The market structures around three tiers: integrated multi-material platforms serving global beverage brands, precision injection-molders qualified for FDA and EMA pharmaceutical protocols, and regional fabricators capturing private-label and seasonal launch volumes. Dominant competitive moves include strategic partnerships with contract packaging organizations and geographic expansion into German pharmaceutical clusters.
Within the integrated packaging tier, Amcor and Crown Holdings occupy positions spanning beverage and pharmaceutical lines. Amcor leverages its global film and closure platform for multi-material tear tab programs. Crown Holdings anchors North American metal closure capacity with in-house coating and forming operations. Berry Global represents the diversified plastics conglomerate archetype with injection-molding scale across consumer and healthcare segments.
| Leading Market Players |
|---|
| Amcor |
| Sonoco Products Company |
| Crown Holdings |
| Silgan Holdings |
| Constantia Flexibles |
| Berry Global |
| StockCap |
| Daemar Inc. |
| CL Smith Company |
| Others |
Value Network & Pricing Analysis
Western European aluminum foil supply concentration for pharmaceutical-grade barrier layers anchors margin capture at composite laminate converters serving EMA-mandated serialization requirements. Contract packaging organizations in German pharmaceutical clusters absorb premium positioning for validated tear tab geometries while beverage bottlers in Asian export zones compress polypropylene living-hinge pricing through volume aggregation.
Pricing Analysis
Aftermarket closure customization revenue drives lifetime value through value-added tamper-evident configurations and multi-year validation service contracts. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated pharmaceutical grades from beverage commodity specifications and private-label retail tiers. Cost compression in beverage polypropylene segments is intensifying because propylene feedstock volatility transfers directly to injection-molded cap producers. Brand-owning pharmaceutical companies exhibit lowest price sensitivity due to regulatory compliance non-negotiability, while seasonal beverage launch managers prioritize 14-week tooling velocity over unit cost optimization.
Supply Chain Analysis
Tariff exposure between United States and Chinese injection-molding equipment suppliers dominates capital expenditure planning for North American beverage bottlers. Manufacturing gravity centers on Zhejiang and Jiangsu provinces for polypropylene living-hinge production, Western Europe for pharmaceutical-grade aluminum foil lamination, and Bavaria for plasma-coated mono-material pilot programs. Raw material dependencies encompass propylene resin streams, pharmaceutical-grade foil stocks, and nucleating compound additives for hinge-force consistency. Single-source vulnerability concentrates in qualified aluminum foil suppliers for oxygen-barrier specifications. Distribution runs through contract packaging organization networks for pharmaceutical applications and direct bottler relationships for beverage volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Child-resistant screw-cap formats and snap-fit induction seals represent active substitution threats that incumbent tear tab manufacturers must neutralize through opening-experience differentiation and regulatory compliance bundling.
For Market Incumbents: Insulate pharmaceutical market share by deepening EMA serialization-ready supplier certification ahead of mandate expansion timelines, while accelerating plasma-coated mono-material R&D to collapse the aluminum-laminate premium tier. Crown Holdings and Amcor should anchor backward integration into propylene resin hedging instruments to stabilize margin exposure in beverage segments. Child-resistant alternative formats threaten volume retention in household chemical applications.
For New Entrants and Emerging Players: Direct-to-pharmacy e-commerce channels for private-label OTC medications represent the most penetrable entry point, bypassing traditional wholesaler gatekeepers and enabling specification influence at pharmacy chain buyers. Mid-sized US pharmaceutical companies seeking patient adherence program differentiation offer second-tier access. Go-to-market execution should emphasize 90-day validation documentation acceleration versus 18-month incumbent qualification cycles.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision injection-molders holding FDA 21 CFR validation portfolios but lacking EMA serialization compliance infrastructure. Five-to-ten year viability hinges on biologic drug container conversion momentum from screw-cap to tear-tab formats for single-use sterility assurance. Monitor CDSCO regulatory alignment with FDA tamper-evident standards as inflection indicator for Indian contract manufacturing zone expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| EMA Serialization Compliance Investment | Creates multi-year contract lock-in with Frankfurt-area pharmaceutical packaging hubs. |
| Plasma-Enhanced Barrier Coating Scale-Up | Eliminates aluminum foil dependency while maintaining oxygen transmission below 0.5 cc per day. |
| Direct-to-Pharmacy Distribution Partnership | Bypasses wholesaler gatekeepers for private-label OTC tear tab specification influence. |
| Biologic Drug Container Format Conversion | Captures high-margin specialty segments through single-use sterility assurance positioning. |
| Propylene Resin Supply Hedging Program | Stabilizes margin exposure against feedstock volatility in price-sensitive beverage tiers. |
Research Methodology
A standing panel of contract packaging organization procurement directors, pharmaceutical regulatory affairs leads, beverage bottler supply chain managers, and injection-molding tooling engineers provided ongoing calibration across primary fieldwork. Secondary validation drew from FDA 21 CFR guidance documents, EMA serialization mandate drafts, REACH SVHC substance databases, and SEC filings of publicly traded packaging conglomerates. Bottom-up tear tab volume modeling triangulated against top-down pharmaceutical container market sizing.
Scenario-bracketing framed low-base-high projections across the analysis window without single-point forecast dependency. Segmentation dimensions encompassed material type, application vertical, end-user authority, and packaging format geometry. CAGRs were derived from regression-adjusted trend extrapolation incorporating polypropylene resin price indices, pharmaceutical serialization mandate implementation schedules, and beverage bottling capital expenditure cycles.
Practitioners should monitor propylene supply disruption patterns, EMA technical documentation requirement finalization, and biologic drug approval trajectories for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Hinged Dispensing Caps Market
Caps and Closures
Poland Plastic Caps and Closures Market
Caps and Closures
Tear-Tab Lids Market
Caps and Closures
Middle East and Africa Plastic Caps and Closures Market
Caps and Closures
India Plastic Caps and Closures Market
Caps and Closures
US Caps and Closure Market
Caps and Closures
Bar Top Corks Market
Caps and Closures
Flip Top Caps and Closures Market
Caps and Closures
Bi-Injected Snap Hinge Closure Market
Caps and Closures
North America Plastic Caps and Closures Market
Caps and Closures
Smooth Hinge Caps and Closure Market
Caps and Closures
Saudi Arabia Plastic Caps and Closures Market
Caps and Closures
Aluminium ROPP Closures Market
Caps and Closures
Egypt Plastic Caps and Closures Market
Caps and Closures
Push Pull Closure Market
Caps and Closures
Dauber Caps Market