
 Russia Automotive Hydraulic Actuators Market | 2026-2036
Russia Automotive Hydraulic Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Automotive Hydraulic Actuators Market Analytics
Heavy-duty specification-grade actuator assemblies is bifurcating the competitive landscape between premium system integrators and volume-oriented component suppliers. Robert Bosch GmbH leverages its established fuel injection heritage to anchor hydraulic actuator development for powertrain applications. Continental AG competes through specialized electro-hydraulic modules that serve steering and suspension platforms across Russian OEM contracts. Denso Corporation sustains its position by concentrating on thermal management-integrated actuator systems that address cold-climate operational requirements.
Russia automotive hydraulic actuators are electromechanical devices that convert fluid pressure into controlled mechanical motion, typically operating at system pressures between 100-350 bar using mineral oil-based hydraulic fluids with integrated position feedback sensors. These components enable precise force transmission in vehicle subsystems where electric motors cannot deliver sufficient torque density or fail-safe redundancy. Actuator assembly and control valve segments command the dominant margin pools due to their complexity and direct interface with vehicle safety systems. Electro-hydraulic technology leads adoption trajectories as OEMs pursue hybrid actuation architectures that combine hydraulic power density with electronic control precision.
Russia's GOST R national standardization system and the Federal Agency on Technical Regulating and Metrology (Rosstandart) enforce mandatory certification for automotive hydraulic components entering domestic assembly lines. The Ministry of Industry and Trade's automotive industry development programs link subsidy eligibility to localized actuator production thresholds, reshaping supplier qualification criteria. Stakeholders must monitor how evolving EAEU technical regulations harmonize with Russia-specific durability testing protocols for hydraulic systems operating in extreme temperature ranges.
Market Dynamics
Electro-hydraulic hybrid architectures are compressing traditional hydraulic actuator margins while forcing tier-one suppliers to recalibrate their engineering roadmaps around electronic control integration.
Growth Catalysts
- Import Substitution Mandates:Russia's industrial localization program ties state procurement contracts to domestic actuator assembly thresholds, redirecting OEM sourcing toward GOST R-certified local production facilities.
- Cold-Climate Performance Requirements:Mineral oil formulations rated for minus-forty-degree operation create specification barriers that favor established thermal management-integrated actuator systems in brake and steering platforms.
- Powertrain Electrification:Hybrid vehicle architectures require redundant hydraulic backup systems for steering and braking, preserving actuator demand even as pure electric actuation advances in other vehicle classes.
Market Restraints
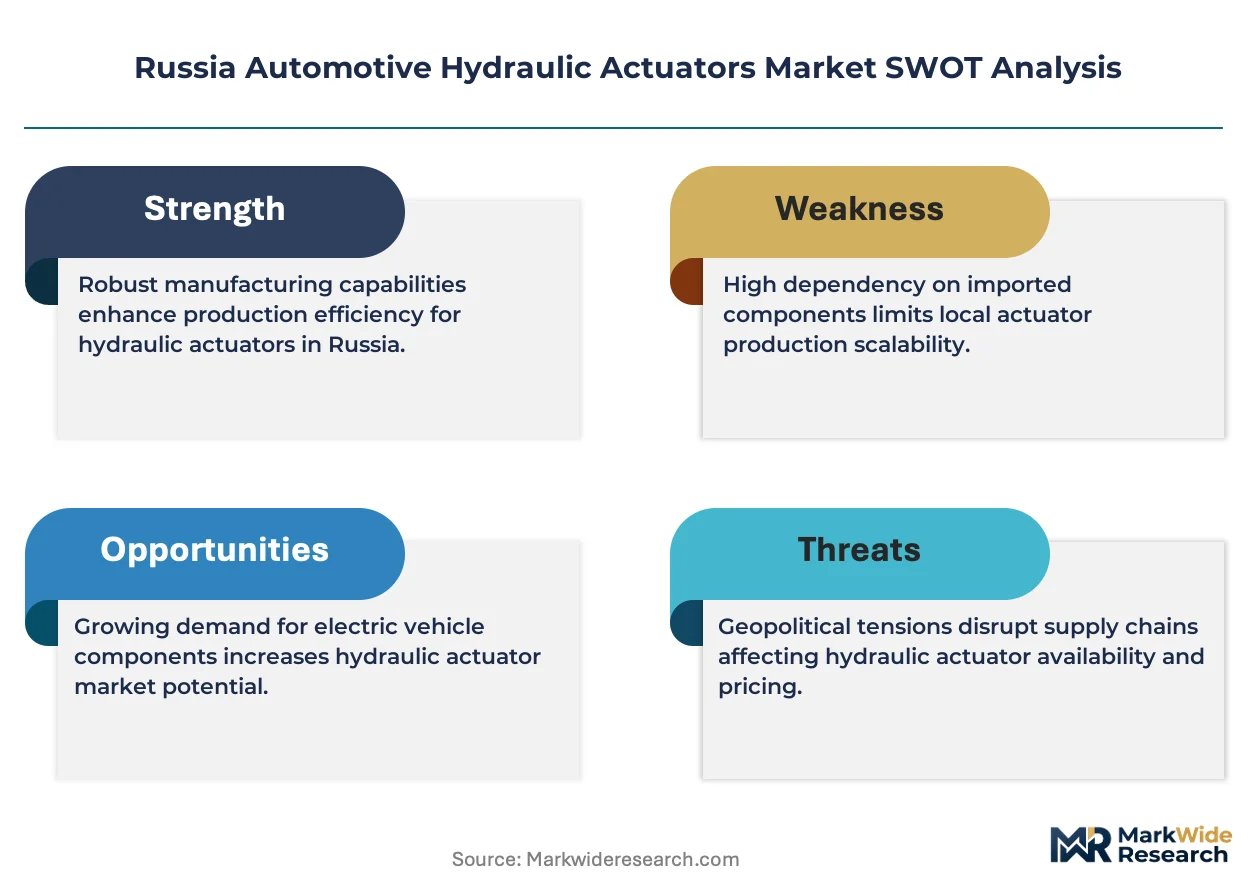
- Specialized Alloy Supply Concentration:High-pressure cylinder manufacturing depends on imported seamless steel tubing, exposing Russian actuator assemblers to sanctions-related input disruptions and extended lead times.
- Sealing Material Technical Limitations:Domestic fluoroelastomer production cannot match the temperature and chemical resistance specifications required for 350-bar brake system actuators, forcing reliance on non-domestic suppliers.
- EAEU Regulatory Friction:Harmonization delays between Eurasian Economic Union technical regulations and Russia-specific durability testing protocols create dual certification burdens that extend product qualification timelines.
Strategic Opportunities
- Volga Federal District Manufacturing Clusters:Tolyatti's vehicle assembly plants offer captive demand for locally produced steering rack actuators, with unused industrial capacity available for hydraulic component manufacturing.
- Aftermarket Channel Digitization:B2B platform procurement of replacement actuator assemblies is displacing traditional distributor networks, enabling direct manufacturer-to-fleet relationships that bypass import-dependent spare parts intermediaries.
- Remanufacturing Regulatory Tailwinds:Russia's circular economy directives for automotive components establish tax incentives for certified hydraulic actuator refurbishment, creating secondary revenue streams beyond original equipment supply.
Industry Challenges
- Precision Machining Skill Scarcity:Tight-tolerance honing operations for actuator cylinder bores require specialized technicians that Russian vocational programs have not scaled to match demand from reshoring initiatives.
- GOST R Certification Timeline Compression:Accelerated product development cycles for new vehicle platforms collide with Rosstandart's extended validation protocols for safety-critical hydraulic systems.
- Legacy Fleet Integration Complexity:Electro-hydraulic retrofit kits for aging commercial vehicle brake systems must interface with obsolete CAN bus architectures that lack standardized diagnostic protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Automotive Hydraulic Actuators Market |
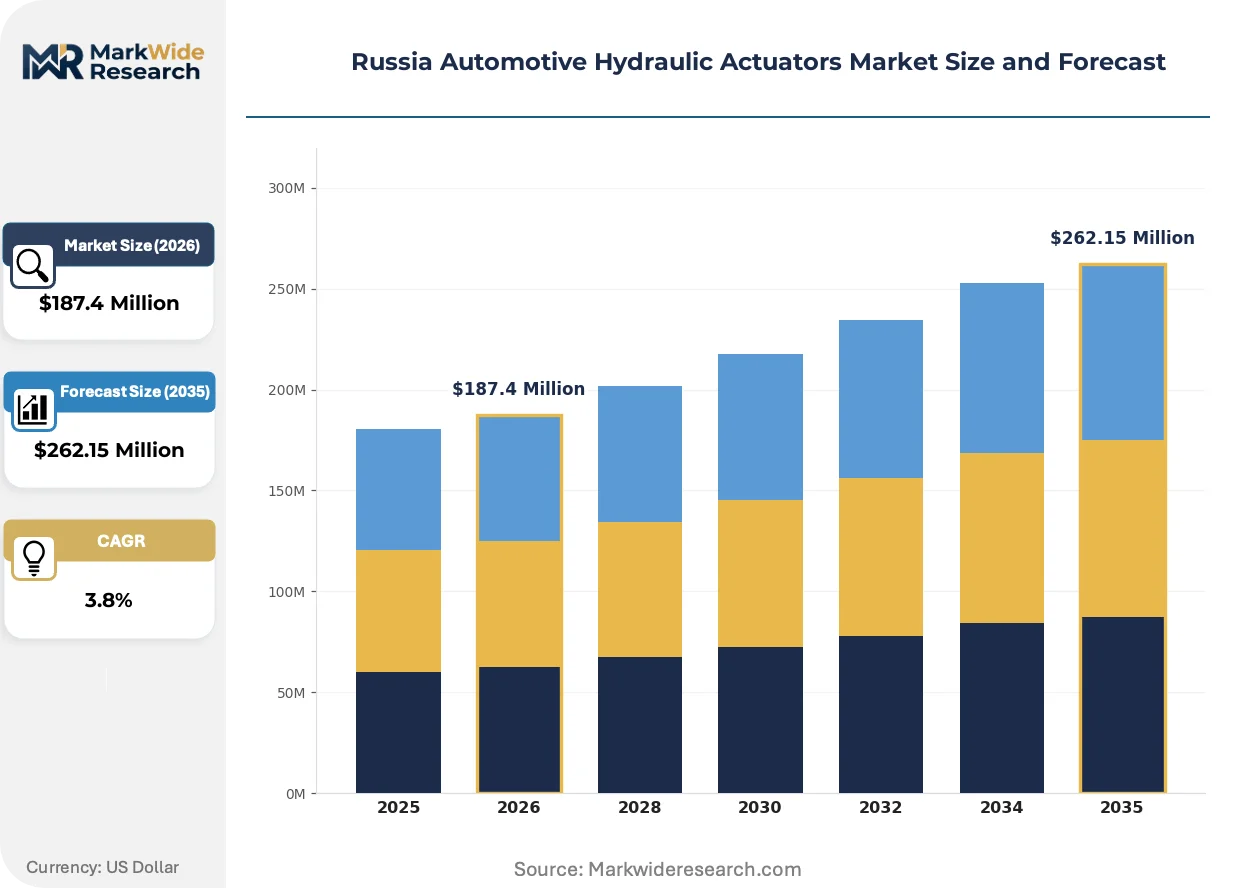
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $262.15 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Actuator Assembly, Control Valve, Pump Actuator, Servo Actuator Technology: Electro-Hydraulic, Mechanical, Pneumatic, Hydraulic End User: OEMs, Aftermarket Providers, Dealerships, Vehicle Assemblers Application: Steering Systems, Brake Systems, Suspension Systems, Powertrain |
| Companies Covered | Hitachi Ltd, Robert Bosch GmbH, Denso Corporation, Parker Hannifin, Bosch Rexroth AG, Mitsubishi Electric Corporation, Continental AG, Moog Inc, Nidec Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Automotive Hydraulic Actuators Market Evolving Landscape
Digital position feedback integration is displacing analog sensor architectures across brake and steering actuators, while material science advances in sealing compounds reshape durability expectations for extreme-climate operation.
Electro-hydraulic actuator modules that combine proportional valve control with integrated position sensing are fragmenting the historical separation between hydraulic power units and electronic control modules. Tier-one brake system suppliers are adopting these converged architectures for new platform development, compressing the addressable market for standalone hydraulic component specialists that cannot deliver closed-loop control integration. This technological convergence is fragmenting competitive boundaries between traditional hydraulics manufacturers and electromechanical system integrators.
Rosstandart's phased implementation of updated GOST R automotive safety standards is mandating redundant position verification for steering rack actuators, forcing redesigns of single-sensor architectures that dominated prior generation products. The regulation's industrial consequence is accelerated obsolescence of analog feedback systems and forced migration toward dual-channel encoder configurations. Brake actuator assemblies face the most compressed compliance timelines, with OEMs targeting platform updates to align with certification renewal cycles.
Fleet operators in the Central Federal District are consolidating hydraulic actuator procurement through integrated maintenance contracts that bundle component supply with predictive replacement scheduling, displacing transactional spare parts purchasing. This behavioral shift compresses supplier margins while extending contractual tenures that lock out competing vendors. Commercial vehicle segments exhibit the most pronounced consolidation, as logistics companies standardize actuator specifications across mixed-brand fleets to simplify inventory management.
Russia Automotive Hydraulic Actuators Market Segmentation
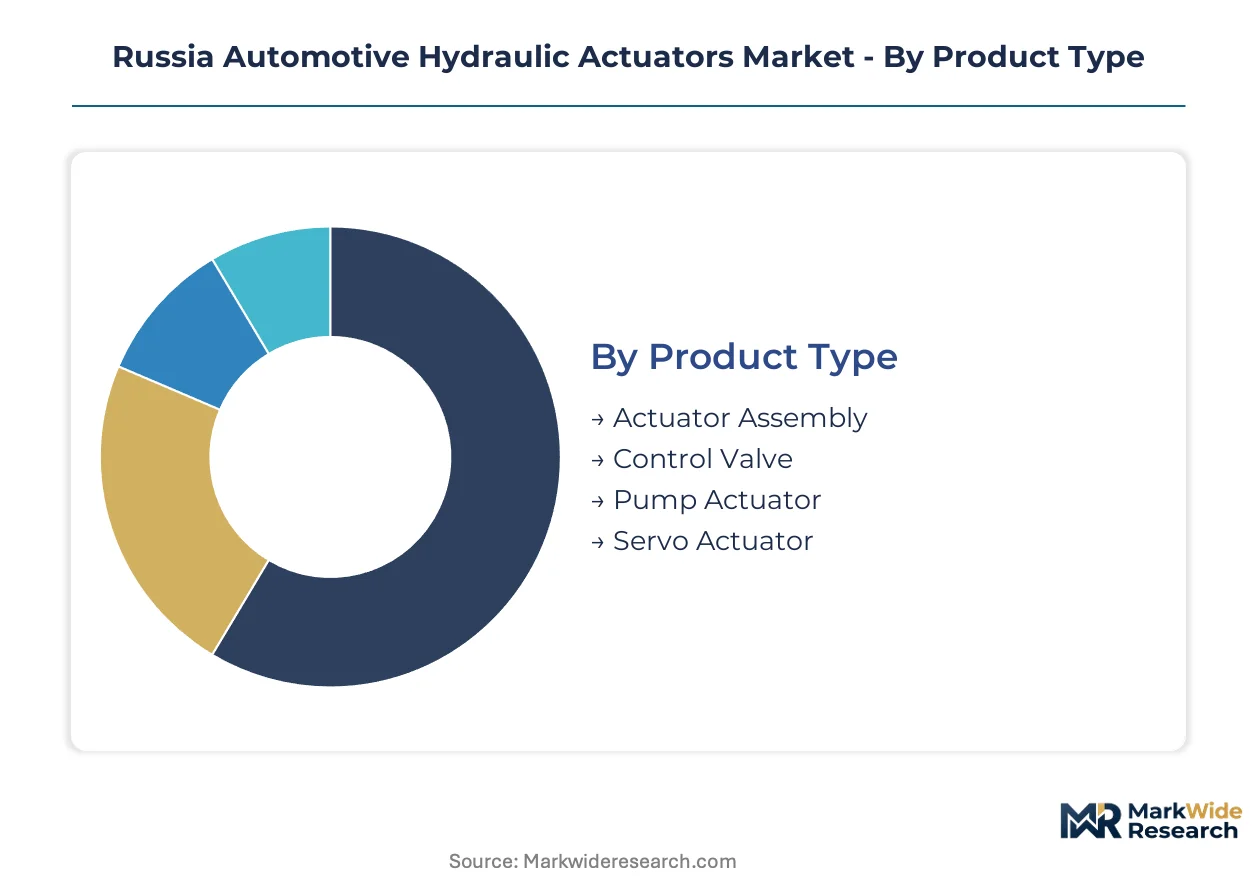
Segmentation of Russia's automotive hydraulic actuator market reveals how GOST R certification requirements and import substitution mandates reshape procurement patterns across component categories. Understanding these divisions exposes where localization incentives concentrate investment and which technical specifications create competitive moats for domestic assemblers.
Product Type:
Margin pools concentrate in precision-machined assemblies that interface directly with vehicle safety systems, where Rosstandart validation protocols extend product lifecycles and protect incumbent positions.
- Actuator Assembly:These integrated units combine cylinder bodies, pistons, and position sensors into sealed modules rated for 350-bar peak pressures. Demand clusters around Moscow's brake system manufacturing corridor, where OEMs source steering rack actuators under state-linked procurement contracts that mandate localized assembly thresholds.
- Control Valve:Proportional and directional valve architectures regulate fluid flow with millisecond response times for dynamic chassis control. Tolyatti's vehicle assembly plants generate captive demand for servo-quality valve bodies, though domestic honing capacity constraints limit output scaling for high-precision spool manufacturing.
- Pump Actuator:Power steering pump-integrated actuators convert engine-driven hydraulic pressure into rack-assist force.
- Servo Actuator:Closed-loop position control units serve automated transmission and clutch engagement systems.
The dominant share belongs to Actuator Assembly, while Control Valve is closing the gap fastest.
Technology:
Cost tier differentiation separates premium electro-hydraulic platforms from commodity mechanical alternatives, with mid-range pneumatic systems losing position in safety-critical applications.
- Electro-Hydraulic:Hybrid architectures merge proportional valve control with CAN-integrated position feedback, enabling closed-loop force modulation for adaptive steering and brake-by-wire systems. Central Federal District OEMs specify these modules for new platform development, compressing demand for standalone hydraulic components that lack electronic integration.
- Hydraulic:Conventional fluid-power systems operating at 100-200 bar serve commercial vehicle brake and steering platforms where fail-safe redundancy outweighs electrification incentives. Volga Federal District truck manufacturers maintain procurement volumes for these proven architectures, particularly in minus-forty-degree mineral oil formulations that address Russia's cold-climate operational requirements.
- Mechanical:Cable and linkage-based actuation persists in economy vehicle segments and legacy fleet retrofit applications.
- Pneumatic:Compressed-air systems retain niche use in heavy commercial vehicle suspension leveling, though hydraulic displacement accelerates in brake and steering functions.
Electro-Hydraulic commands the premium tier, while Hydraulic retains volume leadership in commercial vehicle procurement.
End User:
Customer type determines contract structure, with state-linked OEMs driving localization requirements and aftermarket channels digitizing procurement relationships.
- OEMs:Original equipment manufacturers in the Central Federal District specify GOST R-certified actuator assemblies for brake and steering platform integration, with Ministry of Industry and Trade subsidy eligibility tied to domestic production thresholds. These contracts extend across multi-year vehicle platform lifecycles, locking in supplier relationships through Rosstandart validation timelines.
- Aftermarket Providers:B2B platform procurement of replacement actuator assemblies is displacing traditional distributor networks, enabling direct manufacturer-to-fleet relationships that bypass import-dependent spare parts intermediaries. Predictive maintenance contracts now bundle component supply with scheduled replacement, compressing margins while extending contractual tenures.
- Vehicle Assemblers:Knockdown assembly operations in Tolyatti and Kaluga integrate imported actuator modules into locally finished vehicles.
- Dealerships:Authorized service networks handle warranty-period actuator replacement under manufacturer-directed parts programs.
OEMs retain the dominant procurement volume, while Aftermarket Providers are expanding most quickly through platform-based fleet contracting.
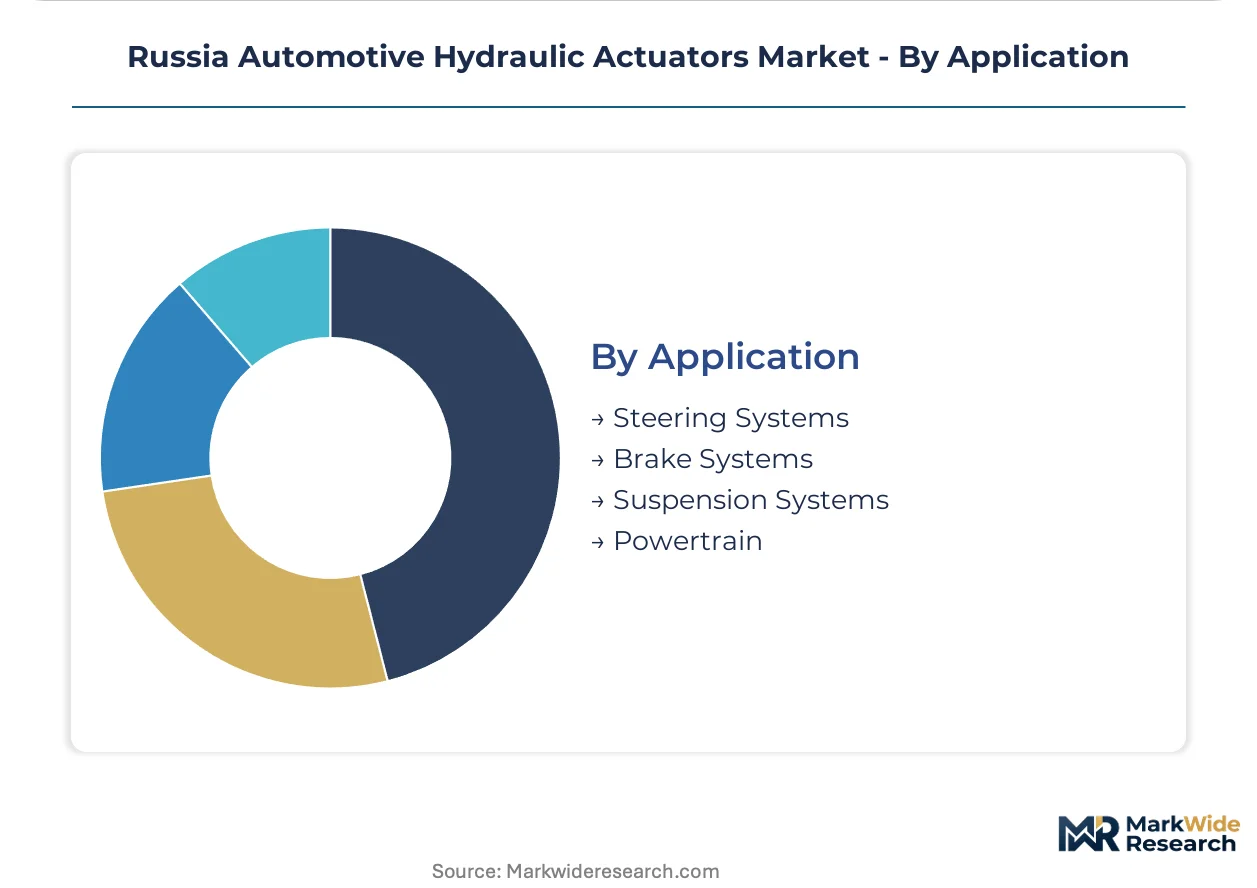
Application:
Volume distribution tracks vehicle production concentration, with steering and brake systems commanding priority placement in platform engineering budgets.
- Steering Systems:Rack-and-pinion and recirculating ball actuators deliver precise torque assist for passenger and commercial vehicle steering columns. Updated GOST R automotive safety standards mandate redundant position verification, forcing migration from single-sensor analog architectures toward dual-channel encoder configurations that accelerate obsolescence of prior-generation products.
- Brake Systems:Hydraulic brake actuators and ABS modulator valves operate at system pressures up to 350 bar with fail-safe redundancy requirements. Domestic fluoroelastomer production limitations force reliance on non-domestic sealing material suppliers, exposing assemblers to sanctions-related input disruptions despite localized cylinder manufacturing.
- Suspension Systems:Active damping actuators adjust shock absorber valving for dynamic ride control in premium vehicle segments.
- Powertrain:Clutch and transmission actuators manage torque transfer in automated manual and dual-clutch architectures.
Steering Systems hold the dominant application share, while Brake Systems face the steepest compliance-driven redesign cycle.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Japanese actuator exports flow through established trade corridors into Russian assembly plants, while domestic production clusters in the Volga and Central Federal Districts absorb redirected procurement under localization mandates.
Central Federal District
Brake system manufacturing corridors around Moscow generate concentrated demand for GOST R-certified steering rack actuators. The Ministry of Industry and Trade ties subsidy eligibility to localized assembly thresholds, reshaping supplier qualification criteria. OEM procurement contracts in this district extend across multi-year platform lifecycles.
Volga Federal District
Tolyatti's vehicle assembly plants create captive demand for servo-quality valve bodies and power steering pump-integrated actuators. Domestic honing capacity constraints limit output scaling for high-precision spool manufacturing despite available industrial capacity. Cold-climate mineral oil formulations rated for minus-forty-degree operation dominate procurement specifications.
Siberian Federal District
Commercial vehicle fleet operators in Novosibirsk and Krasnoyarsk consolidate hydraulic actuator procurement through integrated maintenance contracts. Predictive replacement scheduling now bundles component supply with contractual tenures that lock out competing vendors. Extreme temperature ranges in this region accelerate wear on sealing compounds.
Northwestern Federal District
St. Petersburg's port infrastructure handles residual imports of seamless steel tubing for high-pressure cylinder manufacturing. Sanctions-related input disruptions expose local assemblers to extended lead times for specialized alloy supply. The district's logistics nodes attempt to circumvent supply concentration risks through alternative sourcing routes.
Southern Federal District
Rostov-on-Don's agricultural machinery conversion workshops retrofit legacy hydraulic systems for commercial vehicle applications. Remanufacturing regulatory tailwinds from circular economy directives establish tax incentives for certified actuator refurbishment. Secondary revenue streams from refurbishment operations supplement original equipment supply in this region.
Russia Automotive Hydraulic Actuators Market Competitive Landscape
Listed leaders compete with private specialists across certification-grade tiers, with consolidated positions in electro-hydraulic modules fragmenting against distributed mechanical actuator suppliers. Tier-one system integrators anchor premium platform development while volume-oriented component assemblers capture state-linked procurement contracts. Three archetypes dominate: thermal management-integrated specialists, precision valve manufacturers, and powertrain heritage players. Capacity expansion into localized assembly facilities and strategic partnerships with domestic steel tubing distributors represent the dominant competitive moves reshaping supplier relationships.
Among precision motion control specialists, Hitachi Ltd and Moog Inc occupy positions within the premium electro-hydraulic tier, exemplifying archetypes that bridge electronic control integration with fluid power density. Robert Bosch GmbH anchors the powertrain heritage segment, representing established fuel injection expertise redirected toward hydraulic actuator development. Denso Corporation exemplifies thermal management-integrated system suppliers that address cold-climate operational requirements through combined actuator and climate control architectures.
| Leading Market Players |
|---|
| Hitachi Ltd |
| Robert Bosch GmbH |
| Denso Corporation |
| Parker Hannifin |
| Bosch Rexroth AG |
| Mitsubishi Electric Corporation |
| Continental AG |
| Moog Inc |
| Nidec Corporation |
| Others |
Value Network & Pricing Analysis
Domestic fluoroelastomer substitution for imported sealing compounds simultaneously redraws supply geography toward Volga Federal District polymer processors and compresses pricing premiums for GOST R-certified brake actuator assemblies. This input transition forces tier-one suppliers to recalibrate cost models around localized material qualification timelines while OEMs exploit procurement leverage over incompletely substituted component categories.
Pricing Analysis
Electro-hydraulic module pricing gaps separate current-generation CAN-integrated architectures from prior-generation analog-feedback units and developmental brake-by-wire platforms. Three-tier pricing structure across premium electro-hydraulic, standard conventional hydraulic, and economy mechanical actuator levels reflects certification grade and electronic integration depth. Cost compression in the economy tier is intensifying because aftermarket distributors consolidate procurement through predictive maintenance contracts. Fleet operators in the Central Federal District exhibit highest price sensitivity, while OEM platform engineering teams prioritize fail-safe redundancy over unit cost.
Supply Chain Analysis
Seamless steel tubing chokepoints in Northwestern Federal District port infrastructure expose Russian actuator assemblers to sanctions-extended lead times for high-pressure cylinder manufacturing. Supply draws from Germany, Japan, and residual Chinese alloy shipments for specialized metallurgical inputs. Raw material dependencies center on fluoroelastomer seals, mineral oil formulations rated for arctic operation, and precision-honed cylinder bores. Single-source vulnerability concentrates in non-domestic sealing material suppliers. Distribution runs through Tolyatti vehicle assembly plants and Moscow brake system manufacturing corridors for captive OEM offtake.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Russia's automotive hydraulic actuator market functions as a service-attach opportunity where predictive maintenance contracts and remanufacturing certification programs expand faster than standalone hardware replacement volumes. This recurring-revenue layer rewards suppliers that bundle component supply with lifecycle asset management.
For Market Incumbents: Compound defensive positioning through backward integration into seamless steel tubing distribution networks and captive fluoroelastomer compound qualification with Volga Federal District polymer processors. Electromechanical system integrators encroach on traditional hydraulic territory through electro-hydraulic convergence; counter by deepening Rosstandart certification moats around safety-critical steering rack architectures. Prioritize GOST R validation pipeline investment to compress product qualification timelines against regulatory acceleration. For New Entrants and Emerging Players: Differentiate on remanufacturing certification capabilities that access circular economy tax incentives in the Southern Federal District. Target aftermarket platform digitization for commercial vehicle fleet operators consolidating procurement through B2B channels. Penetrate via direct manufacturer-to-fleet relationships that bypass import-dependent spare parts intermediaries, exploiting the most accessible entry vector for non-incumbent suppliers. For Investors and Strategic Acquirers: The market sits at a localization-mandate acceleration phase that favors precision machining specialists with Rosstandart-validated production facilities. Long-term viability hinges on electro-hydraulic control integration capabilities rather than standalone hydraulic component manufacturing. Monitor EAEU-Russia regulatory harmonization progress as the critical inflection signal for dual certification burden relief or intensification.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Tubing Distribution | Secures specialized alloy supply channels against sanctions-related disruption risks. |
| Electro-Hydraulic Control Module Development | Aligns product roadmaps with OEM hybrid actuation architecture requirements. |
| GOST R Certification Pipeline Expansion | Compresses Rosstandart validation timelines for accelerated platform integration. |
| Remanufacturing Certification Program Launch | Accesses circular economy tax incentives in Southern Federal District operations. |
| Aftermarket Platform Direct Partnership | Bypasses import-dependent intermediaries through B2B fleet procurement channels. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and Rosstandart certification specialists; and secondary validation against vehicle production databases, GOST R regulatory filings, customs import records for seamless steel tubing, and EAEU technical regulation harmonization documents. Bottom-up actuator shipment estimates triangulated against top-down vehicle production forecasts across the analysis window.
Across the projection horizon, the analytical framework modeled volume and value outputs through segmentation dimensions spanning product type, technology generation, end-user contract structure, and application safety-criticality. CAGRs derived from regression analysis of historical production trends, localized content thresholds, and substitution elasticity parameters. Industry-specific forecast inputs incorporated Ministry of Industry and Trade subsidy eligibility criteria and cold-climate mineral oil formulation adoption curves.
Material uncertainties — sanctions regime evolution, EAEU regulatory harmonization delays, and domestic fluoroelastomer production scale-up — sit outside the modeled envelope. Forecasts reflect documented assumptions about continued import substitution policy continuity and stable vehicle production levels in Tolyatti and Moscow manufacturing clusters. Practitioners should keep alternative scenarios live as geopolitical conditions and alloy supply corridor accessibility evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Trailing Arm Bushing Market
Automotive Parts
Malaysia Passenger Vehicles Lubricants Market
Automotive Parts
Car Refrigerator Market
Automotive Parts
Europe Roll Forming Body in White Market
Automotive Parts
North America Automotive Parts Magnesium Die Casting Market
Automotive Parts
Clutch Pedal Kit Market
Automotive Parts
High Speed Rolling Bearings Market
Automotive Parts
Crank Trigger System Market
Automotive Parts
Europe Commercial Vehicles Lubricants Market
Automotive Parts
Asia-Pacific Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Thermal Systems Market
Automotive Parts
Full Synthetic Motor Oil Market
Automotive Parts
Morocco Commercial Vehicles Lubricants Market
Automotive Parts
Automotive Parts Aluminum Die Casting Market
Automotive Parts
AC Electromagnetic Brakes Market
Automotive Parts
Middle East Automotive Engine Oils Market