
 Asia-Pacific Air Separation Unit Market | 2026-2036
Asia-Pacific Air Separation Unit Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Air Separation Unit Market Outlook
China's dual carbon goals is restructuring procurement priorities for large-tonnage oxygen consumers across the Asia-Pacific region. Air Liquide SA leverages its cryogenic technology leadership to anchor long-term supply contracts with coastal petrochemical complexes. Linde PLC competes through operational scale at its integrated gas facilities in South Korea and eastern China. Hangzhou Hangyang Co. Ltd dominates domestic project execution for Chinese steel majors seeking captive supply security.
An air separation unit separates atmospheric air into its primary components—nitrogen, oxygen, and argon—through cryogenic distillation at temperatures below minus 180 degrees Celsius or via non-cryogenic methods such as pressure swing adsorption using molecular sieves. These units produce industrial gases essential for steelmaking, chemical synthesis, medical therapy, and electronics manufacturing. Cryogenic systems command the largest installed base due to their unmatched purity output and economies of scale at volumes exceeding one thousand tons per day. Pressure swing adsorption is gaining ground in mid-scale applications where on-site nitrogen generation eliminates bulk liquid delivery logistics. Membrane separation occupies a niche in portable and low-purity oxygen supply for remote healthcare and small welding operations.
China's MEE enforces tightening emissions benchmarks that elevate energy efficiency to a core procurement criterion for new air separation investments. Japan's METI promotes hydrogen-oxygen co-production pilots that extend air separation infrastructure into clean energy supply chains. India's CEA mandates stricter power plant emissions controls that drive flue gas treatment oxygen demand from chemical sector suppliers. Stakeholders must weigh technology lock-in risks against the flexibility premium of modular adsorption systems as industrial gas demand fragments across scale tiers.
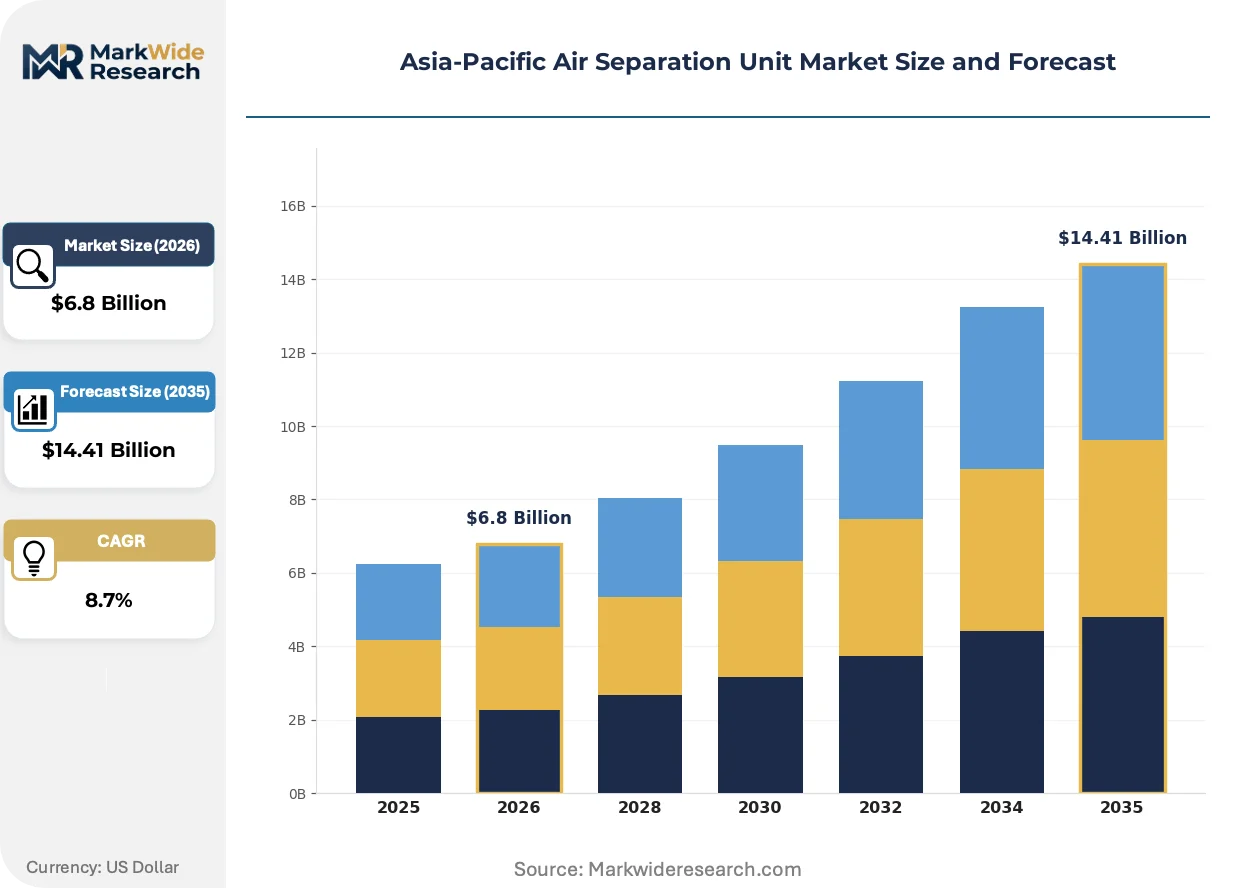
Market Dynamics
China's dual carbon goals are compressing capital cycles for air separation investments, forcing steel and chemical producers to prioritize energy-efficient cryogenic designs over legacy configurations that dominated procurement decisions through the past decade.
Growth Catalysts
- Dual carbon goals:China's MEE enforces tightening emissions benchmarks that elevate energy efficiency to a core procurement criterion for new air separation investments across steel and chemical corridors.
- Captive oxygen generation:Steelmakers in eastern China and India are expanding on-site production to eliminate bulk liquid delivery logistics and secure supply continuity.
- Hydrogen-oxygen co-production:Japan's METI promotes pilot programs that extend air separation infrastructure into clean energy supply chains, creating anchor demand for large-tonnage units.
Market Restraints
- Power cost volatility:Cryogenic distillation consumes substantial electricity, and grid price fluctuations in India and China compress operating margins for merchant gas suppliers.
- Equipment import dependence:High-purity heat exchangers and specialized compressors concentrate supply among European and Japanese vendors, exposing project timelines to currency and shipping risk.
- Membrane substitution ceiling:Pressure swing adsorption and membrane systems capture mid-scale nitrogen demand, constraining cryogenic volume growth in applications below 500 tons per day.
Strategic Opportunities
- Southeast Asia industrialization:Vietnam and Indonesia are expanding petrochemical capacity without established gas infrastructure, creating first-mover positioning for on-site air separation contracts.
- Electronics-grade argon:Semiconductor fabrication in South Korea and Taiwan requires ultra-high-purity argon that commands premium pricing and long-term offtake agreements.
- India CEA mandates:Stricter power plant emissions controls drive flue gas treatment oxygen demand from chemical sector suppliers positioned near coal-fired installations.
Industry Challenges
- Cryogenic engineering talent scarcity:Specialized process design and cold-box commissioning expertise concentrates among aging workforces in Japan and Germany, constraining project execution capacity.
- Legacy system integration:Steel mills retrofitting 1990s-vintage oxygen networks face compatibility failures with modern distributed control systems, extending outage windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Air Separation Unit Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Cryogenic, Pressure Swing Adsorption, Membrane Separation, Vacuum Pressure Swing Adsorption Application: Oxygen Production, Nitrogen Production, Argon Production, Industrial Gases End User: Healthcare, Chemical Industry, Metal Industry, Oil & Gas Distribution Channel: Direct Sales, Distributors, Online Sales, Others |
| Companies Covered | Air Liquide SA, Linde PLC, Praxair Technology, Inc., Air Products & Chemicals, Inc., Messer Group GmbH, Taiyo Nippon Sanso Corporation, Inox Air Products Pvt. Ltd, Iwatani Corp, Hangzhou Hangyang Co. Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Air Separation Unit Market Strategic Shifts
Electrification of compression trains and modular adsorption architectures are fragmenting technology selection criteria, splitting procurement between centralized cryogenic scale and distributed on-site generation.
Magnetic-bearing turboexpanders are electrifying auxiliary power demand in large cryogenic trains, cutting parasitic losses by eliminating oil lubrication systems. Petrochemical complexes in eastern China are specifying these for greenfield projects. The technology is electrifying competitive differentiation among equipment vendors bidding for coastal chemical corridor contracts.
China's MEE is tightening emissions benchmarks for industrial gas production, mandating energy consumption disclosures that factor into state-backed financing approvals. New air separation investments must document specific power-per-ton metrics to secure credit. Steel and chemical producers in the Shanghai-Nanjing corridor are responding by specifying variable-speed compression and optimized distillation column designs.
Long-term take-or-pay contracts are fragmenting into shorter-term, volume-flexible agreements with indexed energy pass-through clauses. Merchant gas distributors in South Korea and eastern China are unbundling equipment ownership from gas supply, selling molecules while retaining balance-sheet control of production assets. This restructuring is most visible among semiconductor and flat-panel manufacturers seeking to avoid stranded asset risk during technology transition cycles.
Asia-Pacific Air Separation Unit Market Segmentation
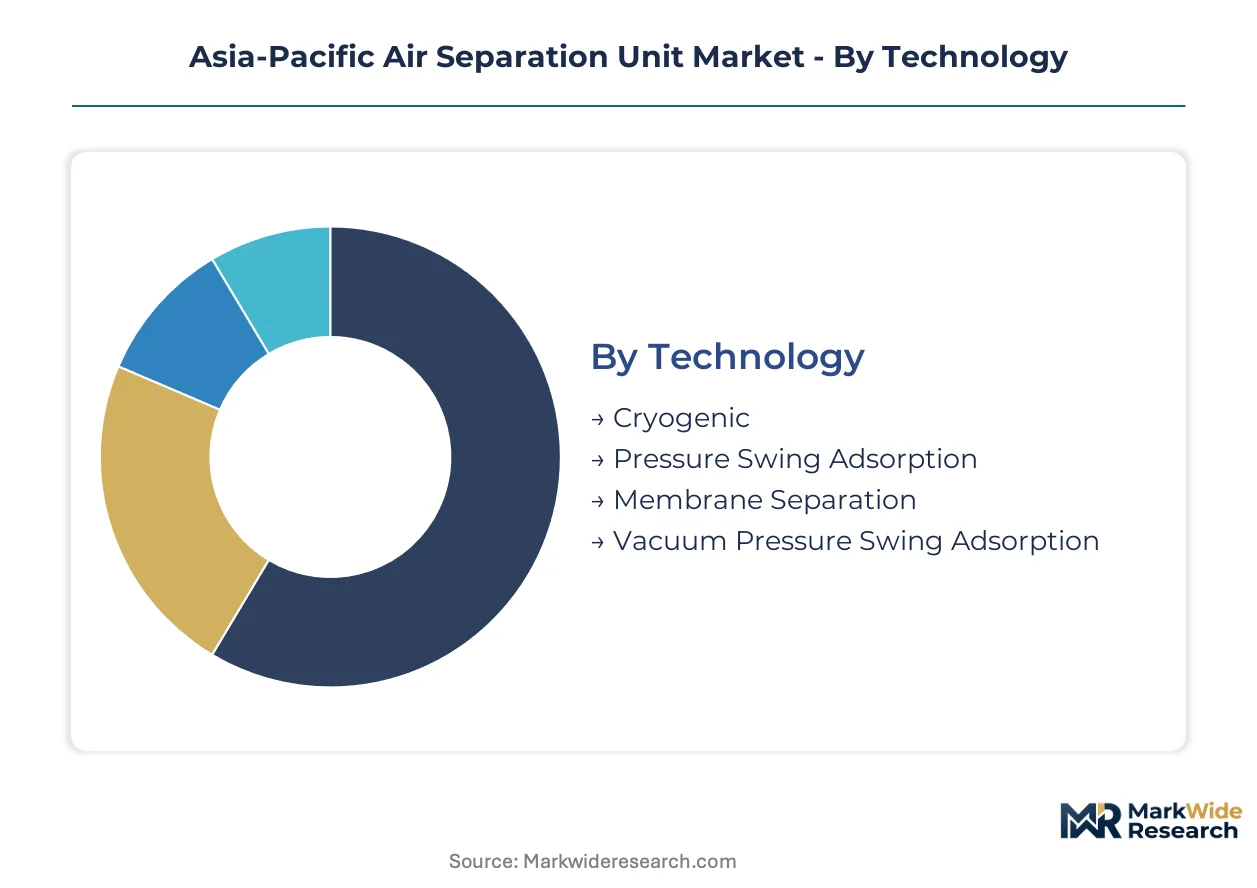
Technology selection in air separation units determines energy efficiency compliance with China's MEE benchmarks and shapes long-term operating economics for steel and chemical producers. Segmentation reveals how procurement priorities fragment across purity requirements, scale thresholds, and captive versus merchant supply models.
Technology:
Certification burdens concentrate on cryogenic systems requiring pressure vessel approvals and cold-box safety inspections under China's GB standards and Japan's METI technical guidelines, while adsorption and membrane systems face lighter regulatory scrutiny.
- Cryogenic:Distillation at sub-minus 180 degrees Celsius delivers ultra-high purity exceeding 99.5% for oxygen and nitrogen, essential for semiconductor-grade argon extraction in South Korea and Taiwan. Steelmakers across China's Shanghai-Nanjing corridor specify these for captive supply security above 1,000 tons per day.
- Pressure Swing Adsorption:Molecular sieve systems generate nitrogen at 95-99.9% purity without liquefaction, eliminating bulk liquid delivery logistics for mid-scale chemical plants. Demand concentrates in eastern India where grid volatility makes cryogenic power consumption uneconomical.
- Membrane Separation:Hollow-fiber polymer modules produce low-purity oxygen for remote healthcare and small welding operations across Southeast Asian archipelagos.
- Vacuum Pressure Swing Adsorption:Enhanced cycle efficiency captures oxygen demand in 50-200 tons per day applications for coal gasification projects in Shanxi province.
Leading the category by volume: Cryogenic. Growing fastest: Vacuum Pressure Swing Adsorption.
Application:
Cost tier stratification separates merchant gas pricing from captive production economics, with premium purity commanding long-term offtake premiums in electronics corridors.
- Oxygen Production:Steelmaking consumes over half of regional oxygen demand through basic oxygen furnaces and electric arc operations, with China's Baowu Group and India's JSW Steel expanding on-site generation to cut logistics costs. MEE emissions disclosures now mandate specific power-per-ton metrics for new investments.
- Nitrogen Production:Inerting and blanketing applications dominate chemical synthesis and oil refining, with Singapore's Jurong Island petrochemical cluster representing concentrated demand for pipeline-supplied volumes.
- Argon Production:Ultra-high-purity extraction for semiconductor fabrication in Hsinchu and Pyeongtaek commands premium pricing through multi-year supply agreements.
- Industrial Gases:Bundled merchant supply serves fragmented small and medium enterprises lacking scale for captive investment across Vietnam and Indonesia.
Dominant by revenue: Oxygen Production. Steepest expansion trajectory: Argon Production.
End User:
Customer type fragmentation splits procurement between state-backed steel majors with balance-sheet capacity for greenfield cryogenic investment and cash-constrained healthcare distributors favoring modular adsorption.
- Healthcare:Medical oxygen demand surged following pandemic supply chain disruptions, with India's Ministry of Health mandating buffer storage at district hospitals. Portable concentrators and small PSA units now serve remote clinics across the Himalayan foothills and Indonesian outer islands.
- Chemical Industry:Ammonia and methanol synthesis require nitrogen-hydrogen ratios precisely controlled through on-site air separation, with China's coal-to-chemicals corridor from Ningxia to Inner Mongolia anchoring large-tonnage demand.
- Metal Industry:Steelmaking oxygen intensity averages 50-60 cubic meters per ton of crude steel, driving captive investment at integrated mills in Guangdong and Maharashtra.
- Oil & Gas:Enhanced oil recovery and refinery inerting consume nitrogen volumes across Southeast Asian offshore platforms and India's Reliance Jamnagar complex.
Volume leader: Metal Industry. Fastest share gain: Healthcare.
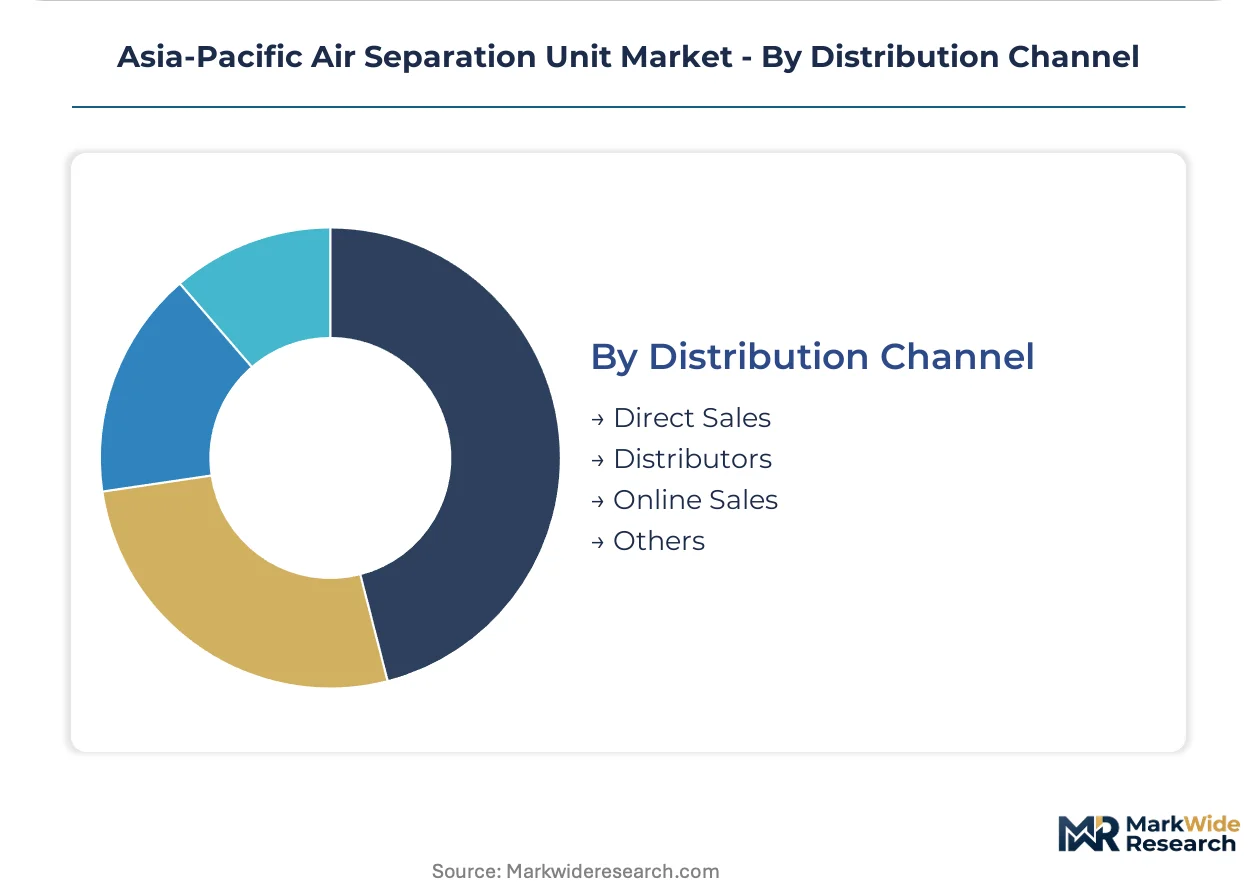
Distribution Channel:
Supply concentration in direct sales reflects the project-engineering intensity of cryogenic installations, while distributor networks capture recurring consumables and spare parts demand.
- Direct Sales:Engineering-procurement-construction contractors manage turnkey cryogenic projects for petrochemical complexes, with Air Liquide and Linde maintaining dedicated sales teams for coastal China and South Korea.
- Distributors:Regional gas equipment dealers supply replacement molecular sieves, compressor parts, and maintenance services to mid-scale PSA operators across India's industrial belts.
- Online Sales:E-commerce platforms penetrate small-scale membrane and portable oxygen concentrator segments for home healthcare and workshop welding applications.
- Others:Leasing and equipment-as-a-service models are emerging among semiconductor manufacturers seeking to avoid stranded asset risk during technology transition cycles.
Channel concentration: Direct Sales. Expanding most quickly: Others.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China produces the majority of regional air separation capacity while India and Southeast Asian markets absorb merchant gas volumes. Steelmakers and chemical producers drive investment geography across coastal industrial corridors.
China
Baowu Group and Jiangsu Shagang anchor captive oxygen demand exceeding one thousand tons per day at integrated coastal mills. The Ministry of Ecology and Environment enforces energy consumption disclosures that gate state-backed financing for new cryogenic investments. Project activity concentrates in the Shanghai-Nanjing chemical corridor where variable-speed compression and optimized distillation column designs dominate greenfield specifications.
India
JSW Steel and Tata Steel are expanding on-site generation to eliminate bulk liquid delivery logistics across Maharashtra and Odisha. The Central Electricity Authority mandates stricter power plant emissions controls that drive flue gas treatment oxygen demand from chemical sector suppliers. Merchant gas distributors cluster near coal-fired installations in Gujarat and Chhattisgarh to serve flue gas desulfurization requirements.
Japan
Semiconductor fabrication in Hsinchu and Pyeongtaek commands ultra-high-purity argon through multi-year supply agreements with Japanese industrial gas producers. METI promotes hydrogen-oxygen co-production pilots that extend air separation infrastructure into clean energy supply chains. Equipment vendors concentrate process design expertise in the Chubu region around Nagoya for cold-box commissioning.
South Korea
Flat-panel and memory chip manufacturers anchor electronics-grade nitrogen demand through pipeline-supplied volumes at Pyeongtaek and Icheon complexes. Merchant gas distributors unbundle equipment ownership from gas supply, selling molecules while retaining balance-sheet control of production assets. Leasing models proliferate among semiconductor manufacturers seeking to avoid stranded asset risk during technology transition cycles.
Vietnam
Petrochemical capacity expansion at Long Son and Nghi Son complexes proceeds without established gas infrastructure, creating first-mover positioning for on-site air separation contracts. Provincial industrial zones offer tax incentives for captive oxygen generation supporting steel re-rolling and welding electrode manufacturing. Mid-scale pressure swing adsorption systems capture nitrogen demand from food packaging and electronics assembly operations.
Asia-Pacific Air Separation Unit Market Competitive Environment
The competitive structure tilts toward integrated industrial gas conglomerates with cryogenic technology leadership and project execution scale. Market concentration reflects high capital barriers for large-tonnage distillation systems and specialized cold-box engineering expertise. Two strategic archetypes dominate: multinational operators leveraging long-term take-or-pay contracts with coastal petrochemical complexes, and domestic fabricators capturing steel sector captive investment through execution speed and local procurement relationships. Capacity expansion and technology licensing represent the dominant competitive moves, with equipment vendors electrifying compression trains to meet tightening emissions benchmarks.
Among multinational operators, Air Liquide SA and Linde PLC occupy positions anchored by coastal China and South Korea infrastructure. Hangzhou Hangyang Co. Ltd exemplifies the domestic execution archetype for Chinese steel majors seeking supply security. Taiyo Nippon Sanso Corporation represents specialized positioning in electronics-grade argon extraction for semiconductor corridors. These three companies illustrate how geographic origin and company structure map to distinct competitive vectors without overlapping strategic territory.
| Leading Market Players |
|---|
| Air Liquide SA |
| Linde PLC |
| Praxair Technology, Inc. |
| Air Products & Chemicals, Inc. |
| Messer Group GmbH |
| Taiyo Nippon Sanso Corporation |
| Inox Air Products Pvt. Ltd |
| Iwatani Corp |
| Hangzhou Hangyang Co. Ltd |
| Others |
Value Chain & Pricing Dynamics
Aluminum alloy price indices on the Shanghai Futures Exchange cascade through cryogenic equipment fabrication costs, compressing margins for cold-box manufacturers serving steel and chemical buyers across eastern China's industrial corridors. Procurement officers at Baowu Group and Jiangsu Shagang negotiate energy-pass-through clauses that index oxygen supply contracts to provincial grid tariffs, fragmenting pricing power between equipment vendors and merchant gas distributors.
Pricing Analysis
Uptime-guarantee pricing anchors long-term offtake agreements for large-tonnage cryogenic units, with semiconductor manufacturers in Hsinchu and Pyeongtaek paying premiums for argon purity exceeding 99.999%. Three-tier pricing structure across premium, standard, and economy levels separates electronics-grade certification from industrial steelmaking grades and portable healthcare concentrators. Cost compression in standard-tier nitrogen supply is intensifying because pressure swing adsorption systems eliminate liquefaction overhead for mid-scale chemical plants. Merchant gas distributors exhibit highest price sensitivity, while captive oxygen investors at integrated steel mills prioritize supply security over unit economics.
Supply Chain Analysis
Direct-to-mill channels handle hyperscale captive oxygen demand from Chinese and Indian steel majors, while distributor networks capture recurring molecular sieve and compressor parts demand from mid-scale PSA operators. High-purity heat exchangers and specialized turboexpanders concentrate supply among German and Japanese precision engineering clusters, with brazed aluminum heat exchanger cores drawing from Austrian and Chinese foundry capacity. Single-source vulnerability in cryogenic cold-box engineering expertise—concentrated among aging workforces in Nagoya and Düsseldorf—exposes project timelines to commissioning delays. Distribution runs through engineering-procurement-construction contractors for greenfield petrochemical complexes, and through regional gas equipment dealers for aftermarket services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where equipment ownership unbundling from gas supply is the downstream lever multinational operators are pursuing to capture recurring revenue streams.
For Market Incumbents: Anticipate membrane and pressure swing adsorption substitution in sub-500-ton applications by securing long-term hydrogen-oxygen co-production pilots with METI-backed clean energy consortia. Defend cryogenic market share through backward integration into variable-speed compression manufacturing, cutting dependence on European drivetrain suppliers exposed to currency volatility. Prioritize certification investment for GB standard compliance to maintain eligibility for state-backed financing at Chinese steel majors. For New Entrants and Emerging Players: Begin with modular vacuum pressure swing adsorption systems targeting 50-200 ton per day oxygen demand in Shanxi province coal gasification corridors, where captive supply security outweighs purity requirements. Vietnam's Long Son and Nghi Son petrochemical expansions represent the most penetrable geography, lacking established gas infrastructure and offering provincial tax incentives for on-site generation. Pursue equipment-as-a-service go-to-market models with semiconductor manufacturers seeking to avoid stranded asset risk during technology transitions. For Investors and Strategic Acquirers: Distressed-cycle entries favor cryogenic engineering specialists with cold-box commissioning expertise in Japan's Chubu region, where capability scarcity constrains regional project execution capacity. Long-term viability over a multi-year horizon hinges on positioning for hydrogen economy infrastructure buildout through oxygen co-production integration. Watch for MEE emissions disclosure enforcement tightening as the inflection indicator for energy-efficient equipment replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compression Manufacturing | Air Liquide and Linde reduce European drivetrain exposure by controlling variable-speed compressor supply for Shanghai-Nanjing corridor projects. |
| Hydrogen-Oxygen Co-Production Pilot | METI-funded consortia in Japan extend air separation infrastructure into clean energy supply chains, creating anchor demand for large-tonnage units. |
| Equipment-as-a-Service Model | South Korean semiconductor manufacturers at Pyeongtaek complexes avoid stranded asset risk by leasing production assets rather than owning them. |
| GB Standard Certification Investment | Hangzhou Hangyang secures state-backed financing eligibility by documenting energy consumption disclosures for Chinese steel majors. |
| Modular VPSA Capacity Expansion | Shanxi province coal gasification projects capture 50-200 ton per day oxygen demand with enhanced cycle efficiency systems. |
Study Parameters
Document review covered customs and trade data from China's General Administration, SEC filings from industrial gas conglomerates, and METI hydrogen economy pilot disclosures, complemented by interviews with plant engineers at Baowu Group and JSW Steel, procurement leads at Singapore's Jurong Island petrochemical cluster, and aftermarket service heads at Indian distributor networks. Secondary validation drew from GB standards documentation, CEA emissions control mandates, and cold-box engineering technical guidelines. Bottom-up project pipeline assessment triangulated against top-down regional industrial gas demand modeling.
Segment-level volume and value trajectories across the projection horizon were derived through technology-by-application matrix analysis, with cryogenic, pressure swing adsorption, membrane, and vacuum pressure swing adsorption systems modeled separately against oxygen, nitrogen, argon, and bundled industrial gas demand from steel, chemical, healthcare, electronics, and oil and gas end users. CAGRs were computed from installed base expansion rates and replacement cycle timing, incorporating provincial grid tariff volatility as a key forecast input alongside MEE emissions disclosure enforcement intensity.
Underlying measurement precision varies by segment; cryogenic large-tonnage installations carry tighter precision than fragmented portable healthcare concentrator demand. Forecasts reflect assumptions regarding dual carbon goal implementation pacing and hydrogen economy infrastructure rollout timing. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Asia-Pacific 3D Printing Construction Market
Others
United States Smart Homes Market
Others
Post Consumer Recycled Bottles Market
Others
Asia-Pacific Induced Pluripotent Stem Cells (Ipscs) Market
Others
Deflectometer Market
Others
Underwater Communication System Market
Others
Middle East and Africa Halal Food & Beverage Market
Others
Ultrasonic Flow Meter Market
Others
Europe Air Separation Unit Market
Others
High Voltage Measuring Equipment Market
Others
Japan Indoor LBS Market
Others
Global Solder Balls Market
Others
Air Separation Module Kit Market
Others
Advanced Combat Helmet Market
Others
Mobile Computer Cart Market
Others
Smart Home As a Service Market