
 IoT Testing Market | 2026-2036
IoT Testing Market Size, Share, and Industry Trends Forecast 2026-2036
IoT Testing Market Intelligence
The substitution of manual testing scripts with AI-driven automated validation platforms is realigning the economics of quality assurance for connected devices. Keysight Technologies, Inc. specializes in hardware-level performance and conformance testing equipment. In contrast, Capgemini SE leverages its broad consulting expertise to deliver end-to-end managed testing services for large enterprises. HCL Technologies Ltd. competes by offering integrated engineering and QA services across the product lifecycle.
IoT testing involves a systematic process to validate the functionality and reliability of interconnected devices and their networks. This process verifies communication protocols, such as MQTT and CoAP, and ensures data integrity from sensor to cloud. Within test types, security testing is the fastest-growing segment due to rising cyber threats. Managed testing services are gaining share over one-off consulting engagements as organizations seek long-term QA partnerships for complex ecosystems.
Regulatory frameworks are critical in shaping testing requirements. The EU's GDPR mandates stringent data privacy validation, while the FCC in the United States sets standards for radio frequency emissions for connected devices. Conformance to technical standards from bodies like ETSI is often required for market access in Europe. Enterprises must now strategically decide whether to build internal testing capabilities or partner with specialized service providers to manage complexity and cost.
Market Dynamics
The central tension in the IoT testing market is the conflict between explosive device proliferation and increasingly stringent cybersecurity mandates. This dynamic is forcing a strategic re-evaluation of quality assurance to meet compliance demands from frameworks like the EU's GDPR.
Growth Catalysts
- Regulatory Mandates:The EU's General Data Protection Regulation (GDPR) and upcoming AI Act require rigorous data protection and security validation, compelling enterprises to invest in comprehensive testing for all connected systems.
- Healthcare Sector Expansion:Growth in telehealth and connected medical devices, governed by regulations like the EU's Medical Device Regulation (MDR), necessitates non-negotiable performance and reliability testing to ensure patient safety.
- Network Modernization:The global rollout of 5G and edge computing architectures increases system complexity, driving demand for advanced interoperability, latency, and performance testing to ensure seamless device communication.
Market Restraints
- Protocol Fragmentation:A diverse and non-standardized landscape of communication protocols, including MQTT, CoAP, Zigbee, and LoRaWAN, complicates test development and execution, increasing the overall cost and time of validation.
- Standardization Gaps:The absence of universally accepted security and interoperability standards across different IoT verticals results in inconsistent testing quality and creates potential vulnerabilities in heterogeneous environments.
- High Capital Outlay:The significant initial investment required for specialized radio frequency (RF) test equipment, anechoic chambers, and automated validation platforms presents a substantial barrier for smaller device manufacturers.
Strategic Opportunities
- Automotive V2X Systems:Testing services for Vehicle-to-Everything (V2X) communication technologies represent a significant opportunity as automakers integrate connected safety and autonomous driving features that require ultra-reliable validation.
- Testing-as-a-Service (TaaS):The shift toward subscription-based TaaS models provides a scalable and cost-effective solution for enterprises seeking continuous validation and access to specialized expertise without large upfront capital expenditures. *Industrial IoT in Emerging Economies: Demand for industrial IoT testing is accelerating in manufacturing hubs within India and Brazil, supported by national digitalization programs and smart factory initiatives.
Industry Challenges
- Specialized Talent Scarcity:A pronounced shortage of engineers possessing a combination of skills in cybersecurity, cloud architecture, and radio frequency engineering creates a significant bottleneck for testing service providers.
- Legacy System Integration:Ensuring new IoT deployments can securely and reliably interface with pre-existing enterprise IT and operational technology (OT) infrastructure remains a major technical and costly challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IoT Testing Market |
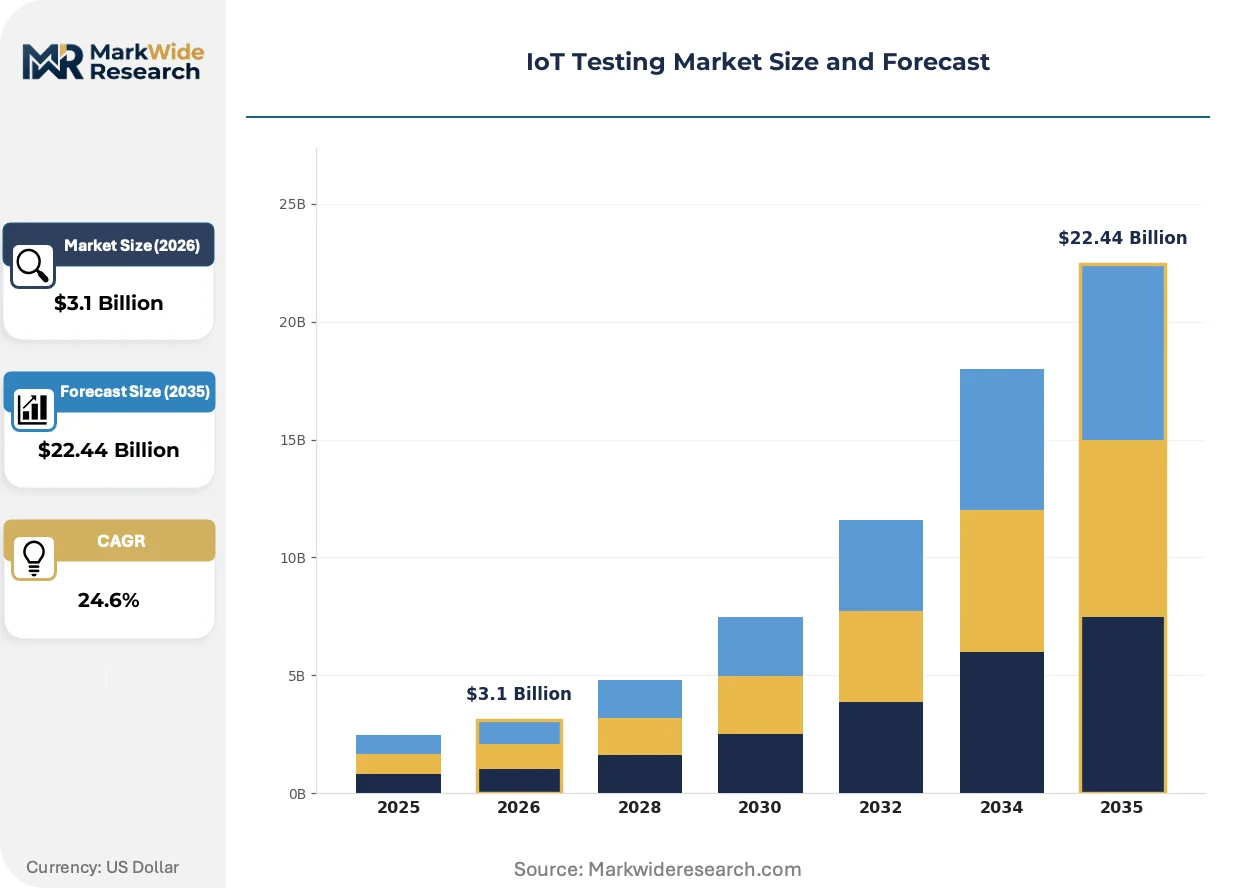
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $22.44 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Functional Testing, Performance Testing, Security Testing, Interoperability Testing Service Type: Test Automation, Consulting Services, Managed Testing, QA Services Deployment Model: On-Premises, Cloud-Based, Hybrid, Edge Computing End User: Manufacturing, Healthcare, Smart Home, Transportation |
| Companies Covered | Capgemini SE, HCL Technologies Ltd., Infosys Limited, Keysight Technologies, Inc., Happiest Minds Technologies Limited, Apica AB, AFour Technologies, Novacoast, Inc., Praetorian Security, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IoT Testing Market Strategic Shifts & Innovations
Convergence of artificial intelligence with test automation platforms is reshaping the economics and execution of quality assurance. This evolution moves the industry away from manual script execution toward predictive, self-healing validation frameworks for connected systems.
Digital twin technology creates virtual replicas of IoT devices and entire physical systems for comprehensive simulation testing. Aerospace and industrial manufacturing sectors are adopting this for pre-deployment validation and predictive maintenance analysis. This simulation-first approach is absorbing workload from physical hardware testing, reducing development timelines.
The United States' Cyber Trust Mark program, administered by the FCC, establishes a voluntary cybersecurity labeling standard for consumer IoT products. This initiative creates a market-based incentive for manufacturers to demonstrate adherence to baseline security requirements. Consumer electronics and smart home device makers are most affected, integrating security testing earlier to qualify.
A clear behavioral shift is occurring from project-based, one-off testing engagements toward long-term managed service partnerships. Enterprises are replacing siloed internal QA teams by outsourcing the entire testing function to specialized providers offering continuous validation. This trend is most visible in European financial services and healthcare, where constant regulatory monitoring is essential.
IoT Testing Market Segmentation
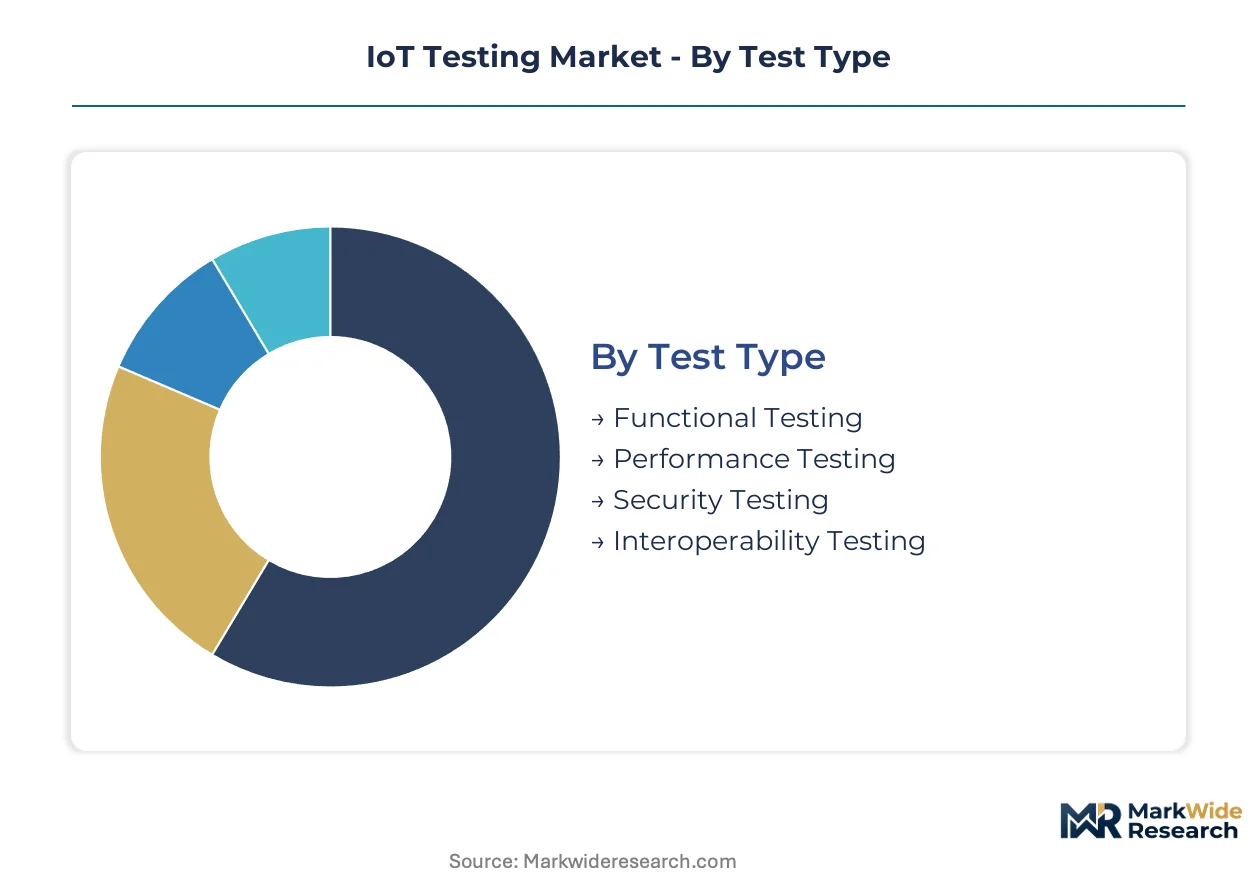
The IoT testing market segments across critical dimensions, reflecting varied technical demands and regulatory landscapes. Understanding these distinctions helps enterprises tailor validation strategies and solution providers address specific industry needs. This segmentation highlights where investment and innovation are concentrating within the complex IoT ecosystem.
Test Type:
Ensuring compliance with diverse national and international standards places a significant certification burden on manufacturers, driving demand across specific test types.
- Security Testing:This test type evaluates the resilience of IoT devices, networks, and applications against cyber threats, including data breaches and unauthorized access. Stringent data protection mandates, such as the EU's GDPR, necessitate comprehensive security testing across all connected systems.
- Performance Testing:Performance testing assesses the responsiveness, stability, and scalability of IoT systems under various load conditions, ensuring devices function reliably in real-world scenarios. The global rollout of 5G and edge computing architectures increases system complexity, driving demand for advanced performance testing.
- Functional Testing:Functional testing verifies that each feature and function of an IoT device or system operates according to its specified requirements. This ensures the basic operation of connected devices.
- Interoperability Testing:This testing validates the seamless communication and data exchange between different IoT devices, platforms, and ecosystems. Interoperability is crucial for heterogeneous environments.
Leading the category by volume: Functional Testing. Growing fastest: Security Testing represents the fastest-growing trajectory.
Service Type:
Different customer needs drive demand across various service types, from specialized consulting to comprehensive managed solutions.
- Managed Testing:Managed testing services involve outsourcing the entire testing function to specialized providers, offering continuous validation and access to expertise. Enterprises in European financial services and healthcare increasingly adopt this for constant regulatory monitoring.
- Test Automation:Test automation platforms leverage AI to execute test cases automatically, significantly reducing manual effort and accelerating validation cycles for connected devices. This technology is reshaping the economics of quality assurance.
- Consulting Services:Consulting services provide expert guidance on testing strategies, tool selection, and process optimization for complex IoT deployments. Capgemini SE leverages broad consulting expertise for large enterprises.
- QA Services:QA services encompass a range of activities aimed at ensuring the overall quality and reliability of IoT products throughout their lifecycle. HCL Technologies Ltd. offers integrated engineering and QA services.
Managed Testing is gaining share, while Test Automation is central to efficiency improvements.
Deployment Model:
The technical architecture required for IoT deployments dictates the choice of testing deployment models, influencing scalability and latency considerations.
- Cloud-Based:Cloud-based testing utilizes scalable cloud infrastructure to perform validation, offering flexibility and remote access for distributed IoT ecosystems. This model supports extensive simulation and parallel testing.
- Edge Computing:Edge computing deployment models focus on testing at or near the data source, crucial for applications requiring low latency and real-time processing. Vehicle-to-Everything (V2X) systems require edge-based validation for safety-critical functions.
- On-Premises:On-premises testing involves deploying testing environments within an organization's own data centers or facilities. This model provides maximum control over data and infrastructure.
- Hybrid:Hybrid deployment models combine elements of both on-premises and cloud-based testing, leveraging the strengths of each for specific IoT testing requirements. This offers a balance of control and scalability.
Cloud-Based models offer scalability, with Edge Computing solutions addressing low-latency requirements.
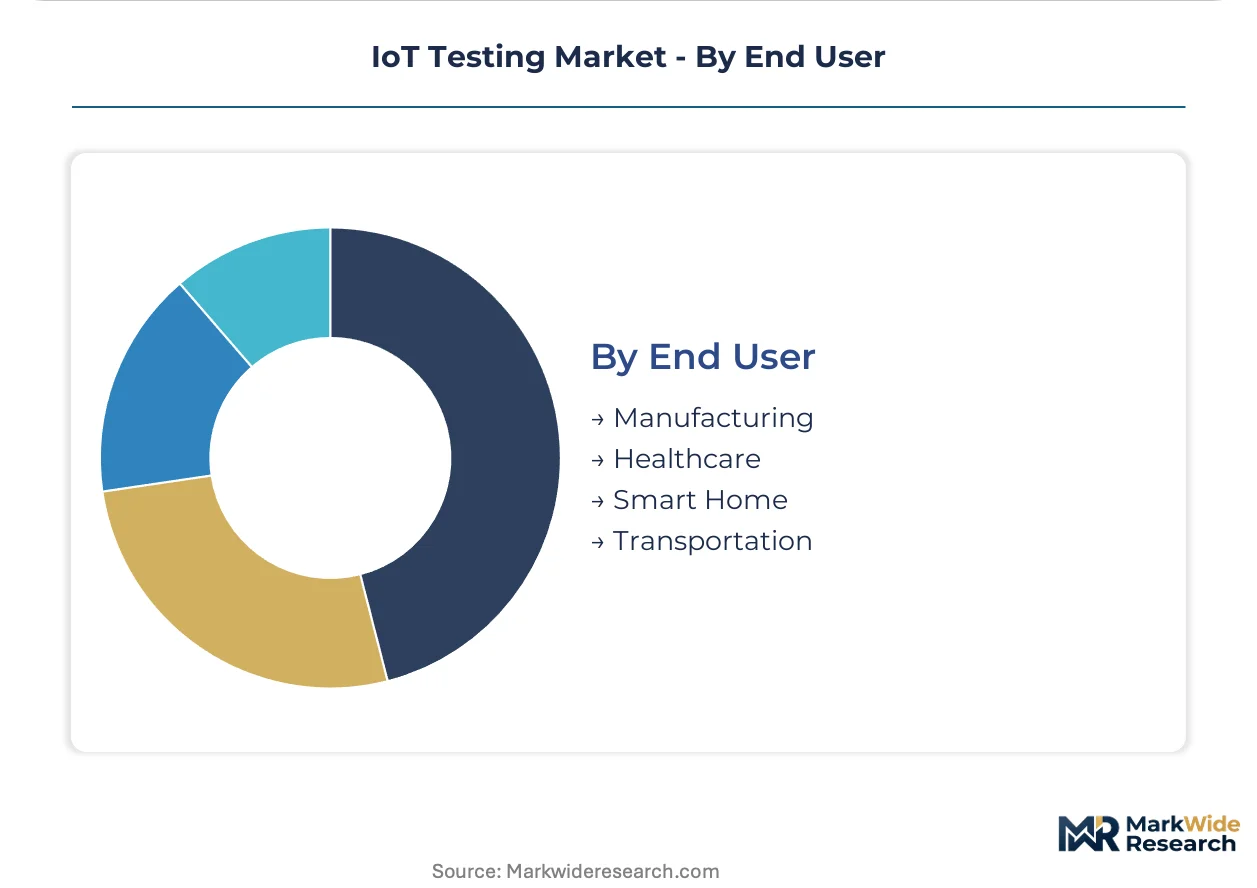
End User:
Regulatory stringency and safety mandates heavily influence the specific testing requirements within each end-user sector, impacting investment priorities.
- Healthcare:The healthcare sector demands rigorous testing for connected medical devices and telehealth solutions to ensure patient safety and data privacy. Regulations like the EU's Medical Device Regulation (MDR) necessitate non-negotiable performance and reliability testing.
- Manufacturing:Manufacturing relies on IoT testing for smart factory initiatives, validating industrial IoT devices and systems for efficiency, predictive maintenance, and operational safety. Demand for industrial IoT testing services is concentrating in Germany and India.
- Smart Home:The smart home segment requires testing for interoperability, security, and user experience across a diverse range of consumer connected devices. The United States' Cyber Trust Mark program incentivizes baseline security testing for these products.
- Transportation:Transportation applications, including automotive V2X systems and fleet management, require extensive testing for connectivity, reliability, and safety. These systems demand ultra-reliable validation for autonomous driving features.
Healthcare and Manufacturing sectors demonstrate substantial investment in IoT testing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing hubs, particularly in Germany and India, drive significant demand for IoT testing, propelled by smart factory initiatives and national digitalization programs. These concentrations necessitate rigorous validation for industrial IoT systems and connected devices. Regulatory mandates further shape testing requirements within these dynamic regions.
United States
The United States market sees strong demand for IoT testing driven by smart home device proliferation and automotive V2X systems. The FCC sets standards for radio frequency emissions for connected devices, impacting market entry for manufacturers. California's Silicon Valley and Texas's tech corridors concentrate development for consumer electronics and autonomous vehicle testing.
Germany
Germany's robust manufacturing sector fuels demand for industrial IoT testing services, driven by advanced smart factory initiatives. The EU's GDPR mandates stringent data privacy validation for connected systems, influencing testing protocols. Bavaria and North Rhine-Westphalia are key industrial regions, focusing on automotive and machinery IoT validation.
India
India's national digitalization programs and growing manufacturing base accelerate demand for industrial IoT testing services. The country's regulatory bodies are developing frameworks for data protection and device certification. Maharashtra and Karnataka lead in smart factory and IT-OT integration projects, driving significant testing requirements.
Brazil
Brazil exhibits rising demand for IoT testing, particularly in smart agriculture and industrial applications, supported by government investment in digital infrastructure. ANATEL, the national telecommunications agency, regulates connected device conformity for market access. São Paulo and Minas Gerais are key areas for agricultural tech and industrial IoT deployments.
France
France's IoT testing market is influenced by strong regulatory requirements, including the EU's GDPR and ETSI technical standards for telecommunications. The nation's healthcare sector and smart city initiatives drive significant testing for connected medical devices and urban infrastructure. Île-de-France and Auvergne-Rhône-Alpes are central to these advanced technology and testing developments.
IoT Testing Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the IoT testing market, reflecting varied technical demands and client needs. This landscape features a blend of established technology providers, niche cybersecurity firms, and comprehensive managed service organizations. Strategic archetypes include hardware-focused conformance testing equipment vendors, broad consulting entities delivering end-to-end solutions, and integrated engineering service providers spanning the product lifecycle. Companies actively pursue portfolio diversification and strategic partnerships to address complex, evolving client requirements and regulatory mandates.
Within the specialized hardware and software solutions tier, Keysight Technologies, Inc. exemplifies a provider focusing on performance and conformance testing equipment. Capgemini SE, a Société Européenne, occupies a position among the broad consulting entities, delivering extensive managed testing services for large enterprises. HCL Technologies Ltd., an Indian multinational, represents firms offering integrated engineering and QA services across the product lifecycle. These entities reflect the varied expertise required to address the diverse technical and regulatory challenges of the IoT testing ecosystem.
| Leading Market Players |
|---|
| Capgemini SE |
| HCL Technologies Ltd. |
| Infosys Limited |
| Keysight Technologies, Inc. |
| Happiest Minds Technologies Limited |
| Apica AB |
| AFour Technologies |
| Novacoast, Inc. |
| Praetorian Security, Inc. |
Cost & Logistics Intelligence
Venture-backed specialist firms in IoT testing shape supply behavior, driving competitive pricing for advanced validation platforms. Their focus on niche expertise and rapid innovation influences service delivery models and cost structures.
Pricing Analysis
Premium pricing for short lead times on complex IoT testing engagements reflects specialized talent scarcity and urgent market access needs. Project-based models dominate bespoke solutions, while subscription services like Testing-as-a-Service gain traction for continuous validation. Customization level and specific regulatory certifications, such as GDPR compliance, drive significant price differentiation. Pricing softness stems from AI-driven automation reducing manual effort, particularly for basic functional testing, making small device manufacturers highly price-sensitive compared to large enterprises.
Supply Chain Analysis
Managed service providers and consulting firms deliver IoT testing services directly to enterprises, while hardware vendors use direct sales or specialized distributors. Geographic supply concentration for services is evident in Germany and India, driven by industrial IoT initiatives. The supply chain draws from specialized RF test equipment and automated validation platforms. A structural risk involves the scarcity of engineers possessing combined cybersecurity, cloud architecture, and radio frequency expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The IoT testing market is experiencing a technology-transition phase, as AI-driven automated validation platforms increasingly replace legacy manual testing scripts. This shift reshapes quality assurance economics for connected devices.
For Market Incumbents: Anchor existing client relationships by integrating AI-driven automated validation platforms to enhance efficiency and reduce testing cycles. Pursue strategic acquisitions of niche cybersecurity testing firms to address rising cyber threats and specialized talent scarcity. Invest in R&D for predictive testing capabilities to stay ahead of the fragmented protocol landscape. Prioritize certification investments for emerging standards like the EU AI Act.
For New Entrants and Emerging Players: The EU's GDPR in Europe opens a window for new entrants to offer specialized data privacy and security validation services for IoT. Target underpenetrated segments like small device manufacturers with scalable, cost-effective Testing-as-a-Service (TaaS) models. Focus on niche verticals such as industrial IoT in emerging economies like India, leveraging national digitalization programs. Develop expertise in specific communication protocols to address market fragmentation.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialist software and service providers in Europe, where regulatory burdens are intensifying. The market offers long-term viability over the next decade due to continued IoT proliferation and rising complexity. Identify acquisition targets with proprietary AI-driven testing IP or deep vertical expertise in areas like medical devices. A key signal to watch is consolidation within the managed testing services segment.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch: AI-driven Predictive Testing Platform | This initiative allows for proactive identification of vulnerabilities, reducing time-to-market for connected devices. |
| Strategic Partnership: With Cloud Providers | Collaborations with hyperscalers enable scalable, distributed testing environments for complex IoT ecosystems. |
| Acquisition of Specialist Firm: Cybersecurity Testing | Acquiring niche cybersecurity firms addresses the critical need for advanced threat validation in IoT deployments. |
| Geographic Expansion: Into Industrial IoT Hubs | Expanding into manufacturing centers like India captures demand from smart factory initiatives and national digitalization. |
| Platform Integration: With Digital Twin Technology | Integrating digital twins enables comprehensive simulation testing, absorbing workload from physical hardware validation. |
Research Approach
Multi-period observation of IoT device proliferation and regulatory compliance trends anchored the trend analysis, supplemented by interviews with industry stakeholders. Primary research involved discussions with QA managers, IoT solution architects, compliance officers, and RF engineers. Secondary validation drew from FCC filings, ETSI standards documents, and academic research on IoT security. This approach employed both bottom-up market sizing and top-down validation.
Segment-weighting across test type, service type, deployment model, and end-user categories formed the quantitative basis for market projections. The analytical framework modeled market evolution across the analysis window by combining historical growth patterns with projected technological shifts. Compound Annual Growth Rates were derived from these integrated inputs. Key forecast inputs included 5G rollout schedules, IoT device shipment forecasts, and cybersecurity threat intelligence reports.
The model assumes a particular technology adoption path; alternative pathways for AI-driven automation would alter the outlook. Forecasts reflect inherent assumptions, and unforeseen regulatory shifts or major cybersecurity breaches represent key risk factors. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
North America 3D Printing Construction Market
Others
Dandelion Market
Others
Shear Testing Equipment Market
Others
Global Injectable Nanomedicine Market
Others
Italy 3D Printing Construction Market
Others
Global Smart Kitchen Market
Others
Infant Fever Stickers Market
Others
Tobacco Packaging Market
Others
AI in Precision Medicine Market
Others
Thermal Energy Flow Metering Solutions Market
Others
Communication Base Station Body Market
Others
Binoculars Market
Others
China Online Gambling Market
Others
Android STB and TV Market
Others
Global Cosmetovigilance Market
Others
ISO Cylinder Market