
 Rubber Compound Market | 2026-2036
Rubber Compound Market Size, Share, and Industry Trends Forecast 2026-2036
Rubber Compound Market Analysis
The capital-intensity divergence between fully integrated petrochemical producers and specialty compounders is bifurcating competitive dynamics across the rubber compound landscape. Bridgestone leverages captive synthetic rubber capacity to secure feedstock cost stability for tire-grade compounds. Kumho Petrochemical anchors its position through backward integration into styrene-butadiene rubber monomers, insulating margin pools from butadiene volatility. LANXESS AG differentiates via high-performance elastomer portfolios targeting automotive under-the-hood applications where temperature resistance commands premium positioning.
Rubber compounds constitute formulated mixtures of base elastomers, reinforcing fillers such as carbon black or silica, vulcanizing agents, and process oils, blended through internal mixing or mill processing to achieve specified hardness, tensile strength, and compression set characteristics for finished component manufacturing. Synthetic rubber formulations dominate volume throughput in tire applications, where solution-polymerized styrene-butadiene rubber delivers superior wet-grip performance relative to emulsion grades. Silicone rubber occupies the fastest-expanding margin pool, driven by electric vehicle thermal management systems requiring sustained elasticity across temperature extremes. Aerospace-grade compounds command specialized certification barriers that limit supplier bases and sustain pricing premiums.
REACH in Europe mandates full substance registration for imported rubber chemicals, while China's SAMR enforces GB standards on tire rolling resistance and wet grip that compound formulations must satisfy. The EPA in the United States regulates volatile organic compound emissions from rubber processing facilities, pushing manufacturers toward solvent-free mixing technologies. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance cost asymmetries will reshape sourcing geography and compound formulation strategies.
Market Dynamics
Automotive electrification is rewriting rubber compound specifications, with thermal management systems demanding elastomers that maintain elasticity across temperature extremes that internal combustion engines never reached.
Growth Catalysts
- Electric vehicle thermal management:Battery pack cooling systems require silicone rubber compounds with sustained performance from minus forty to two hundred degrees Celsius, opening premium formulation demand.
- REACH substance registration:ECHA's full disclosure mandates for imported rubber chemicals are accelerating substitution toward pre-registered, compliant additive packages among European tire manufacturers.
- Southeast Asian tire manufacturing:Production clusters in Thailand and Indonesia are scaling capacity, concentrating procurement volumes for solution-polymerized styrene-butadiene rubber grades.
Market Restraints
- Butadiene feedstock volatility:Synthetic rubber producers face margin compression when naphtha-cracking economics swing, as butadiene constitutes the primary monomer cost in styrene-butadiene formulations.
- Carbon black supply concentration:Reinforcing filler production clusters in China and India create geographic risk for compounders dependent on consistent tensile strength performance.
- Fluorocarbon substitution threat:Perfluoroelastomer seals are penetrating aerospace and chemical processing applications where extreme chemical resistance outweighs cost premiums.
Strategic Opportunities
- India automotive localization:PLI scheme incentives for electric vehicle component manufacturing are drawing compounders to establish mixing facilities near Chennai and Pune assembly plants.
- Recycled carbon black integration:Pyrolysis-derived filler from end-of-life tires is achieving performance parity in non-dynamic applications, enabling circular economy positioning.
- Solvent-free mixing technology:EPA volatile organic compound enforcement is creating first-mover advantage for compounders deploying internal mixing without aromatic process oils.
Industry Challenges
- Compound formulation chemist shortage:Expertise in sulfur vulcanization kinetics and filler dispersion rheology is retiring faster than university polymer programs replenish talent pipelines.
- Aerospace certification timelines:FAA and EASA qualification protocols for nitrile and fluorocarbon compounds extend eighteen to thirty-six months, freezing formulation iterations for commercial aircraft programs.
- Legacy mixing equipment integration:Continuous mixing technologies require capital reconfiguration that conflicts with installed internal mixer depreciation schedules at mid-scale compounders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rubber Compound Market |
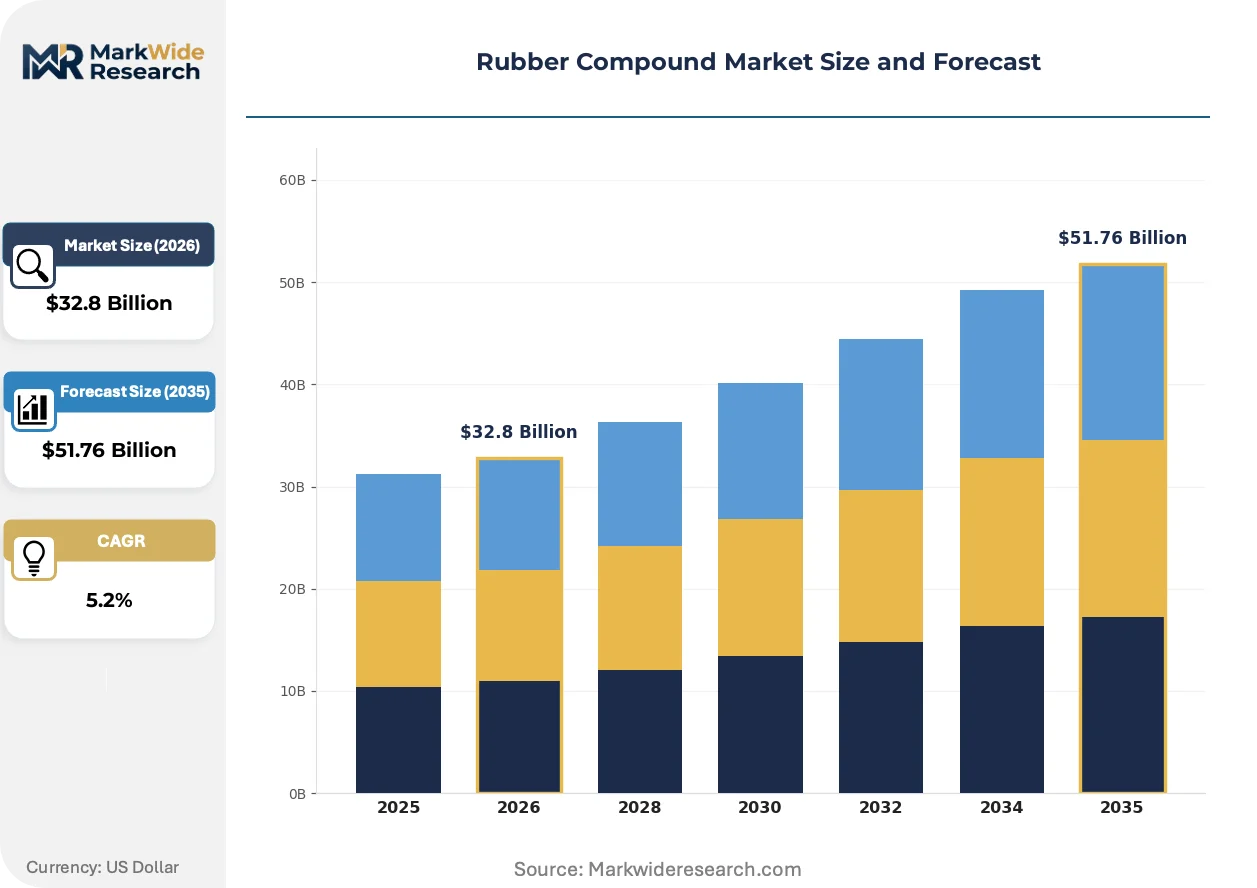
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $51.76 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Rubber, Synthetic Rubber, Silicone Rubber, Butyl Rubber Application: Tires, Seals, Gaskets, Conveyor Belts Grade: Standard Grade, High Performance, Industrial Grade, Aerospace Grade Form: Granules, Sheets, Liquid, Powder |
| Companies Covered | Kumho Petrochemical, Bridgestone, LANXESS AG, JSR Corporation, ContiTech AG, Goodyear Tire and Rubber Company, Sinopec, Zeon Corporation, ExxonMobil Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rubber Compound Market Emerging Trajectories
Material science advances and regulatory chemistry disclosure mandates are converging to reshape how rubber compounds are formulated, tested, and qualified for end-use applications across mobility and industrial segments.
High-consistency silicone rubber is supplanting ethylene-propylene-diene monomer in electric vehicle battery module gaskets. Automotive OEMs specify platinum-cured silicone for its compression set resistance across thermal cycling regimes. Tier-one suppliers are consolidating specification approvals around three to five qualified silicone compounders, compressing vendor bases for thermal interface materials.
China's GB standards for tire rolling resistance and wet grip are tightening compound disclosure protocols. SAMR enforcement requires full formulation documentation for imported tires, pushing foreign manufacturers toward localized mixing partnerships. European compounders with established China facilities are capturing specification lock-in from multinationals seeking compliance pathway certainty.
Direct procurement from compounders is displacing distributor intermediation among large tire manufacturers. Bridgestone and Continental are establishing long-term offtake agreements with synthetic rubber producers, bypassing merchant market exposure. This concentration is most visible in Germany and Japan, where automotive OEMs specify approved compounder lists that exclude non-contracted suppliers from bidding.
Rubber Compound Market Segmentation
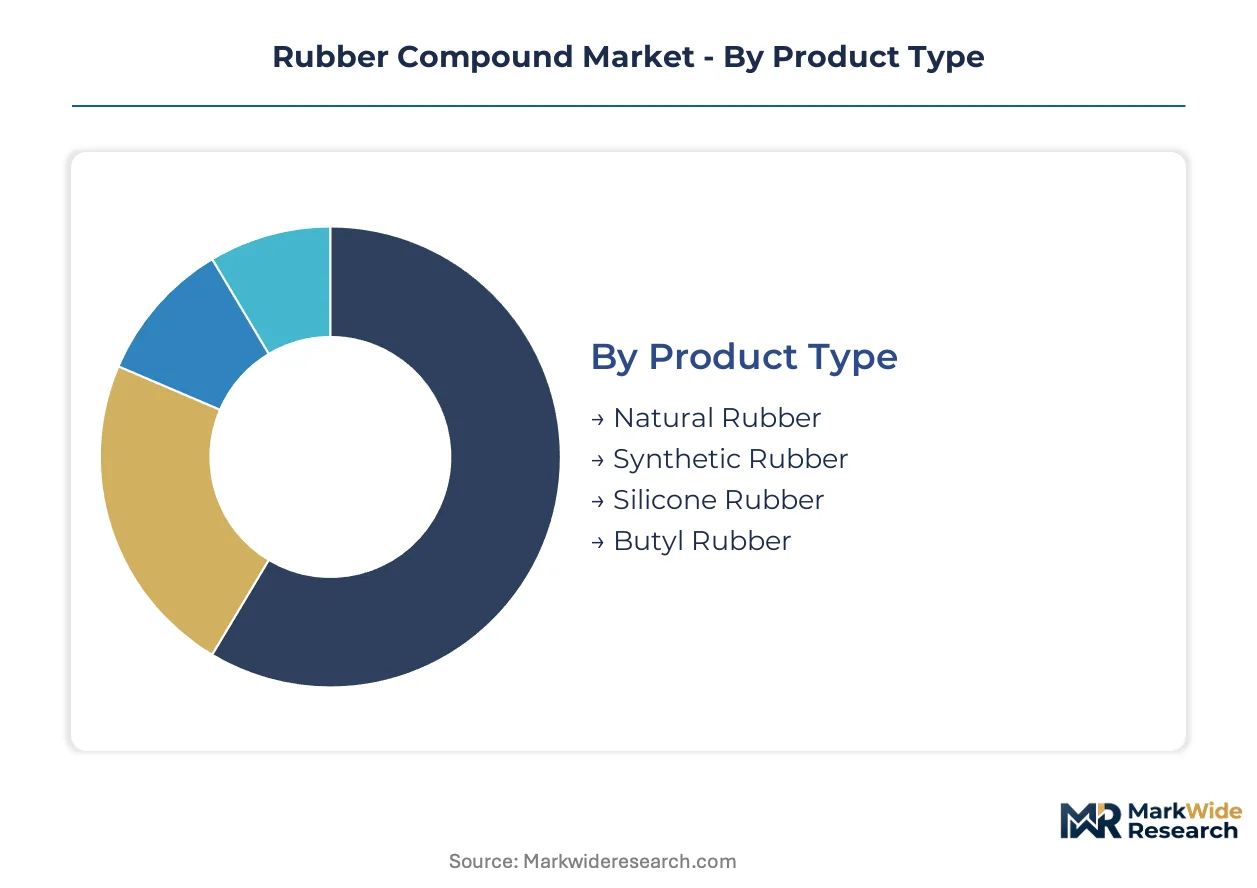
Segmentation in rubber compounds determines formulation priorities, regulatory compliance pathways, and margin capture potential across divergent end-use requirements. Product chemistry, application performance thresholds, and processing form factors each create distinct competitive arenas with unique supplier qualification barriers.
Product Type:
Substitution pressure from advanced elastomers and bio-based alternatives is fragmenting demand across traditional petrochemical-derived categories, with sustainability mandates accelerating displacement timelines for certain formulations.
- Natural Rubber:Isoprene-based polymer harvested from Hevea brasiliensis plantations dominates heavy-duty tire treads and truck tire sidewalls. Demand concentrates in Thai and Indonesian processing facilities serving Southeast Asian tire manufacturing clusters, where rolling resistance specifications under China's GB standards favor its low hysteresis properties.
- Synthetic Rubber:Styrene-butadiene and polybutadiene formulations engineered through solution or emulsion polymerization deliver consistent quality for passenger vehicle tires. Procurement volumes are scaling fastest in India near Chennai assembly plants incentivized under the PLI scheme for electric vehicle localization.
- Silicone Rubber:Siloxane backbone elastomers withstand temperature extremes from minus forty to two hundred degrees Celsius in battery thermal management systems.
- Butyl Rubber:Isobutylene-isoprene copolymer provides impermeability for tire inner liners and pharmaceutical stoppers.
Natural rubber retains volume leadership; silicone rubber holds the steepest expansion curve.
Application:
Performance certification requirements and OEM specification lock-in create divergent margin structures across end-use segments, with mobility applications commanding the most stringent qualification protocols.
- Tires:Formulated tread, sidewall, and inner liner compounds must satisfy rolling resistance and wet grip mandates under China's SAMR enforcement and Europe's REACH substance registration. Solution-polymerized styrene-butadiene grades are displacing emulsion variants in premium tire lines where wet-grip performance differentiates brand positioning.
- Seals:Compression-molded O-rings and gaskets for automotive under-the-hood applications require heat-aging resistance that platinum-cured silicone formulations deliver. Electric vehicle battery pack sealing specifications are consolidating procurement around three to five qualified compounders with proven thermal cycling performance.
- Gaskets:Sheet and molded flange seals for industrial process equipment face fluorocarbon substitution in chemical exposure environments.
- Conveyor Belts:Abrasion-resistant covers and carcass compounds for mining and bulk material handling prioritize tear strength over temperature performance.
Tire applications retain volume leadership; battery sealing systems hold the steepest expansion curve.
Grade:
Certification intensity and testing burden escalate with performance tier, concentrating premium supply bases and sustaining pricing power for qualified compounders.
- Standard Grade:General-purpose formulations for consumer goods and industrial matting balance cost against baseline mechanical properties. Procurement concentrates in China and India where carbon black reinforcement and aromatic process oils keep compound economics competitive for price-sensitive applications.
- High Performance:Automotive under-the-hood and dynamic sealing specifications demand sustained elasticity across temperature and chemical exposure regimes. LANXESS AG and specialty compounders capture margin premiums through proprietary filler dispersion and vulcanization kinetics expertise.
- Industrial Grade:Mining, construction, and agricultural equipment compounds prioritize abrasion resistance and cut-and-chip performance.
- Aerospace Grade:Nitrile and fluorocarbon formulations for fuel system and hydraulic sealing require FAA and EASA qualification protocols extending eighteen to thirty-six months.
Standard grade retains volume leadership; high performance holds the steepest expansion curve.
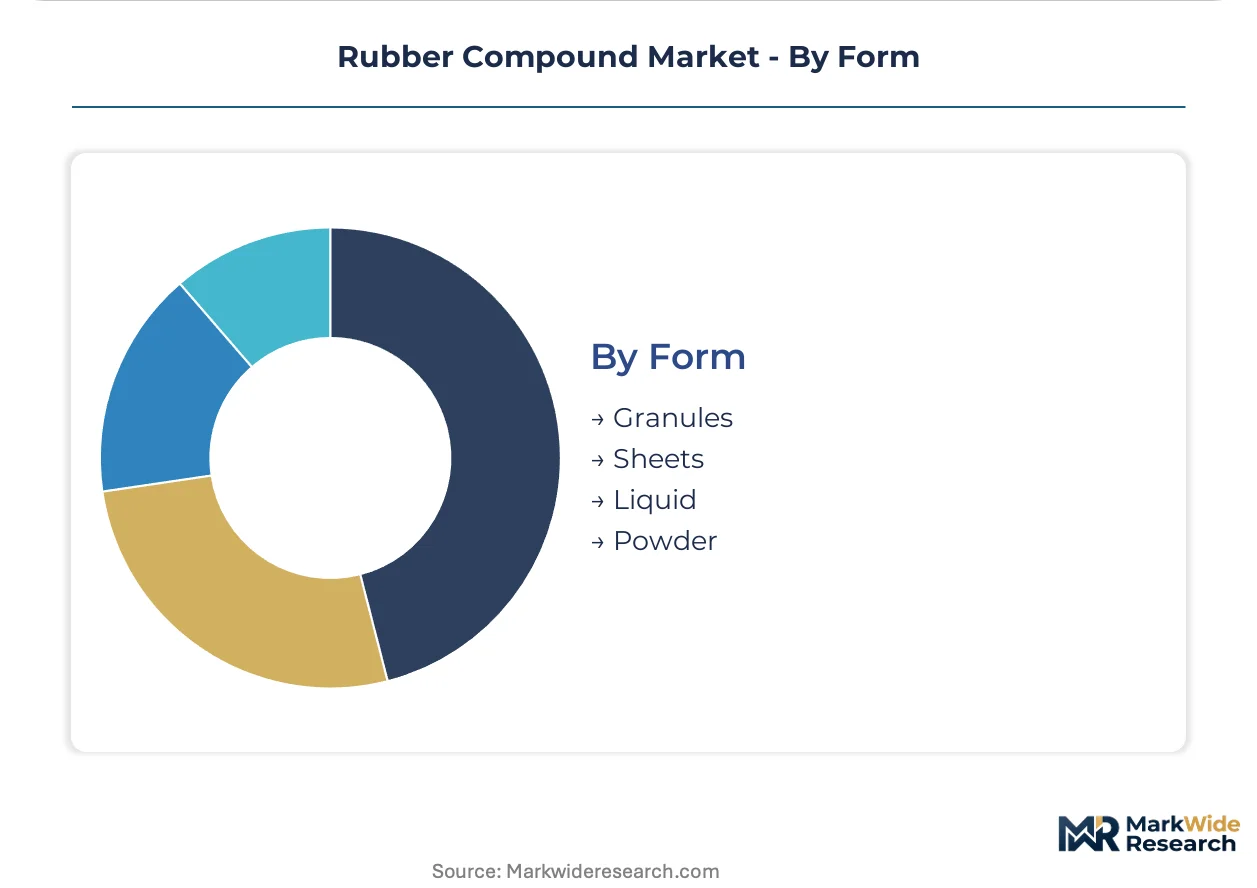
Form:
Processing economics and equipment compatibility shape form factor selection, with continuous mixing technologies favoring certain physical presentations over legacy mill processing.
- Granules:Free-flowing pelletized compound enables automated weighing and feeding in high-volume tire manufacturing. Thailand and Indonesia tire plants are standardizing on granule form to minimize dust exposure and accelerate batch cycle times in internal mixing operations.
- Sheets:Calendered slabs and strip stock support die-cutting and compression molding of gaskets and seals. Automotive tier-one suppliers in Germany and Japan specify sheet form for just-in-time delivery to minimize compound aging and scorch risk.
- Liquid:Two-part pourable silicone systems enable liquid injection molding of complex battery module gaskets.
- Powder:Micronized compound supports specialized adhesive and coating applications.
Granules retain volume leadership; liquid form holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: Southeast Asian tire manufacturers prioritize natural rubber for rolling resistance compliance, while European and North American compounders emphasize heat-resistant silicone formulations for electric vehicle thermal management systems.
Thailand
Tire production capacity expansion drives solution-polymerized styrene-butadiene rubber procurement volumes. The country's Board of Investment offers tax incentives for advanced rubber processing facilities. Eastern Economic Corridor industrial zones near Rayong host mixing operations supplying Japanese and Korean tire OEMs.
Germany
Automotive OEM specification lock-in concentrates demand for platinum-cured silicone compounds in battery sealing applications. ECHA REACH substance registration mandates full chemical disclosure for imported rubber additives. Ruhr Valley chemical parks host LANXESS AG compounding facilities serving Continental and Volkswagen supply chains.
China
SAMR enforcement of GB standards for tire rolling resistance and wet grip tightens formulation documentation requirements. The country's dual carbon goals accelerate solvent-free mixing technology adoption. Shandong Province tire manufacturing clusters scale solution-polymerized styrene-butadiene rubber consumption for export-compliant production.
United States
EPA volatile organic compound regulations push compounders toward aromatic process oil substitution in internal mixing operations. The country's IRA clean vehicle incentives expand electric vehicle platform demand for thermal management elastomers. Southeast automotive assembly corridors near Tennessee and Kentucky draw mixing facility investments from tier-one suppliers.
India
PLI scheme incentives for electric vehicle component manufacturing localize procurement for battery module gaskets and seals. BIS standards for automotive rubber components tighten quality certification protocols. Tamil Nadu industrial corridors near Chennai host mixing operations serving Hyundai and Tata Motors assembly plants.
Rubber Compound Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-layer competitive structure. Fully integrated petrochemical producers with captive synthetic rubber capacity command feedstock cost stability, while specialty compounders compete on formulation expertise and qualification speed. Three archetypes dominate: backward-integrated petrochemical majors, high-performance elastomer specialists, and regional tire-grade compounders. Capacity expansion in Southeast Asia and strategic partnerships for electric vehicle thermal materials represent the dominant competitive vectors.
Among backward-integrated petrochemical majors, Kumho Petrochemical and Sinopec exemplify the archetype of upstream-controlled producers insulating margin pools from butadiene volatility. LANXESS AG occupies a position within the high-performance specialist tier, where temperature resistance and automotive under-the-hood specifications command premium positioning. These three entities represent distinct competitive approaches: captive monomer supply, state-backed scale, and formulation-driven differentiation.
| Leading Market Players |
|---|
| Kumho Petrochemical |
| Bridgestone |
| LANXESS AG |
| JSR Corporation |
| ContiTech AG |
| Goodyear Tire and Rubber Company |
| Sinopec |
| Zeon Corporation |
| ExxonMobil Chemical |
| Others |
Supply Flow & Price Mechanics
ECHA REACH substance registration gates both supplier qualification and price differentiation simultaneously, as compounders without pre-registered additive packages face exclusion from European tire manufacturer procurement lists while certified formulations command tiered premiums based on disclosure compliance depth.
Pricing Analysis
Long-term offtake agreements dominate procurement between synthetic rubber producers and tire OEMs, compressing spot market participation to marginal volume. Pricing stratifies across aerospace-grade, high-performance automotive, and standard tire-grade tiers, with certification intensity as the primary differentiation driver. Cost compression in standard-grade compounds is intensifying because carbon black reinforcement and aromatic process oils face substitution pressure from recycled fillers and solvent-free mixing mandates. Tier-one automotive suppliers exhibit lowest price sensitivity for battery thermal management silicones, while industrial matting buyers drive hardest bargain negotiations.
Supply Chain Analysis
Inventory buffers for butadiene monomer and carbon black filler extend lead times when naphtha-cracking economics swing or Chinese reinforcing filler clusters face logistics disruption. Supply concentrates in Thailand, Indonesia, and China for natural rubber processing and tire manufacturing feedstocks, while Germany and Japan anchor high-performance silicone compounding. Raw material dependencies rest on Hevea brasiliensis plantation output, styrene-butadiene monomer streams from petrochemical crackers, and pyrolysis-derived recycled carbon black emerging from circular economy pilots. Single-source vulnerability concentrates in Chinese carbon black production for consistent tensile strength performance. Distribution runs through direct procurement channels displacing distributor intermediation among large tire manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive electrification disrupts rubber compound specifications at unprecedented velocity, with thermal management system demands rewriting material science requirements and compressing supplier qualification timelines for silicone formulations.
For Market Incumbents: Fortify specification lock-in with automotive OEMs through accelerated platinum-cured silicone certification for battery module gaskets, while securing captive butadiene supply or long-term monomer offtake to defend margin pools against feedstock volatility. Threat of fluorocarbon substitution in aerospace sealing applications demands sustained R&D investment in temperature-extreme performance. Backward integration into styrene-butadiene rubber monomers insulates compounders from naphtha-cracking cycle swings. For New Entrants and Emerging Players: Anchor in India's PLI scheme corridors near Chennai and Pune, where electric vehicle component localization incentives create white-space demand for battery sealing compounds absent entrenched supplier relationships. Target recycled carbon black integration partnerships with pyrolysis operators to capture circular economy positioning ahead of regulatory mandates. Go-to-market angle should emphasize solvent-free mixing technology compliance for EPA-regulated automotive supply chains. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across high-performance silicone compounding as platinum-cured formulation expertise and thermal cycling qualification infrastructure become scarce capabilities. Long-term viability favors compounders with demonstrated OEM specification lock-in and geographic diversification across Southeast Asian tire manufacturing and European automotive thermal management clusters. Acquisition target archetype: mid-scale compounders with latent aerospace certification pathways and underutilized mixing capacity. Signal to watch: tier-one supplier consolidation around three to five qualified silicone compounders for battery sealing procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomers | Kumho Petrochemical's captive butadiene supply insulates styrene-butadiene margin pools from naphtha-cracking volatility. |
| Platinum-Cured Silicone Certification | Automotive OEM specification lock-in for battery thermal management compresses qualified supplier bases to three to five compounders. |
| Solvent-Free Mixing Technology Deployment | EPA volatile organic compound enforcement creates first-mover compliance advantage for internal mixing without aromatic process oils. |
| Recycled Carbon Black Integration | Pyrolysis-derived filler from end-of-life tires achieves performance parity in non-dynamic applications for circular economy positioning. |
| Southeast Asian Capacity Expansion | Thailand and Indonesia tire manufacturing clusters scale solution-polymerized styrene-butadiene procurement volumes for export-compliant production. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs and trade data, SEC and domestic exchange filings, ACC and Cefic industry reports, and regulatory disclosure databases including ECHA substance registrations and SAMR tire labeling enforcement records. Primary interviews engaged plant managers at compounding facilities, procurement leads at tire OEMs and automotive tier-one suppliers, distribution channel partners, and technical R&D directors specializing in vulcanization kinetics. Bottom-up demand modeling across end-use applications triangulates against top-down supply-side capacity assessments.
Segmentation dimensions modeled include product chemistry type, application performance threshold, certification grade tier, and processing form factor across the projection horizon. Analytical framework derives CAGRs from elasticity of substitution between natural and synthetic rubber formulations, electric vehicle platform penetration assumptions, and regional regulatory compliance cost differentials. Industry-specific forecast inputs incorporate butadiene monomer price volatility bands and silicone thermal cycling qualification timeline distributions.
Material uncertainties — butadiene feedstock cost swings, REACH substance registration scope expansions, and aerospace certification timeline extensions — sit outside the modeled envelope. Forecasts reflect assumptions around continued automotive electrification trajectory and Southeast Asian tire manufacturing capacity scaling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Tire Reinforcement Materials Market
Rubber
Global Rubber Market
Rubber
Butyl Reclaimed Rubber Market
Rubber
Rubber Gloves Market
Rubber
Silica for S-SBR Market
Rubber
Metallurgical Rubber Roller Market
Rubber
Rubber Valve Stem Market
Rubber
Rubber Bulbs Market
Rubber
Rubber Masterbatch Market
Rubber
Rubber Foam Materials Market
Rubber
Liquid Polybutadiene Market
Rubber
Isobutylene Market
Rubber
Rubber Tapes Market
Rubber
Global Cast Elastomers Market
Rubber
Tire Recycling Downstream Products Market
Rubber
Acrylic Rubber Market