
 RTD/High Strength Premixes Market | 2026-2036
RTD/High Strength Premixes Market Size, Share, and Industry Trends Forecast 2026-2036
RTD/High Strength Premixes Market Analytics
Asset-light contract manufacturing and third-party co-packing arrangements is reshaping competitive dynamics, allowing new entrants to scale without distillery investments. Diageo PLC leverages its global distribution network to dominate premium flavored spirits. Brown-Forman Corporation anchors its position through sustained brand equity in whiskey-based premixes. Bacardi & Company Limited specializes in rum-derived functional cocktails for tropical markets.
RTD/High Strength Premixes are commercially prepared beverages combining distilled spirits or malt bases with flavorings, sweeteners, and functional additives at alcohol concentrations typically exceeding 5% ABV, manufactured through controlled blending, pasteurization, and cold-fill or hot-fill processes designed for shelf-stable distribution. Their primary purpose is delivering bar-quality cocktail experiences without preparation equipment or trained bartenders. Flavored Spirits commands the largest revenue pool due to established consumer familiarity and higher per-unit pricing, while Functional Cocktails represents the fastest-expanding category as adaptogenic and nootropic ingredients attract wellness-oriented buyers. Protein Beverages occupies a niche position targeting post-workout recovery occasions with lower alcohol or alcohol-free variants.
The US Alcohol and Tobacco Tax and Trade Bureau enforces strict formula approval and label accuracy requirements that constrain formulation speed but protect established producers with compliance infrastructure. The EU Spirits Regulation and REACH chemical standards govern additive permissibility and labeling claims across member states, creating divergent product specifications. Japan's National Tax Agency maintains distinct tax classifications based on alcohol base and dilution ratios that directly affect retail pricing tiers. Stakeholders must monitor evolving low-alcohol thresholds and sugar taxation proposals that could force portfolio restructuring ahead of regulatory implementation.
Market Dynamics
Asset-light contract manufacturing is virtualizing production economics across the RTD/High Strength Premixes landscape, enabling new entrants to bypass distillery capital requirements while established players redeploy capital toward brand building and distribution density.
Growth Catalysts
- Urban Convenience Culture:Young professionals in São Paulo, Tokyo, and New York City drive on-the-go consumption of bar-quality cocktails without preparation infrastructure. Metropolitan density supports impulse purchase patterns and premium pricing tolerance.
- TTB Formula Modernization:The US Alcohol and Tobacco Tax and Trade Bureau streamlined approval pathways for novel flavor compounds, accelerating product pipeline velocity for compliant manufacturers with established regulatory infrastructure.
- Wellness-Functional Convergence:Adaptogenic ingredient integration attracts health-conscious buyers seeking alcohol-inclusive social rituals without next-day impairment, expanding occasion boundaries beyond traditional drinking moments.
Market Restraints
- Input Cost Volatility:Malt base and natural flavor extract prices fluctuate with agricultural commodity cycles, compressing gross margins for producers lacking long-term supply contracts or captive sourcing arrangements.
- Regulatory Fragmentation:Divergent additive permissibility standards between FDA, EFSA, and Japan's National Tax Agency force portfolio customization that erodes scale economies and complicates cross-border distribution.
- Substitution Pressure:Low-alcohol and alcohol-free functional beverages capture wellness-oriented occasions, constraining volume expansion in health-conscious demographic segments.
Strategic Opportunities
- Underpenetrated Secondary Cities:Brazilian interior markets beyond Rio de Janeiro and São Paulo exhibit rising disposable incomes with limited premium RTD availability, creating first-mover advantages for distribution-buildout investments.
- Direct-to-Consumer Channel Development:E-commerce platforms and subscription models bypass traditional three-tier distribution constraints, enabling margin capture and customer data accumulation previously unavailable to alcohol producers.
- EU Green Deal Alignment:Sustainable packaging mandates and carbon footprint disclosure requirements favor producers with early investment in recyclable formats and supply chain transparency, creating differentiation vectors.
Industry Challenges
- Flavor Chemist Talent Scarcity:Formulation expertise combining spirits chemistry with functional ingredient stability remains concentrated among a small specialist workforce, constraining innovation pipeline throughput.
- Co-Packer Quality Consistency:Reliance on third-party manufacturing introduces batch variation risks that threaten brand equity, requiring intensive audit protocols and contractual penalty structures.
- Legacy System Integration:Established producers face friction connecting modern demand-sensing analytics to outdated ERP infrastructure, delaying real-time inventory optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RTD/High Strength Premixes Market |
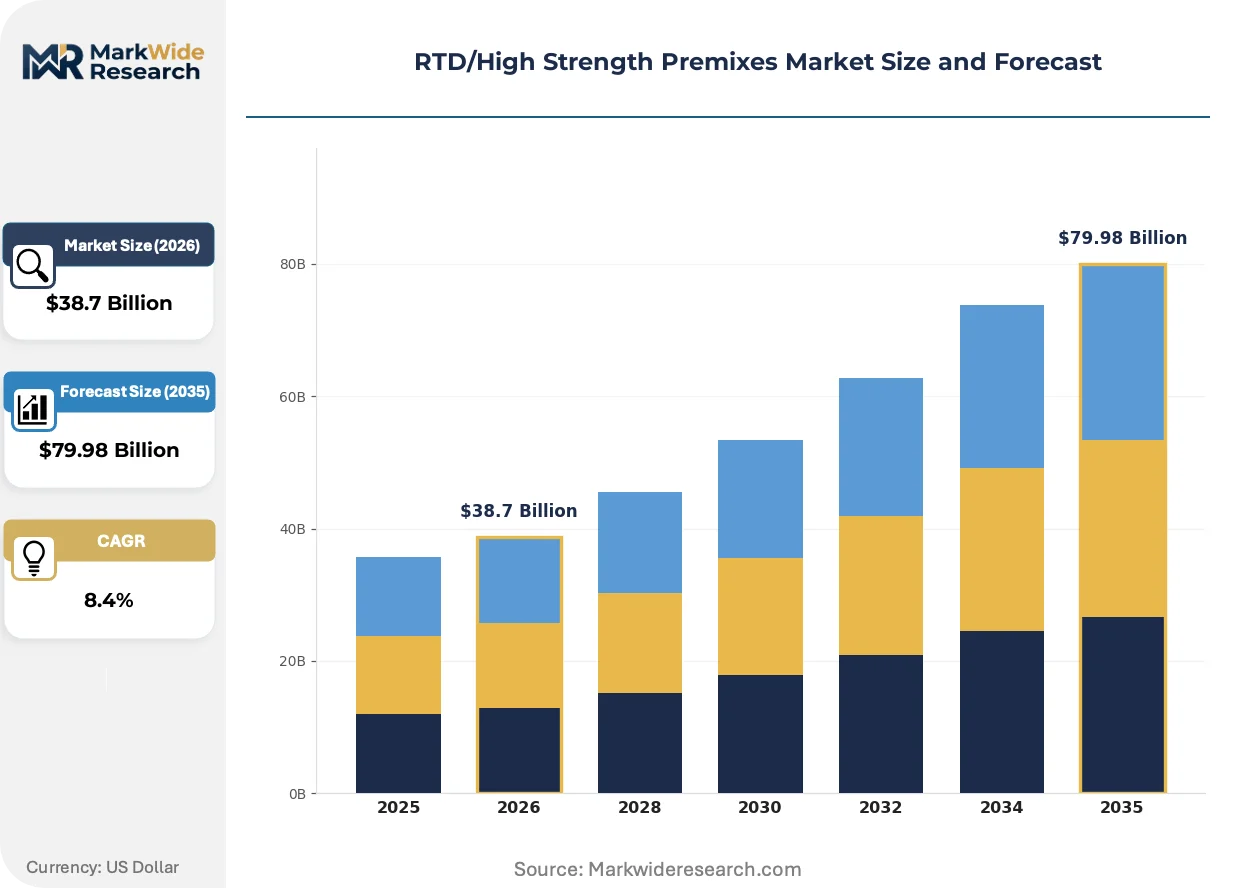
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Energy Drinks, Flavored Spirits, Protein Beverages, Functional Cocktails End User: Retail Consumers, Fitness Enthusiasts, Event Attendees, Bartenders Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Specialty Shops Packaging Type: Cans, Bottles, Tetra Packs, Kegs |
| Companies Covered | Beam Suntory Inc., Campari Group, Anheuser-Busch InBev SA/NV, Jose Cuervo, Diageo PLC, Asahi Group Holdings Ltd., Brown-Forman Corporation, Suntory Holdings, Bacardi & Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RTD/High Strength Premixes Market Evolving Landscape
Digital formulation platforms and precision fermentation are compressing development timelines while regulatory disclosure mandates reshape competitive transparency requirements across the RTD/High Strength Premixes value chain.
Precision fermentation technology is virtualizing flavor compound production, enabling biosynthesis of rare botanical extracts without agricultural cultivation constraints. Mid-sized premix manufacturers in California and the Netherlands adopt these platforms to reduce raw material cost exposure and secure supply continuity. The technology is virtualizing traditional extraction economics, eroding the premium pricing power of terroir-dependent ingredient suppliers.
The EU Spirits Regulation disclosure amendments now mandate granular additive labeling and nutritional declaration, eliminating formulation opacity as a competitive moat. Producers must reformulate or disclose proprietary compound ratios, accelerating convergence toward clean-label ingredient portfolios. Premium flavored spirits segments in Germany and France face the steepest compliance costs, driving consolidation among smaller regional brands lacking regulatory affairs capacity.
Buyer concentration among specialized beverage distributors is compressing switching flexibility and amplifying slotting fee burdens for new market entrants. Independent craft premix brands in Texas and Florida increasingly bypass traditional wholesalers through licensed direct shipping arrangements and owned retail tasting rooms. This channel fragmentation is most visible in states with permissive direct shipment statutes, where producer margins expand fifteen to twenty percentage points versus conventional distribution.
RTD/High Strength Premixes Market Segmentation
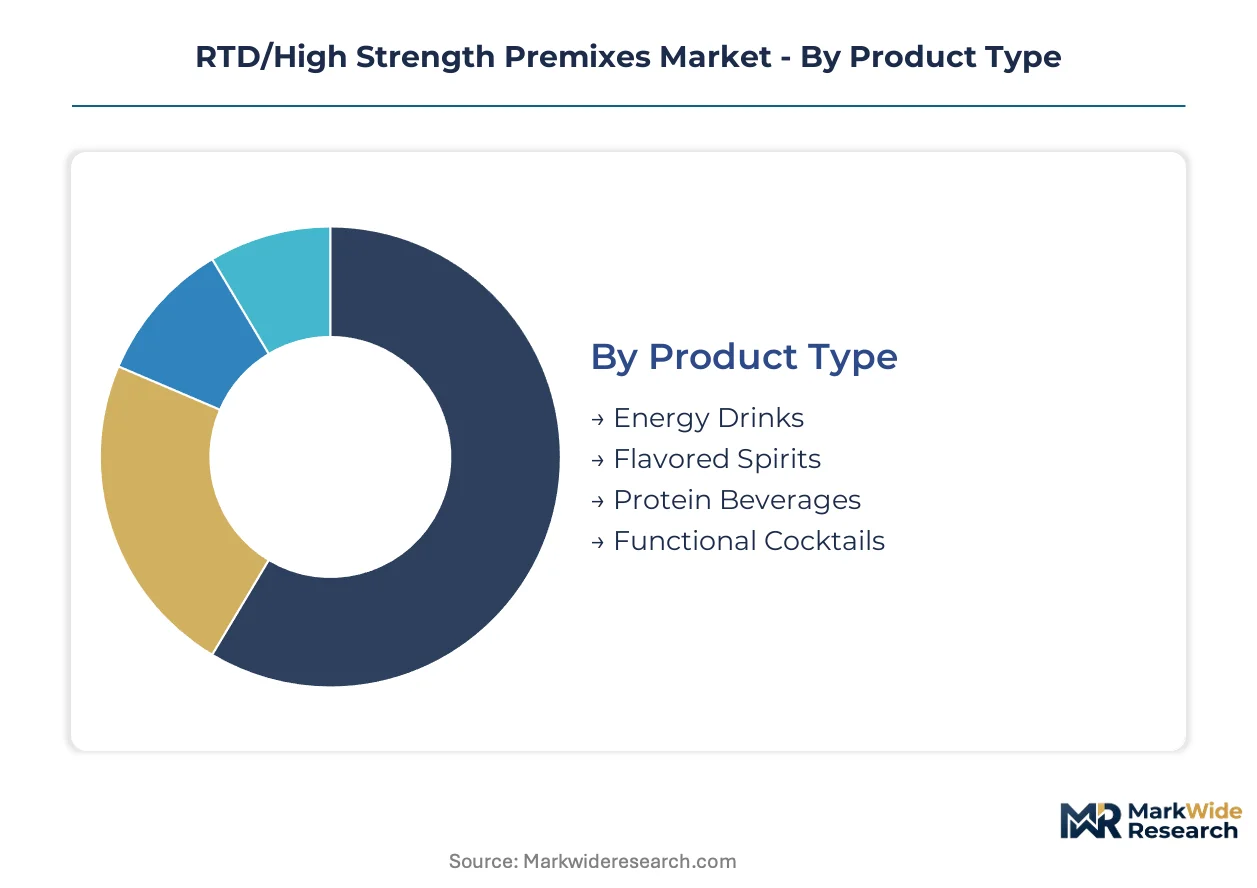
RTD/High Strength Premixes segmentation reveals distinct service and replenishment rhythms across product categories. Each dimension carries unique logistics footprints and margin structures that shape portfolio prioritization decisions.
Product Type:
After-sales service intensity varies dramatically across product types, with functional formulations demanding formulation stability monitoring and flavor-spirits requiring brand experience support.
- Flavored Spirits:Distilled spirit bases blended with natural or artificial flavor compounds at alcohol concentrations typically exceeding 5% ABV, packaged for immediate consumption without dilution. Demand concentrates in metropolitan United States and Brazil where premium cocktail culture supports higher per-unit pricing. Established consumer familiarity sustains volume leadership despite slower innovation velocity.
- Functional Cocktails:Alcohol-inclusive beverages incorporating adaptogenic, nootropic, or botanical ingredients targeting wellness occasions. Young urban professionals in Tokyo and São Paulo drive adoption as social drinking rituals converge with health consciousness. Regulatory complexity around functional claims constrains formulation speed but rewards compliant first-movers.
- Energy Drinks:Caffeine and taurine-fortified alcoholic beverages targeting nightlife and extended social occasions.
- Protein Beverages:Lower-alcohol or alcohol-free variants with protein fortification for post-workout recovery positioning.
By volume, Flavored Spirits leads. By growth pace, Functional Cocktails is ahead.
End User:
Cost tier stratification separates mass-market retail from premium hospitality channels, with fitness-oriented buyers commanding specialized formulation premiums.
- Retail Consumers:Individual purchasers seeking convenience-oriented alcoholic beverages for home consumption or social gatherings. Supermarket and convenience store channels dominate fulfillment, with impulse purchase patterns driving single-serve format preference. Price sensitivity intensifies during economic contraction periods.
- Fitness Enthusiasts:Health-conscious buyers prioritizing protein-fortified or low-calorie variants aligned with training regimens. Direct-to-consumer subscription models capture this segment with fifteen to twenty percentage point margin advantages over conventional distribution.
- Event Attendees:Bulk purchasers for festivals, sporting events, and corporate gatherings requiring efficient large-format dispensing.
- Bartenders:Professional mixologists utilizing premix bases for speed-of-service consistency in high-volume venues.
Retail Consumers generate the largest revenue pool. Fitness Enthusiasts exhibit the steepest expansion trajectory.
Distribution Channel:
Geographic concentration of channel power favors metropolitan clusters where three-tier system constraints are weakest or direct shipment statutes exist.
- Convenience Stores:Impulse-dominant channel capturing on-the-go consumption in urban United States and Japanese metropolitan corridors. Cold-chain infrastructure requirements limit functional cocktail placement due to shelf-stable formulation demands.
- Online Retail:E-commerce platforms and subscription services bypassing traditional wholesale intermediaries. Texas and Florida permit licensed direct shipping, enabling margin expansion and customer data accumulation unavailable through conventional routes.
- Supermarkets:Mass-market volume channel with slotting fee burdens compressing new entrant economics.
- Specialty Shops:Curated retail environments targeting premium and craft positioning with educated staff support.
Convenience Stores move the highest unit volumes. Online Retail is climbing the fastest.
Packaging Type:
Supply concentration among aluminum and glass converters shapes procurement leverage, with sustainable format innovation disrupting established material economics.
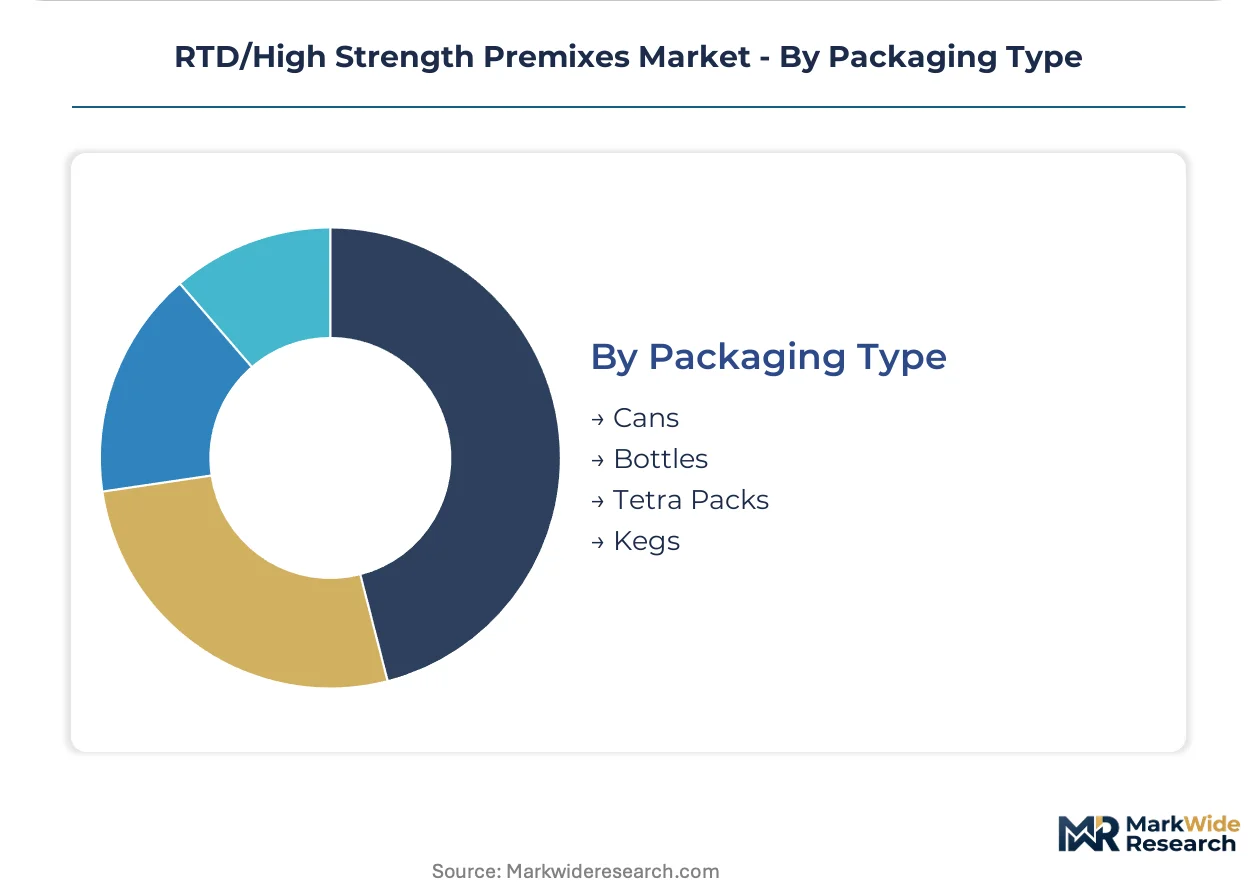
- Cans:Aluminum single-serve containers dominating RTD distribution for portability, chill speed, and recycling infrastructure compatibility. EU Green Deal packaging mandates favor early adopters of recycled content and carbon disclosure transparency.
- Bottles:Glass and PET formats supporting premium positioning and larger volume offerings. Weight and fragility constrain direct-to-consumer shipping economics.
- Tetra Packs:Aseptic carton formats for ambient-stable distribution in emerging market expansion scenarios.
- Kegs:Stainless steel returnable formats for on-premise dispensing at events and hospitality venues.
Cans dominate production volumes. Bottles retain premium positioning power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power in Japan exceeds Brazil by thirty to forty percentage points per equivalent ABV unit, reflecting divergent tax structures and urban income density. The United States captures the largest absolute revenue pool despite lower per-unit margins. Regulatory fragmentation across these three markets forces portfolio customization that erodes cross-border scale economies.
United States
Young urban professionals in New York City and Los Angeles drive on-the-go consumption of convenience-oriented alcoholic beverages. The TTB enforces strict formula approval and label accuracy requirements that constrain formulation speed. California-based contract manufacturers serve as production hubs for emerging brands lacking distillery capital.
Brazil
Rising disposable incomes in São Paulo and Rio de Janeiro sustain premium cocktail culture with strong impulse purchase patterns. ANVISA governs additive permissibility and nutritional labeling claims with standards diverging from FDA frameworks. Brazilian interior markets beyond the coastal metros exhibit limited premium RTD availability, creating first-mover distribution opportunities.
Japan
Metropolitan Tokyo consumers exhibit the highest per-capita spending on functional cocktail variants with adaptogenic ingredients. The National Tax Agency maintains distinct tax classifications based on alcohol base and dilution ratios that directly affect retail pricing tiers. Osaka-based distributors concentrate channel power, compressing switching flexibility for new market entrants.
Germany
Wellness-oriented buyers in Berlin and Munich expand demand for low-sugar, clean-label premix formulations. The EU Spirits Regulation and REACH chemical standards govern additive permissibility with disclosure mandates eliminating formulation opacity. Bavarian specialty retailers curate premium positioning with educated staff support unavailable in mass-market channels.
United Kingdom
London's hospitality sector drives demand for speed-of-service premix bases in high-volume venues. EFSA evaluates functional ingredient claims with standards that constrain adaptogenic formulation speed. Direct-to-consumer subscription models capture fifteen to twenty percentage point margin advantages over conventional three-tier distribution in permissive regulatory environments.
RTD/High Strength Premixes Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with formulation and flavor chemistry capabilities. The vendor base concentrates among multinational beverage conglomerates with established regulatory infrastructure and captive distribution networks. Three strategic archetypes dominate: global spirits houses with premix line extensions, contract manufacturing platforms enabling asset-light scaling, and regional craft specialists leveraging direct shipment statutes. Competitive moves center on M&A activity targeting flavor technology assets and strategic partnerships with precision fermentation platforms.
Within the global spirits house tier, Diageo PLC and Bacardi & Company Limited exemplify platform integrators with extensive distribution density. Brown-Forman Corporation occupies a position among whiskey-focused specialists with sustained brand equity in brown-spirit premixes. Beam Suntory Inc. and Asahi Group Holdings Ltd. represent Asia-Pacific headquartered conglomerates with cross-regional portfolio breadth. Campari Group and Anheuser-Busch InBev SA/NV anchor the European and multinational brewing vectors respectively, while Jose Cuervo and Suntory Holdings exemplify tequila and Japanese spirits heritage positioning.
| Leading Market Players |
|---|
| Beam Suntory Inc. |
| Campari Group |
| Anheuser-Busch InBev SA/NV |
| Jose Cuervo |
| Diageo PLC |
| Asahi Group Holdings Ltd. |
| Brown-Forman Corporation |
| Suntory Holdings |
| Bacardi & Company Limited |
| Others |
Value Network & Pricing Analysis
Tariff exposure on aluminum can imports from China and Mexico determines both three-tier pricing spreads across premium, standard, and economy levels and supply chain shape, as producers dual-source packaging to avoid cost spikes that would compress margins in the mass-market tier.
Pricing Analysis
Retail consumers anchor pricing stratification across premium, standard, and economy tiers, with flavor complexity and ABV concentration driving differentiation. Price differentiation separates craft-positioned functional cocktails from commodity malt-based offerings. Pricing pressure stems from input cost volatility in natural extracts and malt bases, squeezing mid-tier producers lacking long-term contracts. Fitness enthusiasts exhibit lowest price sensitivity due to subscription model capture, while mass retail buyers face heightened elasticity during economic contraction.
Supply Chain Analysis
Extended payment terms from Brazilian and Japanese distributors strain working capital for contract manufacturers serving emerging brands. Supply concentrates in the United States, Brazil, and Japan for finished goods, with raw material dependencies on Chinese aluminum, Mexican agave derivatives, and Indian botanical extracts. Single-source vulnerability in precision fermentation platforms threatens flavor compound continuity. Distribution runs through three-tier wholesale networks in the United States and concentrated distributor oligopolies in Osaka and São Paulo.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The RTD/High Strength Premixes market functions as a service-attach opportunity where formulation consulting and subscription replenishment layers expand faster than base product volume, rewarding producers who bundle recurring revenue with hardware sales.
For Market Incumbents: Entrench regulatory affairs capacity as a defensive moat against TTB formula modernization delays that disadvantage smaller competitors. Deepen captive sourcing of precision fermentation-derived flavor compounds to secure supply continuity against agricultural commodity swings. Acquire contract manufacturing platforms in California and the Netherlands to control production capacity for emerging brand clients. For New Entrants and Emerging Players: Establish a beachhead in Brazilian interior markets beyond Rio de Janeiro and São Paulo where premium RTD availability remains sparse. Target fitness enthusiasts through direct-to-consumer subscription models capturing fifteen to twenty percentage point margin advantages unavailable through conventional distribution. Leverage licensed direct shipping statutes in Texas and Florida to bypass slotting fee burdens. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors flavor technology specialists with regulatory compliance infrastructure. Long-term viability hinges on portfolio diversification across functional and traditional segments. Acquire targets with established TTB formula libraries and EU REACH compliance capabilities. Watch precision fermentation platform partnerships as the signal for innovation pipeline velocity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Channel Launch | Bypasses three-tier distribution constraints in Texas and Florida, expanding margins. |
| Precision Fermentation Partnership | Secures biosynthesized botanical supply independent of agricultural cultivation cycles. |
| Regulatory Compliance Investment | Accelerates TTB formula approval velocity for novel adaptogenic ingredient combinations. |
| Sustainable Packaging Transition | Aligns with EU Green Deal mandates favoring recycled aluminum and carbon disclosure. |
| Functional Ingredient R&D Expansion | Captures wellness-oriented buyers seeking alcohol-inclusive rituals without next-day impairment. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with brand managers at multinational spirits houses, category buyers at convenience store chains, formulation chemists at contract manufacturers, and regulatory affairs directors navigating TTB and EU Spirits Regulation frameworks. Secondary validation drew from TTB formula approval databases, EU REACH chemical registry filings, customs import records for aluminum and glass packaging, and Nielsen retail audit data. Bottom-up volume estimates triangulated against top-down revenue benchmarks.
Calibration against historical volume trajectories and elasticity responses anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end user archetype, distribution channel, and packaging format, with regional regulatory clusters as an industry-specific overlay. CAGRs were derived from fitted growth curves applied to baseline consumption data. Forecast inputs incorporated urbanization rates in São Paulo and Tokyo, and TTB approval pipeline velocity.
Stress conditions across malt commodity price bands, aluminum tariff schedules, and functional ingredient regulatory thresholds were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about consumer occasion migration and distributor consolidation trajectories. Macroeconomic contraction, sugar taxation implementation, or breakthroughs in alcohol-free functional substitutes would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Drum to Hopper Blends Premix Market
Ingredients
North America and Europe Coconut Derivatives Market
Ingredients
Sodium Alginate Market
Ingredients
Global Malt and Malt Extracts Market
Ingredients
Lime Seed Oils Market
Ingredients
Ingredients Market
Ingredients
United States Protein Market
Ingredients
Mineral Premix Market
Ingredients
Fats and Oils Market
Ingredients
Liquid Egg Market
Ingredients
Global Alpha-Lactalbumin Market
Ingredients
Guar Gum Market
Ingredients
Protein Ingredients Market
Ingredients
Zero-Calorie Oil Market
Ingredients
Cocoa Based Polyphenols Market
Ingredients
Egg Membrane Powder Market