
 Ready-To-Drink (RTD) Tea Market | 2026-2036
Ready-To-Drink (RTD) Tea Market Size, Share, and Industry Trends Forecast 2026-2036
Ready-To-Drink (RTD) Tea Market Analysis
A capital-intensity divergence between bottling-network scale and cold-brew processing capability is rotating competitive advantage toward firms that own both assets. The Coca-Cola Company leverages its global fountain and bottling infrastructure to secure shelf space in mass retail. PepsiCo anchors its position through Gatorade-aligned distribution muscle in convenience channels. Ito En specializes in authentic Japanese green tea extraction methods that command premium placement in health shops.
Ready-to-drink tea comprises brewed, blended, or extracted tea formulations that are pasteurized or cold-filled into shelf-stable or refrigerated packaging, typically containing tea solids, water, and optional sweeteners or flavoring agents, designed for immediate consumption without preparation. Green tea variants lead product type momentum as antioxidant positioning attracts functional-beverage buyers, while black tea occupies mature volume pools in traditional markets. Online retail represents the fastest-expanding distribution channel as direct-to-consumer subscriptions bypass conventional grocery slotting fees.
The FDA enforces Nutrition Facts labeling and health claim substantiation for RTD tea sold in the United States, while China's SAMR applies GB standards for sugar content disclosures and additive permissions. EFSA's health claim assessments in Europe constrain functional positioning unless clinical evidence meets regulatory thresholds. Stakeholders must monitor evolving sugar-tax legislation across multiple jurisdictions and decide whether to reformulate proactively or absorb compliance costs.
Market Dynamics
Health-conscious consumption patterns are restructuring RTD tea formulation priorities as unsweetened and functional variants displace traditional sweetened formats in corporate and convenience channels.
Growth Catalysts
- Sugar Tax Legislation:Jurisdictions including the United Kingdom and South Africa impose levy structures on sweetened beverages, accelerating reformulation toward zero-sugar green tea lines that bypass tariff exposure.
- Cold-Brew Extraction Methods:Low-temperature brewing protocols preserve catechin integrity and reduce astringency, enabling premium positioning in health-focused retail formats.
- China's Tier-One Urban Clusters:Shanghai, Beijing, and Guangzhou exhibit concentrated convenience-store penetration that supports grab-and-go consumption velocity for single-serve bottles.
Market Restraints
- Tea Leaf Input Volatility:Assam and Kenyan auction prices fluctuate with monsoon patterns, compressing margin predictability for black tea-dependent portfolios.
- Refrigerated Supply Concentration:Cold-chain infrastructure deficits in India's secondary cities limit chilled RTD distribution to urban corridors.
- Functional Claim Substantiation:EFSA's health claim assessments in Europe demand clinical evidence thresholds that constrain antioxidant positioning without prohibitively expensive trials.
Strategic Opportunities
- Direct-to-Consumer Subscriptions:Online retail bypasses conventional grocery slotting fees and captures repeat-purchase data for flavor personalization.
- India's Urban Metro Expansion:Mumbai, Delhi, and Bangalore present underpenetrated convenience-channel whitespace as modern retail formats proliferate.
- China's Dual Carbon Goals:MEE sustainability mandates incentivize lightweight packaging innovation and renewable energy adoption in bottling facilities.
Industry Challenges
- Tea Sommelier Talent Scarcity:Blending expertise for authentic extraction profiles remains concentrated in Japan and Taiwan, limiting quality replication elsewhere.
- Multi-Jurisdiction Label Compliance:Simultaneous adherence to FDA Nutrition Facts rules, China's GB sugar disclosure standards, and evolving EU front-of-pack schemes fragments packaging workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ready-To-Drink (RTD) Tea Market |
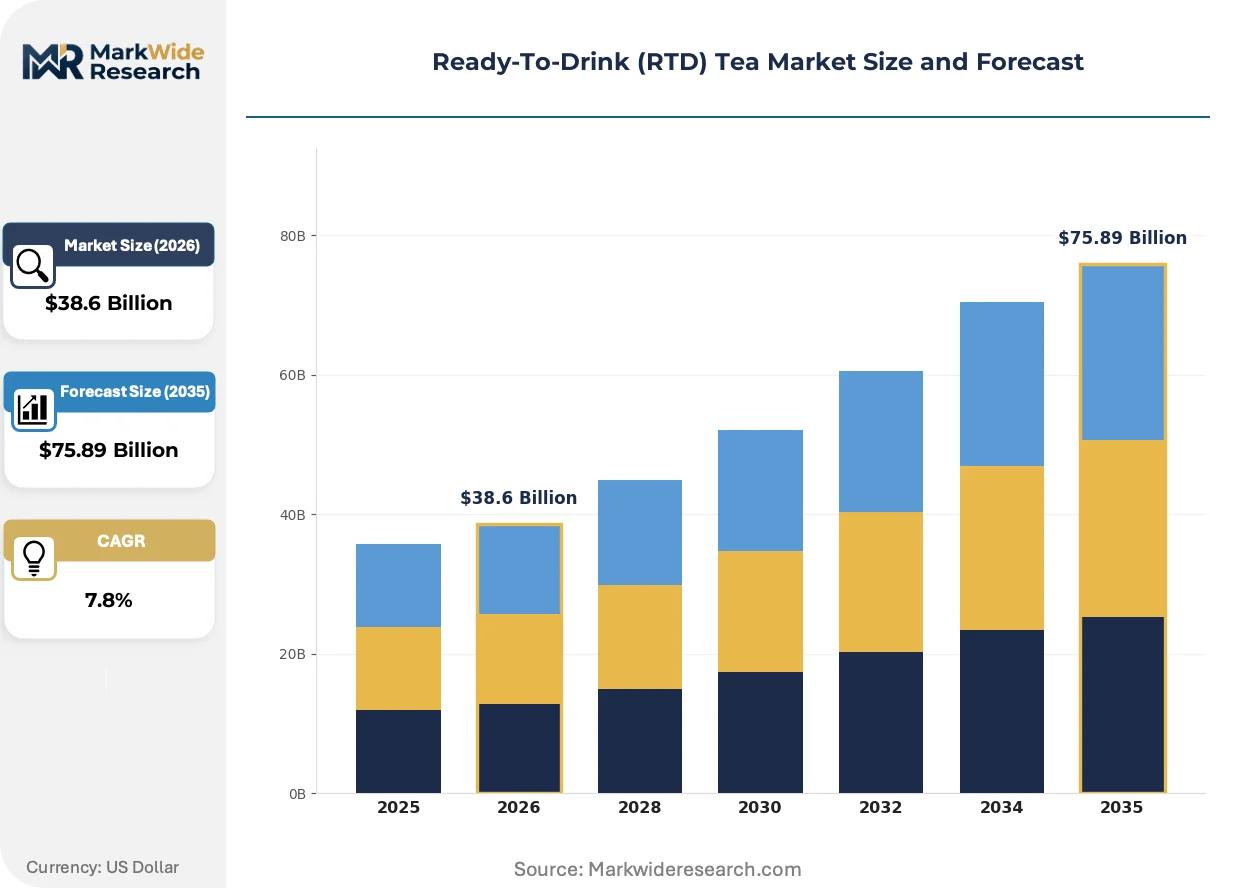
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $75.89 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbal Tea, Green Tea, Black Tea, Fruit Infusions Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Health Shops End User: Individuals, Offices, Cafes, Restaurants Flavor Profile: Citrus, Mint, Berry, Tropical |
| Companies Covered | The Coca-Cola Company, PepsiCo, Nestle, Suntory Holdings, Unilever, Nongfu Spring, Keurig Dr Pepper, Arizona Beverage Company, Ito En, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ready-To-Drink (RTD) Tea Market Emerging Trajectories
Cold-chain logistics and extraction technology are converging to enable fresher taste profiles, while regulatory pressure on sugar content forces simultaneous reformulation across multiple formulation architectures.
Nitrogen-infused cold-brew processing is fragmenting the premium segment by extending shelf stability without thermal degradation. Health-focused millennials in corporate cafeterias adopt these formats for afternoon consumption. The technology compresses the traditional trade-off between freshness credentials and distribution reach.
China's SAMR enforces updated GB standards for sugar content disclosures and additive permissions that tighten formulation flexibility. Domestic manufacturers reformulate proactively to avoid label redesign costs. Imported brands face compliance timelines that delay market entry against local competitors.
Subscription-based replenishment models are displacing impulse-driven convenience store purchasing among urban professionals. Direct-to-consumer platforms capture consumption data that enables flavor customization. This shift concentrates most visibly in China's tier-one cities where delivery infrastructure supports same-day fulfillment.
Ready-To-Drink (RTD) Tea Market Segmentation
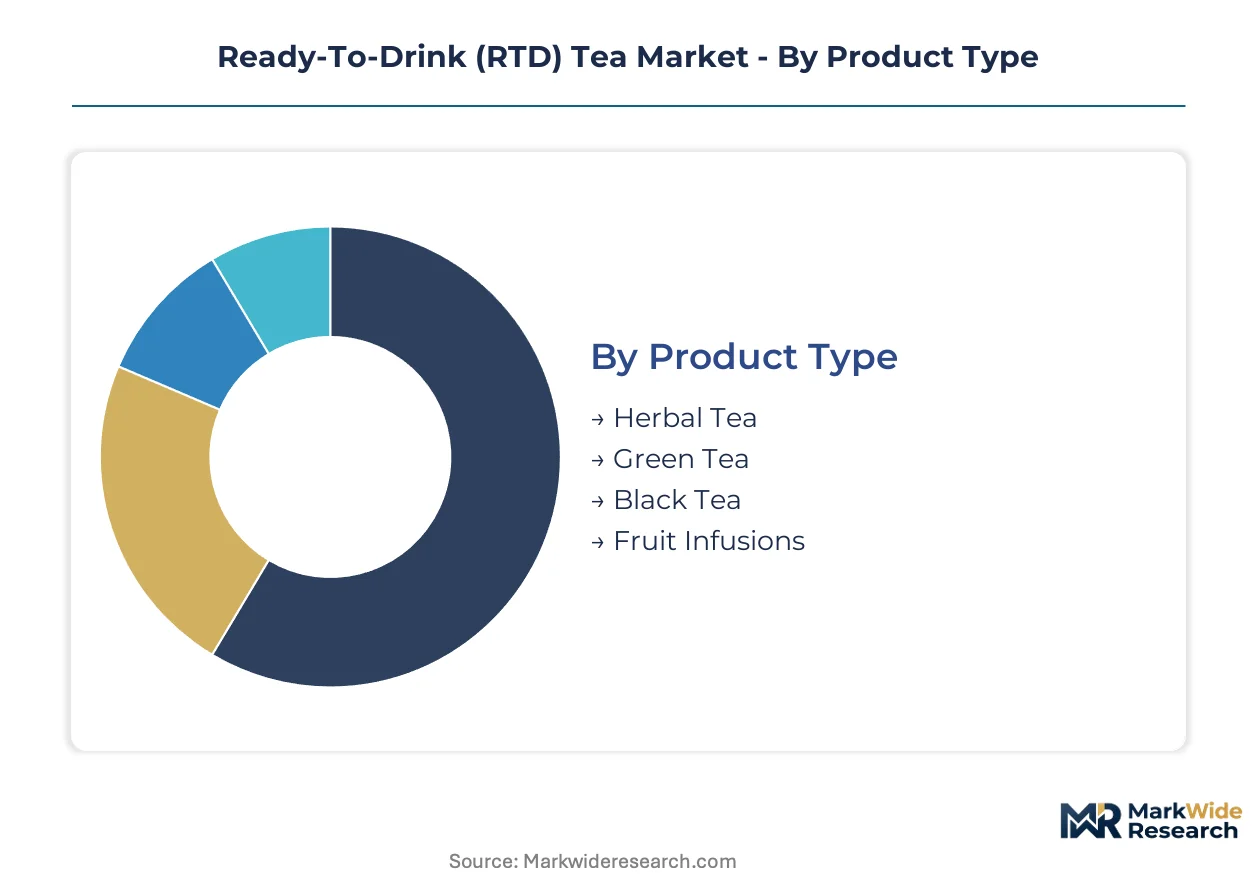
RTD tea segmentation reveals divergent growth trajectories across formulation types and channel access. Product architecture and distribution reach determine margin capture in this transitioning market.
Product Type:
Domestic consumption concentrates on heritage formats while export demand pulls toward functional variants with clinical positioning.
- Green Tea:Brewed from unoxidized Camellia sinensis leaves retaining catechin polyphenols. Corporate cafeterias in China's tier-one cities and India's urban metros are switching to unsweetened formats as sugar-tax exposure reshapes procurement. Cold-brew extraction methods preserve antioxidant integrity for premium placement.
- Black Tea:Fully oxidized leaf processing delivers robust flavor profiles familiar in traditional markets. Mature volume pools concentrate in Commonwealth consumption corridors where established bottling networks maintain distribution economics. Assam and Kenyan auction volatility compresses margin predictability.
- Herbal Tea:Non-camellia botanical infusions including rooibos, chamomile, and hibiscus targeting caffeine-averse demographics.
- Fruit Infusions:Blended formulations combining tea solids with fruit extracts for palatability in entry-tier positioning.
Black tea commands the established base. The steepest expansion runs through green tea as functional positioning accelerates.
Distribution Channel:
Channel selection dictates working capital intensity and consumer data capture depth.
- Online Retail:Direct-to-consumer platforms bypass conventional grocery slotting fees while capturing repeat-purchase data for flavor personalization. Same-day fulfillment infrastructure in China's tier-one cities and India's urban metros supports subscription-based replenishment among urban professionals.
- Convenience Stores:Grab-and-go velocity depends on cold-chain penetration and single-serve bottle economics. Shanghai, Beijing, and Guangzhou exhibit concentrated penetration that supports impulse consumption.
- Supermarkets:Mass retail shelf space secured through bottling-network scale and fountain infrastructure leverage.
- Health Shops:Premium placement contingent on authentic extraction credentials and EFSA-compliant functional claims.
Supermarkets anchor volume throughput. Digital channels are climbing the fastest as subscription models displace impulse purchasing.
End User:
User segmentation maps to consumption occasion and procurement authority structures.
- Individuals:Personal consumption driven by health-conscious switching from carbonated sodas in residential and transit contexts.
- Offices:Corporate cafeteria procurement responding to wellness program mandates and sugar-tax liability management.
- Cafes:Out-of-home premium positioning requiring cold-brew authenticity and nitrogen-infused differentiation.
- Restaurants:Food-service volume contingent on fountain system integration and pour-cost economics.
Individual purchasers sustain baseline demand. Office procurement is gaining share fastest as corporate wellness budgets expand.
Flavor Profile:
Flavor architecture balances palatability engineering against clean-label positioning requirements.
- Citrus:Lemon and grapefruit extracts masking astringency in green tea formulations without sugar reliance.
- Mint:Cooling sensation profiles supporting functional claims around digestion and refreshment.
- Berry:Anthocyanin-rich additions enabling antioxidant stacking for premium-tier positioning.
- Tropical:Mango and passionfruit variants targeting younger demographics in emerging market expansion.
Citrus variants anchor formulation stability. Berry profiles are expanding most quickly as antioxidant marketing intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in RTD tea concentrate manufacturing capability in East Asia while Western markets absorb premium formulations. China's processing infrastructure supplies neighboring markets as India's domestic brands capture local shelf space. Regulatory divergence between FDA Nutrition Facts rules and China's GB standards fragments packaging compliance costs across trade corridors.
China
Shanghai and Beijing convenience-store density drives single-serve consumption velocity among urban professionals. SAMR enforces updated GB standards for sugar content disclosures that compress formulation timelines for imported brands. Yangtze River Delta bottling clusters dominate cold-brew processing capacity for regional export.
United States
Corporate cafeteria procurement shifts toward unsweetened green tea as wellness program mandates expand. FDA Nutrition Facts labeling rules and health claim substantiation requirements constrain antioxidant positioning without clinical evidence. California and New York Metro areas concentrate direct-to-consumer subscription fulfillment infrastructure.
Japan
Authentic extraction expertise for premium green tea variants anchors domestic consumption and regional export reputation. METI standards for food additive permissions shape formulation architectures for functional positioning. Kansai region blending facilities supply specialty formats to health-focused retail channels across Asia-Pacific.
India
Mumbai, Delhi, and Bangalore present underpenetrated convenience-channel whitespace as modern retail formats proliferate. FSSAI labeling requirements for packaged beverages add compliance layers for multinational entrants. Maharashtra and Karnataka bottling networks expand cold-chain reach into secondary urban corridors.
Germany
Sugar-tax exposure across European Union markets accelerates zero-sugar reformulation for export-bound production. EFSA health claim assessments demand clinical evidence thresholds that constrain functional positioning. Bavaria and North Rhine-Westphalia beverage processing hubs serve as distribution gateways for continental shelf placement.
Ready-To-Drink (RTD) Tea Market Vendor Landscape
Concentration sits with multinational beverage conglomerates that leverage fountain infrastructure and bottling-network scale to secure mass retail shelf space. Mid-tier specialists occupy premium health-channel positioning through authentic extraction credentials. Competitive moves center on cold-brew processing capability acquisition and direct-to-consumer platform development to bypass conventional grocery slotting economics.
Among diversified beverage majors, The Coca-Cola Company and PepsiCo exemplify scale-driven archetypes that anchor volume throughput in convenience and mass retail channels. Ito En occupies a position within the premium-tier specialist segment, representing authentic Japanese green tea extraction methods that command placement in health-focused retail formats. These three entities illustrate the bifurcation between network-scale efficiency and craft-credentials positioning that defines competitive structure.
| Leading Market Players |
|---|
| The Coca-Cola Company |
| PepsiCo |
| Nestle |
| Suntory Holdings |
| Unilever |
| Nongfu Spring |
| Keurig Dr Pepper |
| Arizona Beverage Company |
| Ito En |
| Others |
Supply Flow & Price Mechanics
Sixty-day inventory cycles for cold-brew concentrate feed directly into premium pricing power for bottlers that control both extraction and distribution assets. This lead-time compression separates firms with captive supply from those exposed to spot-market tea leaf volatility.
Pricing Analysis
The customization-premium spread between nitrogen-infused single-origin formats and mass-market sweetened lines now exceeds three-to-one in China's tier-one cities. Three-tier pricing structure across premium, standard, and economy levels anchors on extraction method authenticity, with cold-brew and heritage cultivar certification commanding placement in health shops. Cost compression in entry-tier fruit-infusion segments is intensifying because Assam auction volatility transfers directly to contract renegotiations. Corporate cafeteria procurement shows lowest price sensitivity due to wellness budget insulation, while individual convenience-store purchasers exhibit highest elasticity to sugar-tax pass-through.
Supply Chain Analysis
China and Japan anchor global processing capacity for green tea extraction, with Yangtze River Delta bottling clusters supplying regional export markets. Kenyan and Assam auction houses feed raw leaf inputs that rest on monsoon-dependent harvest cycles, creating margin unpredictability for black tea-dependent portfolios. Single-source vulnerability concentrates in Taiwanese blending expertise for authentic cultivar profiles. Distribution runs through refrigerated logistics networks that limit chilled RTD penetration to urban corridors with cold-chain infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
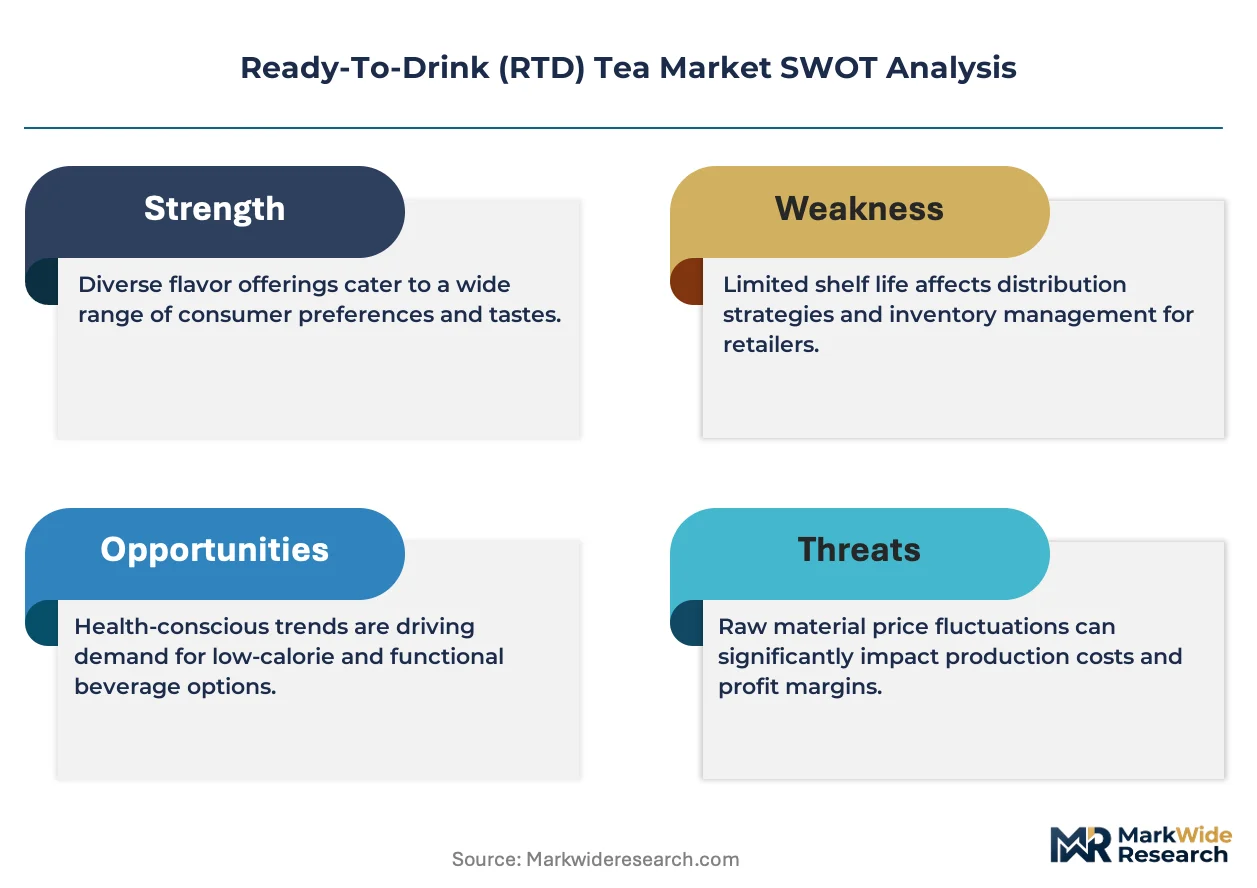
Carbonated functional waters and adaptogenic sodas threaten RTD tea's wellness positioning, forcing incumbents to defend share through formulation differentiation rather than channel presence alone.
For Market Incumbents: Consolidate cold-brew processing capability through acquisition of Japanese or Taiwanese extraction specialists to secure authentic cultivar access. Lock in long-term offtake agreements with Kenyan and Assam auction houses before monsoon volatility transfers to contract pricing. Channel control in China's tier-one convenience networks remains the priority defensive lever against local brand encroachment.
For New Entrants and Emerging Players: Direct-to-consumer subscription fulfillment gaps in India's urban metros offer white-space entry with lower slotting-fee exposure than mass retail. Target cold-chain-deficient secondary cities in Maharashtra and Karnataka where modern retail format expansion outruns incumbent refrigerated distribution. Lead with flavor personalization engines that capture repeat-purchase data for corporate wellness procurement.
For Investors and Strategic Acquirers: Carve-out targets emerge from multinational beverage parents seeking to divest non-core tea portfolios amid sugar-tax liability concentration. Long-term viability hinges on dual capability ownership: bottling-network scale plus extraction-method authenticity. Monitor EFSA health claim assessment precedents as inflection signal for functional positioning permissibility across European export markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Brew Processing Acquisition | Authentic extraction methods from Japanese specialists secure premium health-channel placement. |
| Direct-to-Consumer Platform Launch | Subscription models bypass grocery slotting fees and capture flavor personalization data. |
| Zero-Sugar Reformulation Program | Proactive adaptation to FDA and China's SAMR sugar disclosure standards reduces compliance cost. |
| Lightweight Packaging Innovation | MEE sustainability mandate alignment in China supports dual carbon goal positioning. |
| Corporate Wellness Channel Expansion | Office procurement relationships insulate against individual consumer price sensitivity. |
Methodological Framework
The analysis maps green tea extraction methods, black tea bottling networks, herbal infusion supply chains, and direct-to-consumer platform economics, each validated through bottling plant managers, convenience store category buyers, corporate cafeteria procurement officers, and cold-chain logistics operators. Primary interview findings triangulate against secondary sources including FDA Nutrition Facts filings, China's SAMR GB standard updates, EFSA health claim assessments, Assam and Kenyan tea auction records, and Nielsen retail audit data. Bottom-up volume builds and top-down market sizing converge through iterative reconciliation.
Consistency checks against external benchmarks validate value outputs across the projection horizon. Segmentation dimensions span product type architecture, distribution channel access, end-user procurement authority, and flavor profile positioning. CAGRs derive from modeled volume trajectories adjusted for regulatory reformulation timelines and channel shift elasticity. Forecast inputs incorporate cold-chain infrastructure expansion rates and sugar-tax legislative adoption patterns.
Forecasts assume regulatory continuity in FDA labeling rules, China's SAMR standards, and EU EFSA assessments; material policy shifts would require re-modeling of compliance cost pass-through and functional claim permissibility. Tea leaf auction volatility and monsoon pattern disruption present revision risks for margin projections. Recalibration cycles align with material shifts in sugar-tax adoption, cold-brew technology diffusion, and corporate wellness procurement mandate expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Bottled Milk Tea Market
Tea
Global Tea Bag Market
Tea
China Tea Market
Tea
Tea Polyphenols Market
Tea
Out of Home Tea Market
Tea
Smart Tea Maker Market
Tea
Asia-Pacific Green Tea Market
Tea
US RTD Organic Tea Market
Tea
Matcha Tea Market
Tea
North America Ready-To-Drink Tea Market
Tea
Green Tea Bag Market
Tea
North America Tea Market
Tea
Tea Concentrate Market
Tea
Edible Tea Market
Tea
Rooibos Tea Market
Tea
Green Tea Market