
 Spray-Dried Tea Products Market | 2026-2036
Spray-Dried Tea Products Market Size, Share, and Industry Trends Forecast 2026-2036
Spray-Dried Tea Products Market Analytics
Buyer concentration across food manufacturers is rebalancing as multinational beverage formulators consolidate supplier lists while specialty health stores fragment procurement across smaller craft processors. Tata Global Beverages leverages its integrated tea estate network to secure raw material continuity. Nestlé sustains scale advantages in instant mix applications through captive flavor development capabilities. Unilever competes on brand recognition in retail channels across Europe and South Asia.
Spray-dried tea products are produced by atomizing concentrated tea extracts into a heated chamber, yielding free-flowing powders with moisture content below 5 percent and preserved polyphenol profiles for consistent solubility in industrial formulations. Green tea powders command premium positioning in health-focused applications due to catechin retention requirements, while black tea variants anchor volume in instant beverage mixes where color and astringency standards drive procurement. The bakery application segment shows structural momentum as clean-label reformulations replace artificial flavoring systems with standardized tea extracts.
FDA preventive controls under FSMA mandate validated kill-step documentation for spray-drying operations, elevating compliance costs for mid-scale processors. EFSA guidance on novel food classifications shapes market access pathways for white tea and herbal variants in European jurisdictions. BIS certification requirements in India enforce moisture and microbiological standards for domestic distribution. Stakeholders must monitor evolving residue limits and extraction method disclosures as procurement criteria tighten across regulated end-use channels.
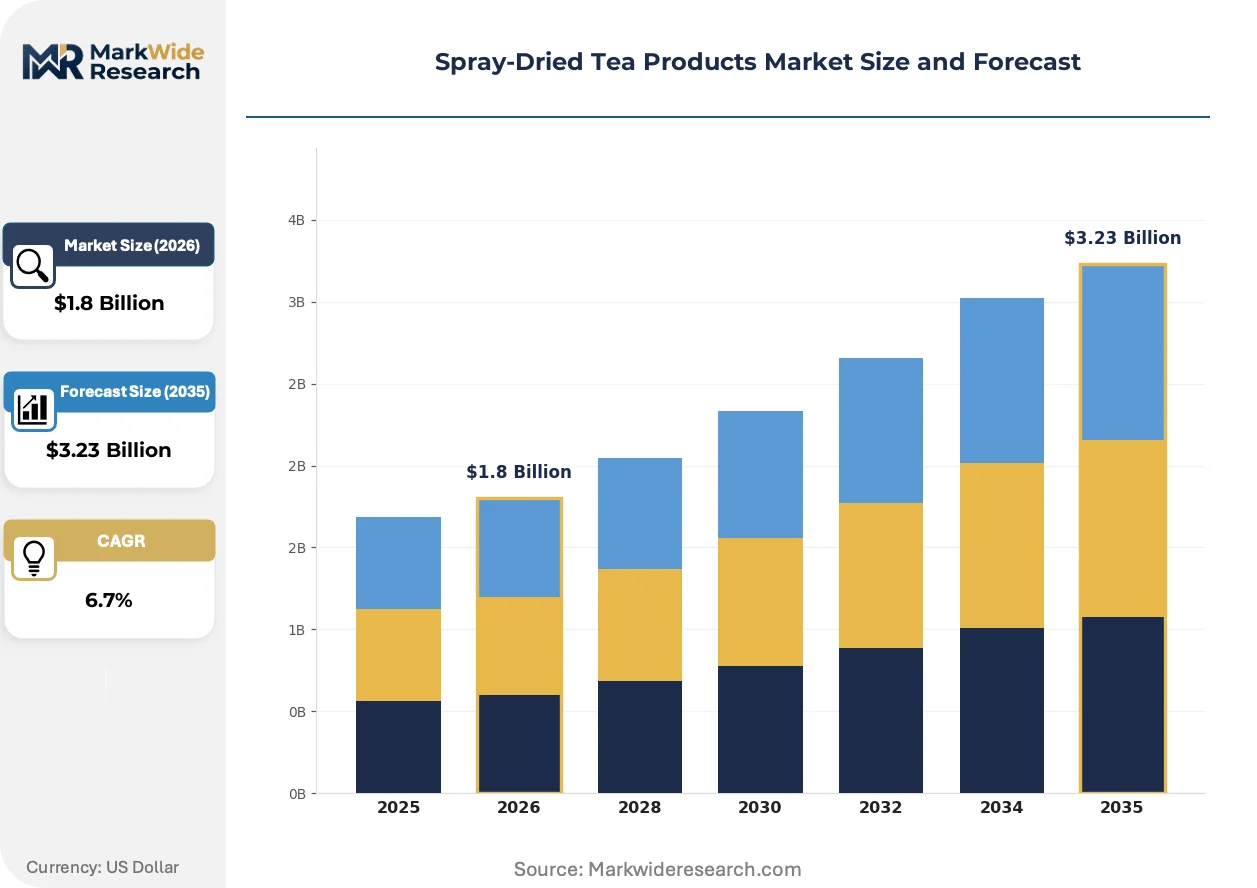
Market Dynamics
Food manufacturers are consolidating supplier lists while demanding validated kill-step documentation under FDA preventive controls, compressing procurement options for mid-scale processors and elevating compliance investments as table stakes for contract eligibility.
Growth Catalysts
- FSMA preventive controls:FDA mandates for validated drying documentation push processors toward certified equipment upgrades, filtering out informal suppliers and concentrating volume with validated operators.
- Clean-label bakery reformulation:Industrial bakers are replacing artificial flavor systems with standardized tea extracts to meet retailer clean-label mandates, creating pull-through demand for spray-dried powders with consistent polyphenol profiles.
- Instant chai infrastructure:India’s domestic consumption patterns and export processing capacity anchor volume demand, with regional processors scaling atomization capacity to serve both packaged goods and foodservice channels.
Market Restraints
- Input cost volatility:Fluctuations in tea leaf auction prices and energy costs for thermal drying compress margins for processors without captive estate supply or long-term procurement hedges.
- Supply concentration risk:Quality-grade tea leaf sourcing concentrates in Assam and Darjeeling estates, exposing formulators to climate disruption and seasonal yield variation without geographic diversification.
- Technical limitation:Catechin degradation during high-temperature atomization constrains green tea powder yield and premium positioning, requiring investment in low-temperature alternatives or modified atmosphere processing.
Strategic Opportunities
- Underpenetrated white tea variants:EFSA novel food classification pathways for white tea extracts create first-mover positioning in European functional beverage and nutraceutical applications.
- Regulatory tailwind:India's PLI scheme for food processing incentivizes capital investment in automated spray-drying lines, reducing payback periods for capacity expansion.
- Direct-to-manufacturer channels:E-commerce procurement platforms are disintermediating traditional distributor networks, enabling smaller craft processors to access industrial formulators with minimum order quantity flexibility.
Industry Challenges
- Skill gap in process validation:Documenting kill-step efficacy for FSMA compliance requires specialized food safety engineering expertise that mid-scale processors struggle to recruit and retain.
- Capex intensity for BIS certification:Upgrading to moisture and microbiological testing infrastructure demanded by India's Bureau of Indian Standards requires capital outlays that strain regional processor balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spray-Dried Tea Products Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Green Tea, Black Tea, Herbal Tea, White Tea Application: Beverages, Instant Mixes, Confectionery, Bakery Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Food Service End User: Consumers, Food Manufacturers, Beverage Manufacturers, Health Stores |
| Companies Covered | Tata Global Beverages, Nestlé, Unilever, Ito En, C. B. Shah & Co. (Tweak), GEA Group Aktiengesellschaft, Givaudan, Archer Daniels Midland, Fonterra Co-operative Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spray-Dried Tea Products Market Evolving Landscape
Atomization technology and extraction methodology are converging to preserve bioactive compounds while meeting industrial solubility standards, reshaping competitive advantage around process control rather than commodity sourcing.
Low-temperature spray-drying systems with nitrogen blanketing are overtaking conventional high-heat atomization for premium green tea applications. Functional beverage formulators in North American and European markets are specifying these systems for catechin retention above 85 percent. This technology compression is enabling smaller processors to compete on quality metrics previously reserved for integrated multinationals with captive R&D.
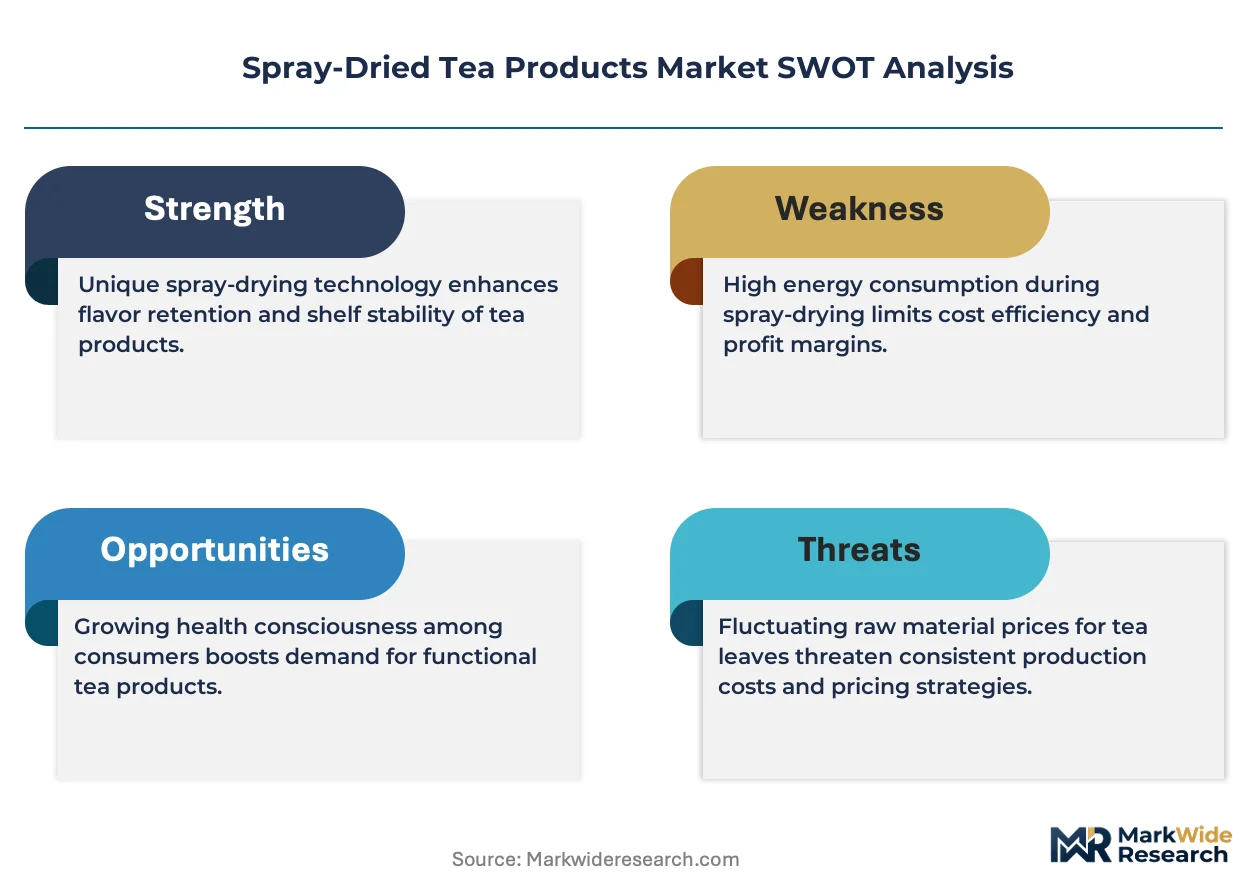
EFSA guidance on novel food classifications is restructuring market access requirements for white tea and herbal variants in European jurisdictions. The framework mandates comprehensive safety dossiers and consumption exposure assessments before placement on the market. Specialty extract suppliers are responding by front-loading toxicology studies and building regulatory affairs capabilities previously unnecessary for conventional black tea powders.
Industrial procurement is compressing supplier qualification cycles as multinational beverage formulators consolidate vendor lists and demand single-source accountability for quality and compliance. Long-term framework agreements with volume commitments are displacing spot-market purchasing for standardized tea extracts. This concentration is most visible in India, where Tata Global Beverages and integrated estate processors are capturing multi-year supply contracts with global instant mix manufacturers.
Spray-Dried Tea Products Market Segmentation
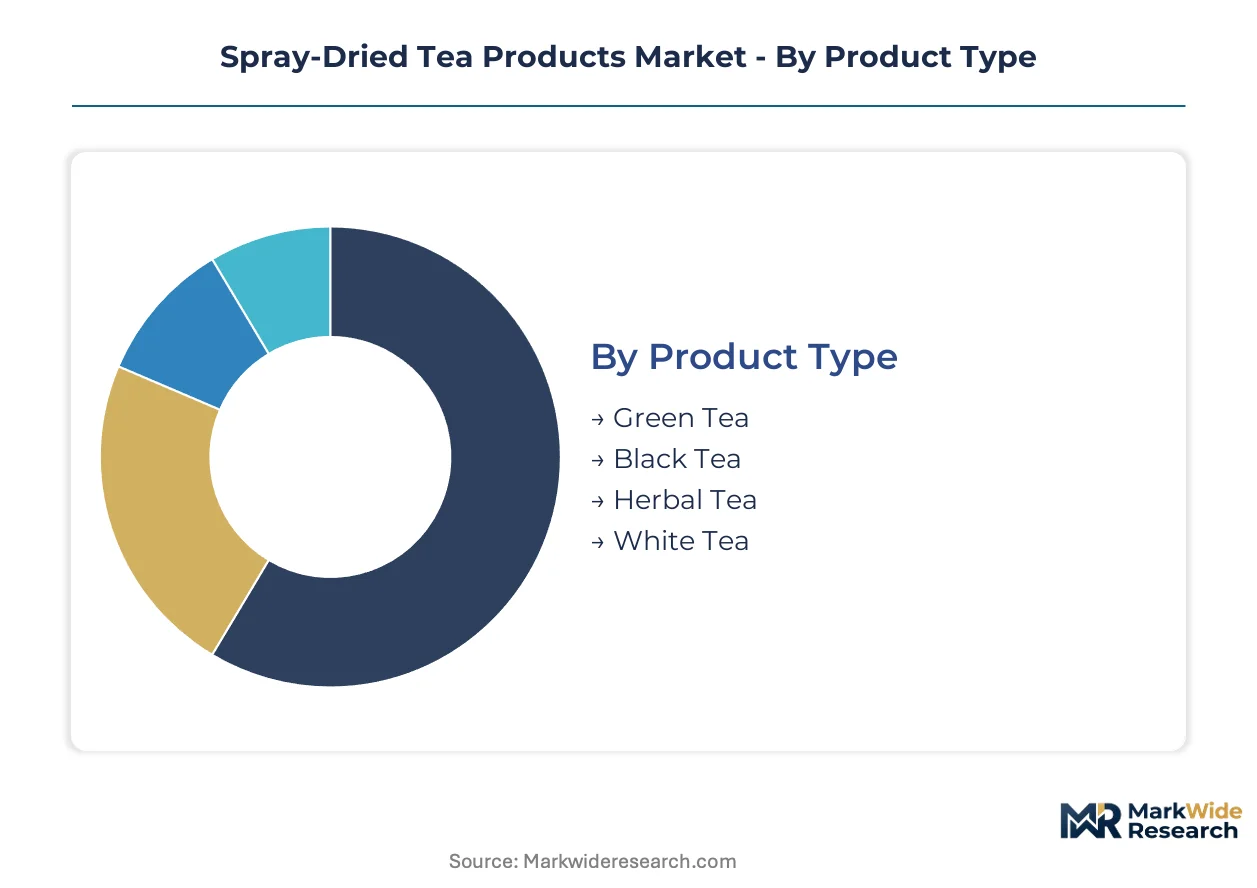
Spray-dried tea powders serve divergent functional requirements across formulation contexts. Segmentation reveals how atomization specifications, solubility standards, and polyphenol retention targets reshape procurement patterns by end-use channel.
Product Type:
Integration depth varies sharply: green and white tea powders embed primarily in premium functional formulations, while black tea anchors mass-market standalone applications.
- Green Tea:Atomization at controlled temperatures preserves epigallocatechin gallate concentrations above 85 percent, meeting specifications from North American nutraceutical formulators. Catechin retention requirements elevate processing costs and filter supplier eligibility to nitrogen-blanketing operators.
- Black Tea:Standardized theaflavin and thearubigin profiles deliver consistent color and astringency for instant chai and iced tea concentrates. Volume concentrates in Indian domestic consumption and export processing corridors serving Gulf and East African markets.
- Herbal Tea:Chamomile, rooibos, and hibiscus variants command specialty positioning in European wellness channels with novel food compliance overhead.
- White Tea:Minimal oxidation preserves delicate flavor matrices for premium cosmetic and beverage applications, constrained by EFSA safety dossier requirements.
Volume placements concentrate in Black Tea; the faster expansion belongs to Green Tea.
Application:
Cost tier stratification separates commodity instant mixes from precision-dosed bakery and confectionery integrations.
- Beverages:Ready-to-drink formulations demand rapid cold-water solubility and turbidity control, driving specification tightness in particle size distribution.
- Instant Mixes:Sachet and jarred chai concentrates require standardized extraction solids and moisture content below 5 percent for shelf stability in tropical climates.
- Confectionery:Chocolate and candy applications prioritize flavor encapsulation and heat stability during conching and tempering processes.
- Bakery:Clean-label reformulations replace artificial flavor systems with standardized tea extracts, pulling demand from industrial bakers serving European retailer mandates.
Procurement scale favors Instant Mixes; margin expansion is steepest in Bakery.
Distribution Channel:
Customer type fragmentation splits procurement between bulk industrial contracts and fragmented specialty retail.
- Online Retail:Direct-to-consumer powders in premium packaging target home baristas and wellness enthusiasts with subscription replenishment models.
- Supermarkets:Mass-market instant mix placement depends on slotting fees and private-label manufacturing relationships with integrated processors.
- Specialty Stores:Curated single-origin and organic variants command price premiums through provenance storytelling and small-batch positioning.
- Food Service:Bubble tea chains and café formulations drive bulk procurement with consistency specifications and just-in-time delivery requirements.
Contract value aggregates in Food Service; channel growth is climbing fastest in Online Retail.
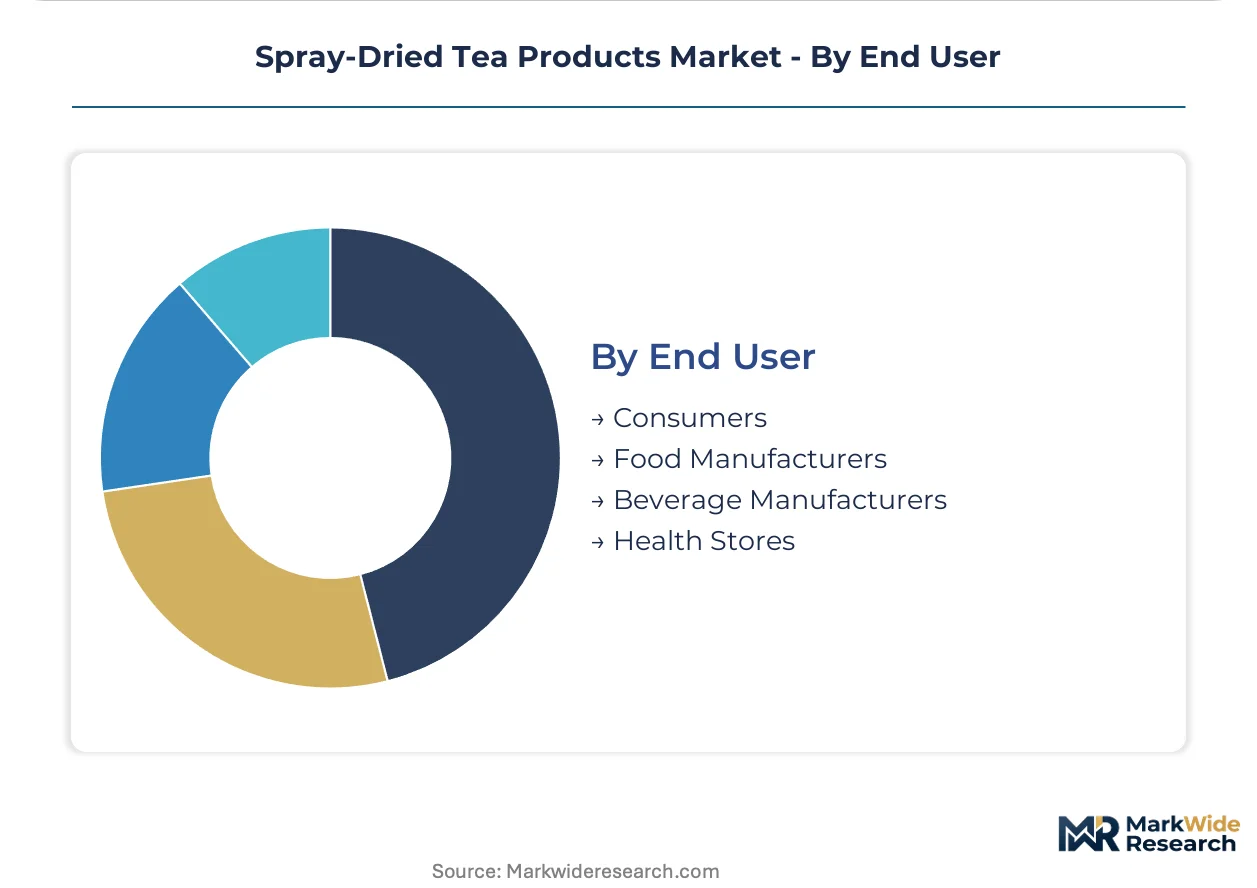
End User:
Supply concentration aligns with volume scale: beverage manufacturers consolidate supplier lists while health stores fragment across craft processors.
- Consumers:Individual purchasers prioritize convenience formats and flavor variety, with limited price sensitivity in premium wellness positioning.
- Food Manufacturers:Industrial bakers and confectioners require validated kill-step documentation and lot traceability under FSMA preventive controls.
- Beverage Manufacturers:Multinational formulators enforce single-source accountability through multi-year framework agreements with volume commitments.
- Health Stores:Specialty retailers source small-batch organic and functional blends with flexible minimum order quantities from regional processors.
Procurement volume concentrates in Beverage Manufacturers; the expanding user base is gaining share fastest in Health Stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates the heaviest procurement pull for spray-dried tea powders, with domestic instant chai consumption and export processing corridors anchoring regional demand. Multinational beverage formulators source standardized black tea extracts from Indian processors to supply Gulf and East African markets. Regulatory divergence across producing and consuming regions is reshaping supplier qualification requirements.
India
Tata Global Beverages and regional processors scale atomization capacity to serve packaged goods and foodservice channels. The FSSAI enforces moisture and microbiological standards alongside BIS certification requirements for domestic distribution. Assam and Darjeeling estates anchor quality-grade tea leaf sourcing, though climate disruption exposes formulators to seasonal yield variation.
United States
Functional beverage formulators in North America specify nitrogen-blanketed low-temperature drying systems for catechin retention above 85 percent. The FDA's FSMA preventive controls mandate validated kill-step documentation, filtering out informal suppliers and elevating compliance investments as contract eligibility requirements. California and New York metro areas concentrate clean-label bakery reformulation demand from industrial bakers.
China
Green tea powder production scales to meet nutraceutical export specifications, with domestic consumption expanding in premium wellness channels. The SAMR enforces GB standards for food additive classifications and residue limits in extraction methods. Zhejiang and Fujian provinces host concentrated processing clusters serving both domestic instant beverage manufacturers and international specialty buyers.
Germany
Industrial bakers and confectioners across Bavaria and North Rhine-Westphalia integrate standardized tea extracts into clean-label reformulations. The EFSA novel food classification framework shapes market access pathways for white tea and herbal variants, mandating comprehensive safety dossiers before placement. Hamburg anchors import and redistribution infrastructure for European processed food manufacturers.
Japan
Matcha and premium green tea powder applications concentrate in functional beverage and cosmetic formulations. METI standards and JIS specifications govern processing equipment validation and quality grading systems. Kansai region processors, particularly around Kyoto and Osaka, maintain traditional stone-ground production alongside industrial spray-drying capacity for export markets.
Spray-Dried Tea Products Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialty health positioning and direct-to-manufacturer channel access. The vendor base stratifies across integrated multinationals with captive estate networks, regional processors scaling atomization capacity, and craft operators serving fragmented specialty retail. Three archetypes dominate: estate-integrated formulators securing raw material continuity, equipment-technology licensors enabling processor upgrades, and flavor houses embedding tea extracts into broader ingredient portfolios. Competitive moves concentrate in multi-year framework agreements with volume commitments and automated spray-drying line investments.
Within the estate-integrated tier, Tata Global Beverages exemplifies upstream control over raw material supply through its integrated tea estate network. Nestlé occupies a position representing scale advantages in instant mix applications through captive flavor development capabilities. Unilever sits within the brand-recognition vector, competing across retail channels in Europe and South Asia. These three anchors illustrate how procurement consolidation favors operators with demonstrated compliance documentation and validated kill-step capabilities under FDA preventive controls.
| Leading Market Players |
|---|
| Tata Global Beverages |
| Nestlé |
| Unilever |
| Ito En |
| C. B. Shah & Co. (Tweak) |
| GEA Group Aktiengesellschaft |
| Givaudan |
| Archer Daniels Midland |
| Fonterra Co-operative Group |
| Others |
Value Network & Pricing Analysis
Nitrogen-blanketed low-temperature atomization systems are displacing conventional high-heat drying methods, simultaneously elevating capital requirements for processors and concentrating procurement power with operators capable of catechin retention above 85 percent. This technology transition compresses margins for mid-scale Indian processors lacking captive estate supply while rewarding integrated multinationals with validated kill-step documentation under FDA preventive controls.
Pricing Analysis
Volume placements concentrate in standardized black tea extracts for instant chai applications, while margin expansion concentrates in premium green tea powders with certified epigallocatechin gallate retention. Three-tier pricing structure across premium, standard, and economy levels separates nitrogen-blanketed specialty operators from conventional atomizers and informal estate processors. Pricing pressure stems from energy cost volatility for thermal drying and tea leaf auction fluctuations, compressing returns for processors without long-term procurement hedges. Beverage manufacturers exhibit lowest price sensitivity due to multi-year framework agreements, while health stores and craft retailers drive hardest bargains on small-batch orders.
Supply Chain Analysis
Freight cost escalation from Assam and Darjeeling estates to Mumbai and Hamburg export corridors is reshaping sourcing economics for European and Gulf market formulators. Supply concentrates in India, China, and Japan, with quality-grade tea leaf sourcing anchored in Assam and Darjeeling estates and processing clusters scaling in Zhejiang and Fujian provinces. Raw material dependencies rest on auction-grade tea leaves, natural gas for thermal drying, and nitrogen supply for blanketing systems. Single-source vulnerability from climate disruption in northeastern Indian estates poses structural risk. Distribution runs through long-term framework agreements with multinational beverage manufacturers, displacing spot-market purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play where FSMA preventive control mandates and BIS certification requirements are forcing mid-scale processors without validated kill-step documentation toward exit or acquisition.
For Market Incumbents: Extend multi-year framework agreements with volume commitments to lock in beverage manufacturer procurement before emerging nitrogen-blanketing operators achieve scale. Deepen upstream control over estate supply through captive Assam and Darjeeling sourcing to insulate against climate-driven yield volatility. Prioritize automated spray-drying line investments under India's PLI scheme to compress payback periods and widen cost advantages over regional competitors. For New Entrants and Emerging Players: EFSA novel food classification pathways in Europe open a window for white tea and herbal variant positioning before incumbents front-load toxicology studies. Target underpenetrated functional beverage applications in North American nutraceutical channels where catechin retention specifications filter supplier eligibility. Pursue direct-to-manufacturer e-commerce procurement platforms to bypass traditional distributor networks and offer minimum order quantity flexibility that health stores demand. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated multinationals seeking validated kill-step capabilities and estate-anchored supply security. Long-term viability favors processors with demonstrated FSMA compliance documentation and nitrogen-blanketing equipment installations. Watch for inflection signals in India's PLI scheme uptake rates, which indicate which regional processors are securing capital for automated capacity expansion versus facing balance sheet strain.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Spray-Drying Line Investment | India's PLI scheme reduces payback periods for processors scaling atomization capacity under FSSAI compliance mandates. |
| Backward Integration into Estate Supply | Captive Assam and Darjeeling sourcing insulates Tata Global Beverages from climate-driven yield volatility and auction price spikes. |
| Novel Food Safety Dossier Submission | EFSA compliance for white tea extracts creates first-mover positioning in European functional beverage channels before incumbent saturation. |
| Direct-to-Manufacturer Channel Development | E-commerce procurement platforms disintermediate traditional distributors and enable craft processors to access industrial formulators with flexible minimum orders. |
| Low-Temperature Nitrogen-Blanketing Upgrade | Catechin retention above 85 percent meets North American nutraceutical specifications and filters supplier eligibility to premium tier. |
Research Methodology
Document review covered FSSAI enforcement circulars, FDA FSMA preventive control guidance documents, and EFSA novel food classification frameworks, complemented by interviews with spray-drying equipment engineers, procurement managers at multinational beverage formulators, regulatory affairs specialists at Indian processors, and quality assurance directors at industrial bakeries. Secondary validation drew from BIS certification registries, Indian tea auction price databases, and customs export records. Bottom-up triangulation across processor capacity installations and top-down reconciliation against end-use demand segments anchored volume estimates.
Output modeling segmented the market by product type (green tea, black tea, herbal tea, white tea), application (beverages, instant mixes, confectionery, bakery), and distribution channel (online retail, supermarkets, specialty stores, food service) across the projection horizon. CAGRs were derived from fitted growth curves against historical capacity expansion patterns and procurement contract visibility. Forecast inputs incorporated tea leaf yield projections from Assam and Darjeeling estates, energy cost trajectories for thermal drying, and regulatory compliance adoption rates under FSMA and BIS frameworks.
The model assumes a particular technology adoption path toward nitrogen-blanketed low-temperature systems; alternative pathways for conventional high-heat atomization with modified atmosphere processing would alter the outlook for green tea powder yield and premium positioning. Forecasts reflect assumptions about PLI scheme participation rates, climate stability in northeastern Indian estates, and EFSA dossier approval timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Green Tea Bag Market
Tea
North America Ready-To-Drink Tea Market
Tea
Tea Concentrate Market
Tea
Europe Tea Market
Tea
Single Origin Tea Market
Tea
Africa Ready to Drink Tea Market
Tea
Moringa Tea Market
Tea
China Tea Market
Tea
Light-Fermented Tea Market
Tea
Organic Tea Market
Tea
Mate Tea Market
Tea
Middle East Ready to Drink Tea Market
Tea
Smart Tea Set Market
Tea
Ready-To-Drink (RTD) Tea Market
Tea
Global Catechin Market
Tea
Herbal Tea Market