
 ROV Tether Management System Market | 2026-2036
ROV Tether Management System Market Size, Share, and Industry Trends Forecast 2026-2036
ROV Tether Management System Market Insights
Aftermarket service revenue is narrowing toward OEM-authorized refurbishment as operators extend umbilical lifecycles in deepwater fields. TechnipFMC anchors its position through captive supply of hydraulic tether systems for ultradeep installations. Oceaneering International differentiates via integrated ROV-to-vessel service contracts that bundle tether management with inspection workflows.
An ROV Tether Management System comprises winch drums, sheave assemblies, and cable reeling mechanisms that deploy, recover, and tension umbilical cables connecting surface vessels to remotely operated vehicles, typically handling loads exceeding 10 metric tons at depths beyond 3,000 meters. Fiber optic technology leads the cable segment due to bandwidth requirements for real-time video and sensor data transmission, while hybrid cable configurations represent the fastest-growing technology category as operators consolidate power and signal pathways. Winch-based systems dominate product type demand for heavy-lift offshore construction, whereas reel-based systems gain share in scientific research vessels where deck footprint constraints apply.
FAA regulations on aviation-linked subsea survey equipment, ISO 13628-7 standards for subsea production systems, and BSEE well control rules in the US Gulf collectively shape tether fatigue-testing protocols and material certification requirements. The EU AI Act and forthcoming MDR-equivalent frameworks for autonomous underwater vehicles will extend compliance burdens to tether-integrated navigation systems. Stakeholders must monitor how classification societies adapt unified rules for synthetic rope tethers before committing to next-generation platform designs.
Market Dynamics
Deepwater field development beyond 3,000 meters is compressing replacement cycles for legacy hydraulic tether systems as operators confront fatigue failures in steel-armored umbilicals. The shift toward fiber-optic telemetry and hybrid power-signal configurations is redrawing supplier qualification requirements across North Sea, Gulf of Mexico, and West African installations.
Growth Catalysts
- EU F-Gas Regulation:Phasedown of fluorinated hydraulic fluids is accelerating retrofit demand for synthetic-based tether systems in Norwegian and UK North Sea operations.
- Fiber-optic telemetry:Bandwidth requirements for 4K subsea video and real-time sensor fusion are displacing copper-core umbilicals in ultradeep construction campaigns.
- Brazil pre-salt cluster:Petrobras-led development of carbonate reservoirs below 2,000 meters is sustaining procurement of 15-metric-ton winch systems.
Market Restraints
- Specialized steel alloy concentration:Super-duplex stainless supply for armored cables concentrates with Nordic and Japanese metallurgical suppliers, exposing procurement to nickel price volatility.
- ISO 13628-7 compliance timelines:Extended fatigue-testing protocols for subsea production system integration are stretching OEM delivery schedules by 8-14 months.
- Autonomous underwater vehicle substitution:Tetherless AUV platforms for pipeline survey are capturing share in inspection workflows previously served by ROV systems.
Strategic Opportunities
- West Africa marginal field development:Ghana and Senegal offshore rounds are creating demand for modular reel-based systems on chartered vessels with deck footprint constraints.
- EU AI Act compliance services:Tether-integrated navigation and collision-avoidance systems for semi-autonomous ROVs require certification support that OEMs can bundle as recurring revenue.
- Fiber-copper hybrid convergence:Consolidation of power and data pathways into single-cable configurations reduces vessel deck complexity and spares inventory for operators.
Industry Challenges
- Subsea hydraulic technician scarcity:Deepwater winch maintenance requires specialized skills in high-pressure fluid systems that offshore labor markets currently undersupply.
- Legacy vessel integration:Retrofitting active heave compensation onto 1990s-built construction vessels demands structural modifications that compress project margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ROV Tether Management System Market |
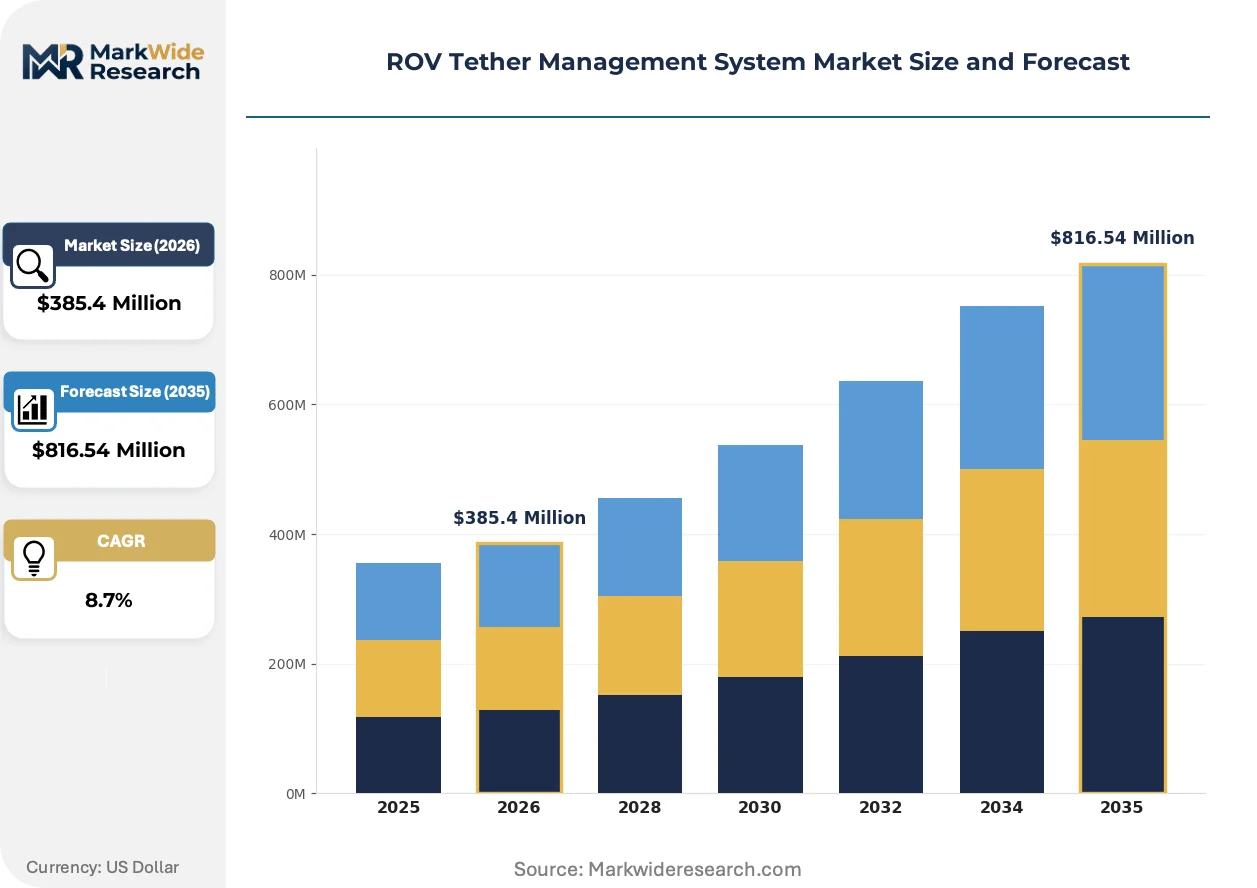
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Winch-Based Systems, Reel-Based Systems, Hydraulic Tether Systems, Pneumatic Tether Systems Technology: Fiber Optic, Coaxial Cable, Electrical Cable, Hybrid Cable, Synthetic Rope Application: Offshore Exploration, Submarine Inspection, Underwater Maintenance, Scientific Research, Salvage Operations End User: Marine Survey Companies, Offshore Drilling Firms, Underwater Construction, Defense & Security |
| Companies Covered | TechnipFMC plc, DOF Subsea AS, Forum Energy Technologies, Inc., Teledyne Technologies Incorporated, Subsea 7 S.A., Fugro N.V., Oceaneering International, Inc., Kongsberg Gruppen ASA, Saab Seaeye Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ROV Tether Management System Market Trends and Innovations
Real-time condition monitoring of umbilical fatigue is displacing calendar-based maintenance schedules across deepwater fleets. Suppliers are embedding distributed fiber-optic sensing into cable cores to capture strain, temperature, and acoustic signatures during deployment.
Synthetic rope tether technology is migrating from experimental research vessels to commercial offshore construction. Fiber Dynamics and Samson Rope have qualified aramid-polyester blends for 12-metric-ton working loads at 4,000-meter depths. Norwegian contractors are piloting these configurations in North Sea decommissioning projects where reduced topside weight improves vessel stability.
The EU F-Gas Regulation and forthcoming MDR-equivalent frameworks for autonomous underwater vehicles are tightening material certification pathways. ECHA substance restrictions on hydraulic fluid additives are forcing reformulation of legacy synthetic esters used in winch systems. OEMs serving Equinor and Aker BP contracts are accelerating qualification of bio-based alternatives ahead of 2027 compliance deadlines.
Integrated service contracting is compressing standalone equipment procurement. Operators in the US Gulf are bundling tether management with inspection workflows and data analytics under multi-year vessel alliances. Oceaneering International and TechnipFMC have restructured offerings to capture this spend shift, displacing spot-market equipment rentals with performance-guaranteed subscriptions.
ROV Tether Management System Market Segmentation
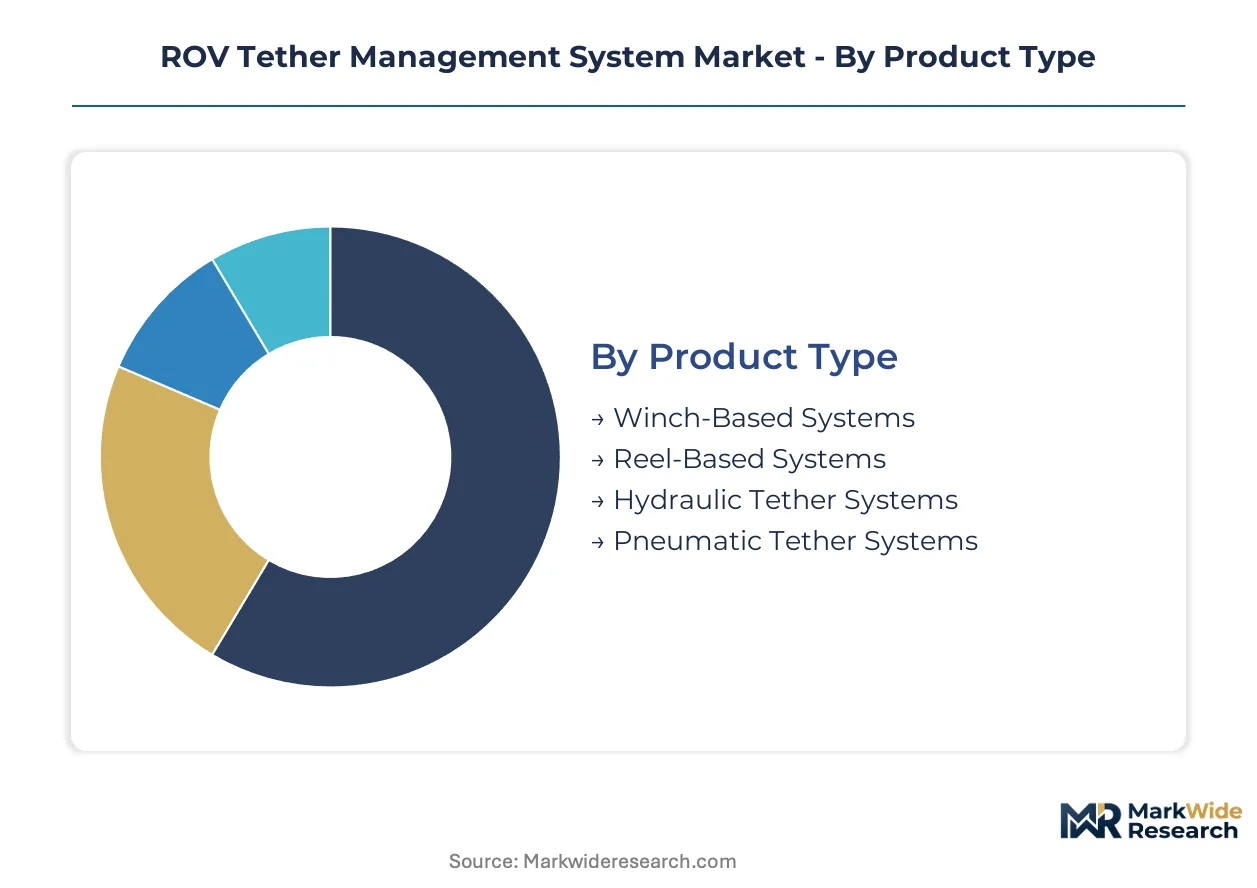
Segmentation in the ROV tether management market reveals divergent equipment lifecycles and service attachment rates across operational environments. Aftermarket revenue concentration varies sharply between heavy-lift offshore construction and research vessel deployments, reshaping how OEMs structure warranty and refurbishment offerings.
Product Type:
After-sales-service intensity escalates with system complexity and deployment depth, creating tiered margin profiles across equipment categories.
- Winch-Based Systems:Heavy-lift drum assemblies with active heave compensation handle loads exceeding 15 metric tons in ultradeep construction. Demand concentrates in Brazil's pre-salt cluster where Petrobras operations require 4,000-meter depth ratings and integrated tension monitoring.
- Reel-Based Systems:Compact cable reeling mechanisms optimize deck footprint on chartered vessels with space constraints. Scientific research fleets in Norway favor these configurations for rapid deployment cycles in fjord and continental shelf operations.
- Hydraulic Tether Systems:High-pressure fluid power transmission for subsea tooling and manipulator arms.
- Pneumatic Tether Systems:Compressed-air delivery for shallow-water inspection and light-duty salvage.
By volume, Winch-Based Systems lead. By growth pace, Reel-Based Systems are expanding most quickly.
Technology:
Material certification pathways and bandwidth specifications create distinct supplier qualification barriers across cable architectures.
- Fiber Optic:Single-mode and multimode silica cores transmit 4K video and sensor fusion data with minimal signal attenuation. North Sea operators under Equinor contracts mandate these for real-time subsea construction monitoring.
- Hybrid Cable:Consolidated copper power conductors and fiber data pathways reduce vessel deck complexity. West African marginal field developments in Ghana and Senegal drive procurement for modular installation campaigns.
- Coaxial Cable:Copper-core shielded transmission for legacy ROV fleets with lower bandwidth requirements.
- Electrical Cable:Multi-conductor copper configurations for power-dominant tether applications.
- Synthetic Rope:Aramid-polyester blended tethers for reduced topside weight in decommissioning operations.
By installed base, Fiber Optic dominates. By share gain velocity, Hybrid Cable is climbing the fastest.
Application:
Operational depth and inspection frequency determine equipment utilization rates and replacement cycle timing.
- Offshore Exploration:Seafloor mapping and well site survey operations in frontier basins.
- Submarine Inspection:Pipeline integrity assessment and structural anomaly detection.
- Underwater Maintenance:Subsea hardware intervention and repair campaigns.
- Scientific Research:Deep-ocean sampling and benthic ecosystem study missions.
- Salvage Operations:Wreck recovery and debris removal in shallow to moderate depths.
By equipment deployed, Offshore Exploration leads. By contract value concentration, Submarine Inspection shows the steepest expansion trajectory.
End User:
Procurement sophistication and in-house technical capability shape purchasing patterns across customer categories.
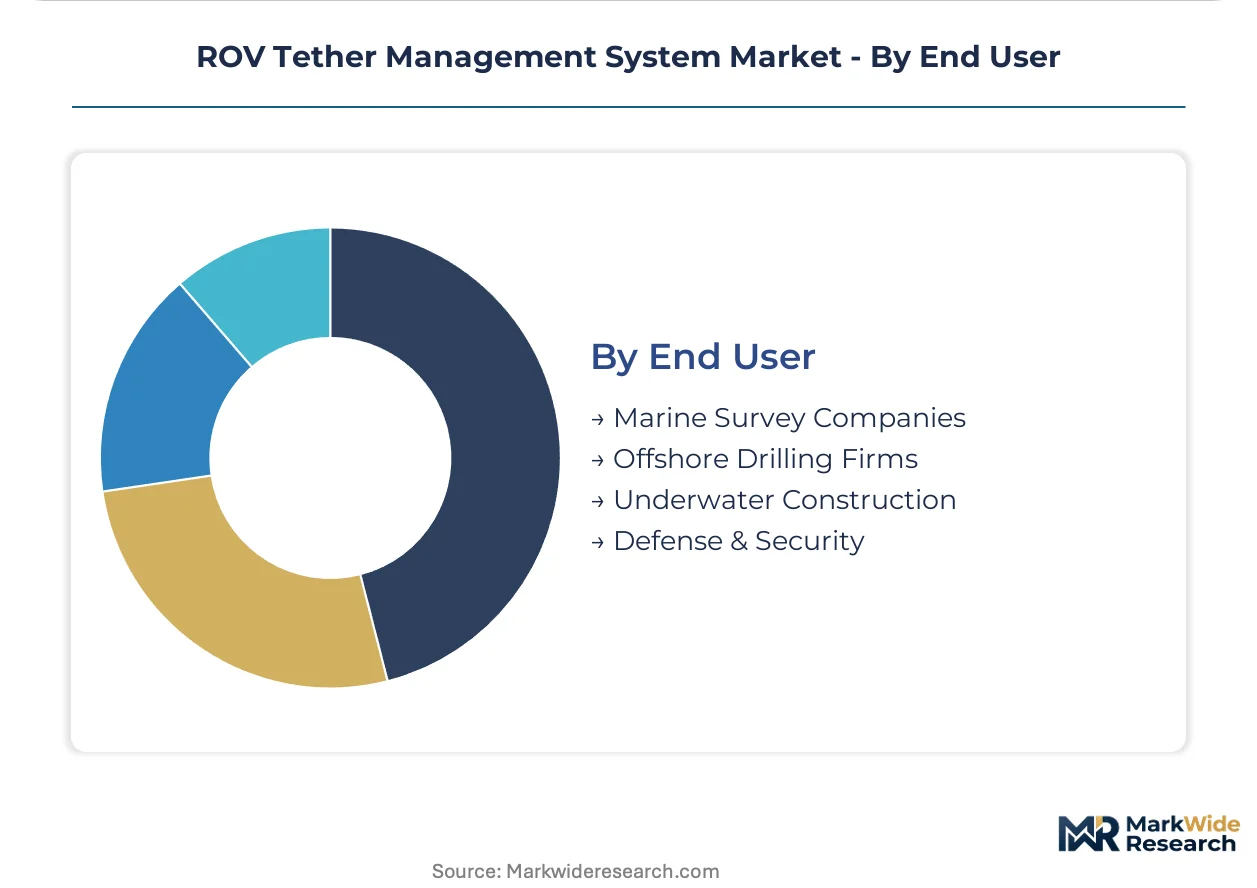
- Offshore Drilling Firms:Integrated drilling contractors with captive ROV fleets and long-term OEM alliances. US Gulf operators under BSEE jurisdiction specify ISO 13628-7 compliant tether fatigue ratings for well control applications.
- Marine Survey Companies:Specialized geophysical and geotechnical service providers with chartered vessel dependencies. Norwegian North Sea clusters drive demand for fiber-optic telemetry integration.
- Underwater Construction:Subsea installation and decommissioning contractors.
- Defense & Security:Naval mine countermeasures and port security operations.
By annual procurement value, Offshore Drilling Firms lead. By contract growth rate, Marine Survey Companies are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norway deploys winch-based systems for ultradeep construction while Brazil favors heavy-lift configurations for pre-salt development, revealing how basin geology shapes equipment selection across offshore markets.
Norway
Equinor and Aker BP operations in the North Sea drive replacement cycles for fiber-optic tether systems as fields mature beyond original design life. The EU F-Gas Regulation accelerates retrofit demand for synthetic-based hydraulic fluids ahead of 2027 deadlines. Bergen and Stavanger clusters concentrate OEM service facilities and umbilical refurbishment capacity.
Brazil
Petrobras-led pre-salt development below 2,000 meters sustains procurement of 15-metric-ton winch systems for carbonate reservoir intervention. ANP regulatory frameworks mandate ISO 13628-7 compliance for subsea production system integration. The Santos Basin offshore Rio de Janeiro anchors heavy-lift construction vessel deployment and tether management service hubs.
United States
BSEE well control rules in the Gulf of Mexico shape tether fatigue-testing protocols for drilling contractors operating at extreme depths. FAA regulations govern aviation-linked subsea survey equipment deployed from offshore platforms. Houston concentrates engineering procurement and construction firms managing integrated ROV service contracts.
United Kingdom
North Sea decommissioning campaigns drive demand for reduced-weight synthetic rope tethers to improve vessel stability during platform removal. The country's national maritime regulator enforces subsea equipment certification aligned with IMO guidelines. Aberdeen maintains specialized hydraulic technician training programs for deepwater winch maintenance.
Ghana
Marginal field developments offshore Takoradi create demand for modular reel-based systems on chartered vessels with deck footprint constraints. Ghana National Petroleum Corporation licensing rounds attract international contractors requiring rapid-deployment tether configurations. The Tano Basin emerging oil province concentrates early-stage exploration ROV operations.
ROV Tether Management System Market Competitive Landscape
Capability concentration sits with specialized subsea engineering firms; scale advantage sits with integrated oilfield service conglomerates. The market structure reflects a two-tier dynamic where captive umbilical supply chains anchor premium positioning while independent service contractors compete on vessel alliance flexibility. Three archetypes dominate: integrated subsea technology providers, ROV fleet operators with captive tether management, and specialized winch engineering houses. M&A activity targets hydraulic system capabilities and geographic expansion into West African markets.
Within the integrated subsea technology tier, TechnipFMC plc and Oceaneering International, Inc. exemplify contrasting strategic positions. TechnipFMC plc, a UK-headquartered limited company, anchors premium-tier positioning through captive supply relationships. Oceaneering International, Inc., a US-incorporated entity, occupies a service-integration archetype bundling tether management with inspection workflows. Kongsberg Gruppen ASA, a Norwegian allmennaksjeselskap, represents Nordic engineering concentration in fiber-optic telemetry systems.
| Leading Market Players |
|---|
| TechnipFMC plc |
| DOF Subsea AS |
| Forum Energy Technologies, Inc. |
| Teledyne Technologies Incorporated |
| Subsea 7 S.A. |
| Fugro N.V. |
| Oceaneering International, Inc. |
| Kongsberg Gruppen ASA |
| Saab Seaeye Limited |
| Others |
Pricing and Supply Chain Analysis
Nordic and Japanese metallurgical suppliers control super-duplex stainless feedstock for armored cables, concentrating margin capture upstream while downstream OEMs compete on service bundling and certification tier differentiation. This supply concentration grants raw material producers outsized pricing leverage during nickel price volatility episodes, compressing fabrication margins for winch system assemblers.
Pricing Analysis
Long-term offtake contracts dominate procurement for ultradeep construction fleets, with Petrobras and Equinor locking in 5-7 year tether management subscriptions that bundle equipment, maintenance, and data analytics. Price differentiation rests on ISO 13628-7 certification tier and active heave compensation integration depth, with premium configurations commanding substantial service attach rates. Cost compression in standard winch systems is intensifying as Brazilian and West African contractors consolidate vendor panels. Charter vessel operators exhibit highest price sensitivity due to project-based utilization, whereas integrated drilling firms prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Super-duplex stainless steel feedstock draws from Norway, Japan, and Sweden, with aramid-polyester synthetic rope fibers sourcing from US and Belgian specialty polymer producers. Fiber-optic cores and high-pressure hydraulic seals represent critical component dependencies with limited qualified suppliers. Single-source vulnerability concentrates in deepwater winch drum forging capacity, where only two Nordic engineering houses maintain 4,000-meter depth certification. Distribution runs through OEM-direct vessel alliances and regional service hubs in Bergen, Houston, and Rio de Janeiro.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ROV tether management sector is accelerating through a technology inflection as fiber-optic telemetry displaces copper-core umbilicals and synthetic rope tethers enter commercial qualification. The EU F-Gas Regulation's synthetic hydraulic fluid mandate is simultaneously reshaping supplier qualification barriers.
For Market Incumbents: Entrench captive supply relationships for fiber-optic cable cores and super-duplex forging capacity before 2027 compliance deadlines tighten. Accelerate backward integration into distributed fiber-optic sensing technology to capture condition-monitoring revenue streams that AUV substitution threatens. Prioritize certification investment for EU AI Act-compliant tether-integrated navigation systems. For New Entrants and Emerging Players: Pursue modular reel-based system opportunities in Ghana and Senegal marginal field developments where deck footprint constraints favor compact configurations. Target scientific research vessel fleets in Norway for rapid-deployment tether contracts with lower qualification barriers than oilfield construction. Differentiate through bio-based hydraulic fluid formulations that preempt ECHA substance restrictions. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap winch engineering houses with Nordic metallurgical supplier relationships and active heave compensation IP. The 5-10 year viability window favors targets with captive umbilical refurbishment capacity in North Sea and Brazil hubs. Watch for synthetic rope tether qualification milestones from Fiber Dynamics and Samson Rope as inflection indicators for next-generation platform adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber-Optic Sensing | OEMs embedding distributed sensing capture recurring condition-monitoring revenue from Equinor and Petrobras fleets. |
| Synthetic Hydraulic Fluid Qualification | Bio-based formulations meeting EU F-Gas Regulation deadlines secure preferred supplier status with Aker BP. |
| West African Service Hub Establishment | Regional refurbishment capacity in Takoradi reduces vessel downtime for Ghana National Petroleum Corporation contractors. |
| EU AI Act Certification Investment | Tether-integrated collision-avoidance systems unlock semi-autonomous ROV contracts under forthcoming MDR-equivalent frameworks. |
| Synthetic Rope Tether Commercialization | Aramid-polyester blends qualified for 4,000-meter depths displace steel-armored umbilicals in North Sea decommissioning. |
Research Methodology
A spread of perspectives from subsea construction project managers, hydraulic systems engineers, vessel chartering directors, and umbilical procurement leads converged on the working assumptions. Primary fieldwork combined with secondary validation from BSEE well control filings, ANP regulatory submissions, ISO 13628-7 certification databases, and offshore vessel utilization reports. Bottom-up equipment deployment counts triangulated against top-down EPC contractor capex disclosures across the analysis window.
Demand-supply balance modeling segmented the projection horizon by product type, cable technology, operational depth tier, and regional regulatory cluster. CAGRs derived from equipment replacement cycle analysis and greenfield project sanctioning rates. Forecast inputs incorporated Petrobras pre-salt development timelines, North Sea decommissioning campaign schedules, and West African licensing round progressions without year-specific anchoring.
Macroeconomic conditions sit as an overlay; deviation in offshore drilling day rates, nickel price volatility, or charter vessel availability would shift the trajectory. Forecasts reflect documented assumptions on fiber-optic adoption curves and synthetic rope qualification timelines. Cross-checking against IHS Markit offshore project databases and Clarksons vessel orderbook data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Pneumatic Strippers Market
Industrial Equipment
Femtosecond Fiber Lasers Market
Industrial Equipment
Parts and Equipment Market
Industrial Equipment
Coil Winding Machine Market
Industrial Equipment
Microwave Equipment Market
Industrial Equipment
Battery Power Tools Market
Industrial Equipment
Resistance Spot Welding Machines Market
Industrial Equipment
Industrial Refrigeration Systems Market
Industrial Equipment
Electric Soldering Iron Gun Market
Industrial Equipment
Precision Machine Market
Industrial Equipment
Asia-Pacific Electro Hydraulic Servo Valve Market
Industrial Equipment
Floor Scales Market
Industrial Equipment
Long-Range Acoustic Device Market
Industrial Equipment
Global Abrasive Waterjet Cutting Machine Market
Industrial Equipment
Latin America Explosion-Proof Equipment Market
Industrial Equipment
Laser Ablation Systems Market