
 Laser Ablation Systems Market | 2026-2036
Laser Ablation Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Laser Ablation Systems Market Outlook
A capital-intensity divergence between integrated photonics conglomerates and specialized component suppliers is reorganizing competitive tiers in laser ablation systems. TRUMPF GmbH + Co. KG leverages captive manufacturing of pump diodes and optical fibers to control cost structures across industrial cutting and medical ablation platforms. Coherent Corp. sustains broad vertical reach from laser crystals to complete system assembly, anchoring its position in semiconductor fabrication tools. Applied Spectra Inc. specializes in compact LIBS and LA-ICP-MS instruments for geochemical and nuclear analysis, occupying a defensible niche against larger players.
Laser ablation systems deliver controlled material removal through focused electromagnetic radiation, with ultrafast variants achieving pulse durations below 10 picoseconds to minimize thermal diffusion into surrounding substrates. These systems serve precision manufacturing, surgical intervention, and analytical spectroscopy by vaporizing target material with spatial resolution reaching sub-micron scales. Fiber laser architectures now dominate industrial material processing applications due to superior wall-plug efficiency and maintenance intervals exceeding 50,000 hours. Ultrafast laser technology represents the fastest-expanding technology segment, driven by semiconductor manufacturers requiring damage-free processing of brittle low-k dielectrics. Medical procedure applications command premium pricing through FDA and CE-marked surgical platforms, while microelectronics demand concentrates in die singulation and through-silicon via formation.
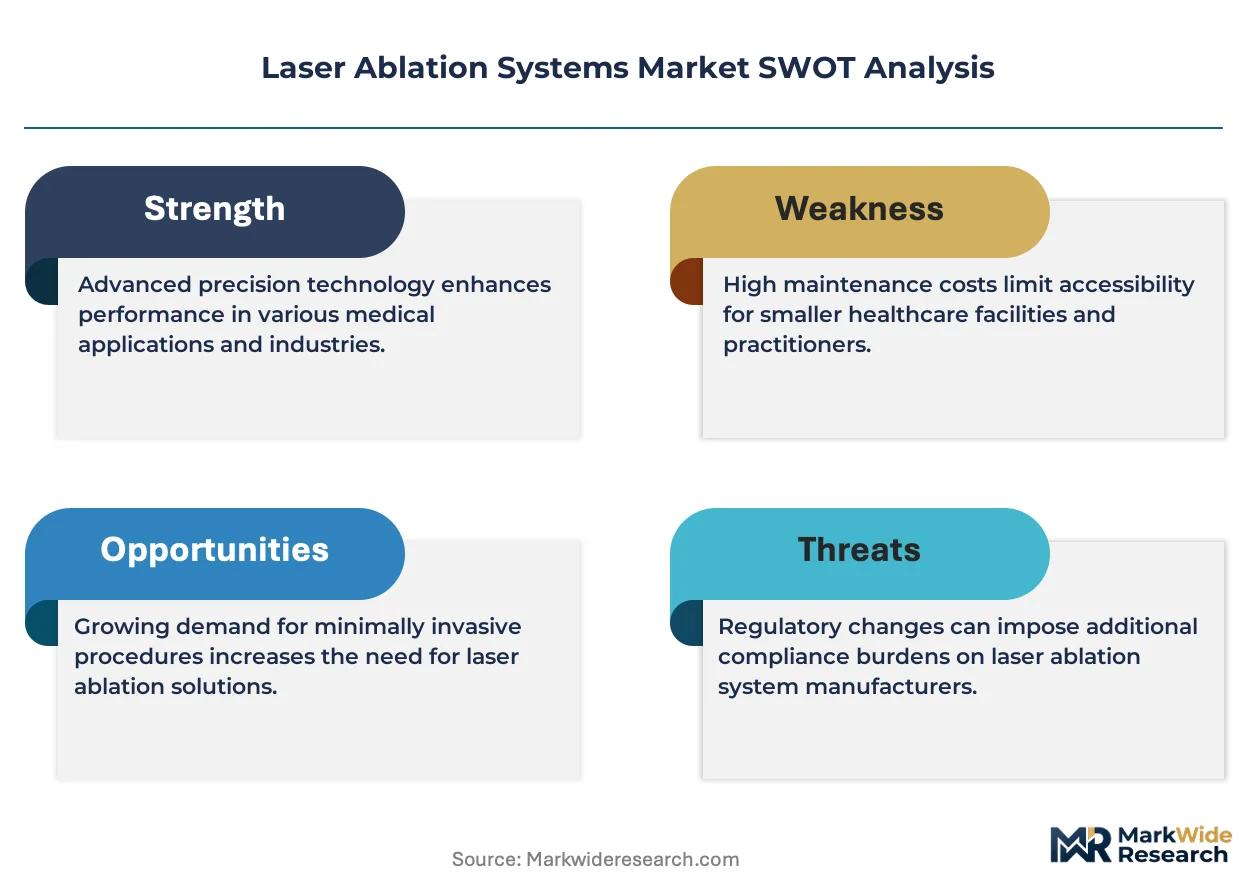
FDA 510(k) clearance requirements shape product development timelines and clinical validation costs for surgical laser ablation devices targeting tumor resection and ophthalmology. EPA air emissions standards and OSHA laser safety regulations govern industrial installation protocols, particularly for high-power CO2 and fiber systems deployed in metalworking facilities. The EU MDR and F-Gas Regulation collectively redirect R&D investment toward solid-state and diode-pumped architectures that eliminate gas laser consumables. Stakeholders must monitor evolving IEC 60825 laser safety classifications and country-specific medical device approval pathways as ultrafast sources penetrate new therapeutic and manufacturing domains.
Market Dynamics
Ultrafast laser architectures are displacing nanosecond and continuous-wave systems in precision manufacturing, driven by semiconductor fabs in Taiwan and South Korea demanding damage-free processing of brittle low-k dielectrics for advanced packaging.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of fluorinated greenhouse gases forces abandonment of gas-based CO2 and excimer lasers, redirecting capital toward solid-state and fiber platforms that eliminate consumable gas media entirely.
- Die singulation demand:Taiwan Semiconductor Manufacturing and Samsung Foundry are expanding ultrafast laser deployment for stealth dicing of silicon wafers, replacing mechanical blade methods that generate microcracks.
- Through-silicon via drilling:3D NAND and advanced logic stacks require high-aspect-ratio holes in silicon substrates, with picosecond lasers achieving aspect ratios above 20:1 without thermal damage to surrounding circuitry.
Market Restraints
- Optical component supply concentration:German and Japanese suppliers dominate production of ultrafast laser crystals, beam delivery fibers, and precision optics, creating single-source vulnerability for system integrators outside these geographies.
- Technical limitation in thick-metal processing:Ultrafast lasers exhibit poor energy coupling in copper and aluminum above 6 millimeters thickness, constraining penetration into heavy industrial cutting applications where fiber lasers retain dominance.
- Substitution threat from plasma etching:Deep reactive-ion etching offers competitive via formation costs at high volumes, pressuring laser ablation pricing in commodity semiconductor manufacturing.
Strategic Opportunities
- India electronics manufacturing:Production-linked incentive schemes for semiconductor and display fabrication are attracting greenfield fab investments that will require first-time laser ablation system procurement without incumbent vendor relationships.
- Regulatory tailwind from EU MDR:Stricter clinical evidence requirements for surgical devices create barriers for new entrants, favoring established laser ablation platform holders with existing FDA and CE mark portfolios.
- LIBS-analytical convergence:Integration of laser-induced breakdown spectroscopy with automated sorting systems enables real-time elemental analysis of scrap metal streams, opening materials recycling applications beyond traditional manufacturing.
Industry Challenges
- Ultrafast laser physicist shortage:System manufacturers compete for scarce talent capable of modeling nonlinear pulse propagation and dispersion compensation, with academic programs producing fewer specialists than industrial demand requires.
- FDA 510(k) timeline compression:Surgical laser platforms face 18-24 month validation cycles for new indications, delaying revenue recognition and requiring sustained R&D funding without near-term commercial return.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laser Ablation Systems Market |
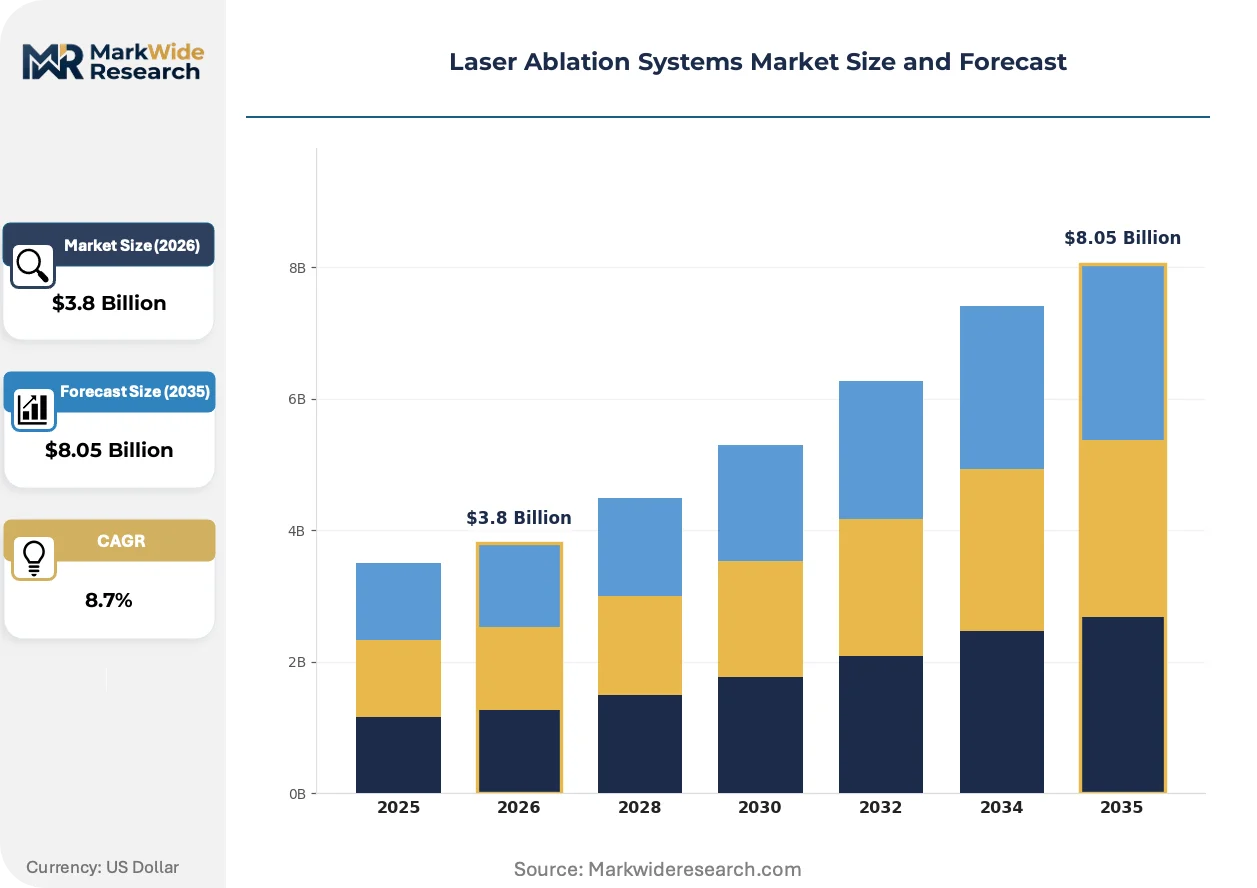
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CO2 Laser, Fiber Laser, Diode Laser, Solid-State Laser Application: Medical Procedures, Material Processing, Semiconductor Manufacturing, Microelectronics End User: Hospitals, Research Laboratories, Industrial Manufacturers, Academic Institutions Technology: Pulsed Laser, Continuous Wave Laser, Ultrafast Laser, Nanosecond Laser |
| Companies Covered | Lumentum Holdings Inc., Han’s Laser Technology Industry Group Co., Ltd., Coherent Corp., Applied Spectra Inc., Teledyne CETAC Technologies, IPG Photonics Corporation, Jenoptik AG, AngioDynamics, TRUMPF GmbH + Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laser Ablation Systems Market Strategic Shifts
Beam delivery architectures and pulse control systems are undergoing fundamental redesign as manufacturers balance thermal management against precision requirements across divergent application sets.
Ultrafast laser technology is bifurcating between industrial material processing and medical therapeutic platforms. Industrial systems prioritize average power scaling above 500 watts for throughput in metal and ceramic machining. Medical platforms emphasize pulse-energy stability and beam-profile uniformity for tissue ablation with minimal collateral damage. This divergence is compressing shared component sourcing and forcing suppliers to choose specialization over platform breadth.
The EU F-Gas Regulation is accelerating elimination of gas laser gain media from new system designs. Manufacturers are redirecting engineering resources toward diode-pumped solid-state and fiber architectures that circumvent fluorinated gas consumption reporting and phasedown obligations. Semiconductor fabrication equipment suppliers in Germany and the Netherlands are most affected, with product roadmaps now excluding excimer laser options for die singulation.
Chinese industrial buyers are consolidating vendor relationships around domestic laser suppliers with captive component manufacturing. Han's Laser and Raycus have captured share in metal cutting and welding applications through integrated production of pump diodes, active fibers, and beam delivery systems. This procurement concentration is displacing historical preferences for imported European and Japanese platforms in mid-power industrial segments.
Laser Ablation Systems Market Segmentation
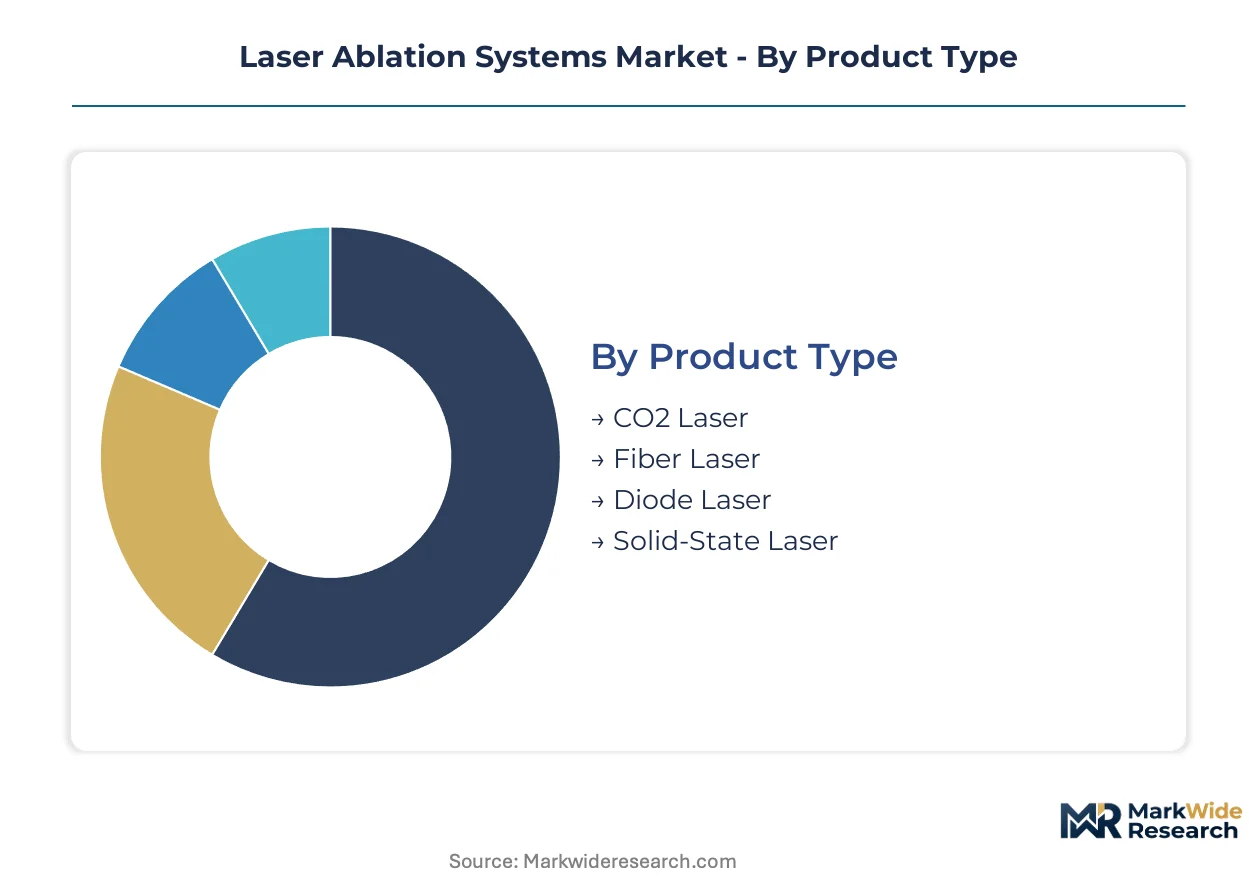
Laser ablation systems fragment across four intersecting dimensions that determine procurement patterns and vendor strategies. Product type and technology architecture dictate capital intensity and maintenance economics, while application and end-user categories shape regulatory pathways and service requirements.
Product Type:
Domestic production clusters dominate fiber and diode laser supply chains in China and South Korea, whereas CO2 and solid-state platforms retain European and North American manufacturing concentration.
- Fiber Laser:These systems employ rare-earth-doped silica fibers as gain media, delivering wall-plug efficiencies exceeding 30% and maintenance intervals above 50,000 hours. Demand concentrates in East Asian electronics manufacturing clusters, particularly for metal cutting and welding applications where Chinese suppliers Han's Laser and Raycus have displaced imported platforms through integrated component production.
- Solid-State Laser:Diode-pumped architectures using Nd:YAG or Yb:YAG crystals eliminate gas consumables entirely. Taiwan Semiconductor Manufacturing and Samsung Foundry drive procurement for die singulation and via drilling, where EU F-Gas Regulation compliance has become a mandatory procurement filter.
- CO2 Laser:Gas-discharge systems using CO2-N2-He mixtures face phasedown pressure under EU F-Gas Regulation, restricting new installations to legacy industrial cutting where thick-metal penetration remains unmatched.
- Diode Laser:Direct-emission architectures from semiconductor junctions occupy low-power material processing and medical therapeutic niches, with German and Japanese suppliers controlling precision beam-shaping optics.
Fiber laser holds the largest share; momentum sits with solid-state laser.
Application:
Medical and semiconductor applications command premium pricing through regulatory certification requirements, while material processing operates on volume-driven cost structures.
- Semiconductor Manufacturing:Stealth dicing of silicon wafers and through-silicon via drilling require sub-picosecond pulse durations to prevent thermal damage to low-k dielectrics. Taiwan and South Korean fabrication facilities are expanding ultrafast laser deployment, replacing mechanical blade methods that generate microcracks in brittle substrates.
- Medical Procedures:FDA 510(k) and CE-marked surgical platforms for tumor resection and ophthalmology command pricing multiples over industrial systems due to clinical validation costs and liability frameworks. The EU MDR's stricter evidence requirements favor established platform holders with existing regulatory portfolios.
- Material Processing:Metal cutting, welding, and surface texturing dominate industrial deployment, with Chinese domestic suppliers capturing mid-power segments through backward integration into pump diodes and active fibers.
- Microelectronics:Printed circuit board drilling, flex circuit processing, and display panel patterning require micron-scale precision, with Japanese and German optics suppliers controlling beam delivery subsystems.
Material processing generates the highest unit volumes; semiconductor manufacturing shows the steepest expansion trajectory.
End User:
Procurement authority and technical specification complexity vary sharply between clinical settings and industrial facilities.
- Industrial Manufacturers:Automotive, aerospace, and electronics fabricators prioritize throughput metrics and total cost of ownership, with maintenance contracts and spare parts availability driving vendor selection. Chinese industrial consolidation around domestic suppliers has reshaped competitive dynamics in metal processing.
- Hospitals:Surgical suites require FDA-cleared or CE-marked platforms with validated clinical protocols, where 18-24 month approval timelines delay revenue recognition for new indications.
- Research Laboratories:National laboratories and corporate R&D centers drive adoption of emerging ultrafast architectures, with funding cycles tied to government research priorities in precision manufacturing and materials science.
- Academic Institutions:University engineering and physics departments train the specialist workforce for nonlinear pulse propagation modeling, though academic program output lags industrial demand for ultrafast laser physicists.
Industrial manufacturers absorb the majority of system shipments; research laboratories are gaining share fastest.
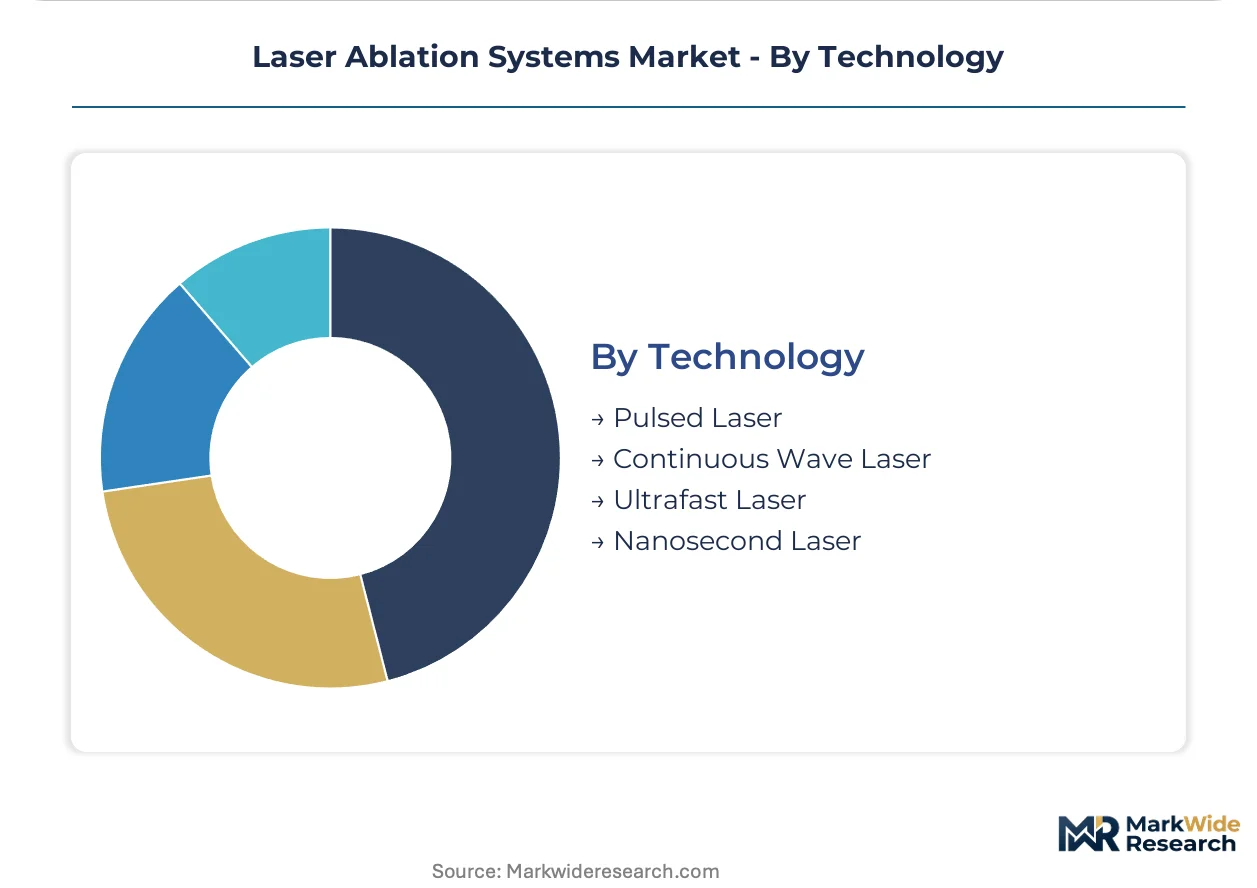
Technology:
Temporal pulse characteristics determine thermal damage thresholds and precision limits across divergent application requirements.
- Ultrafast Laser:Pulse durations below 10 picoseconds minimize thermal diffusion, enabling damage-free processing of brittle dielectrics. Taiwan Semiconductor Manufacturing and Samsung Foundry deployment for advanced packaging drives the fastest-expanding technology segment.
- Pulsed Laser:Nanosecond and microsecond architectures balance peak power against cost, dominating industrial marking and engraving where sub-micron precision is unnecessary.
- Nanosecond Laser:Intermediate pulse durations serve cost-sensitive precision applications, though semiconductor fabs are displacing these systems with ultrafast alternatives for critical die singulation.
- Continuous Wave Laser:Uninterrupted emission suits thermal-based material removal and medical coagulation procedures, with fiber architectures displacing CO2 systems in metal cutting above 6 millimeters thickness.
Pulsed laser retains installed base dominance; ultrafaser laser is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Japanese optics clusters, while Chinese system integrators compress margins through captive component manufacturing. Taiwan and South Korean semiconductor fabs command premium ultrafast specifications. Indian production-linked incentives are attracting first-time procurement without incumbent vendor relationships.
United States
FDA 510(k) clearance requirements shape surgical laser platform development timelines and clinical validation costs. EPA air emissions standards govern industrial installation protocols for high-power fiber systems deployed in metalworking facilities. Research laboratories in the Boston-Cambridge corridor drive adoption of emerging ultrafast architectures for precision manufacturing applications.
Germany
EU F-Gas Regulation redirects engineering resources toward diode-pumped solid-state architectures that circumvent fluorinated gas consumption reporting. TRUMPF GmbH + Co. KG leverages captive manufacturing of pump diodes and optical fibers to control cost structures across industrial cutting platforms. The Stuttgart-Karlsruhe manufacturing belt concentrates ultrafast laser physicist talent and precision optics production.
China
Domestic suppliers Han's Laser and Raycus capture rising share through backward integration into pump diodes and active fibers. The country's dual carbon goals accelerate elimination of gas laser gain media from new system designs. Yangtze River Delta electronics manufacturing clusters are consolidating vendor relationships around domestic laser suppliers with captive component manufacturing.
South Korea
Samsung Foundry expands ultrafast laser deployment for stealth dicing of silicon wafers, replacing mechanical blade methods that generate microcracks. MFDS medical device regulations create barriers for new surgical platform entrants, favoring established holders with existing regulatory portfolios. The Seoul-Suwon semiconductor corridor drives procurement for through-silicon via drilling in 3D NAND and advanced logic stacks.
India
Production-linked incentive schemes for semiconductor and display fabrication attract greenfield fab investments requiring first-time laser ablation system procurement. BIS standards compliance shapes equipment import protocols and domestic assembly requirements. Karnataka and Tamil Nadu electronics manufacturing zones are emerging as procurement centers without historical vendor relationships to displace.
Laser Ablation Systems Market Competitive Environment
Concentration sits with diversified photonics conglomerates and specialized component suppliers. German and Japanese optics clusters dominate production of ultrafast laser crystals, beam delivery fibers, and precision optics. Three archetypes define competitive positioning: integrated photonics conglomerates with captive component manufacturing, specialized ultrafast system suppliers serving semiconductor fabrication, and domestic Chinese suppliers with backward integration into pump diodes and active fibers. M&A activity targets ultrafast laser physicist talent pools and precision optics capabilities, while strategic partnerships bridge gaps in beam delivery subsystem access.
Among German-based diversified manufacturers, TRUMPF GmbH + Co. KG and Jenoptik AG exemplify the integrated photonics conglomerate archetype through captive control over critical component supply chains. Coherent Corp. occupies a position spanning laser crystals to complete system assembly, anchoring representation of the broad vertical reach archetype in semiconductor fabrication tools. Han's Laser Technology Industry Group Co., Ltd. sits within the domestic Chinese supplier tier, representing backward integration strategies that compress system costs through in-house production of pump diodes and active fibers.
| Leading Market Players |
|---|
| Lumentum Holdings Inc. |
| Han's Laser Technology Industry Group Co., Ltd. |
| Coherent Corp. |
| Applied Spectra Inc. |
| Teledyne CETAC Technologies |
| IPG Photonics Corporation |
| Jenoptik AG |
| AngioDynamics |
| TRUMPF GmbH + Co. KG |
| Others |
Value Chain & Pricing Dynamics
Fiber laser architectures displacing gas-based CO2 systems simultaneously relocate supply geography toward East Asian electronics clusters and compress pricing premiums for legacy European platforms. This substitution dynamic concentrates component procurement around Chinese pump diode manufacturers while eroding the cost advantage once held by German and Japanese gas laser specialists.
Pricing Analysis
Configured-to-order pricing for semiconductor-grade ultrafast systems commands spreads exceeding standard industrial fiber laser platforms by factors tied to pulse stability specifications and cleanroom installation protocols. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and after-sales service bundling, with FDA-cleared medical platforms attracting the least price-sensitive buyers and commodity metal-cutting applications showing acute sensitivity to total cost of ownership. Cost compression in mid-power industrial tiers is intensifying because Han's Laser and Raycus leverage in-house production of active fibers and beam delivery systems. Semiconductor fabs in Taiwan and South Korea exhibit minimal price sensitivity for die singulation equipment where thermal damage thresholds determine procurement authority.
Supply Chain Analysis
Germany and Japan anchor production of ultrafast laser crystals, precision optics, and beam-shaping subsystems that feed system integrators worldwide. Manufacturing draws from rare-earth element processing concentrated in China, high-purity synthetic crystal growth in German Stuttgart-Karlsruhe corridor facilities, and specialty beam delivery fibers from Japanese suppliers. Single-source vulnerability in nonlinear optical crystals creates exposure to export licensing restrictions or geopolitical disruption of germanium and yttrium supply channels. Distribution runs through direct OEM relationships for semiconductor fabrication equipment, with industrial metal-processing segments served by regional distributor networks carrying spare parts inventory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Laser ablation system incumbents face substitution defense imperatives as plasma etching technologies press pricing in commodity via formation and Chinese domestic suppliers erode mid-power industrial margins.
For Market Incumbents: Shield proprietary ultrafast laser physicist talent pools through competitive compensation and academic partnership pipelines, as human capital scarcity constrains system development velocity for competitors. Deepen upstream control over pump diode manufacturing to match Chinese cost structures in industrial segments while preserving premium positioning in semiconductor and medical tiers threatened by plasma etching substitution. For New Entrants and Emerging Players: Lead with LIBS-analytical convergence applications in automated scrap metal sorting, where real-time elemental analysis demand outpaces established vendor coverage and regulatory tailwinds from EU recycling mandates accelerate procurement. Target India's production-linked incentive zones for semiconductor fabrication, where greenfield fab investments lack incumbent vendor relationships and BIS compliance pathways remain navigable for first-time entrants. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed precision optics specialists holding captive capabilities in nonlinear crystal growth and dispersion-compensating fiber production. Long-term viability hinges on exposure to semiconductor capital expenditure cycles rather than industrial metal-processing commoditization. Monitor EU F-Gas Regulation enforcement intensity as inflection indicator for accelerated CO2 laser replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Ultrafast Laser Physicist Acquisition | Captures scarce talent capable of modeling nonlinear pulse propagation for next-generation semiconductor processing platforms. |
| Pump Diode Backward Integration | Matches Chinese cost structures in industrial segments through in-house production of active fiber gain media. |
| LIBS-Analytical Platform Launch | Opens materials recycling applications beyond traditional manufacturing through real-time elemental analysis integration. |
| India Greenfield Fab Partnership | Establishes vendor relationships in PLI scheme zones without displacement of entrenched incumbent supply contracts. |
| F-Gas Compliance Certification | Qualifies systems for EU semiconductor fabrication procurement where fluorinated gas elimination is mandatory. |
Study Parameters
A standing panel of semiconductor fabrication equipment procurement managers, ultrafast laser system engineers, hospital biomedical technology directors, and industrial maintenance supervisors provided ongoing calibration across primary interview cycles. Secondary validation drew from SEC filings of listed photonics conglomerates, IEC 60825 laser safety standard revision documentation, EU F-Gas Regulation implementation reports, and customs data tracking rare-earth element trade flows. Bottom-up unit demand modeling triangulated against top-down capital expenditure projections from Taiwan Semiconductor Manufacturing and Samsung Foundry disclosure patterns.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions spanning product architecture, pulse duration technology, application vertical, end-user category, and regional regulatory cluster. CAGRs derived from fitted growth curves anchored to disclosed equipment procurement timelines and replacement cycle assumptions for gas laser phaseout. Industry-specific forecast inputs included EU MDR clinical evidence requirement timelines and MFDS medical device approval pathway durations.
Forecasts assume regulatory continuity in EU F-Gas phasedown schedules and FDA 510(k) clearance protocols; material policy shifts would require re-modeling of replacement demand timing and clinical validation cost structures. Specific risks include accelerated EU MDR enforcement compressing surgical platform development timelines and export restriction expansion affecting germanium crystal supply channels. Recalibration cycles align with material shifts in semiconductor capital expenditure announcements and EU regulatory implementation guidance updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Global Twister Winder Market
Industrial Equipment
Global Refrigeration Compressor Market
Industrial Equipment
Global Industrial Weighing Machines Market
Industrial Equipment
Industrial Joysticks Market
Industrial Equipment
Vacuum Concentrators Market
Industrial Equipment
Industrial I/O Modules Market
Industrial Equipment
Global High Power Laser Systems Market
Industrial Equipment
Air Bearings Market
Industrial Equipment
Asia-Pacific Industrial Centrifuge Market
Industrial Equipment
Cable Granulator Market
Industrial Equipment
Resistance Spot Welding Machines Market
Industrial Equipment
Global Fans and Blowers Market
Industrial Equipment
Air Bearing Spindle Market
Industrial Equipment
Fluid Dispensing Equipment Market
Industrial Equipment
Europe Ceramic Roller Bearings Market
Industrial Equipment
Asia-Pacific Fans and Blowers Market