
 Asia-Pacific Electro Hydraulic Servo Valve Market | 2026-2036
Asia-Pacific Electro Hydraulic Servo Valve Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Electro Hydraulic Servo Valve Market Outlook
Modular valve-integrated manifold assemblies is restructuring how industrial buyers configure hydraulic systems across Asia-Pacific facilities. YUKEN KOGYO CO., LTD leverages its domestic manufacturing footprint to dominate precision valve supply for Japanese machine tool builders. AVIC Nanjing Servo Control System Co., Ltd. anchors military-aerospace demand through captive supply relationships with Chinese state aviation programs. Bosch Rexroth competes by extending its German-engineered servo valve architectures into localized assembly operations serving Southeast Asian automotive press lines.
An electro hydraulic servo valve converts low-power electrical signals into precise hydraulic fluid flow and pressure modulation, typically achieving response frequencies above 100 Hz with contamination sensitivity below 5 microns. These valves govern position, velocity, and force in closed-loop automation systems where mechanical accuracy determines output quality. Directional valves occupy the largest product category as legacy infrastructure replacement cycles sustain steady procurement across mature industrial bases. Digital control operation modes represent the fastest-expanding segment as Chinese and South Korean machinery OEMs integrate Industry 4.0 architectures into new press and mold equipment. Proportional valves concentrate margin pools in aerospace and defense applications where certification barriers limit supplier entry.
China's SAMR enforces GB/T hydraulic equipment standards that dictate fatigue testing protocols and material traceability for valves deployed in critical infrastructure. Japan's METI administers JIS B 8355 specifications covering servo valve dynamic performance validation, while South Korea's MFDS coordinates with industrial safety regulators on pressure equipment conformity assessment. Compliance with these overlapping national standards shapes product development roadmaps and creates differentiated market access tiers for domestic versus foreign manufacturers. Stakeholders must monitor evolving carbon accounting rules under each country's dual carbon commitments, as embodied emissions in valve casting and machining processes face emerging disclosure requirements that will reshape supplier qualification criteria.
Market Dynamics
Modular manifold assemblies are compressing system integration timelines across Asia-Pacific aerospace and automotive production lines, forcing valve suppliers to reconfigure from component sales to subsystem partnerships.
Growth Catalysts
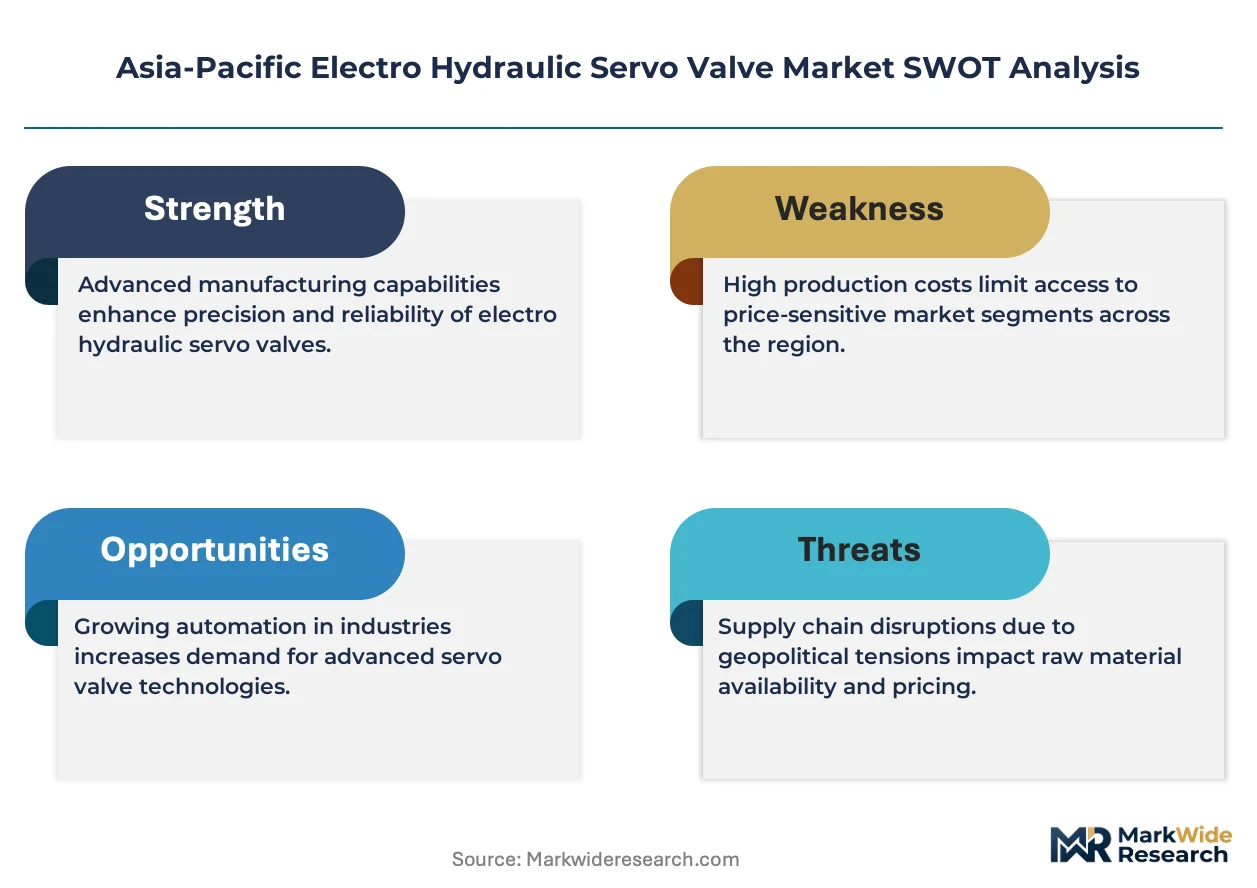
- GB/T Fatigue Testing Mandates:China's SAMR enforcement of material traceability protocols for critical infrastructure valves is accelerating replacement cycles in aging hydraulic systems across eastern manufacturing corridors.
- Machine Tool Precision Demands:Japanese builders of five-axis machining centers are specifying servo valves with sub-micron positioning repeatability, pulling high-bandwidth proportional designs into standard equipment configurations.
- Digital Control Architectures:Industry 4.0 integration by South Korean press and mold OEMs is unifying valve electronics with edge computing nodes, creating specification premiums for Ethernet-enabled servo interfaces.
Market Restraints
- Contamination Sensitivity:Sub-5-micron filtration requirements for high-response valves impose recurring maintenance burdens and consumables costs that compress total cost-of-ownership margins for smaller fabricators.
- Casting Supply Concentration:Specialized ductile iron foundries capable of aerospace-grade material certification cluster in China's Shandong and Hebei provinces, creating geographic chokepoints for valve body sourcing.
- Electromechanical Substitution:Linear motor actuators are displacing hydraulic positioners in cleanroom semiconductor fabrication equipment, eroding addressable demand in South Korea's expanding wafer processing base.
Strategic Opportunities
- Vietnam's Automotive Press Expansion:Japanese and South Korean tier-one suppliers are localizing stamping operations near Haiphong, creating first-mover openings for servo valve distributors with localized technical service capabilities.
- JIS B 8355 Certification Arbitrage:Foreign manufacturers achieving METI-validated dynamic performance credentials can access premium pricing tiers in Japan's replacement parts market currently dominated by domestic incumbents.
- Dual Carbon Disclosure Requirements:China's emerging embodied emissions accounting rules for industrial equipment procurement are creating preference windows for valve suppliers with verified low-carbon machining and heat treatment processes.
Industry Challenges
- Fluid Power Engineering Talent Scarcity:Universities across the Asia-Pacific region have reduced hydraulic systems curricula, constraining OEMs' ability to staff field application engineering roles for complex closed-loop integration.
- Multi-Standard Compliance Burden:Simultaneous GB, JIS, and MFDS certification timelines extend product launch cycles by 14-22 months for valves targeting cross-border aerospace supply chains.
- Legacy System Integration Friction:Analog-interface valves installed in 1990s-era Japanese injection molding equipment resist retrofit with modern digital controllers, fragmenting upgrade pathways and service revenue models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Electro Hydraulic Servo Valve Market |
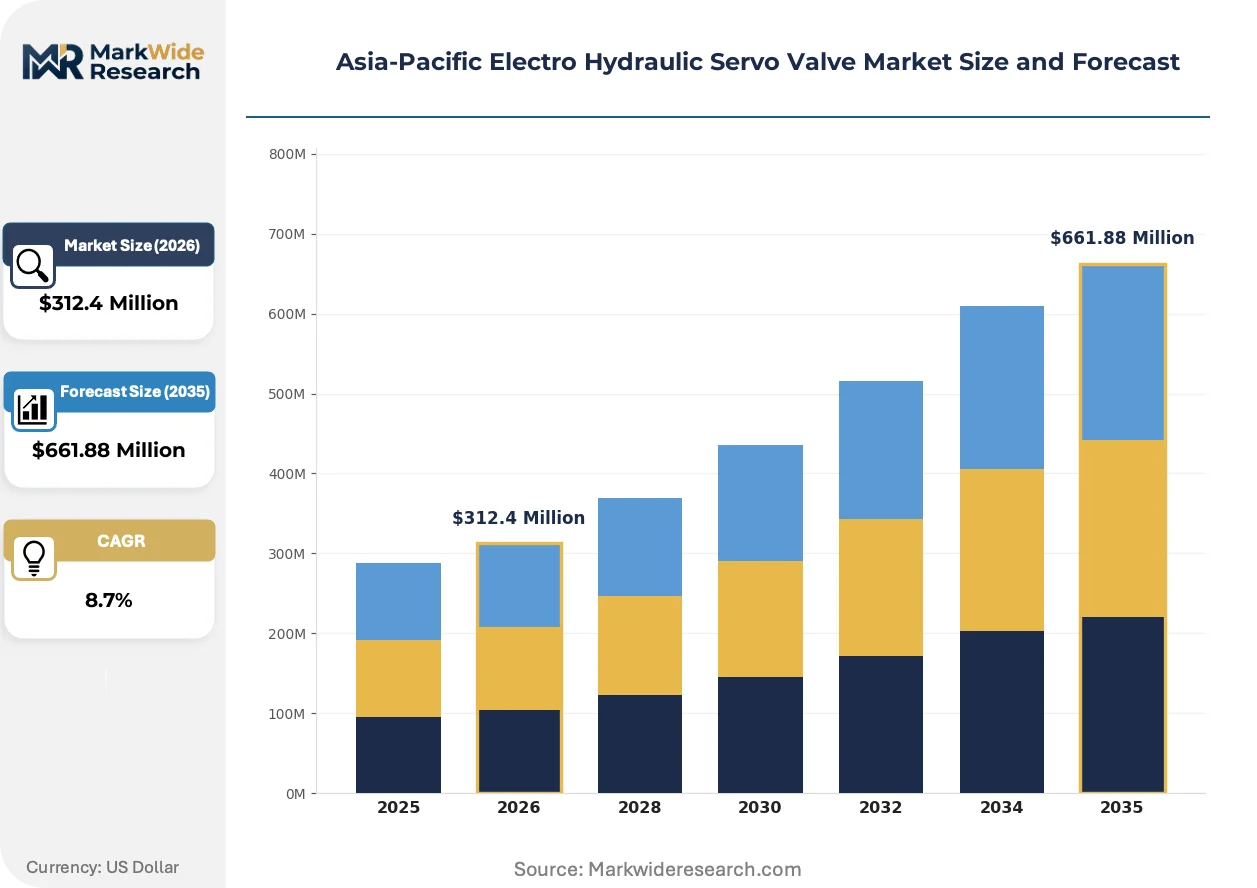
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Proportional Valves, Directional Valves, Flow Control Valves, Pressure Relief Valves End User: Aerospace, Automotive Manufacturers, Industrial Machinery, Marine Applications Installation Type: Onshore, Offshore, Integrated Systems, Standalone Units Operation Mode: Digital Control, Analog Control, Manual Control, Remote Control |
| Companies Covered | YUKEN KOGYO CO., LTD, AVIC Nanjing Servo Control System Co., Ltd., Shanghai Norma Hydraulic System Co., Ltd., BMTI Precision Mechatronics, Moog India, Qinfeng Hydraulic, Bosch Rexroth, Parker Hannifin, Eaton, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Electro Hydraulic Servo Valve Market Strategic Shifts
Electromechanical-hydraulic convergence is dissolving traditional boundaries between valve hardware and control electronics, compressing supplier value capture toward embedded firmware and predictive diagnostics.
Integrated valve-manifold assemblies with embedded pressure and position sensors are unifying distributed sensing with centralized control in aerospace flight surface actuation systems. Chinese COMAC suppliers and Japanese defense contractors are specifying these compact configurations to reduce hydraulic line count and leak points. The technology is unifying what were previously separate component procurement decisions into single-source subsystem awards, consolidating supplier relationships around integrated design capabilities.
METI's tightened energy efficiency directives under Japan's Green Transformation framework are mandating dynamic performance validation for servo valves deployed in industrial presses above 500-ton capacity. The regulation is forcing valve manufacturers to submit third-party test data documenting flow-pressure hysteresis and frequency response under varying thermal loads. Aerospace and heavy equipment segments are responding by pre-qualifying suppliers with established JIS B 8355 certification histories, compressing the vendor pool for new program awards.
Chinese machinery OEMs are consolidating hydraulic component purchasing through centralized procurement platforms operated by industry associations in Jiangsu and Zhejiang provinces. The platform model is disintermediating traditional distributor networks and exposing valve suppliers to direct price benchmarking against domestic competitors. This concentration is most visible in injection molding and die-casting equipment manufacturing, where procurement committees now specify annual volume commitments in exchange for fixed pricing tiers and localized technical support obligations.
Asia-Pacific Electro Hydraulic Servo Valve Market Segmentation
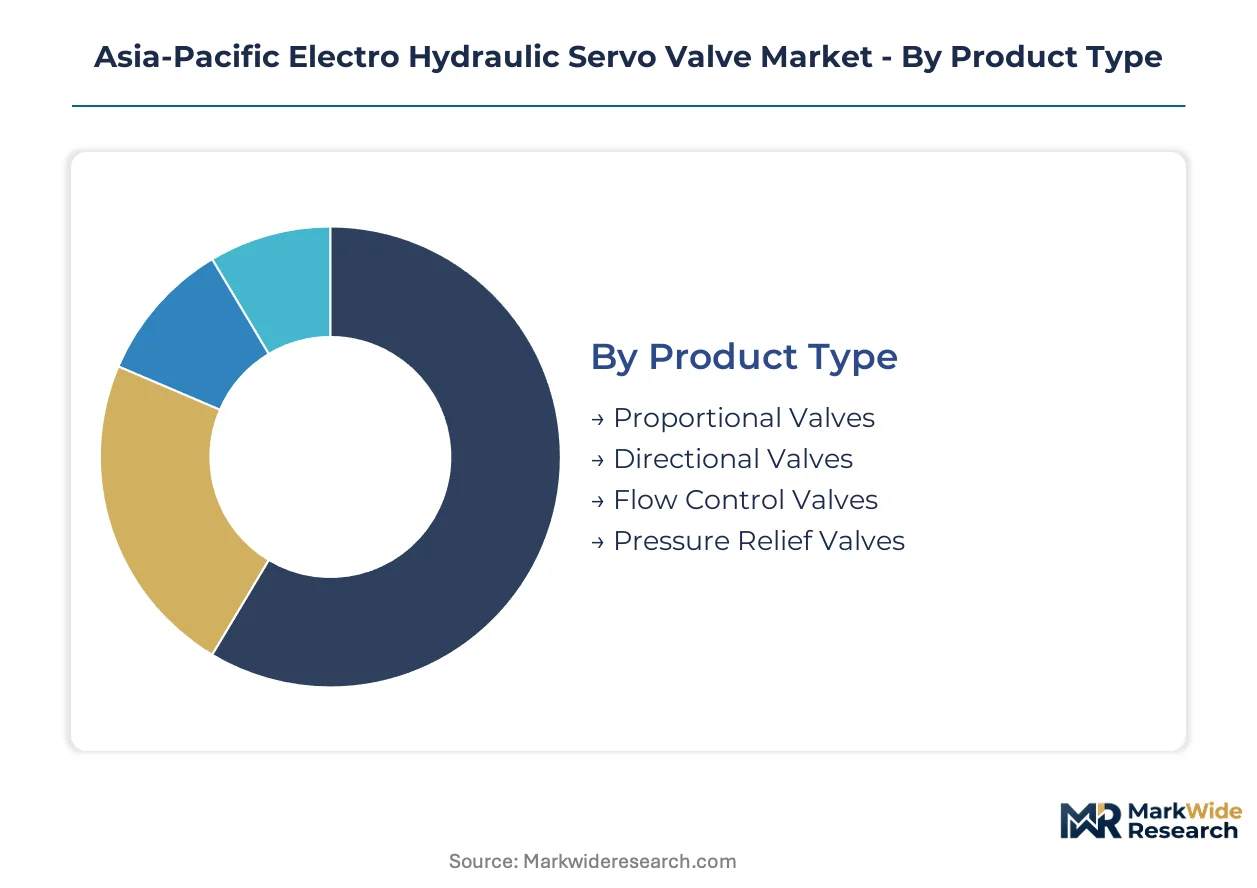
Segmentation in the Asia-Pacific electro hydraulic servo valve market reveals how procurement patterns cluster around certification requirements, integration complexity, and end-use precision demands. Suppliers configure product portfolios differently across these dimensions to match the technical and commercial priorities of aerospace, automotive, and industrial machinery buyers.
Product Type:
Supply concentration among specialized foundries in China's Shandong and Hebei provinces shapes which valve architectures achieve cost-competitive scale.
- Directional Valves:These components manage fluid flow path switching through spool-and-sleeve mechanisms with response times under 10 milliseconds. Replacement cycles in Japan's aging injection molding base and China's eastern manufacturing corridor sustain steady procurement volumes despite slower growth rates.
- Proportional Valves:Continuous-position control enables sub-micron positioning repeatability for five-axis machining centers built by Japanese OEMs. Aerospace and defense applications concentrate margin pools here because GB/T fatigue testing and JIS B 8355 certification barriers limit qualified supplier entry.
- Flow Control Valves:Meter-in and meter-out configurations govern actuator velocity in automotive press lines across Vietnam's expanding Haiphong industrial zone.
- Pressure Relief Valves:Safety-critical deployment in marine hydraulic systems requires compliance with multiple national pressure equipment directives.
Directional valves absorb the bulk of installed capacity; proportional valves are expanding most quickly.
End User:
Cost tier differentiation separates specification-grade procurement for aerospace from volume-driven automotive purchasing.
- Aerospace:Flight surface actuation and landing gear systems demand integrated valve-manifold assemblies with embedded sensing to reduce hydraulic line count. COMAC suppliers and Japanese defense contractors pre-qualify vendors around JIS B 8355 certification histories, compressing the approved supplier pool.
- Automotive Manufacturers:Stamping press automation in China and Vietnam drives demand for high-cycle directional valves with Ethernet-enabled servo interfaces. South Korean and Japanese tier-one suppliers localize production near Haiphong, creating technical service requirements for valve distributors.
- Industrial Machinery:Machine tool builders in Japan specify servo valves for five-axis machining centers where mechanical accuracy determines output quality.
- Marine Applications:Offshore platform hydraulic systems require corrosion-resistant configurations meeting multiple national pressure equipment conformity assessments.
Aerospace commands premium pricing tiers; automotive manufacturing delivers volume scale.
Installation Type:
Application complexity determines whether buyers prioritize modular integration or standalone flexibility.
- Integrated Systems:Valve-integrated manifold assemblies unify distributed sensing with centralized control in aerospace flight surface actuation. Chinese and Japanese contractors specify these compact configurations to eliminate leak points and reduce maintenance access requirements.
- Standalone Units:Discrete valve procurement persists in legacy Japanese injection molding equipment from the 1990s, where analog interfaces resist retrofit with modern digital controllers.
- Onshore:Manufacturing facility installations concentrate in China's Jiangsu and Zhejiang province industrial clusters.
- Offshore:Marine and subsea deployments require specialized sealing and pressure compensation architectures.
Integrated systems capture new program awards; standalone units dominate replacement demand.
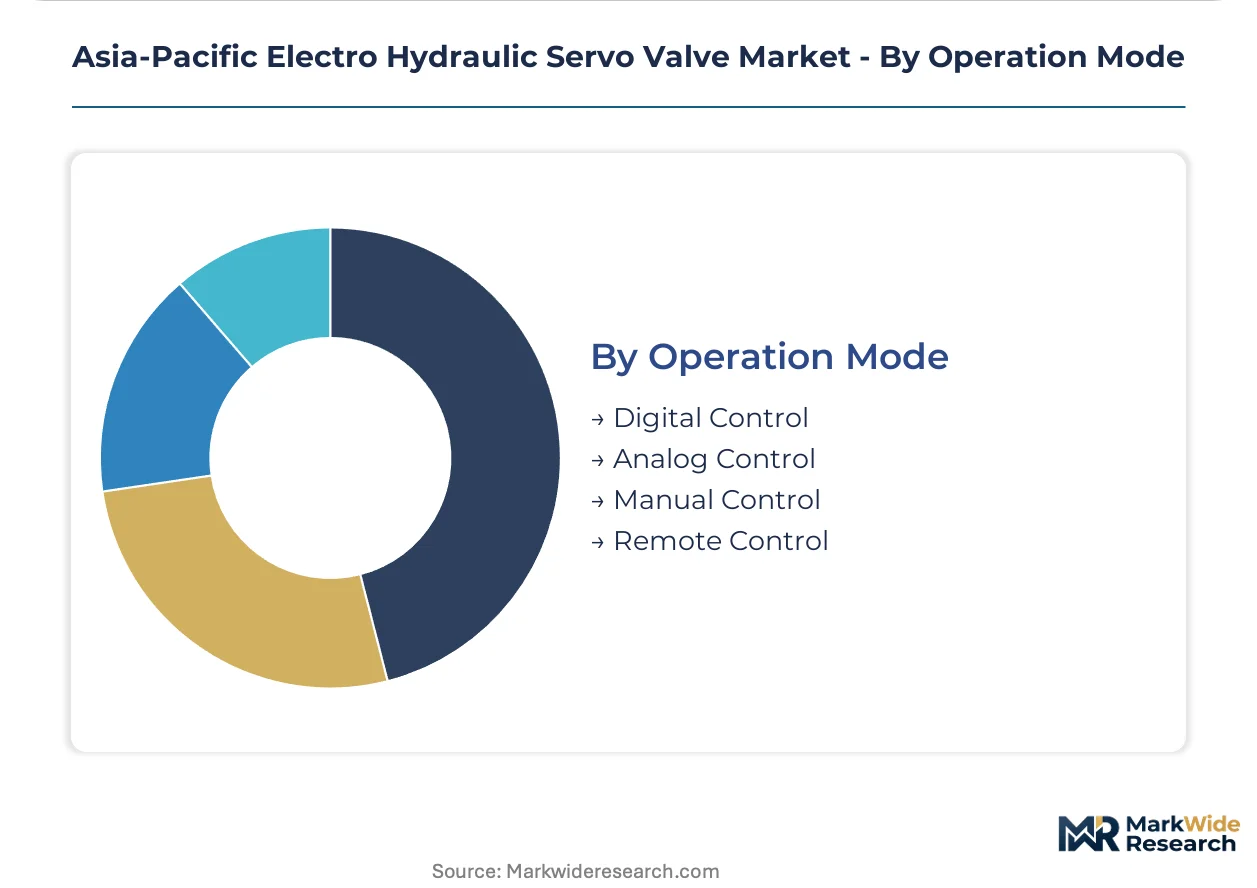
Operation Mode:
Customer type separates digital-ready machinery OEMs from maintenance buyers preserving analog infrastructure.
- Digital Control:Ethernet-enabled servo interfaces unify valve electronics with edge computing nodes in South Korean press and mold equipment. Industry 4.0 integration by Chinese and South Korean machinery OEMs creates specification premiums for networked valve architectures.
- Analog Control:Voltage-current signal processing persists in legacy Japanese injection molding equipment where retrofit costs fragment upgrade pathways. Maintenance departments in mature industrial bases sustain procurement of compatible replacement units.
- Manual Control:Direct operator adjustment remains specified for emergency override functions in marine and heavy equipment applications.
- Remote Control:Distributed hydraulic management in offshore platforms enables centralized monitoring from control rooms.
Analog control retains installed base dominance; digital control is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yangshan Deep Water Port's bonded logistics zone concentrates hydraulic component distribution for eastern China's machine tool builders. Vietnam's Chu Lai Open Economic Zone attracts Japanese and South Korean automotive press manufacturers seeking tariff-advantaged export platforms.
China
COMAC's C919 production ramp drives integrated valve-manifold procurement for flight surface actuation systems. SAMR enforces GB/T fatigue testing protocols that accelerate replacement cycles in aging hydraulic infrastructure. Jiangsu and Zhejiang province industrial clusters host centralized procurement platforms disintermediating traditional distributor networks.
Japan
Five-axis machining center builders specify sub-micron positioning repeatability from high-bandwidth proportional valve designs. METI administers JIS B 8355 specifications covering dynamic performance validation under varying thermal loads. Kanto region machine tool manufacturers pre-qualify vendors around established certification histories.
South Korea
Press and mold OEMs integrate Industry 4.0 architectures unifying valve electronics with edge computing nodes. MFDS coordinates with industrial safety regulators on pressure equipment conformity assessment. Seoul Capital Area machinery builders create specification premiums for Ethernet-enabled servo interfaces.
Vietnam
Japanese and South Korean tier-one suppliers localize stamping operations near Haiphong for regional automotive supply chains. The country's industrial zone incentives reduce landed cost for precision hydraulic components. Northern province manufacturing corridors generate first-mover openings for valve distributors with localized technical service capabilities.
India
Domestic aerospace programs expand procurement of precision hydraulic actuation systems for indigenous platform development. The national aerospace regulator mandates material traceability protocols for flight-critical components. Bangalore and Hyderabad defense manufacturing clusters concentrate subsystem integration activity.
Asia-Pacific Electro Hydraulic Servo Valve Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across certification-tiered market segments. The structure fragments into three tiers: domestic incumbents with captive state-aerospace relationships, multinational industrial automation groups with localized assembly operations, and regional distributors with technical service capabilities. Strategic moves concentrate on JIS B 8355 certification arbitrage for premium pricing access and backward integration into specialized foundry capacity for aerospace-grade material certification.
Within the domestic incumbent tier, AVIC Nanjing Servo Control System Co., Ltd. exemplifies captive supply positioning aligned with state aviation programs. YUKEN KOGYO CO., LTD represents precision-focused manufacturing archetypes serving domestic machine tool builders. Bosch Rexroth occupies a position among multinational industrial automation groups extending German-engineered architectures into localized assembly operations. These three anchors illustrate how competitive positioning stratifies across certification access, manufacturing geography, and end-use specialization.
| Leading Market Players |
|---|
| YUKEN KOGYO CO., LTD |
| AVIC Nanjing Servo Control System Co., Ltd. |
| Shanghai Norma Hydraulic System Co., Ltd. |
| BMTI Precision Mechatronics |
| Moog India |
| Qinfeng Hydraulic |
| Bosch Rexroth |
| Parker Hannifin |
| Eaton |
| Others |
Value Chain & Pricing Dynamics
Modular manifold-integrated valve architectures are compressing procurement economics across Asia-Pacific aerospace and automotive facilities, simultaneously reducing per-unit component counts while concentrating supplier relationships around subsystem-integrated vendors with captive foundry capacity. This production-method transition rewards valve manufacturers with backward control over specialized ductile iron casting and JIS B 8355 certification infrastructure, while fragmenting pricing power among standalone component suppliers lacking integrated design capabilities.
Pricing Analysis
Short lead-time premiums for JIS B 8355-certified proportional valves command substantial markups over spot inventory of standard directional configurations, reflecting certification backlog timelines and aerospace pre-qualification requirements. Three-tier pricing structure across premium certified, standard industrial, and economy unbranded levels separates procurement for COMAC flight systems from Chinese injection molding replacement cycles. Cost compression in the standard tier is intensifying because centralized procurement platforms in Jiangsu and Zhejiang provinces expose foreign suppliers to direct domestic price benchmarking. Tier-one automotive press manufacturers in Vietnam exhibit lowest price sensitivity due to technical service dependencies, while small Chinese fabricators prioritize economy units despite higher lifecycle maintenance burdens.
Supply Chain Analysis
Refurbishment flows for legacy analog-interface valves installed in 1990s-era Japanese injection molding equipment sustain aftermarket revenue streams and buffer primary demand volatility for established suppliers. Geographic supply concentration centers on China's Shandong and Hebei provinces for aerospace-grade ductile iron castings, Japan's Kanto region for precision spool-and-sleeve machining, and South Korea's Seoul Capital Area for Ethernet-enabled electronic valve interfaces. Raw material dependencies draw from rare earth elements for permanent magnet torque motors, high-purity hydraulic fluids meeting METI energy efficiency specifications, and specialized elastomers for subsea sealing architectures. Single-source vulnerability pervades the certified foundry tier where only three Chinese facilities achieve COMAC material traceability protocols. Distribution runs through bonded logistics zones at Yangshan Deep Water Port and localized technical service partnerships near Vietnam's Haiphong industrial corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific electro hydraulic servo valve market sits in a technology-transition phase where digital Ethernet-enabled architectures displace legacy analog signal processing, forcing supplier repositioning around embedded firmware and predictive diagnostics capabilities.
For Market Incumbents: Anchor certification infrastructure against electromechanical substitution threats from linear motor actuators in South Korean semiconductor fabrication. Prioritize JIS B 8355 dynamic performance validation investments to defend premium positioning in Japan's replacement parts market, while extending captive foundry capacity in Shandong province to secure aerospace-grade material certification against Chinese SAMR fatigue testing mandates. For New Entrants and Emerging Players: The premium-to-economy price-point gap in Vietnam's automotive press expansion offers white-space entry for distributors with localized technical service capabilities. Target South Korean machinery OEMs integrating Industry 4.0 architectures as the most penetrable segment for Ethernet-enabled servo interfaces. Pursue JIS B 8355 certification arbitrage as the primary go-to-market angle to access pricing tiers currently captured by domestic Japanese incumbents. For Investors and Strategic Acquirers: Re-rating potential sits with integrated valve-manifold specialists given METI's tightened energy efficiency directives mandating dynamic performance validation for industrial presses above 500-ton capacity. Long-term viability across the projection horizon favors suppliers with verified low-carbon machining processes aligned with China's emerging embodied emissions disclosure requirements. Monitor COMAC C919 production ramp rates and Jiangsu procurement platform volume commitments as inflection indicators for subsystem-integrated vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| JIS B 8355 Certification Investment | METI validation unlocks premium pricing tiers in Japan's replacement parts market. |
| Backward Integration into Foundry Capacity | Captive supply of aerospace-grade ductile iron secures SAMR material traceability compliance. |
| Digital Control Architecture Development | Ethernet-enabled interfaces capture specification premiums from South Korean Industry 4.0 integration. |
| Localized Technical Service Expansion | Haiphong-based support capabilities address Vietnamese automotive press manufacturer requirements. |
| Low-Carbon Process Verification | Verified emissions accounting meets China's dual carbon procurement preference windows. |
Study Parameters
Trade customs databases, METI regulatory filings, and COMAC supplier qualification records formed the secondary backbone for demand sizing and certification timeline analysis. Primary interviews with maintenance directors at Japanese machine tool builders, procurement leads at Chinese injection molding OEMs, aftermarket service heads at hydraulic distributors, and fluid power engineering specialists at South Korean press manufacturers combined with secondary validation to triangulate bottom-up and top-down market estimates.
Bottom-up segmentation modeling across product type, end user, installation configuration, and operation mode anchored volume and value outputs throughout the forecast period. Analytical frameworks incorporated valve response frequency specifications, contamination sensitivity thresholds, and GB/T fatigue testing protocol adoption curves as industry-specific forecast inputs alongside macroeconomic industrial production indices. CAGRs were derived from segment-level growth rate reconciliation against aggregate market trajectory constraints.
Inputs from SAMR regulatory disclosure databases and METI Green Transformation directive documentation were available through the study window; gaps in real-time centralized procurement platform transaction data from Jiangsu and Zhejiang provinces introduce uncertainty bands around Chinese domestic demand estimates. Forecasts reflect assumptions regarding Industry 4.0 adoption velocity and electromechanical substitution rates in cleanroom applications. Practitioners should monitor COMAC production schedule announcements, METI energy efficiency directive enforcement timelines, and Vietnamese automotive FDI registration flows for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Seismic Data Acquisition Equipment Market
Industrial Equipment
Battery Power Tools Market
Industrial Equipment
PCB Punching Machine Market
Industrial Equipment
Demagnetizer Market
Industrial Equipment
Laser Marking Machine Market
Industrial Equipment
Magnetorheological Finishing (MRF) Machine Market
Industrial Equipment
Japan Ceramic Roller Bearings Market
Industrial Equipment
Global High Power Laser Systems Market
Industrial Equipment
Diaphragm Coupling Market
Industrial Equipment
Global Laboratory Vacuum Pumps Market
Industrial Equipment
Grading and Batching Systems Market
Industrial Equipment
Thermoelectric Refrigerator Market
Industrial Equipment
Europe Vacuum Pump Market
Industrial Equipment
Industrial I/O Modules Market
Industrial Equipment
Servo Drive Market
Industrial Equipment
Global Safety Relays and Timers Market