
 Resistance Spot Welding Machines Market | 2026-2036
Resistance Spot Welding Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Resistance Spot Welding Machines Market Outlook
Precision-grade welding specifications are redrawing competitive boundaries in resistance spot welding equipment. Panasonic Welding Systems Co., Ltd. leverages its captive power electronics supply chain to dominate inverter technology development. Miyachi Unitek (AMADA WELD TECH) anchors its position through deep specialization in micro-joining applications for battery tab welding. Lincoln Electric Holdings, Inc. extends its geographic reach through dense distributor networks across North American manufacturing corridors.
Resistance spot welding machines generate localized heat through electrical resistance at the interface of overlapping metal sheets, typically delivering 1,000–20,000 amperes for 5–30 cycles to form a molten nugget without filler material. The process serves as the backbone of high-speed body-in-white assembly lines where cycle times must stay below two seconds per weld. Robotic welders now capture the fastest expansion trajectory as automotive OEMs retool for electric vehicle architectures requiring thousands of precise copper-to-aluminum joints. Stationary welders retain the largest installed base but face margin compression as metal fabrication shops defer replacement cycles. Digital control technology is displacing analog systems in premium installations where real-time adaptive current feedback justifies higher capital outlays.
The EPA enforces energy efficiency benchmarks that favor inverter-based machines over legacy transformer designs, while OSHA electrical safety standards mandate upgraded guarding and isolation systems on new equipment. CE marking under the EU Machinery Directive restricts market access for non-compliant Asian imports, creating protected pricing corridors for European-certified manufacturers. NHTSA structural integrity requirements for crashworthiness indirectly sustain demand for certified weld monitoring systems in US automotive plants. Stakeholders must track how battery chemistry shifts toward solid-state architectures will alter joint geometries and current delivery requirements.
Market Dynamics
Automotive electrification is compressing replacement cycles for legacy AC transformer welders as OEMs retool battery pack lines for copper-aluminum joining precision. This structural force concentrates demand around inverter-based systems with adaptive current control.
Growth Catalysts
- EU Green Deal carbon border adjustments:German Mittelstand fabricators face compliance deadlines that accelerate scrappage of energy-intensive equipment. Inverter machines with verified carbon footprints command procurement preference.
- Solid-state battery architectures:Next-generation cell designs require tab welding at finer geometries with lower heat-affected zones. This specification pull favors precision micro-joining systems.
- OSHA electrical safety standards:Mandated guarding upgrades on new equipment create replacement windows for aging transformer installations across North American metalworking shops.
Market Restraints
- Copper conductor cost volatility:Secondary winding materials expose machine margins to London Metal Exchange price swings. Japanese and Korean suppliers mitigate through long-term cathode contracts.
- Power electronics supply concentration:IGBT and SiC module fabrication clusters in Taiwan and mainland China create single-source vulnerability for inverter assembly lines.
- Laser welding substitution:Fiber laser systems achieve comparable cycle times on thin-gauge aluminum without electrode wear, eroding spot welding's cost advantage in certain EV body applications.
Strategic Opportunities
- India PLI scheme for advanced cell manufacturing:Domestic battery gigafactories under construction in Gujarat and Tamil Nadu require localized welding equipment supply chains.
- Retrofit digital control modules:Analog-to-digital conversion kits extend service life of installed transformer bases while capturing adaptive feedback functionality.
- CE marking as competitive moat:European certification complexity blocks low-cost Asian imports, protecting margin corridors for compliant manufacturers serving EU automotive tier ones.
Industry Challenges
- Weld technician skill attrition:Retirement waves among operators trained on analog timing systems create knowledge gaps for digital parameter optimization.
- ISO 4063 certification timelines:Extended third-party validation periods for new machine designs delay product launches and tie up engineering resources.
- Legacy line integration complexity:Retrofitting adaptive inverter controls into 1990s-era robotic cells requires custom electrical isolation and communication protocol bridging.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Resistance Spot Welding Machines Market |
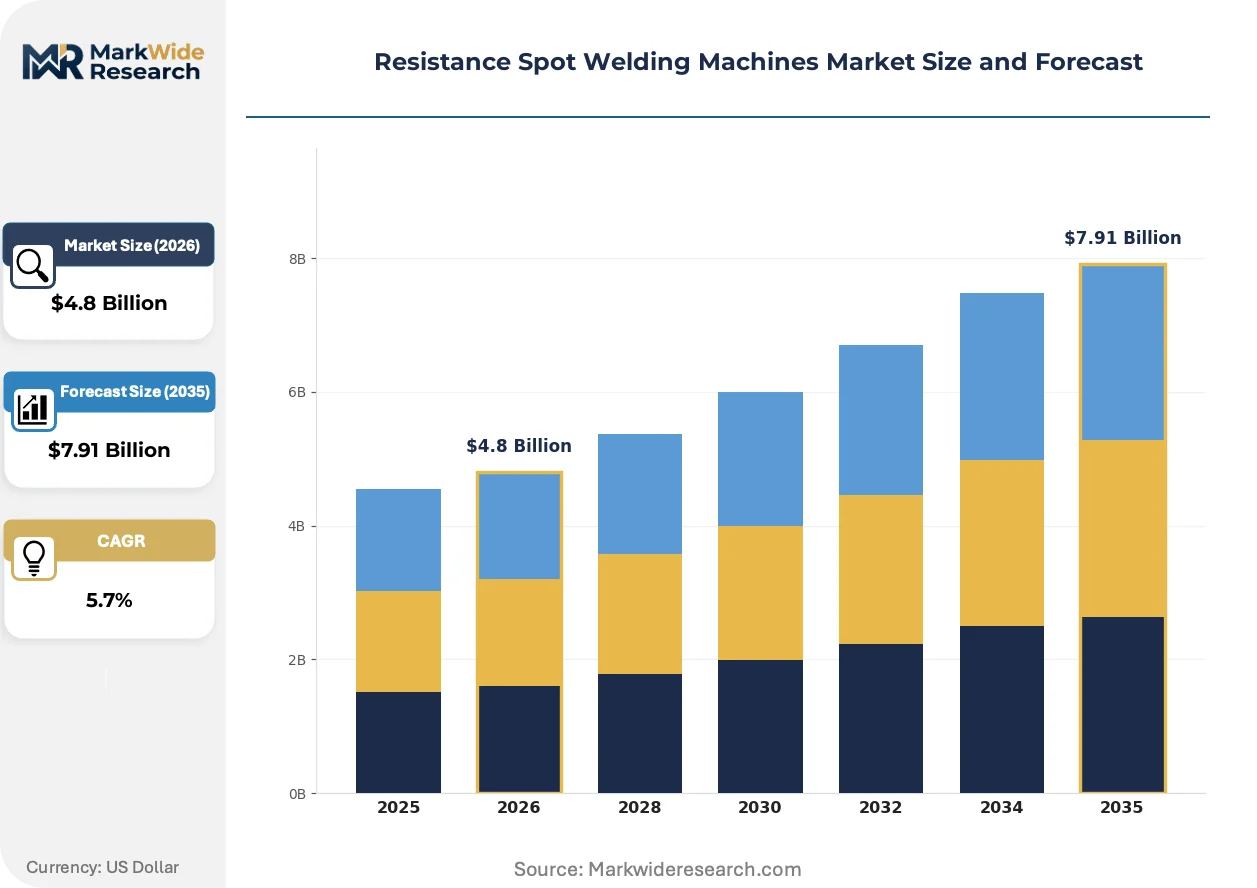
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Welders, Stationary Welders, Multi-Spot Welders, Robotic Welders End User: Automotive OEMs, Aerospace Manufacturers, Electronics Industry, Metal Fabrication Technology: Direct Current, Alternating Current, Inverter Technology, Digital Control Application: Sheet Metal Joining, Component Assembly, Structural Welding, Repair Operations |
| Companies Covered | Panasonic Welding Systems Co., Ltd., Automation International, Inc., CenterLine (Windsor) Ltd., Miyachi Unitek (AMADA WELD TECH), Nimak GmbH, ARO Welding Technologies SAS, Dengensha Manufacturing Co., Ltd., TECNA S.p.A., Lincoln Electric Holdings, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Resistance Spot Welding Machines Market Strategic Shifts
Real-time process monitoring and solid-state power conversion are redefining equipment specifications across automotive and fabrication end-uses. These shifts compress the viable lifecycle of analog-era assets.
Medium-frequency inverter technology is displacing legacy 50/60 Hz transformer designs in high-volume body-in-white installations. Volkswagen Group and Hyundai Motor manufacturing engineers specify 1,000 Hz inverters for aluminum-intensive EV platforms. The technology is displacing conventional AC machines by enabling closed-loop current feedback that maintains nugget consistency across electrode wear cycles.
EPA energy efficiency benchmarks now disqualify transformer-based welders from federal procurement and incentive programs. The regulation compresses replacement demand into a narrower vendor set with certified inverter portfolios. Tier one automotive suppliers in Michigan and Ohio accelerate compliance timelines ahead of enforcement windows.
Outcome-based service contracts are displacing traditional break-fix maintenance arrangements in German and Japanese automotive clusters. Equipment vendors retain ownership of weld monitoring hardware while charging per-qualified-joint fees. This model concentrates in high-volume EV battery lines where uptime guarantees override capital expenditure preferences.
Resistance Spot Welding Machines Market Segmentation
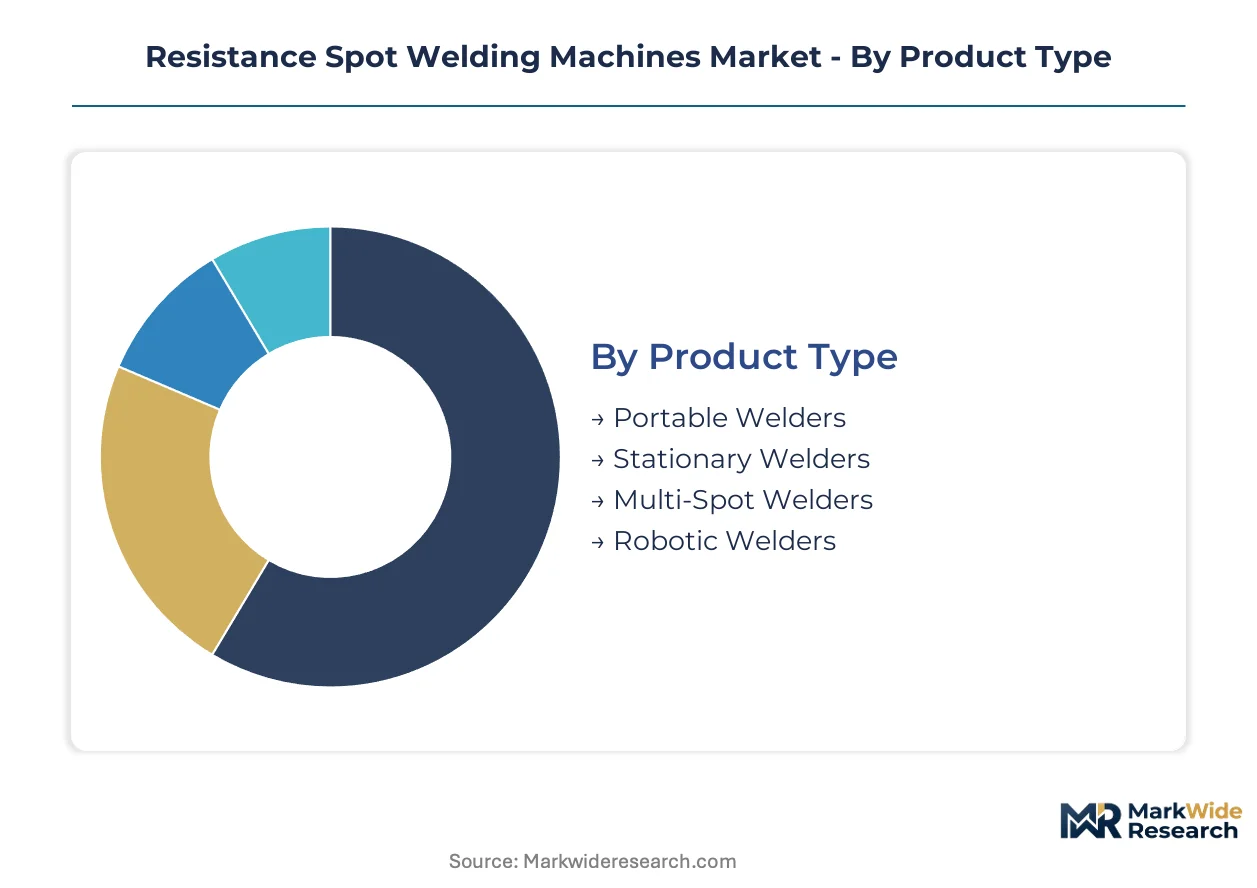
Segmentation in resistance spot welding machines reveals where substitution pressures and technology transitions concentrate investment flows. Each dimension exposes different vulnerability to laser welding displacement, inverter technology migration, and regional regulatory enforcement.
Product Type:
Robotic welders face the most acute substitution pressure from laser systems on thin-gauge aluminum EV body panels, while portable and stationary equipment contend with longer replacement cycles and margin compression.
- Robotic Welders:Six-axis articulated systems integrate adaptive current feedback for copper-to-aluminum battery tab joining. Volkswagen Group and Hyundai Motor manufacturing engineers specify these for aluminum-intensive EV platforms where nugget consistency across electrode wear cycles determines line throughput.
- Stationary Welders:Fixed pedestal configurations dominate legacy body-in-white installations with transformer-based power delivery. German Mittelstand metal fabricators defer replacement of these AC machines despite EU Green Deal compliance deadlines, compressing vendor margins.
- Portable Welders:Manual gun configurations serve repair operations and low-volume fabrication with limited automation integration.
- Multi-Spot Welders:Simultaneous electrode arrays accelerate cycle times on repetitive seam patterns in high-volume automotive stamping operations.
Stationary welders retain volume leadership; robotic welders hold the steepest expansion curve.
End User:
Cost tier stratification separates capital-intensive automotive OEMs from price-sensitive metal fabrication shops, with divergent procurement timelines and technology upgrade urgency.
- Automotive OEMs:Tier one suppliers in Michigan and Ohio drive inverter specification for federal procurement compliance under EPA energy efficiency benchmarks. Battery gigafactory construction in Gujarat and Tamil Nadu under India's PLI scheme redirects demand toward localized equipment supply chains.
- Metal Fabrication:Small-batch job shops prioritize equipment longevity over adaptive control features, extending service intervals for analog-era transformer bases.
- Aerospace Manufacturers:Precision airframe joining demands certified weld monitoring systems under NHTSA structural integrity requirements for crashworthiness validation.
- Electronics Industry:Micro-joining applications for battery tab welding require closed-loop current control at finer geometries with restricted heat-affected zones.
Automotive OEMs command the premium tier; electronics industry procurement is climbing the fastest on solid-state battery architecture requirements.
Technology:
Application maturity divides established AC transformer installations from emerging digital control platforms, with inverter systems capturing specification preference in new line designs.
- Inverter Technology:Medium-frequency 1,000 Hz power conversion enables real-time adaptive feedback that maintains joint consistency across electrode degradation. CE marking under the EU Machinery Directive restricts market access for non-compliant Asian imports, protecting European-certified manufacturers.
- Digital Control:Analog-to-digital conversion modules extend installed transformer base functionality while capturing parameter optimization features that address weld technician skill attrition.
- Alternating Current:Legacy 50/60 Hz transformer designs face EPA disqualification from federal incentive programs, compressing replacement demand into certified inverter vendor sets.
- Direct Current:Capacitive discharge systems serve specialized applications requiring precise energy dosing without line voltage fluctuation sensitivity.
Alternating Current retains installed base dominance; inverter technology is gaining share fastest on regulatory compliance mandates.
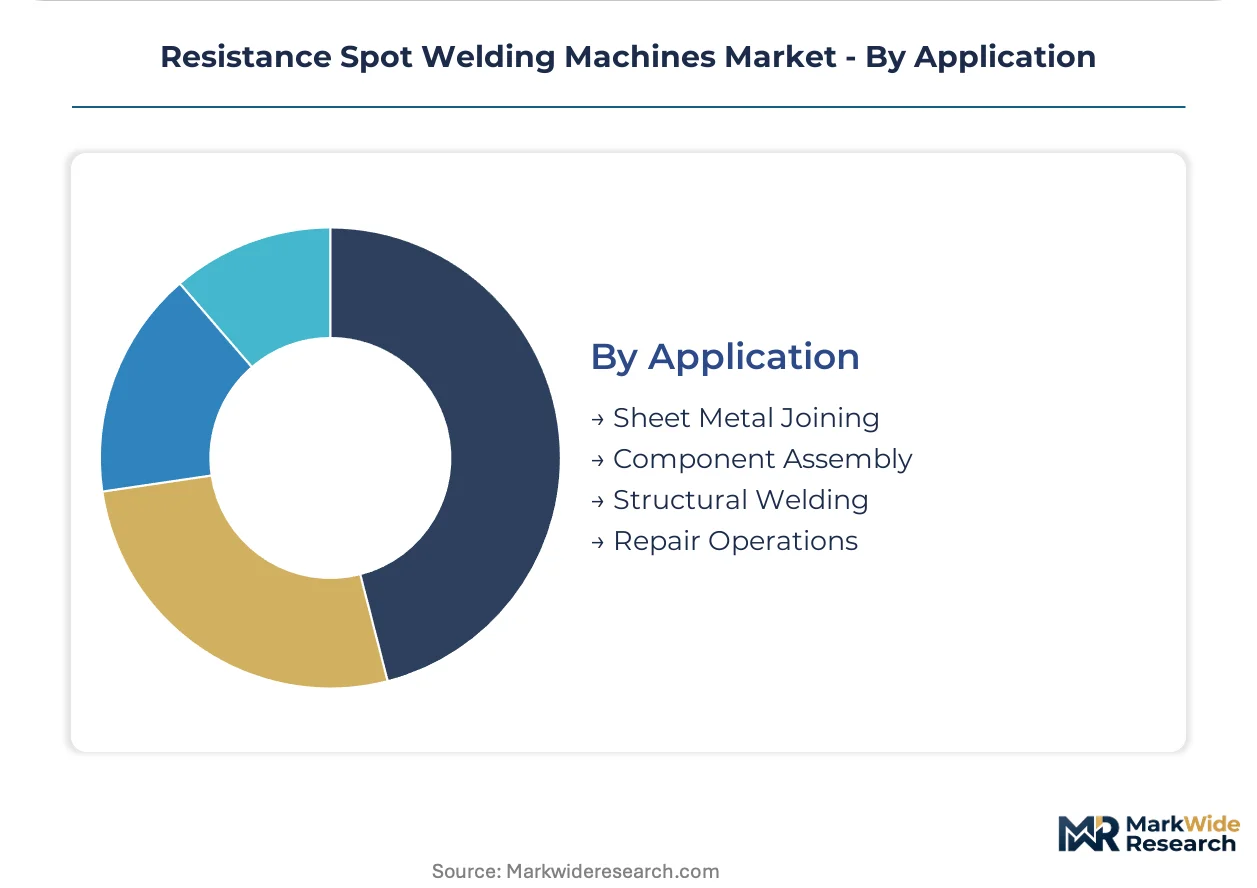
Application:
Volume concentration in high-throughput body-in-white assembly contrasts with fragmented repair and maintenance demand, reshaping service model economics.
- Sheet Metal Joining:Overlapping steel and aluminum panel welding constitutes the core body-in-white operation where cycle times must remain below two seconds per joint. Outcome-based service contracts now concentrate in high-volume EV battery lines where uptime guarantees override capital expenditure preferences.
- Structural Welding:Load-bearing chassis joint specifications mandate certified monitoring systems and extended third-party ISO 4063 validation timelines that delay product launches.
- Component Assembly:Subsystem integration operations span diverse geometries from seat frames to closure panels with varying automation integration.
- Repair Operations:Post-collision body shop applications prioritize equipment portability and technician accessibility over production line throughput metrics.
Sheet metal joining commands the largest revenue pool; structural welding is expanding most quickly on crashworthiness certification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
IGBT and SiC module fabrication clusters concentrate in Taiwan and mainland China, creating single-source vulnerability for inverter assembly lines serving resistance spot welding equipment manufacturers worldwide. Equipment vendors navigate divergent regulatory enforcement timelines across major manufacturing economies. Demand patterns split between automotive electrification hotspots and legacy metal fabrication modernization corridors.
United States
Tier one automotive suppliers in Michigan and Ohio accelerate inverter specification for EPA energy efficiency benchmark compliance ahead of enforcement windows. OSHA electrical safety standards mandate upgraded guarding and isolation systems on new equipment, compressing replacement cycles for aging transformer installations. Detroit-area body-in-white assembly plants drive specification preference for adaptive current feedback systems.
Germany
Mittelstand metal fabricators face EU Green Deal carbon border adjustment compliance deadlines that accelerate scrappage of energy-intensive AC equipment. CE marking under the EU Machinery Directive restricts market access for non-compliant Asian imports, protecting European-certified manufacturers. Stuttgart and Wolfsburg automotive clusters specify medium-frequency inverter technology for aluminum-intensive EV platforms.
China
Battery gigafactory construction concentrates demand for robotic welding systems capable of copper-to-aluminum joining precision. MIIT industrial upgrading programs favor domestic inverter technology development to reduce import dependency. Shenzhen and Shanghai equipment manufacturers leverage captive power electronics supply chains to serve regional automotive OEMs.
India
Domestic battery gigafactories under construction in Gujarat and Tamil Nadu require localized welding equipment supply chains under the PLI scheme for advanced cell manufacturing. BIS certification timelines extend procurement cycles for imported systems. Chennai and Ahmedabad industrial corridors attract equipment vendors establishing regional assembly operations.
Japan
Precision micro-joining applications for solid-state battery architectures pull demand toward closed-loop current control systems with restricted heat-affected zones. METI energy efficiency standards align with global inverter transition trajectories. Nagoya and Toyota City manufacturing clusters sustain demand for high-reliability welding monitoring hardware.
Resistance Spot Welding Machines Market Competitive Environment
Concentration sits with diversified industrial conglomerates and specialized welding equipment fabricators competing across technology tiers. The vendor base spans Japanese electronics conglomerates with captive power electronics supply chains, European precision engineering specialists, and North American distribution-heavy industrial suppliers. Two strategic archetypes dominate: integrated conglomerates leveraging backward integration into semiconductor components, and focused specialists commanding premium positioning in micro-joining applications. Competitive dynamics center on technology licensing arrangements and geographic expansion through distributor network density.
Among Japanese-based conglomerates, Panasonic Welding Systems Co., Ltd. and Miyachi Unitek (AMADA WELD TECH) exemplify the integrated archetype through upstream control over power electronics supply chains. Lincoln Electric Holdings, Inc. anchors the North American tier through dense distributor networks across manufacturing corridors. European specialists including Nimak GmbH and ARO Welding Technologies SAS occupy positions protected by CE marking complexity that blocks low-cost import competition.
| Leading Market Players |
|---|
| Panasonic Welding Systems Co., Ltd. |
| Automation International, Inc. |
| CenterLine (Windsor) Ltd. |
| Miyachi Unitek (AMADA WELD TECH) |
| Nimak GmbH |
| ARO Welding Technologies SAS |
| Dengensha Manufacturing Co., Ltd. |
| TECNA S.p.A. |
| Lincoln Electric Holdings, Inc. |
| Others |
Value Chain & Pricing Dynamics
Ninety-day IGBT module lead times from Taiwan-based fabricators concentrate pricing power among inverter-assembly vendors with captive semiconductor relationships, while copper cathode inventory cycles at London Metal Exchange warehouses feed directly into secondary winding cost volatility for transformer-based equipment buyers.
Pricing Analysis
EPA energy efficiency benchmarks dictate the pricing tier structure across the resistance spot welding equipment landscape. Three-tier pricing structure across premium inverter, standard digital-control, and economy AC-transformer levels separates certified adaptive systems from legacy analog installations. Price differentiation rests on CE marking compliance tier and volume-scale procurement commitments from automotive OEMs versus metal fabrication job shops. Cost compression in the economy tier is intensifying because Mittelstand fabricators defer replacement cycles despite EU Green Deal deadlines. Metal fabrication shops exhibit the highest price sensitivity; Tier one automotive suppliers demonstrate the lowest.
Supply Chain Analysis
Power electronics inventory cycles spanning 60–90 days from Taiwan and mainland China fabrication clusters expose inverter assembly lines to single-source vulnerability. Geographic supply concentration centers on Taiwan for IGBT and SiC modules, Japan for precision welding monitoring hardware, and Germany for CE-certified control systems. Raw material dependencies draw from copper cathodes for transformer windings, aluminum electrodes for battery tab joining, and silicon carbide substrates for next-generation inverters. Tariff exposure on semiconductor imports from mainland China creates supply chain risk for North American equipment vendors. Distribution runs through dense distributor networks across manufacturing corridors, with outcome-based service contracts emerging in high-volume EV battery lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
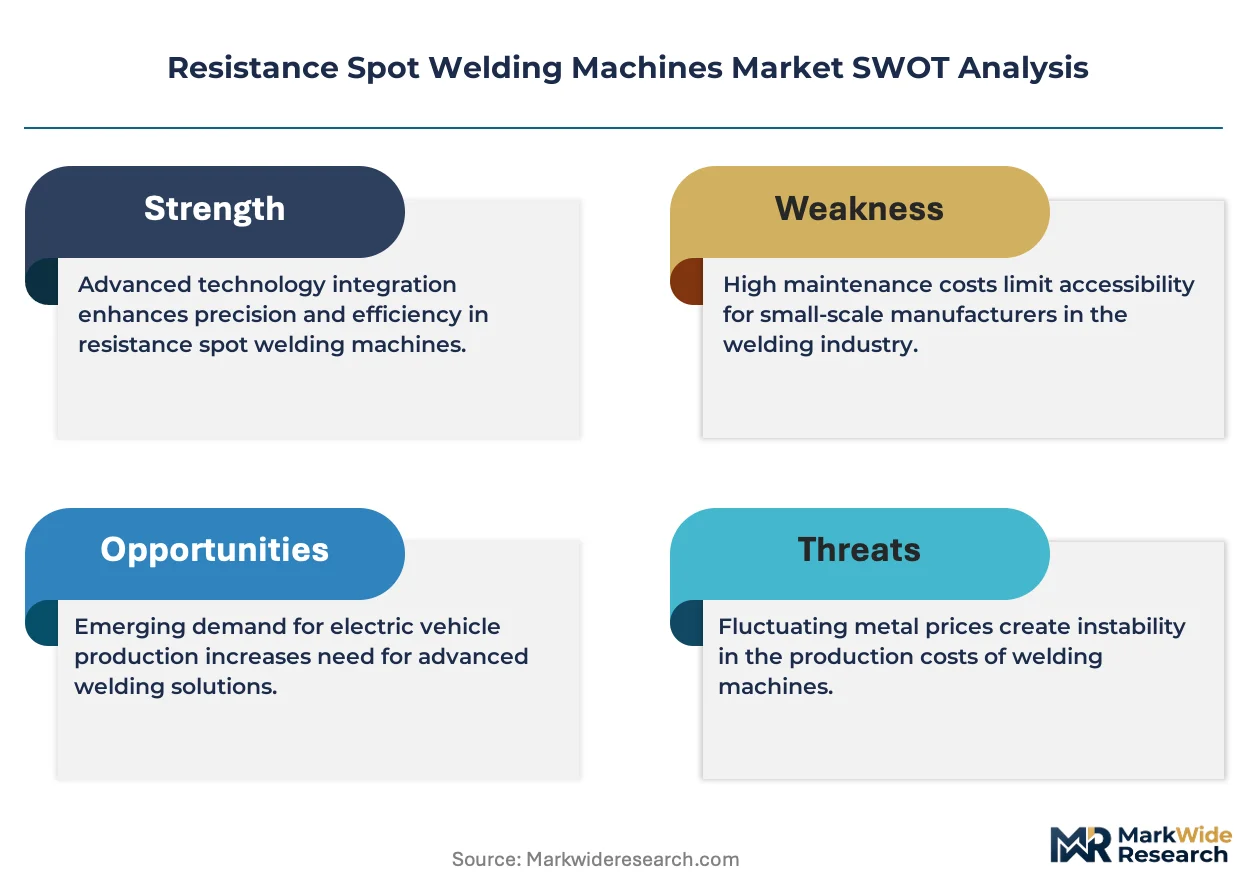
Fiber laser welding substitution on thin-gauge aluminum EV body panels threatens spot welding's cost advantage, forcing incumbents to defend through precision differentiation and service model innovation.
For Market Incumbents: Compound defensive positioning through backward integration into power electronics supply chains and certification moat deepening around CE marking complexity. Laser welding substitution on aluminum-intensive EV platforms demands accelerated inverter specification to maintain nugget consistency advantages. Channel control through dense distributor networks across North American manufacturing corridors remains a critical lever. For New Entrants and Emerging Players: BIS certification fast-track for India's PLI scheme battery gigafactories in Gujarat and Tamil Nadu offers the most penetrable entry corridor. Under-served retrofit digital control modules for legacy transformer bases in German Mittelstand shops present a second white-space target. Go-to-market angle should emphasize analog-to-digital conversion kits that extend installed base service life while capturing adaptive feedback functionality. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across inverter technology sub-segments as semiconductor module costs decline and manufacturing scales. Long-term viability over a five-to-ten-year window favors vendors with captive power electronics supply chains and regional certification expertise. Acquisition target archetype: European-certified specialists with established automotive tier-one relationships. Signal to watch: solid-state battery architecture shifts altering joint geometry specifications and current delivery requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Power Electronics | Panasonic and Miyachi Unitek leverage captive IGBT supply chains to secure inverter assembly margins against Taiwan concentration risk. |
| CE Marking Certification Pathway | European Machinery Directive compliance blocks low-cost Asian imports, protecting margin corridors for Nimak and ARO Welding Technologies. |
| Outcome-Based Service Contracts | Per-qualified-joint pricing models concentrate in high-volume EV battery lines where uptime guarantees override capital expenditure preferences. |
| Retrofit Digital Control Modules | Analog-to-digital conversion kits extend transformer base service life while addressing weld technician skill attrition in aging installations. |
| India PLI Localization | Domestic assembly operations in Chennai and Ahmedabad industrial corridors capture battery gigafactory demand under advanced cell manufacturing incentives. |
Study Parameters
Cross-validation between primary interviews with automotive OEM procurement teams, Tier one supplier plant engineers, and aftermarket service heads anchors the qualitative findings against secondary validation from SEC filings, customs and trade data, and vehicle production databases. Bottom-up triangulation across robotic welder, stationary welder, and portable welder product categories integrates with top-down market sizing from EPA energy efficiency benchmark compliance tracking and EU Green Deal carbon border adjustment enforcement timelines.
Sensitivity analysis across inverter technology, digital control, and alternating current technology segments models adoption trajectories over the projection horizon. Segmentation dimensions include product type, end user industry, technology platform, and application with regional production cluster overlays. CAGRs derive from equipment replacement cycle compression analysis and regulatory compliance deadline clustering. Industry-specific forecast inputs incorporate solid-state battery architecture development timelines and MIIT industrial upgrading program targets for domestic inverter technology development.
The analysis sits within stated boundaries; outcomes outside EPA enforcement window acceleration or EU Green Deal carbon border adjustment expansion would require recalibration. Forecasts reflect assumptions around electrode wear cycle consistency and semiconductor module supply stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Machine Tool Cooling System Market
Industrial Equipment
Global Industrial Enclosures Market
Industrial Equipment
Linear Motion (LM) Shaft Market
Industrial Equipment
Rotary Scroll Air Compressor Market
Industrial Equipment
Seal Inspection Equipment Market
Industrial Equipment
Vibration Isolation Tables Market
Industrial Equipment
Robotic Ultrasonic NDT Cells for Weld and Pressure Vessel Inspection Market
Industrial Equipment
Industrial Monitor Market
Industrial Equipment
Global Twister Winder Market
Industrial Equipment
Latin America Explosion-Proof Equipment Market
Industrial Equipment
Pneumatic Strippers Market
Industrial Equipment
Dust Extraction System Market
Industrial Equipment
Spherical Roller Bearings Market
Industrial Equipment
Fiber Laser Market
Industrial Equipment
Global Dosing Systems Market
Industrial Equipment
Digital Tachometer Market