
 Long-Range Acoustic Device Market | 2026-2036
Long-Range Acoustic Device Market Size, Share, and Industry Trends Forecast 2026-2036
Long-Range Acoustic Device Market Insights
Acoustical engineering talent is collapsing across defense-adjacent manufacturing clusters, forcing LRAD Corporation to leverage its in-house transducer fabrication capabilities while Ultra Electronics Holdings sustains British supply chains through apprenticeship pipelines. Genasys competes on integrated software-hardware bundles that extend its reach into federal emergency response networks. DSPPA anchors Asian production scale for electroacoustic components, though workforce migration into consumer audio sectors challenges retention.
A long-range acoustic device projects highly directional sound beams across distances exceeding one kilometer using phased array or parabolic transducer configurations, achieving narrow beamwidths below fifteen degrees for precise targeting. Portable and vehicle-mounted product types dominate procurement volumes, with fixed installations capturing higher margin pools in critical infrastructure protection. Directional sound technology leads unit shipments while ultrasonic variants occupy niche wildlife deterrence applications where frequency selectivity prevents collateral disturbance.
FCC equipment authorization requirements govern civilian frequency emissions in the United States, while EU CE marking under the Electromagnetic Compatibility Directive conditions market access for European security contractors. Military end users navigate ITAR export controls and NATO standardization agreements that fragment procurement specifications across allied nations. Stakeholders must monitor evolving rules of engagement policies and acoustic exposure liability thresholds as jurisdictions weigh humanitarian use constraints against operational effectiveness claims.
Market Dynamics
Directional sound technology is fragmenting procurement patterns across defense and security verticals as NATO member states rewrite rules of engagement protocols and federal homeland security grants accelerate municipal police modernization cycles.
Growth Catalysts
- Updated NATO engagement protocols:Military procurement teams across allied nations are expanding vehicle-mounted unit orders under revised operational guidelines that prioritize non-lethal escalation capabilities.
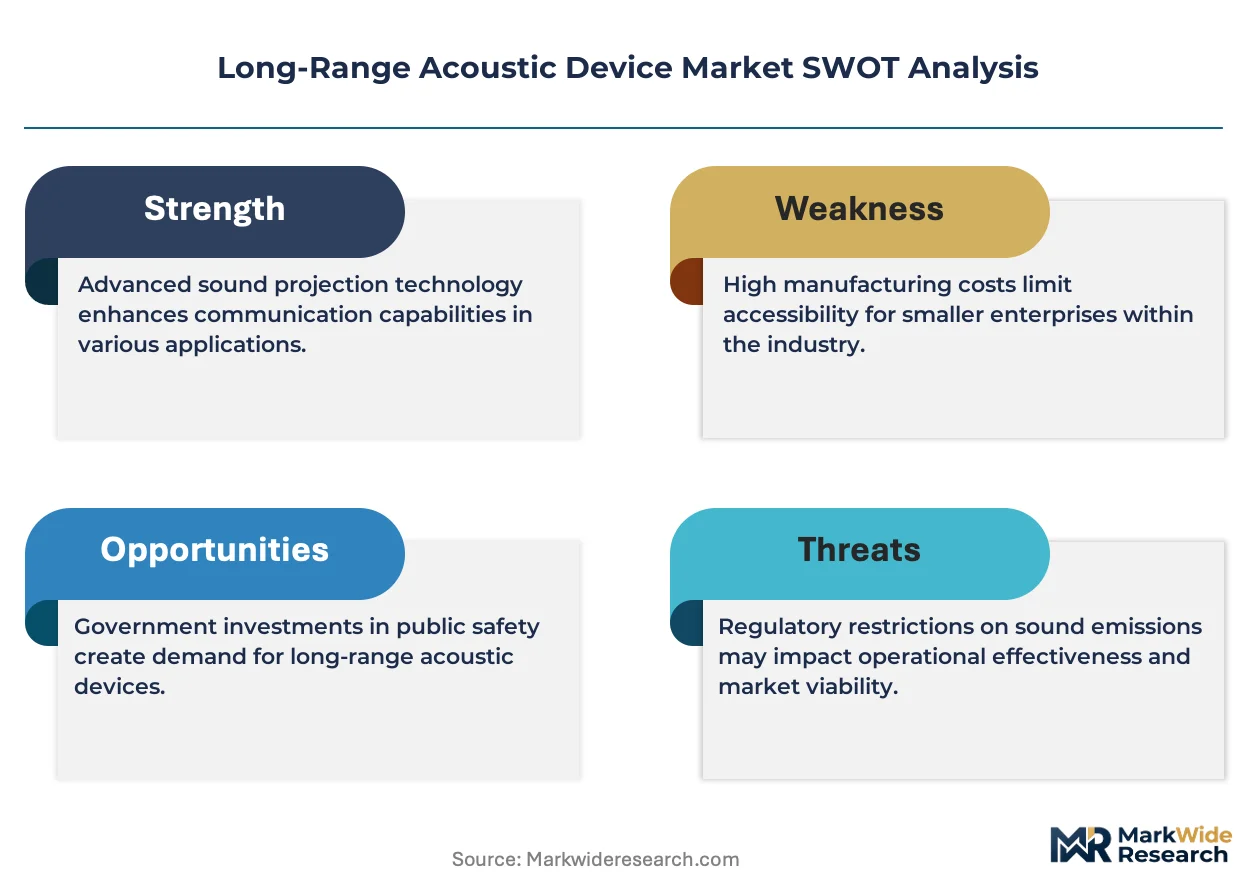
- FCC equipment authorization pathways:Streamlined civilian frequency emission approvals in the United States are reducing time-to-market for perimeter security contractors deploying directional loudspeaker arrays.
- Critical infrastructure protection mandates:Energy facilities and transportation hubs are replacing legacy loudspeaker systems with phased array configurations capable of precise one-kilometer targeting.
Market Restraints
- Acoustical engineering talent scarcity:Defense-adjacent manufacturing clusters face collapsing specialist pipelines as graduates migrate toward consumer audio sectors offering higher compensation.
- ITAR export control fragmentation:Military end users encounter procurement specification divergence across allied nations due to inconsistent NATO standardization agreement implementation.
- Ultrasonic frequency substitution limits:Wildlife deterrence applications face narrow addressable demand due to frequency selectivity requirements that prevent broader security market penetration.
Strategic Opportunities
- Emergency response network integration:Federal emergency management systems present white space for software-hardware bundles that unify acoustic alerting with digital command infrastructure.
- CE marking acceleration in Europe:EU Electromagnetic Compatibility Directive harmonization is creating streamlined market access for security contractors previously blocked by national certification divergence.
- Vehicle-mounted platform convergence:Integration of directional sound with mobile surveillance and drone detection systems opens new procurement categories among border enforcement agencies.
Industry Challenges
- Transducer fabrication skill retention:In-house electroacoustic component production requires specialized workforce pipelines that apprenticeship programs struggle to populate at sufficient scale.
- Acoustic exposure liability thresholds:Jurisdictional variation in humanitarian use constraints creates compliance complexity for manufacturers serving multiple operational theaters.
- Legacy system integration friction:Fixed installation upgrades demand interface compatibility with existing perimeter security architectures that use proprietary communication protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Long-Range Acoustic Device Market |
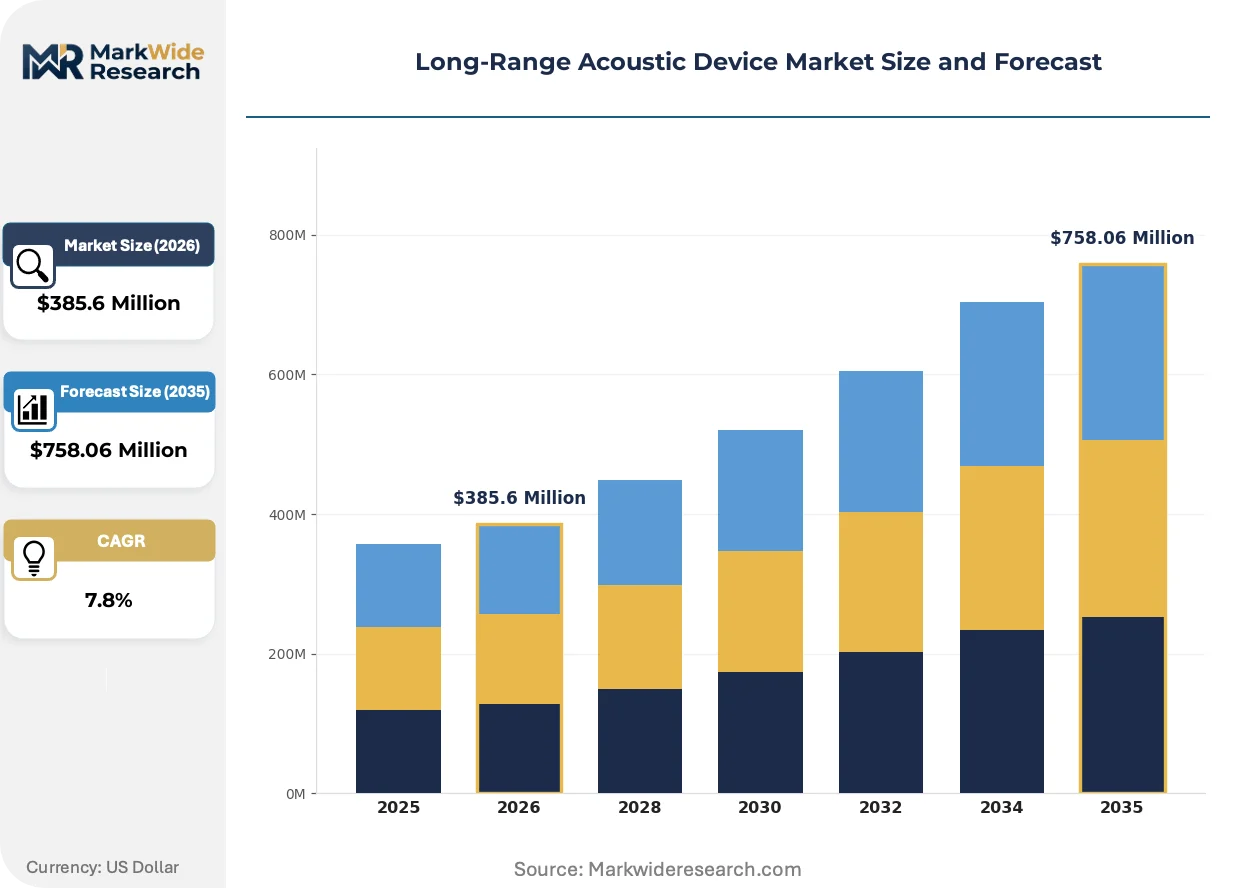
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $758.06 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Fixed, Vehicle-Mounted, Handheld Technology: Directional Sound, Ultrasonic, Parabolic, Electroacoustic Application: Crowd Control, Wildlife Management, Perimeter Security, Industrial Safety End User: Law Enforcement, Military Units, Security Firms, Event Management |
| Companies Covered | DSPPA, Argo-A Security, Genasys, Ultra Electronics Holdings, Summit Engineering Corporation, LRAD Corporation, IMLCORP, CRD Protection AB, D&K Engineering, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Long-Range Acoustic Device Market Trends and Innovations
Phased array configurations are actively reshaping competitive positioning as beamwidth precision becomes the primary performance differentiator separating premium from standard system tiers.
Beam-steering algorithms are fragmenting product architecture across the installed base. Naval and coast guard operators are adopting electronically scanned arrays that eliminate mechanical positioning latency. This capability compression is enabling real-time target tracking against small vessel threats while reducing maintenance intervals for maritime patrol fleets.
EU CE marking under the Electromagnetic Compatibility Directive is conditioning market access trajectories for European security contractors. Industrial consequence includes accelerated conformity assessment outsourcing as manufacturers seek notified body partnerships. Border enforcement agencies in Germany and France are responding by specifying pre-certified subsystem architectures that reduce integration risk.
Specification-driven procurement is compressing vendor qualification cycles among municipal police departments. Traditional resell channels are losing share to direct manufacturer relationships that bundle training and firmware update commitments. California and Texas municipal budgets demonstrate this pattern most visibly, with departments consolidating vendor panels to three approved suppliers per acoustic category.
Long-Range Acoustic Device Market Segmentation
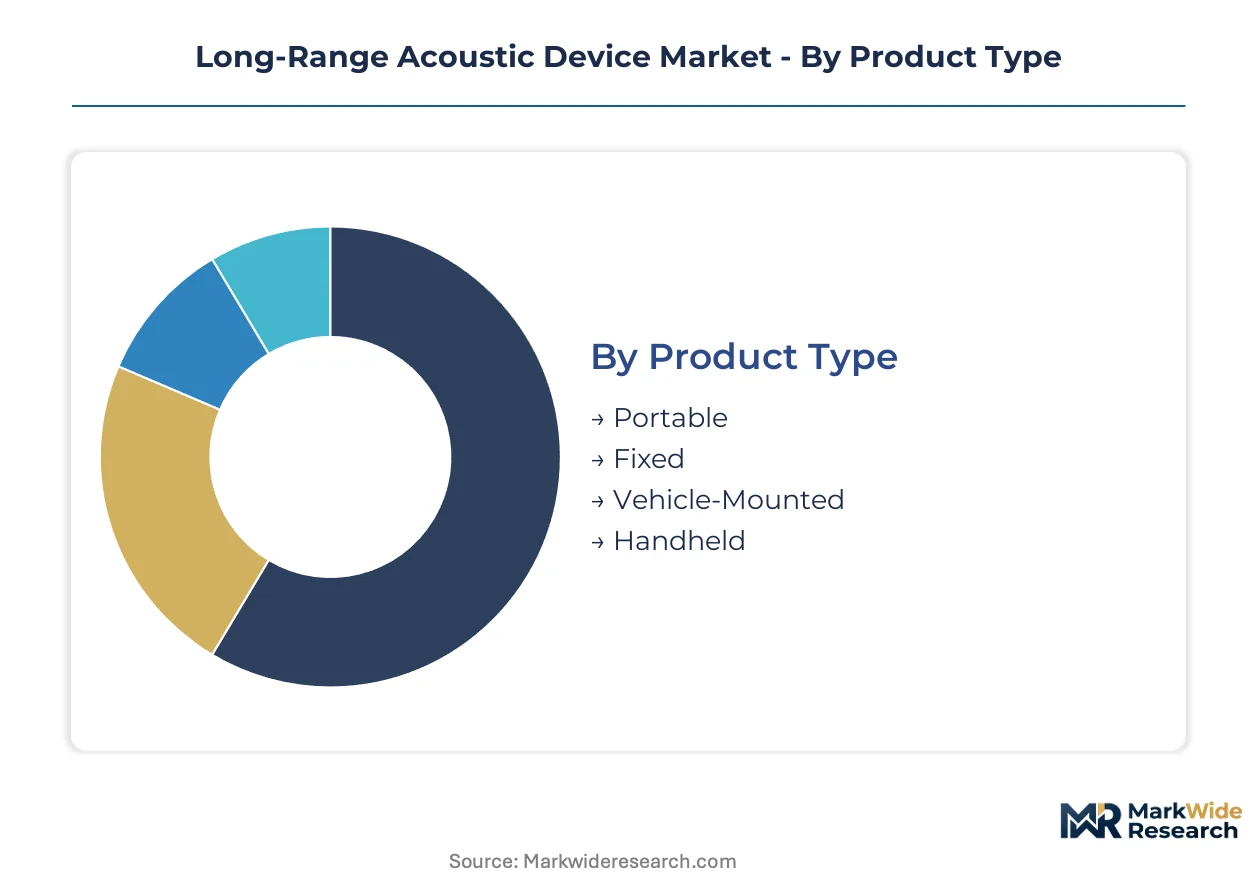
Procurement specifications diverge sharply across deployment contexts, with NATO rules of engagement and municipal police modernization driving divergent performance requirements. Segment boundaries determine margin capture, as fixed installations command premium pricing while portable units sustain volume throughput.
Product Type:
Vehicle-mounted configurations face the strongest substitution pressure from integrated drone detection and mobile surveillance platforms, forcing acoustic suppliers to bundle command software or lose procurement slots.
- Portable:Battery-powered units deploy rapidly for temporary crowd management and tactical team operations. Municipal police departments in the United States concentrate procurement through federal homeland security grants, prioritizing units under 15 kilograms for officer mobility.
- Vehicle-Mounted:Phased array systems integrate with armored personnel carriers and patrol vehicles, achieving one-kilometer targeting precision through electronically scanned configurations. NATO military procurement teams expand orders under revised escalation protocols that prioritize non-lethal capabilities.
- Fixed:Permanent installations protect critical infrastructure with parabolic or phased array architectures hardwired into perimeter security networks.
- Handheld:Compact directional units serve close-range engagement scenarios where beamwidth below ten degrees enables precise individual targeting.
Vehicle-mounted units anchor the volume base while portable configurations gain share at the steepest rate.
Technology:
Cost tier stratification separates premium beam-steering systems from standard electroacoustic arrays, with ultrasonic variants occupying narrow wildlife deterrence niches.
- Directional Sound:Phased array configurations project narrow acoustic beams across distances exceeding one kilometer using electronically controlled transducer timing. Perimeter security contractors in the United States displace legacy loudspeaker arrays, driven by FCC equipment authorization pathways that streamline civilian frequency emission approvals.
- Ultrasonic:Frequency-selective emission above 20 kHz deters wildlife without audible disturbance to human populations. Frequency selectivity constraints prevent broader security market penetration, limiting addressable demand to conservation and agricultural protection zones.
- Parabolic:Dish-shaped reflectors concentrate sound energy into tight beams for cost-sensitive installations requiring mechanical rather than electronic beam steering.
- Electroacoustic:Conventional transducer arrays serve baseline alerting applications where precision targeting remains secondary to broadcast coverage.
Directional sound technology dominates revenue contribution while ultrasonic applications expand most quickly within narrow verticals.
Application:
Customer type concentration varies by operational theater, with military end users prioritizing escalation control and commercial security firms emphasizing liability reduction.
- Perimeter Security:Fixed phased array installations replace legacy loudspeaker systems at energy facilities and transportation hubs. Critical infrastructure protection mandates in the United States drive specification upgrades toward precise targeting capabilities.
- Crowd Control:Portable and vehicle-mounted units enable graduated escalation protocols for civil disturbance management. Acoustic exposure liability thresholds create compliance complexity as jurisdictions weigh humanitarian constraints against operational effectiveness.
- Wildlife Management:Ultrasonic frequency emission prevents crop damage and airport bird strikes through species-selective deterrence.
- Industrial Safety:Directional alerting systems penetrate high-noise manufacturing environments where conventional alarms fail to penetrate hearing protection.
Perimeter security anchors the volume base while wildlife management climbs the fastest on conservation budget expansion.
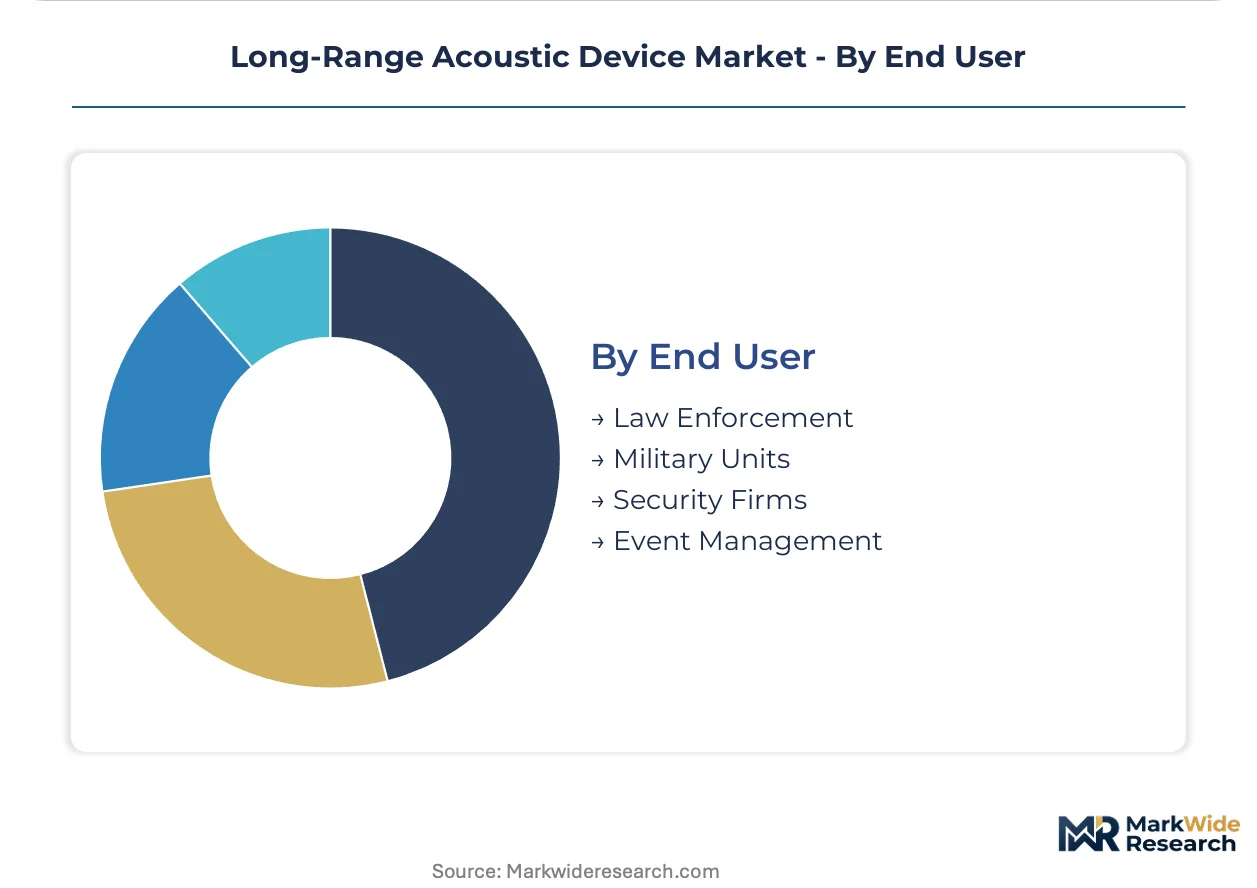
End User:
Supply concentration favors defense-adjacent manufacturing clusters with in-house transducer fabrication, while commercial security procurement fragments across regional integrators.
- Military Units:Vehicle-mounted phased arrays integrate with NATO standardization agreements, though ITAR export controls fragment procurement specifications across allied nations. Rules of engagement protocol updates prioritize non-lethal escalation capabilities.
- Law Enforcement:Municipal police departments consolidate vendor panels to three approved suppliers per acoustic category, bundling training and firmware commitments. California and Texas municipal budgets demonstrate this consolidation pattern most visibly.
- Security Firms:Perimeter protection contractors seek pre-certified subsystem architectures that reduce integration risk under EU CE marking requirements.
- Event Management:Temporary deployment specialists prioritize rapid-setup portable units for crowd flow management at large-scale gatherings.
Law enforcement anchors the volume base while military units drive specification advancement at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC equipment authorization requirements anchor procurement velocity in the United States, while EU CE marking under the Electromagnetic Compatibility Directive conditions European market access. Procurement specifications fragment across allied military systems due to inconsistent NATO standardization agreement implementation.
United States
Federal homeland security grants and municipal police modernization budgets sustain demand for portable and vehicle-mounted units. FCC streamlined civilian frequency emission approvals reduce time-to-market for perimeter security contractors. California and Texas municipal budgets demonstrate vendor panel consolidation most visibly, with departments limiting acoustic category suppliers to three approved sources.
Germany
Border enforcement agencies specify pre-certified subsystem architectures that reduce integration risk under EU CE marking harmonization. The Electromagnetic Compatibility Directive accelerates conformity assessment outsourcing as manufacturers seek notified body partnerships. Industrial clusters in Bavaria and Baden-Württemberg host defense-adjacent manufacturing with in-house transducer fabrication capabilities.
United Kingdom
Ultra Electronics Holdings sustains British supply chains through apprenticeship pipelines addressing acoustical engineering talent scarcity. ITAR export controls fragment military procurement specifications despite NATO membership. Security contractors in Greater London and the Midlands respond to CE marking requirements by specifying pre-certified directional sound systems.
France
ANSM and CNIL regulatory frameworks intersect with defense procurement for crowd control applications. Rules of engagement protocol updates prioritize non-lethal escalation capabilities for vehicle-mounted deployments. Marseille and Lyon metropolitan areas concentrate perimeter security contractor activity for critical infrastructure protection.
China
DSPPA anchors Asian production scale for electroacoustic components, though workforce migration into consumer audio sectors challenges specialist retention. GB standards and MIIT regulations govern domestic frequency emissions for security applications. Yangtze River Delta manufacturing clusters face talent competition from Shenzhen consumer electronics ecosystems.
Long-Range Acoustic Device Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with defense-integrated specialists commanding premium positioning while Asian scale manufacturers penetrate volume tiers. The vendor base separates into three strategic archetypes: in-house transducer fabricators with captive supply chains, software-hardware bundlers targeting federal emergency networks, and component-scale producers serving integrator channels. Competitive moves concentrate on strategic partnerships for emergency response network integration and geographic expansion through CE marking acceleration in Europe.
Within the defense-integrated tier, LRAD Corporation exemplifies in-house transducer fabrication capabilities, while Ultra Electronics Holdings occupies a position sustaining British supply chains through workforce pipelines. Genasys represents the software-hardware bundler archetype extending reach into federal emergency response networks. These three anchors illustrate how competitive positioning fragments across technology specialization, geographic supply chain anchoring, and integrated system bundling rather than converging on uniform scale advantages.
| Leading Market Players |
|---|
| DSPPA |
| Argo-A Security |
| Genasys |
| Ultra Electronics Holdings |
| Summit Engineering Corporation |
| LRAD Corporation |
| IMLCORP |
| CRD Protection AB |
| D&K Engineering |
| Others |
Pricing and Supply Chain Analysis
Ninety-day lead times for phased array transducer assemblies concentrate pricing power with in-house fabricators in the United States and China, while municipal police procurement cycles compress margins for portable unit suppliers dependent on outsourced electroacoustic components. Inventory buffers at defense-integrated manufacturers insulate NATO-facing contracts from spot-market volatility in rare-earth magnet feedstocks.
Pricing Analysis
North American municipal bids trade at fifteen to twenty percent premiums over Asian volume tenders for equivalent acoustic output specifications. Three-tier pricing structure across premium, standard, and economy levels separates FCC-authorized systems with firmware update commitments from bare-bone electroacoustic arrays. Cost compression in portable configurations intensifies as federal homeland security grant eligibility narrows vendor pools. Security contractors exhibit highest price sensitivity, while military procurement teams prioritize ITAR-compliant supply chains over unit economics.
Supply Chain Analysis
Rare-earth magnet processing in China anchors transducer fabrication cost structures, with secondary concentration in Japanese sintering facilities for high-temperature tolerant grades. Neodymium-iron-boron magnets, aluminum voice coil formers, and polyimide diaphragm substrates feed phased array production lines. Single-source vulnerability in Chinese rare-earth separation creates exposure to export license suspensions. Distribution runs through defense-authorized integrators for military end users and direct manufacturer relationships for municipal police departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Firmware subscription layers and training certification programs expand addressable revenue per installed unit faster than hardware replacement cycles, converting transactional acoustic device sales into recurring service relationships.
For Market Incumbents: Compound defensive positioning by deepening in-house transducer fabrication capabilities to offset acoustical engineering talent scarcity, while locking municipal police departments into multi-year firmware update contracts that raise switching costs against emerging software-hardware bundlers. For New Entrants and Emerging Players: Anchor in European perimeter security contractor networks where CE marking harmonization has reduced certification barriers, targeting German and French border enforcement agencies specifying pre-certified subsystem architectures as the most penetrable procurement channel. For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate defense electronics divisions where acoustic device product lines lack management attention relative to core radar or communications portfolios, with long-term viability hinging on rules of engagement protocol permanence; watch NATO standardization agreement implementation consistency as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Emergency Response Network Integration | Genasys-style software-hardware bundles capture federal FEMA procurement slots. |
| CE Marking Acceleration | EU Electromagnetic Compatibility Directive harmonization unlocks German-French border agency contracts. |
| Transducer Fabrication Scale-Up | In-house rare-earth magnet voice coil production insulates against Chinese export license risk. |
| Apprenticeship Pipeline Investment | Ultra Electronics-style workforce programs address collapsing acoustical engineering graduate supply. |
| Vehicle-Mounted Platform Convergence | Drone detection integration opens new border enforcement procurement categories. |
Research Methodology
A standing panel of military procurement officers, municipal police equipment coordinators, perimeter security contractors, and acoustical engineering program directors provided ongoing calibration against secondary validation from FCC equipment authorization databases, NATO standardization agreement repositories, and EU notified body conformity assessment records. Bottom-up unit shipment estimates triangulated against top-down defense budget allocation analysis.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, technology tier, application context, and end-user procurement authority. CAGRs derived from logistic curve fitting to historical procurement velocity adjusted for rules of engagement protocol revision timelines and federal grant cycle phasing.
Underlying assumptions cover NATO escalation protocol permanence and rare-earth magnet supply continuity, with deviation risk concentrated in ITAR regulatory reinterpretation and acoustic exposure liability threshold tightening. Practitioners should keep alternative scenarios live as humanitarian use constraint litigation evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Global Industrial Actuators Market
Industrial Equipment
Thermal Cleaning System Market
Industrial Equipment
Linear Shaft Motor Market
Industrial Equipment
Refrigeration Coolers Market
Industrial Equipment
Global Safety Relays and Timers Market
Industrial Equipment
Global Integrated Drive Systems Market
Industrial Equipment
Industrial Vacuum Evaporation Systems Market
Industrial Equipment
Fusion Splicer Market
Industrial Equipment
Case Handling Machines Market
Industrial Equipment
Ultrasonic Cleaning Equipment Market
Industrial Equipment
Parts and Equipment Market
Industrial Equipment
Actuators Market
Industrial Equipment
Dynamic Scales Market
Industrial Equipment
North America Rental Chillers Market
Industrial Equipment
Coil Winding Machine Market
Industrial Equipment
Middle East and Africa Industrial Centrifuge Market