
 Industrial Refrigeration Systems Market | 2026-2036
Industrial Refrigeration Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Refrigeration Systems Market Analysis
Preventive maintenance contracts and remote monitoring subscriptions is pivoting vendor revenue from hardware sales to recurring service income. Johnson Controls leverages its building automation expertise to bundle refrigeration with energy management platforms. Emerson Electric Co. anchors its position through compressor controls and refrigerant monitoring systems that integrate with facility-wide IoT networks. GEA Group Aktiengesellschaft specializes in custom-engineered freezing solutions for protein processing plants across Northern Europe.
Industrial refrigeration systems encompass engineered assemblies of compressors, condensers, evaporators, and control systems designed to maintain temperatures between minus forty degrees Celsius and fifteen degrees Celsius for commercial and industrial processes. These systems employ ammonia, CO2, or synthetic refrigerants in closed-loop vapor compression cycles to preserve perishable goods, stabilize chemical reactions, and maintain cold chain integrity. Compressors command the largest share of component value due to precision manufacturing requirements and long replacement cycles. Cascade technology configurations using CO2 over ammonia are gaining share in European cold storage facilities seeking lower global warming potential footprints. Food Processing end users generate the most consistent demand volume, though Pharmaceutical applications carry higher margin profiles due to validation and compliance requirements.
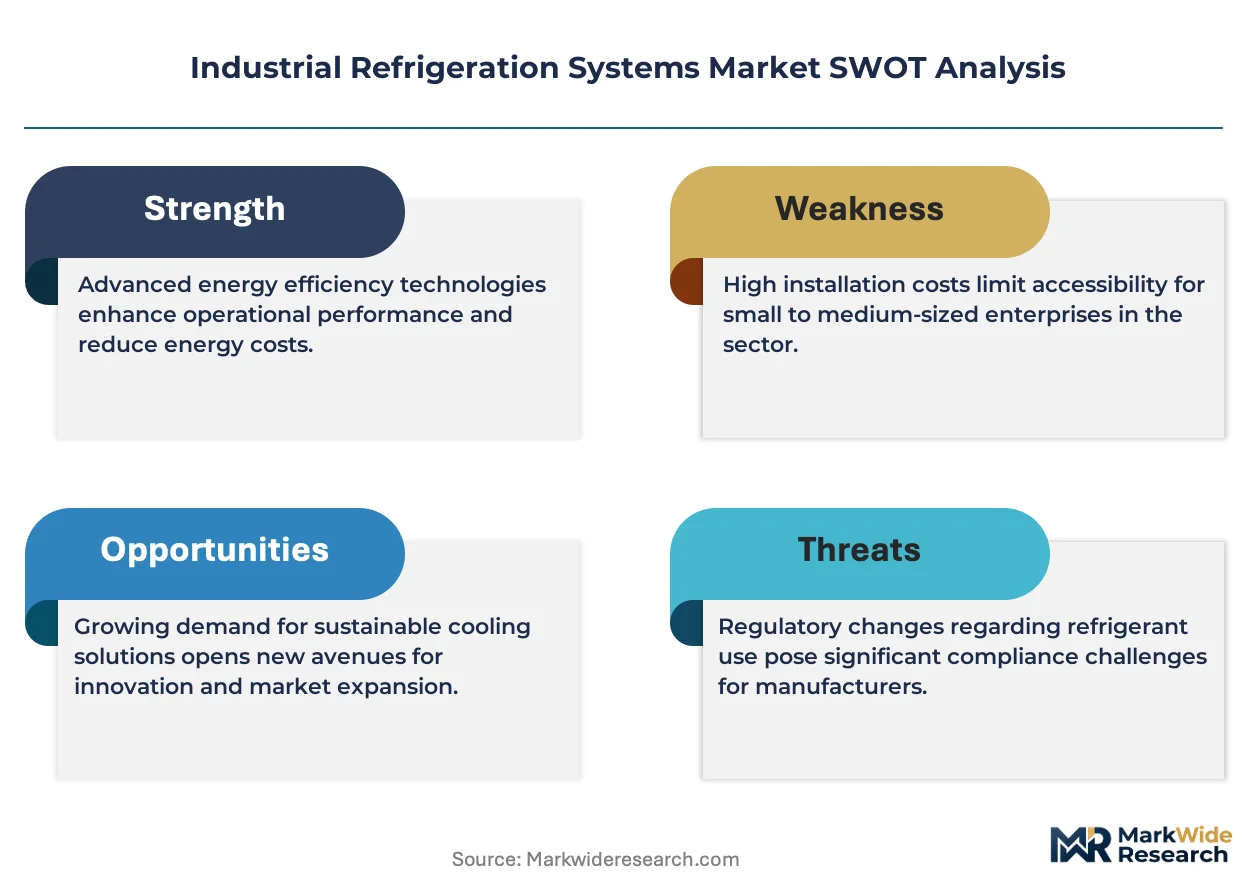
The EPA enforces HFC phasedown schedules under the AIM Act, while the EU F-Gas Regulation mandates refrigerant containment and reporting thresholds that shape equipment design priorities. ISO 5149 and ASHRAE Standard 15 establish safety protocols for ammonia system installations that constrain market entry for uncertified providers. Stakeholders must weigh total cost of ownership against refrigerant transition timelines when committing to new system architectures.
Market Dynamics
The EPA's phasedown of HFC refrigerants under the AIM Act is compressing replacement cycles and forcing capital allocation toward ammonia and CO2 architectures before synthetic refrigerant supply tightens.
Growth Catalysts
- E-commerce cold chain expansion:Grocery fulfillment networks in the United States and China are commissioning multi-temperature distribution centers that require industrial-scale refrigeration infrastructure.
- EU F-Gas Regulation containment mandates:European cold storage operators face escalating compliance costs for synthetic refrigerant leaks, accelerating retrofits to lower-GWP cascade systems.
- Pharmaceutical validation requirements:Vaccine manufacturing and biologics storage in Germany demand precision temperature control systems with full documentation trails for regulatory submission.
Market Restraints
- Copper and steel input volatility:Compressor and heat exchanger manufacturers absorb margin pressure from commodity price swings that defy long-term contract hedging.
- Specialized ammonia system installer scarcity:Certified technicians concentrate in Northern Europe and the Upper Midwest United States, constraining deployment speed elsewhere.
- ASHRAE Standard 15 safety protocols:Charge size limitations and machinery room requirements add civil engineering costs that synthetic refrigerant systems avoid.
Strategic Opportunities
- CO2 transcritical adoption in warm climates:Technology suppliers can penetrate the southeastern United States and southern China where ambient temperatures previously excluded CO2 economics.
- Remote monitoring platform bundling:Vendors capture recurring revenue by integrating compressor diagnostics with facility energy management dashboards.
- Indian cold storage infrastructure gaps:Post-harvest food loss reduction targets under national agricultural policy create procurement pull for distributed refrigeration units.
Industry Challenges
- Ammonia refrigeration technician certification backlogs:OSHA and EPA training program capacity limits installer supply just as retrofit demand surges.
- Legacy control system integration friction:Facilities with 1990s-era SCADA architectures face protocol mismatches when adding IoT-enabled refrigerant monitoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Refrigeration Systems Market |
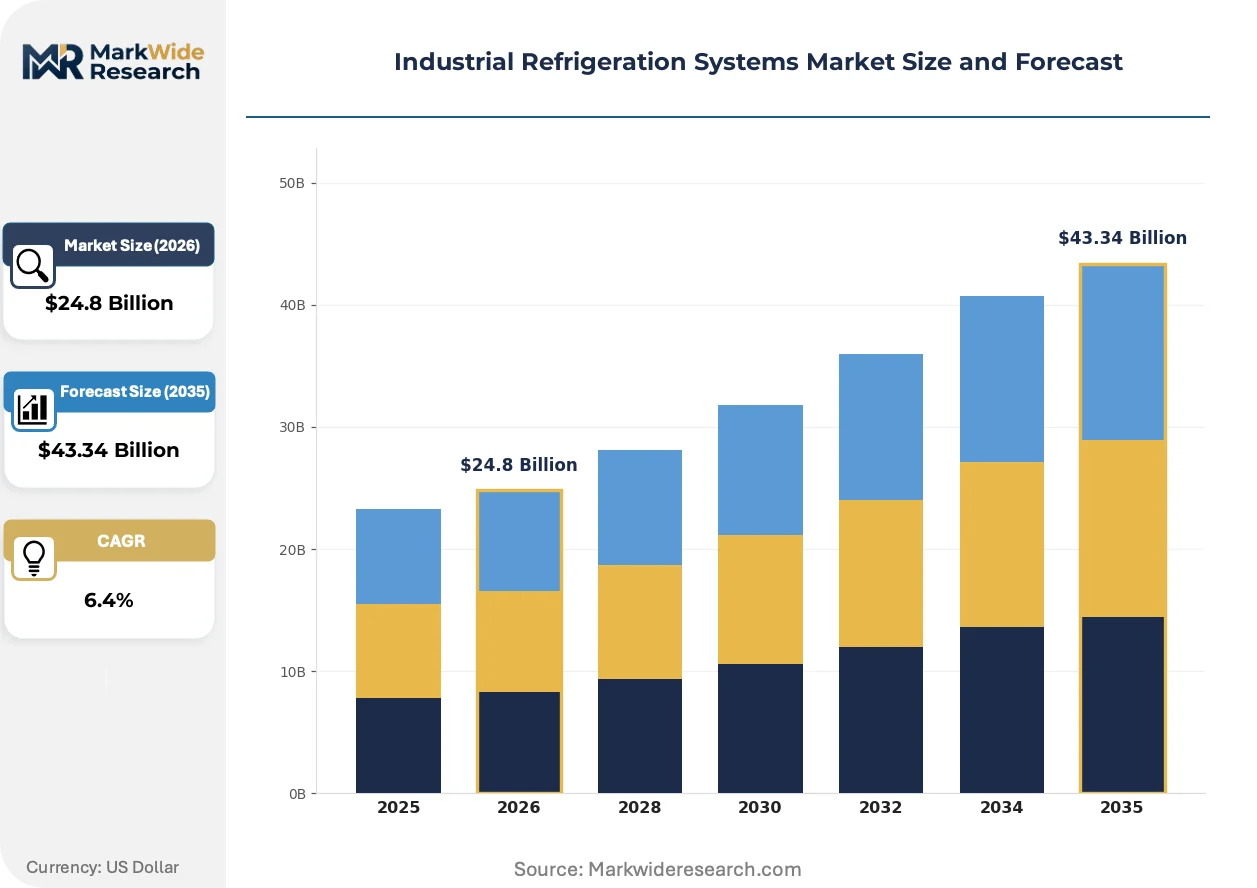
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $43.34 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compressors, Condensers, Evaporators, Expansion Valves Technology: Vapor Compression, Absorption, Cascade, Thermoelectric End User: Food Processing, Pharmaceuticals, Cold Storage, Retail Application: Blast Freezing, Chilling, Refrigerated Transport, Industrial Cooling |
| Companies Covered | Johnson Controls, Emerson Electric Co., GEA Group Aktiengesellschaft, Danfoss, Mayekawa, BITZER, EVAPCO Inc., Daikin Industries Ltd., LU-VE Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Refrigeration Systems Market Emerging Trajectories
Equipment architectures are converging around natural refrigerants while digital layers transform how performance is guaranteed and monetized across the installed base.
Cascade refrigeration configurations pairing CO2 as a secondary fluid with ammonia as the primary refrigerant are consolidating market share in European cold storage facilities seeking to eliminate synthetic refrigerant dependence entirely. Protein processors in Denmark and the Netherlands have standardized on this architecture for new greenfield builds. The technology is consolidating vendor R&D roadmaps and compressing the viable design space for single-refrigerant systems in jurisdictions with aggressive phasedown timelines.
REACH and the EU F-Gas Regulation are tightening containment verification and leak detection frequency requirements for systems above specific charge thresholds. Equipment suppliers now pre-integrate automated refrigerant monitoring sensors to satisfy third-party audit demands. Pharmaceutical manufacturers in Germany and France face the steepest compliance cost escalations and are specifying these sensor packages as standard procurement requirements.
Service contract structures are unbundling hardware warranties from performance guarantees, with operators purchasing uptime commitments and energy efficiency outcomes rather than discrete maintenance visits. Cold storage REITs in the United States are driving this model shift to align vendor incentives with portfolio-level sustainability reporting obligations. The transition is most visible among multi-site operators seeking to standardize service levels across geographically dispersed assets.
Industrial Refrigeration Systems Market Segmentation
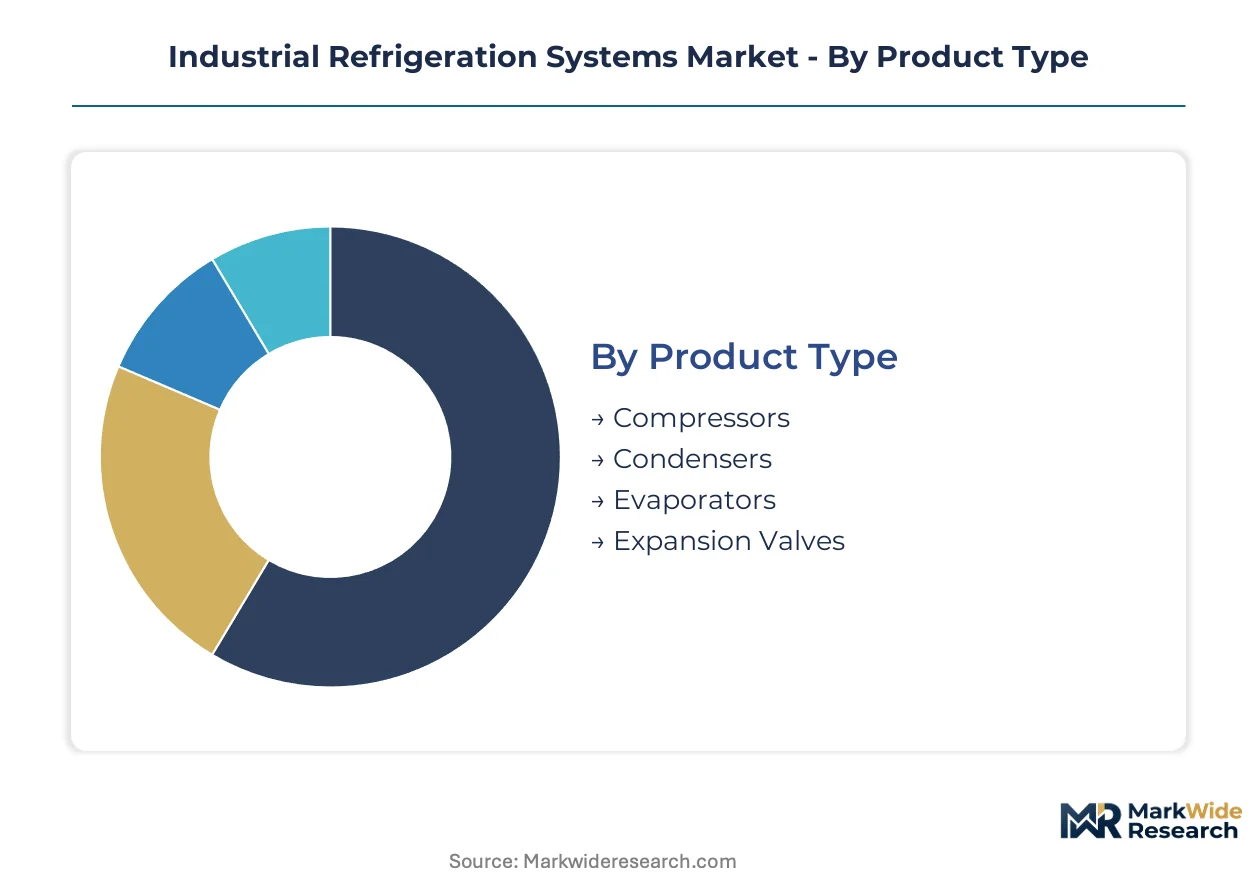
Industrial refrigeration procurement decisions split between capital-intensive component replacements and full-system architecture overhauls. Each segmentation dimension reveals distinct margin structures, technology transition timelines, and regulatory exposure profiles that reshape vendor positioning.
Product Type:
Compressors dominate capital allocation while condensers and evaporators present diverging replacement cycle economics.
- Compressors:Precision-manufactured reciprocating and screw compressors convert electrical energy into refrigerant pressure differentials through mechanical compression. Cold storage operators in the United States and Germany concentrate procurement here due to 15-20 year replacement cycles and AIM Act-driven system rebuilds.
- Condensers:Heat rejection assemblies utilizing air-cooled, water-cooled, or evaporative configurations discharge thermal energy to ambient environments. Chinese food processing clusters favor water-cooled variants for efficiency gains despite higher civil infrastructure requirements.
- Evaporators:Direct-expansion and flooded designs absorb heat from conditioned spaces through refrigerant phase change. Ammonia-compatible evaporator demand is climbing fastest in European retrofits.
- Expansion Valves:Thermostatic and electronic superheat controllers regulate refrigerant flow into evaporator circuits. Electronic expansion valve adoption is accelerating with IoT-enabled system integration.
Today's leader: Compressors. Tomorrow's challenger: Electronic expansion valves.
Technology:
Natural refrigerant architectures are displacing synthetic systems as regulatory phasedowns compress viable design windows.
- Vapor Compression:The dominant thermodynamic cycle employs mechanical compressors to drive refrigerant through condensation, expansion, and evaporation stages. Legacy HFC-based vapor compression installations face accelerated replacement in the United States under EPA enforcement schedules.
- Absorption:Heat-activated systems utilizing lithium bromide or ammonia-water pairs eliminate compressor electricity demand through thermal energy input. Industrial facilities with waste heat recovery potential in Germany specify absorption for base-load cooling.
- Cascade:Stacked refrigeration circuits pair CO2 low-temperature stages with ammonia or HFC high-temperature stages. European cold storage greenfield projects have standardized on CO2-over-ammonia cascade configurations.
- Thermoelectric:Solid-state Peltier devices generate temperature differentials through direct electrical current without moving parts. Niche pharmaceutical packaging applications in Switzerland utilize thermoelectric modules for portable temperature assurance.
Cascade configurations are climbing the fastest as natural refrigerant mandates harden across European and North American jurisdictions.
End User:
Volume concentration diverges sharply from margin capture across end-use verticals.
- Food Processing:Continuous refrigeration demand for protein, dairy, and prepared food manufacturing generates the largest installed base. United States meatpacking corridors in Nebraska and Iowa drive consistent compressor replacement demand.
- Pharmaceuticals:Vaccine production and biologics storage require validated temperature control with full documentation trails. German mRNA manufacturing facilities command premium pricing for compliant system architectures.
- Cold Storage:Third-party logistics operators manage multi-temperature distribution infrastructure for grocery and foodservice supply chains. Chinese e-commerce fulfillment networks are commissioning industrial-scale capacity expansions.
- Retail:Supermarket distribution centers and centralized kitchen facilities require distributed refrigeration with remote monitoring capabilities. Retail consolidation in the United States favors standardized equipment platforms across regional warehouse networks.
Pharmaceuticals capture the steepest margin premiums. Cold storage delivers the largest addressable volume expansion.
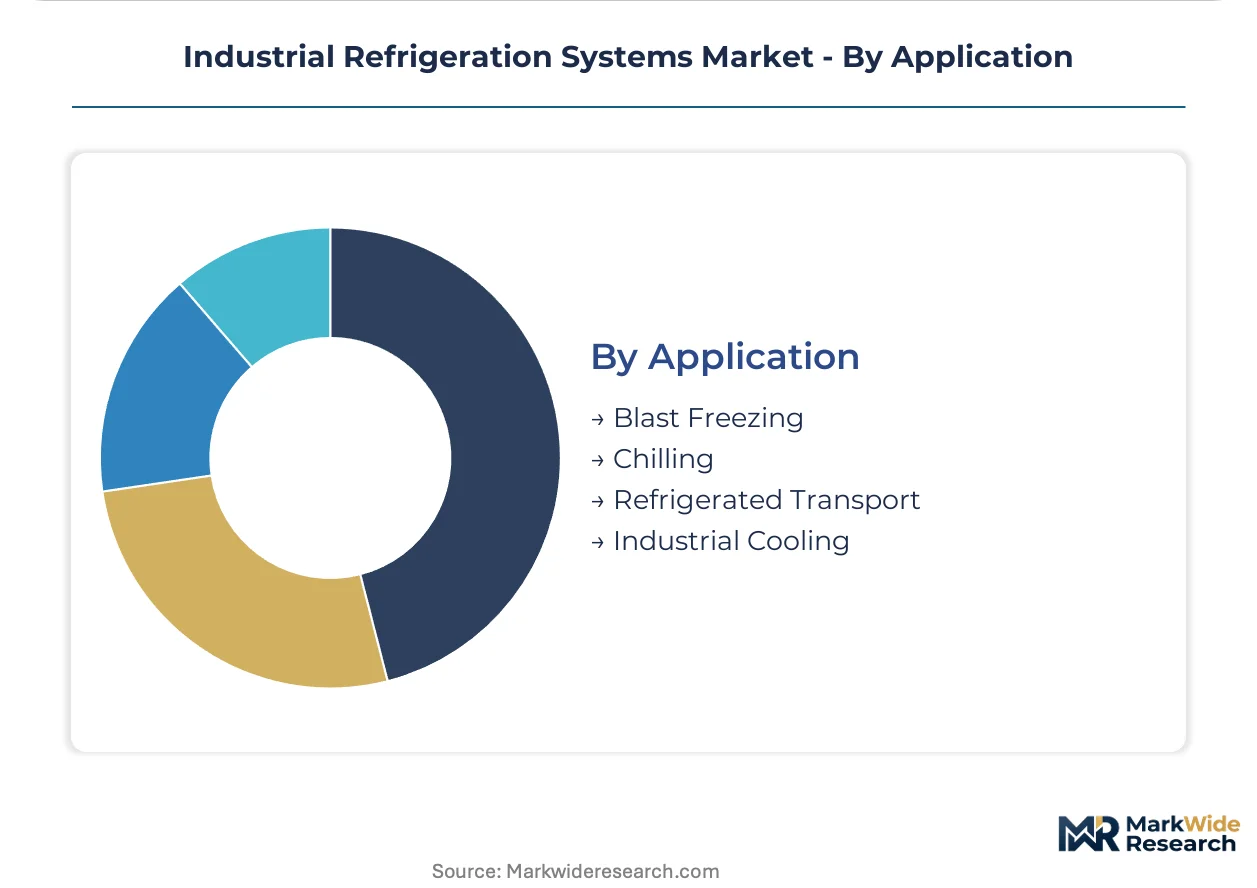
Application:
Process intensity and temperature precision requirements segment application economics.
- Blast Freezing:High-velocity air systems rapidly reduce product core temperatures to minus forty degrees Celsius for quality preservation. European seafood processors in Denmark and Norway specify ammonia-based blast freezing for energy efficiency.
- Chilling:Above-freezing temperature maintenance for fresh produce and dairy products dominates operational hour accumulation. California central valley vegetable processors run chilling systems continuously through harvest windows.
- Refrigerated Transport:Mobile container and vehicle-mounted units extend cold chain integrity through distribution legs. Chinese intermodal rail investments are pulling container refrigeration unit demand.
- Industrial Cooling:Process temperature control for chemical manufacturing and data center applications operates outside food safety regulatory frameworks. German chemical clusters along the Rhine specify industrial cooling with redundant compressor configurations.
Blast freezing commands the highest equipment specification intensity. Chilling generates the longest operational service contract durations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's cold storage buildout outpaces Germany's retrofit intensity, while the United States balances both greenfield expansion and regulatory-driven replacement cycles across distinct regional clusters.
United States
E-commerce grocery fulfillment networks in the Southeast and Texas are commissioning multi-temperature distribution centers requiring industrial-scale ammonia systems. The EPA's AIM Act HFC phasedown compresses replacement timelines for legacy installations. Nebraska and Iowa meatpacking corridors drive consistent compressor demand through 15-20 year replacement cycles.
Germany
mRNA vaccine manufacturing facilities along the Rhine corridor command premium pricing for validated temperature control architectures with full documentation trails. The EU F-Gas Regulation mandates escalating containment verification for synthetic refrigerant systems above specified charge thresholds. Bavarian and North Rhine-Westphalian chemical clusters specify redundant compressor configurations for process cooling applications.
China
Intermodal rail investments and fresh food e-commerce fulfillment networks pull demand for container refrigeration units and distributed cold storage infrastructure. National dual carbon goals accelerate CO2 transcritical adoption in southern provinces where ambient temperatures previously excluded economics. Yangtze River Delta food processing clusters favor water-cooled condenser configurations despite higher civil infrastructure requirements.
India
Post-harvest food loss reduction targets under national agricultural policy create procurement pull for distributed refrigeration units across fragmented cold chain infrastructure. The country's food safety regulator mandates temperature monitoring compliance for perishable commodity storage. Maharashtra and Gujarat pharmaceutical manufacturing zones specify imported compressor packages for validated storage applications.
Denmark
Protein processors have standardized on CO2-over-ammonia cascade configurations for new greenfield builds to eliminate synthetic refrigerant dependence entirely. REACH and EU leak detection frequency requirements shape equipment procurement specifications. Copenhagen-area cold storage operators bundle automated refrigerant monitoring sensors to satisfy third-party audit demands.
Industrial Refrigeration Systems Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-system integrators capturing premium pricing in pharmaceutical validation environments while component fabricators serve price-sensitive retrofit demand. The vendor base concentrates around three strategic archetypes: diversified industrial conglomerates with building automation portfolios, precision compressor specialists with long replacement cycle economics, and regional engineering firms with ammonia system certification depth. Competitive moves center on M&A to acquire IoT-enabled monitoring capabilities and capacity expansion in Southeast Asian fabrication hubs.
Among diversified industrial conglomerates, Johnson Controls and Emerson Electric Co. exemplify the automation-integrated archetype, bundling refrigeration hardware with energy management platforms and facility-wide control networks. GEA Group Aktiengesellschaft occupies a position within the custom-engineering tier, anchoring specialist capability for protein processing applications across Northern European markets. These three entities represent distinct strategic postures: platform breadth versus component precision versus vertical application depth.
| Leading Market Players |
|---|
| Johnson Controls |
| Emerson Electric Co. |
| GEA Group Aktiengesellschaft |
| Danfoss |
| Mayekawa |
| BITZER |
| EVAPCO Inc. |
| Daikin Industries Ltd. |
| LU-VE Group |
| Others |
Supply Flow & Price Mechanics
Certified ammonia refrigeration technicians concentrated in Northern Europe and the Upper Midwest United States anchor labor-cost differentials that widen pricing-tier spreads between premium validated systems and economy-grade packaged units. These geographic skill clusters force buyers in technician-scarce markets to absorb premium installation pricing or accept extended lead times.
Pricing Analysis
Capacity additions in Southeast Asian fabrication hubs are reshaping price floors for standard compressor packages while European greenfield projects sustain premium tier pricing. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-validated architectures with full documentation trails from food-processing commodity systems. Cost compression in standard-tier equipment stems from Chinese water-cooled condenser manufacturing scale. Cold storage REITs demonstrate highest price sensitivity due to portfolio-standardization mandates, while German mRNA manufacturers show least sensitivity given validation compliance requirements.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme for cold chain infrastructure are reshaping sourcing patterns for compressor packages and control systems. Manufacturing concentration centers on Germany for precision screw compressors, China for water-cooled condenser assemblies, and Denmark for CO2 cascade system integration. Supply chains draw from copper sheet and steel coil feedstocks, electronic expansion valve controllers, and ammonia-compatible sealing materials. Single-source vulnerability concentrates in European electronic expansion valve production. Distribution runs through OEM direct sales for large greenfield projects and specialized industrial distributors for retrofit components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on the shift from transactional hardware sales to recurring remote monitoring subscriptions, compressing customer acquisition costs while extending lifetime value.
For Market Incumbents: Deploy IoT-enabled refrigerant monitoring platforms as the anchor lever to capture recurring revenue streams and lock out component-only competitors. Acquire ammonia system certification capabilities in technician-scarce geographies like the southeastern United States to preempt installation bottlenecks. Defensive consolidation should target regional engineering firms with EPA Section 608 certification depth, as the AIM Act enforcement timeline accelerates retrofit demand beyond existing installer capacity. For New Entrants and Emerging Players: Direct-to-facility-engineer digital channels bypass incumbent distributor relationships and accelerate specification capture in fragmented cold storage markets. White-space targets include CO2 transcritical retrofits in southern China where ambient temperatures previously excluded economics, and distributed refrigeration units for India's post-harvest food loss reduction programs. Specification-selling through energy management platform partnerships offers the most penetrable go-to-market angle against bundled automation incumbents. For Investors and Strategic Acquirers: Building automation conglomerates are the most active acquirer in this space, seeking refrigeration specialists to complete energy management platform integration. Long-term viability favors targets with installed base density in pharmaceutical validation environments where replacement cycles extend and margin profiles sustain. Acquisition target archetype: regional ammonia system integrators with EPA certification and established relationships with protein processors. Watch CO2 transcritical technology cost curves as the inflection signal for warm-climate market penetration economics.| Strategic Initiative | Industry Significance |
|---|---|
| Remote Monitoring Platform Integration | Johnson Controls and Emerson Electric capture recurring service revenue from cold storage REITs through bundled energy dashboards. |
| Natural Refrigerant Certification Investment | EPA Section 608 and OSHA ammonia safety program capacity constraints create defensive moats for certified installers. |
| CO2 Transcritical Technology Licensing | Danfoss and BITZER penetrate southern United States and Chinese markets previously excluded by ambient temperature economics. |
| Backward Integration into Compressor Manufacturing | GEA Group secures precision screw compressor supply for protein processing greenfield builds across Northern Europe. |
| Joint Venture for Indian Cold Storage Infrastructure | Mayekawa and LU-VE Group address FSSAI temperature monitoring mandates through distributed refrigeration unit partnerships. |
Methodological Framework
Bottom-up cold storage operator and food processing facility modeling reconciled against top-down compressor manufacturer shipment tracking forms the analytical core of this study. Primary interviews with maintenance directors at multi-site cold storage REITs, plant engineers at protein processing facilities, OEM procurement teams at compressor fabricators, and aftermarket service heads at regional ammonia system integrators informed demand-side assumptions. Secondary validation drew from EPA AIM Act enforcement schedules, EU F-Gas Regulation containment databases, SEC 10-K filings of listed industrial conglomerates, and customs records of refrigeration equipment trade flows. Triangulation across these sources produced volume and value estimates.
Input-output matrices map compressor, condenser, evaporator, and control system production capacities against end-use demand across food processing, pharmaceutical, cold storage, and retail verticals throughout the forecast period. Segmentation dimensions include refrigerant architecture, temperature range application, facility scale tier, and regional regulatory cluster. CAGRs derive from installed base replacement cycle analysis and greenfield capacity expansion pipelines. Industry-specific forecast inputs incorporate EPA HFC phasedown enforcement intensity and EU REACH leak detection frequency requirements.
The model assumes a particular technology adoption path; alternative pathways for CO2 transcritical systems in warm climates would alter the outlook if ambient temperature economics shift faster than projected. Forecasts reflect assumptions regarding certification program capacity expansion and commodity input price stabilization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Battery Power Tools Market
Industrial Equipment
Diaphragm Coupling Market
Industrial Equipment
Fusion Splicer Market
Industrial Equipment
Automatic Laser Welding Machine Market
Industrial Equipment
Global DC Drives Market
Industrial Equipment
Magnetorheological Finishing (MRF) Machine Market
Industrial Equipment
Industrial Tags Market
Industrial Equipment
North America Industrial Centrifuge Market
Industrial Equipment
Global Linear Bearings Market
Industrial Equipment
Demagnetizer Market
Industrial Equipment
Europe Vacuum Pump Market
Industrial Equipment
UV Conveyor Systems Market
Industrial Equipment
Global Industrial Actuators Market
Industrial Equipment
TIG Torch Market
Industrial Equipment
United States Fusion Splicer Market
Industrial Equipment
Global Servo Presses Market