
 Precision Machine Market | 2026-2036
Precision Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Precision Machine Market Analytics
Aftermarket service revenue is reshaping profitability pools across the precision machine landscape. Proto Labs leverages its digital quoting platform to compress lead times for custom fabrication orders. Celestica Inc. anchors high-mix, low-volume production for aerospace and medical device OEMs. Xometry competes through distributed supplier networks that match capacity to demand spikes without fixed asset burdens.
Precision machines are computer-controlled equipment systems that remove material from metal, ceramic, or polymer workpieces to achieve dimensional tolerances typically within ±0.001 mm, serving industries where geometric accuracy determines functional performance. CNC Machining dominates current output volumes across turned parts and milled components, while Additive Manufacturing captures expanding prototype development and custom fabrication workflows as design-to-part cycle times compress. EDM technology specializes in hardened alloy geometries that conventional cutting cannot achieve, occupying premium niches in tool production and aerospace component finishing.
FDA quality system regulations and ISO 13485 medical device standards mandate documented process validation for contract manufacturers serving healthcare OEMs, raising compliance barriers for smaller shops. EPA metalworking fluid emissions rules and OSHA machining particulate limits add environmental and workplace safety compliance costs that favor scaled operators with dedicated EHS infrastructure. Buyers should monitor how NIST measurement traceability requirements and evolving EU machinery safety directives reshape supplier qualification criteria and cross-border equipment certification pathways.
Market Dynamics
Precision machine manufacturers face a structural squeeze between aerospace OEMs demanding tighter tolerances and contract shops absorbing compliance costs from FDA and EMA medical device quality mandates. The divergence between high-mix, low-volume medical work and high-volume automotive production is fragmenting supplier capabilities.
Growth Catalysts
- EMA MDR compliance deadlines:European medical device manufacturers are outsourcing validated CNC processes to contract specialists ahead of 2027 certification requirements, pulling capacity toward ISO 13485-qualified shops.
- Titanium aluminide turbine blades:Aerospace engine programs in Germany and the United States require five-axis machining of gamma alloys that conventional equipment cannot process, forcing capital upgrades across tier-one suppliers.
- Osaka-Tokyo manufacturing corridor:Japanese precision clusters are consolidating EDM and grinding expertise for semiconductor capital equipment, capturing spillover demand from Tokyo Electron and Nikon lithography supply chains.
Market Restraints
- Tungsten carbide supply concentration:Cutting tool substrate production clusters in China's Hunan province expose Western machine shops to export quota volatility and dual-use material restrictions.
- ISO 13485 validation timelines:Medical device contract manufacturers face 18-24 month qualification periods that freeze capacity allocation and deter mid-size shops from entering healthcare supply chains.
- Additive Manufacturing substitution:Metal powder bed fusion is capturing prototype and low-volume production previously routed to CNC machining, particularly for titanium orthopedic implants and aerospace brackets.
Strategic Opportunities
- Indian PLI scheme for medical devices:Domestic production incentives are attracting German and Japanese precision machine suppliers to establish joint ventures in Gujarat and Tamil Nadu medical device parks.
- In-process metrology convergence:Integration of optical measurement probes with live five-axis correction loops enables lights-out production for unmanned night shifts, compressing effective machine utilization rates.
- EPA metalworking fluid emissions rules:Near-dry and minimum quantity lubrication systems are qualifying for accelerated depreciation under US environmental compliance programs, subsidizing technology transitions for Midwest job shops.
Industry Challenges
- Five-axis programming expertise:CAM software complexity for simultaneous contouring exceeds the training pipeline output of US technical colleges, constraining shop floor expansion regardless of equipment availability.
- NIST measurement traceability audits:Aerospace prime contractors are demanding AS9100-certified labs with documented uncertainty budgets, disqualifying suppliers lacking interferometer calibration chains.
- Legacy ERP integration:Digital quoting platforms require API connections to shop floor data collection systems that 1980s-era MRP installations cannot support without six-figure middleware investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Precision Machine Market |
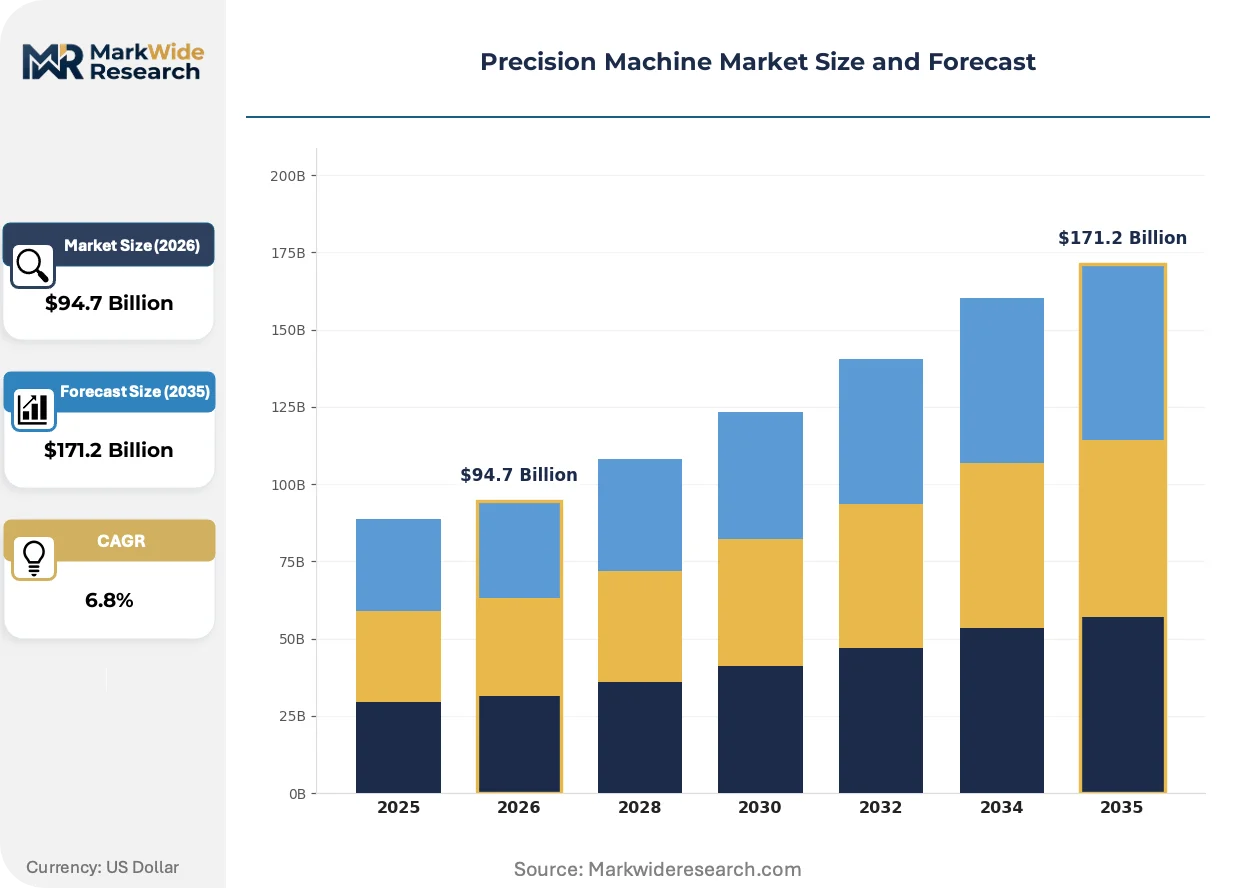
| Market Size in 2026 | $94.7 Billion |
| Market Size in 2035 | $171.2 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Turned Parts, Milled Components, Drilled Elements, Finished Assemblies Technology: CNC Machining, Laser Cutting, EDM, Additive Manufacturing End User: Aerospace, Automotive Suppliers, Medical Devices, Electronics Application: Tool Production, Prototype Development, Batch Manufacturing, Custom Fabrication |
| Companies Covered | DFF Corp., Proto Labs, Portland Precision Manufacturing Co., Celestica Inc., Xometry, Ultra Precision Machining & Grinding, Inc., The Federal Group USA, Impro Industries USA, Inc., Ace Precision, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Precision Machine Market Evolving Landscape
Digital thread architectures are collapsing design-to-part workflows across precision manufacturing, compressing iteration cycles and redefining competitive advantage around data continuity rather than equipment scale alone.
Ultrafast laser ablation systems operating at picosecond pulse durations are rendering obsolete mechanical polishing and chemical etching for hardened steel mold cavities. Medical implant manufacturers in Switzerland and Massachusetts are adopting these systems for surface finishing of cobalt-chrome acetabular cups, eliminating hand-finishing bottlenecks that previously constrained batch throughput.
EU Machinery Regulation updates mandating functional safety validation for autonomous robotic cells are forcing retrofits of existing CNC installations with safety-rated monitored stops and collaborative force-limiting features. German automotive suppliers operating 24-hour unmanned lines face six-figure compliance costs per machine center, accelerating consolidation toward integrated automation specialists with in-house TÜV certification capabilities.
Aftermarket service contracts are unbundling from equipment sales as buyers demand outcome-based availability guarantees rather than preventive maintenance schedules. Japanese machine tool distributors in the American Midwest are piloting spindle vibration monitoring subscriptions that trigger technician dispatch before thermal drift degrades part tolerances, converting capital equipment vendors into uptime insurance providers.
Precision Machine Market Segmentation
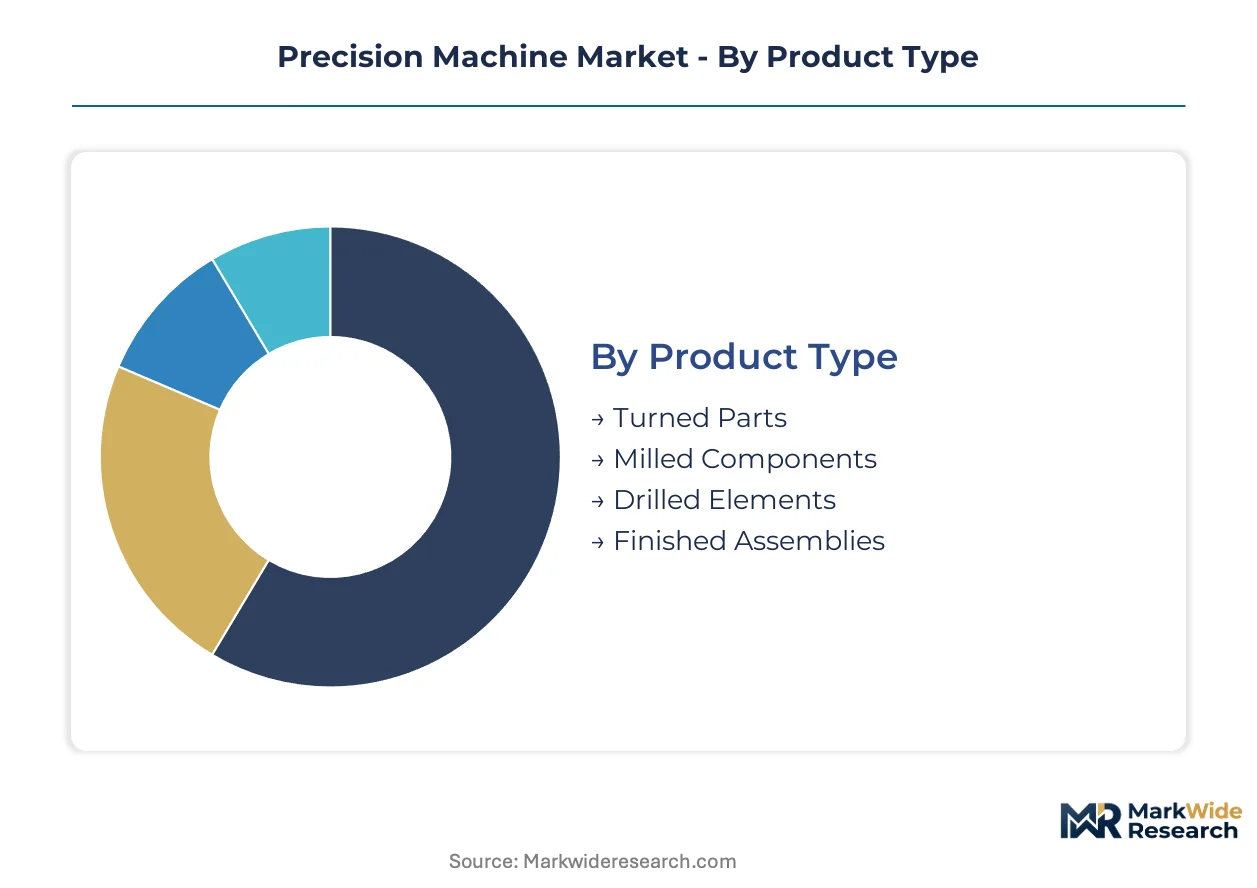
Precision machine market segmentation reveals how capability specialization determines supplier selection across radically different tolerance requirements and volume profiles. Distinct technology-product-application combinations command premium pricing power based on validation depth and geometric complexity rather than commodity machining capacity alone.
Product Type:
Mature geometries dominate current output volumes while emerging assembly formats capture expanding value pools through integrated subsystem supply.
- Turned Parts:Cylindrical components produced through rotational cutting achieve concentricity tolerances critical for shaft and bearing applications. German automotive suppliers and Japanese precision clusters in Aichi Prefecture concentrate demand for high-volume turned fuel injection components where cycle time optimization determines contract awards.
- Milled Components:Prismatic geometries requiring multi-axis contouring absorb the majority of five-axis programming expertise and capital investment. Aerospace engine programs in the United States and Germany specify milled titanium structural brackets where simultaneous five-axis motion eliminates fixture repositioning errors.
- Drilled Elements:Precision hole-making for fluid circuits and fastener patterns serves hydraulic manifold producers across Midwest US manufacturing corridors.
- Finished Assemblies:Subsystem integration combining machined elements with purchased components captures expanding medical device outsourcing from Swiss and Massachusetts OEMs.
Turned parts handle the majority of throughput; finished assemblies are gaining share fastest through OEM consolidation of supplier bases.
Technology:
Cost tier stratification separates established subtractive platforms from emerging digital fabrication methods with radically different capital intensity and skill requirements.
- CNC Machining:Computer-numerical control platforms executing programmed toolpaths across turning and milling centers constitute the installed base foundation. ISO 13485-validated CNC workflows in FDA-regulated medical device supply chains command 40-60% price premiums over general industrial work due to documentation burdens and audit frequency.
- EDM:Electrical discharge machining specializes in hardened alloy geometries beyond conventional cutting capability, occupying tool production and aerospace finishing niches. Japanese EDM specialists in the Osaka-Tokyo corridor dominate global supply for semiconductor capital equipment components requiring sub-micron surface finishes.
- Laser Cutting:High-speed sheet and tube processing serves automotive exhaust and appliance producers across US Midwest and German Ruhr manufacturing belts.
- Additive Manufacturing:Metal powder bed fusion and directed energy deposition capture prototype development and low-volume titanium orthopedic implant production previously routed to machining.
CNC machining anchors volume output; additive manufacturing shows the steepest expansion trajectory as design-to-part cycle compression accelerates adoption.
End User:
Application-driven margin differentiation separates regulated medical and aerospace verticals from price-sensitive automotive and electronics production.
- Aerospace:Turbine blade, structural bracket, and landing gear component production demands AS9100 certification and documented uncertainty budgets for dimensional measurement. EMA MDR compliance deadlines are pulling European aerospace suppliers toward validated process controls that mirror medical device rigor.
- Medical Devices:Implantable hardware and surgical instrument manufacturing requires FDA quality system regulation compliance and ISO 13485 certification with 18-24 month qualification timelines. Swiss cobalt-chrome acetabular cup producers and Massachusetts orthopedic OEMs concentrate demand for ultrafast laser surface finishing systems.
- Automotive Suppliers:Powertrain and chassis component machining operates at volume scale with compressed margins across German and US Midwest production corridors.
- Electronics:Semiconductor capital equipment and connector housing production in Japanese and Taiwanese precision clusters tolerates shorter validation cycles than medical or aerospace work.
Aerospace commands the highest per-part margins; medical devices are expanding most quickly through outsourcing acceleration ahead of regulatory deadlines.
Application:
Volume scale separates high-mix prototype services from dedicated batch production lines with divergent equipment utilization economics.
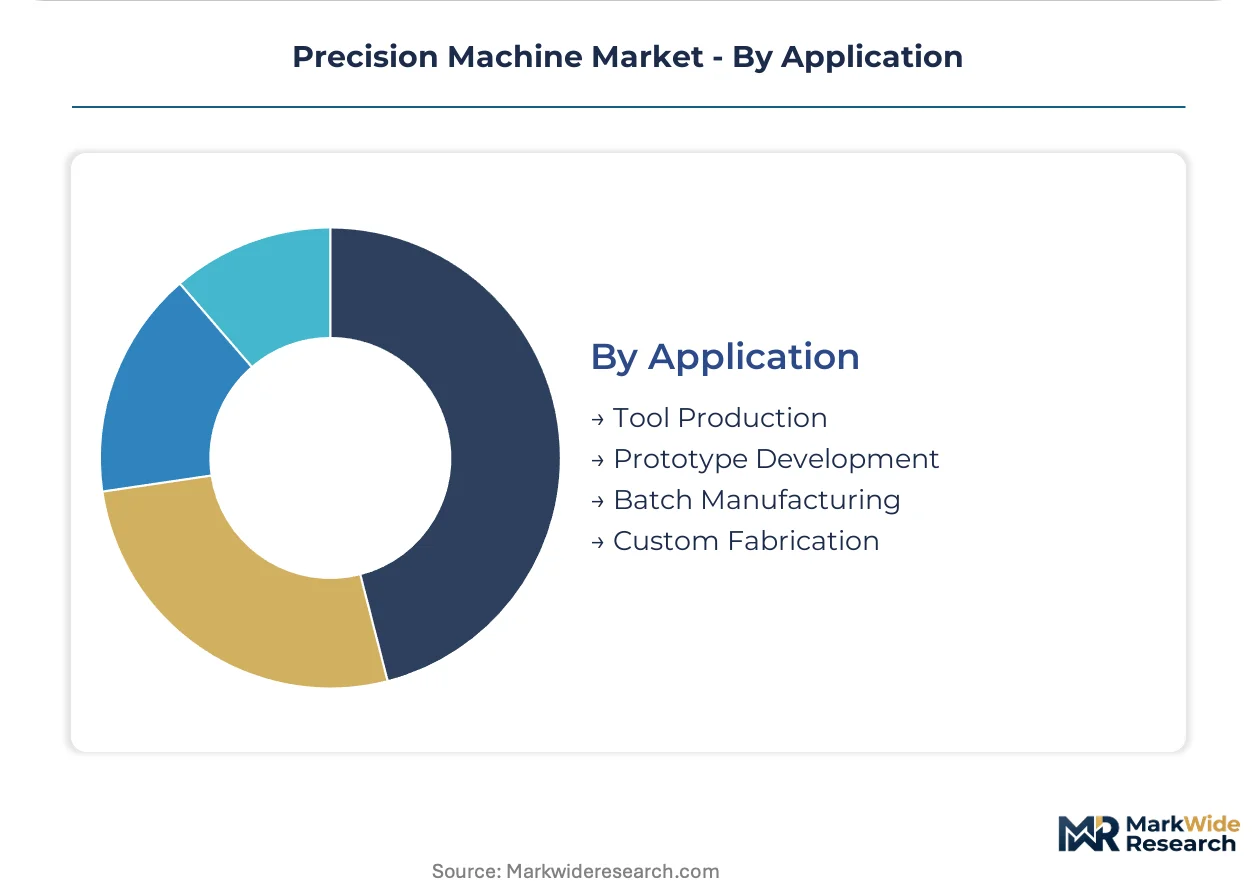
- Batch Manufacturing:Recurring production runs of validated part numbers enable equipment dedication, fixture amortization, and statistical process control implementation. German automotive suppliers and Japanese electronics capital equipment producers concentrate demand for unmanned night-shift batch production utilizing in-process metrology correction loops.
- Custom Fabrication:Engineer-to-order workflows responding to unique specifications capture premium pricing through digital quoting platforms and distributed supplier networks. US and European medical device OEMs increasingly outsource custom surgical instrument fabrication to validated contract specialists rather than maintaining captive machining capacity.
- Tool Production:Mold and die manufacturing for plastic injection and metal forming serves automotive and consumer goods producers across Chinese and German manufacturing bases.
- Prototype Development:Design iteration support for pre-production validation compresses lead times through additive manufacturing and rapid CNC programming.
Batch manufacturing absorbs the majority of equipment hours; custom fabrication is climbing the fastest as OEMs shed captive capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German aerospace OEMs prioritize five-axis machining for gamma titanium aluminide turbine blades, while Japanese precision clusters concentrate on EDM surface finishing for semiconductor capital equipment—revealing how geography dictates technology specialization rather than uniform adoption patterns.
United States
Midwest manufacturing corridors in Illinois, Michigan, and Ohio absorb the majority of automotive powertrain machining hours. EPA metalworking fluid emissions rules are accelerating near-dry lubrication system adoption across Ohio and Indiana job shops. Greater Boston and Massachusetts orthopedic OEMs concentrate demand for ultrafast laser surface finishing of cobalt-chrome acetabular cups.
Germany
Aerospace engine programs in Bavaria and Baden-Württemberg require simultaneous five-axis contouring of titanium structural brackets. EMA MDR compliance deadlines are pulling validated CNC capacity toward ISO 13485-qualified contract specialists in Baden-Württemberg. The Stuttgart-Tübingen precision cluster anchors gamma alloy machining expertise for turbine blade production.
Japan
Tokyo Electron and Nikon lithography supply chains drive EDM and grinding demand across the Osaka-Tokyo manufacturing corridor. METI industrial policy supports consolidation of sub-micron surface finishing capabilities for semiconductor capital equipment. Aichi Prefecture automotive suppliers concentrate high-volume turned fuel injection component production.
Switzerland
Swissmedic-regulated implant manufacturers in the Jura Arc and Lake Geneva region command premium pricing for validated cobalt-chrome machining workflows. ISO 13485 medical device standards mandate 18-24 month qualification timelines that freeze capacity allocation for contract specialists. Bern and Neuchâtel clusters specialize in orthopedic implant surface finishing through ultrafast laser ablation systems.
India
PLI scheme incentives for domestic medical device production are attracting German and Japanese precision machine suppliers to Gujarat and Tamil Nadu medical device parks. CDSCO quality system regulations are raising compliance barriers for contract manufacturers serving export markets. The Chennai-Bengaluru corridor is consolidating EDM and CNC machining capacity for semiconductor capital equipment spillover demand.
Precision Machine Market Competitive Landscape
Capability concentration sits with specialized EDM and five-axis machining shops; scale advantage sits with distributed digital platforms and integrated electronics manufacturing services. The market structures around three tiers: validated medical-aerospace specialists, high-mix digital fabricators, and commodity automotive suppliers. Dominant competitive moves include strategic partnerships for ISO 13485 qualification acceleration and technology licensing for in-process metrology integration.
Within the digital fabrication tier, Proto Labs and Xometry occupy positions exemplifying platform-based capacity matching. Among validated contract manufacturers, Celestica Inc. represents the integrated electronics manufacturing services archetype. Portland Precision Manufacturing Co. and Ultra Precision Machining & Grinding, Inc. sit within the specialized machining tier, anchoring geographic proximity advantages for Midwest US aerospace and medical device OEMs.
| Leading Market Players |
|---|
| DFF Corp. |
| Proto Labs |
| Portland Precision Manufacturing Co. |
| Celestica Inc. |
| Xometry |
| Ultra Precision Machining & Grinding, Inc. |
| The Federal Group USA |
| Impro Industries USA, Inc. |
| Ace Precision |
| Others |
Value Network & Pricing Analysis
Tungsten carbide supply concentration in China's Hunan province exposes Western machine shops to export quota volatility that simultaneously widens pricing tier spreads between certified medical-aerospace specialists and commodity automotive suppliers while compressing supplier margins through dual-use material restriction compliance costs.
Pricing Analysis
Long-term offtake contracts dominate validated medical device supply chains where ISO 13485-certified shops command 40-60% premiums over general industrial work, while spot-market transactions govern automotive powertrain components where volume scale determines contract awards. Price differentiation separates FDA-validated workflows with documented process traceability from commodity CNC capacity lacking certification depth. Pricing pressure stems from additive manufacturing substitution in titanium orthopedic implant production, eroding margins for low-volume machining specialists. Automotive suppliers exhibit highest price sensitivity due to compressed margins across German and US Midwest production corridors, while medical device OEMs absorb premium pricing for qualified capacity.
Supply Chain Analysis
Extended payment terms from aerospace prime contractors strain working capital across tier-one suppliers, forcing supply-chain finance facility adoption among mid-size contract shops. Cutting tool substrate production clusters in China, Germany, and Japan anchor upstream supply, drawing from tungsten carbide feedstocks and cobalt-chrome alloy inputs. Single-source vulnerability concentrates in Hunan province tungsten processing, exposing Western shops to export restriction risk. Distribution runs through validated contract manufacturer networks for medical-aerospace work and direct OEM procurement channels for automotive volume production.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The precision machine market tracks aerospace production cycles, with turbine blade program ramp-ups in Germany and the United States signaling recovery-phase capacity absorption ahead of OEM inventory restocking.
For Market Incumbents: Entrench ISO 13485-validated capacity through accelerated qualification timelines for medical device contract manufacturing, capturing outsourcing pull from EMA MDR compliance deadlines. Acquire in-process metrology capabilities to enable lights-out production economics, defending against additive manufacturing substitution in titanium orthopedic implant workflows. For New Entrants and Emerging Players: Pursue Indian PLI scheme joint ventures in Gujarat and Tamil Nadu medical device parks, exploiting domestic production incentives and underdeveloped precision machining infrastructure. Target semiconductor capital equipment spillover demand across the Chennai-Bengaluru corridor, leveraging lower-cost EDM and five-axis machining capacity against Japanese cluster pricing. For Investors and Strategic Acquirers: EMA MDR compliance deadlines reshape the acquisition landscape toward ISO 13485-qualified contract specialists with validated CNC workflows and documented uncertainty budgets. Five-to-ten year viability favors scaled operators with dedicated EHS infrastructure and TÜV certification capabilities. Watch FDA quality system regulation enforcement intensity as inflection indicator for medical device outsourcing acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Qualification Acceleration | EMA MDR deadlines pull European medical device outsourcing toward validated contract specialists with documented process controls. |
| In-Process Metrology Integration | Optical measurement probe adoption enables unmanned night-shift production for aerospace and medical device batch manufacturing. |
| Near-Dry Lubrication Transition | EPA metalworking fluid emissions compliance subsidizes technology upgrades across Midwest US job shops through accelerated depreciation. |
| Indian Joint Venture Formation | PLI scheme incentives attract German and Japanese precision suppliers to Gujarat and Tamil Nadu medical device parks. |
| Five-Axis Programming Pipeline Investment | CAM software complexity exceeds US technical college output, constraining shop floor expansion regardless of equipment availability. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, customs and trade databases, FDA quality system regulation documentation, and EMA MDR implementation guidance. Conversations with contract manufacturing executives, aerospace procurement directors, medical device quality affairs leads, and machine tool distributor operations heads inform demand-side validation. Bottom-up equipment shipment analysis triangulates against top-down OEM capital expenditure disclosures across German, Japanese, and United States manufacturing clusters.
Forecast inputs incorporate technology adoption curves for additive manufacturing substitution, regulatory compliance cost trajectories under FDA and EMA frameworks, and aerospace production cycle indicators. Segmentation modeling spans product type, technology platform, end-use vertical, and application mode across the projection horizon. CAGRs derive from equipment replacement cycles, outsourcing penetration rates in medical device supply chains, and capacity utilization trends in semiconductor capital equipment production.
Macroeconomic conditions sit as an overlay; deviation in aerospace OEM capital expenditure patterns, medical device regulatory enforcement intensity, or tungsten carbide supply availability would shift the trajectory. Forecasts reflect documented assumptions regarding EMA MDR implementation timelines, EPA metalworking fluid rule stringency, and additive manufacturing cost reduction curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Global Industrial Actuators Market
Industrial Equipment
Magnetizing Equipment Market
Industrial Equipment
Bellows Vacuum Suction Cup Market
Industrial Equipment
Latin America Explosion-Proof Equipment Market
Industrial Equipment
Global DC Drives Market
Industrial Equipment
Global Cryostat Market
Industrial Equipment
Global Flat Glass Tempering Machines Market
Industrial Equipment
Electric Cartridge Heaters Market
Industrial Equipment
Thermal Cleaning System Market
Industrial Equipment
Dustless Workstations Market
Industrial Equipment
Europe Vacuum Pump Market
Industrial Equipment
Microbubble Cleaning Device Market
Industrial Equipment
Digital Load Indicator Market
Industrial Equipment
Cleanroom Equipment Market
Industrial Equipment
Vertical Centrifugal Separator Market
Industrial Equipment
Conveyor Drive Market