
 Seawater Pump Market | 2026-2036
Seawater Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Seawater Pump Market Insights
Preventive maintenance contracts is repositioning how seawater pump vendors capture lifetime value from desalination and marine cooling clients. KSB Aktiengesellschaft leverages its global service network to lock in long-term aftermarket revenue across European and Middle Eastern installations. Desmi A/S anchors its competitiveness in offshore and shipboard segments through specialized corrosion-resistant engineering. Sundyne differentiates with high-speed integrally geared pump technology for high-pressure seawater injection duties.
A seawater pump is a fluid-handling device engineered to transport saline water with elevated chloride content, typically constructed from duplex stainless steel, super duplex alloys, or titanium to resist pitting and crevice corrosion at flow rates exceeding 1,000 cubic meters per hour. Its primary industrial purpose is to intake, circulate, or discharge seawater in desalination, thermal power generation, and offshore hydrocarbon processing. Centrifugal pumps dominate installed capacity due to their efficiency in high-flow, moderate-head applications, while submersible pumps represent the fastest-growing product category as offshore aquaculture and deep-water intake structures proliferate. Diaphragm pumps occupy a narrower but higher-margin niche in chemical dosing and precise metering within desalination pretreatment trains.
The EPA's Clean Water Act discharge standards and the EU's F-Gas Regulation shape pump efficiency mandates and refrigerant-based marine cooling system redesigns across North American and European installations. Saudi Arabia's national water regulator and China's MEE enforce escalating salinity control and energy consumption benchmarks that filter market access for non-compliant equipment suppliers. Stakeholders must monitor how corrosion-resistant material standards and carbon intensity disclosures converge to redefine total cost of ownership calculations in procurement decisions.
Market Dynamics
Preventive maintenance contracts are repositioning how seawater pump vendors capture lifetime value from desalination and marine cooling clients, locking in recurring revenue streams that offset cyclical equipment sales.
Growth Catalysts
- EU Green Deal water reuse directives:Tightening discharge standards across European desalination facilities are mandating pump upgrades with higher efficiency and corrosion resistance.
- Saudi Arabia's coastal megaprojects:National water infrastructure expansion is concentrating demand for high-capacity intake and circulation systems.
- Super duplex alloy adoption:Advanced metallurgy extending pump lifespans in chloride-rich environments is reducing total cost of ownership calculations for offshore operators.
Market Restraints
- Nickel and titanium price volatility:Raw material cost swings for corrosion-resistant alloys compress margins on fixed-price contracts.
- Foundry capacity concentration in East Asia:Limited qualified suppliers for super duplex castings create single-source vulnerabilities.
- Cavitation damage thresholds:Physical erosion limits at high suction speeds constrain operational flexibility in deep-water intake designs.
Strategic Opportunities
- Offshore aquaculture proliferation:Submersible pump demand for deep-water fish farming installations represents an underpenetrated vertical.
- China's MEE energy consumption benchmarks:Escalating efficiency mandates filter market access and reward compliant technology providers.
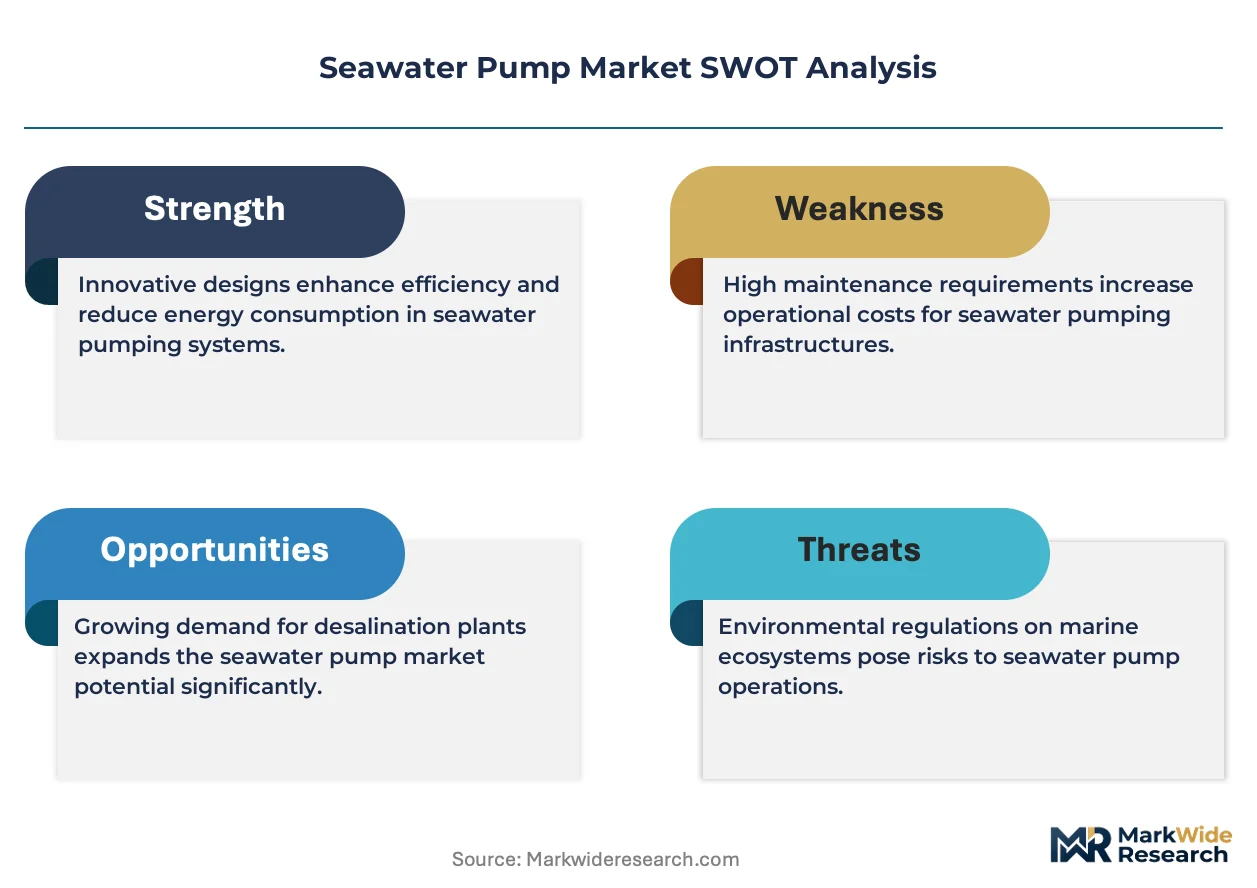
- Digital twin integration with predictive maintenance:IoT-enabled condition monitoring converges with service contracting to create differentiated vendor positioning.
Industry Challenges
- Welding certification for exotic alloys:Qualified technician scarcity delays field repairs and extends downtime in remote offshore locations.
- Legacy control system integration:Retrofitting variable frequency drives into existing SCADA architectures creates commissioning complexity and cost overruns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seawater Pump Market |
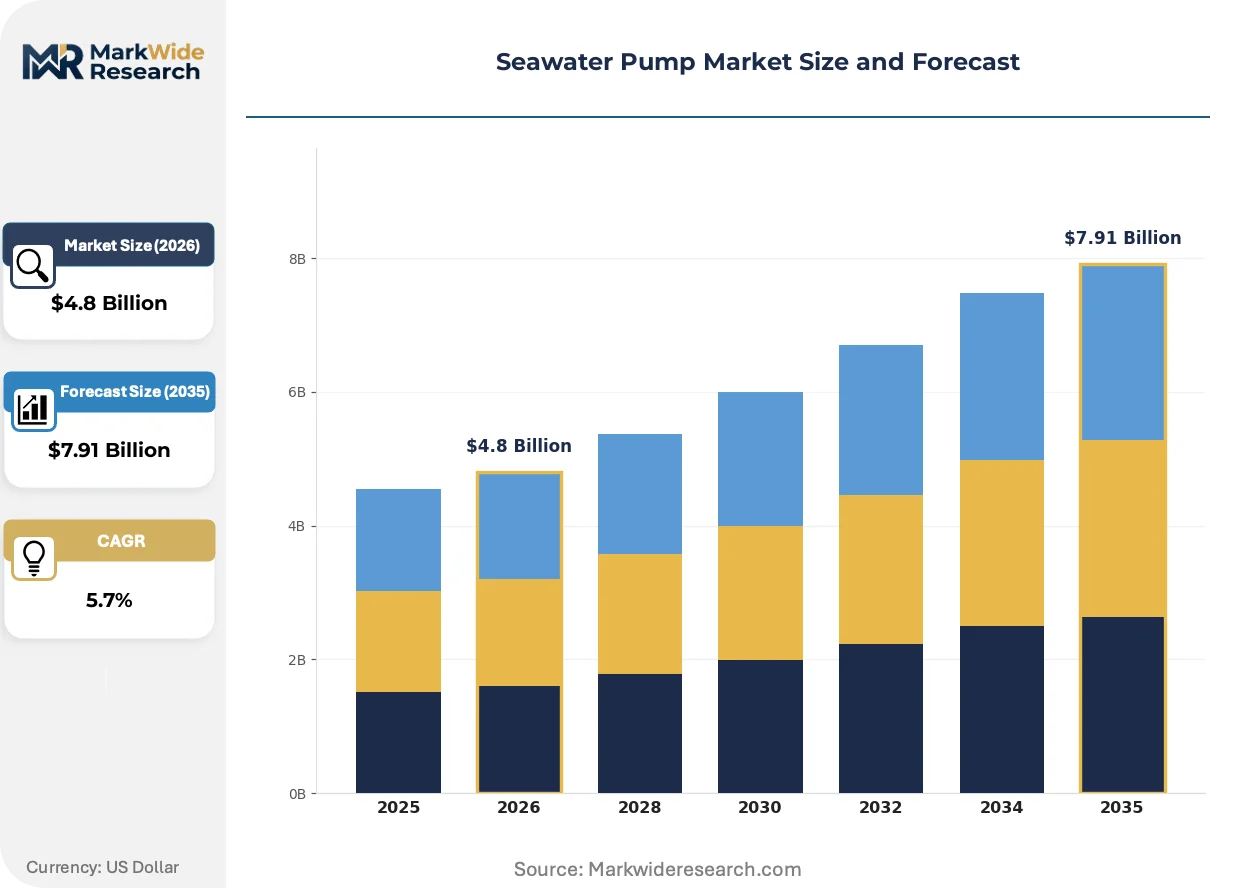
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Submersible Pumps, Centrifugal Pumps, Diaphragm Pumps, Positive Displacement Pumps Application: Desalination, Aquaculture, Marine Cooling, Water Circulation End User: Agriculture, Industrial, Municipal, Power Generation Installation: Onshore, Offshore, Coastal, Shipboard |
| Companies Covered | Lenntech B.V., Sundyne, Waterax, Tsurumi Manufacturing Co. Ltd., Crest Pumps Ltd., Rotech Pumps & Systems Inc., Dab Pumps Spa, Desmi A/S, KSB Aktiengesellschaft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seawater Pump Market Trends and Innovations
Electrification of pump drivetrains and predictive analytics integration are compressing maintenance intervals while expanding operational envelopes for high-salinity applications.
Permanent magnet synchronous motor technology paired with variable frequency drives is electrifying efficiency benchmarks in high-flow seawater intake duties. Desalination plant operators in the Middle East are retrofitting existing installations to capture energy savings. This electrification is compressing the payback period for capital-intensive pump upgrades from seven years to under four.
The EPA's Clean Water Act discharge standards are tightening permissible thermal and chemical effluent limits for coastal power generation facilities. American utilities are redesigning cooling water circuits to reduce intake volumes and improve entrainment protection. Combined-cycle gas turbine installations in Florida and California face the most acute compliance timelines and are accelerating pump procurement cycles.
Long-term service agreements are displacing transactional equipment sales as the dominant commercial model in European desalination markets. EPC contractors are unbundling aftermarket risk and transferring operational accountability to OEM service networks. This restructuring is most advanced in Spanish and Italian municipal water projects where public-private partnership frameworks dominate procurement.
Seawater Pump Market Segmentation
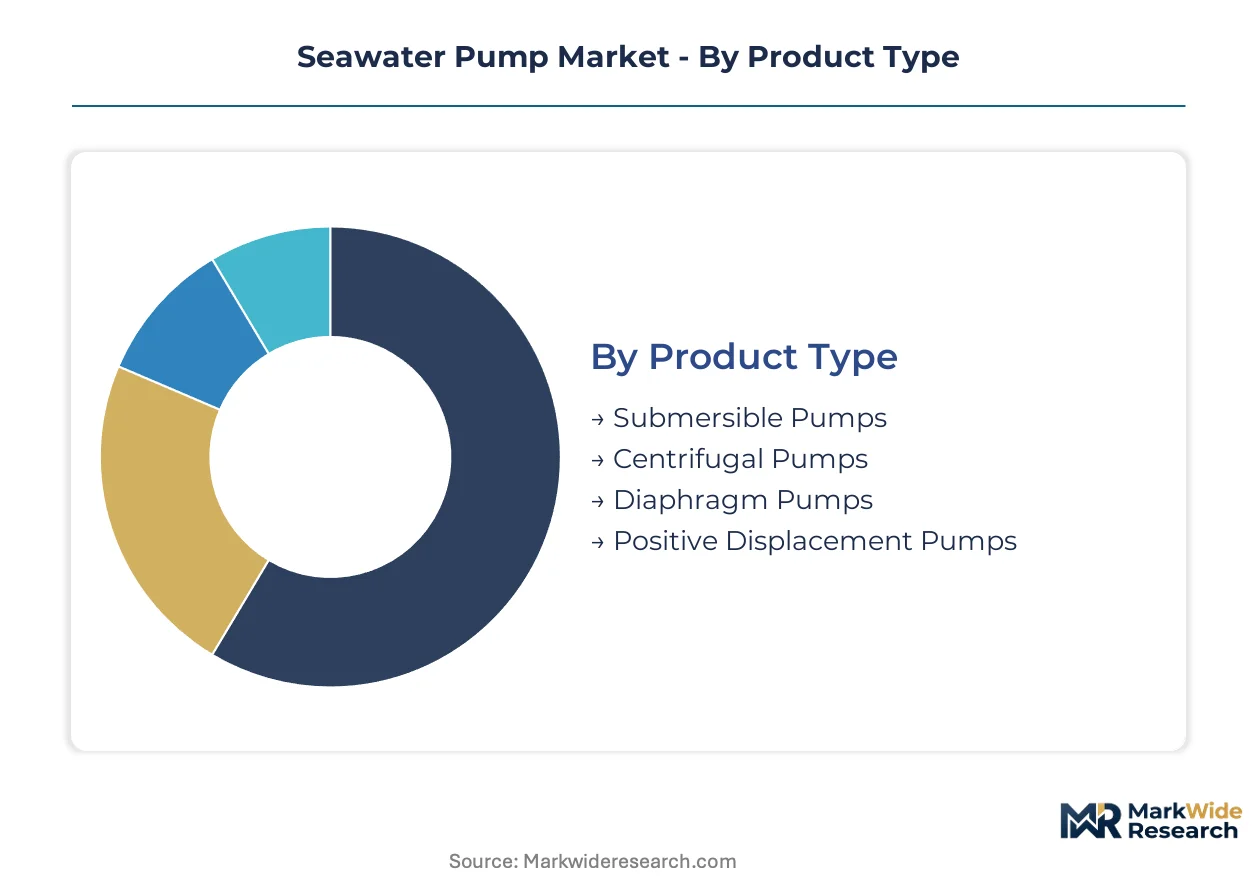
Seawater pump procurement decisions diverge sharply across operating environments, from high-volume desalination intakes requiring continuous duty cycles to intermittent shipboard ballast operations. Equipment specifications, metallurgy grades, and service contracting terms all pivot on which segment axis dominates the buyer's technical requirements.
Product Type:
Capital intensity escalates dramatically with submersible configurations, where deep-water pressure housings and sealed motor assemblies multiply upfront equipment costs against surface-mounted alternatives.
- Centrifugal Pumps:Single-stage and multistage impeller designs dominate high-flow, moderate-head duties across desalination pre-treatment and cooling water circuits. Demand concentrates in Saudi Arabia's coastal megaprojects where intake volumes exceed 10,000 cubic meters per hour, though cavitation susceptibility at high suction speeds constrains deep-water deployment.
- Submersible Pumps:Fully sealed motor-pump units engineered for direct immersion eliminate suction lift limitations and reduce civil infrastructure requirements. Offshore aquaculture installations in Norwegian and Chilean waters are driving specification upgrades for pressure-rated enclosures and corrosion-resistant cable penetrations.
- Diaphragm Pumps:Positive displacement mechanisms deliver precise chemical dosing for desalination pre-treatment trains.
- Positive Displacement Pumps:Rotary and reciprocating architectures handle high-viscosity fluids and abrasive-laden seawater in specialized hydrocarbon processing duties.
Most installed capacity flows through Centrifugal Pumps. Expansion is steepest in Submersible Pumps.
Application:
Margin structures vary by duty cycle intensity, with continuous-process desalination commanding premium pricing against intermittent aquaculture or shipboard applications.
- Desalination:Reverse osmosis and thermal distillation facilities require corrosion-resistant intake, booster, and brine discharge pumps operating at 90%+ annual availability. EU Green Deal water reuse directives are tightening discharge standards across Spanish and Italian municipal installations, accelerating pump replacement cycles.
- Marine Cooling:Coastal power generation and industrial facilities circulate seawater through condensers and heat exchangers. American utilities in Florida face acute EPA Clean Water Act compliance timelines for entrainment protection, compressing procurement decisions.
- Aquaculture:Oxygenation and water exchange systems for offshore fish farming represent an underpenetrated vertical with specialized submersible requirements.
- Water Circulation:Harbor flushing, marina circulation, and coastal flood management applications operate at lower pressure differentials with reduced metallurgical specifications.
Desalination absorbs the majority of high-value pump shipments. Aquaculture is climbing the fastest as deep-water farming platforms proliferate.
End User:
Procurement authority concentrates differently across customer types, with municipal tenders emphasizing lifecycle cost against industrial buyers prioritizing operational uptime guarantees.
- Power Generation:Combined-cycle and thermal plants require massive circulating water pumps with decades-long service intervals. China's MEE energy consumption benchmarks are filtering market access for non-compliant suppliers.
- Municipal:Public water authorities and desalination utilities drive standardization through framework agreements and public-private partnerships.
- Industrial:Petrochemical and mining operations demand ruggedized configurations for abrasive-laden seawater handling.
- Agriculture:Coastal irrigation and greenhouse operations utilize smaller-capacity units with lower specification thresholds.
Power Generation accounts for the largest share of super duplex alloy consumption. Municipal procurement is expanding most quickly under concession financing structures.
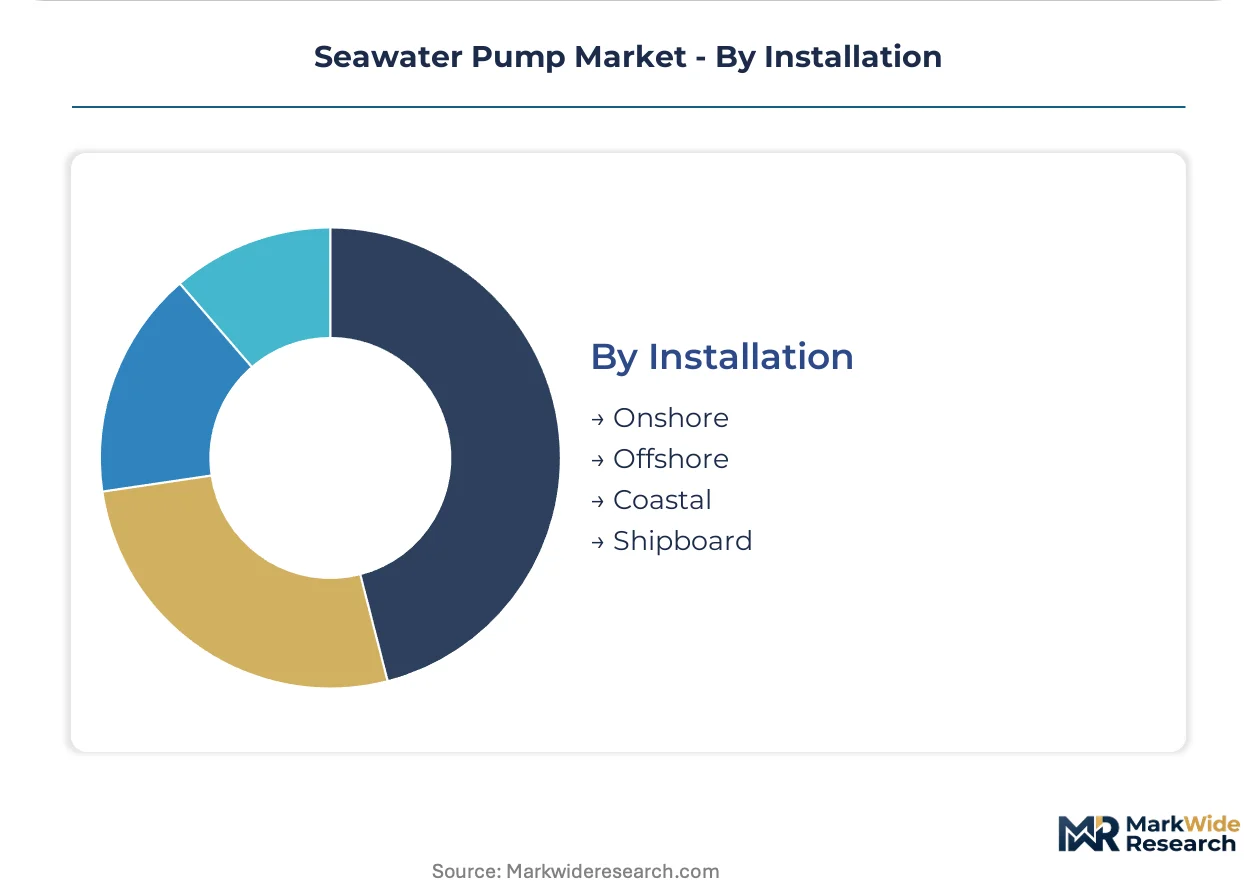
Installation:
Supply chain configuration and field service reach determine competitive positioning, with offshore and shipboard segments rewarding vendors with specialized marine engineering capabilities.
- Offshore:Platform-mounted and subsea installations demand pressure-rated housings, remote monitoring integration, and helicopter-accessible maintenance protocols. Norwegian North Sea operators and Brazilian pre-salt developments specify API-compliant designs with 25-year design lives.
- Shipboard:Space-constrained marine vessels require compact, vibration-isolated pump packages with classification society certifications. Specialized corrosion-resistant engineering anchors competitiveness in this segment.
- Onshore:Land-based installations benefit from conventional maintenance access and standard foundation requirements.
- Coastal:Intertidal and near-shore structures face unique biofouling and storm surge exposure profiles.
Onshore sites host the majority of existing pump population. Offshore installations are gaining share fastest as hydrocarbon and aquaculture activity moves into deeper waters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's coastal megaprojects absorb more super duplex alloy tonnage than Germany's entire desalination sector, yet European regulatory tightening is accelerating replacement cycles faster than Middle Eastern capacity expansion.
Saudi Arabia
NEOM and the Red Sea Project are driving procurement of high-capacity intake pumps exceeding 10,000 cubic meters per hour. The national water regulator enforces escalating salinity control benchmarks that filter non-compliant suppliers. Jeddah and Jubail Industrial City host concentrated fabrication and installation activity for reverse osmosis facilities.
United States
Combined-cycle gas turbine installations in Florida and California face acute EPA Clean Water Act compliance timelines for entrainment protection. The EPA's tightening thermal and chemical effluent limits are compressing procurement decisions for coastal power generators. Tampa Bay and San Diego clusters are retrofitting cooling water circuits with upgraded circulation systems.
China
The Ministry of Ecology and Environment enforces energy consumption benchmarks that reward compliant pump technology providers. Thermal power plants along the eastern seaboard are replacing legacy circulating water pumps to meet dual carbon goals. Shandong and Jiangsu provinces concentrate manufacturing capacity for super duplex castings.
Germany
The EU Green Deal's water reuse directives mandate efficiency upgrades across municipal desalination installations. The F-Gas Regulation shapes refrigerant-based marine cooling system redesigns for North Sea and Baltic coastal facilities. Hamburg and Bremen harbor zones are integrating predictive maintenance protocols into public-private partnership frameworks.
Norway
Offshore aquaculture platforms in Norwegian waters are specifying pressure-rated submersible enclosures for deep-water fish farming. The Norwegian Maritime Authority enforces classification society certifications for helicopter-accessible maintenance protocols. Trøndelag and Nordland counties host proliferating salmon farming installations with specialized pumping requirements.
Seawater Pump Market Competitive Landscape
Top-tier vendors anchor premium-tier positioning through global service networks, while mid-scale specialists occupy corrosion-resistant engineering niches. The vendor base stratifies across three tiers: integrated multinationals with captive aftermarket capabilities, regional fabricators with foundry-to-field integration, and technology licensors with specialized high-speed or submersible designs. Dominant competitive moves include preventive maintenance contract unbundling from EPC risk and digital twin integration with IoT-enabled condition monitoring.
Within the integrated multinational tier, KSB Aktiengesellschaft and Desmi A/S exemplify divergent strategic anchors. KSB represents the global service network archetype with aftermarket revenue capture across European and Middle Eastern installations. Desmi occupies a position within specialized marine engineering, exemplifying corrosion-resistant competency for offshore and shipboard segments. Sundyne sits within the high-speed technology specialist tier, representing integrally geared pump architectures for high-pressure injection duties.
| Leading Market Players |
|---|
| Lenntech B.V. |
| Sundyne |
| Waterax |
| Tsurumi Manufacturing Co. Ltd. |
| Crest Pumps Ltd. |
| Rotech Pumps & Systems Inc. |
| Dab Pumps Spa |
| Desmi A/S |
| KSB Aktiengesellschaft |
| Others |
Pricing and Supply Chain Analysis
Nickel and titanium price indices on the London Metal Exchange cascade through super duplex alloy procurement into three-tier pricing structures across premium, standard, and economy pump tiers. Foundry capacity concentration in East Asia amplifies cost pass-through volatility for corrosion-resistant castings, compressing margins on fixed-price EPC contracts while rewarding vendors with captive metallurgical supply.
Pricing Analysis
Capacity additions in Shandong and Jiangsu provinces are reshaping price floors for standard-grade centrifugal pumps serving municipal desalination clients. Project-based contracting with long-term service bundling dominates premium tiers, while spot procurement governs economy segments for intermittent aquaculture duties. Price differentiation hinges on API certification grade and super duplex alloy content. Cost compression in the standard tier intensifies because Chinese foundries are expanding super duplex casting output. Municipal utilities exhibit highest price sensitivity due to concession financing constraints; offshore oil operators show least sensitivity given uptime guarantee priorities.
Supply Chain Analysis
Qualified welding technicians for exotic alloys remain scarce in European and Middle Eastern fabrication hubs, extending repair lead times and inflating field service premiums. Manufacturing gravity centers on China, Germany, and Saudi Arabia for foundry-to-field integration. The supply chain draws from nickel ore concentrates, titanium sponge, and rare earth elements for permanent magnet motors. Single-source vulnerability concentrates in East Asian super duplex casting capacity. Distribution runs through EPC contractor networks with OEM aftermarket service layering.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The seawater pump market functions as a stable compounder anchored by irreversible desalination capacity expansion in water-stressed coastal economies. Recurring service revenue streams dampen cyclicality and support predictable cash flow profiles across the vendor base.
For Market Incumbents: Extend preventive maintenance contract penetration to lock in lifetime value from Saudi coastal megaprojects and European municipal utilities. Deepen backward integration into super duplex alloy supply through offtake agreements with Shandong foundries. Counter margin pressure from Chinese cost leaders by embedding digital twin capabilities that elevate switching costs for desalination operators.
For New Entrants and Emerging Players: Submersible pump electrification with permanent magnet synchronous motors offers a technology-first wedge against established centrifugal incumbents. Target Norwegian and Chilean offshore aquaculture installations where specialized corrosion-resistant engineering requirements filter out generalist competitors. Pursue pilot-to-scale partnerships with salmon farming operators seeking pressure-rated deep-water pump packages.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale specialists commanding foundry-to-field integration and captive super duplex casting capacity. The five-to-ten year viability window favors vendors positioned at the intersection of EU Green Deal compliance and Middle Eastern capacity expansion. Watch for inflection in China's MEE enforcement intensity as the signal for accelerated replacement cycle timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Preventive Maintenance Contract Expansion | Locks recurring revenue from Saudi desalination megaprojects and European municipal utilities. |
| Super Duplex Alloy Backward Integration | Captures margin from nickel price volatility through Shandong foundry offtake structures. |
| Digital Twin Platform Deployment | Converges IoT condition monitoring with service contracting for differentiated vendor positioning. |
| Submersible Electrification R&D | Permanent magnet motor adoption compresses payback periods for Middle East retrofit installations. |
| Offshore Aquaculture Partnership | Pilot-to-scale agreements with Norwegian salmon operators penetrate underdeveloped vertical demand. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to construct demand and supply estimates. Primary fieldwork engaged desalination plant engineering directors, EPC contractor procurement leads, foundry operations managers, aftermarket service heads, and municipal utility planning officers. Secondary validation drew from customs trade data for pump and alloy shipments, SEC filings for listed pump manufacturers, EU Green Deal regulatory disclosures, and Saudi national water regulator capacity announcements. Bottom-up unit economics and top-down macro allocation triangulated to final market sizing.
Historical reference periods anchored the projection horizon through verified installation data and replacement cycle analysis. The analytical framework modeled segmentation across product type, application intensity, end-user procurement authority, and installation environment complexity. CAGRs derived from segment-level growth rate synthesis weighted by revenue exposure. Forecast inputs incorporated super duplex alloy price trajectories, desalination capacity buildout pipelines, and regulatory compliance timeline acceleration.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to nickel price volatility, foundry capacity expansion timing, and MEE enforcement intensity in China. The analysis reflects documented assumptions on replacement cycle duration and service contract attach rates. Material deviation in alloy cost trajectories or regulatory compliance deadlines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Self-Priming Centrifugal Pump Market
Pumps and Control Devices
Reverse Osmosis Pump Market
Pumps and Control Devices
Fire Pump Test Meters Market
Pumps and Control Devices
Centrifugal Water Pump Market
Pumps and Control Devices
Intelligent Pump Market
Pumps and Control Devices
Vacuum Pump Stations Market
Pumps and Control Devices
Air Breathing Hose Market
Pumps and Control Devices
Global Self Priming Pumps Market
Pumps and Control Devices
Fuel Transfer Pump Market
Pumps and Control Devices
Global Lobe Pumps Market
Pumps and Control Devices
Europe Centrifugal Pumps Market
Pumps and Control Devices
Automatic Tube Cleaning System Market
Pumps and Control Devices
Vertical Inline Pumps Market
Pumps and Control Devices
Fluid Power Equipment Market
Pumps and Control Devices
Global Hydraulic Gear Pump Market
Pumps and Control Devices
Global Vacuum Pump Market