
 Rotary Tools Market | 2026-2036
Rotary Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Rotary Tools Market Analytics
Home improvement is restructuring demand composition across the rotary tools landscape as residential renovation activity shifts channel mix toward big-box retail and direct-to-consumer platforms. Milwaukee leverages its battery ecosystem dominance to anchor cordless rotary tool penetration in professional trades. Bosch competes through brushless motor technology leadership and integrated dust extraction compatibility. Dremel specializes in precision accessory ecosystems that extend its grip on engraving and light-duty crafting applications.
Rotary tools are handheld power devices employing high-speed rotating collets, typically operating between 5,000 and 35,000 RPM, to perform cutting, grinding, polishing, and engraving tasks across metal, wood, and composite substrates. Cordless rotary tools are capturing growth momentum as lithium-ion battery energy density improvements enable runtime parity with corded alternatives in intermittent-use applications. Brushless motor technology commands premium positioning due to thermal efficiency gains and extended service intervals, while pneumatic rotary tools retain durable demand in fixed manufacturing lines where compressed air infrastructure already exists. The engraving application segment is gaining traction among small-scale jewelry and signage producers seeking desktop precision capabilities.
OSHA workplace silica exposure limits in the United States and REACH chemical compliance requirements in Europe are compelling manufacturers to redesign guard systems and specify sealed bearing architectures. The EU Green Deal circular economy provisions are pressuring battery-powered tool platforms toward standardized cell formats and end-of-life recyclability. Stakeholders must monitor regulatory divergence between North American and European safety certification paths when configuring regional product portfolios and service networks.
Market Dynamics
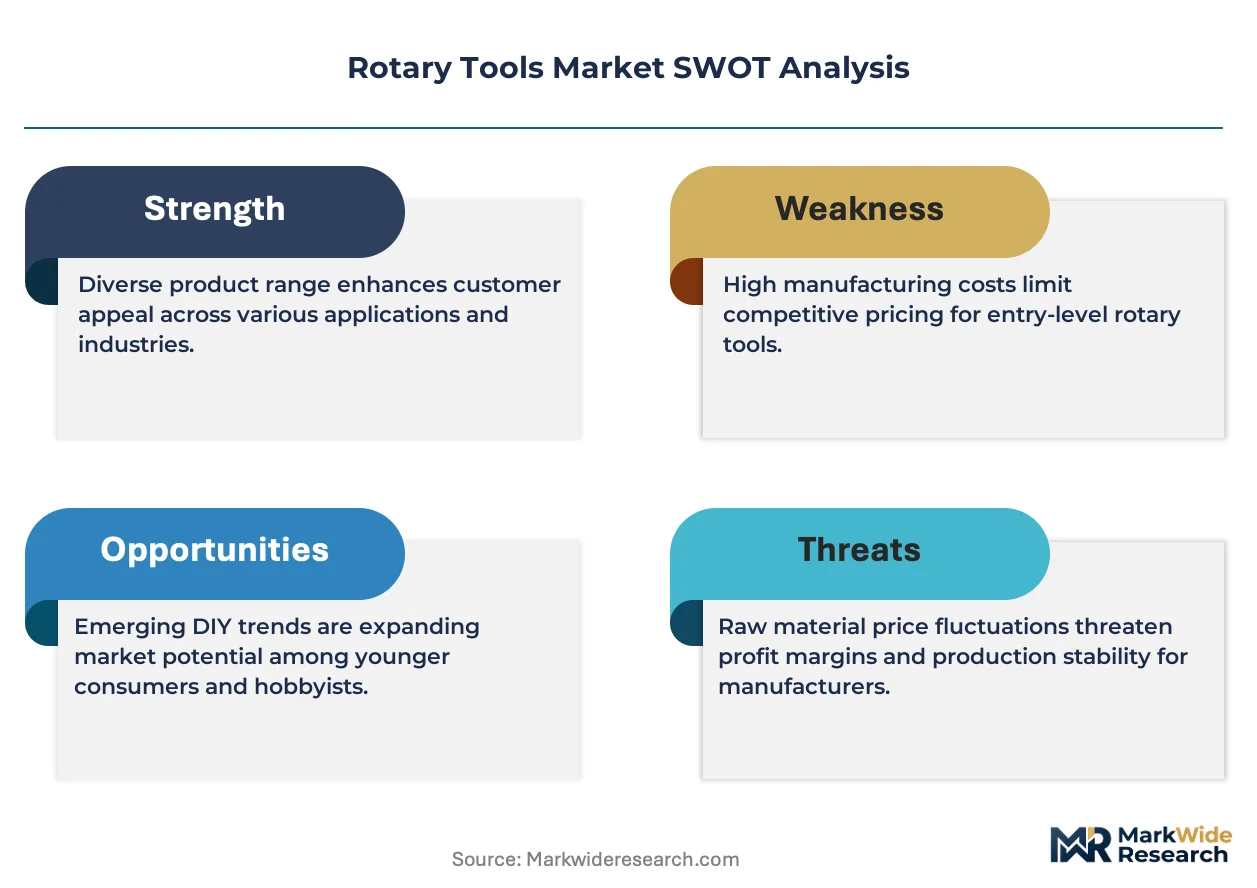
Brushless motor technology is consolidating competitive advantage across the rotary tools landscape as thermal efficiency requirements intensify and professional users demand extended service intervals. This platform shift is redrawing supplier hierarchies and compressing margins for legacy motor architectures.
Growth Catalysts
- OSHA Silica Exposure Limits:United States workplace safety mandates are compelling professional contractors to upgrade dust-extraction-compatible rotary tool systems. Equipment replacement cycles are shortening as compliance deadlines approach.
- Residential Renovation Surge:Home improvement retail channels are capturing elevated household spending on DIY finishing and repair tasks. Big-box retailers are expanding dedicated rotary tool aisle space to match traffic.
- Lithium-Ion Energy Density Gains:Battery chemistry improvements are delivering runtime parity between cordless and corded rotary tools for intermittent-use applications. Cordless platforms are displacing pneumatic alternatives in mobile job site environments.
Market Restraints
- Rare Earth Magnet Supply Concentration:Neodymium and dysprosium sourcing dependencies in China are exposing brushless motor producers to price volatility and export restriction risks. Alternative magnet formulations remain cost-prohibitive at scale.
- Compressed Air Infrastructure Lock-In:Pneumatic rotary tool demand persists in fixed manufacturing lines where capital investment in air compressor systems creates switching costs. Cordless penetration faces structural ceilings in heavy-duty continuous-use settings.
- REACH Chemical Compliance Burden:European Union substance restrictions on coatings and lubricants are extending product development timelines and testing expenditures. Smaller accessory manufacturers lack regulatory affairs capacity.
Strategic Opportunities
- EU Green Deal Circular Economy Provisions:Battery standardization mandates and end-of-life recyclability requirements are creating first-mover advantages for modular tool platform designs. Remanufacturing service networks can capture recurring revenue streams.
- Jewelry and Signage Micro-Production:Desktop precision engraving applications are proliferating among small-scale artisans and custom fabricators. Accessory ecosystem depth determines supplier selection in this fragmented buyer base.
- Direct-to-Consumer Platform Expansion:E-commerce channels are bypassing traditional distributor markups for light-duty rotary tool categories. Video-centric product demonstration formats are compressing purchase consideration cycles.
Industry Challenges
- Brushless Motor Controller Firmware Expertise:Power electronics engineering talent scarcity is constraining product development velocity for mid-tier manufacturers. Recruitment competition with electric vehicle and renewable energy sectors intensifies compensation pressure.
- Dual Certification Path Divergence:UL and CE marking testing requirements are diverging on electrical safety and electromagnetic compatibility standards. Parallel certification programs extend launch timelines and fragment engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rotary Tools Market |
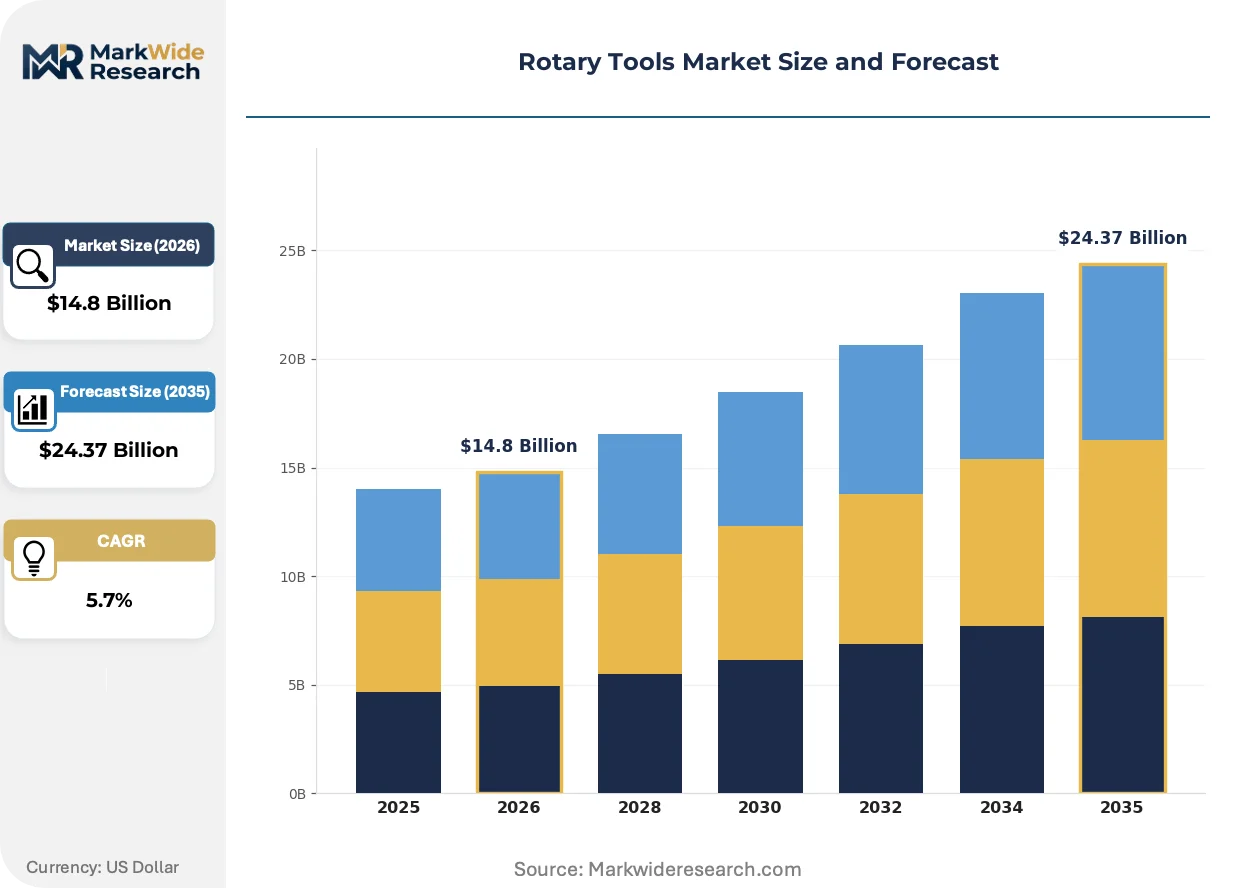
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.37 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Rotary Tools, Pneumatic Rotary Tools, Cordless Rotary Tools, Mini Rotary Tools End User: Manufacturing, Metalworking, Woodworking, Home Improvement Technology: Brushless Motor, Brush Motor, Variable Speed, High Torque Application: Cutting, Grinding, Polishing, Engraving |
| Companies Covered | Milwaukee, Craftsman, Dremel, Worx, Ryobi, Bosch, Stanley Black & Decker, Proxxon, Makita, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rotary Tools Market Evolving Landscape
Intelligent motor control systems are embedding diagnostic and connectivity capabilities into rotary tool platforms, transforming hardware into data-generating assets. This convergence is enabling predictive maintenance models and usage-based service monetization.
Brushless motor architecture is integrating Hall-effect sensors and field-oriented control algorithms to deliver torque stability across variable load conditions. Professional trades in Germany and the United States are specifying these systems for precision finishing tasks. The technology is integrating sealed bearing housings and thermal management subsystems that extend mean time between failures beyond legacy benchmarks.
REACH chemical compliance requirements in the European Union are mandating substitution of chromium-based surface treatments and perfluorinated lubricants in rotary tool manufacturing. Suppliers are reformulating bearing greases and anodizing processes to maintain corrosion resistance. The regulation is forcing accessory producers to requalify material specifications and resubmit technical documentation to notified bodies.
Buyers in residential renovation segments are consolidating purchase decisions around battery ecosystem compatibility rather than standalone tool performance metrics. Home improvement retailers are responding with bundled platform incentives and cross-category loyalty programs. This behavior is most pronounced in the United States, where Milwaukee and DeWalt battery universes anchor contractor and consumer loyalty respectively.
Rotary Tools Market Segmentation
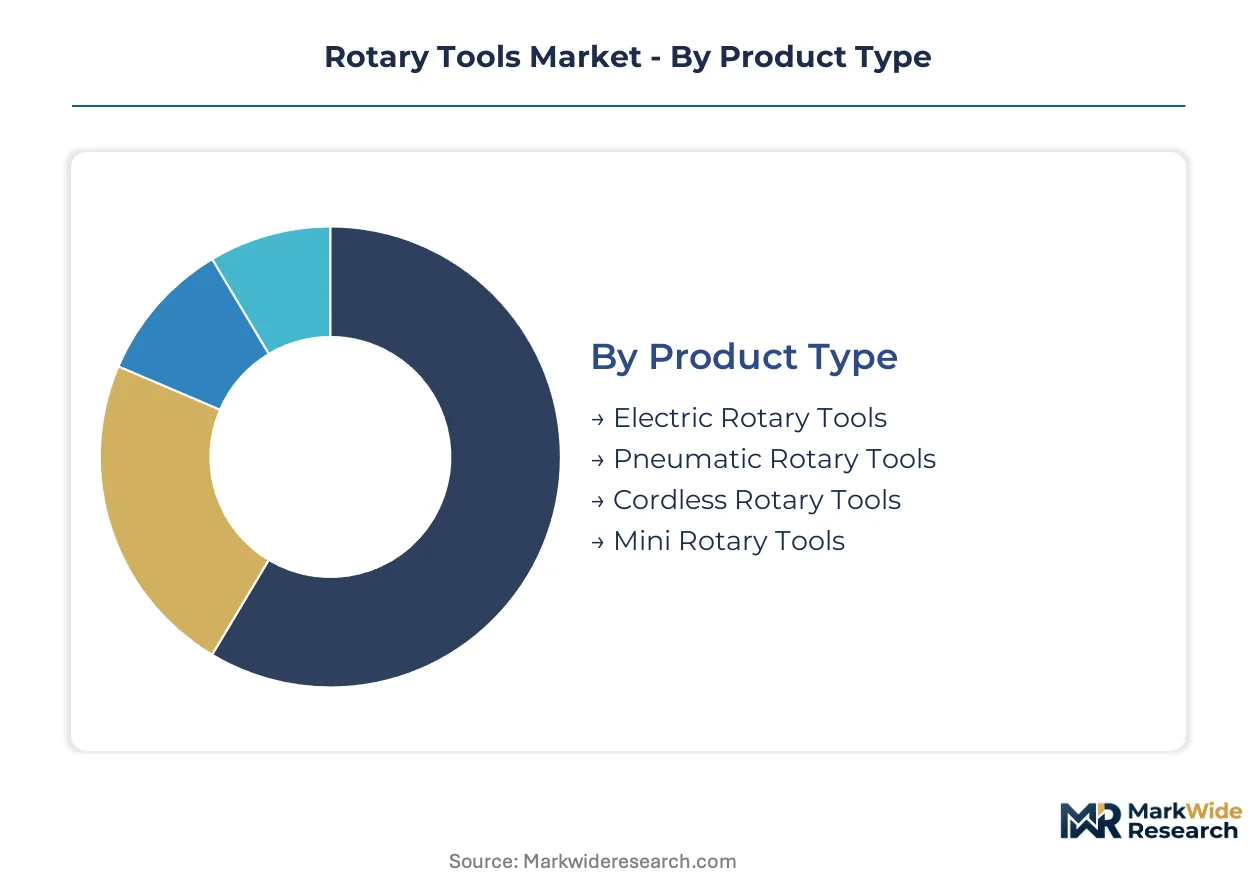
Rotary tool procurement patterns diverge sharply across user sophistication levels, power delivery architectures, and precision requirements. Segmentation reveals how brushless motor platforms and cordless battery ecosystems are fragmenting traditional category boundaries while creating new margin pools.
Product Type:
Standardization dominates mass-market electric and pneumatic categories, while cordless and mini segments reward customization through battery ecosystem lock-in and precision accessory depth.
- Electric Rotary Tools:Mains-powered units deliver sustained high-RPM operation for continuous manufacturing duty cycles. Demand concentrates in Germany's automotive component sector, where fixed production lines prioritize thermal stability over portability. Brush motor architectures still dominate this installed base due to capital equipment replacement inertia.
- Cordless Rotary Tools:Lithium-ion platforms achieve runtime parity with corded alternatives in intermittent-use scenarios. United States residential renovation contractors are consolidating purchases around Milwaukee and DeWalt battery universes, making ecosystem compatibility a primary selection criterion over standalone tool specifications.
- Pneumatic Rotary Tools:Compressed air infrastructure in legacy manufacturing facilities sustues demand despite cordless encroachment. China's industrial clusters retain substantial installed base where centralized compressor systems amortize across multiple workstations.
- Mini Rotary Tools:Compact collet designs target precision engraving and jewelry fabrication with reduced vibration profiles. Desktop micro-production in Italy's goldsmithing districts drives specification requirements for sub-0.5mm bit compatibility.
Most installed capacity flows through Electric Rotary Tools. Expansion is steepest in Cordless Rotary Tools.
End User:
Volume concentration sits with manufacturing procurement, while margin capture shifts toward home improvement channels as DIY finishing tasks proliferate.
- Manufacturing:Automated assembly lines and quality control stations specify rotary tools for deburring and surface preparation. Germany's automotive tier-one suppliers are mandating brushless motor platforms with sealed bearing architectures to satisfy compressed maintenance windows.
- Home Improvement:Residential renovation spending is restructuring channel mix toward big-box retail and direct-to-consumer platforms. United States consumers are purchasing rotary tool kits for countertop refinishing, tile grout removal, and decorative engraving projects.
- Metalworking:Fabrication shops require high-torque collet systems for ferrous material cutting and weld seam grinding. OSHA silica exposure compliance is shortening replacement cycles for dust-extraction-compatible equipment.
- Woodworking:Cabinet makers and furniture producers utilize variable-speed control for intricate routing and detail sanding. European craft workshops prioritize low-vibration designs to reduce repetitive strain injury risk.
Manufacturing commands the largest equipment fleet. Home Improvement is climbing the fastest as channel mix shifts toward consumer-direct platforms.
Technology:
Performance tier stratification separates premium brushless architectures from cost-optimized brush motor systems, with variable speed and high torque serving as cross-cutting specification requirements.
- Brushless Motor:Electronic commutation eliminates brush wear and enables precision torque control through field-oriented algorithms. Professional trades in the United States specify these systems for thermal efficiency gains in continuous-duty metalworking applications.
- Brush Motor:Carbon brush architectures persist in price-sensitive consumer segments and legacy manufacturing equipment. China's export-oriented producers dominate cost-optimized supply for emerging market distributors.
- Variable Speed:Electronic speed control modules enable RPM adjustment across 5,000 to 35,000 ranges for substrate-specific optimization. Engraving applications in Japan's precision manufacturing sector require stable low-speed operation for detailed work.
- High Torque:Enhanced gearbox ratios deliver elevated cutting force for dense material penetration. Metalworking shops in India's automotive component clusters are specifying these variants for stainless steel fabrication.
Brush Motor retains the broadest installed base. Brushless Motor is gaining share fastest as thermal efficiency requirements intensify.
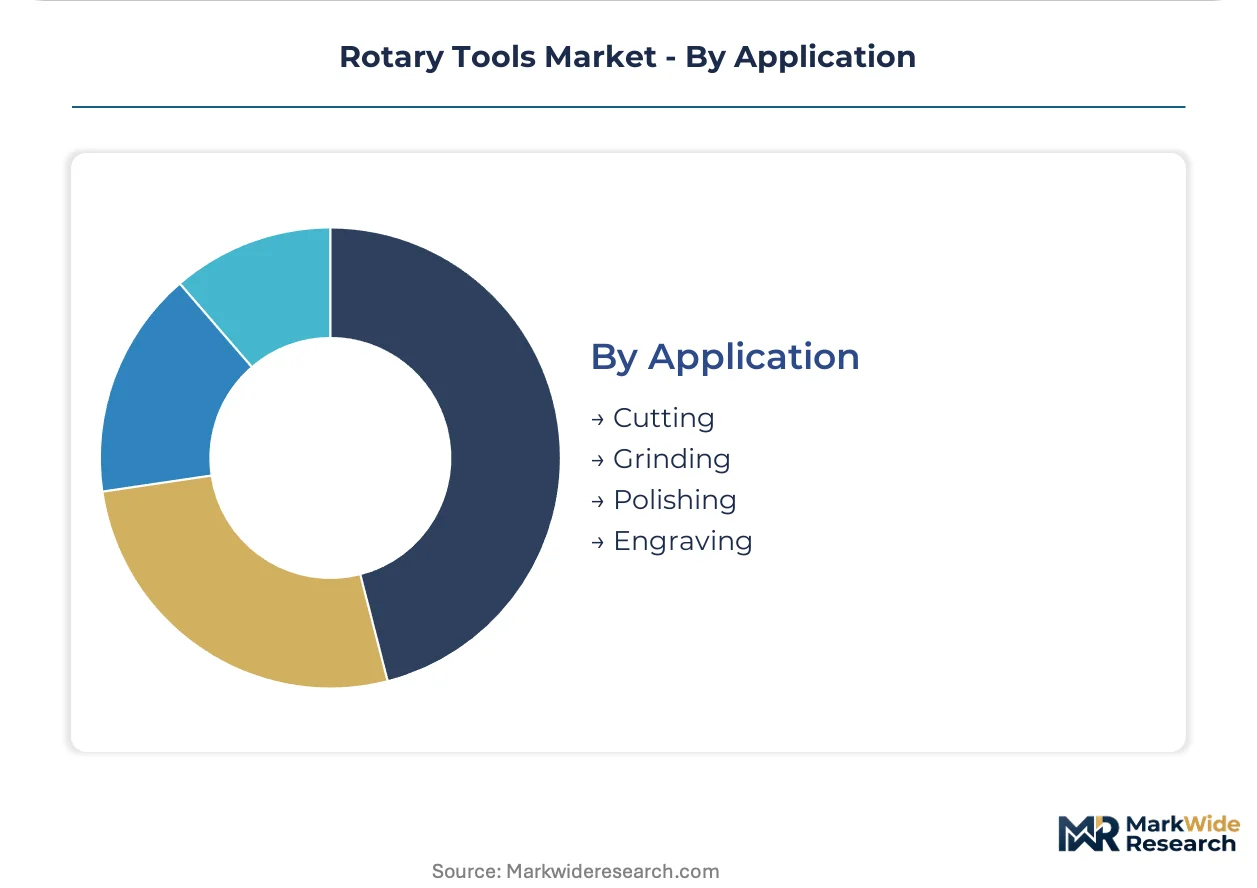
Application:
Precision requirements and material substrate characteristics create distinct specification profiles across cutting, grinding, polishing, and engraving functions.
- Grinding:Abrasive wheel compatibility demands rigid collet clamping and vibration damping for surface finish quality. Germany's tool-and-die manufacturers specify these configurations for mold finishing operations.
- Engraving:Micro-precision bit holding and stable low-speed operation enable detailed work in jewelry and signage production. Italy's artisanal goldsmithing districts and United States custom fabricators are driving demand for desktop-capable systems.
- Cutting:Reinforced cutoff wheels and high-RPM operation target metal and composite separation tasks. China's construction sector utilizes these applications for on-site rebar and pipe modification.
- Polishing:Felt and foam wheel compatibility with variable speed control delivers cosmetic finishing on automotive and furniture surfaces. United States auto detailing professionals are adopting cordless platforms for mobile operation.
Grinding represents the largest application volume. Engraving is expanding most quickly as desktop micro-production proliferates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping rotary tool manufacturing footprints as producers migrate toward jurisdictions with streamlined chemical compliance and lower energy costs. Cost-of-compliance gaps between Europe and Asia are accelerating supplier relocation decisions.
United States
Residential renovation contractors are consolidating purchases around Milwaukee and DeWalt battery ecosystems. OSHA silica exposure mandates are shortening replacement cycles for dust-extraction-compatible equipment. Dallas-Fort Worth and Atlanta metropolitan construction corridors are driving cordless rotary tool volume through big-box retail channels.
Germany
Automotive tier-one suppliers are mandating brushless motor platforms with sealed bearing architectures for compressed maintenance windows. REACH chemical restrictions on chromium-based surface treatments are forcing bearing grease reformulation. Stuttgart and Munich industrial clusters anchor precision rotary tool specification requirements for mold finishing operations.
China
Construction sector demand for metal cutting and pipe modification applications sustains high-RPM electric rotary tool consumption. GB standards on electromagnetic compatibility are diverging from CE marking requirements. Yangtze River Delta manufacturing bases retain substantial pneumatic rotary tool installed base where centralized compressor systems amortize across workstations.
Italy
Artisanal goldsmithing districts in Vicenza and Arezzo are driving specification requirements for sub-0.5mm bit compatibility in mini rotary tools. EU Green Deal circular economy provisions are pressuring battery-powered platforms toward standardized cell formats. Desktop precision engraving demand is proliferating among small-scale jewelry micro-producers.
Japan
Precision manufacturing sector requirements for stable low-speed operation are shaping variable-speed control module specifications. METI industrial efficiency guidelines are accelerating brushless motor adoption in continuous-duty applications. Nagoya and Osaka machining clusters specify rotary tools for detailed engraving work in automotive component finishing.
Rotary Tools Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with battery ecosystem owners capturing professional trade loyalty while precision accessory specialists dominate craft applications. The vendor base concentrates around three tiers: premium brushless motor platforms, mid-tier cordless ecosystems, and economy brush motor alternatives. Strategic archetypes include battery universe anchors, precision accessory ecosystem builders, and pneumatic infrastructure incumbents. Competitive moves center on cross-category battery compatibility expansion and dust extraction system integration partnerships.
Among North American battery ecosystem anchors, Milwaukee and Craftsman occupy positions as archetypal platform owners whose cordless rotary tool penetration depends on cross-category battery compatibility. Dremel exemplifies the precision accessory specialist archetype, anchoring the engraving and light-duty crafting segment through bit ecosystem depth rather than power platform dominance. These three companies represent the strategic poles around which competitive positioning organizes: ecosystem scale, precision specialization, and professional trade loyalty.
| Leading Market Players |
|---|
| Milwaukee |
| Craftsman |
| Dremel |
| Worx |
| Ryobi |
| Bosch |
| Stanley Black & Decker |
| Proxxon |
| Makita |
| Others |
Value Network & Pricing Analysis
EU Green Deal circular economy provisions gate qualified supply and premium-tier pricing access, forcing battery-powered rotary tool platforms toward standardized cell formats and end-of-life recyclability. Manufacturers bearing remanufacturing service capabilities command tier-one positioning, while uncertified competitors face margin compression in economy segments.
Pricing Analysis
Distributor margin layers stratify across three-tier pricing structure across premium, standard, and economy levels, with brushless motor platforms capturing 40-60 point markups over brush motor alternatives. Price differentiation rests on certification grade—UL and CE marking tiers—and battery ecosystem compatibility. Cost compression in economy cordless segments is intensifying because China's export-oriented producers flood emerging market channels. Home improvement retail buyers exhibit highest price sensitivity, while German automotive tier-one suppliers prioritize thermal efficiency over unit cost.
Supply Chain Analysis
Regional distribution centers in Germany, China, and the United States anchor hub-and-spoke patterns for finished rotary tool deployment. Manufacturing concentrates in China's Yangtze River Delta, Germany's Stuttgart industrial cluster, and Mexico's border assembly zones. Neodymium magnet sourcing draws from China's rare earth processing infrastructure, lithium-ion cells from South Korea and Japan, and precision bearings from Germany and Switzerland. Single-source vulnerability in rare earth magnet supply exposes brushless motor producers to export restriction risks. Distribution runs through big-box retail partnerships in the United States, specialized industrial distributors in Germany, and e-commerce direct-to-consumer platforms for light-duty categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rotary tools market functions as a geographic-arbitrage play, with REACH chemical compliance costs in Europe running 15-25 points above Asia-Pacific regulatory burdens, creating manufacturing relocation incentives.
For Market Incumbents: Anchor brushless motor platform dominance through backward integration into controller firmware development, countering power electronics engineering talent scarcity. Expand sealed bearing architecture certification investment to satisfy compressed German automotive maintenance windows. Defend against cordless ecosystem displacement by locking professional trades into cross-category battery compatibility programs. For New Entrants and Emerging Players: Big-box retail private label partnerships offer lowest-friction entry vectors for cordless rotary tool categories. Target United States residential renovation contractors through direct-to-consumer video demonstration formats, bypassing incumbent distributor networks. White-space sits in precision engraving accessory ecosystems for Italy's goldsmithing micro-producers, where bit compatibility depth determines supplier selection. For Investors and Strategic Acquirers: Roll-up economics work for precision accessory specialists because fragmented artisan buyer bases reward ecosystem depth over manufacturing scale. Five-to-ten year viability favors modular battery platform owners with remanufacturing service infrastructure. Watch OSHA silica enforcement intensity as inflection indicator for dust-extraction-compatible equipment replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Brushless Motor Platform Expansion | Milwaukee and Bosch capture professional trade loyalty through thermal efficiency gains in continuous-duty metalworking. |
| Dust Extraction System Integration | OSHA compliance mandates shorten replacement cycles for compatible equipment across United States construction corridors. |
| Battery Ecosystem Lock-In Programs | Cross-category loyalty incentives consolidate contractor purchases around Milwaukee and DeWalt universes. |
| Precision Accessory Ecosystem Depth | Dremel's bit compatibility range anchors engraving segment share against power-platform competitors. |
| Remanufacturing Service Network Buildout | EU Green Deal recyclability requirements create recurring revenue streams for modular tool platform owners. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region's stakeholder base. The analysis combines structured interviews with plant engineers, OEM procurement teams, aftermarket service heads, and home improvement retail category buyers with secondary validation from SEC filings, customs and trade databases, and OSHA regulatory enforcement records. Bottom-up demand modeling triangulates against top-down macroeconomic indicators.
Granularity-level framing segments the rotary tools market by product type, end user, technology, and application dimensions at the country level. CAGRs derive from historical trajectory analysis and forward-looking regulatory impact assessment across the analysis window. Industry-specific forecast inputs include lithium-ion energy density improvement curves and REACH chemical substitution timelines for bearing lubricants.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to rare earth export policy shifts and brushless motor controller firmware talent availability. Forecasts reflect assumptions about regulatory enforcement intensity and battery chemistry evolution. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Measuring Wheels Market
Tools
Squeegee Market
Tools
Key Cutting Machine Market
Tools
Floor Saw Market
Tools
Electric Power Tools Market
Tools
Friction Washer Market
Tools
Fatigue Testing Machine Market
Tools
Forging Press Market
Tools
Global Metal Forming Machine Tools Market
Tools
Multi Spindle Machines Market
Tools
Automated Plasma Beveller Market
Tools
Grease Gun Market
Tools
Cordless Bandsaw Sander Market
Tools
Metal Cutting Machine Market
Tools
Pliers Market
Tools
Drill Bit Market