
 Automated Plasma Beveller Market | 2026-2036
Automated Plasma Beveller Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Plasma Beveller Market Analytics
South Korean shipyard automation is reshaping procurement patterns for heavy-duty plasma bevelling systems. ESAB leverages its welding technology heritage to anchor integrated cutting-beveling solutions for marine construction. Hypertherm sustains technology leadership through consumables-to-systems bundling. Lincoln Electric dominates the Americas through its distribution network and captive power supply integration.
An automated plasma beveller employs ionized gas jets to cut and chamfer metal edges simultaneously, operating at temperatures exceeding 20,000°C with CNC-controlled torch positioning for repeatability within ±0.1 mm. The equipment serves primary industrial purposes in shipbuilding, pressure vessel fabrication, and structural steel preparation where weld joint geometry compliance is mandatory. Industrial Bevellers occupy the dominant volume tier due to continuous-duty cycles in heavy fabrication yards. Atmospheric Plasma technology leads installed base share for open-air cutting operations, while Low-Pressure Plasma commands premium positioning in electronics clean room environments where contamination control determines process yield.
OSHA hexavalent chromium exposure standards and EU Machinery Directive CE marking requirements shape product design specifications and market access conditions for equipment vendors. The EPA National Emission Standards for Hazardous Air Pollutants further constrain thermal cutting operations in US-based fabrication facilities. Stakeholders must monitor evolving ISO 9013 thermal cutting quality classifications and assess how dual-carbon regulatory timelines in key manufacturing jurisdictions will reshape equipment replacement cycles.
Market Dynamics
OSHA's tightening hexavalent chromium exposure limits are forcing fabrication facilities toward automated plasma systems that eliminate manual grinding operations and reduce worker contact with toxic metal particulates.
Growth Catalysts
- Shipyard automation mandates:South Korean marine construction yards are replacing mechanical edge preparation with plasma bevelling for thick plate welding, driven by precision requirements and labor cost pressures.
- EU Machinery Directive compliance:CE marking requirements for thermal cutting equipment are accelerating replacement cycles in German automotive supplier networks.
- Consumables-to-systems bundling:Torch electrode and nozzle supply contracts are locking in long-term equipment commitments from heavy fabrication operators.
Market Restraints
- Power supply cost volatility:High-frequency inverter components and copper winding materials face price instability from concentrated Asian semiconductor foundry supply.
- Technical limitation in aluminum processing:Plasma arc instability with reflective alloys restricts adoption in aerospace sheet metal operations.
- Substitution threat from laser systems:Fiber laser cutting with integrated bevel heads is capturing thin-to-medium plate applications below 25mm thickness.
Strategic Opportunities
- Underpenetrated Indian infrastructure:Bridge and highway steel fabrication is shifting from manual oxy-fuel to automated plasma for National Highway Authority projects.
- Technology convergence:Machine vision alignment systems are integrating with CNC torch positioning to enable unmanned night-shift operations.
- EPA NESHAP tailwind:National Emission Standards for Hazardous Air Pollutants compliance deadlines are triggering equipment upgrades at US pressure vessel shops.
Industry Challenges
- CNC programming skill scarcity:Torch path optimization and kerf compensation expertise is concentrated among aging machinist cohorts in mature manufacturing economies.
- ISO 9013 certification timelines:Thermal cutting quality classification testing delays equipment commissioning by four to eight weeks in European contract fabrication.
- Legacy ERP integration friction:Shop floor data collection from plasma bevelling cells requires middleware development for SAP and Oracle manufacturing modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Plasma Beveller Market |
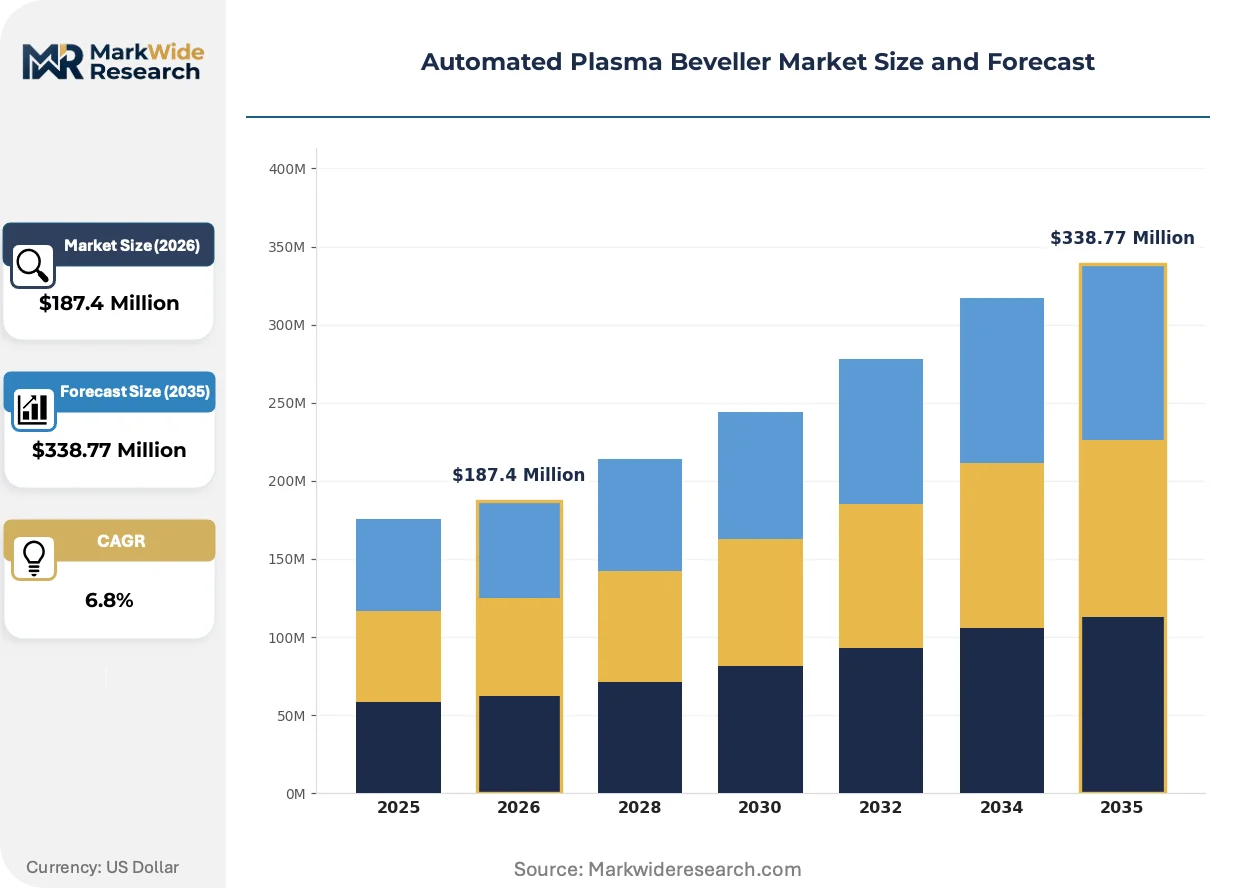
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desktop Bevellers, Industrial Bevellers, Laboratory Bevellers, Portable Bevellers Technology: Low-Pressure Plasma, Atmospheric Plasma, RF Plasma, Microwave Plasma End User: Aerospace, Electronics, Automotive Components, Medical Devices Application: Surface Treatment, Material Coating, Circuit Board Manufacturing, Clean Room Operations |
| Companies Covered | Plasma Technology, Inc., SENTECH Instruments GmbH, PVA TePla AG, ESAB, Messer Cutting Systems, Hypertherm, Lincoln Electric, Koike Aronson, Inc., Komatsu NTC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Plasma Beveller Market Evolving Landscape
Digital twin technology is virtualizing equipment commissioning and process validation, compressing deployment timelines while regulatory emissions tracking reshapes equipment specification workflows.
Plasma process simulation software is virtualizing torch parameter development for new material grades and joint configurations. German automotive suppliers are adopting these tools to reduce physical test plate consumption by half. This virtualization is compressing process qualification cycles from weeks to days.
EPA National Emission Standards for Hazardous Air Pollutants enforcement is mandating fume extraction upgrades at US thermal cutting facilities. Fabrication shops are retrofitting plasma bevelling stations with high-velocity capture arms and filtration systems. The pressure vessel segment is absorbing the highest compliance costs through captive maintenance contracts.
Outcome-based equipment leasing is displacing capital purchase models among mid-sized structural steel contractors. Lincoln Electric's distributor network is piloting per-meter-cut pricing in the Americas. German industrial belt fabricators are resisting this shift, preferring asset ownership for balance sheet leverage.
Automated Plasma Beveller Market Segmentation
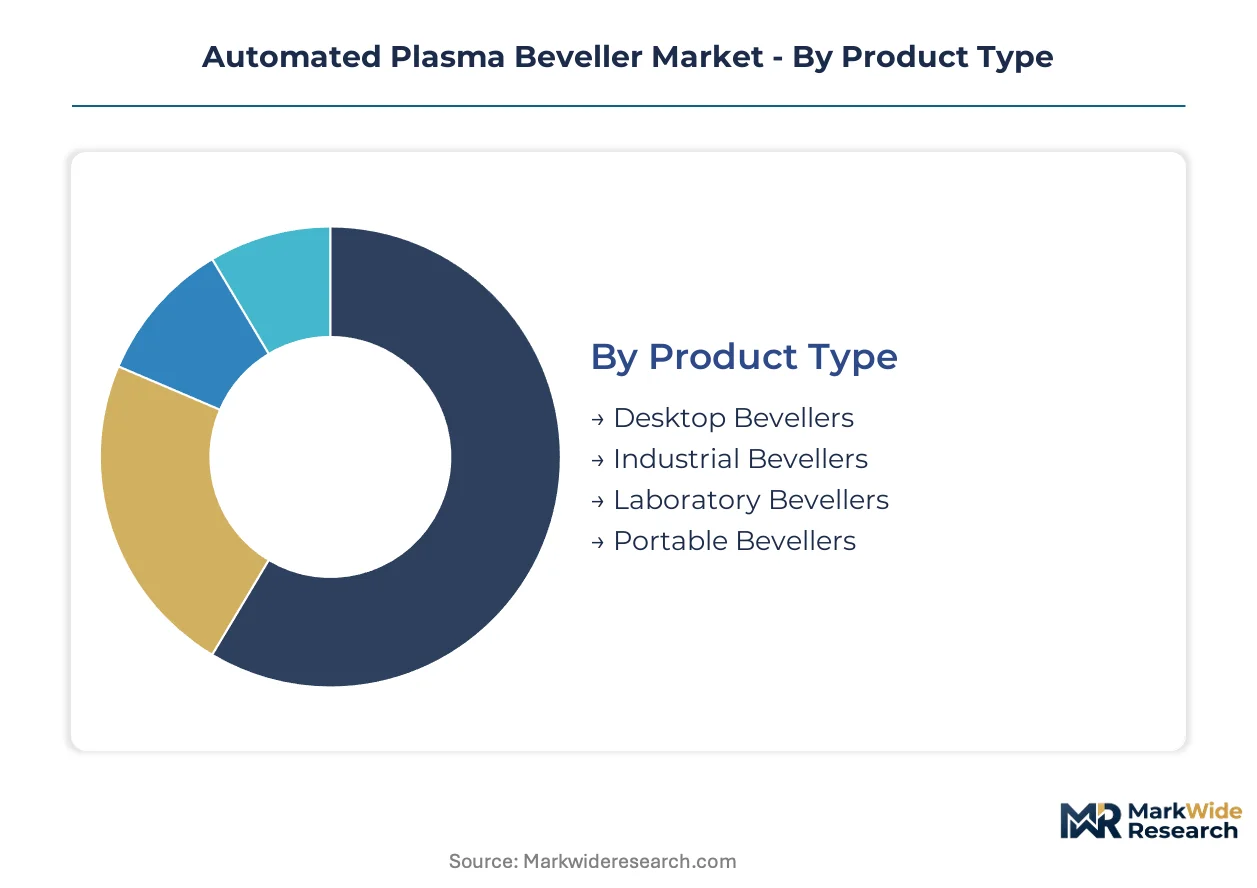
Equipment specification varies sharply across fabrication scales, from benchtop electronics work to heavy shipyard duty cycles. Technology selection determines plasma stability, cutting speed, and fume generation profiles. End-use segmentation reveals which industries absorb compliance costs versus those driving automation adoption.
Product Type:
Replacement cycles stretch from three years for portable field units to twelve-plus years for fixed industrial installations, creating divergent aftermarket revenue profiles.
- Industrial Bevellers:Heavy-duty systems rated for continuous-duty cycles exceeding sixteen hours daily in open-air fabrication yards. South Korean shipbuilders specify these for thick plate welding preparation, driven by precision tolerances and labor cost pressures.
- Portable Bevellers:Mobile units with integrated power supplies and fume extraction for on-site structural steel work. Bridge contractors in India's National Highway Authority projects deploy these for field weld joint preparation where fixed infrastructure is unavailable.
- Desktop Bevellers:Compact benchtop systems for small-batch precision work in electronics prototyping labs.
- Laboratory Bevellers:Research-grade equipment with parameter logging for process development and material science applications.
Industrial Bevellers dominate installed base. Portable Bevellers are where expansion concentrates.
Technology:
Cost tiers separate atmospheric open-air systems from clean-room-rated low-pressure configurations requiring vacuum chambers and gas recovery infrastructure.
- Atmospheric Plasma:Open-air arc systems operating with compressed air or oxygen-nitrogen mixtures at ambient pressure. German automotive suppliers integrate these into just-in-time component lines for edge preparation before robotic welding.
- Low-Pressure Plasma:Vacuum chamber systems with precise gas composition control for contamination-sensitive electronics manufacturing. Clean room operations in semiconductor fabrication specify these for surface activation prior to bonding processes.
- RF Plasma:Radio frequency-excited systems offering uniform ion density for thin-film coating applications.
- Microwave Plasma:Magnetron-driven configurations achieving higher electron temperatures for specialized material synthesis.
Atmospheric Plasma captures volume leadership. Low-Pressure Plasma commands the steepest expansion trajectory in electronics clean rooms.
End User:
Customer maturity ranges from specification-driven aerospace primes to price-sensitive automotive tier suppliers negotiating consumables bundling contracts.
- Automotive Components:Tier suppliers producing chassis and powertrain parts requiring consistent weld joint geometry for robotic assembly. EU Machinery Directive CE marking accelerates replacement cycles in Germany's industrial belt.
- Aerospace:Airframe and engine manufacturers with stringent NADCAP thermal processing requirements and traceability mandates.
- Electronics:PCB fabricators and semiconductor packaging houses requiring plasma surface treatment for adhesion promotion.
- Medical Devices:Implant and instrument manufacturers with biocompatibility surface modification needs.
Automotive Components leads equipment shipments. Electronics is gaining share fastest on clean room capacity expansion.
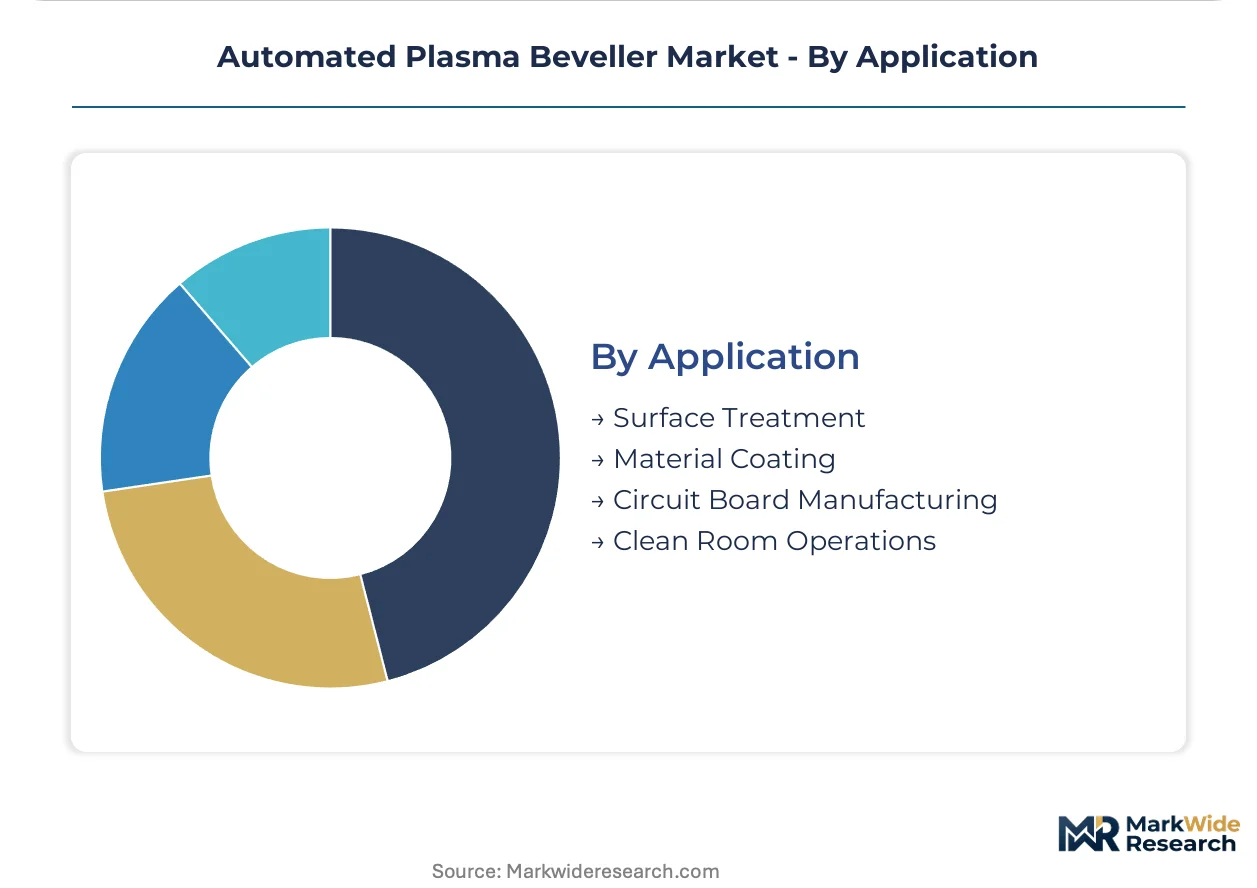
Application:
Process margins vary from commodity surface treatment to high-value clean room operations where contamination control determines yield economics.
- Surface Treatment:Plasma activation and cleaning of metal substrates prior to coating or bonding operations. Pressure vessel shops in the US retrofit these capabilities to meet EPA NESHAP fume capture requirements.
- Clean Room Operations:Contamination-controlled plasma processing for semiconductor and medical device manufacturing. Electronics fabrication in clean room environments drives specification for low-particulate systems.
- Material Coating:Plasma spraying and vapor deposition for wear-resistant and thermal barrier layers.
- Circuit Board Manufacturing:Desmearing and surface activation for high-density interconnect substrates.
Surface Treatment anchors the installed base. Clean Room Operations is where technology premiums concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA hexavalent chromium exposure mandates anchor North American demand, while South Korean shipyard automation and German automotive supplier networks drive equipment procurement across three distinct industrial clusters.
United States
Pressure vessel fabricators and structural steel contractors absorb EPA NESHAP compliance costs through equipment upgrades. OSHA workplace exposure limits force grinding operation elimination at fabrication facilities. Houston-Gulf Coast petrochemical construction and Great Lakes ship repair yards concentrate plasma system deployment for thick plate welding preparation.
Germany
Automotive tier suppliers integrate atmospheric plasma systems into just-in-time chassis component lines. EU Machinery Directive CE marking requirements accelerate replacement cycles in supplier networks. The Baden-Württemberg industrial belt and Bavarian automotive clusters specify precision bevelling equipment for robotic welding compatibility.
South Korea
DSME and Hyundai Heavy Industries mandate plasma bevelling for thick plate edge preparation in newbuild construction. MFDS workplace safety enforcement parallels OSHA standards for metal particulate exposure. Ulsan and Geoje shipyard complexes drive procurement of continuous-duty industrial systems rated for sixteen-hour daily cycles.
China
Bridge and infrastructure steel fabrication shifts from manual oxy-fuel toward automated plasma for National Highway Authority specifications. MIIT industrial upgrading directives encourage CNC cutting technology adoption. Yangtze River Delta fabrication centers and Shandong Peninsula heavy industry zones absorb medium-duty portable systems for field construction deployment.
India
National Highway Authority bridge projects create demand for portable plasma bevellers at remote construction sites. BIS equipment standardization and CEA electrical safety regulations shape product certification requirements. Gujarat infrastructure corridors and Maharashtra industrial zones concentrate initial adoption among structural steel contractors replacing manual edge preparation.
Automated Plasma Beveller Market Competitive Landscape
Integrated welding technology groups and specialized cutting equipment manufacturers split the market between bundled consumables-to-systems offerings and standalone precision machinery. The vendor base concentrates around three strategic archetypes: diversified industrial conglomerates with captive power supply integration, pure-play plasma technology specialists leveraging consumables lock-in, and regional fabrication equipment houses serving price-sensitive emerging markets. Dominant competitive moves include geographic distributor network expansion and vertical integration into torch electrode and nozzle manufacturing.
Among European-headquartered precision equipment houses, SENTECH Instruments GmbH and PVA TePla AG exemplify the clean room technology tier, while ESAB represents the diversified industrial archetype with integrated welding-cutting portfolios. These three anchors occupy distinct positioning vectors across atmospheric and low-pressure plasma applications.
| Leading Market Players |
|---|
| Plasma Technology, Inc. |
| SENTECH Instruments GmbH |
| PVA TePla AG |
| ESAB |
| Messer Cutting Systems |
| Hypertherm |
| Lincoln Electric |
| Koike Aronson, Inc. |
| Komatsu NTC |
| Others |
Value Network & Pricing Analysis
Undercapacity in South Korean shipyard power supply manufacturing is compressing lead times for high-frequency inverter components while simultaneously hardening pricing postures among torch electrode suppliers serving German automotive integrators. This utilization squeeze feeds directly into equipment procurement cycles, forcing buyers to lock in consumables bundling contracts earlier in the sales process to secure system availability.
Pricing Analysis
Price spreads between German precision-tier systems and Indian portable units exceed three-to-one on equivalent power ratings, reflecting certification grade differentiation and after-sales service bundling. Equipment procurement stratifies across premium continuous-duty industrial systems, standard automotive line-integrated units, and economy-grade portable field machines. Cost compression in the economy tier is intensifying because Chinese fabricators are absorbing margin erosion to capture National Highway Authority project volume. Structural steel contractors in emerging markets exhibit the highest price sensitivity, while aerospace primes with NADCAP requirements show minimal elasticity.
Supply Chain Analysis
Contract manufacturing for plasma power electronics concentrates in Taiwan and South Korea, with Shenyang and Shenzhen facilities handling torch assembly and fume extraction integration. Copper winding materials and high-frequency semiconductor components draw from concentrated Asian foundry supply, while precision nozzle machining rests on German and Japanese tooling equipment. Single-source vulnerability in IGBT module supply creates exposure to foundry allocation decisions. Distribution runs through captive distributor networks for integrated welding groups and direct technical sales for precision clean room specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CNC programming expertise for torch path optimization and kerf compensation has concentrated among aging machinist cohorts in mature manufacturing economies, creating a bottleneck that constrains equipment utilization rates and shapes vendor support service pricing.
For Market Incumbents: Insulate installed base relationships through captive consumables supply contracts and embedded service technician networks that neutralize price competition from emerging portable equipment vendors. Fiber laser substitution in thin plate applications threatens atmospheric plasma market share below 25mm thickness, making consumables bundling the critical defensive lever. Prioritize backward integration into electrode and nozzle manufacturing to defend margin position against commodity torch suppliers. For New Entrants and Emerging Players: India's National Highway Authority bridge construction projects represent the most penetrable entry point for medium-duty portable plasma bevellers displacing manual oxy-fuel preparation. Clean room electronics fabrication in Southeast Asia expansion zones offers white-space opportunity for low-pressure plasma surface treatment systems. Lead with per-meter-cut outcome-based leasing to circumvent capital budget constraints among mid-sized structural steel contractors. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance-driven replacement cycle play because OSHA hexavalent chromium enforcement and EPA NESHAP deadlines create non-discretionary equipment upgrade demand. Acquisition targets with established CE marking pathways and ISO 9013 certification capabilities command premium positioning. Monitor EPA enforcement action frequency and South Korean shipyard automation mandate expansion as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Consumables-to-Systems Bundling | Long-term electrode supply contracts lock in equipment commitments from Hyundai Heavy Industries and DSME procurement teams. |
| Machine Vision Integration | CNC torch alignment automation enables unmanned night-shift operations at German automotive supplier lines. |
| Clean Room Capacity Expansion | Low-pressure plasma system deployment captures semiconductor packaging house surface activation demand. |
| EPA NESHAP Compliance Retrofit | Fume extraction upgrades at Houston-Gulf Coast pressure vessel shops trigger captive maintenance contract growth. |
| Outcome-Based Equipment Leasing | Per-meter-cut pricing pilots among Americas structural steel contractors displace traditional capital purchase models. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with shipyard production engineers, automotive tier supplier welding supervisors, pressure vessel fabrication plant managers, and plasma system aftermarket service heads. Secondary validation drew from EPA NESHAP enforcement records, OSHA workplace exposure compliance databases, EU Machinery Directive CE marking registries, and customs trade data for thermal cutting equipment imports. Bottom-up equipment shipment analysis and top-down industrial capital expenditure triangulation anchored market sizing.
Calibration against historical replacement cycle patterns and regulatory compliance deadline clustering shaped the analytical framework across the analysis window. Segmentation dimensions modeled include equipment duty cycle tier, plasma technology type, end-use industry vertical, and geographic regulatory cluster. CAGRs were derived from equipment procurement pipeline analysis and consumables attach rate trajectories. Shipyard automation mandate intensity and automotive supplier robotic welding penetration served as industry-specific forecast inputs.
Stress conditions across copper and semiconductor input cost volatility, OSHA enforcement intensity variation, and fiber laser substitution pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory timeline adherence and industrial capacity utilization maintenance. Quarterly review of EPA enforcement action filings, South Korean shipyard order backlogs, and German automotive production schedules is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Multi Wire Cutting Machine Market
Tools
Set Screw Market
Tools
Edge Bending Machine Market
Tools
Laser Engraving Machine Market
Tools
Woodworking Circular Saw Blades Market
Tools
Cordless Planer Market
Tools
Power Press Machines Market
Tools
Global Flange Fasteners Market
Tools
Tension Tester Market
Tools
Digital Laser Levels Market
Tools
Parting-Off Blades Market
Tools
Woodworking CNC Tools Market
Tools
Reamer Market
Tools
Jade Engraving Machines Market
Tools
Squeegee Market
Tools
Horizontal Milling Machine Market