
 Multi Spindle Machines Market | 2026-2036
Multi Spindle Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Multi Spindle Machines Market Analytics
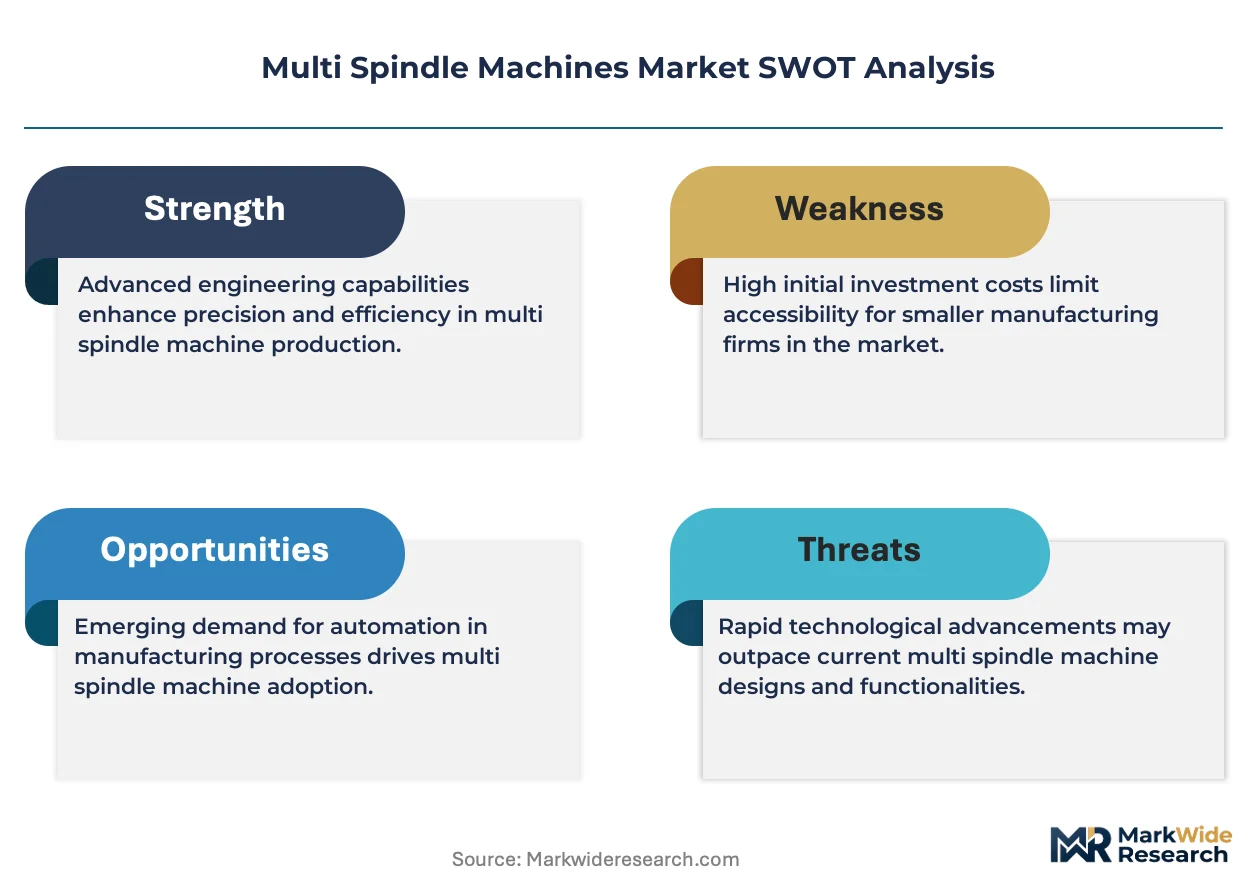
Modular spindle configurations with swappable tool magazines and interchangeable axis modules is hardening as the dominant procurement pattern among tier-one suppliers. INDEX-Werke GmbH & Co. KG Hahn & Tessky leverages its deep specialization in modular multi-spindle platforms to anchor premium positioning across European automotive supply chains. EMAG GmbH & Co. KG competes through integrated automation ecosystems that extend beyond standalone machines into full process lines. Tornos Group differentiates via precision-focused verticals in medical micro-machining, occupying niche segments where tolerance requirements exceed standard industrial thresholds.
Multi spindle machines are metal-cutting equipment employing two or more rotating spindles operating simultaneously on a single workpiece or multiple workpieces, typically achieving rotational speeds between 8,000 and 15,000 RPM with positional accuracies of ±0.005 mm for precision-grade units. These systems execute drilling, milling, turning, and tapping operations in parallel cycles, reducing per-part machining time by consolidating sequential operations into synchronized processes. CNC multi spindle configurations lead the product type landscape due to programmability demands from aerospace and medical device manufacturers seeking lot-size flexibility without retooling downtime. The automotive vertical dominates industry segmentation by volume, though medical devices generates disproportionate margin pools where validated processes command equipment premiums. Mass production manufacturing stage applications sustain the largest installed base, while custom manufacturing represents the fastest-growing deployment mode as contract manufacturers adopt reconfigurable platforms.
ISO 23125 machinery safety standards and the EU Machinery Directive shape equipment design mandates, compelling spindle guard interlocks and emergency stop architectures that add engineering cost but create compliance barriers for non-certified entrants. Germany's KBA and France's ANSM enforce sector-specific traceability requirements that propagate into machine tool specifications, particularly for automotive and medical end-uses where process validation documentation is mandatory. The US OSHA machinery guarding standards and emerging EPA metalworking fluid emission rules add parallel compliance layers for suppliers serving North American customers. Stakeholders must monitor harmonization gaps between regional certification regimes when configuring platform architectures for multi-territory deployment.
Market Dynamics
Automotive component manufacturers are consolidating machining operations into fewer, more capable multi-spindle platforms to offset labor scarcity and footprint constraints. This operational compression is reshaping equipment specification priorities across tier-one supply chains.
Growth Catalysts
- EU Machinery Directive compliance:Mandatory spindle guard interlocks and emergency stop architectures are compelling replacement cycles among European automotive suppliers seeking certified platforms.
- Medical device micro-machining:Validated processes for orthopedic implants and surgical instruments command equipment premiums, expanding addressable margin pools beyond industrial applications.
- Stuttgart-Aalen precision corridor:Concentrated demand from Germany's automotive supply base sustains high-volume orders for modular, reconfigurable spindle systems.
Market Restraints
- Ball screw and linear guide supply concentration:Japanese and German specialty component suppliers create input bottlenecks during capacity expansions.
- ISO 23125 certification timelines:Extended validation periods for safety-critical architectures delay revenue recognition and tie up engineering resources.
- Five-axis machining center substitution:Flexible single-spindle platforms with pallet pools compete for mid-volume contracts previously won by fixed multi-spindle configurations.
Strategic Opportunities
- Indian contract manufacturing expansion:PLI scheme incentives for automotive component production are creating first-time demand for precision metal-cutting infrastructure.
- Digital twin integration:Convergence of physics-based simulation with live spindle monitoring enables predictive maintenance contracts and recurring revenue streams.
- REACH-compliant metalworking fluid systems:Biobased coolant formulations open retrofit and upgrade pathways for installed European machine populations.
Industry Challenges
- CNC macro programming expertise:Shortage of technicians capable of optimizing synchronized multi-axis toolpaths constrains utilization rates at customer sites.
- Legacy CAM software integration:Post-processor compatibility gaps between new modular architectures and established programming environments extend commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi Spindle Machines Market |
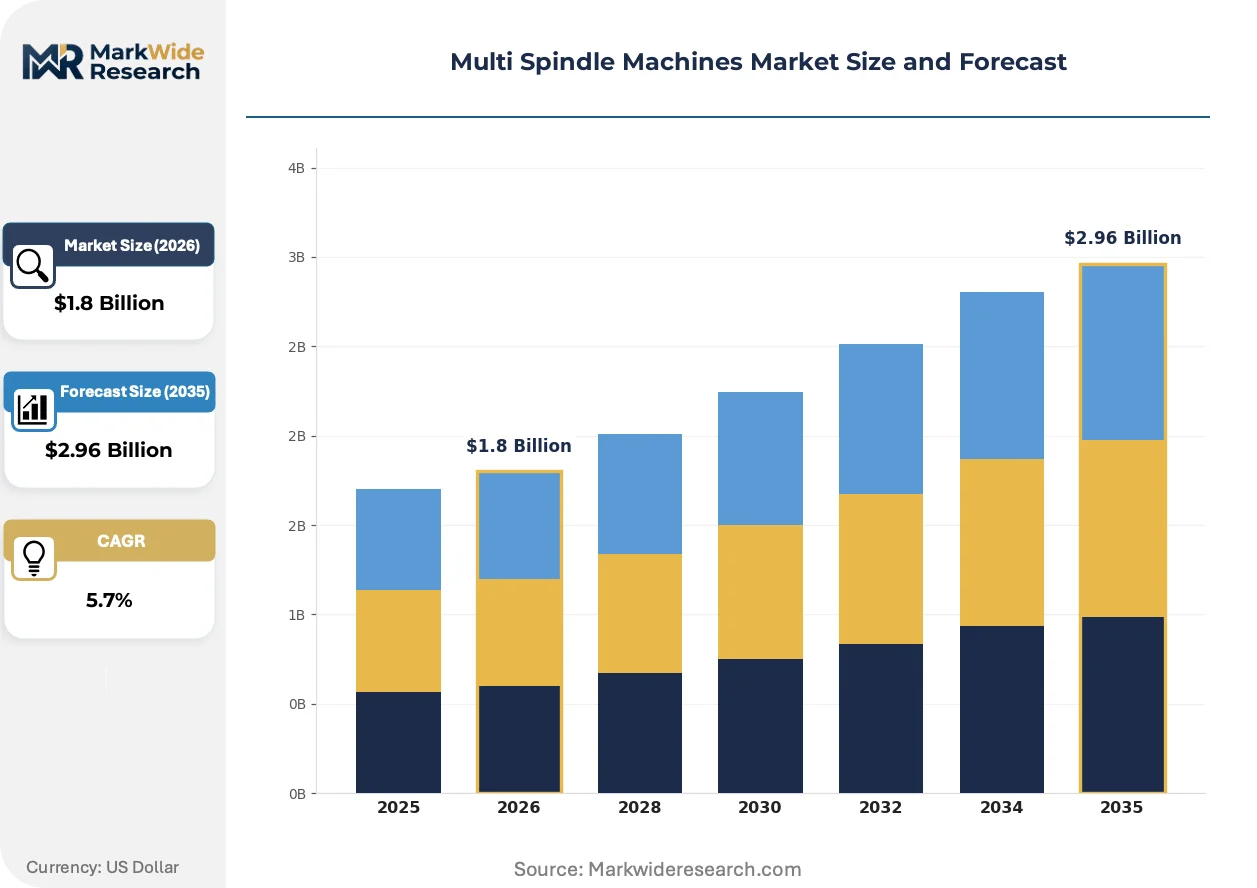
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Spindle, Horizontal Spindle, CNC, Manual Industry Vertical: Aerospace, Automotive, Medical Devices, Electronics Manufacturing Stage: Prototype, Mass Production, Custom Manufacturing, Post-Production Application: Precision Machining, Parts Fabrication, Assembly, Tooling |
| Companies Covered | DMG MORI Co., Ltd., Yamazaki Mazak Corporation, Okuma Corporation, Haas Automation, Inc., Doosan Machine Tools Co., Ltd., EMAG GmbH & Co. KG, INDEX-Werke GmbH & Co. KG Hahn & Tessky, Citizen Machinery Co., Ltd., Tornos Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi Spindle Machines Market Evolving Landscape
Equipment architecture is converging around reconfigurable platforms that accommodate shifting production mixes without mechanical retooling. This flexibility imperative is compressing traditional hardware replacement cycles and elevating software-defined capabilities.
Swappable tool magazines with automatic recognition systems are consolidating changeover workflows into single automated sequences. Tier-one automotive suppliers in Germany and the Czech Republic are deploying these configurations to handle mixed-model production with lot sizes below 500 units. The technology is consolidating what previously required dedicated lines into unified, reprogrammable cells.
REACH chemical restrictions and evolving EPA metalworking fluid emission rules are mandating closed-loop coolant management architectures. Equipment suppliers must now engineer integrated filtration and reclamation subsystems that add cost but create compliance differentiation. Medical device manufacturers in Switzerland and France are specifying these configurations to satisfy ANSM process validation requirements.
Contract manufacturers are unbundling after-sales service from initial equipment purchases, favoring third-party maintenance providers with spindle rebuild expertise. This disintermediation pressures OEM service margins while creating independent service network opportunities. The pattern is most visible in North American automotive supply chains where fleet standardization across multiple brand platforms complicates captive service models.
Multi Spindle Machines Market Segmentation
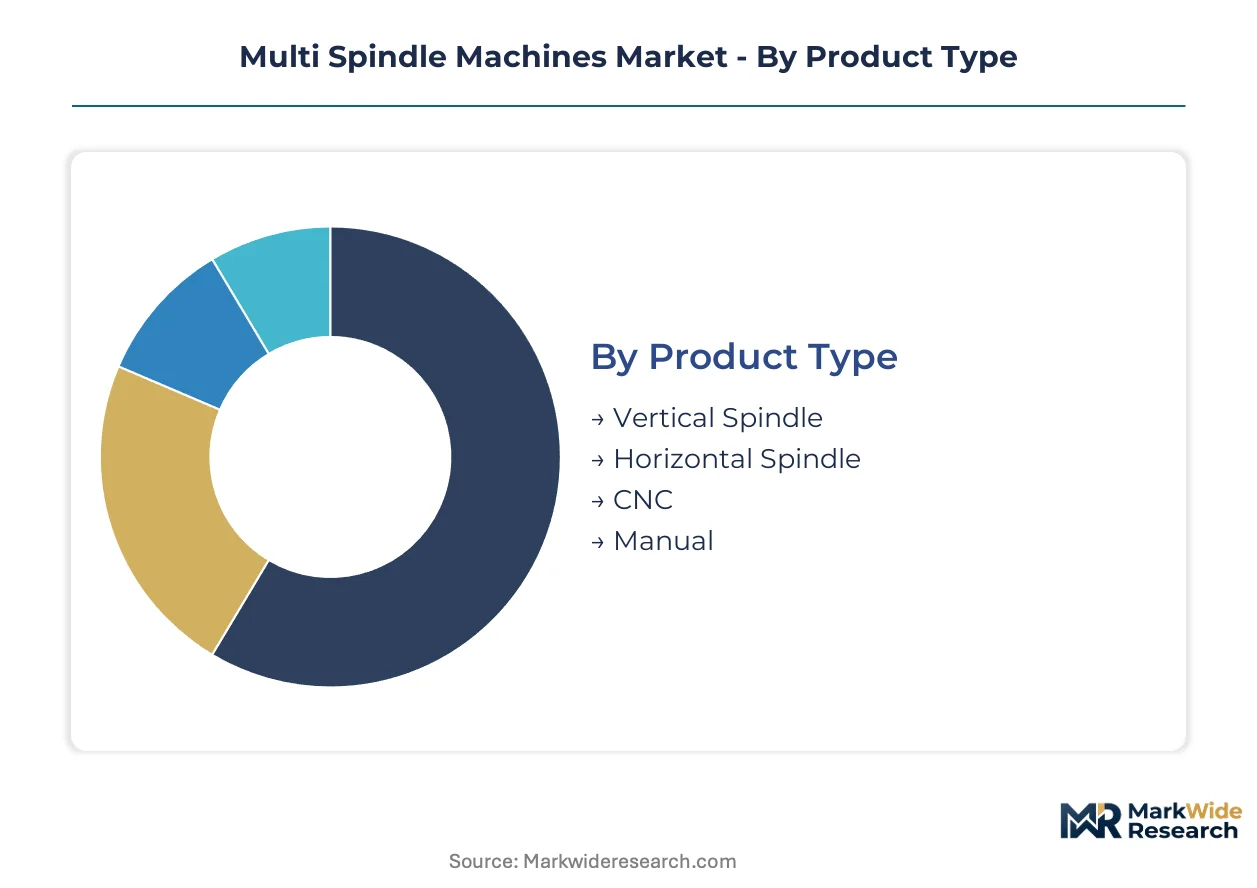
Multi spindle machine procurement patterns diverge sharply across operational contexts, with specification priorities shifting between throughput maximization, tolerance precision, and reconfiguration speed. Understanding these segment boundaries clarifies where equipment suppliers can defend premium positioning versus competing on unit economics.
Product Type:
Customization intensity varies from fully programmable CNC architectures to fixed mechanical configurations, creating distinct margin tiers across the equipment spectrum.
- CNC:Computer numerical control platforms enable rapid program switching between part geometries without mechanical changeover. Aerospace manufacturers in Germany and medical device producers in Switzerland prioritize these configurations for validated process documentation and lot-size flexibility below 200 units.
- Horizontal Spindle:Side-mounted spindle arrangements optimize chip evacuation and gravity-assisted workpiece handling for extended unmanned operation. Automotive tier-one suppliers in the Stuttgart-Aalen corridor deploy these systems for high-volume transmission component output where thermal stability outweighs floor space constraints.
- Vertical Spindle:Top-down cutting orientation suits compact footprints and ergonomic loading workflows for smaller workpieces.
- Manual:Operator-controlled mechanical systems persist in prototype workshops and maintenance facilities requiring minimal capital outlay.
Most installed capacity flows through CNC configurations. Expansion is steepest in horizontal spindle platforms serving automotive supply chains.
Industry Vertical:
End-use tolerance requirements and validation protocols create divergent equipment specification patterns across customer segments.
- Automotive:Powertrain and chassis component manufacturers drive volume demand with specifications emphasizing cycle time reduction and 24/7 operational reliability. German KBA traceability mandates propagate into machine tool requirements for process documentation and spindle monitoring capabilities.
- Medical Devices:Orthopedic implant and surgical instrument producers command equipment premiums exceeding standard industrial applications. ANSM validation requirements in France and Swissmedic protocols necessitate closed-loop coolant systems and thermal compensation architectures that add engineering cost but create compliance barriers.
- Aerospace:Structural component and landing gear producers require large work envelopes and high-torque spindle configurations for titanium and nickel alloy machining.
- Electronics:Connector and housing manufacturers prioritize compact platforms with rapid acceleration profiles for aluminum and engineered polymer workpieces.
Automotive verticals absorb the largest equipment volumes. Medical device applications generate the highest margin realization per installed unit.
Manufacturing Stage:
Production phase determines the trade-off between dedicated high-throughput systems and reconfigurable platforms accommodating design iteration.
- Mass Production:Dedicated multi-spindle cells with fixed tooling configurations dominate high-volume contracts where changeover frequency remains below monthly intervals. These installations concentrate in Czech Republic and Poland automotive supply bases serving German OEMs.
- Custom Manufacturing:Contract manufacturers adopt modular spindle platforms with swappable tool magazines to handle mixed-model sequences without mechanical retooling. Indian PLI scheme beneficiaries are deploying these configurations for first-time precision metal-cutting infrastructure.
- Prototype:Engineering validation and design iteration phases favor reduced spindle counts with rapid programmability over synchronized multi-axis operation.
- Post-Production:Finishing, inspection, and repair workflows utilize specialized spindle configurations for surface treatment and dimensional verification.
Mass production stages retain the dominant installed base. Custom manufacturing is climbing the fastest as contract manufacturers reconfigure for shorter product lifecycles.
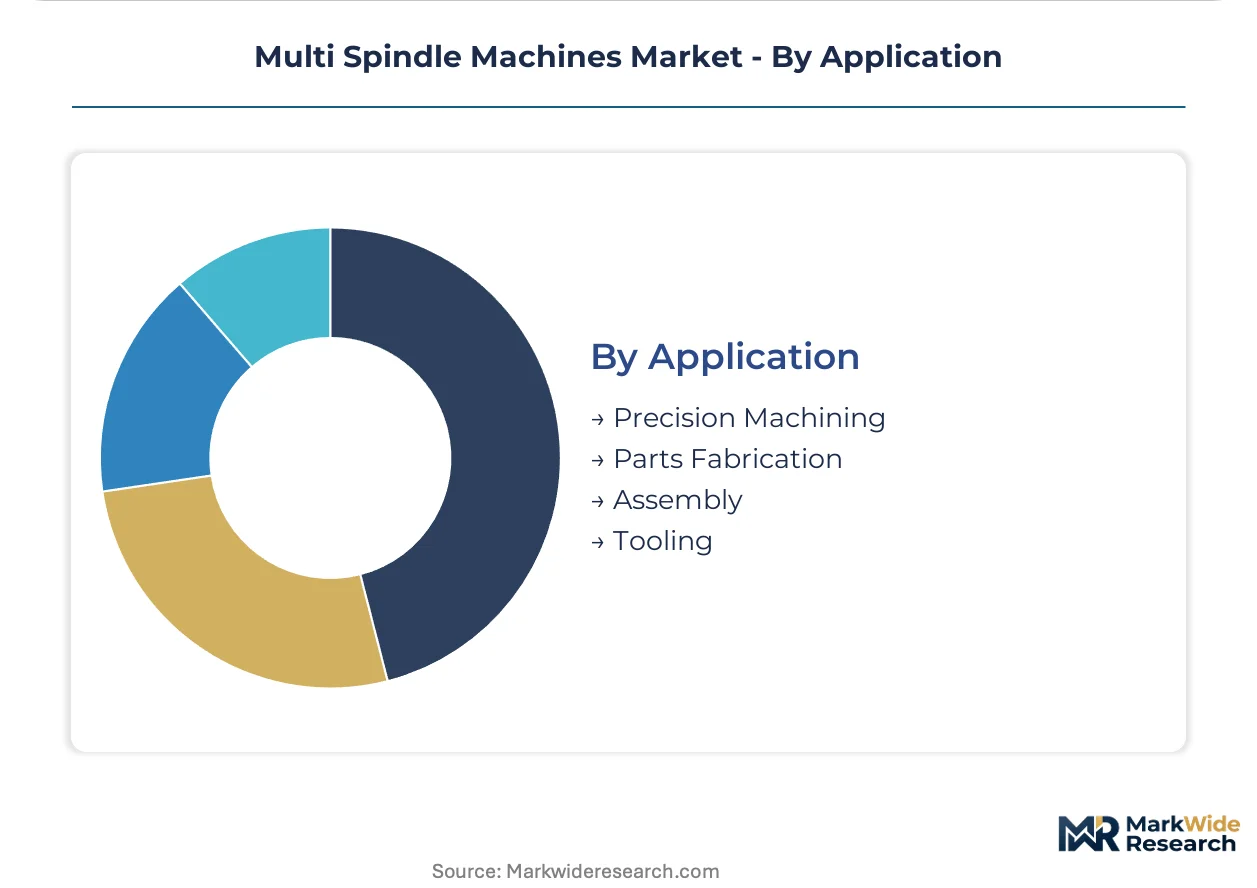
Application:
Functional purpose shapes spindle count, tool magazine capacity, and axis configuration priorities across deployment contexts.
- Precision Machining:Tolerance-critical operations for medical implants and aerospace structural components demand thermal compensation, vibration damping, and real-time dimensional feedback. These specifications propagate into equipment premiums of 40-60% above standard industrial configurations.
- Parts Fabrication:Volume-oriented cutting, drilling, and tapping operations prioritize synchronized spindle synchronization and automatic tool replacement to minimize per-part cycle times.
- Assembly:Press-fit, staking, and fastening operations utilize modified spindle platforms with force-controlled feed mechanisms.
- Tooling:Cutting tool and fixture production requires grinding and sharpening adaptations to standard multi-spindle architectures.
Precision machining commands the highest specification intensity. Parts fabrication sustains the broadest installed base across automotive supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Multi-spindle machine tool manufacturing traces its industrial lineage to 19th-century Swiss and German precision engineering traditions. INDEX-Werke and Tornos Group both emerged from this heritage, establishing design philosophies that still govern high-volume metal-cutting architectures. Contemporary demand geography reflects this historical concentration while expanding into new industrializing regions.
Germany
Automotive powertrain manufacturers in Baden-Württemberg sustain the densest concentration of installed multi-spindle capacity outside Japan. KBA traceability mandates for brake and transmission components propagate into machine specifications requiring integrated spindle monitoring and process documentation. The Stuttgart-Aalen corridor hosts tier-one suppliers deploying modular platforms for mixed-model transmission output.
Japan
Precision component fabricators serving Toyota and Honda supply chains favor compact vertical spindle configurations with sub-50 mm work envelopes. METI's Smart Manufacturing initiative subsidizes IoT-enabled machine tool retrofits, accelerating digital twin adoption among mid-sized automotive subcontractors. Nagoya's industrial belt concentrates demand for high-accuracy units serving hybrid powertrain component families.
United States
Medical device contract manufacturers in Minnesota and Massachusetts specify thermal-compensated architectures for orthopedic implant machining. OSHA machinery guarding standards and emerging EPA metalworking fluid emission rules create compliance cost layers distinct from European requirements. The Great Lakes automotive supply base favors horizontal spindle platforms for uninterrupted transmission component output.
China
Domestic electric vehicle battery housing producers are commissioning first multi-spindle installations for aluminum cell tray fabrication. MIIT's equipment upgrade subsidies under the 14th Five-Year Plan reduce capital barriers for precision metal-cutting adoption. Yangtze River Delta contract manufacturers in Suzhou and Ningbo represent the fastest-expanding addressable customer segment.
India
PLI scheme beneficiaries in Tamil Nadu and Gujarat are deploying initial precision machining infrastructure for automotive component export contracts. BIS certification requirements for imported machine tools extend commissioning timelines but create preference windows for locally assembled platforms. Pune's supplier parks concentrate first-time multi-spindle orders from tier-two component fabricators.
Multi Spindle Machines Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification intensity and application specialization. The vendor base stratifies into three tiers: integrated automation ecosystems, modular platform specialists, and precision vertical niche operators. Consolidation pressure concentrates among mid-scale European fabricators facing Japanese and Korean scale competition. Dominant competitive moves include backward integration into spindle and control system production, plus geographic expansion through distributor acquisition in Southeast Asian growth markets.
Within the modular platform tier, INDEX-Werke GmbH & Co. KG Hahn & Tessky and EMAG GmbH & Co. KG exemplify divergent strategic positioning—INDEX-Werke representing deep specialization in swappable spindle configurations, EMAG occupying integrated automation ecosystem architecture. Tornos Group anchors the precision-focused vertical, serving tolerance requirements exceeding standard industrial thresholds. These three German-origin entities collectively illustrate how heritage engineering concentration shapes contemporary competitive archetypes.
| Leading Market Players |
|---|
| DMG MORI Co., Ltd. |
| Yamazaki Mazak Corporation |
| Okuma Corporation |
| Haas Automation, Inc. |
| Doosan Machine Tools Co., Ltd. |
| EMAG GmbH & Co. KG |
| INDEX-Werke GmbH & Co. KG Hahn & Tessky |
| Citizen Machinery Co., Ltd. |
| Tornos Group |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between ISO 23125-compliant architectures and non-certified alternatives splits pricing power along compliance ladders, with KBA-traceable configurations in Germany commanding substantial premiums while standard industrial units face compression from Asian scale competitors. This bifurcation concentrates margin capture among modular platform specialists who control spindle and control system production in-house, while commodity-tier assemblers absorb ball screw and linear guide cost volatility from Japanese and German specialty suppliers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs equipment transactions, with differentiation anchored in CE marking tier, after-sales service bundling, and spindle rebuild program inclusion. Pricing pressure stems from five-axis machining center substitution for mid-volume contracts, eroding fixed multi-spindle configuration margins. Tier-one automotive suppliers in Stuttgart demonstrate lowest price sensitivity due to KBA-mandated process validation requirements, whereas Indian PLI scheme beneficiaries exhibit highest sensitivity as first-time precision infrastructure buyers.
Supply Chain Analysis
Freight cost exposure from precision component sourcing elevates landed costs for ball screws from Japan, linear guides from Germany, and CNC control systems from Taiwan. Raw material dependencies center on hardened steel alloys, ceramic spindle bearings, and servo motor windings. Single-source vulnerability concentrates in Japanese specialty bearing suppliers serving high-RPM configurations. Distribution runs through OEM-direct channels for tier-one automotive contracts and regional distributor networks for mid-scale contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Machinery Directive safety mandates and REACH chemical compliance perpetuate replacement cycles among European automotive suppliers. These regulatory milestones sustain demand for certified platforms even amid macroeconomic softness.
For Market Incumbents: To counter five-axis machining center substitution, INDEX-Werke and EMAG should deepen backward integration into spindle and control system production, securing captive supply of high-RPM bearing assemblies. Certification investment in ANSM-compliant architectures for French medical device producers creates defensible margin pools beyond commodity automotive contracts. For New Entrants and Emerging Players: Enter via Indian PLI scheme automotive component clusters in Tamil Nadu and Gujarat, where first-time precision infrastructure demand outpaces established supplier presence. White-space targets include REACH-compliant coolant system retrofits for installed European machine populations and digital twin integration services for mid-sized German automotive subcontractors. A service-first go-to-market angle—spindle rebuild expertise unbundled from equipment sales—circumvents capital-intensive manufacturing entry barriers. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale European fabricators face Japanese and Korean scale competition without modular platform differentiation. Long-term viability favors precision vertical specialists serving medical device tolerance thresholds exceeding standard industrial specifications. Acquisition target archetype: German-origin modular platform specialists with established KBA-traceability integration. Signal to watch: BIS certification timeline extensions in India creating preference windows for locally assembled platforms versus fully imported units.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Spindle Production | Captive bearing supply secures margin control against Japanese specialty supplier bottlenecks. |
| Digital Twin Platform Development | Predictive maintenance contracts with Stuttgart automotive suppliers generate recurring revenue streams. |
| REACH-Compliant Coolant System Retrofit | Closed-loop filtration upgrades capture installed base upgrade cycles across European machine populations. |
| Indian PLI Scheme Geographic Expansion | Tamil Nadu and Gujarat assembly facilities reduce BIS certification friction for first-time automotive component exporters. |
| Medical Device Certification Investment | ANSM and Swissmedic validation pathways command equipment premiums exceeding standard industrial configurations. |
Research Methodology
Multiple input streams — primary interviews with plant engineers and OEM procurement teams, secondary validation through customs data and machinery safety filings, and technical specification analysis — were reconciled to construct segment-level demand estimates. Primary fieldwork engaged maintenance directors at tier-one automotive suppliers, aftermarket service heads, and CNC macro programming technicians across German, Japanese, and North American manufacturing clusters. Secondary sources incorporated ISO 23125 machinery safety documentation, KBA traceability requirement filings, and SEC 10-K disclosures from listed machine tool manufacturers. Bottom-up equipment shipment tallies and top-down industrial capex allocation patterns were triangulated to anchor volume forecasts.
Historical shipment trajectories were cross-referenced against panel input from procurement officers at INDEX-Werke, EMAG, and Tornos Group distribution partners to calibrate growth assumptions across the projection horizon. Segmentation dimensions modeled include product type architecture, industry vertical tolerance requirements, manufacturing stage operational context, and geographic regulatory cluster. CAGRs were derived from equipment replacement cycle analysis and industrial capacity expansion announcements. Industry-specific forecast inputs encompassed METI Smart Manufacturing subsidy uptake rates and PLI scheme beneficiary capital allocation patterns.
The model holds under stable regulatory enforcement intensity across EU Machinery Directive and REACH frameworks; deviation in harmonization gaps between regional certification regimes would shift equipment platform architecture requirements. Stakeholders should weight assumptions against their own operating context, particularly regarding CNC programming expertise availability and legacy CAM software integration timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
China Power Tools Market
Tools
Extensometer Market
Tools
Power Press Machines Market
Tools
Construction Anchors Market
Tools
Impact Wrenches Market
Tools
CNC Leather Cutting Machine Market
Tools
Global Diamond Tools Market
Tools
Screw Fastener Market
Tools
Step Ladder Market
Tools
Industrial Ladder Market
Tools
Sand Control Tools Market
Tools
Collated Screws Market
Tools
Horizontal Milling Machine Market
Tools
Industrial Hand Tools Market
Tools
Engraver Machine Market
Tools
Portable Milling Machine Market