
 Squeegee Market | 2026-2036
Squeegee Market Size, Share, and Industry Trends Forecast 2026-2036
Squeegee Market Analytics
Multi-source procurement for rubber compounds is pivoting away from sole-supplier arrangements as manufacturers hedge against elastomer price volatility. Unger Global leverages its European compounding partnerships to sustain blade consistency across climate zones. Ettore Products Company anchors its position through proprietary edge-retention technology in commercial channels. 3M Company competes by extending fluoropolymer-coated blade lines into automotive OEM specifications.
A squeegee is a handheld tool comprising a flat blade mounted to a rigid or articulated handle, engineered to displace liquids from flat surfaces through controlled contact pressure typically measured in blade durometer from 35 to 95 Shore A. The device serves industrial, commercial, and residential sectors where surface preparation, cleaning, or moisture removal determines operational throughput or aesthetic outcome. Rubber blades occupy the mature volume tier across window and floor applications where cost sensitivity dominates procurement. Silicone blades represent the fastest-expanding product category, particularly in automotive and high-frequency commercial use where thermal stability and UV resistance justify premium positioning. The medium size band captures the broadest cross-application utility, while large-format blades concentrate margin pools in industrial floor-care contracts where equipment integration and replacement scheduling drive lifetime value calculations.
FDA regulations on indirect food-contact materials shape rubber formulation choices for squeegees deployed in food processing environments, while EPA guidelines on hazardous air pollutants constrain domestic vulcanization processes. REACH compliance in Europe mandates full material disclosure for imported elastomer components, elevating documentation burdens on non-EU suppliers. OSHA slip-resistance standards for commercial cleaning operations indirectly steer handle design and blade width specifications to reduce worker strain during extended use cycles. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions across multiple jurisdictions, as pending limitations on fluorinated coatings could force rapid reformulation of premium blade segments.
Market Dynamics
Silicone-blade technology is compressing replacement cycles across commercial cleaning operations as facilities managers prioritize labor efficiency over upfront tool costs. This material shift is redrawing supplier relationships and forcing compounders to certify thermal stability across wider climate ranges.
Growth Catalysts
- REACH compliance mandates:Full material disclosure requirements for imported elastomer components are accelerating documentation investments among European distributors, filtering non-compliant Asian suppliers from procurement shortlists.
- Automotive OEM surface preparation:Precision coating applications in vehicle assembly lines are specifying fluoropolymer-coated blades for contaminant-free substrate treatment, pulling premium-grade procurement volumes.
- German industrial window-cleaning contractors:Concentrated demand from facilities management clusters in Munich and Hamburg is sustaining premium pricing for extended-reach articulated handles.
Market Restraints
- Natural rubber price volatility:Harvest disruptions in Southeast Asian plantation zones are compressing margins for volume-tier blade manufacturers locked into annual supply contracts.
- Fluorinated coating restrictions:Pending per- and polyfluoroalkyl substance limitations across multiple jurisdictions are forcing rapid reformulation of premium blade segments before substitute chemistries achieve equivalent durability.
- Technical performance ceiling:Silicone formulations above 70 Shore A durometer exhibit accelerated edge chipping in sub-zero conditions, constraining Nordic market penetration.
Strategic Opportunities
- Food processing hygiene mandates:FDA indirect food-contact material regulations are creating specification openings for thermoplastic elastomer blades that eliminate vulcanization residue concerns in protein handling facilities.
- Integrated floor-care equipment:Convergence of IoT-enabled usage tracking with predictive blade-replacement algorithms is enabling subscription-based consumable models for industrial cleaning fleets.
- India's organized retail expansion:Hypermarket and mall construction in Bangalore and Hyderabad is generating first-time demand for professional-grade window maintenance tools among facility management startups.
Industry Challenges
- Elastomer compounding expertise scarcity:Formulation chemists capable of balancing UV resistance with Shore A consistency across climate zones command premium compensation, constraining R&D throughput at mid-tier manufacturers.
- Multi-jurisdiction certification timelines:Simultaneous EPA hazardous air pollutant reviews and ECHA substance evaluations are extending product launch windows for novel rubber formulations by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Squeegee Market |
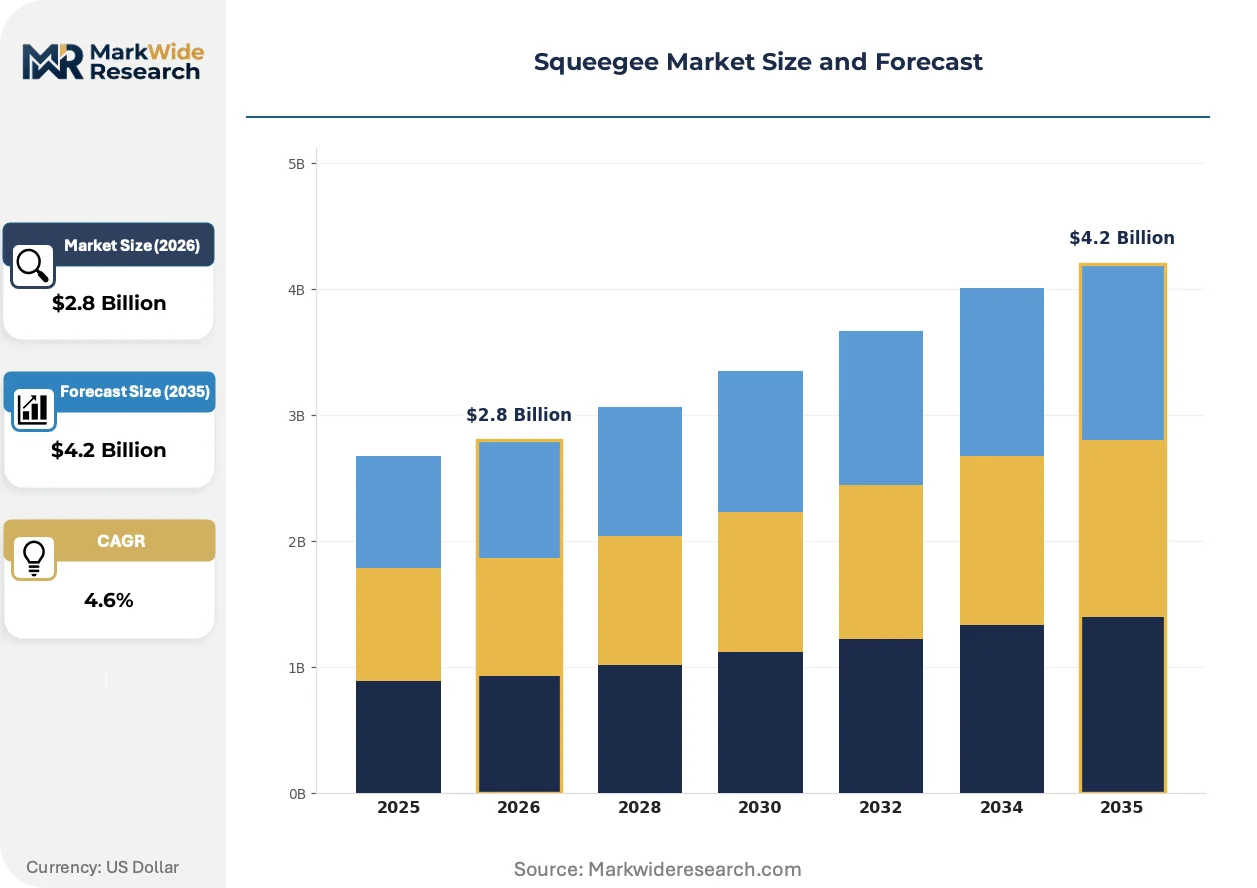
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rubber, Silicone, Metal, Plastic End User: Residential, Commercial, Industrial, Automotive Size: Small, Medium, Large, Extra Large Application: Windows, Floors, Vehicles, Walls |
| Companies Covered | Unger Global, Ettore Products Company, 3M Company, Vileda, Libman Company, Haviland Corporation, Tennant, Pulex, Moerman, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Squeegee Market Evolving Landscape
Material science advances and procurement digitization are converging to reshape how blade performance is specified, measured, and contracted across end-use verticals.
Fluoropolymer surface coatings are absorbing premium segment volume as automotive OEMs and semiconductor cleanroom operators specify zero-contaminant contact surfaces. Tier-one suppliers in Germany and Japan are qualifying these blades for five-year replacement intervals, compressing revenue per site for traditional rubber compounders while expanding lifetime value calculations for coating specialists.
REACH Article 33 disclosure obligations are forcing full supply chain transparency for elastomer imports into EU member states. Compounders must now document Substances of Very High Concern content at 0.1% thresholds, redirecting formulation strategies toward low-vulcanization chemistries. German industrial distributors are responding by consolidating procurement around pre-certified European compounding partners.
Usage-based contracting is displacing transactional blade sales in commercial cleaning fleets. Facility management platforms in North American metropolitan markets are integrating RFID-enabled handle sensors to track contact pressure and stroke frequency, unbundling blade replacement from equipment purchase. This instrumentation shift favors suppliers capable of API integration with workforce management software.
Squeegee Market Segmentation
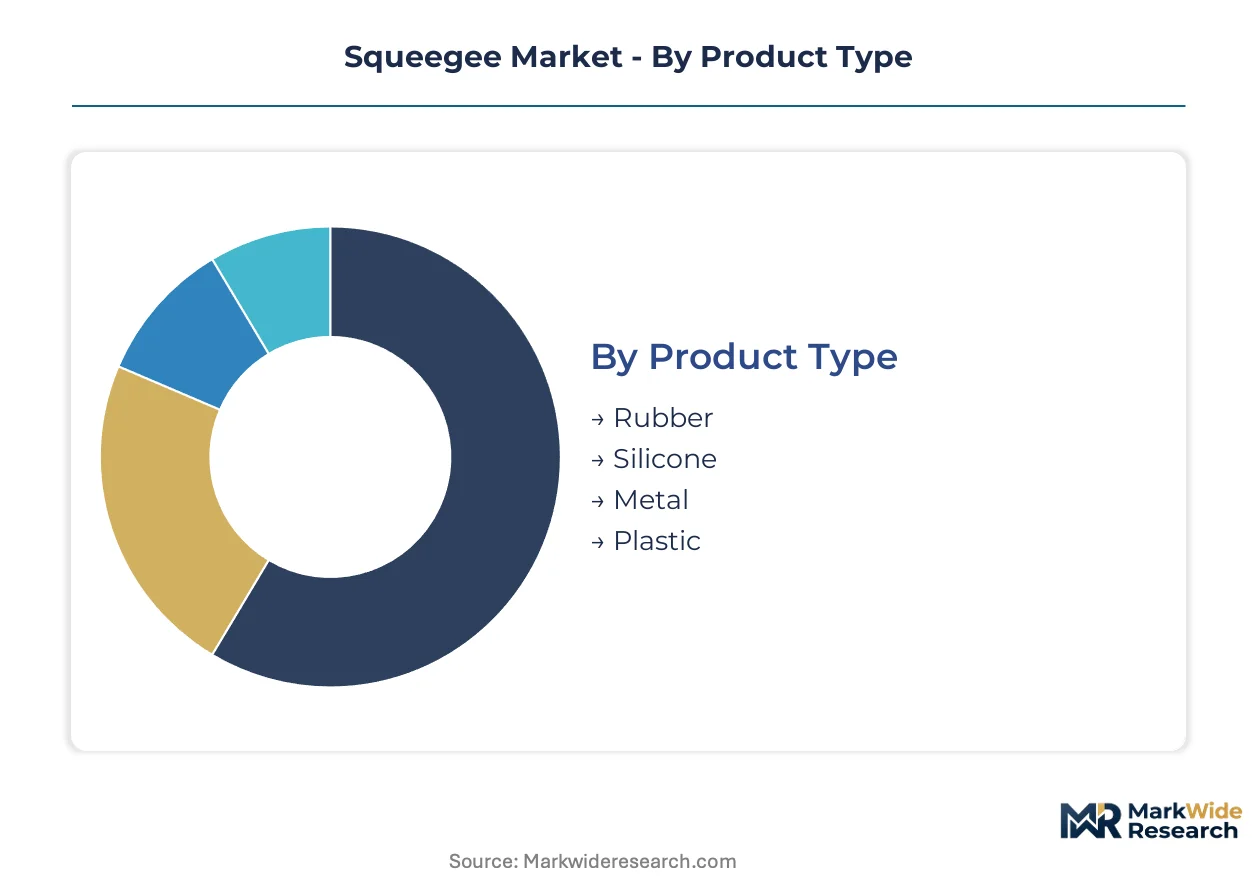
Procurement patterns in squeegee markets diverge sharply by blade chemistry and handle configuration, with facilities managers, automotive OEMs, and residential buyers each prioritizing distinct performance thresholds. Understanding how these preference clusters map to product specifications enables suppliers to align R&D investments with margin concentration points.
Product Type:
Cost sensitivity and replacement frequency separate buyers across material categories, with premium procurement favoring thermal stability while volume tiers optimize per-unit economics.
- Rubber:Natural and synthetic elastomer formulations dominate window and floor applications where procurement teams prioritize unit cost over longevity. Harvest disruptions in Southeast Asian plantation zones are compressing margins for manufacturers locked into annual supply contracts, redirecting some volume toward nitrile-blend alternatives.
- Silicone:Thermally stable formulations from 35 to 95 Shore A durometer are expanding fastest in automotive OEM surface preparation and high-frequency commercial cleaning where UV resistance justifies premium positioning. REACH compliance mandates are accelerating documentation investments among European distributors, filtering non-compliant Asian suppliers from silicone procurement shortlists.
- Metal:Stainless steel and aluminum blade carriers serve industrial floor-care equipment integration where rigid contact pressure requirements exceed elastomer structural limits. German industrial distributors consolidate procurement around pre-certified European metalworking partners.
- Plastic:Thermoplastic elastomer and polypropylene constructions address food processing hygiene mandates where FDA indirect food-contact regulations eliminate vulcanization residue concerns in protein handling facilities.
Rubber leads volumes today; silicone is gaining share fastest.
End User:
Application intensity and specification stringency determine procurement sophistication, with regulated environments demanding certified formulations that residential buyers disregard.
- Residential:Price-sensitive consumers purchasing through retail channels prioritize ergonomic handles and standardized blade widths for intermittent window and shower maintenance. Big-box retailers in North American metropolitan markets dominate distribution.
- Commercial:Facilities management platforms specify streak-free performance and extended replacement cycles, with RFID-enabled handle sensors enabling usage-based contracting unbundled from equipment purchase. Munich and Hamburg contractor clusters sustain premium pricing for extended-reach articulated handles.
- Industrial:Floor-care fleet operators integrate predictive blade-replacement algorithms with IoT-enabled usage tracking, favoring suppliers capable of API integration with workforce management software. OSHA slip-resistance standards indirectly steer handle design specifications.
- Automotive:Vehicle assembly lines specify fluoropolymer-coated blades for contaminant-free substrate treatment in precision coating applications, pulling premium-grade procurement volumes with five-year replacement intervals.
Commercial commands the largest revenue pool; automotive shows the steepest expansion trajectory.
Size:
Equipment compatibility and worker ergonomics dictate dimensional selection, with integrated systems requiring precise blade-carrier interfaces.
- Small:Compact blades under 12 inches serve residential shower enclosures and automotive detailing where maneuverability outweighs coverage efficiency.
- Medium:The broadest cross-application utility spans residential window maintenance through light commercial cleaning, capturing volume concentration across retail and distributor channels.
- Large:Industrial floor-care contracts concentrate margin pools where equipment integration and replacement scheduling drive lifetime value calculations; blade widths from 18 to 24 inches dominate automated scrubber specifications.
- Extra Large:Specialized architectural glass and atrium maintenance requires custom-engineered 36-inch and wider formats with reinforced carriers to prevent blade deflection under contact pressure.
Medium sizes lead volumes today; large formats are expanding most quickly in industrial fleet procurement.
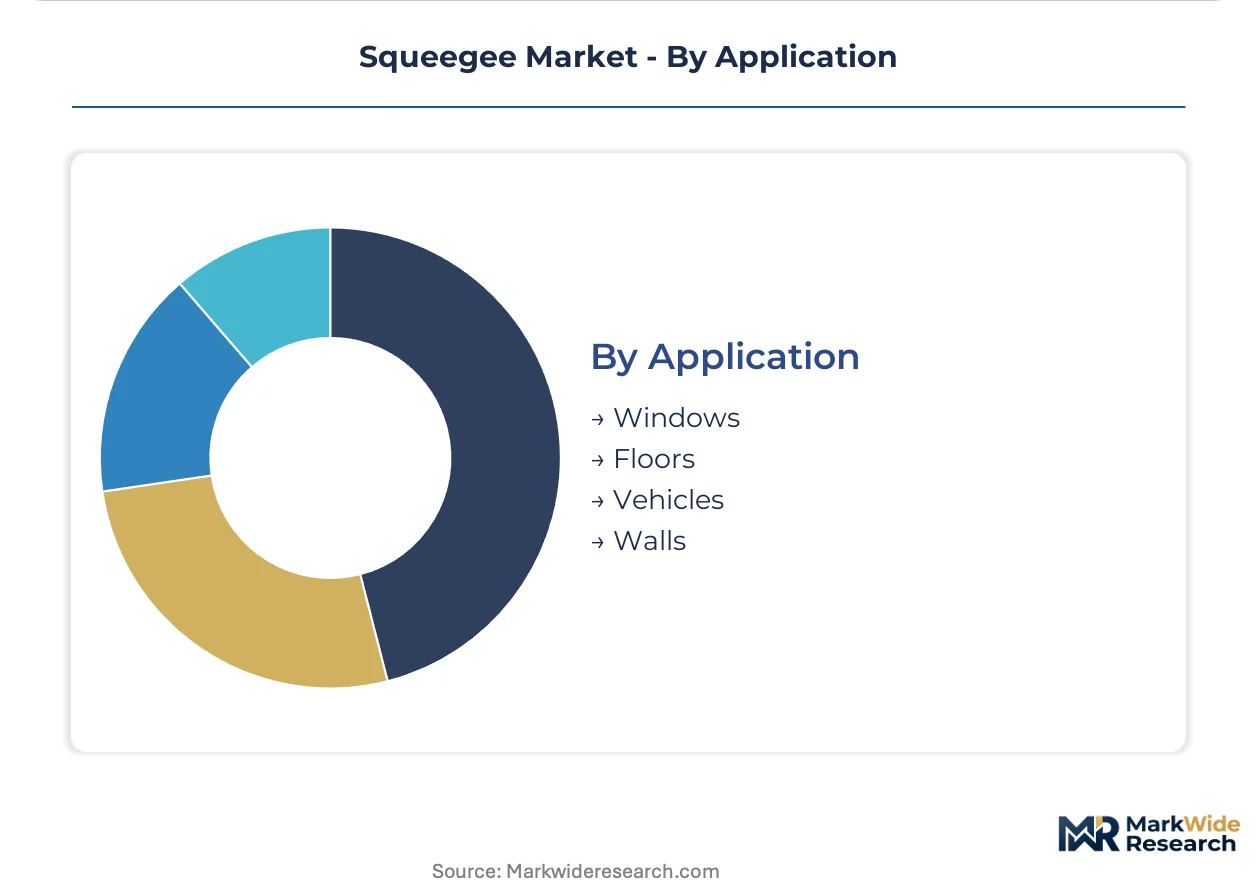
Application:
Surface material and contamination type determine blade durometer and edge geometry specifications, with each vertical presenting distinct chemical exposure profiles.
- Windows:Glass substrate cleaning demands streak-free elastomer performance across climate zones, with silicone formulations above 70 Shore A exhibiting accelerated edge chipping in sub-zero Nordic conditions that constrains regional penetration.
- Floors:Industrial concrete and epoxy surface preparation requires abrasion-resistant blade compounds integrated with automated scrubber-dryer equipment; predictive maintenance algorithms are displacing transactional blade sales in North American fleet contracts.
- Vehicles:Automotive OEM paint booth and final assembly line specifications mandate zero-contaminant contact surfaces, with fluoropolymer-coated blades qualified for extended replacement intervals by tier-one suppliers in Germany and Japan.
- Walls:Tiled and painted vertical surfaces in healthcare and food service environments require FDA-compliant formulations that eliminate vulcanization residue, creating specification openings for thermoplastic elastomer alternatives.
Window applications lead volumes today; floor-care integration is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting elastomer compounding capacity toward jurisdictions with streamlined chemical disclosure frameworks. Manufacturers face divergent compliance burdens across major demand centers, reshaping where formulation expertise concentrates.
Germany
Industrial window-cleaning contractors in Munich and Hamburg sustain premium demand for extended-reach articulated handles. REACH Article 33 mandates full material disclosure at 0.1% SVHC thresholds, filtering non-compliant Asian suppliers from procurement shortlists. The Rhine-Ruhr manufacturing corridor hosts pre-certified European compounding partners serving blade consistency requirements.
United States
Commercial cleaning fleets in Chicago and New York metropolitan markets are integrating IoT-enabled usage tracking for predictive blade replacement. EPA hazardous air pollutant guidelines constrain domestic vulcanization processes, extending product launch timelines for novel rubber formulations. Midwest distribution hubs consolidate procurement for volume-tier rubber blades.
China
Organized retail expansion in Shanghai and Shenzhen is generating first-time demand for professional-grade window maintenance tools among facility management startups. GB standards on industrial chemical safety shape elastomer import specifications for food processing applications. Yangtze River Delta manufacturing zones concentrate nitrile-blend alternative production.
India
Hypermarket and mall construction in Bangalore and Hyderabad is driving procurement of silicone-blade tools among emerging facility management startups. BIS certification requirements for rubber products create entry barriers for unqualified imports. Western Maharashtra industrial clusters host domestic compounding operations serving regional blade demand.
Japan
Automotive OEM surface preparation specifications in Nagoya and Toyota City mandate fluoropolymer-coated blades for contaminant-free substrate treatment. METI industrial standards on chemical substance management elevate documentation requirements for imported elastomer components. Kansai region tier-one suppliers qualify blades for extended replacement intervals.
Squeegee Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue food-contact compliance specializations and IoT-integrated service models. The vendor base spans multinational diversified industrials, regional blade specialists, and contract manufacturers serving private-label retail channels. Three archetypes dominate: European compounding-integrated manufacturers, North American channel-anchored brands, and Asia-Pacific scale-driven exporters. Competitive moves concentrate on REACH pre-certification partnerships and API integration with workforce management platforms.
Among diversified industrial conglomerates, 3M Company exemplifies premium-tier positioning through fluoropolymer coating expertise. Unger Global and Ettore Products Company anchor the specialist manufacturer archetype, with the former representing European compounding-integrated operations and the latter exemplifying channel-anchored brand strength in commercial cleaning verticals. These three entities collectively illustrate how formulation control, distribution depth, and specification-grade certification separate competitive tiers.
| Leading Market Players |
|---|
| Unger Global |
| Ettore Products Company |
| 3M Company |
| Vileda |
| Libman Company |
| Haviland Corporation |
| Tennant |
| Pulex |
| Moerman |
| Others |
Value Network & Pricing Analysis
Formulation chemists capable of balancing UV resistance with Shore A consistency command premium compensation in the Rhine-Ruhr corridor, widening labor-cost spreads between certified European compounders and volume-tier Asian suppliers. This workforce concentration shapes pricing tiers: REACH-compliant silicone blades from German distributors carry substantial premiums over natural rubber alternatives sourced through Southeast Asian contract manufacturers.
Pricing Analysis
Distributor margins in commercial cleaning channels absorb 25-35 points before facility management platforms take delivery, while direct-to-OEM automotive contracts trade volume commitments for preferential unit economics. Three-tier pricing structure across premium, standard, and economy levels separates fluoropolymer-coated automotive specifications from commercial silicone grades and commodity rubber retail packs. Pricing pressure stems from natural rubber harvest volatility in Thai and Indonesian plantation zones compressing margins for locked-in annual contracts. Residential retail buyers exhibit highest price sensitivity, while automotive OEM procurement teams prioritize contaminant-free performance over per-unit cost.
Supply Chain Analysis
Freight cost differentials between containerized elastomer imports from Malaysia and Vietnam versus European pre-certified compounders are redirecting procurement consolidation toward Rhine-Ruhr logistics hubs. Raw material dependencies center on Southeast Asian natural rubber plantations, German silicone feedstock operations, and Chinese nitrile-blend alternative production. Single-source vulnerability concentrates in Thai rubber harvests exposed to climate disruption and labor availability swings. Distribution runs through industrial distributor networks in Germany, big-box retail channels in North America, and emerging facility management platforms in Indian metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where REACH Article 33 disclosure mandates are accelerating documentation investments and filtering non-compliant suppliers from European procurement shortlists.
For Market Incumbents: To counter fluorinated coating restrictions forcing rapid reformulation of premium blade segments, Unger Global and Ettore Products Company should deepen backward integration into low-vulcanization elastomer compounding partnerships. Certification investment in pre-qualified European supply chains represents the critical defensive lever against Asian suppliers filtered from REACH-compliant shortlists. For New Entrants and Emerging Players: Launch via direct-to-facility-management platform integration targeting Indian hypermarket and mall construction clusters in Bangalore and Hyderabad. Food processing hygiene mandates in protein handling facilities create the most penetrable specification opening, with thermoplastic elastomer blades eliminating vulcanization residue concerns as the differentiated entry angle. For Investors and Strategic Acquirers: Industrial cleaning equipment manufacturers are the most active acquirer in this space, seeking consumable attachment to automated scrubber-dryer fleets. Long-term viability hinges on API integration capabilities with workforce management software platforms. The signal to watch is RFID-enabled handle sensor adoption rates in North American metropolitan commercial cleaning contracts.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Pre-Certification Partnership | Secures access to German industrial window-cleaning contractor procurement shortlists. |
| Fluoropolymer Coating Reformulation | Addresses pending PFAS limitations while maintaining automotive OEM qualification standards. |
| IoT Handle Sensor Integration | Enables usage-based contracting unbundled from equipment purchase in commercial fleets. |
| Low-Vulcanization Elastomer Development | Eliminates hazardous air pollutant exposure in EPA-constrained domestic manufacturing. |
| Indian Distribution Channel Establishment | Captures first-time professional-grade demand from Bangalore facility management startups. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with facilities management procurement directors, elastomer compounding plant managers, automotive OEM surface preparation engineers, and industrial distributor category buyers with secondary validation through REACH SVHC disclosure databases, EPA hazardous air pollutant guidelines, customs trade data on elastomer imports, and SEC filings from diversified industrial conglomerates. Bottom-up blade volume estimates triangulated against top-down market sizing from end-use application analysis.
Segment-weighting applied blade material chemistry, handle configuration, end-user vertical, and geographic regulatory cluster as core dimensions across the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating replacement cycle compression from silicone technology adoption and REACH compliance filtering effects. Industry-specific inputs included automotive OEM specification timelines and commercial cleaning fleet IoT instrumentation penetration rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated PFAS restriction implementation or Southeast Asian rubber harvest disruption scenarios. Forecasts reflect documented assumptions on elastomer price trajectories and regulatory enforcement intensity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Manual Cutting Equipment Market
Tools
Fatigue Testing Machine Market
Tools
Cold and Hot Tool Steel Market
Tools
Mallets and Sledgehammers Market
Tools
Adjustable Gripping Hand Tools Market
Tools
Bottle Jack Market
Tools
Coil Fed Punching and Cutting Machines Market
Tools
North America Power Tools Market
Tools
Power Tools Market
Tools
Entrenching Tool Market
Tools
Surface Planer Market
Tools
Garden Digging Tools Market
Tools
High-Speed Steel Metal Cutting Tools Market
Tools
Global Electric Portable Drill Market
Tools
Drill Presses Market
Tools
Total Station Market