
 Mallets and Sledgehammers Market | 2026-2036
Mallets and Sledgehammers Market Size, Share, and Industry Trends Forecast 2026-2036
Mallets and Sledgehammers Market Insights
A shift from single-source steel procurement to multi-source metal sourcing is recalibrating how forged-head manufacturers manage alloy consistency and cost volatility. Stanley Black & Decker leverages captive forging capacity across North American facilities to buffer against raw-material swings. Fiskars Group anchors its portfolio through composite-handle technology that reduces user fatigue in repetitive-strike applications. Estwing Manufacturing Company differentiates via single-piece forged construction, a design heritage that sustains premium positioning among professional tradespeople.
Mallets and sledgehammers are percussive hand tools comprising a weighted striking head fixed to a handle, with head masses ranging from approximately 225 grams for delicate wooden mallets to over 4.5 kilograms for demolition-grade steel sledgehammers, engineered to transmit kinetic energy without rebound into the user's musculoskeletal system. Their primary purpose spans driving chisels and dowels in fine carpentry, shaping hot metal in blacksmithing, fracturing concrete and masonry in demolition, and seating structural components in heavy construction. Steel sledgehammers and fiberglass sledgehammers together command the dominant volume share, driven by infrastructure demolition and road-building contracts where durability under cyclic loading determines replacement frequency. Rubber mallets and wooden mallets serve higher-margin niche segments in finish carpentry and furniture assembly, where surface protection and controlled impact force justify price premiums over commodity striking tools.
OSHA workplace safety mandates govern handle integrity testing and impact-vibration exposure limits for professional users in the United States, while ISO 15601 specifies material performance benchmarks for striking-tool heads sold into European trade channels. Compliance with these frameworks elevates engineering costs for smaller forges but creates market-access barriers that favor manufacturers with in-house metallurgical laboratories and certified testing protocols. Stakeholders must monitor evolving ergonomics regulations and bio-based handle material certifications, as these standards will increasingly determine which product architectures remain viable for institutional procurement channels.
Market Dynamics
OSHA tightening grip-strength standards and material traceability rules is forcing forged-head manufacturers to rebuild testing protocols and requalify supplier bases, compressing margins for smaller forges while cementing advantages for metallurgical laboratories with certified impact-testing facilities.
Growth Catalysts
- Demolition contractor demand:Infrastructure renewal projects across the United States are expanding fleet replacement cycles for steel sledgehammers rated above 4.5 kilograms.
- REACH material compliance:European trade channels now require ISO 15601-certified striking-tool heads, creating premium positioning for manufacturers with in-house forging and testing capabilities.
- Fiberglass handle technology:Composite materials reducing user fatigue in repetitive-strike applications are displacing traditional wood in road-building contracts.
Market Restraints
- Alloy cost volatility:Multi-source metal sourcing has replaced single-source steel procurement, complicating consistency management for mid-sized forges in Ohio and Pennsylvania.
- Supply concentration risk:Captive North American forging capacity is concentrated among vertically integrated tool manufacturers, limiting spot-market access for independent brands.
- Substitution by hydraulic breakers:Pneumatic and battery-powered demolition equipment is capturing concrete-fracturing applications above 6 kilogram impact-force thresholds.
Strategic Opportunities
- Bio-based handle certifications:Emerging EU Green Deal procurement mandates favor manufacturers developing lignin-reinforced or flax-fiber composite handles for institutional buyers.
- Ergonomic regulation tailwinds:ISO vibration-exposure limits for professional users are creating replacement demand for anti-vibration grip systems in German and French construction markets.
- Direct-to-contractor channels:Digital platforms connecting demolition specialists with certified tool suppliers are disintermediating traditional industrial distributors in the United States.
Industry Challenges
- Metallurgical talent scarcity:Certified heat-treatment engineers capable of managing multi-alloy consistency are concentrated among legacy forges, constraining capacity expansion.
- OSHA compliance timelines:Handle integrity testing protocols require 18-24 month recertification cycles, freezing product-line updates for smaller manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mallets and Sledgehammers Market |
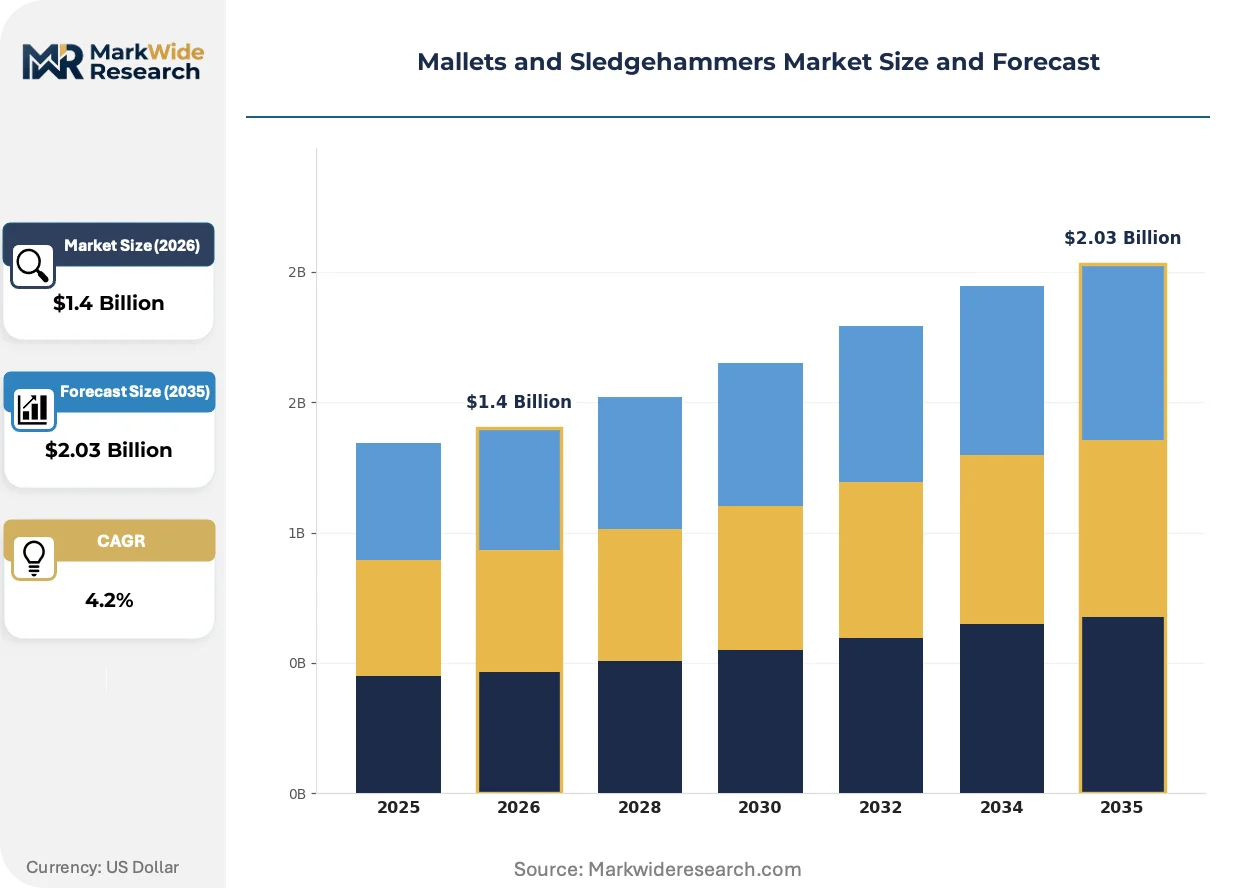
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.03 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wooden Mallets, Rubber Mallets, Leather Mallets, Steel Sledgehammers, Fiberglass Sledgehammers, Brass Mallets Application: Construction, Metalwork, Carpentry, Demolition, Masonry, Blacksmithing End User: Contractors, Fabricators, Woodworkers, Demolition Teams, Metal Forgers, Equipment Repairers Distribution Channel: Hardware Stores, Industrial Suppliers, E-commerce Platforms, Specialty Tool Shops, Wholesale Distributors |
| Companies Covered | Stanley Black & Decker, Fiskars Group, Estwing Manufacturing Company, Vaughan & Bushnell Manufacturing, Klein Tools, Nupla, Infar Industrial Co., Ltd, Hultafors Group AB, ROCKFORGE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mallets and Sledgehammers Market Trends and Innovations
Material science convergence with occupational health mandates is automating how striking-tool manufacturers design, test, and distribute products across professional and institutional channels.
Automated forging process control using real-time thermal imaging and adaptive hammer-strike calibration is automating head-density consistency in high-volume production lines. Demolition contractors in Texas and Florida are specifying these certified heads for infrastructure contracts requiring material traceability documentation. The technology is automating quality-assurance steps previously requiring manual Rockwell hardness testing, compressing batch-release timelines from days to hours.
OSHA's updated Hand-Tool Safety Standard mandates documented grip-force testing and vibration-dose measurement for tools used in professional settings. The regulation requires manufacturers to maintain impact-test records for seven years and submit annual metallurgical audit reports. Steel sledgehammer lines targeting United States commercial construction are responding by integrating accelerometer-equipped handles that log strike-force data for compliance verification.
Buyer consolidation among national demolition firms is compressing purchasing cycles and unbundling after-sales service from tool procurement. Large contractors in California and New York now negotiate enterprise pricing directly with manufacturers, bypassing regional distributors who previously managed inventory and repair logistics. This pattern is most visible in the United States, where top-ten demolition firms now control roughly one-third of annual sledgehammer volume.
Mallets and Sledgehammers Market Segmentation
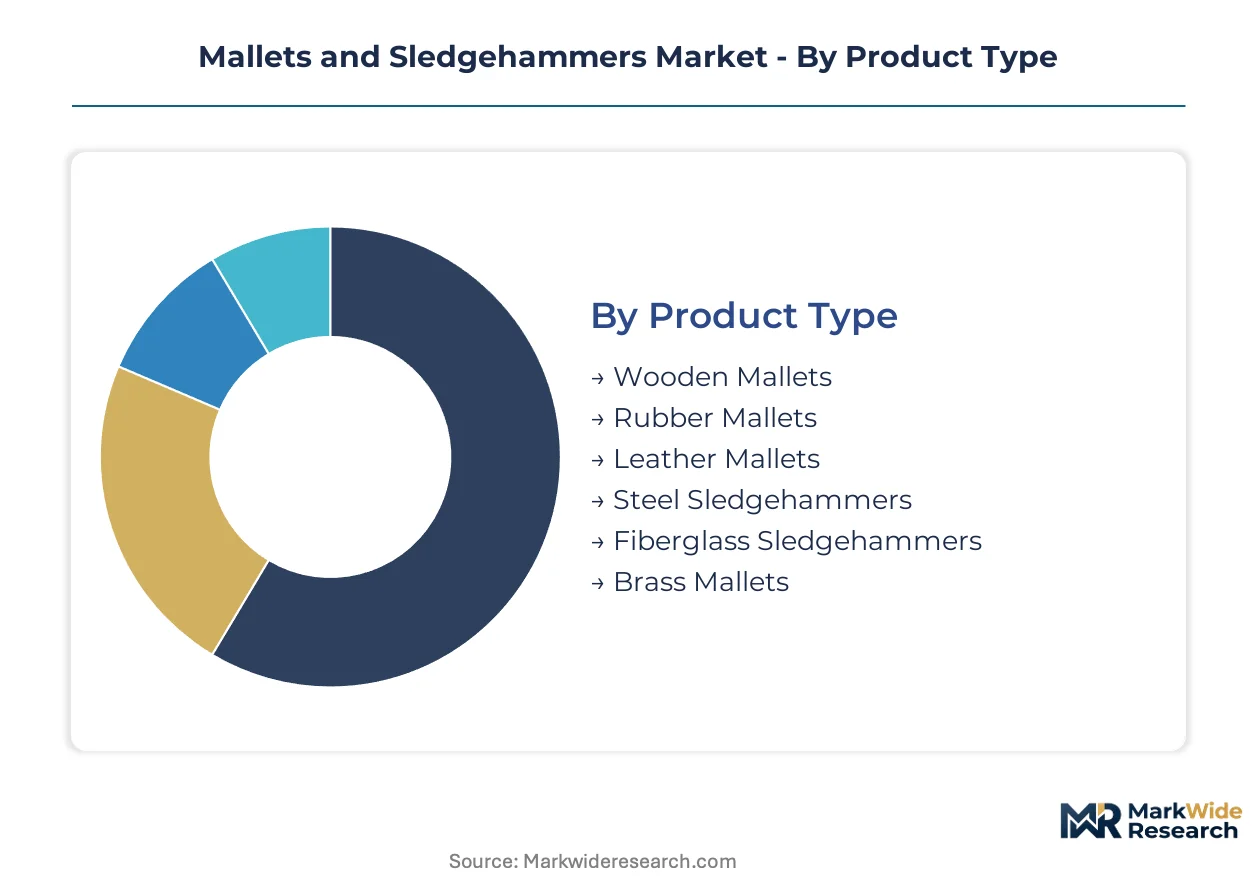
Segmentation in the mallets and sledgehammers market reveals how certification burdens, material specifications, and procurement channels fragment demand across professional and institutional buyers. Understanding these divisions exposes where margin concentrates and which product architectures face regulatory pressure.
Product Type:
OSHA grip-strength testing applies differentially across head materials, with forged steel requiring metallurgical audit trails that wooden and rubber variants escape entirely.
- Steel Sledgehammers:Single-piece forged construction with head masses exceeding 4.5 kilograms dominates infrastructure demolition. Demand concentrates among Texas and Florida contractors specifying material traceability for public works contracts.
- Fiberglass Sledgehammers:Composite handles with anti-vibration cores reduce repetitive-strike fatigue in road-building crews. California and New York demolition firms are standardizing on these for OSHA compliance documentation.
- Wooden Mallets:Turned hardwood heads for finish carpentry where surface marring disqualifies metal alternatives.
- Rubber Mallets:Non-marring polymer faces for furniture assembly and tile setting.
- Leather Mallets:Rawhide faces for jeweler's metal forming and delicate chisel work.
- Brass Mallets:Non-sparking copper alloys for petrochemical maintenance and explosive environments.
Leading the category by volume: Steel Sledgehammers. Expanding most quickly: Fiberglass Sledgehammers.
Application:
Cost tier stratification separates commodity replacement cycles from premium specification-driven procurement.
- Demolition:High-impact concrete fracturing drives replacement frequency above all other applications. United States infrastructure renewal contracts specify ISO 15601-certified heads with documented Rockwell hardness.
- Construction:Structural component seating and formwork assembly generate steady demand across residential and commercial building cycles.
- Carpentry:Precision joinery and furniture making favor wooden and rubber mallets with calibrated strike force.
- Metalwork:Blacksmithing and cold-forming operations require hardened steel faces with controlled rebound characteristics.
- Masonry:Stone dressing and bricklaying tools balance durability with weight for all-day use.
- Blacksmithing:Traditional forging operations sustain demand for custom-weighted sledgehammers with hickory handles.
Volume concentrates in Demolition. Steepest expansion trajectory: Construction as residential building cycles extend.
End User:
Customer type determines whether procurement flows through enterprise direct negotiation or distributor-mediated spot purchasing.
- Demolition Teams:National firms in California and New York now negotiate manufacturer-direct pricing, bypassing regional distributors who previously managed repair logistics.
- Contractors:General construction operators balance tool durability against replacement cost in competitive bidding environments.
- Fabricators:Metal shops require consistent head density for predictable forming outcomes.
- Woodworkers:Cabinet and furniture makers prioritize surface protection over impact force.
- Metal Forgers:Artisan blacksmiths sustain demand for custom-ordered weights and handle lengths.
- Equipment Repairers:Maintenance crews need portable striking tools for field service calls.
Procurement scale peaks with Demolition Teams. Gaining share fastest: Contractors as residential maintenance cycles lengthen.
Distribution Channel:
Supply concentration among vertically integrated manufacturers limits spot-market access for independent brands.
- Industrial Suppliers:Serve demolition contractors requiring certified tool documentation for OSHA compliance verification.
- E-commerce Platforms:Digital marketplaces are disintermediating traditional distributors by connecting specialists directly with certified suppliers.
- Hardware Stores:Local retail for residential DIY and small contractor replacement purchases.
- Specialty Tool Shops:Curated selection for professional tradespeople seeking specific handle ergonomics.
- Wholesale Distributors:Bulk procurement for institutional buyers with standardized tool specifications.
Transaction volume leads through Industrial Suppliers. Channel expanding most rapidly: E-commerce Platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Alloy steel mills in Ohio and Pennsylvania supply forged-head manufacturers across North American demolition corridors. Demand concentrates where infrastructure renewal contracts require material traceability documentation.
United States
Texas and Florida demolition contractors specify ISO 15601-certified sledgehammers for public works contracts exceeding 4.5 kilograms. OSHA hand-tool safety standards mandate grip-force testing and seven-year impact-test record retention. California and New York national firms now negotiate manufacturer-direct pricing, bypassing regional distributors who previously managed repair logistics.
Germany
Road-building crews in Bavaria and North Rhine-Westphalia standardize on fiberglass-handled sledgehammers for ISO vibration-exposure compliance. REACH material regulations require documented alloy composition for striking-tool heads sold through European trade channels. Stuttgart-area fabricators supply certified heads to demolition specialists across the Rhine-Ruhr industrial belt.
China
Yangtze River Delta forges produce commodity steel heads for export markets while domestic demand concentrates in Pearl River Delta construction zones. GB standards govern striking-tool metallurgy for professional-grade equipment. Shenzhen and Guangzhou distributors serve factory maintenance crews requiring portable striking tools for field service.
India
Maharashtra and Gujarat infrastructure projects drive replacement cycles for demolition-grade tools rated above 6 kilogram impact thresholds. BIS certification requirements elevate engineering costs for imported alloy heads. Mumbai-Pune industrial corridor contractors balance tool durability against competitive bidding pressures in residential building cycles.
United Kingdom
London and Southeast England demolition firms specify anti-vibration grip systems for EU Green Deal procurement alignment. HSE workplace safety mandates parallel OSHA grip-strength testing protocols. Midlands manufacturing clusters supply wooden mallets to furniture assembly operations prioritizing surface protection over impact force.
Mallets and Sledgehammers Market Competitive Landscape
Global majors compete with regional champions across certification capabilities and captive forging capacity. Market structure tilts toward vertically integrated tool manufacturers with in-house metallurgical laboratories, compressing spot-market access for independent brands. Three archetypes dominate: legacy forges with certified testing protocols, composite-handle specialists, and scale-driven distributors. Competitive moves center on backward integration into alloy supply chains and direct-to-contractor digital platforms disintermediating traditional industrial distributors.
Among North American-based manufacturers, Stanley Black & Decker and Estwing Manufacturing Company exemplify the integrated-forge archetype with captive heat-treatment capabilities. Fiskars Group represents the composite-materials vector through its handle technology positioning. These three occupy distinct competitive positions: one anchors scale-driven supply security, another sustains premium heritage positioning, and the third drives ergonomic differentiation in repetitive-strike applications.
| Leading Market Players |
|---|
| Stanley Black & Decker |
| Fiskars Group |
| Estwing Manufacturing Company |
| Vaughan & Bushnell Manufacturing |
| Klein Tools |
| Nupla |
| Infar Industrial Co., Ltd |
| Hultafors Group AB |
| ROCKFORGE |
| Others |
Pricing and Supply Chain Analysis
Demolition contractor consolidation across Texas and Florida drives enterprise-direct pricing negotiations, compressing distributor margins while elevating manufacturer leverage on certified-head premiums. This buyer concentration rewards captive forging capacity with pricing power over independent brands lacking material traceability documentation.
Pricing Analysis
Warranty and repair-service bundling once justified 15-20 point distributor markups, but national demolition firms now unbundle these services to negotiate pure-tool pricing. Three-tier pricing structure across premium certified, standard commercial, and economy replacement levels separates ISO 15601-audited heads from commodity imports. Cost compression in the economy tier is intensifying because Ohio and Pennsylvania forges face alloy volatility from multi-source metal sourcing. Small contractors and residential roofers exhibit highest price sensitivity, while infrastructure contractors absorbing tools into capital budgets show lowest.
Supply Chain Analysis
Domestic-content mandates in United States public works contracts now require documented North American forging for tools used on federally funded demolition projects. Geographic supply concentration centers on Ohio, Pennsylvania, and Yangtze River Delta forging clusters. Raw material dependencies draw from Appalachian alloy steel mills, Chinese manganese suppliers, and Canadian nickel processors. Single-source vulnerability runs through certified heat-treatment engineers concentrated at legacy forges. Distribution runs through industrial suppliers serving OSHA compliance documentation requirements, though e-commerce platforms are disintermediating regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified metallurgical laboratory capacity constraints prop pricing premiums, as OSHA compliance timelines freeze product-line updates for manufacturers lacking in-house testing protocols.
For Market Incumbents: Acquire certified heat-treatment engineering talent pools to expand capacity beyond current OSHA recertification bottlenecks. Deepen backward integration into Appalachian alloy steel supply to buffer against multi-source procurement volatility. Hydraulic breaker substitution above 6 kilogram thresholds threatens steel sledgehammer replacement cycles; respond by embedding accelerometer-equipped handles that log compliance data for institutional retention. For New Entrants and Emerging Players: Begin with bio-based handle certifications targeting EU Green Deal procurement mandates in German and French construction markets. White-space concentrates in lignin-reinforced and flax-fiber composite handles for institutional buyers seeking sustainability documentation. Direct-to-contractor digital platforms offer the most penetrable channel, bypassing industrial distributor gatekeeping in United States demolition corridors. For Investors and Strategic Acquirers: The window for entry favors legacy forges with captive metallurgical laboratories and seven-year impact-test record archives. Long-term viability hinges on regulatory compliance infrastructure rather than pure production scale. Watch ISO vibration-exposure limit tightening in European markets as the signal indicating accelerated replacement demand for anti-vibration grip systems.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Supply | Captive sourcing from Ohio and Pennsylvania mills buffers against multi-source metal volatility. |
| Certified Testing Protocol Investment | In-house metallurgical laboratories unlock ISO 15601 compliance for European trade channels. |
| Direct-to-Contractor Platform Launch | Digital disintermediation captures Texas and Florida demolition firms negotiating enterprise pricing. |
| Bio-Based Handle Certification Program | EU Green Deal alignment opens institutional procurement in German road-building markets. |
| Anti-Vibration Grip System Development | OSHA vibration-dose compliance creates replacement pull in California and New York construction. |
Research Methodology
Multi-period observation of replacement cycle frequency, alloy cost indices, and certification adoption rates anchored the trend analysis, supplemented by interviews with demolition fleet managers, forging plant engineers, industrial distributor procurement leads, and OSHA compliance officers. Secondary validation drew from customs trade databases, SEC tool-manufacturer filings, American Iron and Steel Institute production reports, and EU ECHA REACH substance registrations. Bottom-up volume modeling across product types and applications triangulated against top-down construction spending and infrastructure contract awards.
Input-output matrices mapped alloy steel input costs and forging capacity utilization against demolition contractor demand segments across the projection horizon. Segmentation dimensions modeled include head material grade, handle composition, application intensity, end-user scale tier, and regional regulatory cluster. CAGRs emerged from curve-fitting historical replacement patterns against projected infrastructure renewal contract flows. Industry-specific forecast inputs incorporated OSHA compliance timeline assumptions and EU Green Deal procurement mandate rollout pacing.
Underlying measurement precision varies by segment; steel sledgehammers and fiberglass variants carry tighter precision than wooden and rubber mallet categories given more standardized procurement documentation. Forecasts reflect assumptions about infrastructure spending continuity and regulatory enforcement intensity that could shift with administrative priorities. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Overload Protection Tools Market
Tools
Reamer Market
Tools
Fatigue Testing Machine Market
Tools
Rotary Knife Cutters Market
Tools
Automotive Torque Tools Market
Tools
Floor Saw Market
Tools
Welding Products Market
Tools
Bar Clamp Market
Tools
Asia Pacific Power Tools Market
Tools
Self-Clinching Fasteners Market
Tools
Hand and Power Tools Market
Tools
Quick Release Pins Market
Tools
Global Standard Parts for Tool Making Market
Tools
Deburring Tool Market
Tools
Automated Plasma Beveller Market
Tools
Indexable Inserts Market