
 Mechanical Springs Market | 2026-2036
Mechanical Springs Market Size, Share, and Industry Trends Forecast 2026-2036
Mechanical Springs Market Foresight
Digital thread integration across design-to-manufacturing workflows is fragmenting traditional spring sourcing models, as OEMs demand finite-element-validated fatigue data before qualification. Barnes Group Inc. leverages its aerospace pedigree to anchor premium compression spring contracts with jet engine programs. Lesjöfors AB sustains automotive volume through captive wire-forming capacity in Nordic mills. Schaeffler AG differentiates via integrated sensor-spring modules for chassis electrification.
Mechanical springs are elastic machine elements fabricated from wire or strip stock through coiling, heat treatment, and surface finishing operations, typically specified by spring rate, free length, and maximum solid height to store and release mechanical energy in assemblies requiring controlled deflection. Compression springs occupy the largest material throughput across industrial machinery and automotive platforms, where standardization sustains margin pressure. Stainless steel grades command premium positioning in aerospace and medical instrumentation due to corrosion-fatigue performance, while constant force springs represent the fastest-expanding type category driven by retractor mechanisms in consumer electronics and cable management systems.
The EPA enforces material composition limits on plated coatings through hazardous substance thresholds, while REACH mandates full substance disclosure for European-sourced alloys, effectively filtering non-compliant Asian suppliers from EU qualification lists. The FAA's fatigue-life documentation requirements for commercial aviation springs create a de facto barrier to entry for uncertified producers. Stakeholders must weigh backward integration into wire-drawing operations against the capital flexibility of specialist spring manufacturers as OEMs consolidate supplier bases.
Market Dynamics
Automotive electrification is compressing spring qualification timelines as OEMs demand finite-element-validated fatigue data before supplier onboarding, forcing wire-forming operations to integrate simulation capabilities upstream.
Growth Catalysts
- REACH substance disclosure mandates:Full material traceability requirements for European-sourced alloys filter non-compliant suppliers from EU qualification lists, consolidating volume among certified producers.
- Battery module precision assemblies:Electric vehicle platforms require calibrated spring rates in thermal management and cell retention systems, creating specification-intensive demand streams.
- Stuttgart-Tokyo-Detroit manufacturing clusters:Tier-one suppliers co-locating with OEM final assembly plants reduce logistics costs and enable just-in-time spring delivery.
Market Restraints
- Specialty alloy input volatility:Nickel and chromium price swings compress margins on stainless steel grades specified for aerospace and medical instrumentation.
- Wire-drawing capacity concentration:Captive Nordic and German mill supply limits independent spring manufacturers' backward integration options.
- Aviation fatigue-life documentation:FAA certification timelines for commercial aerospace springs extend 18-24 months, freezing out uncertified producers from premium contracts.
Strategic Opportunities
- India automotive component sourcing:PLI scheme incentives for advanced manufacturing equipment attract spring producers to Pune and Chennai industrial corridors.
- Sensor-spring module convergence:Chassis electrification programs integrate load-sensing coils with real-time telemetry for predictive maintenance.
- Constant force spring retractor mechanisms:Cable management systems in consumer electronics and medical devices expand application scope beyond traditional compression designs.
Industry Challenges
- Heat treatment technician scarcity:Specialized furnace operation and metallurgical process control skills face retirement-driven attrition in German and Japanese facilities.
- Multi-standard compliance layering:Simultaneous EPA hazardous substance thresholds, REACH disclosure rules, and FAA fatigue documentation create overlapping audit burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mechanical Springs Market |
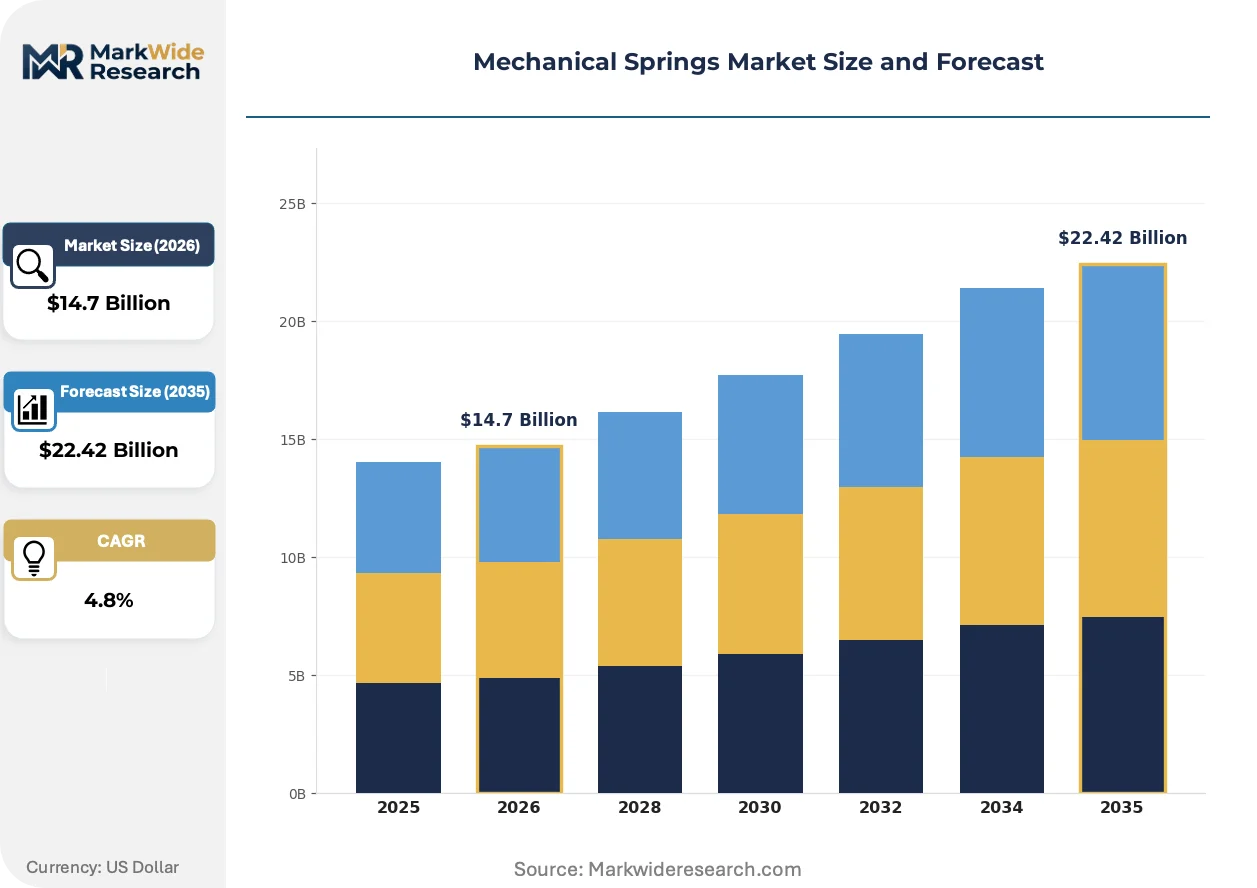
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Compression Springs, Extension Springs, Torsion Springs, Constant Force Springs Material: Steel Alloys, Stainless Steel, Plastic, Brass Application: Aerospace, Automotive, Industrial Machinery, Consumer Electronics End User: Manufacturers, OEMs, Maintenance Providers, Retailers |
| Companies Covered | Barnes Group Inc., MYD Metal, Lesjöfors AB, Thomson Industries Inc., Nabtesco Corporation, Schaeffler AG, Lee Spring Company Inc., Misumi Group Inc., Eaton Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mechanical Springs Market Shifts & Advancements
Digital thread integration is collapsing traditional design-to-manufacturing handoffs, with finite element analysis now embedded in supplier qualification rather than post-prototyping validation.
Generative design algorithms are digitizing spring topology optimization, enabling weight reduction in aerospace landing gear and suspension systems. Boeing and Airbus engineering teams now mandate topology-optimized spring submissions for new platform bids. This compression of iterative design cycles is digitizing the traditional prototype-test-certify sequence into simulation-first workflows.
REACH Annex XVII restrictions on hexavalent chromium plating are forcing conversion to trivalent alternatives or physical vapor deposition finishes across European automotive supply chains. Surface treatment facilities in Germany and Poland face capital-intensive retooling to maintain OEM qualification. The regulation's substance disclosure cascade is pushing tier-two wire suppliers to certify batch-level composition data.
Consolidated supplier base strategies are compressing approved vendor lists at major OEMs, with single-source spring contracts replacing dual-source arrangements. Procurement teams at Stellantis and Volkswagen now require finite-element validation packages before qualification sampling. This concentration is most visible in German automotive clusters, where tier-one integrators absorb spring manufacturing to secure capacity allocation.
Mechanical Springs Market Segmentation
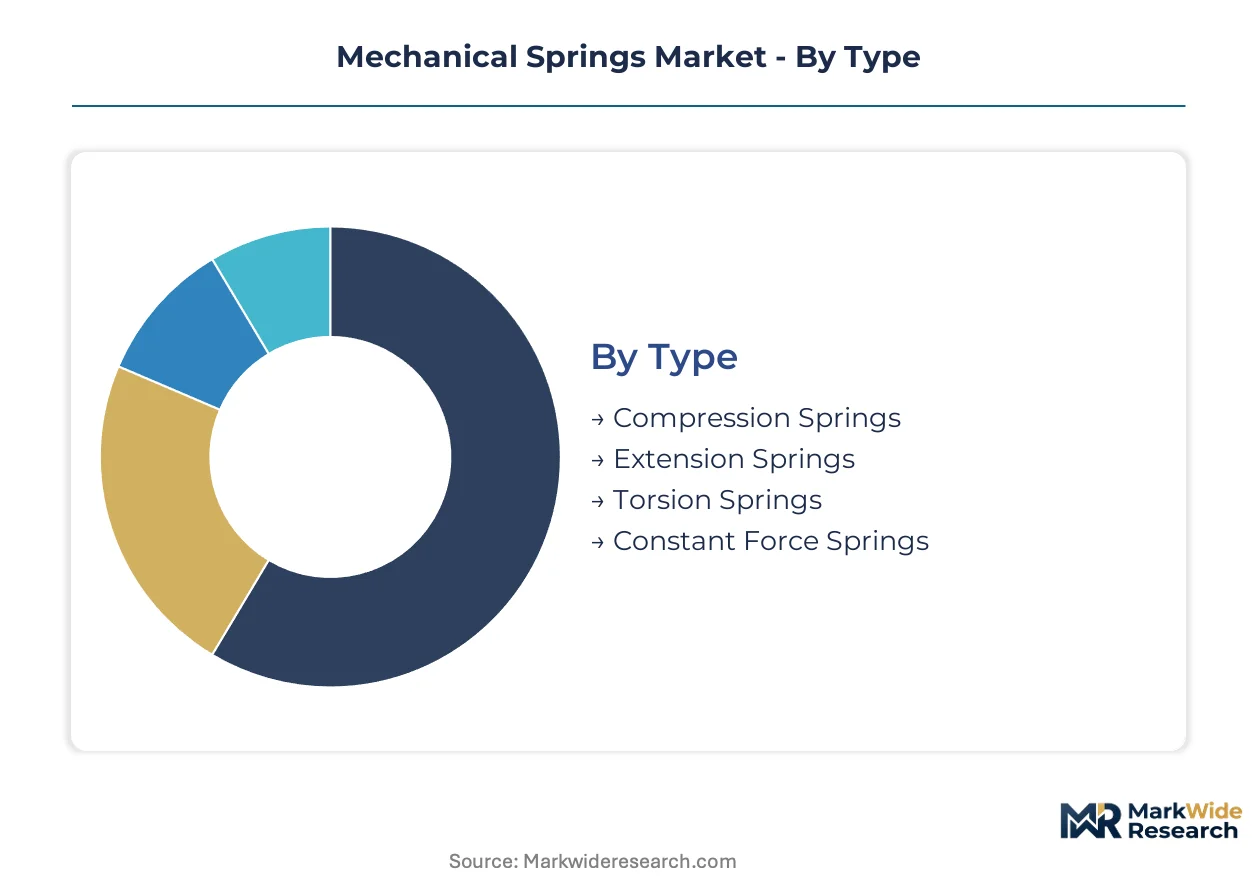
Mechanical springs serve divergent performance regimes across automotive suspension, aerospace landing gear, and consumer electronics retraction systems. Specification intensity varies by load cycle frequency, corrosion exposure, and dimensional tolerance requirements. Procurement patterns fragment accordingly, with OEMs demanding finite-element validation for safety-critical applications while industrial buyers prioritize volume pricing.
Type:
Application load profiles and motion requirements determine spring topology selection across end-use platforms.
- Compression Springs:Helical coils designed to resist axial compressive loads, specified by spring rate and solid height. Demand concentrates in automotive suspension systems and industrial machinery, where Stellantis and Volkswagen procurement teams mandate finite-element fatigue validation before supplier qualification.
- Constant Force Springs:Pre-stressed strip material coiled on a drum to deliver near-uniform torque across deflection range. Expansion accelerates in cable management systems for medical devices and consumer electronics, driven by miniaturization trends in laptop hinge mechanisms and surgical instrument retractors.
- Extension Springs:Coils with integral hooks or loops resisting tensile loads, common in garage door hardware and agricultural equipment. Farm machinery OEMs in Iowa and Nebraska specify powder-coated variants for corrosion resistance.
- Torsion Springs:Helical elements transmitting torque through angular deflection, prevalent in automotive seat recliners and industrial door counterbalance systems. Clipsal and Legrand specify these for electrical panel hardware.
Compression springs anchor established industrial and automotive volume. The steepest expansion trajectory runs through constant force configurations.
Material:
Corrosion-fatigue performance and magnetic permeability requirements stratify alloy selection across end-use tiers.
- Steel Alloys:Carbon and alloy grades dominate high-volume automotive and industrial applications where cost efficiency outweighs corrosion exposure. German and Japanese tier-one suppliers specify shot-peened variants for suspension components.
- Stainless Steel:Austenitic and precipitation-hardened grades command aerospace and medical instrumentation positioning due to corrosion-fatigue resistance. Boeing and Airbus engineering teams mandate these for landing gear and control surface applications.
- Plastic:Polymer formulations serve non-conductive, lightweight requirements in consumer electronics and MRI-compatible medical devices. Apple and Samsung suppliers specify these for internal component retention.
- Brass:Copper-zinc alloys provide electrical conductivity and spark resistance for hazardous environment switches and marine hardware. Oilfield equipment manufacturers in Texas specify these for explosion-proof instrumentation.
Steel alloys sustain the volume base. Stainless steel climbs fastest on electrification and aerospace specification intensity.
Application:
Certification burden and specification precision fragment demand across safety-critical and commodity tiers.
- Automotive:Battery module thermal management and cell retention systems require calibrated spring rates with tight tolerance bands. Electric vehicle platforms at Tesla and Rivian compress qualification timelines for precision spring assemblies.
- Aerospace:FAA fatigue-life documentation requirements create 18-24 month certification barriers for commercial aviation springs. Boeing and Airbus programs demand topology-optimized submissions with full traceability documentation.
- Industrial Machinery:Standardized compression and extension springs face margin pressure from catalog distributors. German machine tool builders specify DIN-compliant variants for press and automation equipment.
- Consumer Electronics:Miniaturization drives demand for micro-springs in hinge mechanisms, battery contacts, and cable retractors. Foxconn and Pegatron procurement teams prioritize surface-mount compatible geometries.
Automotive commands the revenue base. Aerospace delivers the steepest margin expansion on certification barriers.
End User:
Technical capability and volume scale determine sourcing relationships across the procurement spectrum.
- OEMs:Original equipment manufacturers consolidate approved vendor lists, demanding finite-element validation packages and co-located production capacity. Volkswagen and Stellantis now require single-source contracts with integrated sensor-spring modules.
- Manufacturers:Tier-two component builders source standard catalog springs for assembly integration. Pune and Chennai industrial corridors attract producers under India's PLI scheme incentives.
- Maintenance Providers:Aftermarket and MRO operations prioritize inventory availability over specification customization. Delta and United Airlines maintenance divisions stock FAA-certified springs at hub locations.
- Retailers:Distributors and hardware chains serve small-volume repair and DIY demand through catalog and e-commerce channels. Grainger and McMaster-Carr stock DIN and inch-series variants for next-day fulfillment.
OEMs anchor specification-intensive demand. The fastest volume expansion runs through manufacturers in emerging production corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEM procurement teams concentrate spring demand in manufacturing corridors adjacent to final assembly plants. Tier-one suppliers co-locate wire-forming capacity to enable just-in-time delivery and compress qualification timelines.
United States
Detroit-area OEMs compress supplier qualification timelines for electric vehicle battery module springs. FAA fatigue-life documentation requirements extend 18-24 months for commercial aviation contracts. Dallas-Fort Worth aerospace clusters anchor certified spring production for landing gear programs.
Germany
Stuttgart automotive clusters demand finite-element-validated fatigue data before supplier onboarding. REACH Annex XVII restrictions on hexavalent chromium plating force surface treatment retooling in Bavarian facilities. Dortmund-area mills supply captive wire-drawing capacity to independent spring manufacturers.
Japan
Nagoya automotive engineering centers specify shot-peened alloy variants for suspension components. METI industrial standards govern heat treatment process documentation for export certification. Osaka industrial corridors face technician scarcity in specialized furnace operations.
China
Shanghai EV battery producers require calibrated spring rates for thermal management systems. GB standards and MIIT regulations govern material composition disclosure for automotive supply chain entry. Shenzhen consumer electronics manufacturers drive constant force spring demand for cable retractors.
India
Pune and Chennai automotive corridors attract spring producers under PLI scheme incentives for advanced manufacturing equipment. BIS certification requirements filter non-compliant suppliers from domestic OEM qualification lists. Tamil Nadu industrial parks host expanding wire-forming operations serving component exporters.
Mechanical Springs Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented tier structures. Consolidation pressures mount as OEMs compress approved vendor lists from dual-source to single-source arrangements. Three archetypes dominate: aerospace-certified precision specialists, automotive volume integrators with captive wire capacity, and catalog distributors serving maintenance providers. M&A activity targets heat treatment capabilities and sensor-spring module integration.
Among established fabricators, Barnes Group Inc. and Lesjöfors AB exemplify divergent strategic positions. Barnes Group Inc. occupies a certification-intensive tier anchored by aerospace pedigree. Lesjöfors AB represents automotive volume integration through Nordic mill relationships. Schaeffler AG sits within the chassis electrification convergence space, positioning around sensor-spring module development.
| Leading Market Players |
|---|
| Barnes Group Inc. |
| MYD Metal |
| Lesjöfors AB |
| Thomson Industries Inc. |
| Nabtesco Corporation |
| Schaeffler AG |
| Lee Spring Company Inc. |
| Misumi Group Inc. |
| Eaton Corporation |
| Others |
Supply & Pricing Matrix
Nordic and German captive wire-drawing capacity concentrates upstream supply, anchoring margin pools with tier-one automotive integrators while independent spring manufacturers face compressed negotiating leverage on specialty alloy inputs.
Pricing Analysis
Cost-plus contracts with London Metal Exchange nickel and chromium indexation dominate stainless steel grade transactions for aerospace and medical instrumentation. Three-tier pricing structure across aerospace-certified, automotive-volume, and industrial-catalog levels separates Boeing-qualified suppliers from Stellantis dual-source arrangements and Grainger catalog distributors. Cost compression in industrial compression springs is intensifying because Chinese producers undercut DIN-compliant European equivalents on spot markets. Maintenance providers and tier-two manufacturers exhibit highest price sensitivity, while OEMs absorb premiums for finite-element-validated fatigue documentation.
Supply Chain Analysis
Specialty wire rod feeds from Swedish, German, and Japanese integrated mills tether downstream spring forming to captive upstream capacity. Nickel-chromium-molybdenum alloy dependencies draw from South African chromite and Indonesian nickel processing. Single-source vulnerability concentrates in heat treatment furnace operations facing technician attrition in Osaka and Dortmund industrial corridors. Distribution runs through tier-one integrator co-location with Stuttgart, Detroit, and Nagoya automotive clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive electrification capital expenditure cycles signal cyclical recovery, with battery module precision assembly demand cresting as EV platform launches accelerate through OEM engineering centers.
For Market Incumbents: Insulate aerospace certification tiers from margin erosion by deepening heat treatment technician apprenticeship pipelines in German and Japanese facilities. Acquire sensor-spring module capabilities before chassis electrification programs consolidate supplier lists at Volkswagen and Stellantis. Lock in long-term nickel alloy offtake with Nordic mills to hedge against specialty input volatility.
For New Entrants and Emerging Players: Build out wire-forming capacity in Pune and Chennai industrial corridors to capture PLI scheme incentives and serve component exporters to European automotive clusters. Target constant force spring retractor mechanisms for Foxconn and Pegatron cable management specifications. Pursue surface-mount compatible micro-spring geometries as the most penetrable entry point.
For Investors and Strategic Acquirers: Capital is best deployed toward aerospace-certified precision specialists with FAA fatigue-life documentation and Boeing-Airbus approved vendor status. Long-term viability over the next decade hinges on digital thread integration and generative design algorithm capabilities. Watch for topology-optimized spring submission mandates as the inflection indicator for simulation-first workflow adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wire Drawing | Captive Nordic mill supply secures alloy allocation for Stellantis and Volkswagen programs. |
| Sensor-Spring Module Development | Integrated load-sensing coils meet Schaeffler chassis electrification specifications. |
| Heat Treatment Technician Training | Osaka and Dortmund furnace operations face retirement-driven attrition without pipeline investment. |
| REACH-Compliant Surface Treatment Retooling | Trivalent chromium conversion maintains Bavarian facility OEM qualification under Annex XVII. |
| Constant Force Spring Capacity Expansion | Shenzhen consumer electronics manufacturers drive cable retractor demand for laptop hinge mechanisms. |
Research Methodology
Desk research of SEC 10-K filings, customs trade databases, and FAA certification records preceded structured interviews with OEM procurement directors, tier-one supplier engineering leads, heat treatment facility managers, and automotive platform engineers. Primary fieldwork across Stuttgart, Detroit, and Nagoya manufacturing clusters combined with secondary validation from IHS Markit vehicle production data and DIN standard documentation. Bottom-up spring volume estimates triangulated against top-down automotive and aerospace expenditure forecasts.
Assumptions held fixed include current REACH and EPA regulatory frameworks, nickel-chromium price correlation patterns, and OEM supplier consolidation trajectories. Segmentation modeling across spring type, material grade, application intensity, and end-user procurement tier generated volume and value outputs across the projection horizon. CAGRs derived from regression analysis of historical automotive production and electrification content-per-vehicle curves, with battery module precision assembly specifications and aerospace fatigue-life documentation requirements as key forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by catalog distributors or technology-driven disintermediation of finite-element validation workflows would shift outcomes. Cross-checking against IHS Markit automotive production forecasts and Boeing-Airbus order backlogs is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Global DC Torque Tool Market
Tools
Brushcutter Market
Tools
Masonry Cleaners Market
Tools
Ultra Hard Material Cutting Machines Market
Tools
Tile Saw Market
Tools
Mold Racks Market
Tools
Global Swaging Machine Market
Tools
Europe Machine Tools Market
Tools
Spindle Shaper Market
Tools
Level Floats Market
Tools
Technical Drawing Tools Market
Tools
Foldable Ladder Market
Tools
Bearing Installation Tool Kit Market
Tools
Land Survey Equipment Market
Tools
China Power Tools Market
Tools
Fixed Cutter Bits Market