
 Global Data Resiliency Market | 2026-2036
Global Data Resiliency Market Size, Share, and Industry Trends Forecast 2026-2036
Global Data Resiliency Market Foresight
GDPR enforcement is broadening the cost-of-entry calculus for data resiliency vendors serving European enterprises. IBM Corporation leverages its hybrid cloud architecture to sustain leadership in enterprise backup ecosystems. Dell Technologies Inc. anchors its position through integrated hardware-software recovery stacks. Veeam Software differentiates via software-native replication tools that compete aggressively in mid-market segments.
Data resiliency encompasses the architectural discipline of ensuring data availability, integrity, and recoverability through redundant storage systems, automated replication protocols, and sub-hour recovery point objectives across distributed infrastructure. Its primary commercial purpose is to eliminate operational downtime and regulatory penalties when primary systems fail or suffer compromise. Cloud-based deployment now leads solution delivery as enterprises abandon capital-intensive on-premises tape libraries, while disaster recovery represents the fastest-expanding solution offering due to ransomware frequency. Large enterprises command the deepest margin pools in customer type segmentation, though government agencies are accelerating procurement cycles.
FDA, HIPAA, and SEC frameworks in the United States impose strict data retention and auditability requirements that directly expand resiliency spending in healthcare and financial sectors. EMA and GDPR in Europe enforce cross-border data sovereignty rules that fragment infrastructure design and elevate regional vendor qualifications. Stakeholders must monitor how divergent national encryption standards reshape interoperability between sovereign cloud deployments and global backup orchestration platforms.
Market Dynamics
Ransomware frequency is compressing recovery point objectives from 24 hours toward 15 minutes, forcing enterprises to abandon tape-based backup architectures in favor of continuous data protection systems that replicate in real-time across distributed cloud nodes.
Growth Catalysts
- EU AI Act compliance mandates:Cross-border data handling rules under GDPR and the EU AI Act compel financial institutions to deploy sovereign backup infrastructure with jurisdictional data residency controls.
- Healthcare digitization:FDA 21 CFR Part 11 and HIPAA audit trail requirements drive hospital systems toward immutable storage with write-once-read-many compliance architectures.
- Japan METI operational continuity standards:Critical infrastructure operators in manufacturing and energy must maintain sub-hour recovery capabilities under revised business continuity frameworks.
Market Restraints
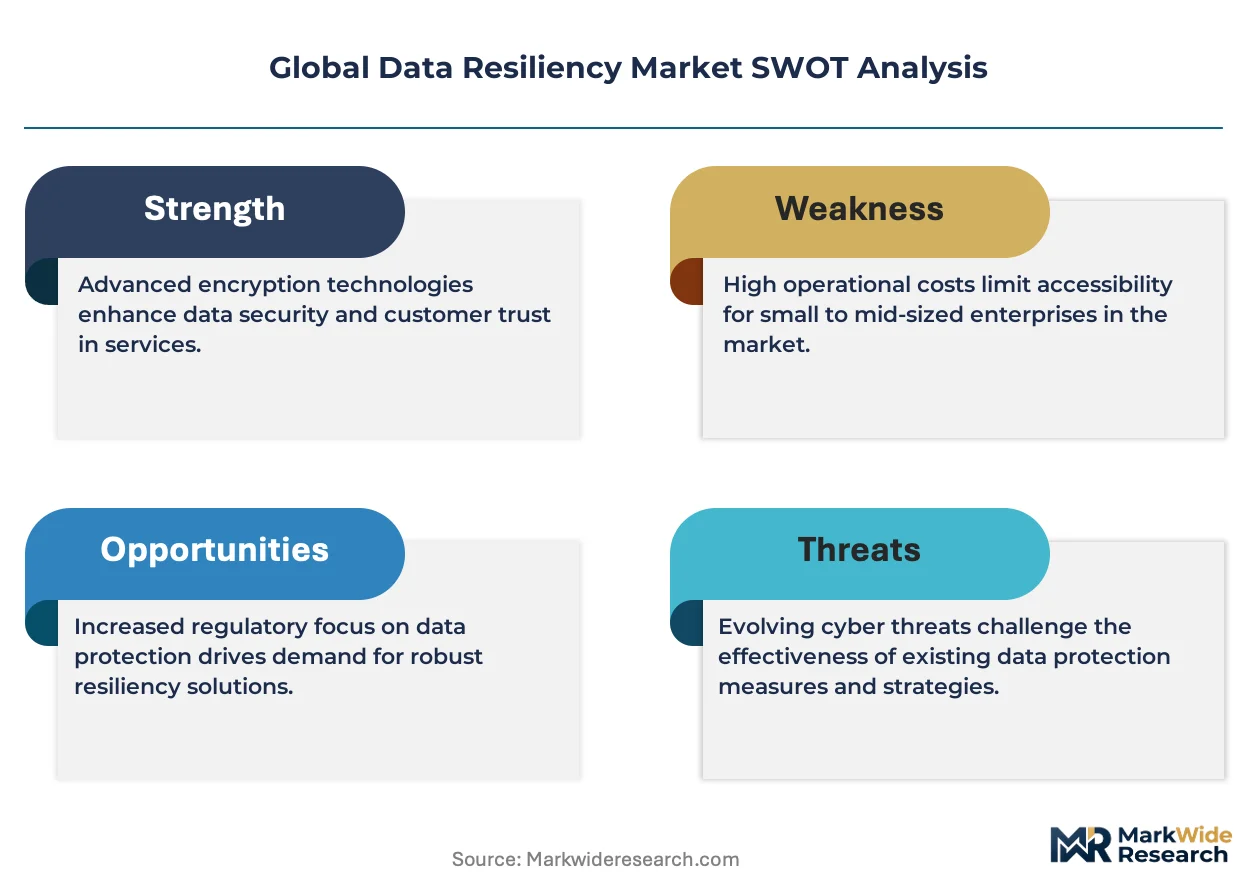
- Specialized engineering talent scarcity:Cloud-native disaster recovery architects command premium compensation, constraining mid-market enterprise deployment velocity.
- Encryption standard fragmentation:Divergent national cryptographic protocols between US FIPS 140-3, EU GDPR sovereign requirements, and China's GB/T standards complicate global backup orchestration.
- Legacy storage asset stranding:Enterprises with substantial on-premises tape library investments face sunk-cost resistance when migrating to cloud-native replication.
Strategic Opportunities
- India's data localization mandate:RBI and CERT-In requirements for financial data domestic storage create demand for indigenous backup infrastructure providers with sovereign cloud partnerships.
- Edge computing convergence:Integration of 5G network slicing with containerized backup agents enables real-time protection for industrial IoT deployments in manufacturing and logistics.
- CSRD sustainability disclosure:EU corporate sustainability reporting requirements elevate energy-efficient backup storage as a procurement criterion, favoring vendors with carbon-neutral data center certifications.
Industry Challenges
- Immutable storage certification complexity:SEC 17a-4(f) and FINRA compliance for financial record immutability requires vendor-specific engineering validation that extends sales cycles.
- Multi-cloud orchestration integration:Enterprises operating across AWS, Azure, and Google Cloud environments face API heterogeneity that complicates unified recovery orchestration.
- Forensic recovery expertise gaps:Post-ransomware restoration without ransom payment demands specialized incident response capabilities that outstrip current service provider capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Data Resiliency Market |
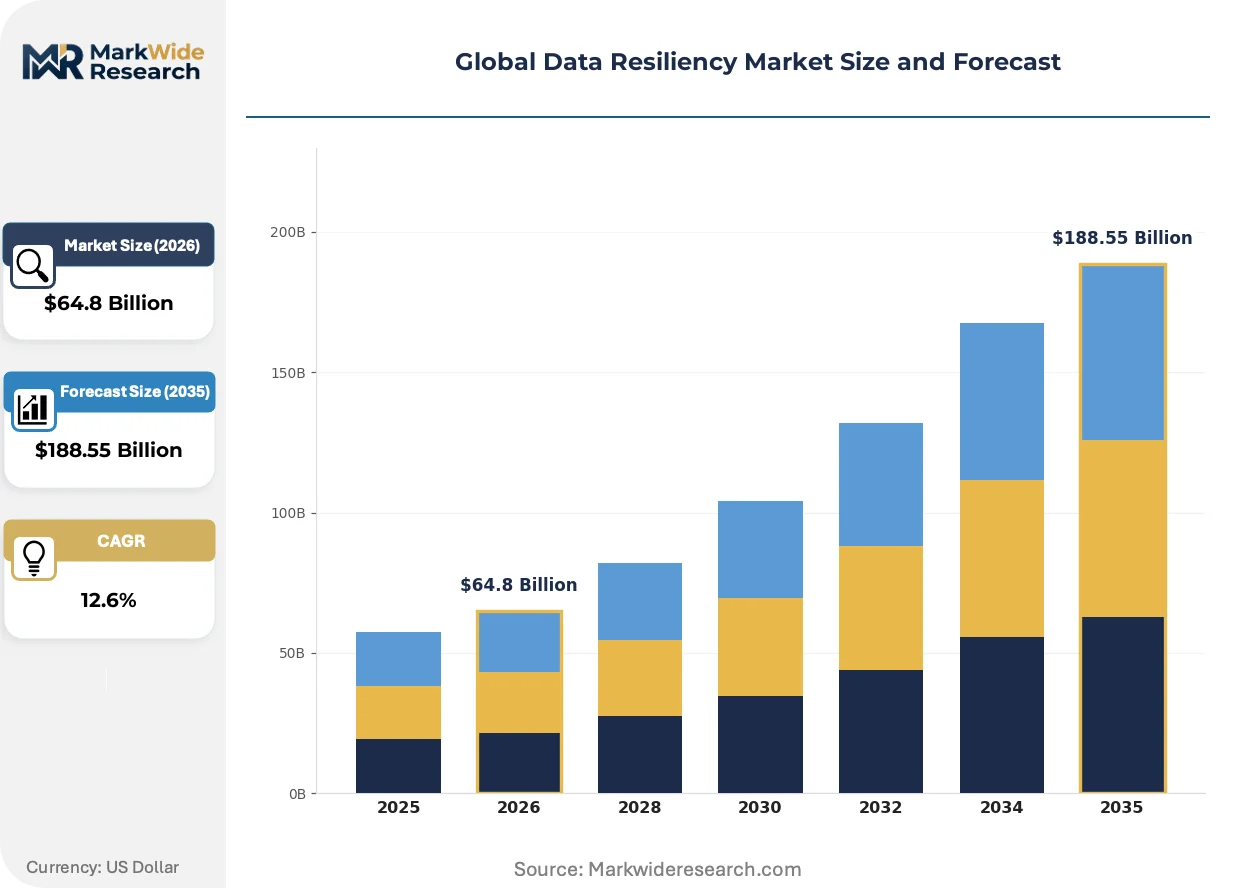
| Market Size in 2026 | $64.8 Billion |
| Market Size in 2035 | $188.55 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing Solution Offering: Backup & Recovery, Replication, Archiving, Disaster Recovery Use Case: Business Continuity, Compliance Management, Data Integrity, System Optimization Customer Type: Large Enterprises, SMBs, Government Agencies, Educational Institutions |
| Companies Covered | IBM Corporation, Microsoft Corporation, Dell Technologies Inc., NetApp Inc., Commvault Systems Inc., VMware Inc., Acronis International GmbH, Veeam Software, Open Text Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Data Resiliency Market Shifts & Advancements
Immutable object storage architectures are displacing traditional backup software layers as the foundational data protection paradigm, compressing vendor value capture toward hardware-native capabilities and away from licensed agent-based solutions.
Continuous data protection with block-level replication is expanding into mid-market manufacturing and professional services segments previously served by nightly backup windows. These organizations now demand recovery point objectives measured in minutes rather than hours, compressing acceptable data loss windows by an order of magnitude. The technology is expanding into sectors that historically prioritized cost over availability, reshaping vendor targeting strategies toward price-sensitive buyers.
GDPR Article 44-49 cross-border transfer restrictions are fragmenting global backup architectures into region-locked data sovereignty zones. European enterprises must now maintain physically separated replication targets with cryptographic controls that prevent unauthorized jurisdictional access. Healthcare and financial services verticals in Germany, France, and the Netherlands are responding by procuring EU-only backup infrastructure with local encryption key custody.
Consumption-based pricing for disaster recovery infrastructure is displacing perpetual licensing models across enterprise procurement functions. Buyers now prefer metered recovery capacity with burst provisions for ransomware events rather than fixed-capacity contracts. This shift is most visible in United States financial services and German automotive supply chains, where CFOs demand operational expenditure treatment for business continuity spending.
Global Data Resiliency Market Segmentation
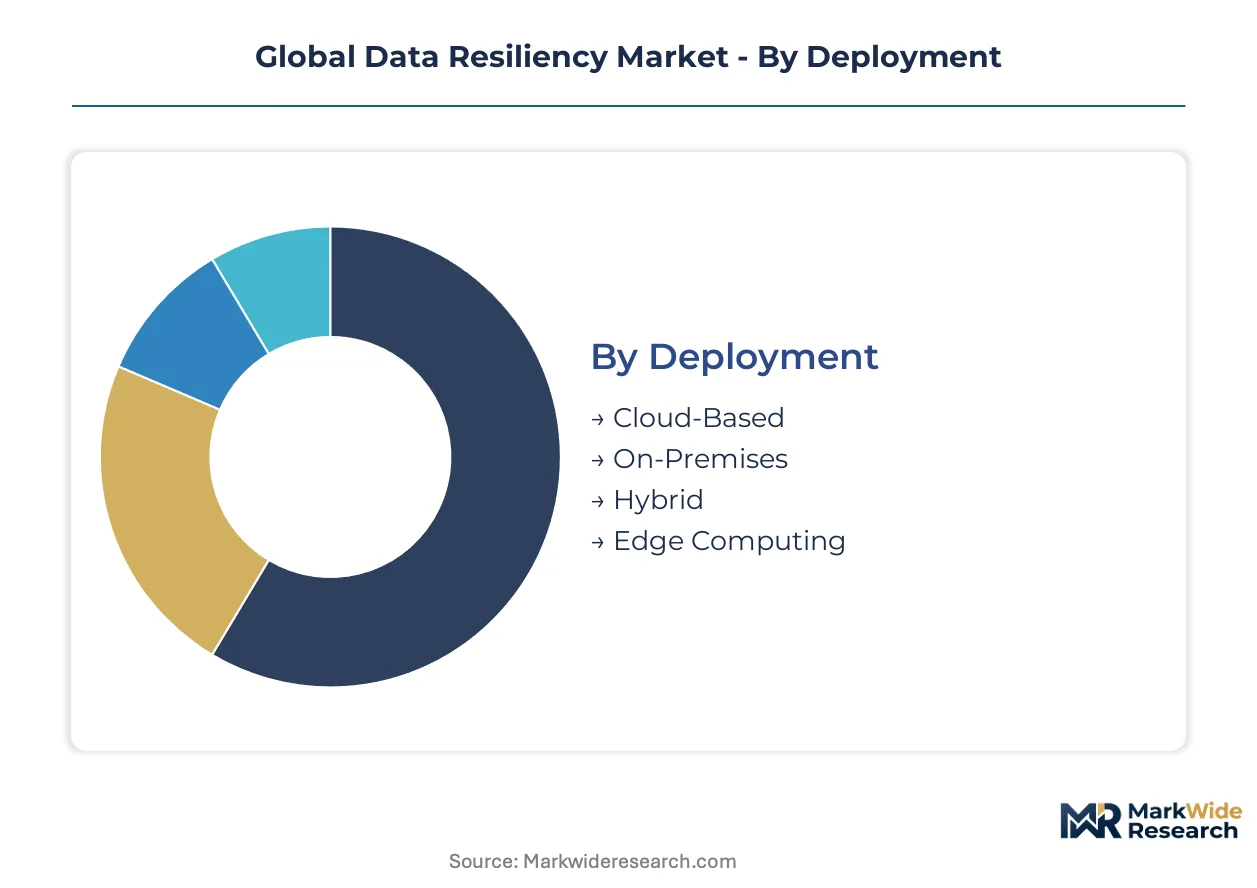
Data resiliency procurement patterns diverge sharply across deployment architectures and organizational scale. Vendor pricing power and margin structure vary significantly by segment, requiring differentiated go-to-market positioning.
Deployment:
Supply concentration in hyperscale cloud infrastructure is redistributing value capture from hardware vendors to platform operators.
- Cloud-Based:Multi-tenant infrastructure with consumption-based metering eliminates capital expenditure for storage arrays. Financial services institutions in the United States and Germany dominate procurement as GDPR and SEC 17a-4(f) mandates accelerate abandonment of self-managed tape libraries.
- Hybrid:Orchestration layers spanning on-premises and public cloud environments enable workload portability while maintaining data sovereignty controls. Japanese manufacturing conglomerates under METI operational continuity standards are expanding hybrid deployments to balance latency requirements with geographic redundancy.
- On-Premises:Dedicated storage area networks retain relevance in classified government environments with air-gapped security requirements.
- Edge Computing:Containerized backup agents deployed on 5G network infrastructure protect industrial IoT data streams at manufacturing facilities.
Cloud-Based absorbs the bulk of installed capacity; Edge Computing is expanding most quickly.
Solution Offering:
Customer willingness-to-pay escalates with recovery speed requirements, creating tiered margin pools across solution types.
- Disaster Recovery:Automated failover orchestration with sub-15-minute recovery point objectives commands premium pricing in ransomware-exposed sectors. Healthcare systems under FDA 21 CFR Part 11 and HIPAA audit trail mandates in the United States are prioritizing immutable disaster recovery architectures.
- Backup & Recovery:Scheduled snapshot replication with granular file-level restoration serves cost-sensitive mid-market buyers. German automotive supply chains favor consumption-based backup pricing to align operational expenditure with production volatility.
- Replication:Synchronous block-level copying between geographically separated sites ensures zero data loss for transaction-intensive workloads.
- Archiving:Write-once-read-many storage for long-term regulatory retention with reduced retrieval performance requirements.
Backup & Recovery retains the largest installed base; Disaster Recovery is climbing the fastest.
Use Case:
Compliance-driven procurement generates higher margins than availability-focused buying, reshaping vendor sales targeting.
- Compliance Management:Immutable storage with cryptographic proof of integrity satisfies GDPR Article 44-49 cross-border transfer restrictions and SEC audit trail requirements. European financial institutions in France, Germany, and the Netherlands are procuring EU-only backup infrastructure with local encryption key custody.
- Business Continuity:Operational resilience frameworks under Japan METI standards and India RBI data localization mandates drive manufacturing and banking investment. Critical infrastructure operators must maintain sub-hour recovery capabilities under revised continuity frameworks.
- Data Integrity:Hash-verified storage ensuring tamper-evident records for forensic and legal discovery purposes.
- System Optimization:Storage tiering and deduplication reducing redundant data footprint across primary and secondary systems.
Business Continuity commands the deepest deployment penetration; Compliance Management is gaining share fastest.
Customer Type:
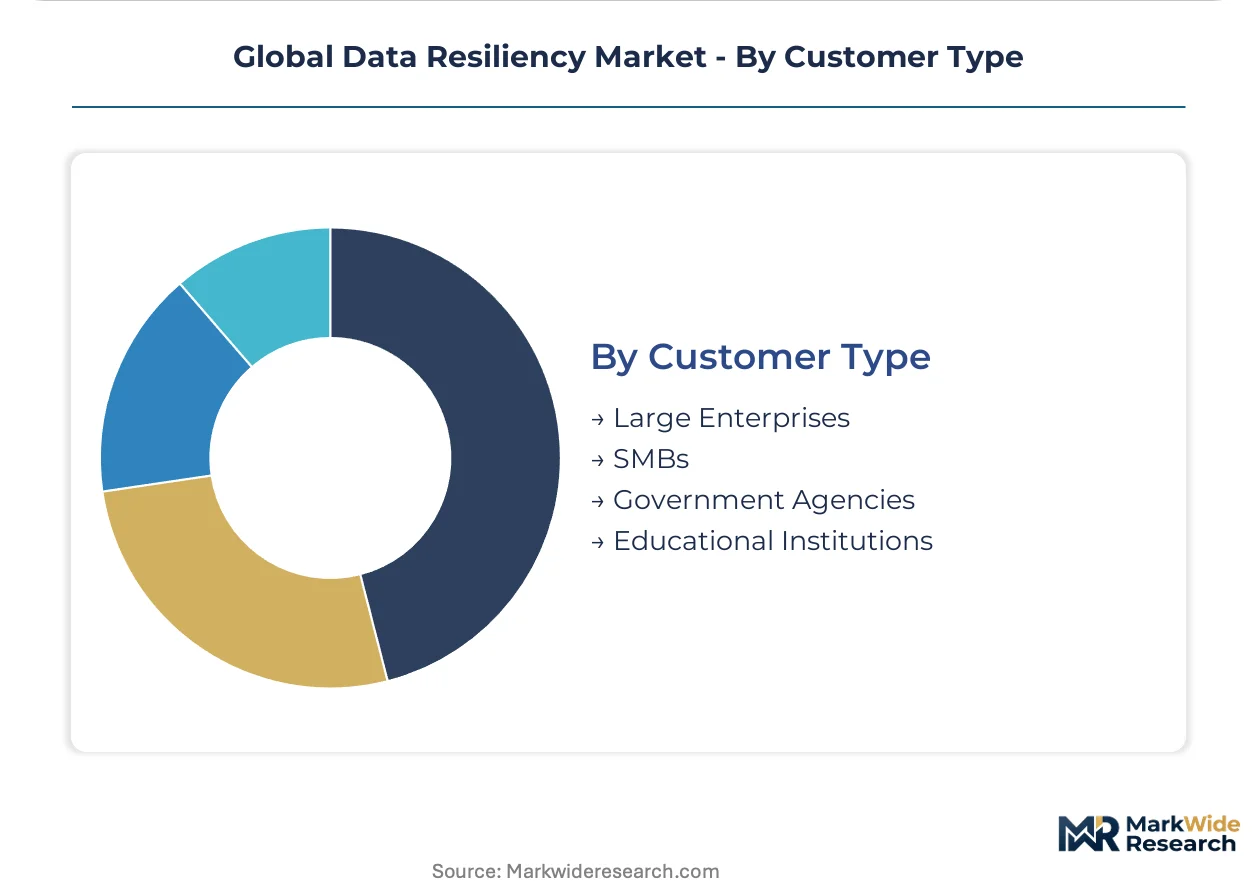
Procurement complexity and contract value scale non-linearly with organizational size, fragmenting vendor sales motions.
- Large Enterprises:Multi-year framework agreements with dedicated account engineering support and custom service level agreements. United States healthcare systems and German automotive manufacturers negotiate sovereign cloud partnerships with jurisdictional data residency controls.
- Government Agencies:Accelerating procurement cycles for classified and critical infrastructure protection under national cybersecurity directives. India's CERT-In requirements for financial data domestic storage are expanding public sector backup infrastructure investment.
- SMBs:Standardized subscription packages with self-service portals and limited professional services engagement.
- Educational Institutions:Grant-funded research data protection with emphasis on long-term digital preservation and open science repository integration.
Large Enterprises capture the greatest vendor attention; Government Agencies are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Shenzhen and Shanghai concentrate data center investment incentives that reshape backup infrastructure deployment patterns across Asia-Pacific. These zones accelerate sovereign cloud partnerships for financial institutions navigating cross-border compliance mandates.
United States
Healthcare systems under FDA 21 CFR Part 11 and SEC 17a-4(f) mandates drive immutable storage procurement in Boston and New York financial corridors. HIPAA audit trail requirements compress recovery point objectives toward sub-15-minute targets. Silicon Valley hyperscale operators anchor cloud-native disaster recovery capacity expansion.
Germany
Automotive supply chains in Baden-Württemberg favor consumption-based backup pricing to align operational expenditure with production volatility. GDPR Article 44-49 cross-border transfer restrictions fragment replication architectures into EU-only sovereignty zones. Frankfurt's financial district concentrates sovereign cloud partnerships with local encryption key custody.
Japan
Manufacturing conglomerates under METI operational continuity standards expand hybrid deployments to balance latency requirements with geographic redundancy. Kanto region critical infrastructure operators must maintain sub-hour recovery capabilities under revised business continuity frameworks. Osaka's industrial IoT deployments drive edge computing backup agent integration.
India
RBI and CERT-In data localization mandates for financial data domestic storage expand indigenous backup infrastructure investment. Mumbai and Bangalore technology corridors witness accelerating sovereign cloud partnerships with indigenous providers. Maharashtra's manufacturing sector adopts containerized backup agents for 5G-enabled industrial IoT protection.
Global Data Resiliency Market Competitive Landscape
United States producers anchor one tier; European specialists hold differentiated positions in sovereign compliance segments. The vendor base stratifies across hyperscale cloud operators, integrated hardware-software stack providers, and software-native replication specialists. Three archetypes dominate: platform operators capturing consumption-based revenue, legacy infrastructure vendors defending installed base relationships, and agile software vendors attacking mid-market price points. M&A activity concentrates on cloud-native replication capabilities, while strategic partnerships proliferate around sovereign cloud certification.
Within the integrated infrastructure tier, Dell Technologies Inc. and IBM Corporation occupy positions exemplifying hardware-software recovery stack consolidation. Veeam Software sits within the software-native archetype, representing aggressive mid-market replication tool competition. These three entities collectively illustrate the competitive tension between capital-intensive platform control and agile software disruption that defines vendor rivalry dynamics.
| Leading Market Players |
|---|
| IBM Corporation |
| Microsoft Corporation |
| Dell Technologies Inc. |
| NetApp Inc. |
| Commvault Systems Inc. |
| VMware Inc. |
| Acronis International GmbH |
| Veeam Software |
| Open Text Corporation |
| Others |
Supply & Pricing Matrix
EU CSRD carbon-neutral data center certification gates qualified supply for premium-tier disaster recovery infrastructure, restricting vendor participation to operators with verified renewable energy procurement and elevating pricing access for certified providers serving financial services institutions in Frankfurt and Amsterdam.
Pricing Analysis
Lead-time-driven pricing stratification rewards rapid deployment capacity with premium positioning, while spot inventory of legacy tape-based systems trades at distressed levels. Consumption-based SaaS metering dominates cloud-native segments, with price differentiation anchored in GDPR sovereign compliance certification and sub-15-minute recovery point objective guarantees. Pricing pressure stems from hyperscale cloud operators absorbing infrastructure margins into platform economics. Mid-market manufacturing buyers in Germany exhibit acute price sensitivity, whereas United States healthcare systems under FDA mandates prioritize immutable storage integrity over cost optimization.
Supply Chain Analysis
Certification gating through FIPS 140-3, GDPR sovereign encryption, and Japan JIS standards fragments qualified component sourcing across United States, Germany, and Japan manufacturing bases. Supply draws from specialized semiconductor fabrication for encryption accelerators, rare earth elements for high-density storage media, and precision cooling systems for hyperscale facilities. Single-source vulnerability concentrates in Taiwanese chip foundries producing data processing units. Distribution runs through direct enterprise sales forces for large contracts, supplemented by cloud marketplace integrations for consumption-based procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market constitutes a vertical-integration race where control over sovereign cloud infrastructure and encryption key custody systems determines margin capture. Players are pursuing backward integration into carbon-certified data center real estate to defend pricing power.
For Market Incumbents: Anticipate displacement from software-native replication vendors by accelerating sovereign cloud certification investments in EU and India markets. Consolidate position through captive supply of immutable storage hardware to escape hyperscale platform commoditization. Prioritize METI compliance engineering for Japanese manufacturing conglomerates as defensive moat. For New Entrants and Emerging Players: India's RBI data localization mandate opens a window for indigenous backup infrastructure partnerships with Mumbai and Bangalore technology corridors. Target containerized edge computing agents for 5G-enabled industrial IoT deployments in Maharashtra manufacturing zones. Pursue consumption-based pricing models to bypass incumbent enterprise sales force advantages. For Investors and Strategic Acquirers: Accelerating government procurement cycles for classified infrastructure protection is the leading indicator that sovereign compliance capabilities will command acquisition premiums. Long-term viability centers on vendors with demonstrated EU AI Act and GDPR Article 44-49 engineering validation. Monitor CERT-In certification timelines as inflection signal for India market entry viability.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | GDPR Article 44-49 compliance unlocks EU financial services procurement in Frankfurt and Amsterdam corridors. |
| Immutable Storage Hardware Integration | Vertical control over write-once-read-many architectures defends margin against software-only competitors. |
| Edge Computing Agent Development | Containerized 5G backup solutions capture METI-mandated sub-hour recovery in Osaka industrial zones. |
| Carbon-Neutral Data Center Buildout | CSRD disclosure requirements elevate certified facilities in German automotive supply chain selection. |
| Multi-Cloud Orchestration Platform | Unified AWS-Azure-Google Cloud recovery APIs address API heterogeneity friction in United States enterprises. |
Research Methodology
Multi-period observation of ransomware incident frequency, sovereign cloud certification timelines, and hyperscale capex disclosures anchored the trend analysis, supplemented by interviews with chief information security officers, cloud infrastructure procurement leads, disaster recovery architects, and regulatory compliance officers at financial services and healthcare institutions. Secondary validation drew from SEC 10-K infrastructure spending disclosures, EU AI Act implementation guidance, RBI circulars on data localization, and METI operational continuity framework updates. Bottom-up segmentation modeling triangulated against top-down macroeconomic scenario analysis.
Input-output matrix framing connected deployment architecture adoption rates to solution offering penetration across customer type segments over the projection horizon. Segmentation dimensions modeled encompass cloud-hybrid-on-premises-edge deployment modes, disaster recovery-backup-replication-archiving solution tiers, and compliance-driven versus availability-driven procurement motivations. CAGRs were derived from elasticity-adjusted technology substitution curves and regulatory mandate implementation schedules. Forecast inputs included ransomware recovery point objective compression trajectories and sovereign data residency requirement expansion patterns.
The model assumes a particular technology adoption path favoring cloud-native continuous data protection; alternative pathways favoring air-gapped on-premises retention for classified environments would alter the outlook. Forecasts reflect assumptions regarding regulatory enforcement intensity and hyperscale pricing discipline. A model refresh is warranted upon material change in EU AI Act cross-border transfer rulings or India CERT-In certification timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disaster Recovery Solutions
Disaster Preparedness Systems Market
Disaster Recovery Solutions
Flood Protection Sandbags Market
Disaster Recovery Solutions
France Ransomware Protection Market
Disaster Recovery Solutions
Global Security Solutions Market
Disaster Recovery Solutions
Rope Rescue Harness Market
Disaster Recovery Solutions
Global Data Protection and Recovery Solutions Market
Disaster Recovery Solutions
Incident Response System Market
Disaster Recovery Solutions
Spain Ransomware Protection Market
Disaster Recovery Solutions
Business Continuity Management Solutions Market
Disaster Recovery Solutions
Business Continuity Management Planning Solution Market
Disaster Recovery Solutions
Global Incident Response Market
Disaster Recovery Solutions
Intelligent Emergency Response Systems and Infrastructure (IRIS) Market
Disaster Recovery Solutions
Incident and Deviation Management Solution Market
Disaster Recovery Solutions
Latin America Incident Response Services Market
Disaster Recovery Solutions
Global Disaster Recovery Software Market
Disaster Recovery Solutions
Italy Ransomware Protection Market