
 Biomethane Certificate Trading Platform Market | 2026-2036
Biomethane Certificate Trading Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Biomethane Certificate Trading Platform Market Insights
The capital-intensity gap between blockchain-native entrants and legacy registry operators is collapsing as cloud infrastructure costs fall and API standards mature. STX Group leverages its Amsterdam-based trading infrastructure to anchor European certificate liquidity pools. CEGH competes through its Central European Gas Hub connectivity, while Ecohz specializes in Nordic corporate buyer aggregation.
Biomethane certificate trading platforms are digital marketplaces that verify, register, and transfer proof-of-origin claims for upgraded biogas injected into gas grids, typically recording megawatt-hour equivalents, injection dates, and sustainability criteria per certificate. Their primary commercial purpose is to separate the environmental attribute from the physical commodity, enabling corporate buyers to claim emissions reductions without direct gas offtake. Blockchain-based platform types are attracting development capital due to immutable audit trails, though cloud-hosted deployments currently occupy the largest installed base because of lower implementation friction. Corporate sustainability applications represent the fastest-expanding segment as Scope 3 reporting obligations intensify, while regulatory compliance applications sustain the steadiest revenue streams through mandated utility procurement quotas.
The EU Green Deal and RED III directive shape demand by mandating renewable gas targets and certificate-of-origin tracking, while EMA and national regulators enforce verification standards that determine platform eligibility. Germany's Federal Network Agency and the Dutch Emissions Authority both require registry interoperability, forcing technology providers toward common data exchange protocols. Stakeholders must monitor whether emerging national biomethane registries adopt mutual recognition frameworks or fragment into non-interoperable systems that would multiply compliance costs.
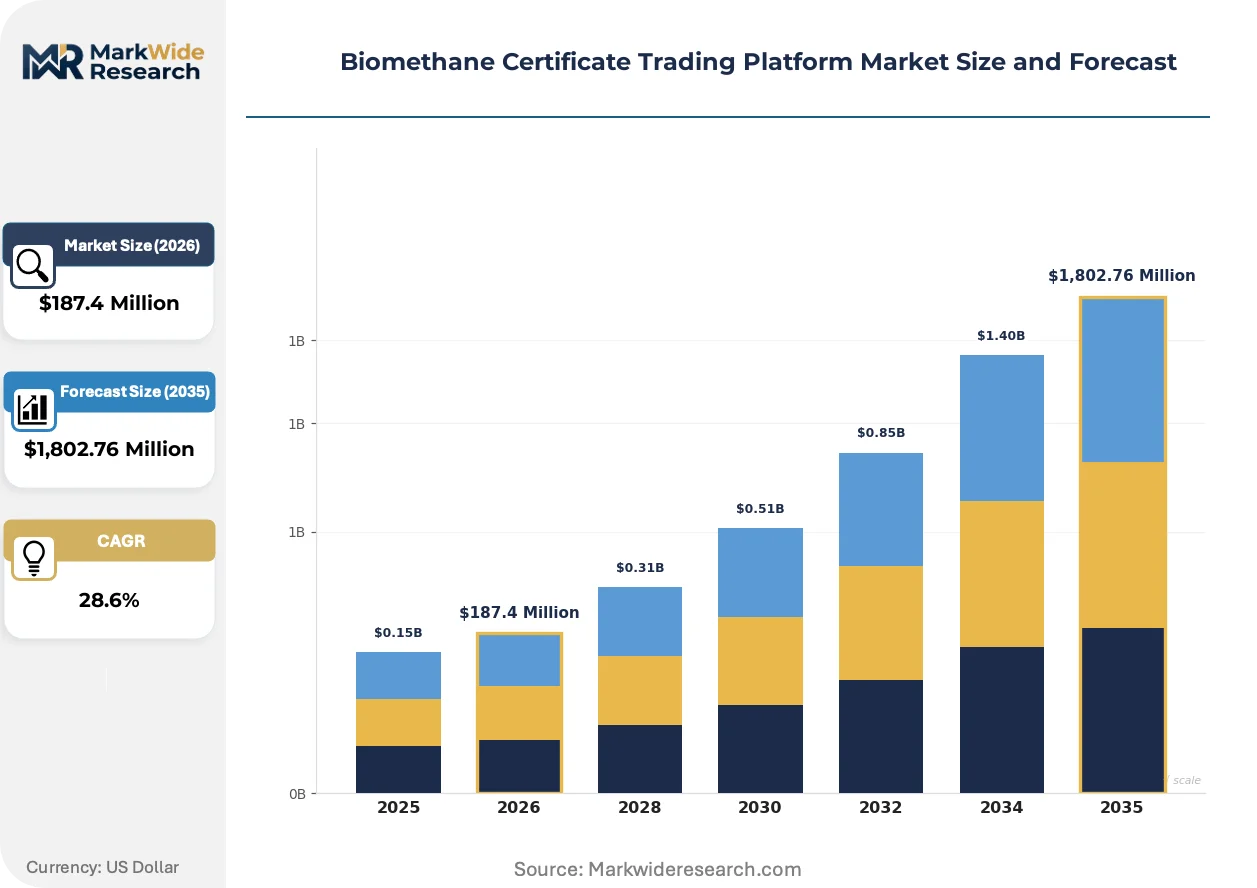
Market Dynamics
The EU F-Gas Regulation and RED III directive are compressing verification timelines, forcing registry operators toward real-time data exchange protocols that collapse the latency between biomethane injection and certificate issuance.
Growth Catalysts
- Corporate Scope 3 mandates:CDP and SBTi reporting frameworks are compelling industrial gas consumers to document supply-chain emissions reductions through verifiable certificate purchases rather than offset claims.
- RED III renewable gas targets:The directive's sub-targets for advanced biofuels and renewable fuels of non-biological origin create binding demand floors that utilities must meet via certificate-stacked procurement.
- Blockchain audit infrastructure:Distributed ledger implementations are displacing paper-based chain-of-custody documentation, slashing verification costs for cross-border certificate transfers.
Market Restraints
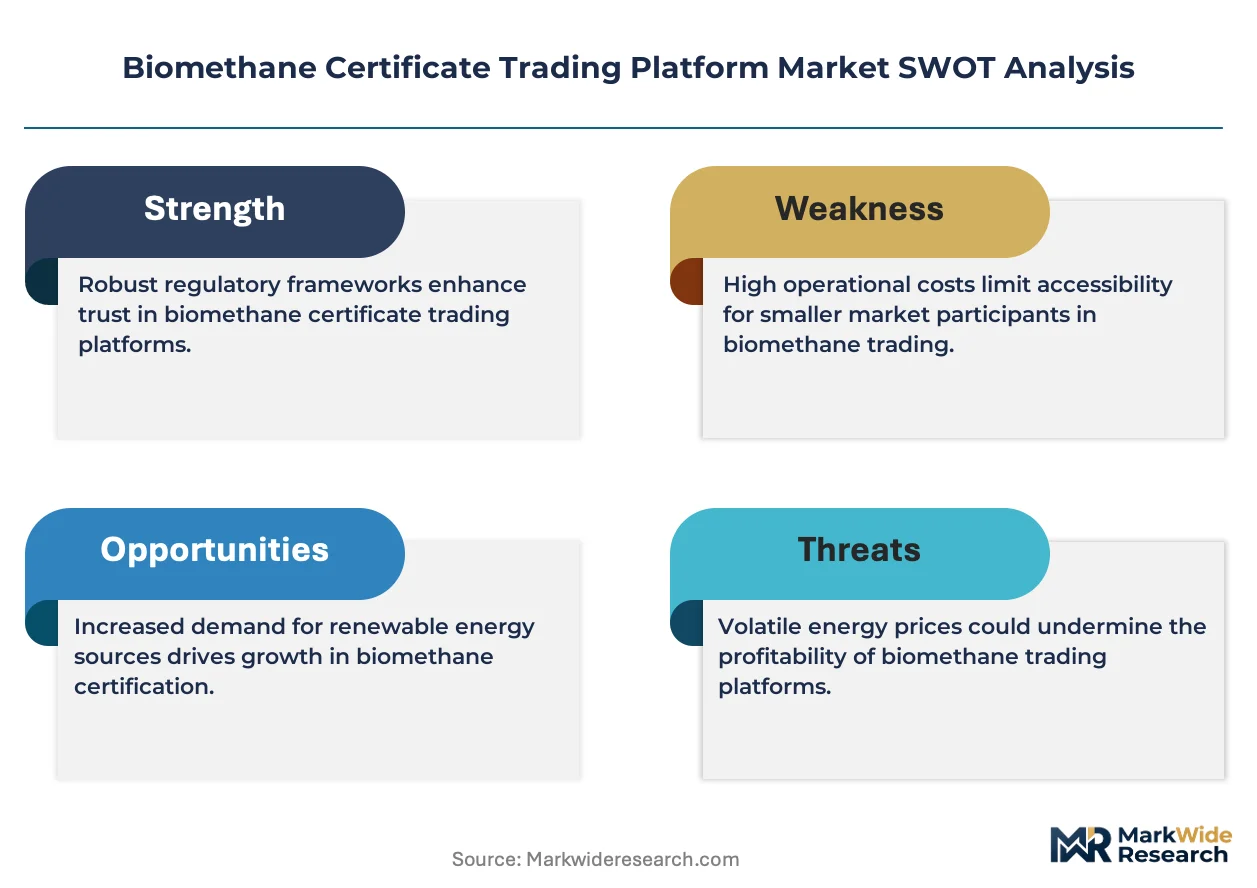
- Registry fragmentation risk:Germany's Federal Network Agency and the Dutch Emissions Authority operate non-interoperable national databases, multiplying compliance costs for pan-European traders.
- Biomethane feedstock competition:Agricultural residue diversion toward biofuels and biochemicals is tightening substrate availability for anaerobic digestion plants in Denmark and the Netherlands.
- Verification lag:Physical gas chromatography testing for certificate issuance creates 14-30 day delays that prevent real-time spot market trading.
Strategic Opportunities
- Industrial heat decarbonization:German cement and steel producers are piloting certificate-stacked renewable gas procurement to replace grey hydrogen in high-temperature processes.
- Cross-registry API standardization:The Association of Issuing Bodies is developing harmonized data exchange protocols that would unlock liquidity pooling across national registries.
- Power-to-gas convergence:Electrolytic hydrogen blending with biogenic CO2 capture is creating synthetic methane certificates that command premium pricing in corporate sustainability programs.
Industry Challenges
- Legacy ERP integration:Utility back-office systems require bespoke middleware development to ingest certificate registry data streams, extending implementation timelines.
- Mass-balance accounting complexity:Commingled pipeline gas flows complicate physical traceability claims, exposing buyers to greenwashing litigation risk under the EU Green Claims Directive.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biomethane Certificate Trading Platform Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,802.76 Million |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Blockchain-Based, Cloud-Hosted, On-Premises, Hybrid Application: Renewable Energy Trading, Carbon Offset Management, Regulatory Compliance, Corporate Sustainability End User: Energy Suppliers, Environmental Consultants, Certification Bodies, Corporate Buyers Service Model: Software as a Service, Subscription-Based, Pay-Per-Transaction, Enterprise License |
| Companies Covered | STX Group, CEGH, AFS Energy, Ecohz, Landwärme, Agriportance, ERGaR, Eurogas, S&P Global Commodity Insights, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biomethane Certificate Trading Platform Market Trends and Innovations
Immutable ledger architectures are compressing settlement cycles while regulatory pressure on Scope 3 disclosures intensifies buyer-side platform engagement. Three developments are restructuring competitive positioning.
Smart contract automation is displacing manual certificate transfer reconciliation. These self-executing protocols validate injection data against registry records before triggering payment release. Corporate sustainability teams at energy-intensive manufacturers are adopting this infrastructure to compress procurement cycle times. The structural consequence is collapsing margin capture for traditional brokerage intermediaries that previously intermediated price discovery.
The EU Green Deal's delegated acts on renewable gas are tightening sustainability criteria definitions. Industrial consequence includes mandatory verification of feedstock origin and land-use change impacts for certificate eligibility. German biomethane producers are responding by investing in satellite-based supply-chain monitoring to document compliance with the delegated act's no-deforestation thresholds.
Certificate unbundling from physical offtake contracts is fragmenting buyer profiles. Small and mid-cap enterprises without direct grid connections are purchasing certificates through retail aggregators to meet supply-chain decarbonization requirements. This pattern is most visible in the Netherlands, where corporate renewable gas procurement has decoupled from industrial park pipeline access.
Biomethane Certificate Trading Platform Market Segmentation
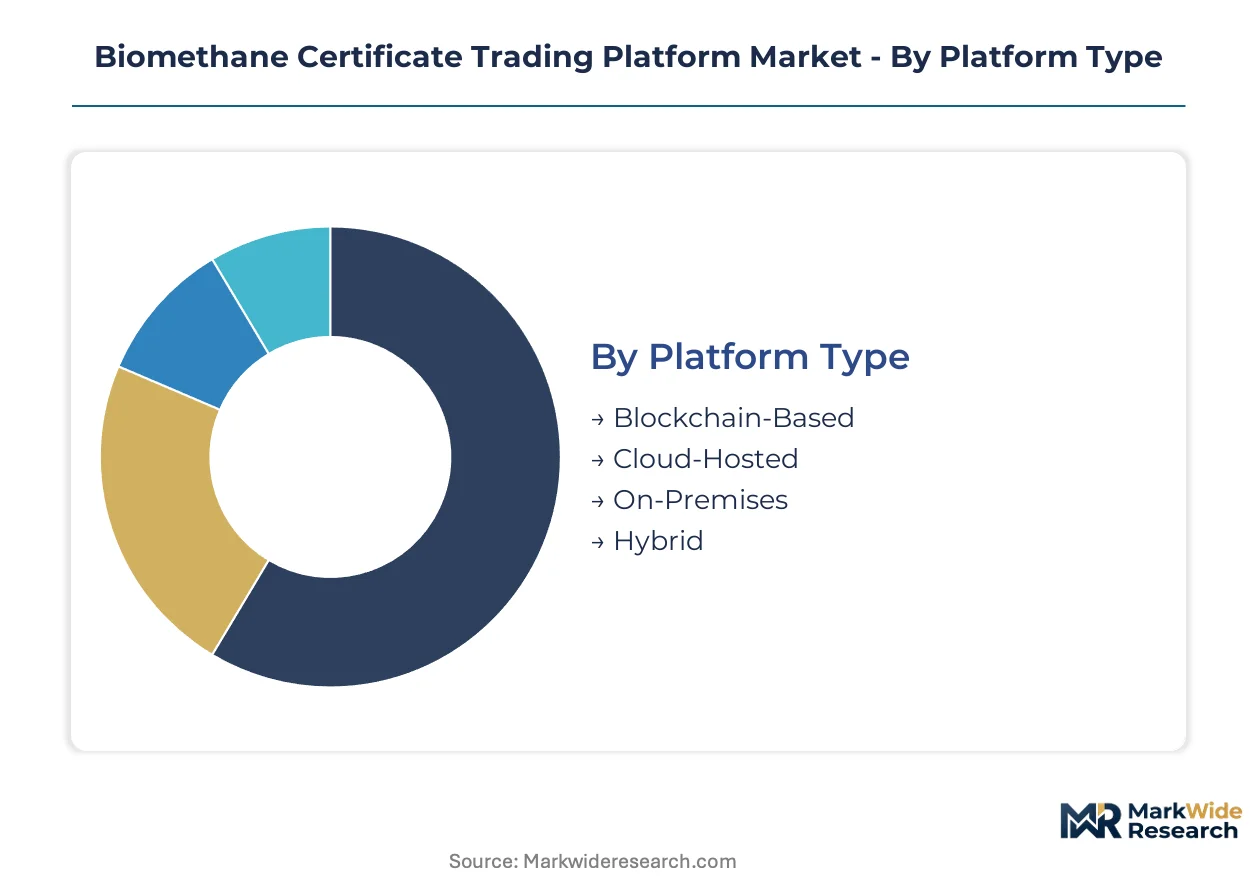
Certificate trading platforms fragment across deployment architectures, use cases, and commercial arrangements. Each segmentation axis reveals distinct margin structures and geographic concentration patterns that shape vendor strategy and buyer procurement decisions.
Platform Type:
Geographic adoption varies sharply by infrastructure maturity. Cloud-hosted deployments dominate in markets with reliable connectivity and standardized grid codes, while blockchain-native platforms cluster in jurisdictions with explicit distributed-ledger recognition in regulatory frameworks.
- Blockchain-Based:Immutable ledger architectures record certificate provenance through cryptographic hashing, eliminating reconciliation disputes in cross-border transfers. Demand concentrates among German utilities and Dutch corporate aggregators seeking audit-trail certainty for EU Green Claims Directive defense. Implementation costs and energy consumption for consensus mechanisms constrain deployment scale.
- Cloud-Hosted:API-first deployments on hyperscaler infrastructure enable rapid registry onboarding without capital expenditure. Nordic and Benelux markets favor this model due to mature cloud compliance regimes and pre-integrated grid data feeds. Lower switching costs intensify price competition among platform providers.
- On-Premises:Air-gapped installations serve national regulators and strategic infrastructure operators with data sovereignty mandates. French and Polish certificate registries specify this architecture for critical energy system cybersecurity compliance.
- Hybrid:Split configurations anchor sensitive verification data on-premises while pushing trading interfaces to cloud nodes. Danish district heating cooperatives pilot this model to balance operational agility with member-owned governance requirements.
Cloud-hosted platforms command the established base. The steepest expansion runs through blockchain-based architectures.
Application:
Buyer sophistication and procurement volume determine which use cases absorb platform development investment and sales resource allocation.
- Renewable Energy Trading:Spot and forward markets for certificate bundles require real-time price discovery and automated matching engines. German energy exchanges and Dutch TSO-linked platforms anchor liquidity in this segment.
- Carbon Offset Management:Integration of biomethane certificates with broader emissions accounting systems demands standardized metadata schemas. Corporate sustainability software vendors in the Netherlands and Belgium drive interoperability requirements.
- Regulatory Compliance:Mandated utility procurement quotas under RED III create predictable demand floors. German Bundesnetzagentur and Dutch Emissions Authority verification protocols shape platform feature roadmaps.
- Corporate Sustainability:Scope 3 reporting obligations are pulling mid-cap manufacturers without direct grid connections into certificate markets. This application is climbing the fastest as CDP and SBTi disclosure frameworks tighten.
Regulatory compliance commands the established base. The steepest expansion runs through corporate sustainability applications.
End User:
Procurement authority and technical integration capacity segment the buyer base into distinct sales motion requirements.
- Energy Suppliers:Vertically integrated utilities with captive trading desks demand high-throughput APIs and regulatory reporting modules. RWE and Enexis in Germany and the Netherlands respectively set performance benchmarks.
- Environmental Consultants:Advisory firms resell platform access to corporate clients lacking in-house carbon accounting expertise. Danish and Swedish sustainability consultancies bundle certificate procurement with emissions strategy services.
- Certification Bodies:Accredited verifiers require audit-trail access and dispute resolution workflows. Germany's TÜV and the Netherlands' Kiwa influence platform data standards through accreditation requirements.
- Corporate Buyers:Industrial gas consumers without utility status purchase certificates through retail aggregators. German cement and steel producers represent the fastest-growing cohort as process heat decarbonization accelerates.
Energy suppliers command the established base. The steepest expansion runs through corporate buyers.
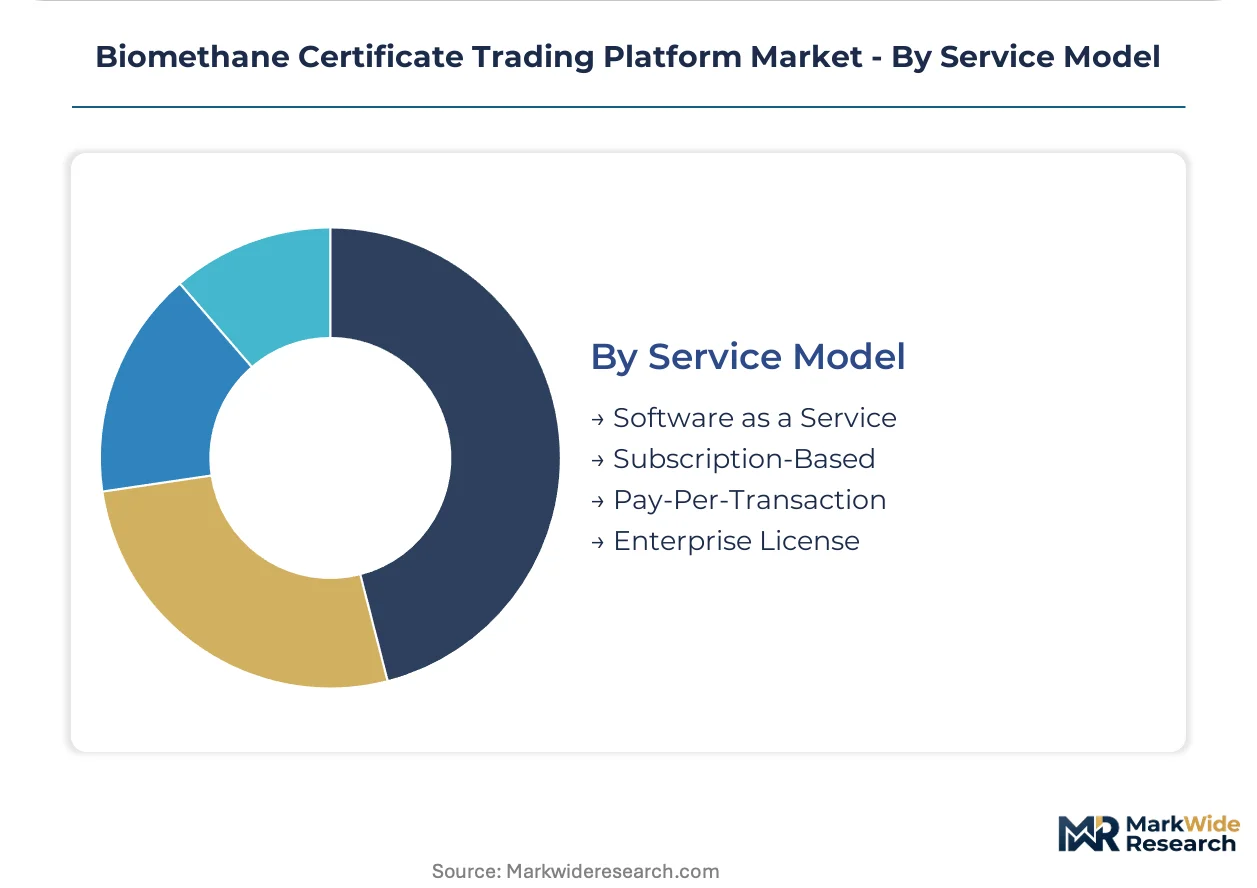
Service Model:
Contract structures align platform revenue predictability with buyer preference for fixed versus variable cost exposure.
- Software as a Service:Multi-tenant deployments with usage-based metering suit trading operations with volatile transaction volumes. Benelux certificate aggregators favor this model for seasonal demand flexibility.
- Subscription-Based:Fixed annual fees for defined user counts and transaction tiers appeal to corporate sustainability teams with budget certainty requirements. German industrial mid-caps standardize on this structure.
- Pay-Per-Transaction:Per-certificate issuance and transfer fees align costs with actual platform utilization. Danish agricultural cooperatives with intermittent biomethane production prefer this exposure-matched pricing.
- Enterprise License:Perpetual or term-limited source code access enables deep customization for national registry operators. Polish and Romanian energy regulators specify this model for sovereignty-compliant deployments.
Subscription-based contracts command the established base. The steepest expansion runs through software as a service offerings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in biomethane certificate markets concentrates in German and Dutch trading hubs, while peripheral markets absorb liquidity spillovers through cross-border arbitrage. Certificate premiums in the Netherlands routinely exceed Danish benchmarks by double-digit percentages, reflecting tighter supply constraints and corporate buyer density.
Germany
Industrial heat decarbonization and utility procurement quotas under RED III drive platform engagement. The Federal Network Agency mandates registry interoperability standards that compress implementation timelines for new entrants. The Ruhr industrial cluster anchors certificate demand as cement and steel producers pilot renewable gas substitution for grey hydrogen.
Netherlands
Corporate Scope 3 reporting obligations and TSO-linked platform infrastructure sustain liquidity concentration. The Dutch Emissions Authority enforces verification protocols that exceed baseline EU requirements, elevating compliance costs for foreign registry operators. Rotterdam's port industrial zone generates concentrated demand from chemical manufacturers seeking process heat abatement credentials.
Denmark
Agricultural cooperative biomethane production and district heating integration create distributed supply patterns. The Danish Energy Agency operates a unified national registry that eliminates fragmentation costs faced by pan-European traders. Jutland's anaerobic digestion clusters feed certificate issuance volumes that disproportionately serve Nordic corporate buyer pools.
France
National data sovereignty mandates and strategic infrastructure operator requirements sustain on-premises deployment demand. The national energy regulator specifies air-gapped registry architectures for critical system cybersecurity compliance. The Grand Est region's biogas upgrading facilities are expanding pipeline injection capacity to qualify for certificate-eligible production.
United Kingdom
Post-Brexit regulatory divergence and corporate net-zero commitments create parallel certificate demand channels. The national gas grid operator maintains verification standards that partially overlap with but remain distinct from EU frameworks. Industrial clusters in the Humber region are testing biomethane certificate procurement as a compliance pathway for carbon border adjustment preparation.
Biomethane Certificate Trading Platform Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with blockchain-native developers commanding verification innovation premiums while cloud-hosted incumbents capture scale economies through API standardization. The vendor base separates into three strategic tiers: Amsterdam-anchored trading infrastructure operators, Central European hub connectivity providers, and Nordic corporate buyer aggregators. Consolidation pressure intensifies as national registry interoperability requirements force technology convergence. Dominant competitive moves include cross-registry API partnership development and middleware integration capacity expansion for utility back-office systems.
Within the trading infrastructure tier, STX Group and CEGH exemplify contrasting geographic anchoring strategies. STX Group occupies a position centered on Amsterdam-based liquidity pools, while CEGH represents Central European hub connectivity specialization. Ecohz sits within the corporate buyer aggregation archetype, focusing on Nordic market penetration. These three entities collectively illustrate how platform differentiation fragments across trading velocity, geographic coverage, and buyer segment depth rather than converging on uniform feature sets.
| Leading Market Players |
|---|
| STX Group |
| CEGH |
| AFS Energy |
| Ecohz |
| Landwärme |
| Agriportance |
| ERGaR |
| Eurogas |
| S&P Global Commodity Insights |
| Others |
Pricing and Supply Chain Analysis
The EU Green Claims Directive gates both supply qualification and price differentiation simultaneously, mandating that certificate origin documentation meet defensible audit standards before environmental attributes command premium positioning against standard commodity gas benchmarks.
Pricing Analysis
Configured-to-order pricing spreads widen against standard certificate benchmarks as corporate buyers demand bundled verification services including satellite-based feedstock monitoring and third-party sustainability auditing. Subscription-based SaaS tiers dominate platform revenue models, while per-transaction fees apply to spot market liquidity provision. Price differentiation centers on certification grade alignment with RED III delegated act criteria and geographic delivery cost to buyer clusters. Cost compression in cloud-hosted infrastructure tiers is intensifying because hyperscaler competition reduces compute margins, though blockchain-native deployments retain pricing power for cross-border settlement certainty. Mid-cap corporate buyers without dedicated sustainability teams exhibit highest price sensitivity, while German utilities with mandated procurement quotas show lowest elasticity.
Supply Chain Analysis
Port congestion on Rotterdam-Antwerp container corridors elevates inbound logistics costs for hardware components supporting on-premises registry deployments, particularly cryptographic security modules and air-gapped server infrastructure. Supply concentrates in Germany, the Netherlands, and Denmark for biomethane production capacity feeding certificate issuance volumes. Raw material dependencies include agricultural substrate streams, biogas upgrading membrane technologies, and pipeline injection compression equipment. Single-source vulnerability runs through specialized verification software providers accredited by national regulators. Distribution runs through utility-linked aggregators in core markets and retail sustainability consultancies serving peripheral corporate demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biomethane certificate trading platforms constitute a high-growth disruption as RED III mandates and Scope 3 disclosure frameworks compress procurement cycle times toward real-time settlement infrastructure.
For Market Incumbents: Compound API standardization investments to capture cross-registry liquidity pooling before interoperability protocols commoditize connectivity layers. Defend margin position by deepening vertical integration into middleware development for utility ERP systems, offsetting margin pressure from cloud-native entrants with lower implementation friction. Prioritize certification body partnerships that entrench data standard influence. For New Entrants and Emerging Players: Lead with corporate sustainability applications as the most penetrable segment, targeting mid-cap manufacturers in the Netherlands and Belgium lacking direct grid connections but facing CDP disclosure deadlines. Develop retail aggregator partnerships that bundle certificate procurement with emissions accounting software, reducing customer acquisition costs versus direct enterprise sales motions. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-hosted platform deployments as containerized infrastructure reduces upfront capex requirements. Long-term viability favors acquisition targets with established regulatory accreditation in multiple national registries rather than single-jurisdiction operators. Monitor the Association of Issuing Bodies harmonization timeline as the critical inflection signal for liquidity consolidation plays.| Strategic Initiative | Industry Significance |
|---|---|
| Cross-Registry API Partnership | Unlocks liquidity pooling across German, Dutch, and Danish national certificate databases. |
| Middleware Integration Expansion | Captures utility back-office system connectivity revenue streams from RWE and Enexis procurement teams. |
| Blockchain Settlement Infrastructure | Compresses certificate transfer reconciliation cycles for corporate buyers under SBTi disclosure pressure. |
| Satellite Feedstock Monitoring | Documents EU delegated act compliance for German biomethane producers seeking no-deforestation certification. |
| Retail Aggregator Channel Development | Extends platform reach to mid-cap industrial buyers without direct pipeline access in Benelux markets. |
Research Methodology
Cross-validation between primary interviews with utility procurement officers, platform engineering leads, certification body auditors, and sustainability consultancy principals anchors the qualitative findings, while secondary validation draws from RED III delegated act documentation, Bundesnetzagentur registry protocols, Dutch Emissions Authority verification standards, and EEA renewable gas statistics. Bottom-up transaction volume modeling triangulates against top-down regulatory target allocation across national implementation schedules.
Sensitivity analysis stress-tests volume and value outputs across platform type, application, and end-user segmentation dimensions throughout the forecast period. CAGRs derive from regression against historical certificate issuance trajectories and projected RED III sub-target compliance obligations, incorporating electrolytic hydrogen blending adoption curves and corporate Scope 3 disclosure penetration rates as industry-specific forecast inputs.
Forecasts assume regulatory continuity in EU Green Deal implementation and national biomethane registry mutual recognition frameworks; material policy shifts toward fragmented national standards or suspended sustainability criteria would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Renewable Energy Certificate Market
Renewable Energy
Africa Solar E-Bike Market
Renewable Energy
Renewable Energy Consulting Service Market
Renewable Energy
Solar Oven Market
Renewable Energy
Botswana Renewable Energy Market
Renewable Energy
Net-Zero Energy Buildings Market
Renewable Energy
Hybrid Solar Wind System Market
Renewable Energy
Wind Turbine Foundation Market
Renewable Energy
Solar Balloon Market
Renewable Energy
Wind Turbine Crane Market
Renewable Energy
East Asia Renewable Energy Market
Renewable Energy
China Wind Power Market
Renewable Energy
Renewable Energy Sources Market
Renewable Energy
Solar Street Lighting Market
Renewable Energy
Drone Inspection Service for Renewable Energy Market
Renewable Energy
India Renewable Energy Market