
 Wellhead System Market | 2026-2036
Wellhead System Market Size, Share, and Industry Trends Forecast 2026-2036
Wellhead System Market Outlook
Market Dynamics
Asset-light leasing frameworks for subsea wellhead equipment is tilting competitive dynamics toward service providers with balance-sheet capacity. Schlumberger leverages integrated project delivery to bundle wellhead installation with completions services. Baker Hughes sustains technology leadership through proprietary metal-to-metal sealing architectures rated for 20,000 psi. NOV Inc. anchors North American onshore demand with standardized frac stack and wellhead packages optimized for Permian Basin pad drilling.
Product Landscape
A wellhead system comprises the surface or subsea pressure-containing interface between casing strings and the blowout preventer or Christmas tree, typically forged from low-alloy steel with API 6A compliance and designed to manage annular pressures exceeding 15,000 psi during drilling, completion, and production phases. Conventional wellhead configurations still dominate replacement cycles in mature basins, though integrated wellhead systems are capturing margin pools in deepwater developments by reducing rig time and eliminating flange connections. Smart wellhead technology, encompassing real-time pressure monitoring and remote choke actuation, represents the fastest-growing technology segment as operators prioritize well integrity automation.
Regulatory Environment
API 6A and ISO 10423 govern material qualification and pressure testing protocols for wellhead equipment across North American and international markets, while Norway's Petroleum Safety Authority enforces well integrity management regulations that mandate independent verification of subsea wellhead fatigue life. Brazil's ANP certification requirements for pre-salt equipment are creating localized demand for high-specification forged components. Stakeholders must monitor how methane emission detection mandates from the US EPA and EU methane strategy reshape wellhead sealing specifications and fugitive emissions testing protocols.
Market Dynamics
Deepwater operators are consolidating procurement around integrated wellhead packages that compress rig time, forcing suppliers to absorb engineering risk through performance-based contracting rather than discrete equipment sales.
Growth Catalysts
- Pre-salt exploration off Brazil:ANP certification mandates for high-pressure subsea equipment are pulling capital toward forged alloy wellhead systems rated for 15,000 psi annular pressures.
- API 6A material upgrades:Tightened qualification protocols for sour service environments are accelerating replacement cycles in mature North American basins.
- Pad drilling standardization:Permian Basin operators are specifying modular frac stack packages that reduce connection count and simplify logistics across multi-well pads.
Market Restraints
- Nickel-molybdenum alloy volatility:Forged low-alloy steel feedstock costs fluctuate with mining output from Indonesian and Philippine concentrate suppliers.
- Subsea foundry concentration:High-specification forging capacity for 20,000 psi wellhead housings clusters among a handful of European and Japanese mill suppliers.
- 20,000 psi sealing architecture complexity:Metal-to-metal seal qualification timelines extend project schedules and strain engineering bandwidth.
Strategic Opportunities
- West Africa deepwater:Offshore developments in Angola and Nigeria lack indigenous high-pressure forging infrastructure, creating service bundling openings.
- Smart wellhead integration:Convergence of fiber-optic pressure sensing and remote choke actuation enables real-time well integrity automation.
- EU methane strategy alignment:Fugitive emissions detection mandates are reshaping sealing specifications and testing protocols for North Sea operators.
Industry Challenges
- API 6A/ISO 10423 dual certification timelines:Material qualification protocols for sour service environments extend product development cycles by 18-24 months.
- Legacy flange connection incompatibility:Integrated wellhead systems require reconfiguration of existing BOP stacks and riser interfaces.
- Subsea welding specialist scarcity:Hyperbaric qualification for deepwater installation crews limits deployment velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wellhead System Market |
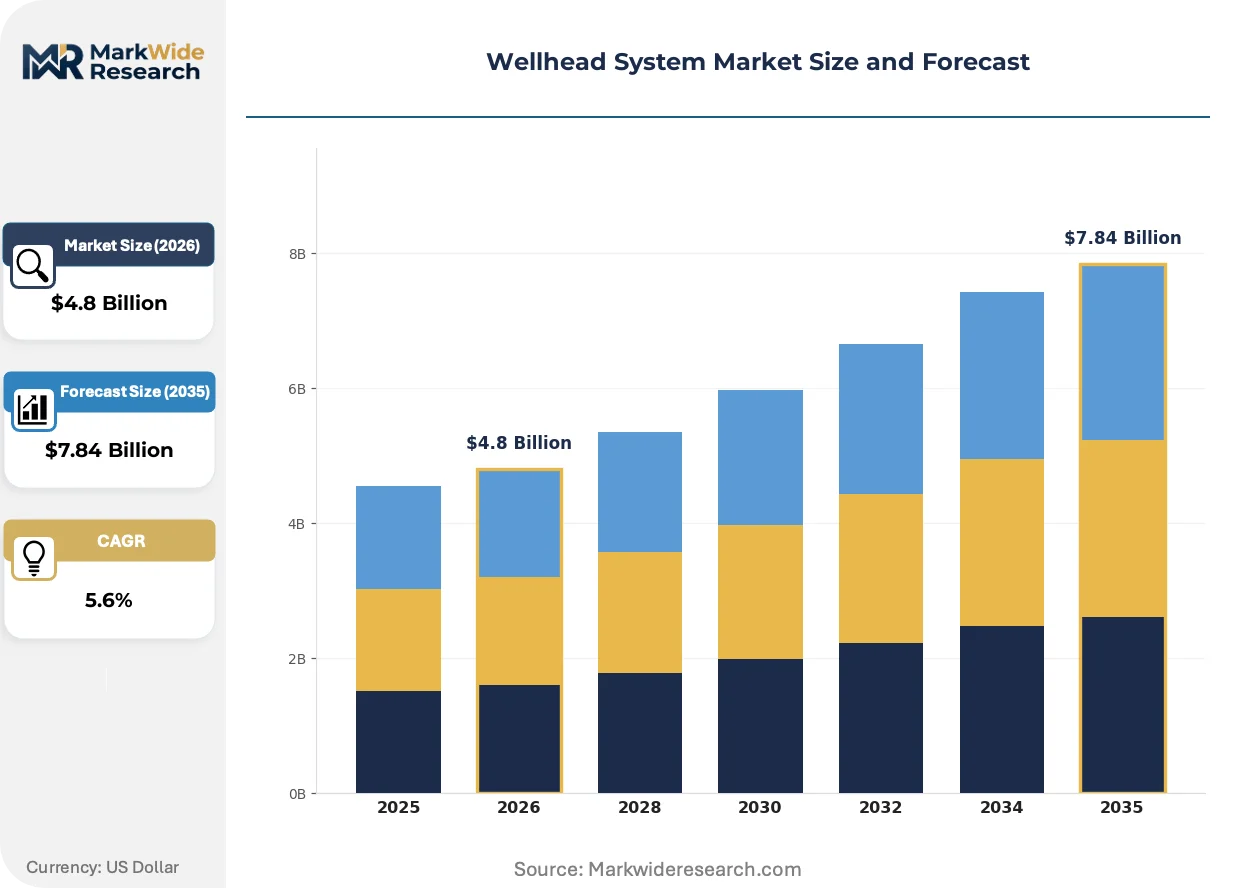
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
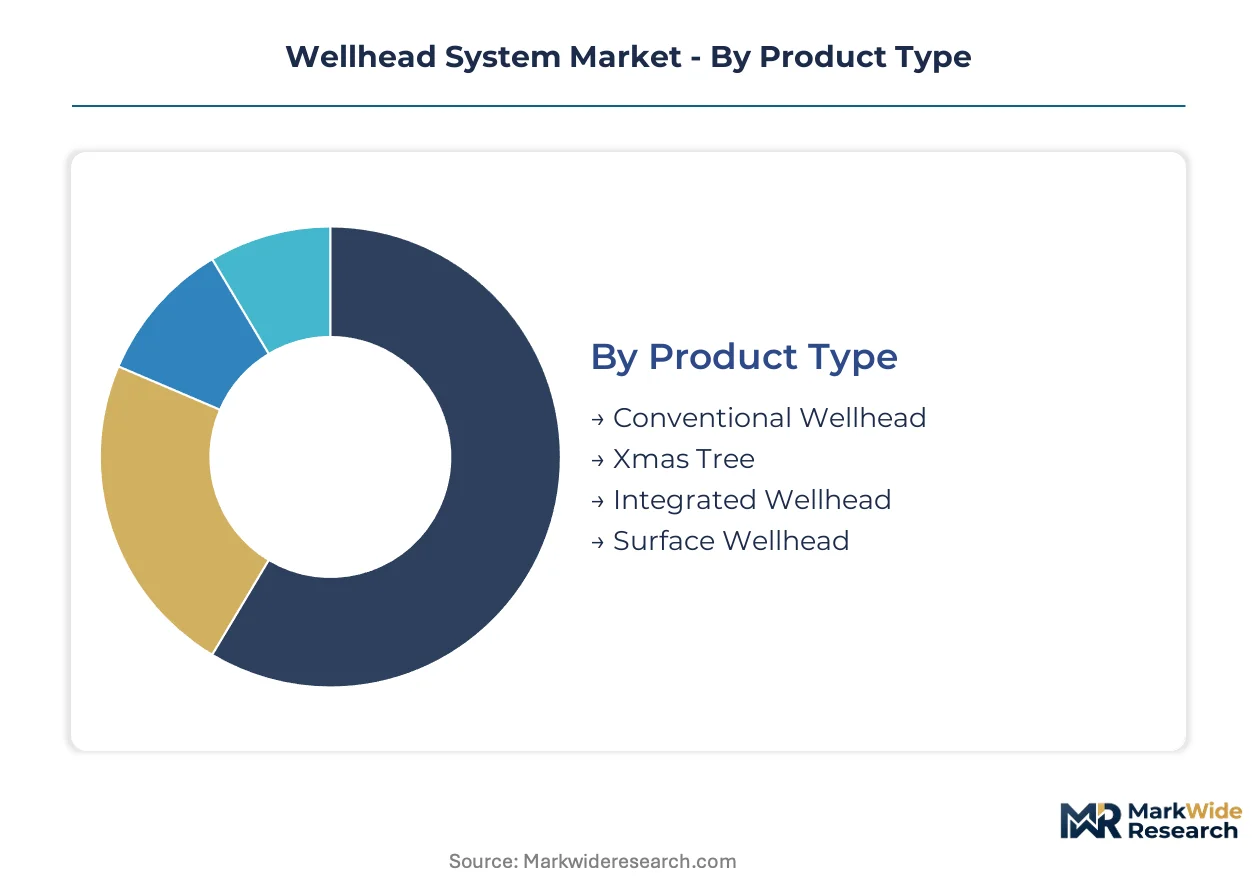
| Segmentation | Product Type: Conventional Wellhead, Xmas Tree, Integrated Wellhead, Surface Wellhead Technology: Electronic Control, Hydraulic Control, Mechanical Control, Smart Wellhead Installation: Onshore, Offshore, Subsea, Hybrid End User: Oil & Gas, Marine Services, Drilling Companies, Energy Sector |
| Companies Covered | Weatherford International, Cactus Inc., Schlumberger, Aker Solutions, Weir Group, Baker Hughes, NOV Inc., Jereh Group, TechnipFMC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wellhead System Market Strategic Shifts
Wellhead architecture is converging around automation-ready platforms that embed sensing and actuation at the pressure boundary, compressing the traditional separation between mechanical sealing and digital control layers.
Composite riser tensioner integration with subsea wellhead housings is hybridizing structural load paths, enabling lighter deployment configurations. Ultra-deepwater operators in Brazil and the US Gulf of Mexico are specifying these hybrid systems for pre-salt and Lower Tertiary developments. The technology is compressing dry weight requirements and expanding vessel-deployable installation options.
Norway's Petroleum Safety Authority well integrity regulations now mandate independent fatigue life verification for subsea wellhead connectors. Operators must submit third-party validation of cyclic loading performance before production commencement. North Sea developments are responding by front-loading engineering analysis and specifying forged components with enhanced crack-arrest properties.
Asset-light leasing frameworks are displacing capital purchase models for subsea wellhead equipment. Deepwater operators now prefer rental structures that transfer obsolescence risk to service providers. This shift concentrates most visibly in the US Gulf of Mexico, where independent producers lack balance-sheet capacity for 20,000 psi capital equipment.
Wellhead System Market Segmentation
Wellhead system procurement patterns diverge sharply by operational environment, with subsea installations commanding forged alloy specifications while onshore pad drilling drives modularity requirements. Segmentation reveals how capital allocation splits between replacement cycles in mature basins and greenfield deepwater developments.
Product Type:
Operators deploy distinct wellhead architectures depending on pressure ratings, water depth, and rig-time economics.
- Integrated Wellhead:These systems eliminate flange connections between casing spools and hangers, reducing installation time on floating rigs. Pre-salt operators off Brazil specify integrated packages rated for 15,000 psi annular pressures to compress critical path schedules.
- Conventional Wellhead:Comprising discrete casing heads, spools, and hangers assembled at surface, this configuration dominates replacement demand in the Permian Basin and other mature North American plays where existing BOP stacks constrain upgrade paths.
- Xmas Tree:The production control interface incorporating chokes, valves, and gauges for flow regulation.
- Surface Wellhead:Land-based pressure-containing assemblies for onshore drilling and completion operations.
Established volume favors conventional wellheads; emerging adoption favors integrated systems.
Technology:
Control layer sophistication determines maintenance protocols and remote operability across offshore and onshore deployments.
- Smart Wellhead:Fiber-optic pressure sensing and remote choke actuation enable real-time annular monitoring without intervention vessels. Gulf of Mexico independents prioritize these platforms to reduce opex on marginal deepwater fields.
- Hydraulic Control:Proven subsea architecture using pressurized fluid lines for valve and choke actuation. Norwegian North Sea operators specify hydraulic systems for 20,000 psi metal-to-metal sealing verification under PSA well integrity mandates.
- Electronic Control:Electric actuator systems for surface and shallow-water installations.
- Mechanical Control:Direct manual operation for onshore conventional wellheads.
Hydraulic systems anchor current offshore deployment; smart wellheads are climbing the fastest.
Installation:
Water depth and seabed conditions dictate structural load paths and deployment vessel requirements.
- Subsea:Pressure-containing housings landed on the seabed with tieback connections to surface facilities. West Africa deepwater projects in Angola and Nigeria drive demand for forged alloy systems with fatigue-resistant connectors.
- Onshore:Surface wellhead assemblies for land drilling operations, standardized across multi-well pads.
- Offshore:Platform-based wellhead systems for fixed installations.
- Hybrid:Configurations combining surface and subsea elements for tieback developments.
Onshore installations dominate unit volume; subsea commands capital intensity per well.
End User:
Balance-sheet capacity and technical risk appetite shape procurement models across operator categories.
- Oil & Gas:Integrated majors and independents specify wellhead equipment through long-term framework agreements. US Gulf of Mexico operators increasingly prefer rental structures that transfer obsolescence risk for 20,000 psi subsea assets.
- Drilling Companies:Contract drillers procure frac stack and wellhead packages for pad drilling campaigns in the Permian Basin.
- Marine Services:Installation contractors for subsea deployment and intervention.
- Energy Sector:Diversified energy companies with upstream exposure.
Oil & gas operators concentrate capital deployment; drilling contractors drive standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated majors dominate procurement in Brazil and Norway, while independent operators in the US Gulf of Mexico favor rental structures. National oil companies in West Africa and the Middle East are consolidating vendor lists around forged-alloy specialists with subsea installation capabilities.
United States
Permian Basin pad drilling sustains demand for modular frac stack packages, with operators specifying standardized wellhead configurations across multi-well sites. EPA methane emission detection mandates are reshaping sealing specifications for surface installations. Houston anchors the supplier ecosystem, where service companies bundle wellhead equipment with completions services under asset-light leasing frameworks.
Brazil
Pre-salt exploration off the Santos Basin is pulling capital toward 15,000 psi subsea wellhead systems rated for high-pressure carbonate reservoirs. ANP certification requirements mandate localized forging partnerships for high-specification components. Rio de Janeiro concentrates engineering talent and subsea installation vessel capacity for deepwater developments.
Norway
North Sea operators front-load fatigue life verification under PSA well integrity regulations, mandating third-party validation of subsea wellhead connectors. Tightened material protocols for sour service environments are accelerating replacement cycles in mature fields. Stavanger hosts the engineering clusters coordinating independent verification services and forged component qualification.
Nigeria
Deepwater developments in the Niger Delta lack indigenous high-pressure forging infrastructure, creating openings for integrated service bundling. The country's petroleum regulator enforces local content requirements for subsea equipment procurement. Lagos serves as the coordination hub for offshore installation campaigns and vendor logistics.
Saudi Arabia
Gas field development in the Empty Quarter is driving demand for sour service wellhead systems rated for high-H2S environments. The national oil company specifies API 6A compliance with enhanced material traceability for critical pressure-containing components. Dhahran concentrates domestic engineering capabilities and long-term framework agreement negotiations with international suppliers.
Wellhead System Market Competitive Environment
Channel-controlling players compete with product-specialist players across a tiered structure where scale-driven energy service conglomerates face focused forging specialists. The vendor base clusters around three archetypes: integrated project delivery platforms, forged-component specialists with metallurgical expertise, and regional installation service providers. Competitive moves center on performance-based contracting structures that transfer engineering risk to suppliers, alongside backward integration into captive forging capacity for 20,000 psi housings.
Among US-based energy service conglomerates, Schlumberger, Baker Hughes, and NOV Inc. occupy positions spanning integrated project delivery and standardized equipment packaging. Schlumberger exemplifies the bundled-service archetype combining wellhead installation with completions. Baker Hughes anchors the high-pressure sealing technology tier through proprietary metal-to-metal architectures. NOV Inc. represents the onshore standardization play with modular packages optimized for Permian Basin logistics. These three illustrate how scale-driven players are absorbing obsolescence risk through rental frameworks while specialists concentrate on forged-alloy metallurgy and subsea fatigue verification.
| Leading Market Players |
|---|
| Weatherford International |
| Cactus Inc. |
| Schlumberger |
| Aker Solutions |
| Weir Group |
| Baker Hughes |
| NOV Inc. |
| Jereh Group |
| TechnipFMC |
| Others |
Value Chain & Pricing Dynamics
Rotterdam-Antwerp freight corridors for forged alloy components transmit nickel-molybdenum price volatility directly into subsea wellhead housing costs, amplifying margin compression for European mill-dependent suppliers while enabling price differentiation between captive-forging integrated providers and procurement-reliant competitors.
Pricing Analysis
Cost-plus contracts with London Metal Exchange indexation dominate procurement frameworks for 20,000 psi subsea wellhead systems. Three-tier pricing structure across API 6A premium certification, standard sour service, and economy onshore grades separates integrated majors from Permian independents. Pricing pressure stems from asset-light leasing frameworks transferring obsolescence risk to suppliers. Drilling contractors exhibit highest price sensitivity; deepwater operators with production commencement deadlines show lowest.
Supply Chain Analysis
Low-alloy steel feedstock draws from Indonesian and Philippine nickel concentrate, Japanese and European forging capacity, and Houston distribution clusters. Critical inputs include nickel-molybdenum alloy billet, API-certified heat treatment services, and hyperbaric welding consumables. Single-source vulnerability concentrates in 20,000 psi forging presses located in Japan and Germany. Distribution runs through integrated service company rental fleets and direct OEM sales to national oil companies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is tilting toward deepwater operators consolidating vendor lists around performance-based contracting, fragmenting procurement authority previously held by discrete equipment purchasers.
For Market Incumbents: Build captive forging capacity moats by securing 20,000 psi press access in Japan or Germany before competitor lock-up. Absorb engineering risk through integrated project delivery bundling wellhead installation with completions services. Counter Schlumberger-scale bundling threats by anchoring metal-to-metal sealing technology leadership through proprietary qualification protocols.
For New Entrants and Emerging Players: Build out West African service bundling capabilities targeting Angolan and Nigerian deepwater developments lacking indigenous forging infrastructure. Penetrate smart wellhead integration white space by converging fiber-optic sensing with remote choke actuation for Gulf of Mexico independents. Pursue ANP certification partnerships with Brazilian forging specialists as go-to-market anchor.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors forged-component specialists with metallurgical expertise over capital-light installation service providers. Five-to-ten year viability hinges on backward integration into captive 20,000 psi housing production. Monitor API 6A/ISO 10423 dual certification timeline compression as inflection signal for engineering bandwidth scarcity.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Forging Capacity Buildout | Secures 20,000 psi press access in Japan or Germany against competitor lock-up. |
| Integrated Project Delivery Bundling | Combines wellhead installation with completions services under performance-based contracts. |
| Smart Wellhead Technology Licensing | Enables fiber-optic pressure sensing convergence for Gulf of Mexico marginal field operators. |
| ANP Certification Partnership | Establishes localized forging relationships for Brazilian pre-salt equipment mandates. |
| Asset-Light Leasing Framework Expansion | Transfers obsolescence risk to service providers for US Gulf independent producers. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of API certification databases, SEC 10-K equipment segment disclosures, ANP regulatory filings, and subsea installation vessel utilization reports. Interviews with drilling contractors, procurement leads at integrated majors, forging mill technical directors, and subsea installation supervisors anchor demand-side validation. Bottom-up wellhead unit economics triangulate against top-down capital expenditure tracking across Brazil, West Africa, and US Gulf deepwater developments.
Forecast inputs incorporate pressure rating tier migration, water depth deployment mix, and regulatory certification timeline shifts across the projection horizon. Segmentation dimensions model product type, control technology sophistication, installation environment, and end-user balance-sheet capacity. CAGRs derive from equipment replacement cycle analysis and greenfield project sanctioning velocity. Subsea rig dayrate trajectories and nickel alloy spot price corridors feed sensitivity testing.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese forging entrants or accelerated smart wellhead technology cycles would shift outcomes. Cross-checking against subsea tree order intake data from publicly filed equipment suppliers is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Bunker Liners Market
Oil & Gas
Canada Oil and Gas Pipeline Services Market
Oil & Gas
Middle East and Africa Early Production Facility Market
Oil & Gas
Venezuela Oil and Gas Market
Oil & Gas
Middle East and North Africa Oilfield Services Market
Oil & Gas
Central Asia Oil and Gas Midstream Market
Oil & Gas
Oil and Gas Field Services Market
Oil & Gas
Oil and Gas Automation and Instrumentation Market
Oil & Gas
Open Hole Logging Services Market
Oil & Gas
Vacuum Gas Oil Market
Oil & Gas
Indonesia Oil and Gas Market
Oil & Gas
Thermal Spray Coating for Oil and Gas Market
Oil & Gas
Middle East Wireline Services Market
Oil & Gas
Romania Oil and Gas Upstream Market
Oil & Gas
Expandable Liner Hanger System Market
Oil & Gas
Oil & Gas Defoaming Separator Market