
 South America Courier, Express, and Parcel (CEP) Market | 2026-2036
South America Courier, Express, and Parcel (CEP) Market Size, Share, and Industry Trends Forecast 2026-2036
South America Courier, Express, and Parcel (CEP) Market Insights
Brazil is reshaping competitive dynamics in South American parcel logistics through sustained warehouse automation investments near Campinas and Guarulhos. DHL Group leverages its integrated air-ground network to dominate cross-border express lanes into Mercosur corridors. United Parcel Service of America anchors premium B2B contract logistics for pharmaceutical and automotive shippers requiring temperature-validated chain of custody. FedEx competes on intermodal density, linking its Miami hub to São Paulo and Santiago with bonded warehouse privileges.
Courier, Express, and Parcel services constitute time-definite logistics solutions encompassing document envelopes through palletized freight, typically governed by dimensional weight pricing and service-level agreements specifying delivery windows from same-day to deferred five-day transit. The primary commercial purpose centers on inventory velocity for manufacturers and fulfillment reliability for digital retailers operating on promise-based customer retention. Same-day delivery and next-day delivery command the dominant margin pools as urban consumers and just-in-time manufacturers absorb premium pricing for speed certainty, while scheduled delivery sustains volume scale in B2B contract accounts with predictable replenishment cadences. Ground delivery mode occupies the mature cost-optimized tier, whereas air freight captures express premium segments where perishables and high-value electronics justify unit economics above fifteen dollars per kilogram.
Brazil's ANTT road freight regulations, Argentina's customs modernization under AFIP, and Chile's SERNAGEOMIN hazardous materials transport standards collectively shape operational compliance costs and cross-border clearance velocity across the Andean-Pacific corridor. These frameworks determine fleet specification requirements, driver certification burdens, and bonded facility placement decisions that directly filter market access for foreign operators. Stakeholders must monitor regulatory divergence between Mercosur harmonization talks and unilateral national digital customs platforms that could fragment interoperability standards.
Market Dynamics
Brazil's ANTT freight pricing regulations are compressing last-mile margins while simultaneously forcing carriers to reconfigure network density around automated sortation hubs in São Paulo state. This regulatory pressure is accelerating capital deployment toward warehouse robotics and intermodal handoff points.
Growth Catalysts
- E-commerce fulfillment velocity:Digital retailers operating in Brazil's Southeast corridor are demanding same-day slotting capabilities, pulling investment into urban micro-fulfillment nodes near Campinas and Guarulhos.
- ANTT regulatory clarity:Brazil's federal road freight pricing framework has stabilized carrier cost forecasting, enabling longer-term contract structures with pharmaceutical and automotive shippers requiring temperature-validated chain of custody.
- Mercosur customs harmonization:Cross-border express lanes into Argentina and Paraguay are benefiting from simplified documentation protocols, reducing dwell time at border transfer points.
Market Restraints
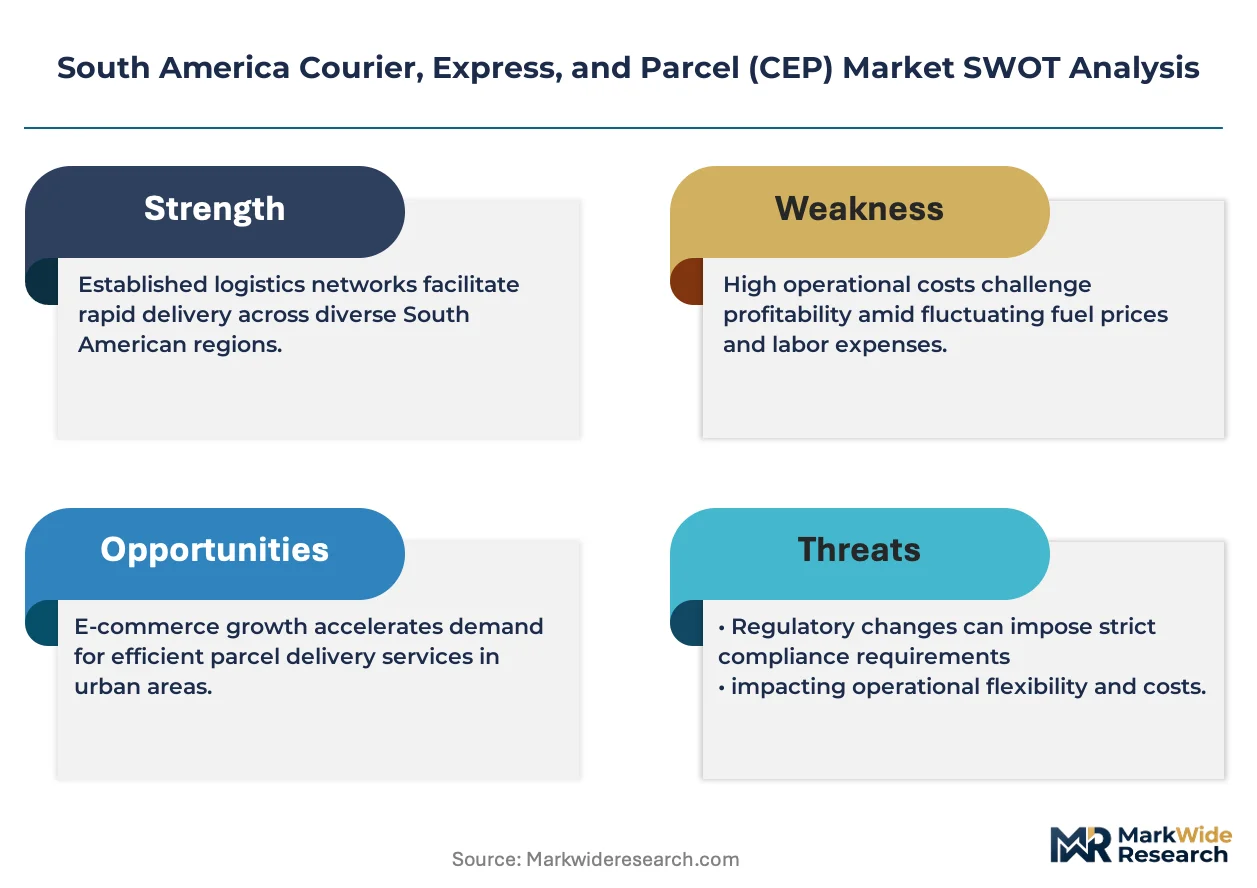
- Fuel cost volatility:Diesel price fluctuations indexed to international crude benchmarks directly erode ground delivery unit economics across Brazil's extended highway networks.
- Last-mile labor scarcity:Driver certification requirements under ANTT regulations have tightened qualified operator pools in São Paulo state's dense urban cores.
- Air freight capacity concentration:Express premium segments depend on bonded warehouse privileges at Miami and São Paulo hubs, creating chokepoint vulnerability during peak volume windows.
Strategic Opportunities
- Andean-Pacific corridor expansion:Chile's SERNAGEOMIN hazardous materials transport standards are creating specialized carrier niches for lithium battery logistics serving energy storage manufacturers.
- Reverse logistics monetization:E-commerce return flows in Argentina's Buenos Aires metro are enabling secondary revenue streams through refurbishment and resale channel integration.
- Digital customs platform integration:AFIP's modernization of Argentine customs procedures is opening bonded facility placement opportunities for operators with real-time declaration capabilities.
Industry Challenges
- Automated sortation capex intensity:Warehouse robotics deployment in Brazil's Southeast requires capital commitments that strain mid-tier carrier balance sheets.
- Temperature validation certification timelines:Pharmaceutical chain-of-credential compliance under ANVISA standards extends onboarding cycles for new cold-chain entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Courier, Express, and Parcel (CEP) Market |
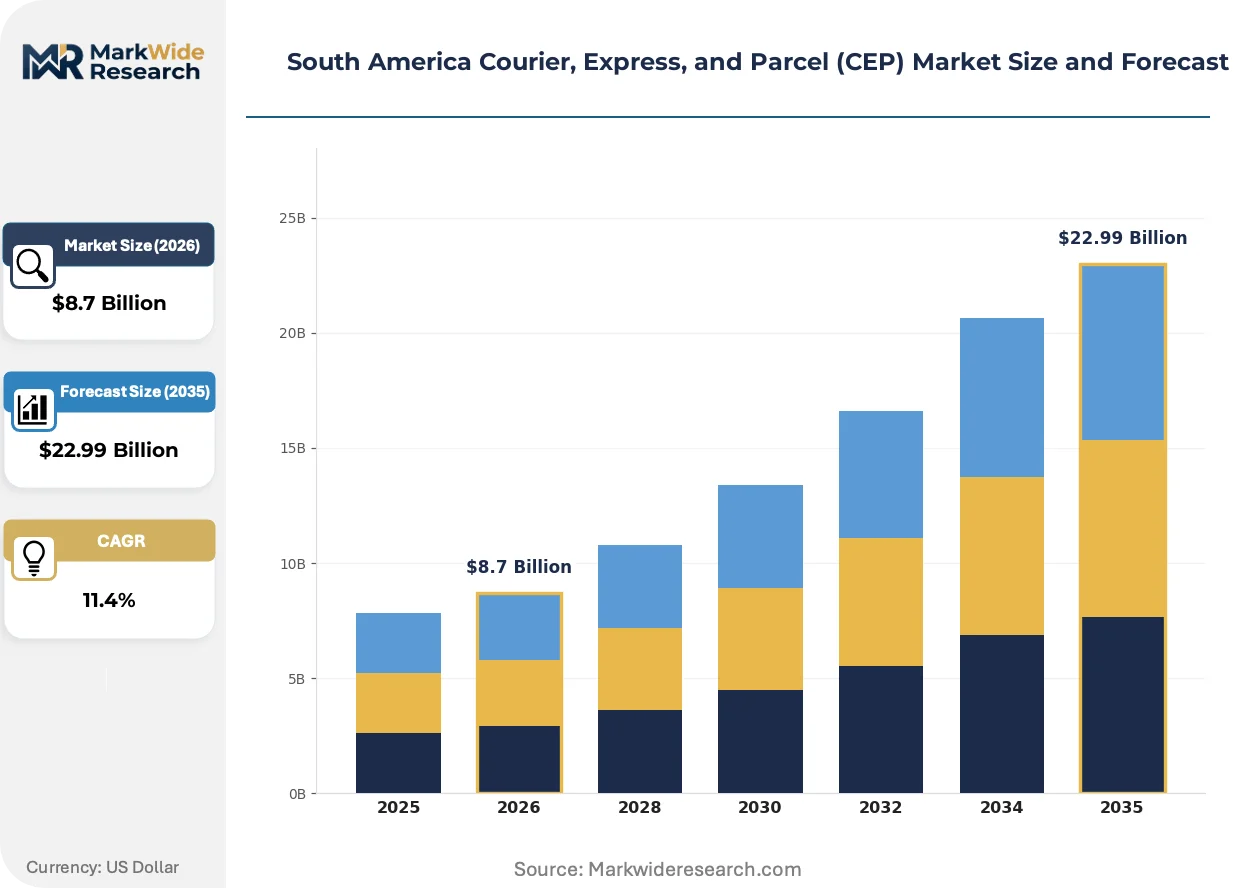
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Same-Day Delivery, Next-Day Delivery, Scheduled Delivery, Standard Delivery Delivery Mode: Ground, Air, Sea, Intermodal Customer Type: B2B, B2C, E-Commerce Platforms, Retailers Package Size: Small, Medium, Large, Oversized |
| Companies Covered | DHL Group, United Parcel Service of America, FedEx, Empresa Brasileira de Correios e Telegrafos, Correo Argentino, Correos de Chile, Chilexpress, Aramex, DSV A/S, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Courier, Express, and Parcel (CEP) Market Trends and Innovations
Parcel logistics across South America is experiencing compression of delivery time expectations alongside automation of physical handling and documentation flows. Three intersecting developments are restructuring competitive requirements.
Autonomous mobile robots in warehouse sortation are collapsing the labor cost curve for high-volume parcel handling. E-commerce fulfillment centers in São Paulo state are deploying these systems at accelerating pace. The structural consequence is collapsing the viability of manual sortation for operators above fifty thousand daily parcel volume.
Argentina's AFIP customs modernization is mandating pre-arrival declaration systems for all bonded freight. Industrial consequence includes accelerated clearance velocity for compliant operators and exclusion penalties for paper-dependent carriers. Cross-border express segments serving Buenos Aires are responding by integrating directly with AFIP's digital platform.
Urban consumers are compressing delivery window tolerance from next-day to same-day for non-prescription categories. Digital marketplaces in Brazil's Southeast are displacing scheduled delivery with slot-based appointment systems. This pattern is most visible in São Paulo state's grocery and electronics verticals where inventory proximity determines merchant conversion rates.
South America Courier, Express, and Parcel (CEP) Market Segmentation
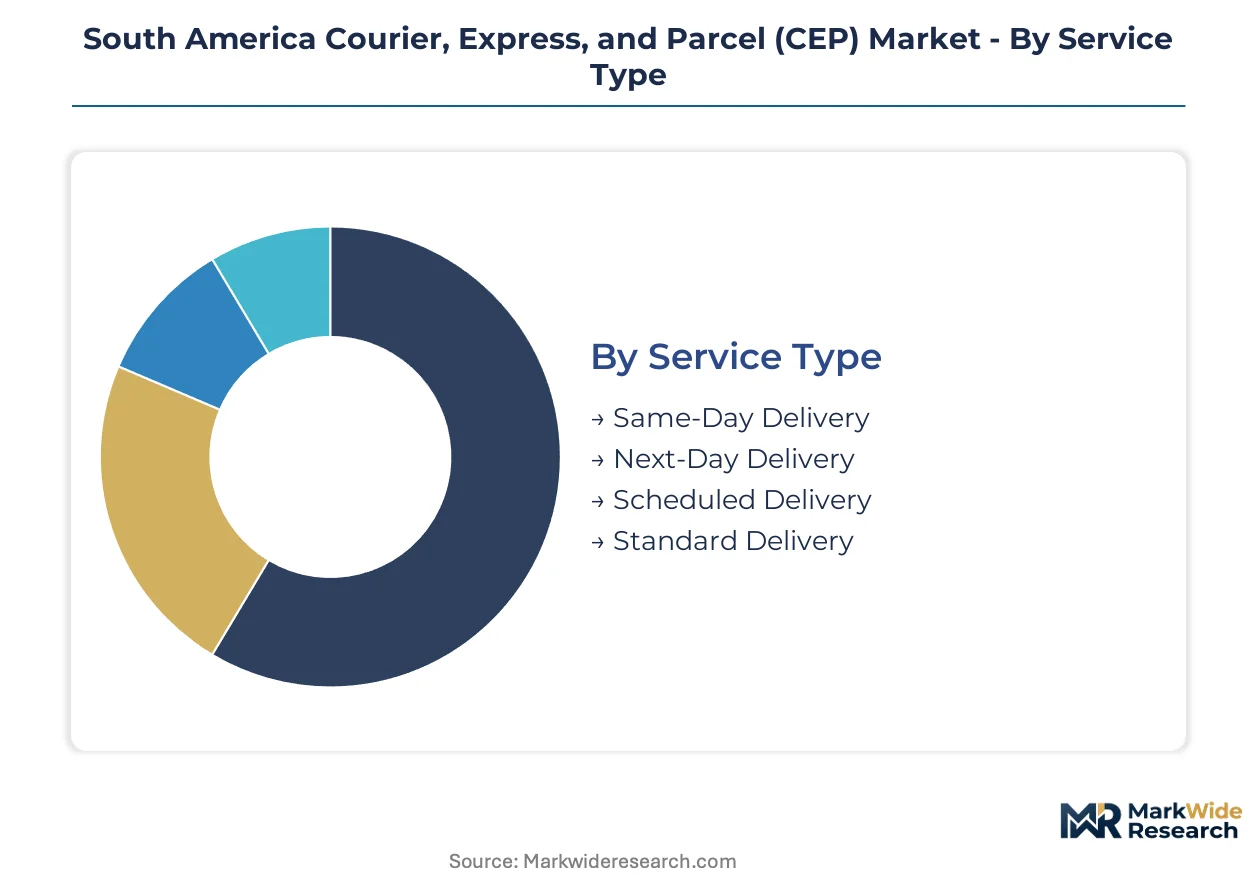
Parcel logistics in South America demands granular segmentation because service economics diverge sharply across delivery velocity commitments and modal configurations. Regulatory frameworks from ANTT to AFIP create compliance boundaries that reshape segment viability by corridor.
Service Type:
Velocity tiers span from immediate fulfillment to deferred transit, each commanding distinct margin structures and infrastructure requirements.
- Same-Day Delivery:Urban micro-fulfillment networks enable slot-based appointment systems for grocery and electronics verticals in São Paulo state. Brazil's Southeast corridor absorbs premium pricing as digital marketplaces compete on inventory proximity.
- Next-Day Delivery:Express premium segments rely on bonded warehouse privileges at Miami and São Paulo hubs, with air-ground intermodal handoffs compressing transit windows. Pharmaceutical and automotive shippers under ANTT regulations anchor contract volume here.
- Scheduled Delivery:Predictable replenishment cadences sustain B2B contract accounts with cost-optimized routing across Brazil's extended highway networks.
- Standard Delivery:Deferred five-day transit captures price-sensitive volume in Argentina's Buenos Aires metro where customs modernization under AFIP determines clearance velocity.
The dominant share belongs to Next-Day Delivery, while Same-Day Delivery is gaining share fastest.
Delivery Mode:
Modal selection directly filters unit economics and regulatory exposure across the Andean-Pacific corridor.
- Ground:Diesel-indexed cost structures dominate Brazil's highway networks, though ANTT driver certification requirements constrain qualified operator pools in dense urban cores.
- Air:Express premium segments justify unit economics above fifteen dollars per kilogram for perishables and high-value electronics, with capacity concentration at São Paulo and Santiago creating chokepoint vulnerability.
- Sea:Bulk parcel consolidation serves deferred segments with lowest cost per kilogram across Mercosur maritime corridors.
- Intermodal:Bonded warehouse privileges at Miami hub linkages enable seamless air-ground transfers into Santiago and São Paulo with customs pre-clearance.
Ground transport holds the dominant share, while Intermodal is climbing the fastest as carriers reconfigure network density.
Customer Type:
Demand concentration patterns split between inventory velocity for manufacturers and fulfillment reliability for digital retailers.
- B2B:Pharmaceutical and automotive shippers require temperature-validated chain of custody under ANVISA standards, extending onboarding cycles for new cold-chain entrants.
- B2C:Urban consumers in Brazil's Southeast corridor compress delivery window tolerance from next-day to same-day for non-prescription categories.
- E-Commerce Platforms:Digital retailers accelerate parcel volume growth through promise-based customer retention models tied to fulfillment speed certainty.
- Retailers:Brick-and-mortar networks leverage scheduled delivery for predictable replenishment across Argentina's interior provinces.
E-Commerce Platforms command the dominant share, while B2C is expanding most quickly as marketplace penetration deepens.
Package Size:
Dimensional weight pricing governs commercial terms across the handling spectrum from document envelopes to palletized freight.
- Small:Document envelopes and single-item parcels dominate cross-border express lanes into Mercosur corridors with simplified documentation protocols.
- Medium:Electronics and apparel verticals in São Paulo state drive automated sortation capex as volumes exceed fifty thousand daily parcel thresholds.
- Large:Palletized freight serves B2B contract logistics with temperature validation requirements for pharmaceutical distribution.
- Oversized:Specialized handling for lithium battery logistics under Chile's SERNAGEOMIN hazardous materials standards creates carrier niches serving energy storage manufacturers.
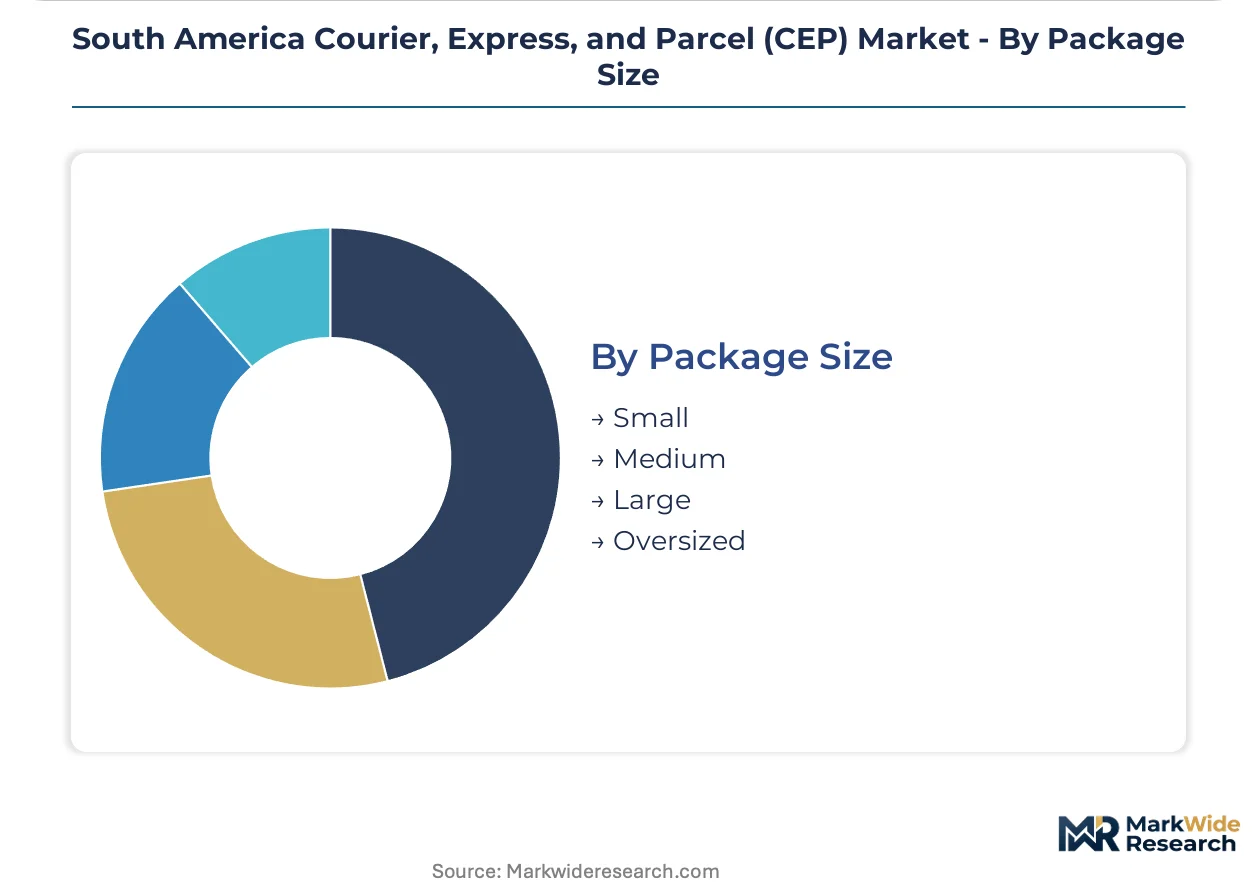
Medium packages hold the dominant share, while Small parcels are gaining share fastest as e-commerce penetration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Logistics infrastructure concentrates in Brazil's São Paulo state, where automated sortation hubs and bonded warehouse clusters support cross-border express lanes into Mercosur corridors. Argentina and Chile anchor secondary capacity nodes shaped by distinct regulatory frameworks governing customs clearance and hazardous materials transport.
Brazil
E-commerce fulfillment velocity and pharmaceutical cold-chain demand pull investment toward Campinas and Guarulhos micro-fulfillment nodes. ANTT federal road freight pricing regulations stabilize carrier cost forecasting for long-term contract structures. São Paulo state's logistics density enables same-day slotting capabilities that digital marketplaces leverage for customer retention.
Argentina
Cross-border express volumes into Buenos Aires benefit from simplified Mercosur documentation protocols reducing border dwell times. AFIP customs modernization mandates pre-arrival declaration systems that accelerate clearance for compliant operators. The Buenos Aires metro area concentrates reverse logistics monetization through refurbishment and resale channel integration.
Chile
Lithium battery logistics for energy storage manufacturers create specialized carrier niches under SERNAGEOMIN hazardous materials transport standards. Santiago's bonded warehouse privileges enable seamless air-ground intermodal handoffs with Miami hub linkages. The Andean-Pacific corridor supports express premium segments for perishables and high-value electronics.
Colombia
Bogotá's elevated logistics costs drive ground delivery optimization across extended highway networks connecting Andean population centers. The national customs authority's digital platform integration determines bonded facility placement decisions for foreign operators. Medellín's industrial corridor absorbs scheduled delivery volume for predictable B2B replenishment cadences.
Peru
Lima's coastal position supports maritime consolidation for deferred five-day transit segments serving price-sensitive volume. The national transport authority's driver certification requirements constrain qualified operator pools in dense urban cores. Callao's port logistics cluster handles bulk parcel consolidation across Pacific maritime corridors.
South America Courier, Express, and Parcel (CEP) Market Competitive Landscape
Integrated express networks and postal incumbents split the market between premium cross-border velocity and cost-optimized domestic coverage. The structure consolidates around three strategic archetypes: global integrators with bonded warehouse privileges, national postal operators with last-mile density, and regional specialists with hazardous materials certification. Competitive moves center on warehouse automation capex deployment and intermodal handoff point expansion.
Within the global integrator tier, DHL Group and United Parcel Service of America exemplify network-scale positioning through integrated air-ground infrastructure. FedEx occupies a position linking Miami hub operations to São Paulo and Santiago corridors. Among national postal operators, Empresa Brasileira de Correios e Telegrafos represents domestic last-mile density advantages under federal regulatory frameworks.
| Leading Market Players |
|---|
| DHL Group |
| United Parcel Service of America |
| FedEx |
| Empresa Brasileira de Correios e Telegrafos |
| Correo Argentino |
| Correos de Chile |
| Chilexpress |
| Aramex |
| DSV A/S |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in São Paulo state's automated sortation infrastructure is compressing carrier margins while simultaneously concentrating pricing power among operators with bonded warehouse privileges at Guarulhos and Campinas. This utilization squeeze forces mid-tier carriers to absorb diesel-indexed cost volatility or exit express premium segments entirely.
Pricing Analysis
ANTT federal road freight pricing regulations dictate the pricing tier structure across Brazil's CEP market, anchoring contract-based long-term offtake agreements for pharmaceutical and automotive shippers. Three-tier pricing structure across premium, standard, and economy levels separates temperature-validated chain-of-credential services from deferred ground delivery. Cost compression in standard delivery is intensifying because diesel price fluctuations directly erode highway network unit economics. E-commerce platforms absorb premium pricing for same-day velocity, while Argentina's interior provinces exhibit highest price sensitivity on deferred five-day transit.
Supply Chain Analysis
Export-control regimes on warehouse robotics and automated sortation systems from Germany, Japan, and South Korea constrain capital deployment timelines for Brazilian carriers seeking volume thresholds above fifty thousand daily parcels. Equipment sourcing draws from these jurisdictions, with lithium battery logistics components resting on Chilean and Australian supply corridors. Single-source vulnerability concentrates in Miami hub air freight capacity for cross-border express into Mercosur. Distribution runs through São Paulo state micro-fulfillment nodes, with last-mile handoffs to certified operator pools under ANTT driver certification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South America CEP market is cycling through a recovery phase as e-commerce fulfillment velocity rebounds from regulatory-adjustment troughs. ANTT pricing clarity has stabilized carrier cost forecasting, enabling longer-term contract structures that anchor capital deployment cycles.
For Market Incumbents: Pre-empt margin erosion by accelerating warehouse robotics deployment at Campinas and Guarulhos before mid-tier carriers achieve automated sortation scale. Secure temperature-validation certification under ANVISA standards to lock pharmaceutical contract renewals. Bonded warehouse privileges at São Paulo hubs represent the priority defensive lever against cross-border express entrants.
For New Entrants and Emerging Players: Pursue lithium battery logistics niches under Chile's SERNAGEOMIN hazardous materials standards, where specialized carrier certification creates artificial scarcity. Argentina's Buenos Aires metro reverse logistics flows offer the most penetrable white-space for refurbishment and resale channel integration. Direct AFIP digital customs platform integration enables faster clearance velocity as a differentiated go-to-market angle.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated sortation infrastructure as manual handling viability collapses above fifty thousand daily parcel thresholds. Acquisition targets should display existing ANVISA cold-chain certification and São Paulo state logistics density. Watch for ANTT regulatory harmonization talks with Mercosur partners as the signal indicating cross-border express lane expansion viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Warehouse Automation Deployment | Campinas and Guarulhos robotics investments collapse labor cost curves for high-volume parcel handling. |
| Bonded Facility Expansion | Miami-São Paulo-Santiago hub linkages enable seamless air-ground intermodal handoffs with customs pre-clearance. |
| Temperature Validation Certification | ANVISA pharmaceutical chain-of-credential compliance extends contract renewal cycles and excludes uncertified entrants. |
| Digital Customs Platform Integration | AFIP pre-arrival declaration systems accelerate Buenos Aires clearance velocity for compliant operators. |
| Reverse Logistics Channel Development | Buenos Aires metro refurbishment and resale integration monetizes e-commerce return flows as secondary revenue streams. |
Research Methodology
A spread of perspectives from logistics network planners, pharmaceutical supply chain directors, e-commerce fulfillment operators, and ANTT regulatory compliance officers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against customs modernization filings, ANTT regulatory bulletins, SEC 10-K disclosures from listed integrators, and Mercosur trade flow databases. Bottom-up parcel volume modeling across service type, delivery mode, and customer type segments was triangulated against top-down macroeconomic consumption indicators.
Demand-supply balance dynamics across the projection horizon shaped the analytical framework, with segmentation dimensions spanning velocity tiers, modal configurations, package size categories, and regional regulatory clusters. CAGRs were derived from trend extrapolation of e-commerce penetration rates, ANTT pricing stabilization effects, and AFIP digital customs adoption curves. Forecast inputs incorporated diesel price volatility indices, automated sortation capex deployment schedules, and temperature-validation certification pipeline timelines.
Sensitivities concentrate around ANTT regulatory divergence from Mercosur harmonization, AFIP digital platform interoperability setbacks, and Miami hub capacity constraints during peak volume windows. Forecasts reflect documented assumptions about e-commerce growth sustainment and customs modernization velocity. Cross-checking against IATA air freight capacity reports and national customs authority disclosure filings is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Illinois Freight and Logistics Market
Logistics and Shipping
North America Pharmaceutical Logistics Market
Logistics and Shipping
Last-Mile Delivery Market
Logistics and Shipping
Third-Party Logistics (3PL) Market
Logistics and Shipping
Singapore Shipping Agency Services Market
Logistics and Shipping
Japan Freight and Logistics Market
Logistics and Shipping
Russia Third-Party Logistics (3PL) Market
Logistics and Shipping
China Digital Freight Forwarding Market
Logistics and Shipping
Finished Vehicle Logistics Market
Logistics and Shipping
Malaysia Road Freight Transport Market
Logistics and Shipping
North America Same Day Delivery Market
Logistics and Shipping
Peru Road Freight Transport Market
Logistics and Shipping
United States Digital Freight Forwarding Market
Logistics and Shipping
Italy Courier Market
Logistics and Shipping
Asia-Pacific Cold Chain Logistics Market
Logistics and Shipping
South Korea Parcel Delivery Market