
 Roll-On Bottles Market | 2026-2036
Roll-On Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Roll-On Bottles Market Analytics
REACH compliance is restructuring material sourcing decisions for European roll-on bottle suppliers. Gerresheimer leverages its glass-forming expertise to sustain premium pharmaceutical contracts across multiple continents. Takemoto anchors Asian supply chains through specialized precision-molding capabilities for cosmetic roll-ons. SGD Pharma competes on borosilicate durability standards that meet stringent essential oil compatibility requirements.
Roll-on bottles are cylindrical containers fitted with a rotating ball applicator, typically manufactured from glass, plastic, or biodegradable polymers with precision tolerances of 0.1–0.3 mm for ball-to-neck fitment, designed to dispense controlled liquid volumes in personal care and pharmaceutical applications. Plastic roll-on bottles dominate unit volume due to cost-efficient injection-blow molding, while glass formats command margin pools in pharmaceutical and luxury essential oil segments where chemical inertness justifies premium positioning. Biodegradable materials represent the fastest-growing structural category as brand owners reformulate packaging roadmaps around extended producer responsibility frameworks.
The FDA governs pharmaceutical roll-on packaging through container-closure integrity requirements, while the EU Green Deal mandates recycled content minimums that reshape material procurement across European supply chains. BIS certification in India enforces dimensional and chemical safety standards for imported cosmetic packaging components. Stakeholders must monitor evolving extended producer responsibility implementations to determine capital allocation between conventional plastic retooling and biodegradable production scale-up.
Market Dynamics
EU Green Deal packaging waste directives are forcing material transitions across European supply chains, compressing decision timelines for converters choosing between conventional plastic retooling and biodegradable production scale-up.
Growth Catalysts
- Extended Producer Responsibility frameworks:EU member states are implementing packaging waste accountability rules that incentivize brand owners to specify refillable and recyclable roll-on formats.
- Serum application expansion:Personal care manufacturers are retrofitting production lines to accommodate precision-dispensing roll-on bottles for facial and under-eye treatments.
- Germany:Cosmetic manufacturers in this market are accelerating sustainable packaging adoption ahead of 2025 regulatory deadlines.
Market Restraints
- Biopolymer feedstock volatility:PLA and PHA resin prices fluctuate with agricultural commodity cycles, compressing margins for converters committed to biodegradable transitions.
- Glass supply concentration:Borosilicate roll-on bottle production clusters in specialized European and Asian glassworks, creating geographic vulnerability for pharmaceutical clients.
- Ball-to-neck tolerance limits:Precision molding within 0.1–0.3 mm tolerances restricts viable supplier pools for high-volume cosmetic contracts.
Strategic Opportunities
- India:BIS certification requirements for imported cosmetic packaging components create captive demand for domestic precision-molding capacity expansion.
- Pharmaceutical essential oils:Chemical inertness requirements for concentrated botanical formulations favor glass roll-on formats with specialized ball materials.
- Refill station networks:Direct-to-consumer retail channels in European urban centers are piloting bulk dispensing systems compatible with durable roll-on vessels.
Industry Challenges
- Multi-material separation:Roll-on bottles combining plastic housings, stainless balls, and glass reservoirs complicate post-consumer recycling streams and automated sortation.
- REACH compliance timelines:Substance of Very High Concern notifications for novel biopolymers extend qualification periods for European market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Roll-On Bottles Market |
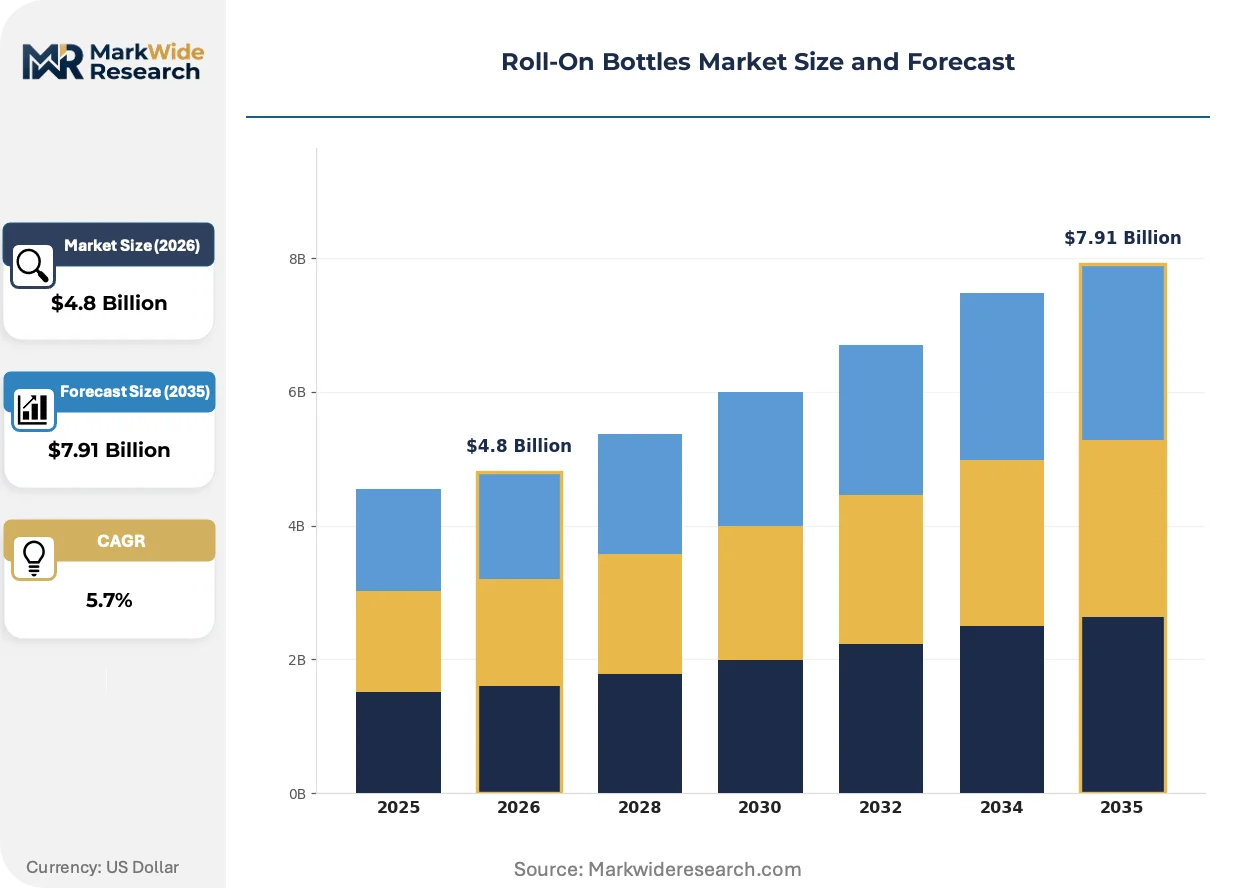
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass, Plastic, Biodegradable, Refillable Use Case: Cosmetics, Pharmaceuticals, Essential Oils, Personal Care Closure Type: Snap On, Screw Cap, Roll-On Ball, Dropper Capacity: 10 ml, 15 ml, 20 ml, 30 ml |
| Companies Covered | PauPack, Kaufman Container, Daxin, Richards Packaging, SGD Pharma, Gerresheimer, Stoelzle Glass Group, Takemoto, TricorBraun, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Roll-On Bottles Market Evolving Landscape
Material science advances and regulatory pressure are converging to reshape roll-on bottle construction, with precision molding and sustainability specifications now determining supplier viability across personal care and pharmaceutical segments.
Biodegradable polymer formulations are modularizing roll-on bottle supply chains by enabling brand owners to meet extended producer responsibility targets without sacrificing precision tolerances. Cosmetic manufacturers in Germany and France are piloting PLA-PHA blends for mass-market deodorant applications. This material transition is compressing the viable supplier base to converters with dual conventional-biopolymer capability.
REACH substance restrictions are restructuring sourcing decisions for European roll-on bottle suppliers by mandating substitution assessments for legacy plasticizers and stabilizers. ECHA candidate list updates now cover several compounds common in ball-bearing lubricants and neck seal formulations. Pharmaceutical packaging buyers are responding by qualifying alternative chemistries ahead of authorization deadlines.
Direct refill programs are disrupting traditional single-use packaging procurement in European personal care markets by transferring volume risk from brand owners to durable vessel manufacturers. Specialty retailers in Paris and Berlin are deploying in-store dispensing infrastructure that rewards consumer vessel reuse. This channel evolution concentrates demand with converters capable of producing impact-resistant glass and engineered polymer formats rated for 50+ refill cycles.
Roll-On Bottles Market Segmentation
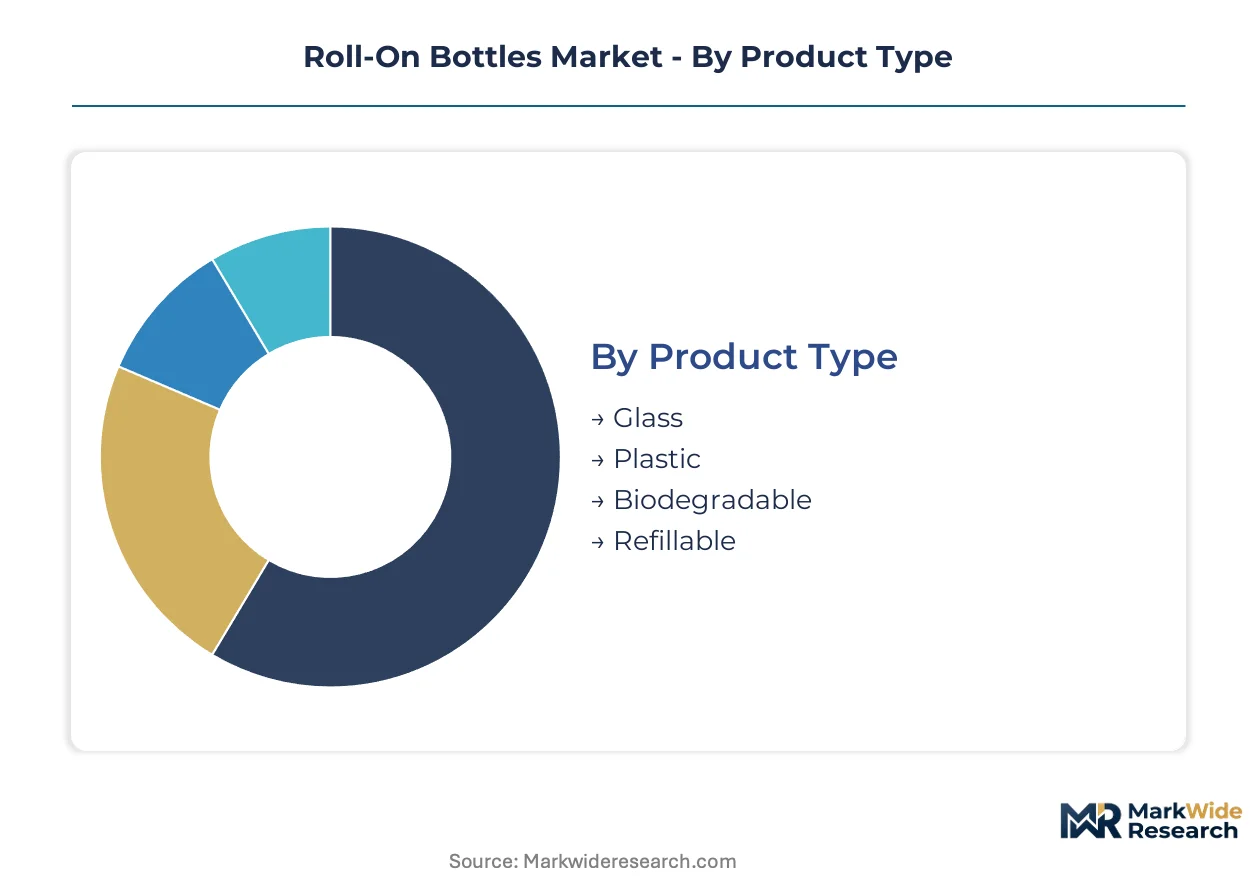
Roll-on bottle procurement patterns diverge sharply across material chemistry, application requirements, and dispensing precision needs. Buyers prioritize chemical compatibility, regulatory compliance, and end-consumer convenience when selecting specifications.
Product Type:
Cost tier separates mass-market converters from premium pharmaceutical suppliers.
- Glass:Borosilicate and soda-lime formulations deliver chemical inertness for essential oil and pharmaceutical applications. Germany and France concentrate demand for amber and cobalt blue variants that protect photosensitive formulations.
- Plastic:PET and HDPE formats dominate unit economics through injection-blow molding efficiency. Cosmetic manufacturers in India specify these for deodorant mass markets where BIS certification governs import compliance.
- Biodegradable:PLA-PHA blends serve EU Green Deal mandates for extended producer responsibility compliance.
- Refillable:Engineered polymer and impact-resistant glass constructions withstand 50+ reuse cycles in European retail refill networks.
Plastic leads volumes today; biodegradable formats are gaining share fastest.
Use Case:
Application determines tolerance specifications and material qualification timelines.
- Cosmetics:Facial serums and under-eye treatments require 0.1–0.3 mm ball-to-neck precision for controlled dispensing. German manufacturers retrofit production lines to accommodate these specifications.
- Pharmaceuticals:FDA container-closure integrity requirements and EMA stability protocols mandate borosilicate glass for topical drug delivery.
- Essential Oils:Concentrated botanical formulations demand inert materials that resist terpene degradation.
- Personal Care:Deodorant applications prioritize cost-efficient plastic formats with stainless steel ball bearings.
Personal care commands unit volume leadership; cosmetics applications show steepest expansion trajectory.
Closure Type:
Volume scale and automation compatibility distinguish procurement patterns.
- Snap On:Single-use cosmetic applications favor rapid-assembly formats compatible with high-speed filling lines.
- Screw Cap:Pharmaceutical and essential oil segments specify child-resistant and tamper-evident threaded closures.
- Roll-On Ball:Precision-molded stainless steel, glass, or ceramic spheres deliver 0.1–0.3 mm tolerance fitment. REACH substance restrictions now cover legacy ball-bearing lubricants, forcing chemistry substitutions.
- Dropper:Serum and treatment applications combine roll-on dispensing with pipette functionality for dual-mode usage.
Roll-on ball closures dominate functional demand; dropper hybrids are climbing the fastest among specialty formats.
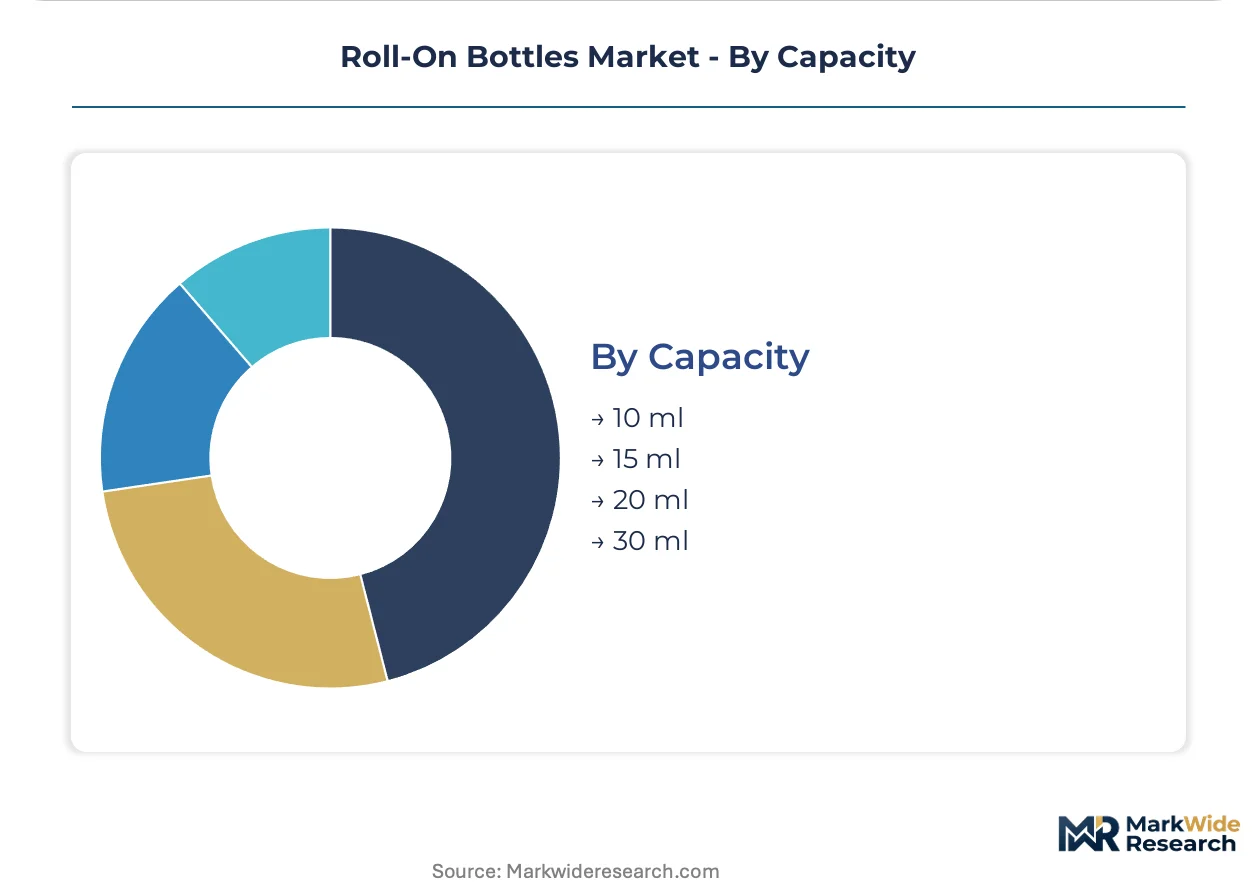
Capacity:
Travel retail regulations and dosage duration shape size selection.
- 10 ml:Airline carry-on compliance and sampling programs drive specification for trial-size cosmetics and pharmaceutical samples.
- 15 ml:Under-eye serums and targeted treatments balance portability with 30-day usage duration.
- 20 ml:Standard deodorant and facial treatment formats align with European refill station dispensing economics.
- 30 ml:Extended-use essential oil and pharmaceutical applications justify larger reservoir capacity.
20 ml leads standard procurement volumes; 10 ml formats are expanding most quickly in travel retail channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized glass-forming workforces in Germany and precision-molding engineering talent in Japan anchor production quality standards across the industry. Cosmetic packaging converters cluster near regulatory decision centers in France and regulatory compliance expertise concentrates in Switzerland.
United States
FDA container-closure integrity requirements drive pharmaceutical roll-on specifications for topical drug delivery. The EPA oversees chemical safety in packaging materials through TSCA substance notifications. New Jersey and Pennsylvania host specialty glassworks serving essential oil and pharmaceutical clients with borosilicate formats.
Germany
EU Green Deal packaging waste directives compress timelines for biodegradable material transitions in cosmetic applications. ECHA REACH substance restrictions mandate substitution assessments for legacy plasticizers in ball-bearing lubricants. North Rhine-Westphalia manufacturers retrofit production lines for PLA-PHA blend processing ahead of 2025 regulatory deadlines.
China
NMPA pharmaceutical packaging standards align with international stability protocols for topical drug delivery systems. SAMR enforces GB standards for cosmetic packaging chemical safety and dimensional consistency. Yangtze River Delta converters scale injection-blow molding capacity for mass-market deodorant roll-ons serving domestic and export markets.
India
BIS certification requirements for imported cosmetic packaging components create captive demand for domestic precision-molding expansion. CDSCO pharmaceutical packaging regulations mirror FDA container-closure integrity frameworks. Maharashtra and Gujarat host emerging converter clusters targeting regional personal care brand procurement.
France
Extended producer responsibility frameworks incentivize refillable roll-on format adoption in Paris and Lyon retail networks. ANSM pharmaceutical packaging standards govern topical drug delivery container specifications. Île-de-France specialty retailers pilot bulk dispensing infrastructure compatible with durable vessel reuse programs.
Roll-On Bottles Market Competitive Landscape
The competitive structure tilts toward precision-specialist incumbents with dual conventional-biopolymer capability. Glass-forming specialists compete on borosilicate durability and chemical inertness for pharmaceutical contracts. Plastic converters dominate unit economics through injection-blow molding efficiency. Strategic moves concentrate on capacity expansion for biodegradable production lines and partnerships with refill station network operators.
Among European glass-forming specialists, Gerresheimer and SGD Pharma exemplify premium-tier positioning through pharmaceutical qualification depth. Takemoto anchors Asian supply chain reliability through precision-molding specialization. These three occupy positions that bridge regulatory compliance capability with production scale across multiple continental markets.
| Leading Market Players |
|---|
| PauPack |
| Kaufman Container |
| Daxin |
| Richards Packaging |
| SGD Pharma |
| Gerresheimer |
| Stoelzle Glass Group |
| Takemoto |
| TricorBraun |
| Others |
Value Network & Pricing Analysis
Glass-to-plastic certification divergence separates pharmaceutical premium tiers from commodity cosmetic volumes, with borosilicate qualification timelines extending pricing power for European glassworks while injection-blow converters compete on throughput economics in mass-market deodorant segments. This material-performance split concentrates supply chain decisions around REACH compliance costs in Germany and BIS certification requirements in India, reshaping procurement geography for brand owners.
Pricing Analysis
Component-plus-service unbundling distinguishes pharmaceutical contracts from cosmetic spot purchases, with borosilicate roll-on bottles commanding sustained premiums through FDA container-closure integrity documentation while PET formats compete on three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on EMA stability protocol certification and stainless steel ball precision grades. Cost compression in plastic tiers is intensifying because of PLA-PHA feedstock volatility. Mass-market personal care buyers exhibit highest price sensitivity; pharmaceutical procurement teams prioritize chemical inertness guarantees over unit economics.
Supply Chain Analysis
Ocean freight rate volatility from Asia to Europe compresses margin pools for precision-molding converters dependent on just-in-time ball-bearing component deliveries. Production gravity centers on Germany for borosilicate glass, China for injection-blow PET capacity, and India for emerging domestic precision-molding expansion. Raw material flows draw from Saudi petrochemical feedstocks, Brazilian sugarcane for PLA biopolymers, and German specialty glass sands. Single-source vulnerability concentrates in European borosilicate furnace capacity for pharmaceutical-grade formats. Distribution runs through brand-owner direct procurement for pharmaceutical segments and distributor networks for cosmetic mass markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU Green Deal compliance costs accelerating German converter retooling and India's BIS certification creating captive domestic demand at lower regulatory overhead.
For Market Incumbents: Extend biopolymer processing capabilities ahead of 2025 ECHA substance restriction deadlines, converting conventional plastic lines to PLA-PHA blend capacity in North Rhine-Westphalia. Deepen backward integration into specialty glass sand sourcing to defend borosilicate margin pools against Asian furnace expansions. Prioritize dual-certification investment for FDA and EMA container-closure protocols to sustain pharmaceutical contract stickiness. For New Entrants and Emerging Players: Mid-tier cosmetic manufacturers in Maharashtra and Gujarat represent underserved buyer archetypes seeking BIS-compliant precision-molding alternatives to Chinese imports. White-space concentration appears in refillable engineered polymer formats for Paris and Berlin retail station networks. Target domestic Indian brand owners with localized technical service and rapid prototype turnaround as primary go-to-market angle. For Investors and Strategic Acquirers: Consolidation pressure builds where precision-tolerance capability overlaps with biopolymer processing scale, fragmenting viable supplier pools for high-volume cosmetic contracts. Five-to-ten year viability favors converters with dual conventional-biodegradable production lines and established pharmaceutical qualification depth. Acquisition target archetype: mid-cap German glass-forming specialists with underutilized borosilicate capacity. Signal to watch: ECHA candidate list expansion accelerating substitution assessments for legacy ball-bearing lubricants.| Strategic Initiative | Industry Significance |
|---|---|
| Biopolymer Production Scale-Up | PLA-PHA blend capacity expansion secures EU Green Deal compliance for German cosmetic manufacturers. |
| Precision-Molding Facility Expansion | Domestic Indian capacity captures BIS-certified demand from Maharashtra personal care brands. |
| Refill Station Network Partnership | Direct retail channel alignment in Paris and Berlin concentrates volume with durable vessel suppliers. |
| Pharmaceutical Qualification Investment | FDA and EMA container-closure documentation sustains premium positioning for borosilicate formats. |
| Backward Integration into Feedstocks | Specialty glass sand sourcing secures supply continuity for European pharmaceutical glassworks. |
Research Methodology
Coverage spans Germany, France, India, China, and the United States, with primary inputs from each market informing material transition timelines and regulatory compliance patterns. The approach combines structured interviews with cosmetic packaging procurement managers, pharmaceutical quality assurance directors, precision-molding plant engineers, and specialty glassworks operations heads with secondary validation from ECHA substance restriction databases, FDA container-closure guidance documents, BIS certification registries, and customs trade flow records. Bottom-up capacity assessments and top-down demand modeling were triangulated to establish market size parameters.
Rate-of-change decomposition separates volume growth from value expansion across the projection horizon, with CAGRs derived from segment-level modeling of material chemistry transitions, application-specific tolerance requirements, and closure type automation compatibility. Segmentation dimensions include product type, use case, closure configuration, and capacity tier, with additional modeling of regulatory framework clusters affecting qualification timelines. Forecast inputs incorporate EU Green Deal implementation pacing, ECHA candidate list update frequency, and refill station network pilot expansion rates.
Inputs from regulatory filing databases and converter capacity announcements were available through the study window; gaps in privately held biopolymer resin pricing introduce uncertainty bands around biodegradable segment forecasts. Forecasts reflect documented assumptions regarding ECHA substance restriction timelines and BIS certification enforcement intensity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Containers
Foldable Mailer Box Market
Packaging Containers
Acrylic Boxes Market
Packaging Containers
Food Portion Pack Market
Packaging Containers
Candle Box Market
Packaging Containers
Latin America Aerosol Cans Market
Packaging Containers
Can Holders Market
Packaging Containers
Shipping Mailers Market
Packaging Containers
Europe Punnet Trays Market
Packaging Containers
Self - Locking Trays Market
Packaging Containers
Pump Dispenser Market
Packaging Containers
Insulated Food Containers Market
Packaging Containers
Glass Vape Cartridge Market
Packaging Containers
VCI Bags Market
Packaging Containers
Double Seam Bowl Market
Packaging Containers
Africa Flexitank Market
Packaging Containers
Chalk Boxes Market