
 Cocoa Fiber Market | 2026-2036
Cocoa Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Cocoa Fiber Market Outlook
Asset-light toll processing and third-party milling arrangements is fragmenting competitive control across the cocoa fiber value chain. Barry Callebaut leverages captive bean processing infrastructure to secure upstream fiber supply. Cargill anchors its position through integrated cocoa liquor operations that generate fiber as a co-product. Healy Group competes as a specialized trader with focused European distribution.
Cocoa fiber comprises the lignocellulosic material recovered from cocoa bean husks and shells after winnowing, typically containing 40-60% dietary fiber with notable insoluble fractions. Food manufacturers incorporate it as a functional ingredient for moisture retention and texture modification in baked goods and chocolate formulations. Fiber powder leads product type demand due to superior dispersion properties in industrial batching. Dietary supplements represent the fastest-growing application as nutraceutical firms formulate prebiotic blends. Cosmetics applications occupy a premium niche where exfoliant-grade particle sizing commands higher value.
The EU Green Deal and REACH frameworks incentivize upcycled ingredient sourcing across European food processing. FDA GRAS self-affirmation pathways shape US market access for novel fiber ingredient applications. Stakeholders must monitor evolving fiber content labeling thresholds in major consuming jurisdictions and calibrate sourcing strategies accordingly.
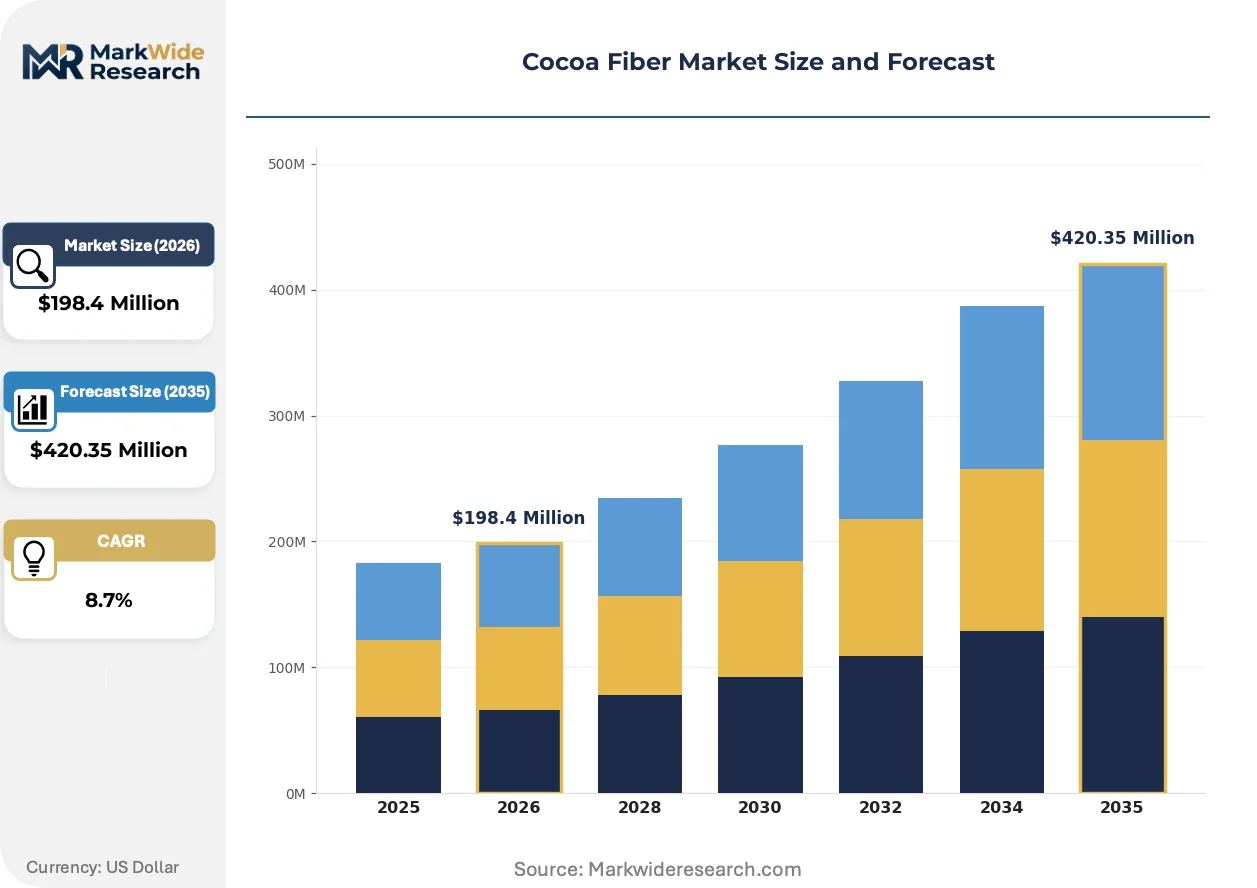
Market Dynamics
EU Green Deal mandates on circular economy sourcing are restructuring cocoa fiber procurement, forcing food processors to abandon virgin material streams in favor of upcycled husk-derived ingredients with verified carbon footprints.
Growth Catalysts
- REACH framework incentives:ECHA registration pathways for upcycled food ingredients reduce regulatory friction for cocoa fiber entrants, accelerating novel food dossier approvals across European member states.
- Bakery sector reformulation:Industrial bakers in Germany and France substitute cocoa fiber for modified starches to achieve clean-label claims while maintaining moisture retention in laminated dough systems.
- Prebiotic formulation science:Nutraceutical developers leverage cocoa fiber's fermentation-resistant oligosaccharide profile to formulate synbiotic blends targeting gut microbiome modulation.
Market Restraints
- Raw material geographic concentration:Cocoa husk supply clusters in Côte d'Ivoire and Ghana processing corridors, exposing fiber processors to West African bean harvest volatility and export license disruptions.
- FDA GRAS affirmation costs:Self-affirmation documentation requirements for novel fiber applications impose six-figure legal and toxicology burdens on US market entrants without guaranteed timeline certainty.
- Insoluble fiber substitution:Oat fiber and sugarcane bagasse compete at lower price points in high-volume bakery applications, compressing cocoa fiber's addressable market in cost-sensitive formulations.
Strategic Opportunities
- Cosmeceutical exfoliant grade:Micronization to 50-100 micron particle sizes opens premium dermabrasion applications where cocoa fiber commands 3-4x food-grade pricing from Paris and Milan formulators.
- EU CSRD disclosure mandates:Corporate sustainability reporting requirements drive Scope 3 emissions reduction targets, creating procurement pull for upcycled ingredients with negative carbon intensity scores.
- Japan functional foods channel:FOSHU and Foods with Function Claims regulatory frameworks permit gut health positioning for cocoa fiber, unlocking pharmacy and convenience store distribution networks.
Industry Challenges
- Microbiological stabilization capex:Steam sterilization and irradiation infrastructure requirements for pathogen control demand seven-figure capital deployment that fragments processor scale economics.
- Fiber content assay standardization:AOAC versus Englyst method discrepancies in dietary fiber quantification create label claim disputes between suppliers and food manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cocoa Fiber Market |
| Market Size in 2026 | $198.4 Million |
| Market Size in 2035 | $420.35 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Husk, Shell, Fiber Powder, Fiber Granules Application: Food, Cosmetics, Dietary Supplements, Animal Feed End User: Food Manufacturers, Cosmetics Companies, Nutraceutical Firms, Pet Food Producers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale Distributors |
| Companies Covered | Barry Callebaut, Cargill, Archer Daniels Midland Company, Healy Group, Greenfield Natural Ingredients, United Cocoa Processor, Jindal Cocoa, Interfiber, Touton S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cocoa Fiber Market Strategic Shifts
Digital traceability infrastructure and precision milling technologies are compressing quality variance in cocoa fiber supply, enabling specification-grade consistency that expands addressable applications beyond commodity bulk filler roles.
Near-infrared spectroscopy coupled with AI-driven sorting is virtualizing quality control workflows in cocoa husk processing facilities. European toll processors deploy these systems to real-time classify fiber fractions by lignin content and particle morphology. This virtualization eliminates batch-wise laboratory testing delays, compressing lead times from winnowing to finished powder.
EU Green Deal Farm to Fork Strategy binding targets on food waste reduction are mandating upcycled ingredient quotas in public procurement contracts. German federal catering contracts now specify minimum percentages of valorized agricultural byproducts. Chocolate manufacturers supplying these channels must document husk-to-fiber conversion rates in sustainability audits.
Direct contracting between fiber processors and artisan chocolate makers is displacing commodity exchange purchasing for premium grades. Small-batch bean-to-bar producers in Belgium and Switzerland negotiate fixed-volume agreements specifying husk provenance and roasting profiles. This channel shift concentrates margin capture upstream while fragmenting spot market liquidity for standard grades.
Cocoa Fiber Market Segmentation
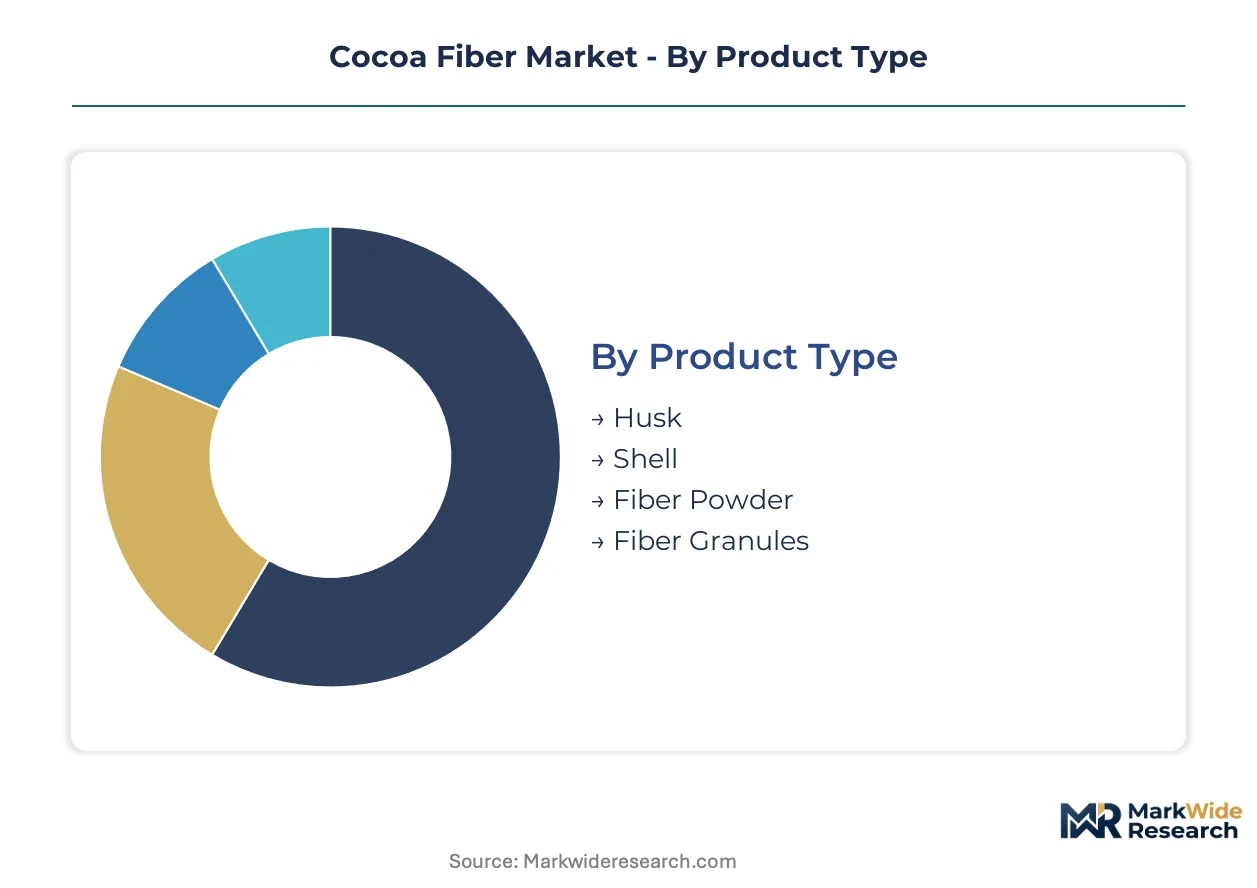
Cocoa fiber segmentation reflects divergent technical specifications across downstream industries. Food processors prioritize particle size and fiber assay consistency, while cosmetics formulators demand precise micronization and microbiological purity. Understanding these segment-specific requirements enables suppliers to align milling investments with margin capture opportunities.
Product Type:
Cycle times vary dramatically across product types, with fiber powder moving through production pipelines fastest due to standardized industrial batching protocols, while specialty granules face extended qualification timelines for novel applications.
- Fiber Powder:Fine-milled fractions with 40-60% total dietary fiber content and optimized dispersion profiles for industrial mixing. German chocolate manufacturers specify this grade for clean-label reformulations targeting moisture retention in praline fillings. AOAC-compliant fiber assays differentiate supplier tiers.
- Husk:Raw lignocellulosic material from winnowing operations requiring downstream processing for food-grade applications. Côte d'Ivoire and Ghana processing corridors supply bulk volumes to European toll processors under sustainability audit requirements. Raw material volatility constrains pricing predictability.
- Shell:Harder fractions separated during bean cracking with higher lignin concentrations suitable for abrasive applications. French and Italian cosmetics formulators source this grade for exfoliant formulations commanding premium pricing.
- Fiber Granules:Coarse-cut particles targeting animal feed and select bakery applications where texture modification outweighs dispersion requirements. Pet food producers in Germany integrate this grade for fiber enrichment claims.
Fiber powder anchors the volume base while fiber granules gain share at the steepest rate as animal feed applications expand.
Application:
Cost tiers separate these segments sharply, with cosmetics applications absorbing 3-4x food-grade pricing for validated particle morphology and pathogen-free certification.
- Food:Bakery and confectionery manufacturers incorporate cocoa fiber as a bulking agent and moisture binder in clean-label reformulations. French industrial bakers substitute this ingredient for modified starches in laminated dough systems. EU Green Deal procurement mandates accelerate uptake in public catering contracts.
- Dietary Supplements:Nutraceutical developers formulate prebiotic blends leveraging cocoa fiber's fermentation-resistant oligosaccharide profile. Synbiotic positioning targets gut microbiome modulation claims. Japan's FOSHU framework permits functional health positioning in pharmacy channels.
- Cosmetics:Premium dermabrasion and exfoliant applications demand 50-100 micron particle sizing with validated microbiological stability. Paris and Milan formulators pay substantial premiums for exfoliant-grade material with documented roasting provenance.
- Animal Feed:Pet food producers utilize coarser fractions for fiber enrichment in premium positioning strategies. German and Dutch manufacturers specify sustainable sourcing credentials for consumer-facing packaging claims.
Food applications anchor the volume base while dietary supplements expand most quickly on prebiotic formulation science advances.
End User:
Customer concentration patterns shape procurement leverage, with multinational food manufacturers commanding volume discounts while artisan chocolate makers negotiate provenance-specific premiums.
- Food Manufacturers:Industrial-scale chocolate producers and bakery groups specify fiber powder for standardized reformulation pipelines. German federal catering contracts mandate upcycled ingredient quotas that concentrate procurement pull.
- Nutraceutical Firms:Prebiotic and synbiotic developers require validated fiber content assays and fermentation profile documentation. Regulatory pathways through EFSA novel food dossiers shape supplier qualification timelines.
- Cosmetics Companies:Formulators in France, Italy, and Switzerland source exfoliant-grade material with particle size distributions validated for dermabrasion efficacy. Premium pricing reflects micronization capex and irradiation sterilization costs.
- Pet Food Producers:Premium positioning strategies drive fiber enrichment claims in dog and cat nutrition. Sustainability credentials influence consumer purchase decisions in German and Benelux markets.
Food manufacturers anchor the volume base while nutraceutical firms climb the fastest on gut health positioning expansion.
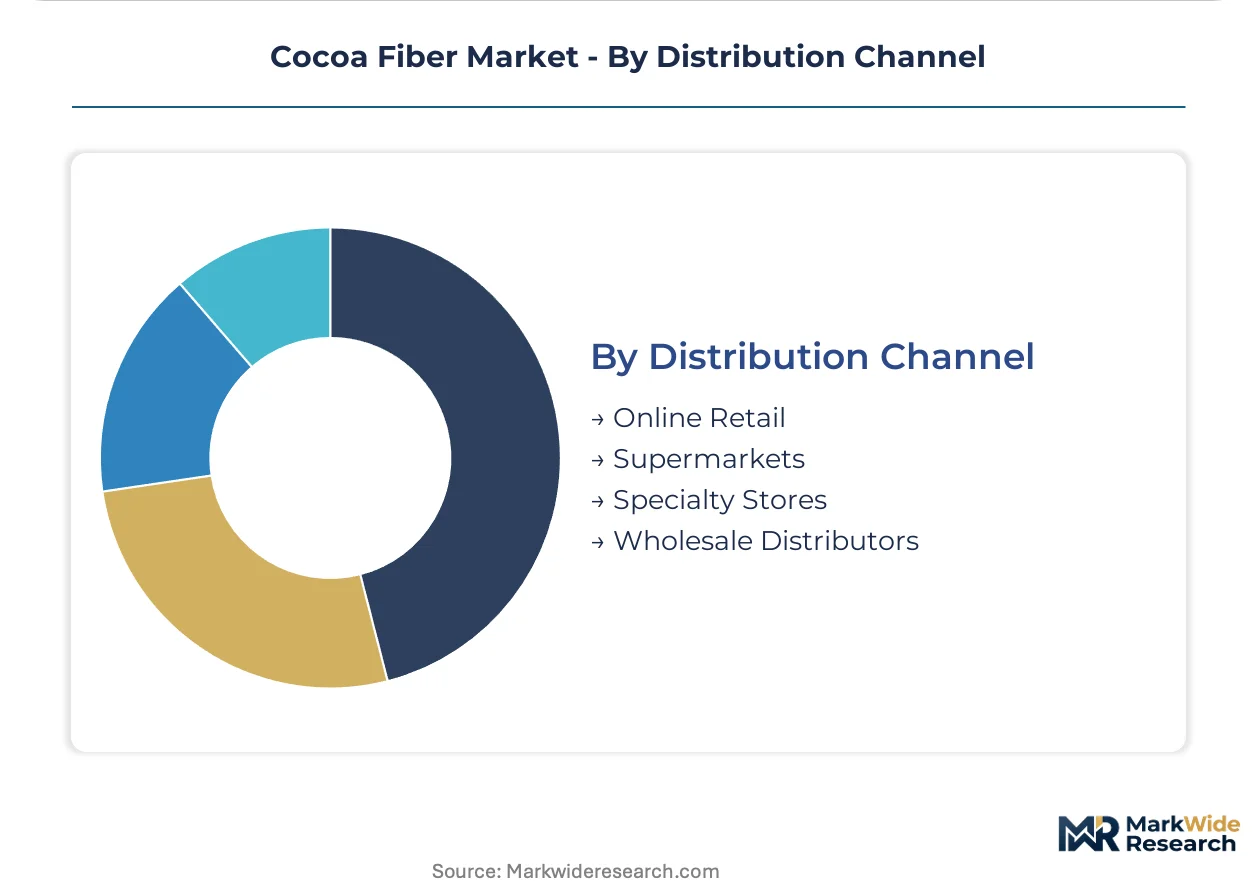
Distribution Channel:
Supply chain configuration determines margin distribution, with wholesale distributors capturing logistics value while direct contracting fragments spot market liquidity for premium grades.
- Wholesale Distributors:Industrial ingredient specialists manage bulk logistics for food manufacturers with standardized specification requirements. Inventory pooling reduces lead time volatility for high-volume buyers.
- Specialty Stores:Artisan and small-batch producers source provenance-specific grades through regional traders with roasting profile documentation. Belgian and Swiss bean-to-bar makers negotiate fixed-volume agreements directly.
- Online Retail:E-commerce platforms serve nutraceutical and cosmetics formulators with smaller batch requirements and rapid reorder cycles. Digital traceability infrastructure enables specification-grade consistency validation.
- Supermarkets:Limited penetration for finished cocoa fiber products; channel relevance concentrates in co-packed consumer-facing fiber supplements with established brand recognition.
Wholesale distributors anchor the volume base while specialty stores gain share fastest on direct contracting trends between fiber processors and artisan producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cocoa fiber trade flows reflect a structural deficit in processing regions versus surplus in bean-origin corridors. Germany and Switzerland import husk volumes for powder production while West African origins concentrate raw material supply. Regulatory frameworks in destination markets increasingly govern procurement terms.
Germany
Industrial bakers and chocolate manufacturers in Cologne and Hamburg drive cocoa fiber uptake for clean-label reformulations. The EU Green Deal Farm to Fork Strategy mandates upcycled ingredient quotas in federal catering contracts. North Rhine-Westphalia hosts toll processors supplying standardized fiber powder to multinational food manufacturers.
Switzerland
Bean-to-bar chocolate makers in Zurich and Geneva negotiate direct husk contracts specifying roasting provenance for premium fiber grades. Swissmedic oversight shapes cosmetics-grade pathogen standards for exfoliant applications. Basel-area processors command premium pricing for micronized fractions targeting dermabrasion formulators.
France
Paris and Lyon cosmetics laboratories absorb exfoliant-grade cocoa fiber at multiples of food-grade pricing. ANSM registration pathways for novel cosmetic ingredients filter supplier qualification. Hauts-de-France industrial bakers substitute cocoa fiber for modified starches in laminated dough systems under clean-label pressure.
United States
Prebiotic nutraceutical developers in New Jersey and California formulate synbiotic blends leveraging cocoa fiber fermentation profiles. FDA GRAS self-affirmation requirements impose documentation burdens on novel fiber entrants. Chicago-area distributors manage bulk logistics for standardized industrial specifications.
Japan
Functional food manufacturers in Tokyo and Osaka pursue FOSHU approvals for gut health positioning of cocoa fiber blends. METI guidelines on Foods with Function Claims enable pharmacy and convenience store distribution. Osaka-based formulators integrate fiber into synbiotic products targeting microbiome modulation claims.
Cocoa Fiber Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with captive processing assets. The vendor base stratifies between integrated cocoa processors with bean-to-fiber conversion capabilities and specialized traders focused on European distribution logistics. Three archetypes dominate: vertically integrated chocolate manufacturers securing upstream fiber supply, toll processors deploying third-party milling infrastructure, and ingredient traders managing specification-grade consistency for cosmetics and nutraceutical channels. Competitive moves center on backward integration into husk sourcing and capacity expansion in micronization capabilities for premium grades.
Among integrated processors, Barry Callebaut and Cargill exemplify the captive supply archetype through bean processing infrastructure that generates fiber as a co-product. Healy Group occupies a position within the specialized trading tier, anchoring European distribution networks for specification-grade material. These three entities represent distinct competitive vectors: integrated processing scale, logistics specialization, and provenance-negotiated premium capture.
| Leading Market Players |
|---|
| Barry Callebaut |
| Cargill |
| Archer Daniels Midland Company |
| Healy Group |
| Greenfield Natural Ingredients |
| United Cocoa Processor |
| Jindal Cocoa |
| Interfiber |
| Touton S.A. |
| Others |
Value Chain & Pricing Dynamics
Rotterdam-Antwerp freight corridors carry husk volumes from West African bean processing clusters, with container rate volatility feeding directly into European toll processor margins and creating three-tier spreads between food-grade powder, cosmetics-grade micronized fractions, and raw husk bulk.
Pricing Analysis
Industrial OEM buyers anchor cocoa fiber pricing structures around long-term offtake contracts indexed to bean processing volumes. Price differentiation separates cosmetics-grade material with Swissmedic-validated pathogen clearance from standard food-grade powder and unprocessed husk feedstock. Cost compression in food-grade tiers is intensifying because oat fiber and sugarcane bagasse compete at lower price points in high-volume bakery applications. Contract manufacturers exhibit highest price sensitivity, while Paris and Milan cosmetics formulators absorb substantial premiums for provenance-documented exfoliant grades.
Supply Chain Analysis
Toll processing concentration in Germany, Belgium, and the Netherlands holds European milling capacity for specification-grade fiber production. Raw material flows draw from Côte d'Ivoire and Ghana winnowing operations, with logistics tethered to Abidjan and Tema port infrastructure. Single-source vulnerability concentrates in West African bean harvest corridors exposed to export license disruptions and seasonal volatility. Distribution runs through wholesale industrial ingredient specialists managing bulk logistics for multinational food manufacturers, supplemented by direct contracting channels for artisan bean-to-bar producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cocoa fiber sits in early-cycle expansion as EU Green Deal procurement mandates create structural demand pull for upcycled ingredients with verified carbon footprints, accelerating penetration beyond commodity filler applications into premium functional food and cosmeceutical channels.
For Market Incumbents: Entrench supply security through backward integration into West African husk sourcing and capacity expansion in micronization infrastructure for cosmetics-grade production. Oat fiber substitution in cost-sensitive bakery applications threatens margin capture in standard grades, demanding certification investment in EU organic and carbon-negative labeling to defend pricing power.
For New Entrants and Emerging Players: Japan's FOSHU regulatory pathway offers the most penetrable geographic entry point, with functional gut health positioning enabling pharmacy and convenience store distribution networks underserved by established European suppliers. Direct contracting with Tokyo and Osaka nutraceutical formulators bypasses wholesale distributor consolidation.
For Investors and Strategic Acquirers: Specialized toll processors with Swissmedic and ANSM cosmetics-grade certifications represent the priority acquisition archetype, capturing 3-4x food-grade pricing multiples from Milan and Paris dermabrasion formulators. Watch EFSA novel food dossier approval velocity as the inflection signal for prebiotic supplement channel expansion timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Husk Sourcing | Captures upstream margin from Côte d'Ivoire and Ghana processing corridors while securing supply against export volatility. |
| Micronization Capacity Expansion | Enables 50-100 micron particle production for Swissmedic-compliant cosmetics grades commanding premium pricing from Milan formulators. |
| EFSA Novel Food Dossier Filing | Unlocks prebiotic health claims in European dietary supplements, accelerating nutraceutical channel penetration. |
| Direct Contracting with Artisan Producers | Bypasses wholesale distributor margin capture through provenance-specific agreements with Belgian and Swiss bean-to-bar makers. |
| Digital Traceability Infrastructure Deployment | Supports EU Green Deal sustainability audit requirements for federal catering contracts in Germany and France. |
Study Parameters
The analysis maps cocoa fiber product types, application segments, and regional regulatory clusters, each validated through primary interviews with toll processing plant managers, chocolate manufacturer procurement leads, cosmetics formulator R&D directors, and nutraceutical regulatory affairs specialists. Secondary sources include EFSA novel food dossier filings, EU Green Deal Farm to Fork Strategy procurement guidelines, Swissmedic cosmetics ingredient registrations, and customs trade data for husk and fiber powder volumes. Bottom-up volume modeling triangulates against top-down value estimates derived from processor capacity disclosures and end-use pricing benchmarks.
Assumptions hold EU Green Deal binding targets on food waste reduction and upcycled ingredient quotas at current enforcement trajectories, with REACH framework incentives for novel food ingredients remaining stable across the analysis window. Segmentation dimensions modeled include product type, application, end user, and distribution channel, with geographic regulatory clusters treated as scenario variables. CAGRs derive from volume-demand elasticity coefficients calibrated to bakery sector reformulation rates and prebiotic supplement launch pipelines, incorporating bean harvest volatility and freight cost indices as sensitivity inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by integrated cocoa processors into captive fiber supply would shift outcomes through spot market liquidity fragmentation. Cross-checking against EFSA novel food approval timelines and EU member state procurement contract award data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Murumuru Butter Market
Ingredients
Sesame Oil Market
Ingredients
Casein Glycomacropeptide Market
Ingredients
Omega 6 Market
Ingredients
Asia-Pacific Soy Protein Market
Ingredients
Cheese Ripening Enzymes Market
Ingredients
South Africa Sodium Reduction Ingredients Market
Ingredients
Vegetable Fats Market
Ingredients
Torula Yeast Market
Ingredients
Botanical Ingredients Market
Ingredients
Non-GMO Oil Market
Ingredients
Asia-Pacific Prebiotic Ingredients Market
Ingredients
Anti-Aging Ingredients Market
Ingredients
Mediterranean Marine Ingredients for Pet Health Market
Ingredients
Bean Flour Market
Ingredients
Industrial and Bar-B-Que Charcoal Market