
 Asia-Pacific Protein Market | 2026-2036
Asia-Pacific Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Protein Market Outlook
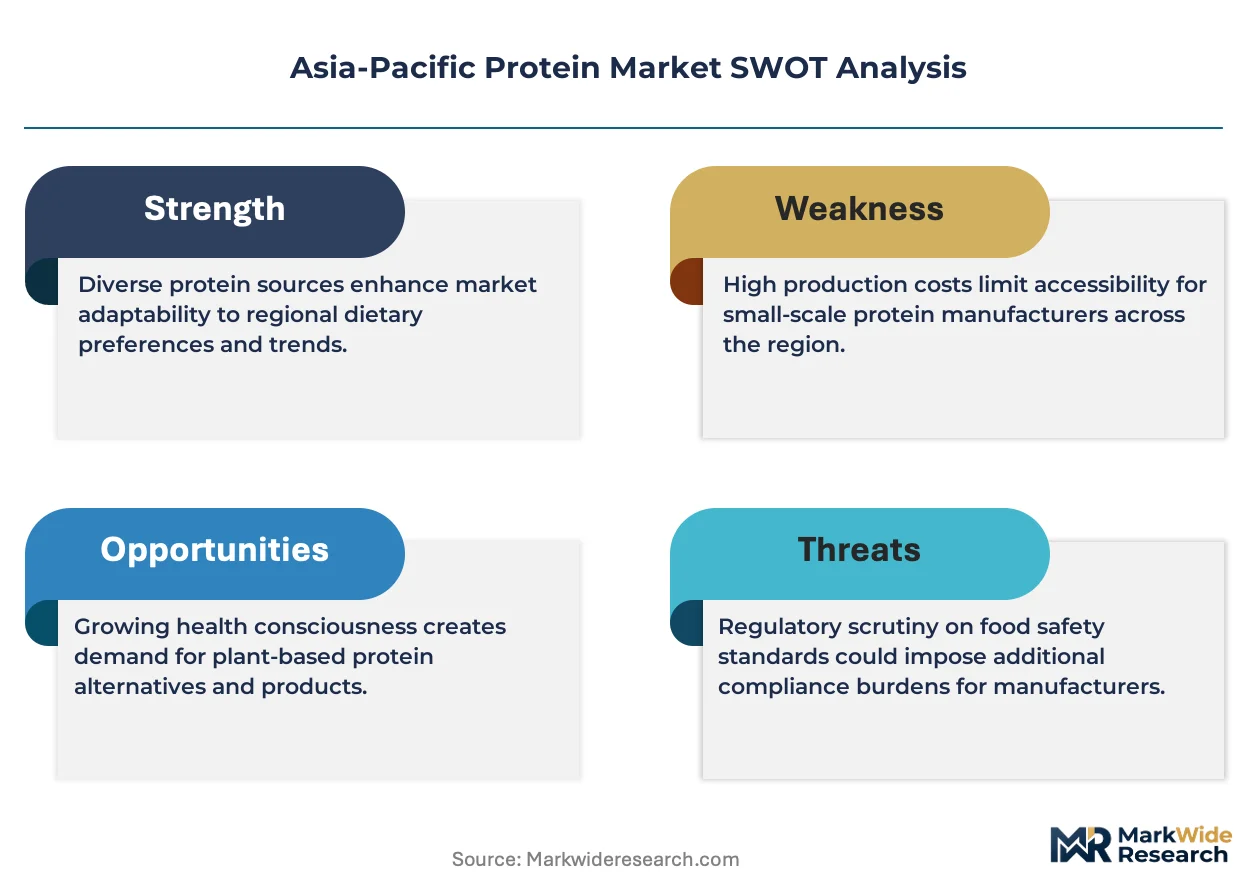
Ingredient formulation services is rewriting margin distribution across the Asia-Pacific protein value chain, pulling returns away from commodity trading and toward customized blends. Kerry Group plc leverages its regional application labs to capture premium pricing on functional protein systems. Wilmar International Ltd anchors supply security through its integrated oilseed crushing and fractionation footprint across Southeast Asia. dsm-firmenich differentiates via fermentation-derived protein ingredients and precision nutrition capabilities.
Asia-Pacific protein encompasses amino acid chains derived from animal, plant, insect, and marine biomass, typically processed through enzymatic hydrolysis, extraction, or fermentation to achieve specified protein content, digestibility scores, and functional properties such as emulsification or gelation. These inputs serve food fortification, clinical nutrition, feed conversion efficiency, and therapeutic applications. Animal protein still occupies the largest revenue pool, though plant protein from legumes and grains is registering the fastest volume expansion as formulators reduce reliance on dairy and meat isolates. Marine protein, sourced from fishmeal and emerging krill or algae processes, sustains niche margins in pharmaceutical-grade applications and premium aquaculture feed.
China's SAMR enforces GB standards for protein content claims and novel food ingredient approvals, while India's FSSAI mandates labeling and safety protocols for protein-fortified products and supplements. Japan's METI coordinates with PMDA on functional food registrations that include protein-based health claims, creating a multi-layered compliance environment. Stakeholders must track how divergent national approval pathways for alternative proteins reshape market access timelines and localization requirements.
Market Dynamics
China's dual carbon goals and stricter GB standards from SAMR are compressing timelines for animal protein expansion while accelerating capital flows into fermentation-derived and plant-based alternatives across the region.
Growth Catalysts
- FSSAI protein fortification mandates:India's food safety regulator is tightening labeling requirements for protein-enriched products, compelling domestic manufacturers to reformulate portfolios and expand isolate sourcing.
- Precision fermentation scale-up:Bioreactor capacity additions in Singapore and South Korea are enabling commercial volumes of whey-identical proteins without dairy supply chains.
- Sports nutrition end-use expansion:Gym penetration rates in Vietnam and Indonesia are climbing fastest in Southeast Asia, pulling isolate demand into previously underdeveloped channels.
Market Restraints
- Soybean import concentration:Crushing capacity across Southeast Asia depends heavily on Brazilian and Argentinian seed flows, exposing margin structures to currency and freight volatility.
- GB novel food approval timelines:SAMR's extended safety assessment protocols for insect and microbial proteins delay product launches by 18-24 months versus conventional ingredients.
- Functional parity gaps:Plant proteins from rice and pea still fail to match dairy isolates on leucine density and foaming stability, limiting penetration in premium clinical nutrition.
Strategic Opportunities
- Philippines aquaculture feed gap:Marine protein demand from shrimp and tilapia producers exceeds domestic fishmeal supply, creating import substitution openings for krill and algae processors.
- Japan METI functional food registration:Protein-specific FOSHU claims for sarcopenia prevention command shelf price premiums and lock in multi-year offtake contracts with aged-care distributors.
- Direct-to-brand e-commerce channels:Cross-border platforms are collapsing traditional importer-distributor layers, allowing ingredient suppliers to capture margin previously lost to intermediaries.
Industry Challenges
- Bioprocess engineering talent scarcity:Fermentation scale-up expertise concentrates in Singapore and Shanghai, forcing regional players to bid against pharmaceutical manufacturers for the same technical workforce.
- Halal certification complexity:Multi-country supply chains serving Indonesia and Malaysia must navigate MUI and JAKIM audit requirements that lack mutual recognition, duplicating compliance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Protein Market |
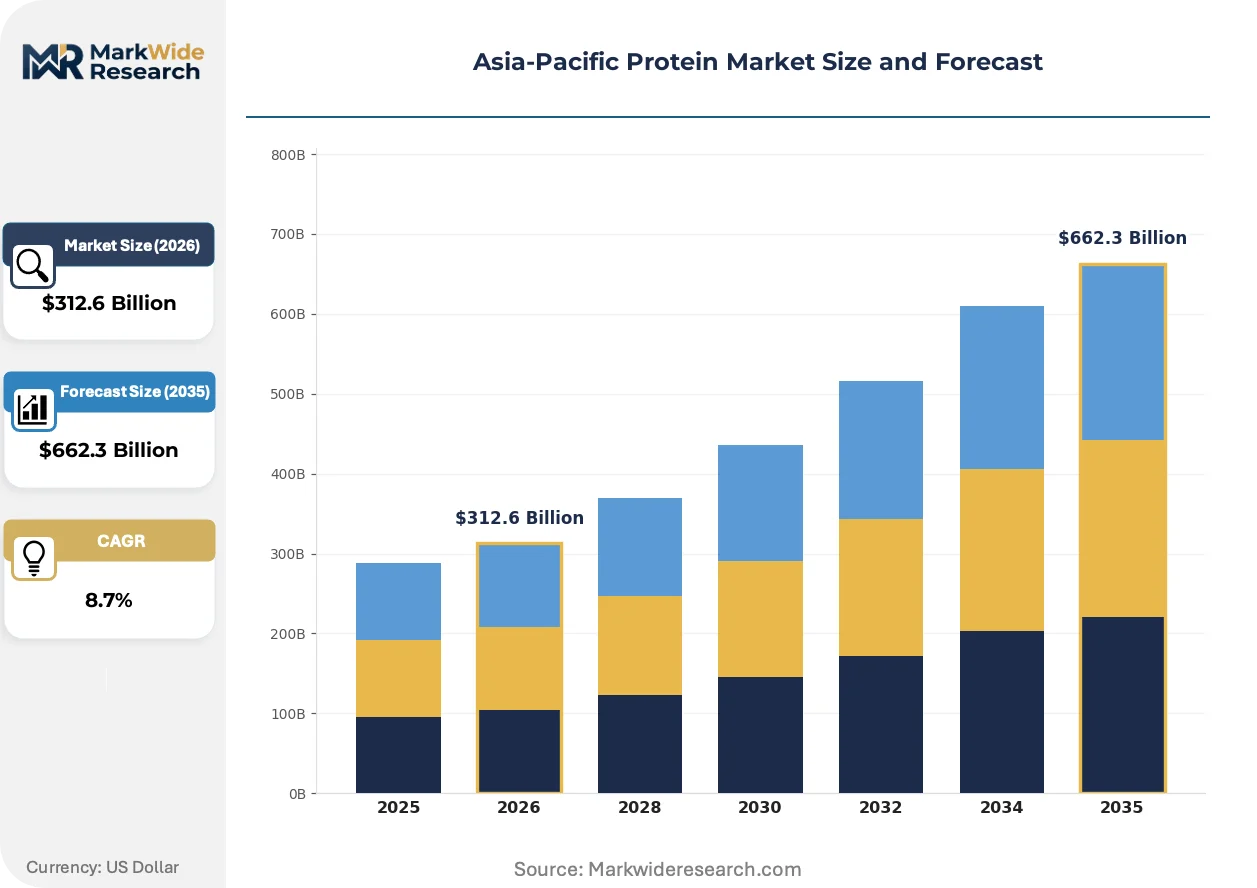
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $662.3 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Animal Protein, Plant Protein, Insect Protein, Marine Protein End Use: Food & Beverage, Dietary Supplements, Animal Feed, Pharmaceuticals Source: Meat, Dairy, Legumes, Grains Form: Powder, Liquid, Bar, Capsule |
| Companies Covered | Ingredion, Glanbia PLC, Archer Daniels Midland Company, Roquette Frères, Fonterra Co-operative Group Limited, Kerry Group plc, Wilmar International Ltd, dsm-firmenich, Cargill, Incorporated, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Protein Market Strategic Shifts
Fermentation infrastructure and enzymatic processing advances are converging to collapse cost curves for non-animal proteins, while regulatory fragmentation across national approval pathways is forcing suppliers to build parallel compliance capabilities.
Precision fermentation is hybridizing protein production economics by decoupling amino acid sequences from agricultural land use. Pharmaceutical-grade bioreactor operators in South Korea and Singapore are repurposing capacity for food proteins, achieving titers that undercut dairy isolate costs at commercial scale. This technology is hybridizing competitive positioning between traditional commodity traders and biotech-enabled ingredient specialists.
Japan's PMDA and METI coordination on FOSHU registrations is tightening evidentiary standards for protein health claims, particularly around muscle maintenance and immune function. Manufacturers must now fund clinical trials domestically rather than relying on foreign data packages, extending time-to-market for imported ingredients. Aged-care and sports nutrition segments are responding by deepening partnerships with Japanese contract research organizations to accelerate dossier preparation.
Brand-direct procurement from ingredient suppliers is displacing layered distributor networks across Southeast Asia. E-commerce platforms and private-label manufacturers in Thailand and Vietnam now contract directly with fractionation facilities, bypassing regional trading houses that previously controlled price discovery and quality arbitration. This pattern is most visible in plant protein isolates, where specification transparency and batch consistency have become primary selection criteria over relational contracting.
Asia-Pacific Protein Market Segmentation
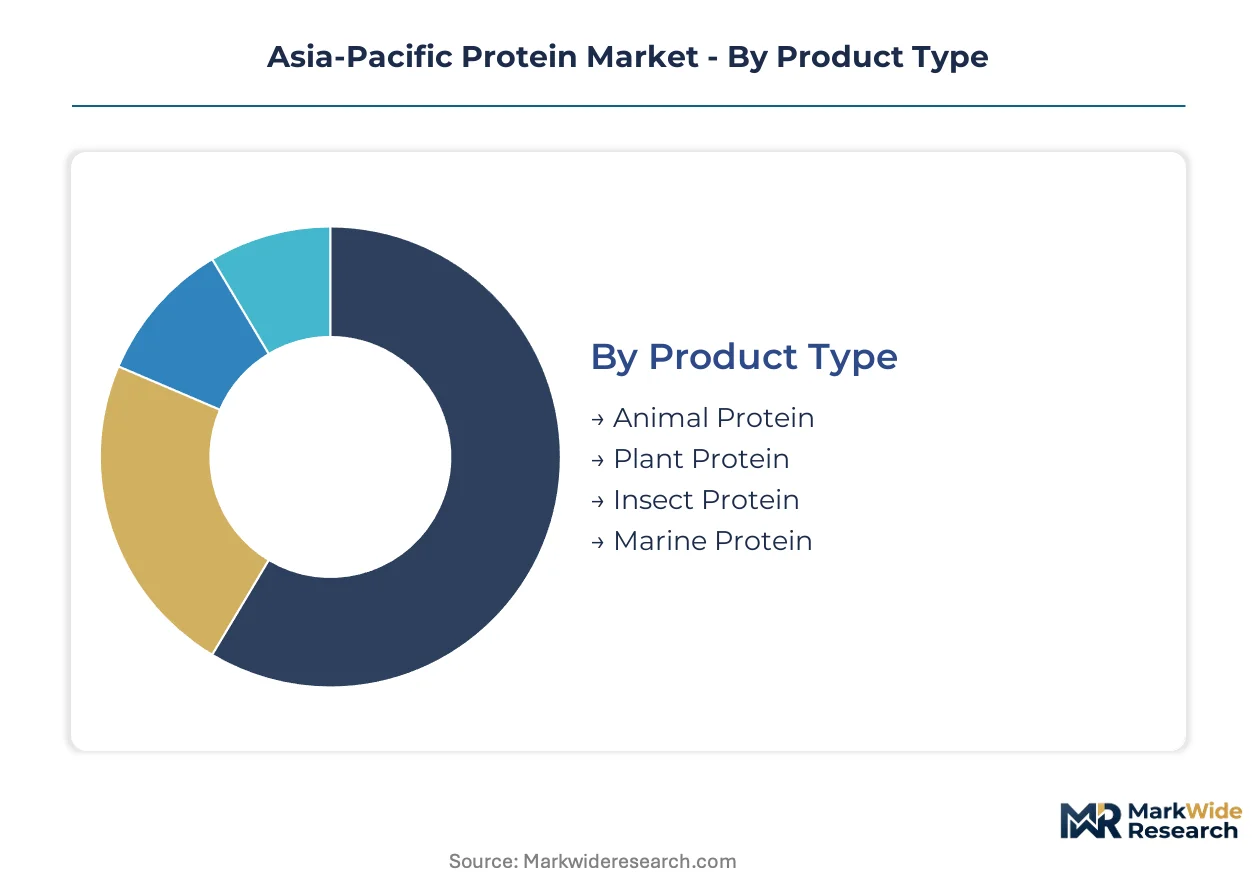
Protein segmentation across Asia-Pacific reflects divergent supply chain economics and regulatory maturity. Each dimension—product origin, end-use application, biological source, and physical form—carries distinct margin profiles and compliance burdens that reshape supplier strategies.
Product Type:
Mature isolates from animal and marine biomass anchor current revenue pools, while emerging fermentation and insect platforms are recalibrating capital allocation timelines.
- Animal Protein:Dairy and meat isolates deliver complete amino acid profiles with PDCAAS scores exceeding 0.9, satisfying clinical nutrition specifications in Japan's aged-care facilities. China's SAMR enforcement of stricter GB standards is compressing expansion timelines for conventional livestock-derived production.
- Plant Protein:Pea, rice, and soy concentrates from Wilmar's Southeast Asian crushing network are displacing dairy in sports nutrition formulations across Vietnam and Indonesia. Functional parity gaps on leucine density and foaming stability still limit penetration in premium medical applications.
- Insect Protein:Black soldier fly larvae meal from Malaysian and Thai facilities serves aquaculture and pet food channels, though SAMR's 18-24 month novel food approval timelines delay human-grade launches.
- Marine Protein:Krill and algae-derived isolates from South Korean bioreactors command pharmaceutical-grade margins in pharmaceutical applications and premium shrimp feed.
Animal protein handles the majority of throughput; plant protein is expanding most quickly on share as formulators reduce dairy dependence.
End Use:
Application-driven procurement patterns split between specification-heavy regulated channels and volume-driven commodity offtake.
- Food & Beverage:Fortified dairy alternatives and bakery applications in India's urban centers are absorbing expanded pea and rice isolate capacity following FSSAI protein fortification mandates.
- Dietary Supplements:Sports nutrition powders and ready-to-drink formulations for Vietnam's climbing gym penetration rates are pulling isolate demand through direct-to-brand e-commerce channels.
- Animal Feed:Aquaculture operations in the Philippines exceed domestic fishmeal supply, creating import substitution demand for krill and algae processors.
- Pharmaceuticals:PMDA-coordinated FOSHU registrations for sarcopenia prevention command shelf price premiums and lock in multi-year contracts with Japanese aged-care distributors.
Food and beverage absorbs the largest volume base; dietary supplements are climbing the fastest as gym culture penetrates Southeast Asia.
Source:
Biological origin determines supply security exposure and halal certification complexity across multi-country supply chains.
- Meat:Beef and poultry isolates face dual carbon policy pressure in China while serving established processed food manufacturers in Australia.
- Dairy:Whey and casein from New Zealand and Australian processors maintain functional performance benchmarks that plant alternatives still fail to match on foaming stability.
- Legumes:Soy crushing capacity across Southeast Asia depends heavily on Brazilian seed flows, exposing margin structures to currency and freight volatility.
- Grains:Rice protein from Thai fractionation facilities is gaining formulation share in hypoallergenic infant nutrition applications.
Dairy retains the highest value per kilogram; legumes are gaining share fastest as crushing infrastructure expands regionally.
Form:
Physical presentation dictates manufacturing equipment requirements and distribution economics across ambient and cold chains.
- Powder:Bulk isolates for industrial formulators dominate export volumes from Singapore and Malaysian toll-processing facilities.
- Liquid:Ready-to-drink protein beverages for convenience channels in South Korea and Japan require aseptic filling capacity that concentrates production among established dairy processors.
- Bar:Extruded protein bars for sports nutrition in Indonesia and Thailand bypass distributor layers through cross-border e-commerce platforms.
- Capsule:Hard-shell gelatin and vegetable capsules for pharmaceutical-grade applications in Japan carry the steepest evidentiary requirements under PMDA guidance.
Powder commands the greatest tonnage; bars are expanding most rapidly as direct-to-consumer channels collapse traditional distribution layers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across Asia-Pacific protein markets. Indian buyers demonstrate acute sensitivity to isolate premiums, while Japanese aged-care distributors absorb steep markups for FOSHU-certified ingredients without volume contraction.
China
Dual carbon goals and SAMR's stricter GB standards are compressing timelines for conventional livestock-derived protein expansion. Novel food approval protocols for insect and microbial proteins extend safety assessments by 18-24 months versus conventional ingredients. Yangtze River Delta bioreactor clusters near Shanghai are repurposing pharmaceutical-grade fermentation capacity for whey-identical proteins.
India
Rising disposable incomes and expanding urban populations are reshaping protein consumption patterns in Mumbai and Delhi-NCR. FSSAI protein fortification mandates are compelling domestic manufacturers to reformulate portfolios and expand isolate sourcing. Crushing infrastructure in Gujarat and Maharashtra is absorbing expanded pea and rice fractionation capacity.
Japan
PMDA-coordinated FOSHU registrations for sarcopenia prevention command shelf price premiums in Tokyo and Osaka aged-care channels. METI evidentiary standards now require domestically funded clinical trials rather than foreign data packages. Kanto region contract research organizations are deepening partnerships with ingredient suppliers to accelerate dossier preparation.
South Korea
Precision fermentation scale-up is achieving commercial titers that undercut dairy isolate costs at bioreactor facilities near Seoul and Busan. MFDS regulatory alignment with pharmaceutical-grade standards is attracting repurposed capacity from antibiotic and enzyme manufacturers. Daegu-Gyeongbuk industrial complexes are concentrating enzymatic processing expertise.
Vietnam
Gym penetration rates are climbing fastest in Southeast Asia, pulling isolate demand through direct-to-brand e-commerce channels in Ho Chi Minh City and Hanoi. Sports nutrition powders and ready-to-drink formulations are bypassing traditional importer-distributor layers. Cross-border platforms are collapsing price discovery functions previously controlled by regional trading houses.
Asia-Pacific Protein Market Competitive Environment
Capability concentration sits with fermentation-enabled specialists; scale advantage sits with integrated oilseed processors. The vendor base stratifies across three tiers: global ingredient conglomerates with regional application labs, Southeast Asian crushing and fractionation operators, and precision fermentation startups with biotech licensing models. Dominant competitive moves include backward integration into oilseed origination and strategic partnerships with e-commerce platforms to bypass distributor layers.
Among the integrated processors, Wilmar International Ltd anchors supply security through its Southeast Asian crushing footprint. Kerry Group plc occupies a position within the formulation services tier, leveraging regional application labs to capture premium pricing. dsm-firmenich sits within the fermentation-derived segment, differentiating via precision nutrition capabilities and bioreactor partnerships in Singapore and South Korea.
| Leading Market Players |
|---|
| Ingredion |
| Glanbia PLC |
| Archer Daniels Midland Company |
| Roquette Frères |
| Fonterra Co-operative Group Limited |
| Kerry Group plc |
| Wilmar International Ltd |
| dsm-firmenich |
| Cargill, Incorporated |
| Others |
Value Chain & Pricing Dynamics
Brazilian and Argentinian soybean origination anchors crushing economics across Southeast Asia, concentrating margin capture with integrated processors who control seed flows and fractionation capacity rather than commodity traders or brand formulators. Wilmar International Ltd's regional crushing footprint exemplifies this upstream leverage, enabling premium pricing on isolate specifications that bypass spot market volatility.
Pricing Analysis
After-sales formulation services now drive lifetime value for ingredient suppliers, with Kerry Group plc's regional application labs commanding recurring revenue streams beyond commodity isolate sales. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade certifications separates premium FOSHU-registered isolates in Japan from standard sports nutrition powders in Vietnam and economy aquaculture meals in the Philippines. Pricing pressure stems from direct-to-brand e-commerce channels collapsing traditional distributor markups, compressing margins for trading houses while benefiting toll-processors with specification transparency. Indian buyers demonstrate acute price sensitivity on isolate premiums, whereas Japanese aged-care distributors absorb steep FOSHU-certified markups without volume contraction.
Supply Chain Analysis
Upstream feedstock dependence centers on Brazilian and Argentinian soybean flows for Southeast Asian crushing capacity, South Korean and Singaporean bioreactor clusters for fermentation-derived proteins, and Thai and Malaysian insect meal facilities for aquaculture applications. Raw material inputs include oilseeds, pharmaceutical-grade fermentation media, and black soldier fly larvae substrate. Supply chain risk concentrates in single-source vulnerability for novel protein approvals, with SAMR's extended safety assessment protocols creating 18-24 month launch delays versus conventional ingredients. Distribution runs through direct-to-brand e-commerce platforms that displace layered importer-distributor networks across Thailand and Vietnam.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific protein sits in early-cycle expansion, with precision fermentation scale-up and sports nutrition penetration across Southeast Asian gym cultures providing structural tailwinds for isolate demand.
For Market Incumbents: Pre-empt fermentation-enabled entrants by repurposing pharmaceutical-grade bioreactor capacity for whey-identical proteins before cost curves collapse dairy isolate premiums. Anchor supply security through backward integration into oilseed origination, capturing crushing margins that commodity traders currently extract. Defend formulation services revenue by deepening partnerships with Japanese contract research organizations to accelerate FOSHU dossier preparation against regulatory tightening. For New Entrants and Emerging Players: Establish a beachhead in Philippines aquaculture feed, where marine protein demand from shrimp and tilapia producers exceeds domestic fishmeal supply and import substitution openings remain underexploited. Target Vietnam's climbing gym penetration rates through direct-to-brand e-commerce channels that bypass entrenched distributor layers controlling traditional sports nutrition offtake. Lead with krill and algae-derived isolates that command pharmaceutical-grade margins while building specification credibility for downstream expansion. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision fermentation startups possessing bioreactor partnerships in Singapore and South Korea but lacking commercial offtake scale. Long-term viability favors platforms with regulatory dossier capabilities across multiple national approval pathways rather than single-market specialists. Watch halal certification harmonization between Indonesia's MUI and Malaysia's JAKIM as an inflection signal for multi-country supply chain economics.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Repurposed pharmaceutical bioreactors in South Korea achieve titers undercutting dairy isolate costs. |
| Backward Integration into Oilseed Origination | Wilmar's Southeast Asian crushing footprint anchors supply security against Brazilian currency volatility. |
| FOSHU Registration Partnership | Kanto region contract research organizations accelerate dossier preparation for Japanese aged-care channels. |
| Direct-to-Brand E-Commerce Launch | Cross-border platforms in Thailand and Vietnam collapse distributor layers previously controlling price discovery. |
| Halal Certification Harmonization | MUI-JAKIM mutual recognition would eliminate duplicated compliance costs for Indonesia-Malaysia supply chains. |
Study Parameters
Initial hypotheses were tested against primary input from ingredient procurement managers at food and beverage manufacturers, regulatory affairs leads navigating SAMR and FSSAI approval pathways, formulation scientists at regional application labs, and aquaculture feed operations directors across Southeast Asia, then refined through secondary validation against customs trade data, GB and FSSAI regulatory filings, bioreactor capacity announcements, and gym penetration statistics from fitness industry databases. Bottom-up isolate volume estimates from crushing facilities and toll-processors were triangulated against top-down protein fortification mandate implementation timelines.
Demand-supply-balance framing anchored the analytical framework across the analysis window, modeling protein segmentation by biological source, end-use application, physical form, and certification grade. CAGRs were derived from installed bioreactor capacity trajectories, crushing infrastructure expansion plans, and sports nutrition channel penetration curves. Industry-specific forecast inputs included precision fermentation titer improvement rates and FOSHU registration approval velocity under PMDA evidentiary standards.
Stress conditions across Brazilian soybean freight rates, SAMR novel food approval timelines, and gym membership growth trajectories in Vietnam and Indonesia were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding bioprocess engineering talent availability and halal certification audit harmonization. Specific risk factors that could revise projections include regulatory restriction on genetically modified fermentation strains and commodity price volatility in oilseed markets. Cross-checking against MFDS and PMDA regulatory filing databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Chicory Root Fiber Market
Ingredients
South America Plant Protein Ingredients Market
Ingredients
Organic Edible Oil Market
Ingredients
Broccoli Powder Market
Ingredients
Barley Malt Extract Market
Ingredients
Isoamyl Laurate Market
Ingredients
Demineralized Whey Powder Ingredient Market
Ingredients
Mediterranean Marine Ingredients for Pet Health Market
Ingredients
South America Insoluble Dietary Fibers Market
Ingredients
Ahiflower Oil Market
Ingredients
Asia-Pacific Yeast and Yeast Extract Market
Ingredients
North America Whey Protein Ingredients Market
Ingredients
Global Infant Nutrition Ingredients Market
Ingredients
Mung Bean Starch Market
Ingredients
Textured Wheat Protein Market
Ingredients
Carob Powder Market