
 Africa Automotive Market | 2026-2036
Africa Automotive Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Automotive Market Analysis
Euro 4 emission compliance is collapsing the cost advantage of grey-import used vehicles across coastal African markets. Toyota Motor Corporation sustains dominant channel control through its certified pre-owned network and spare parts backward integration in Kenya and Ghana. Volkswagen AG anchors assembly investments in Rwanda and Ethiopia, leveraging government-backed industrial park incentives. Hyundai Motor Company differentiates via localized kit assembly that navigates import duty escalation on fully built units.
The Africa Automotive Market comprises motor vehicles designed for passenger and goods transport, typically engineered with reinforced suspension systems, elevated ground clearance, and tropicalized cooling circuits to withstand unpaved road surfaces and ambient temperatures exceeding 40°C. These vehicles serve commercial logistics, informal public transport, and emerging middle-class mobility across infrastructure-constrained environments. SUV and pickup configurations command structural priority due to their durability premiums and higher residual values in secondary markets. Fleet operators represent the fastest-expanding customer type as e-commerce fulfillment and agricultural distribution professionalize vehicle procurement. Electric fuel type penetration remains nascent but attracts policy attention where grid reliability improves and renewable energy integration accelerates.
Kenya's National Transport and Safety Authority enforces age limits on commercial vehicle imports, redirecting demand toward newer, safer stock. South Africa's National Regulator for Compulsory Specifications mandates seatbelt anchorages and frontal impact standards that reshape product planning for economy-segment entrants. Nigeria's Standards Organisation regulates exhaust emissions in Lagos and Abuja, creating compliance cost tiers between coastal and inland supply channels. Stakeholders must monitor how divergent national enforcement timelines fragment homologation strategies and whether regional economic community harmonization accelerates or delays unified technical specifications.
Market Dynamics
Fleet professionalization across East Africa is compressing replacement cycles for commercial vehicles as logistics operators abandon informal procurement channels. National age-limit enforcement on vehicle imports is redirecting demand toward certified new and near-new stock, collapsing the historical cost advantage of grey-market used imports.
Growth Catalysts
- Kenya's National Transport and Safety Authority age limits:Commercial vehicle import restrictions redirect demand toward newer stock with reinforced safety systems. Fleet operators accelerate replacement of aging minibus cooperatives.
- E-commerce fulfillment densification:Agricultural distribution and last-mile logistics professionalize vehicle procurement. Cold-chain operators expand refrigerated truck fleets across Nigeria's northern corridor.
- Rwanda and Ethiopia industrial park incentives:Government-backed assembly zones attract kit-based manufacturing investments. Localized production navigates escalating import duties on fully built units.
Market Restraints
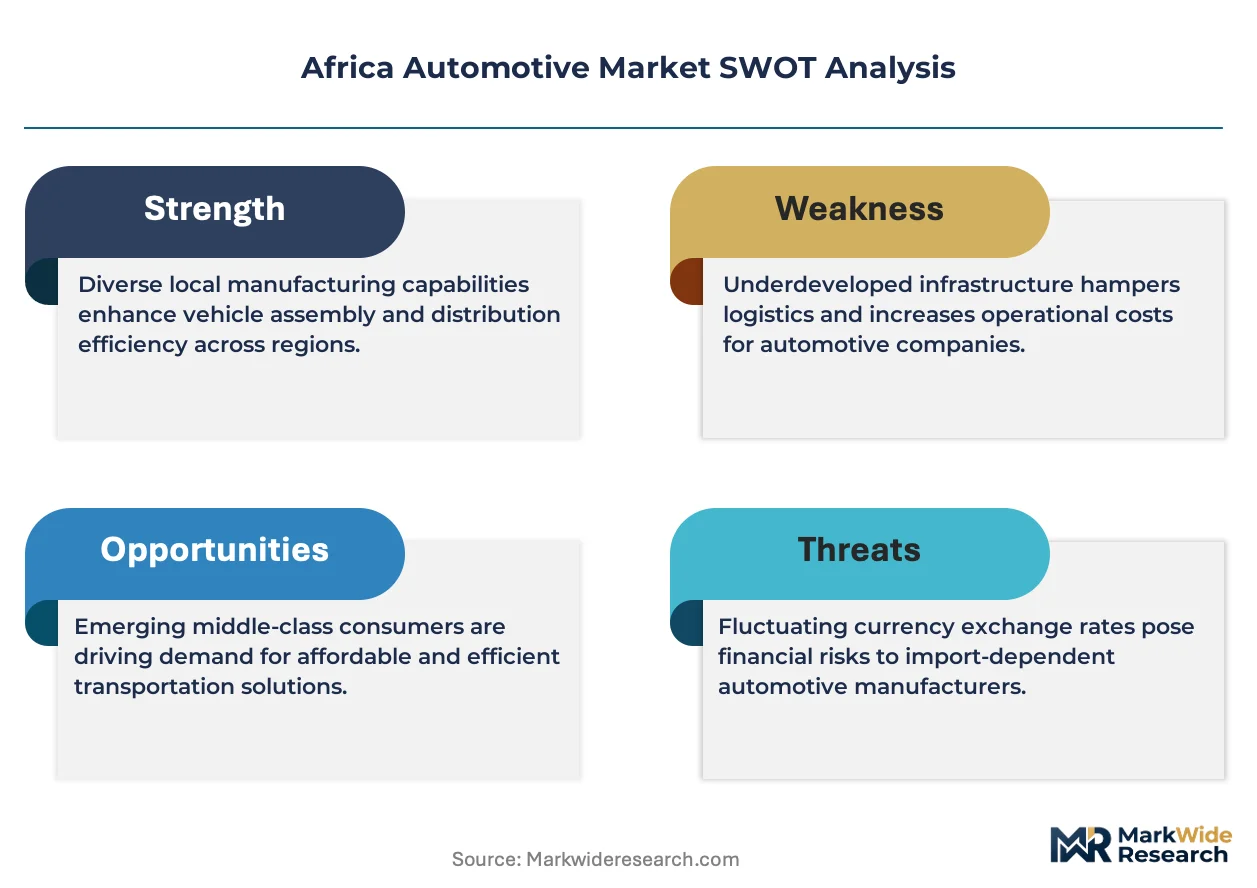
- Foreign exchange volatility:Dollar-denominated component imports expose assemblers to currency risk. Ethiopian birr and Nigerian naira instability compress operating margins.
- Spare parts supply concentration:Backward-integrated distribution networks in Kenya and Ghana create channel dependency. Independent repair shops face sourcing bottlenecks for tropicalized cooling circuits.
- Grid reliability constraints:Electric power infrastructure gaps limit battery-electric commercial vehicle deployment. Charging network absence blocks fleet electrification outside South African metropolitan zones.
Strategic Opportunities
- Rwanda kit assembly expansion:Government industrial zone incentives enable tariff-efficient production scaling. Regional export positioning targets Burundi and eastern Democratic Republic of Congo.
- Renewable energy convergence:Solar-powered charging infrastructure pairs with off-grid commercial vehicle operations. Agricultural cooperatives deploy electric two-wheelers for produce collection.
- Certified pre-owned channel formalization:Backward-integrated spare parts networks capture secondary market value. Quality-assured used stock displaces unverified grey imports in Ghanaian coastal markets.
Industry Challenges
- Homologation fragmentation:Divergent national enforcement timelines across South Africa's National Regulator for Compulsory Specifications, Kenya's NTSA, and Nigeria's Standards Organisation complicate unified product planning.
- Technical skill scarcity:Diagnostic capability for electronic fuel injection and ABS systems concentrates in Johannesburg and Nairobi. Rural service networks lack trained technicians for modern powertrain maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Automotive Market |
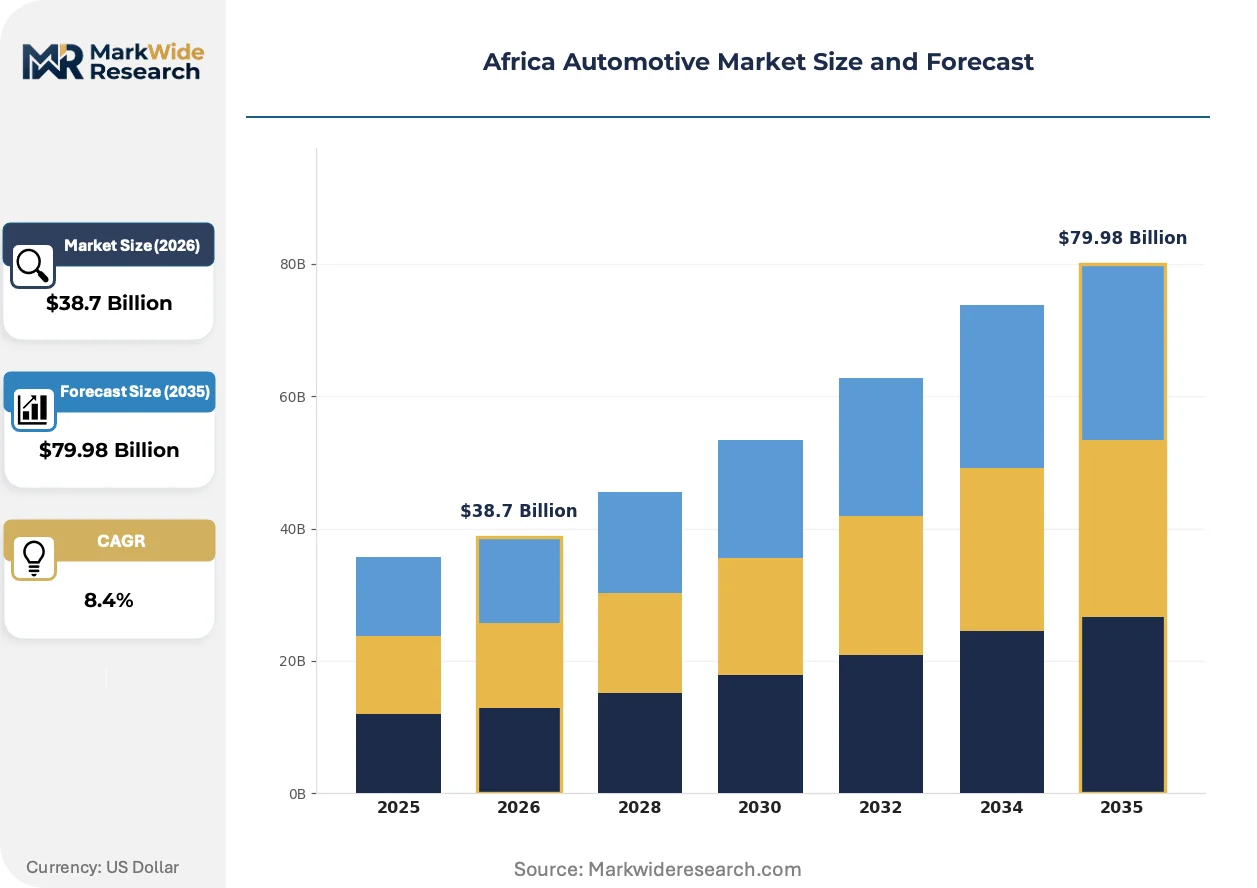
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: SUV, Sedan, Hatchback, Pickup Fuel Type: Petrol, Diesel, Electric, Hybrid Customer Type: Individual Buyers, Fleet Operators, Government, Corporates Market Segment: Luxury, Economy, Mid-Range, Commercial |
| Companies Covered | Hyundai Motor Company, Stellantis, Toyota Motor Corporation, Daimler AG, BYD Auto, Volkswagen AG, Ford Motor Company, Nissan Motor Company, Groupe Renault, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Automotive Market Emerging Trajectories
Tropicalized vehicle engineering and digital fleet management are compressing total cost of ownership calculations for commercial operators. Regulatory enforcement divergence is fragmenting homologation strategies while professionalizing procurement channels.
Reinforced suspension systems with elevated ground clearance are supplanting standard passenger car configurations in commercial applications. Agricultural distributors and mining contractors specify these durability-enhanced platforms for unpaved road surfaces. The shift is compressing residual value gaps between SUV/pickup segments and conventional sedans in secondary markets.
South Africa's National Regulator for Compulsory Specifications mandates seatbelt anchorages and frontal impact standards that reshape economy-segment product planning. OEMs redesign entry-level offerings to meet crashworthiness requirements previously absent in budget categories. Nigerian and Kenyan commercial importers face compliance cost tiers that favor newer stock over depreciated grey-market alternatives.
Fleet operators now specify vehicles through centralized procurement departments rather than informal cooperative structures. Professional buyers demand standardized maintenance contracts and residual value guarantees previously absent in fragmented channels. This behavioral shift concentrates purchasing power among East African logistics companies with balance sheet capacity for volume discounts.
Africa Automotive Market Segmentation
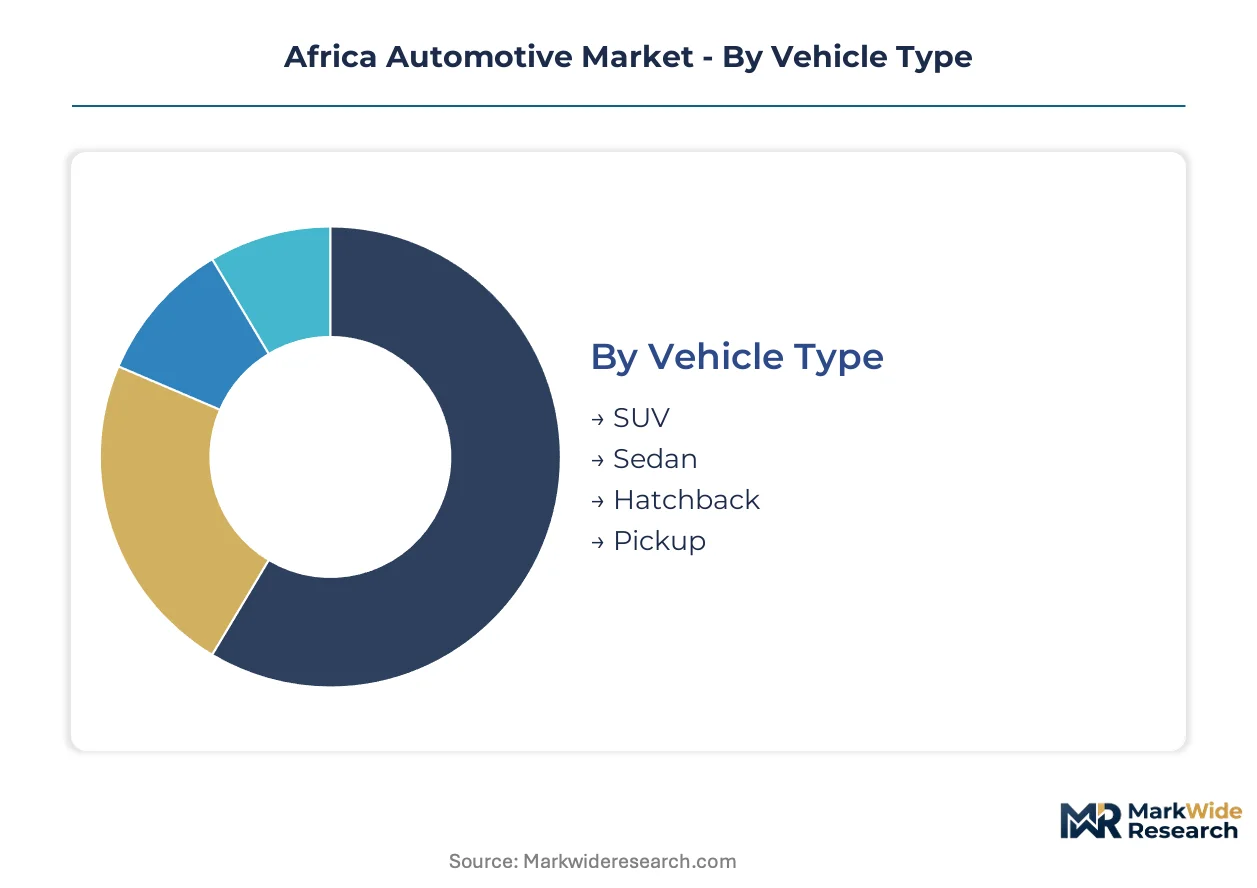
Vehicle specifications and procurement channels diverge sharply across African markets. Segmentation reveals how reinforced engineering requirements and regulatory enforcement reshape demand concentration by use case and buyer type.
Vehicle Type:
Channel flows split between certified dealer networks for new SUVs and pickups versus informal auctions for imported sedans and hatchbacks. Fleet procurement departments now centralize volume purchasing of durability-rated platforms.
- SUV:Reinforced ladder-frame construction with elevated ground clearance handles unpaved road surfaces across Nigeria's northern corridor and Kenya's agricultural districts. Mining contractors and safari tourism operators in South Africa specify these configurations for residual value retention in secondary markets.
- Pickup:Double-cab and single-cab configurations dominate commercial logistics across East Africa's expanding e-commerce fulfillment networks. Cold-chain distributors in Lagos and Nairobi prioritize refrigerated pickup variants for last-mile agricultural distribution.
- Sedan:Compact three-box designs concentrate in urban ride-hailing fleets and corporate staff transport programs.
- Hatchback:Two-box economy configurations flow through grey-market import channels in coastal Ghanaian cities.
Pickup and SUV configurations dominate installed base across commercial applications. Hatchback represents where expansion concentrates among price-sensitive individual buyers in coastal urban markets.
Fuel Type:
Cost tiers separate petrol and diesel infrastructure maturity from emerging electric and hybrid compliance positioning. Procurement patterns track fuel availability and maintenance network density.
- Petrol:Port-fuel-injected and direct-injection gasoline engines power the majority of individual buyer acquisitions across Kenya and Nigeria. Urban congestion and stop-start driving patterns in Lagos and Nairobi favor petrol's cold-start reliability over diesel particulate filter maintenance burdens.
- Diesel:Compression-ignition engines with reinforced cooling circuits sustain long-haul commercial operations across South Africa's freight corridors and East African agricultural logistics. Fleet operators specify these for fuel efficiency premiums on high-mileage routes.
- Electric:Battery-electric configurations concentrate in South African metropolitan zones with grid reliability and nascent charging infrastructure.
- Hybrid:Parallel and series hybrid systems attract policy attention in Rwanda and Ethiopia where renewable energy integration accelerates.
Diesel dominates installed base in commercial vehicle fleets. Electric is where expansion concentrates among policy-backed pilot programs and renewable energy convergence zones.
Customer Type:
Procurement professionalization separates centralized fleet purchasing from fragmented individual transactions. Volume discounts and standardized maintenance contracts reshape channel economics.
- Fleet Operators:Centralized procurement departments with balance sheet capacity negotiate volume discounts and residual value guarantees. East African logistics companies and Nigerian transport cooperatives professionalize vehicle replacement cycles.
- Individual Buyers:Price-sensitive acquisitions concentrate in certified pre-owned channels and informal grey-market auctions.
- Government:Public sector tenders specify crashworthiness compliance and local assembly content preferences.
- Corporates:Staff transport and executive mobility programs prioritize brand reliability and maintenance contract standardization.
Fleet operators dominate installed base renewal rates. Individual buyers represent where channel formalization concentrates as certified pre-owned networks displace grey imports.
Market Segment:
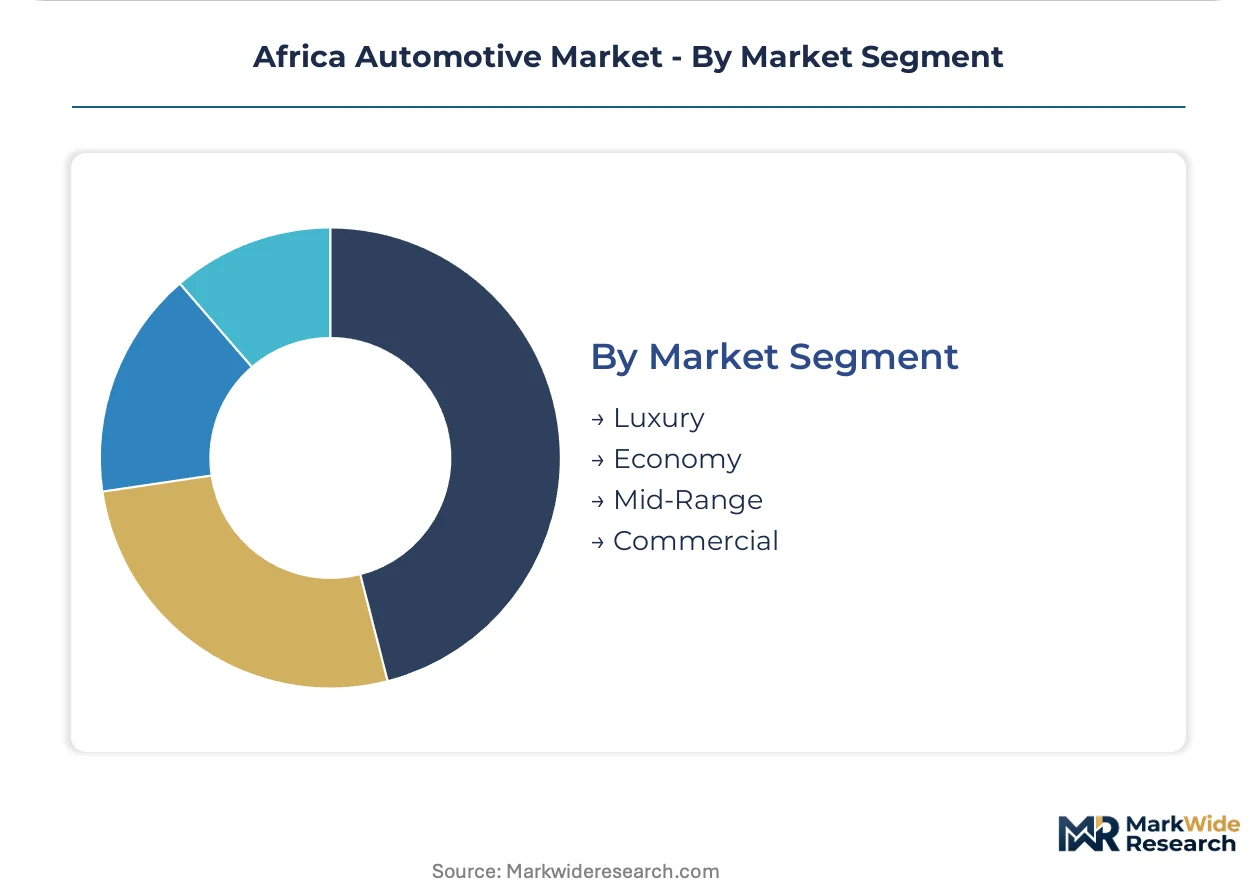
Margin structures and specification requirements separate luxury import channels from economy kit-assembly production. Compliance cost tiers fragment product planning across regulatory jurisdictions.
- Commercial:Reinforced suspension, tropicalized cooling, and elevated ground clearance specifications address unpaved infrastructure across agricultural and mining applications. South Africa's National Regulator for Compulsory Specifications and Kenya's NTSA age limits reshape safety system requirements.
- Economy:Entry-level platforms face redesign pressures from crashworthiness mandates previously absent in budget categories. Nigerian and Kenyan importers navigate compliance cost tiers favoring newer stock.
- Mid-Range:Balanced specification packages attract emerging middle-class mobility demand in urban centers.
- Luxury:Premium configurations concentrate in corporate executive transport and diplomatic fleet channels.
Commercial segment dominates unit volume across logistics and agricultural applications. Economy segment is where regulatory enforcement concentrates, collapsing historical grey-import cost advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Assembly investments concentrate in East African industrial zones where government-backed incentives attract kit-based manufacturing. Currency volatility and fragmented regulatory enforcement create divergent cost structures across national markets.
South Africa
Domestic production anchors sub-Saharan vehicle supply through established component networks and technical labor pools. The National Regulator for Compulsory Specifications enforces seatbelt anchorages and frontal impact standards that reshape economy-segment product planning. Gauteng province hosts concentrated assembly capacity serving both domestic consumption and regional export positioning.
Nigeria
Informal transport cooperatives across the northern corridor drive commercial vehicle demand as aging minibus fleets require replacement. The Standards Organisation regulates exhaust emissions in Lagos and Abuja, creating compliance cost tiers between coastal and inland supply channels. Kano and Kaduna emerge as logistics hubs where agricultural distribution networks professionalize procurement.
Kenya
E-commerce fulfillment densification accelerates commercial vehicle replacement cycles among logistics operators. The National Transport and Safety Authority enforces age limits on commercial vehicle imports, redirecting demand toward certified new and near-new stock. Mombasa port throughput shapes regional distribution patterns for tropicalized vehicle configurations.
Ethiopia
Industrial park incentives attract assembly investments seeking tariff-efficient production scaling. Birr instability compresses operating margins for dollar-denominated component imports. Addis Ababa anchors government-backed manufacturing zones targeting regional export to Burundi and eastern Democratic Republic of Congo.
Rwanda
Policy-backed pilot programs for renewable energy convergence attract electric mobility experimentation. Government industrial zone incentives enable kit assembly operations with regional export positioning. Kigali hosts concentrated policy attention where grid reliability improvements and solar integration accelerate fleet electrification discussions.
Africa Automotive Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the African automotive market. Consolidated channel control characterizes the competitive structure, with a handful of multinational OEMs dominating certified distribution networks while fragmented grey-market operators serve price-sensitive segments. Three strategic archetypes define positioning: established OEMs with backward-integrated spare parts networks, emerging assemblers leveraging government industrial zone incentives, and kit-based manufacturers navigating import duty escalation. Dominant competitive moves include strategic partnerships with local distributors and geographic expansion through government-backed assembly investments.
Among multinational OEMs, Toyota Motor Corporation exemplifies channel control through certified pre-owned networks and spare parts backward integration in Kenya and Ghana. Hyundai Motor Company occupies a position within the kit-assembly archetype, leveraging localized production to navigate import duty structures. Volkswagen AG anchors the industrial zone investment vector through assembly presence in Rwanda and Ethiopia.
| Leading Market Players |
|---|
| Hyundai Motor Company |
| Stellantis |
| Toyota Motor Corporation |
| Daimler AG |
| BYD Auto |
| Volkswagen AG |
| Ford Motor Company |
| Nissan Motor Company |
| Groupe Renault |
| Others |
Supply Flow & Price Mechanics
Ninety-day component lead times for tropicalized cooling circuits and reinforced suspension kits concentrate pricing power with backward-integrated distributors in Kenya and Ghana. Inventory velocity at Mombasa and Lagos ports shapes working capital requirements for assemblers navigating dollar-denominated import exposures.
Pricing Analysis
South Africa's National Regulator for Compulsory Specifications dictates the pricing tier structure by mandating seatbelt anchorages and frontal impact standards that compress margin structures in economy-segment offerings. Three-tier pricing separates crashworthiness-compliant new stock from certified pre-owned channels and unverified grey-market imports. Price differentiation rests on safety certification grade and after-sales service bundling. Cost compression in the grey-import tier is intensifying because Kenya's NTSA age limits redirect demand toward newer, compliant stock. Fleet operators demonstrate lowest price sensitivity due to residual value guarantees, while informal individual buyers in coastal Ghana remain most price-sensitive.
Supply Chain Analysis
Strategic stockpiling of dollar-denominated components prevails over just-in-time approaches as Ethiopian birr and Nigerian naira volatility compress operating margins. Geographic supply concentration centers on South Africa for established component networks, China for electronics and battery inputs, and Japan for powertrain engineering. Raw material dependencies include steel for reinforced ladder-frame construction, copper for tropicalized cooling circuits, and semiconductors for electronic fuel injection systems. Single-source vulnerability concentrates in backward-integrated spare parts networks controlling Kenya and Ghana distribution channels. Distribution runs through certified dealer networks for new vehicles and informal auction channels for grey-market imports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Africa Automotive Market represents an early-cycle expansion story as fleet professionalization across East Africa accelerates replacement cycles and compresses historical reliance on depreciated grey-market stock.
For Market Incumbents: Compound channel control through backward-integrated spare parts networks that capture secondary market value in Kenya and Ghana. Expand certified pre-owned certification programs to displace unverified grey imports in coastal Nigerian markets. Invest in tropicalized engineering capabilities to meet South Africa's National Regulator for Compulsory Specifications crashworthiness mandates before competitors redesign economy-segment offerings.
For New Entrants and Emerging Players: Differentiate on kit-assembly localization to navigate escalating import duties on fully built units in Rwanda and Ethiopia. Target Rwanda's government-backed industrial zones as the most penetrable geography for tariff-efficient production scaling. Pursue agricultural cooperative fleet contracts in Nigeria's northern corridor where informal transport structures professionalize procurement channels.
For Investors and Strategic Acquirers: Long-term, this sits as a logistics-infrastructure play because e-commerce fulfillment densification and cold-chain expansion drive commercial vehicle demand across infrastructure-constrained environments. Acquisition candidates include kit-assemblers with established government industrial zone relationships and spare parts distributors with backward-integrated channel control. Watch for grid reliability improvements in South African metropolitan zones as the inflection signal for battery-electric commercial vehicle deployment scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| Kit Assembly Localization | Navigates escalating import duties on fully built units in Rwanda and Ethiopia government industrial zones. |
| Certified Pre-Owned Network Expansion | Captures secondary market value and displaces grey-market imports through quality-assured used stock channels. |
| Tropicalized Engineering Investment | Meets South Africa's National Regulator for Compulsory Specifications crashworthiness mandates for economy-segment compliance. |
| Fleet Procurement Centralization | Professionalizes vehicle replacement cycles among East African logistics operators abandoning informal cooperative structures. |
| Renewable Energy Charging Infrastructure | Pairs solar-powered charging with off-grid commercial vehicle operations where grid reliability remains constrained. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interviews with fleet procurement managers, OEM platform engineers, aftermarket distributors, and government industrial zone authorities. Secondary validation drew from vehicle production databases, IHS Markit registration data, national regulatory filings from South Africa's National Regulator for Compulsory Specifications and Kenya's NTSA, and customs trade records. Bottom-up volume modeling triangulated against top-down macroeconomic indicators across the analysis window.
Across the projection horizon, the analytical framework segmented by vehicle class, propulsion architecture, and regional production cluster. CAGRs were derived from regression analysis against GDP per capita trajectories, infrastructure investment flows, and regulatory enforcement timelines. Forecast inputs included fleet operator replacement cycle compression rates and grey-market import volume displacement curves under tightening age-limit enforcement.
The analysis sits within stated boundaries; outcomes outside sustained currency stability in Nigeria and Ethiopia or accelerated regional economic community harmonization would require recalibration. Forecasts reflect documented assumptions regarding enforcement continuity for Kenya's NTSA age limits and South Africa's crashworthiness mandates. Revision becomes warranted when grid reliability improvements in metropolitan zones cross thresholds enabling commercial fleet electrification at scale.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Assemblies
Automotive Strut Bar Market
Automotive Assemblies
Automotive Armrest Market
Automotive Assemblies
Automotive Steering Rack Market
Automotive Assemblies
Automotive Trailer Drawbar Market
Automotive Assemblies
Automotive Ball Joints Market
Automotive Assemblies
Global Automotive Transfer Case Market
Automotive Assemblies
Automotive Throttle Body Assembly Market
Automotive Assemblies
Automotive Rocker Arm Market
Automotive Assemblies
Global Automotive Cross Car Beam Market
Automotive Assemblies
Automotive Idler Arm Market
Automotive Assemblies
Global 3D Printing Automotive Market
Automotive Assemblies
Automotive Clock Spring Market
Automotive Assemblies
Global Automotive Center Stacks Market
Automotive Assemblies
Automotive Die-Stamping Equipment Market
Automotive Assemblies
Robotic Welding for Automotive Manufacturing Market
Automotive Assemblies
Automotive Roof Rails Market