
 Disinfectant Robot Market | 2026-2036
Disinfectant Robot Market Size, Share, and Industry Trends Forecast 2026-2036
Disinfectant Robot Market Analysis
Subscription-based fleet management software is recalibrating how disinfection robot vendors monetize hardware deployments. Blue Ocean Robotics leverages its UVD Robots subsidiary to anchor recurring revenue through remote monitoring and protocol optimization services. Xenex Disinfection Services competes on hospital-specific outcome guarantees rather than per-unit sales. TMiRob Technology extends its position through integrated maintenance contracts that reduce total cost of ownership for healthcare facility buyers.
Disinfectant robots are autonomous or semi-autonomous electromechanical systems engineered to deliver antimicrobial agents or germicidal radiation, typically operating at UV-C wavelengths between 200 and 280 nanometers to achieve log-reduction of pathogens on surfaces and in air. Their primary commercial purpose is to replace or augment manual environmental cleaning in settings where bioburden control carries operational or regulatory consequences. UV Disinfection technology leads installed base because hospitals prioritize validated kill-rate documentation over speed, while Hybrid Systems represent the fastest-expanding category as buyers seek single-platform coverage for surface, air, and water treatment protocols. Mobile Robots capture the dominant share of new orders due to flexibility across ward configurations, though Fixed Robots retain margin pools in surgical suite builds where permanent infrastructure integration reduces per-cycle labor.
FDA 510(k) clearance requirements for medical device claims shape product development timelines and limit market access for uncertified entrants in the United States, while the EU Medical Device Regulation (MDR) imposes parallel conformity assessment burdens on systems deployed in European healthcare facilities. EPA registration of chemical disinfectants used in fogging robots adds a secondary compliance layer that determines which formulations robot vendors can legally deploy. Stakeholders must monitor how evolving CMS hospital-acquired condition penalties and Joint Commission survey priorities redirect capital allocation between standalone UV-C towers and fully autonomous navigation platforms.
Market Dynamics
Autonomous navigation software is compressing disinfection cycle times and forcing legacy UV-C tower manufacturers to integrate mobility stacks or cede hospital procurement decisions to robotics vendors.
Growth Catalysts
- CMS Reimbursement Tightening:US hospital procurement departments face documentation requirements for infection-control outcomes that autonomous systems satisfy better than manual protocols.
- UV-C Wavelength Optimization:Advances in 254 nanometer lamp efficiency and 222 nanometer far-UVC safety margins validate log-reduction claims for resistant pathogens in surgical suites.
- Germany KBA-Equivalent Standards:Dense hospital networks in Bavaria and North Rhine-Westphalia accelerate replacement of terminal cleaning with certified medical device robots.
Market Restraints
- Lithium-Ion Battery Supply Concentration:Mobile robot fleets depend on cylindrical cell supply chains concentrated in East Asian manufacturing zones, exposing vendors to input volatility and export control friction.
- FDA 510(k) Clearance Timelines:Medical device claims for pathogen kill-rates require 12-18 month validation studies that delay market entry for UV-C system startups.
- Manual Terminal Cleaning Substitution:Low-wage environmental services labor in long-term care facilities competes on first-cost against capital-intensive robot deployments.
Strategic Opportunities
- India CDSCO Medical Device Registration:Private hospital chains in Mumbai and Delhi are piloting disinfection robots ahead of mandatory infection-control audits under revised national health standards.
- Hybrid System Convergence:Single-platform robots combining UV-C surface treatment with hydrogen peroxide fogging and HEPA air filtration capture multi-protocol contracts from integrated health networks.
- Subscription Fleet Management:Remote monitoring software and protocol optimization services convert one-time hardware sales into recurring revenue streams with 3-5 year contract terms.
Industry Challenges
- Autonomous Navigation Certification:FDA and EU MDR require extensive clinical validation of obstacle-avoidance algorithms in patient-occupied corridors, extending development cycles.
- EPA Chemical Disinfectant Registration:Fogging robot vendors must secure separate registrations for each antimicrobial formulation, creating compliance bottlenecks for multi-chemistry platforms.
- Legacy EMR Integration:Disinfection cycle documentation must interface with hospital electronic medical record systems through HL7 or FHIR protocols, demanding specialized health IT engineering capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disinfectant Robot Market |
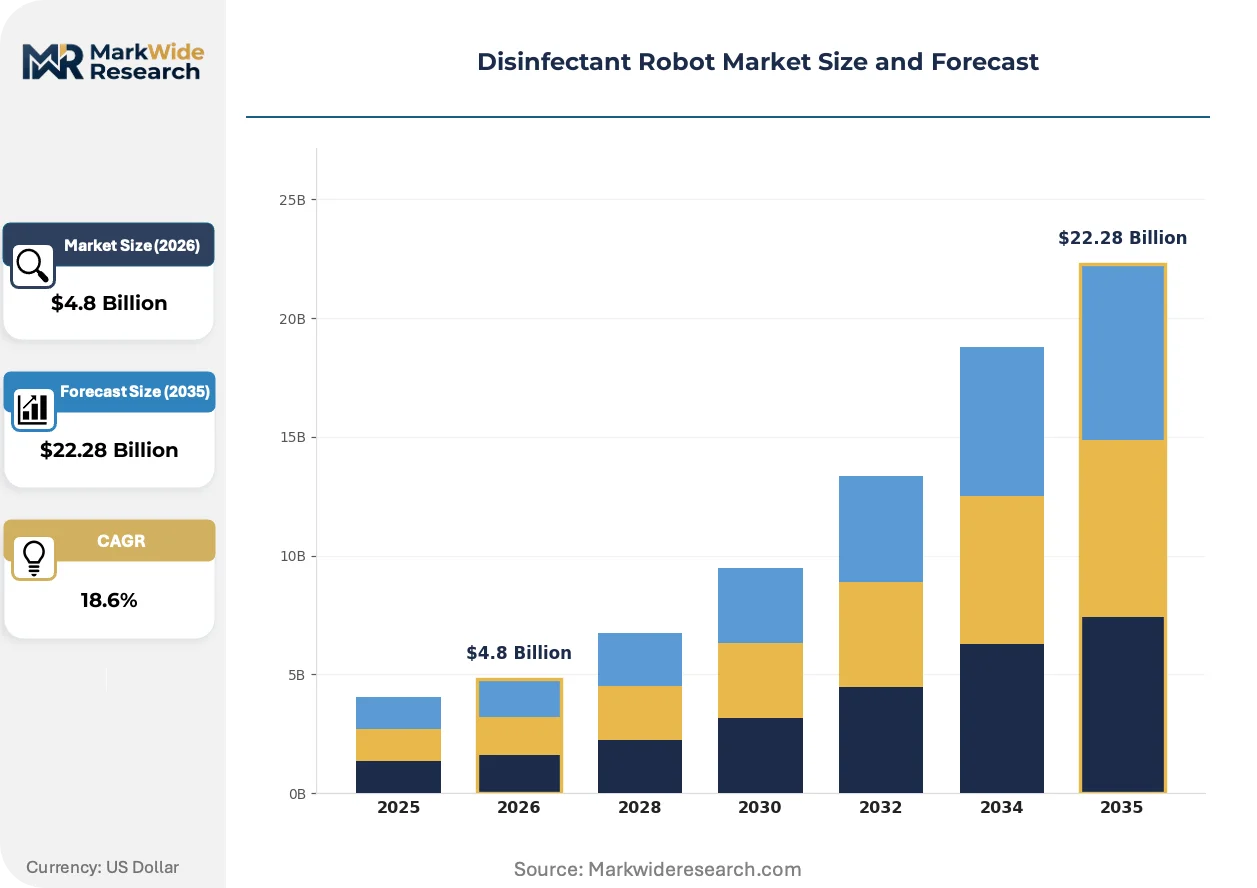
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Robots, Fixed Robots, UV-C Robots, Fogging Robots Technology: UV Disinfection, Chemical Disinfection, Electromagnetic Disinfection, Hybrid Systems End User: Healthcare Facilities, Educational Institutions, Hospitality Sector, Commercial Spaces Application: Surface Disinfection, Air Purification, Water Treatment, Emergency Response |
| Companies Covered | Blue Ocean Robotics, Xenex Disinfection Services, Finsen Technologies, Skytron, Tru-D SmartUVC, TMiRob Technology, OTSAW Digital Pte Ltd, Mediland Enterprise Corporation, Akara Robotics Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disinfectant Robot Market Emerging Trajectories
Disinfection robotics is absorbing capabilities from adjacent automation sectors, with sensor fusion and fleet coordination software migrating from warehouse logistics into healthcare environmental services.
Far-UVC semiconductor emitters at 222 nanometers are absorbing safety validation studies from Columbia University and other research institutions, enabling deployment in occupied spaces that conventional 254 nanometer lamps cannot access. Hospital infection control committees in the United States are piloting these systems in emergency department waiting areas. The structural consequence is that lamp vendors without semiconductor emitter roadmaps are absorbing margin pressure from early movers.
EU Medical Device Regulation (MDR) conformity assessment is absorbing notified body capacity and extending certification timelines for UV-C robots marketed in Germany, France, and Italy. Technical documentation requirements for clinical evaluation reports have intensified since 2021. European healthcare facility buyers are responding by consolidating procurement around vendors with established MDR certificates, compressing the supplier base.
Outcome-based service contracts are absorbing capital expenditure risk from hospital balance sheets and transferring it to robot vendors and third-party sterilization service providers. Buyers in the United Kingdom NHS and US integrated delivery networks now prefer per-disinfection pricing or hospital-acquired infection reduction guarantees. This shift is most visible in California and Texas health systems where private equity-backed facility management companies control environmental services purchasing.
Disinfectant Robot Market Segmentation
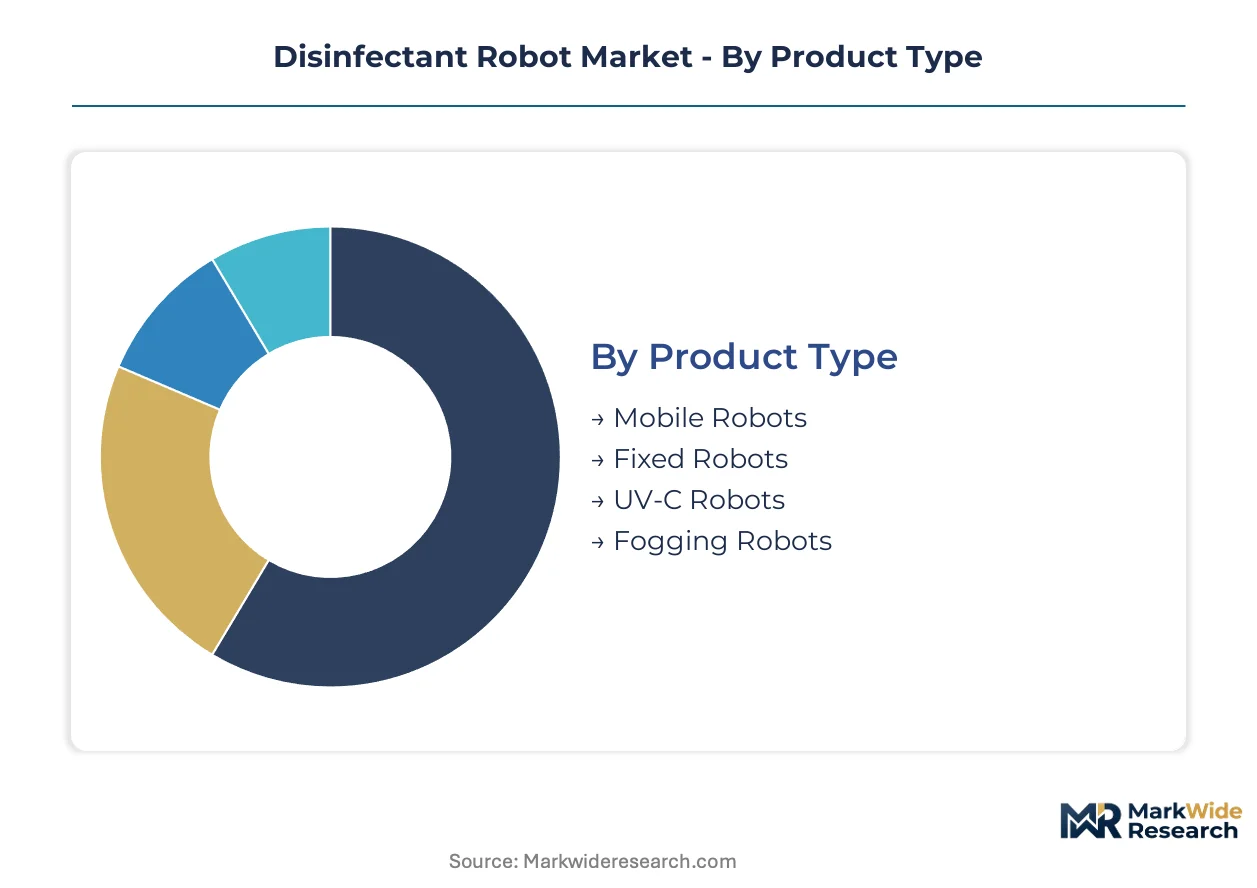
Segmentation in the Disinfectant Robot Market reveals how procurement priorities diverge across facility types and operational constraints. Buyers trade off capital intensity against cycle speed, regulatory documentation against labor substitution, and single-protocol validation against multi-modal flexibility.
Product Type:
Capital allocation decisions pivot on ward configuration flexibility versus permanent infrastructure integration.
- Mobile Robots:Autonomous navigation platforms with lithium-ion powertrains and LiDAR obstacle avoidance dominate new order flows from acute care hospitals. US health systems in Texas and California prioritize these units for emergency department turnover where patient flow variability demands repositionable coverage.
- UV-C Robots:Trolley-mounted or self-propelled systems engineered around 254 nanometer mercury vapor or 222 nanometer excimer lamp arrays deliver validated log-reduction documentation. German hospital networks in Bavaria specify these for surgical suite terminal cleaning under KBA-equivalent medical device certification requirements.
- Fixed Robots:Ceiling-mounted or wall-integrated installations with permanent power and data connections serve operating theaters and sterile processing departments where infrastructure amortization aligns with decade-long facility lifecycles.
- Fogging Robots:Electrostatic or pneumatic spray platforms dispensing hydrogen peroxide, quaternary ammonium, or peracetic acid formulations target long-term care and food processing environments where UV-C shadowing limits efficacy.
Volume sits with Mobile Robots; growth tilts toward UV-C Robots.
Technology:
Validation requirements and chemistry registration burdens reshape competitive positioning across technology platforms.
- UV Disinfection:Germicidal irradiation at 200-280 nanometer wavelengths achieves 4-6 log pathogen reduction on surfaces and in air without chemical residue. Hospital infection control committees prioritize this modality for occupied room turnover where EPA-registered fogging agents face ventilation constraints.
- Hybrid Systems:Converged platforms alternating UV-C emission with hydrogen peroxide vapor or HEPA filtration capture integrated health network contracts seeking single-vendor accountability. UK NHS trusts and US IDNs in Florida specify these for multi-ward standardization.
- Chemical Disinfection:Fogging and spray systems dependent on EPA-registered antimicrobial formulations serve hospitality and commercial cleaning where pathogen validation requirements are less stringent than healthcare.
- Electromagnetic Disinfection:Pulsed xenon or microwave-induced plasma technologies remain developmental, with limited installed base constrained by energy consumption and material compatibility testing gaps.
UV Disinfection commands current installed base; Hybrid Systems are climbing the fastest.
End User:
Regulatory pressure and reimbursement exposure determine willingness-to-pay across customer categories.
- Healthcare Facilities:Acute care hospitals, ambulatory surgery centers, and long-term care operators face CMS hospital-acquired condition penalties and Joint Commission survey priorities that justify capital expenditure on validated disinfection automation.
- Educational Institutions:K-12 districts and university facilities management departments pilot UV-C towers and mobile units for classroom turnover, though budget cycles and non-clinical status limit penetration.
- Hospitality Sector:Hotels and cruise operators deploy fogging robots for guest room and food service sanitation, prioritizing cycle speed over kill-rate documentation.
- Commercial Spaces:Corporate campuses, retail, and transportation terminals represent emerging demand as facility management contracts incorporate infection-control service level agreements.
Revenue concentrates in Healthcare Facilities; Educational Institutions show steepest expansion trajectory.
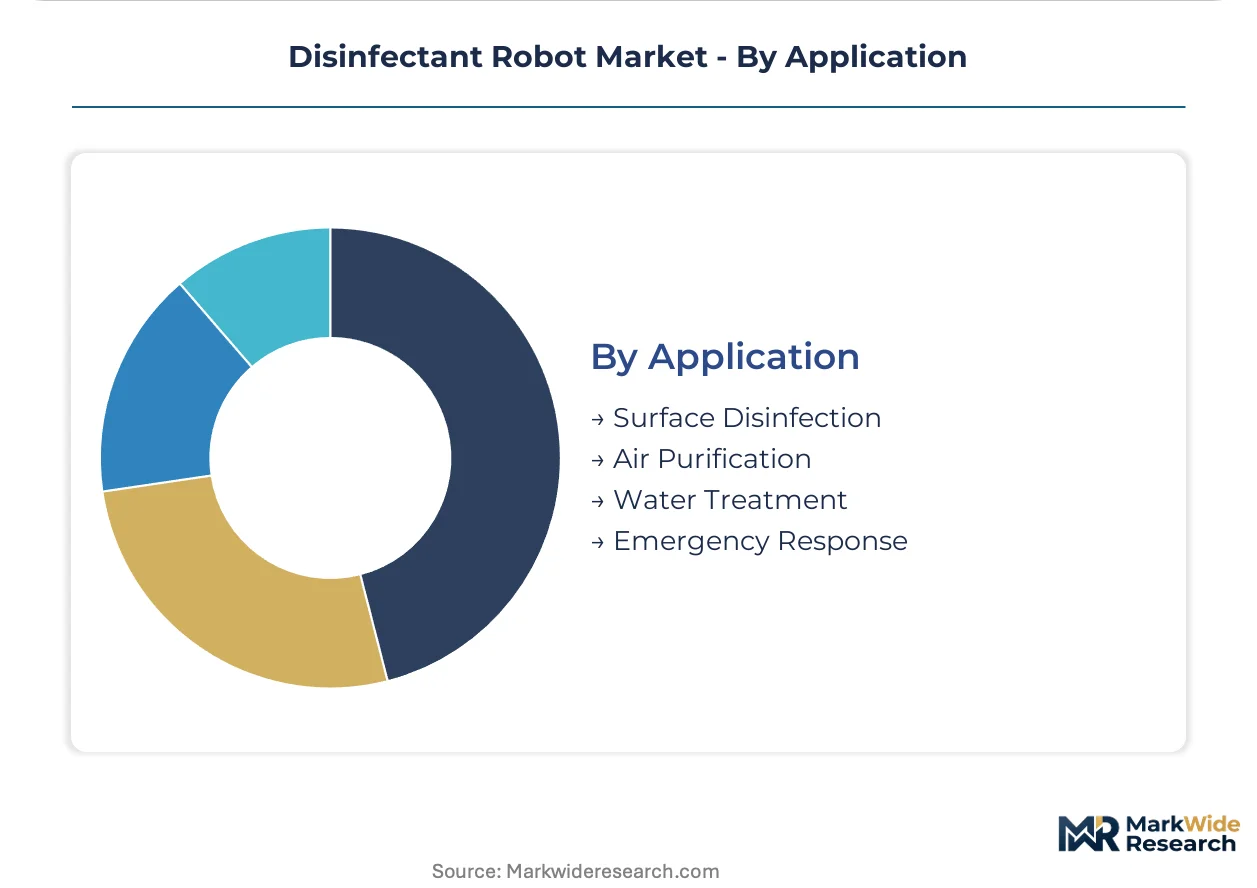
Application:
Use case specificity dictates sensor configuration, cycle programming, and documentation integration requirements.
- Surface Disinfection:Terminal cleaning of patient beds, surgical tables, and high-touch equipment dominates robot utilization rates, with UV-C shadow compensation algorithms and multiple positioning cycles ensuring comprehensive coverage.
- Air Purification:Upper-room UVGI and far-UVC 222 nanometer whole-room treatment address airborne transmission in emergency departments and waiting areas where HVAC retrofit costs exceed robot capital outlay.
- Water Treatment:UV-C and advanced oxidation process robots for medical device reprocessing and dialysis water loops serve specialized clinical engineering departments with distinct regulatory oversight.
- Emergency Response:Rapidly deployable trailer-mounted or portable units for outbreak containment and disaster medical response represent contingency procurement with irregular demand patterns.
Surface Disinfection absorbs current fleet hours; Air Purification gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in East Asian electronics clusters while demand concentrates in Western healthcare systems with stringent infection-control mandates. Procurement in Germany and the United States absorbs premium-tier UV-C systems, whereas Indian and Chinese facilities prioritize cost-optimized mobile platforms.
United States
Acute care hospitals in Texas and California drive fleet deployments as CMS tightens documentation requirements for hospital-acquired condition reimbursement. FDA 510(k) clearance timelines extend 12-18 months for pathogen kill-rate claims, filtering market access. The Southeast corridor from Florida to Georgia pilots far-UVC 222 nanometer systems in emergency department waiting areas.
Germany
Dense hospital networks in Bavaria and North Rhine-Westphalia accelerate terminal cleaning automation under KBA-equivalent medical device certification. EU MDR conformity assessment absorbs notified body capacity, compressing the supplier base around established certificate holders. Stuttgart and Munich host integration engineering clusters for surgical suite fixed installations.
China
Domestic robot OEMs in Shenzhen and Shanghai scale lithium-ion powered mobile platforms for hospital and transportation terminal contracts. NMPA medical device registration aligns with GB standards for electromagnetic compatibility and safety. The Yangtze River Delta concentrates fogging robot manufacturing for hospitality and commercial cleaning exports.
India
Private hospital chains in Mumbai and Delhi pilot disinfection robots ahead of CDSCO medical device registration mandates under revised national health standards. Low-wage environmental services labor in long-term care facilities competes on first-cost against capital-intensive deployments. Bangalore and Hyderabad emerge as health IT integration hubs for EMR-connected fleet management.
United Kingdom
NHS trusts prefer per-disinfection pricing and hospital-acquired infection reduction guarantees over capital purchases. Outcome-based contracts transfer expenditure risk to vendors and third-party sterilization service providers. London and Manchester integrated delivery networks standardize on hybrid systems combining UV-C with hydrogen peroxide fogging protocols.
Disinfectant Robot Market Vendor Landscape
Top-tier vendors anchor premium UV-C certification tiers, while mid-scale fabricators compete on mobile platform cost optimization. The supplier base stratifies across three archetypes: medical device incumbents with FDA 510(k) portfolios, autonomous navigation specialists migrating from warehouse logistics, and chemical fogging equipment legacy players adding robotics stacks. Consolidation pressure intensifies through M&A targeting MDR certificate assets and strategic partnerships for lithium-ion battery supply security.
Within the medical device archetype, Blue Ocean Robotics and Xenex Disinfection Services occupy positions emphasizing outcome-based service models over per-unit sales. TMiRob Technology exemplifies the integrated maintenance contract approach reducing total cost of ownership for healthcare facility buyers. These three entities represent divergent monetization strategies—recurring software revenue, clinical outcome guarantees, and lifecycle service bundling—now reshaping competitive positioning across procurement departments.
| Leading Market Players |
|---|
| Blue Ocean Robotics |
| Xenex Disinfection Services |
| Finsen Technologies |
| Skytron |
| Tru-D SmartUVC |
| TMiRob Technology |
| OTSAW Digital Pte Ltd |
| Mediland Enterprise Corporation |
| Akara Robotics Ltd |
| Others |
Supply Flow & Price Mechanics
EU Green Deal compliance requirements for circular electronics and restricted substance controls gate qualified supply access for UV-C robot vendors while compressing margin pools for non-certified competitors seeking premium-tier hospital contracts in Germany and France.
Pricing Analysis
Margin tightening in standard-tier mobile robots reflects lithium-ion cell cost volatility and East Asian OEM price competition. Three-tier pricing structure across premium certified, standard mobile, and economy fogging tiers separates FDA 510(k) holders from uncertified entrants. Pricing pressure intensifies as German hospital networks consolidate procurement around MDR-certificate holders. Long-term care facilities exhibit highest price sensitivity; acute care surgical suites show lowest.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Singapore anchor hub-and-spoke patterns for UV-C lamp arrays and autonomous navigation modules. Manufacturing concentrates in Shenzhen for lithium-ion powertrains, Stuttgart for precision optics, and South Korea for excimer emitters. Raw material dependencies span rare earth phosphors, high-purity quartz glass, and semiconductor-grade aluminum nitride substrates. Single-source vulnerability in cylindrical battery cells exposes vendors to export control friction. Distribution runs through healthcare GPOs and direct hospital contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into semiconductor emitter fabrication and captive battery cell supply represents the decisive competitive race as vendors seek insulation from input volatility and certification bottlenecks.
For Market Incumbents: Anticipate margin compression from Chinese mobile platform OEMs by deepening backward integration into UV-C lamp manufacturing and securing MDR certificate assets through targeted acquisition. Prioritize software companion development for EMR integration to lock in hospital switching costs against emerging autonomous navigation specialists migrating from warehouse logistics. For New Entrants and Emerging Players: Long-term care facilities in India and Southeast Asia present the most penetrable buyer archetype given minimal regulatory documentation requirements and first-cost sensitivity that favors economy-tier fogging platforms. Target per-disinfection service contracts rather than capital sales to bypass procurement committee resistance. Partner with local facility management companies for channel access. For Investors and Strategic Acquirers: CDSCO registration completion for India-based pilots is the leading indicator that Southeast Asian hospital chains will accelerate robot procurement under revised national health standards. Position for five-to-ten year viability by targeting MDR-certificate holding mid-cap specialists with established German hospital relationships rather than pre-revenue UV-C startups facing validation timeline risk. Monitor EPA chemical disinfectant registration backlogs as signal for fogging robot vendor distress.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Certificate Acquisition | Compresses European supplier base around notified body-approved vendors in Germany. |
| Semiconductor Emitter Integration | Enables far-UVC 222nm deployment in occupied spaces beyond conventional lamp limitations. |
| Subscription Fleet Management Launch | Converts Blue Ocean Robotics hardware sales into recurring revenue with multi-year contracts. |
| Hospital System Partnership | Secures outcome-based pilot contracts with Texas and California IDNs for outcome guarantees. |
| EMR Integration Development | Demands HL7/FHIR engineering capacity for CMS documentation compliance in US acute care. |
Methodological Framework
Independent corroboration across hospital procurement directors, biomedical engineering leads, GPO contracts managers, and infection control specialists underwrites the qualitative findings. Primary interviews with UV-C system vendors and autonomous navigation software developers combined with secondary validation from FDA 510(k) filings, EU MDR notified body registers, CMS hospital-acquired condition penalty data, and hospital procurement databases. Bottom-up order flow analysis and top-down healthcare capital expenditure triangulation anchor market sizing.
Comparable-period anchoring to historical disinfection automation adoption curves and UV-C validation study timelines shaped the projection framework. Segmentation modeling spanned product mobility class, technology modality, end-user facility type, application protocol, and regional regulatory cluster. CAGRs derive from fitted adoption curves weighted by reimbursement pressure intensity and certification timeline constraints. Forecast inputs incorporated lithium-ion battery supply elasticity and MDR notified body capacity absorption rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EPA registration backlog resolution and far-UVC safety validation completion. Outputs reflect documented assumptions regarding CMS penalty enforcement continuity and EU MDR certificate renewal patterns. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Gantry (Cartesian) Robot Market
Robotics and Automation
Global AI Based Surgical Robots Market
Robotics and Automation
Latin America Cloud Robotics Market
Robotics and Automation
Healthcare Assistive Robot Market
Robotics and Automation
Drone Package Delivery Market
Robotics and Automation
Delta Robotics Market
Robotics and Automation
Global Robot Kitchen Market
Robotics and Automation
Global Security Robots Market
Robotics and Automation
US Cloud Robotics Market
Robotics and Automation
AGV & AMR in Logistics Market
Robotics and Automation
Retail Robotics Market
Robotics and Automation
Firefighting Robots Market
Robotics and Automation
Human-Robot Collaborative Picking Optimization Platforms Market
Robotics and Automation
Automotive Robotics Market
Robotics and Automation
Asia-Pacific Service Robotics Market
Robotics and Automation
Underwater Exploration Robots Market