
 Medical Service Robots Market | 2026-2036
Medical Service Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Service Robots Market Intelligence
The capital-intensity divergence between full-stack hardware developers and software-centric platform vendors is unwinding competitive dynamics in medical service robotics. Toyota Motor Corp. leverages its automotive manufacturing scale to produce precision robotic actuators at unit economics that pure-play medical firms struggle to match. Blue Ocean Robotics sustains a diversified portfolio across disinfection and telepresence applications, reducing single-segment risk. Diligent Robotics specializes in autonomous hospital logistics, occupying a narrow but defensible niche in medication delivery workflows.
Medical service robots encompass electromechanical systems equipped with manipulator arms, sensor arrays, and navigation software designed to perform clinical support tasks with minimal human supervision. These platforms integrate LiDAR, computer vision, and haptic feedback modules to operate safely in sterile corridors and patient rooms. Surgical robots command the largest installed base among product categories, though disinfection robots are expanding fastest as infection control budgets harden post-pandemic. Rehabilitation robots capture concentrated margin pools in developed markets where reimbursement codes for automated physical therapy have stabilized. Among end users, hospitals remain the dominant procurement channel, while nursing homes represent the most underserved addressable segment due to capital constraints and fragmented purchasing authority.
FDA 510(k) clearance timelines and EU MDR technical documentation requirements shape product development roadmaps and market access sequencing for manufacturers. Japan's PMDA has streamlined approval pathways for elder-care robotics, accelerating domestic deployment of patient monitoring and mobility assistance platforms. China's NMPA is tightening cybersecurity standards for networked medical devices, adding compliance layers for AI-enabled service robots. Stakeholders must monitor evolving reimbursement frameworks and interoperability mandates as health systems transition from pilot programs to fleet-scale procurement of automated clinical support systems.
Market Dynamics
Hospital capital committees are compressing vendor evaluation cycles from eighteen months to six months as post-pandemic staffing crises force immediate automation procurement decisions. This acceleration is restructuring supplier relationships and technical validation protocols across the installed base.
Growth Catalysts
- FDA 510(k) Streamlining:The FDA's expanded pre-submission program for autonomous mobile robots reduces clearance timelines for disinfection platforms. Hospital systems in the United States are fast-tracking these devices into infection control workflows.
- EU MDR Conformity Pathways:The Medical Device Regulation's harmonized technical documentation requirements enable cross-border certification reciprocity. German and French hospital groups are leveraging this to deploy fleet-scale logistics robots.
- Actuator Miniaturization:Advances in compact harmonic drive systems reduce robot footprint in crowded clinical corridors. Japanese precision manufacturers are supplying these components to global OEMs at volume scale.
Market Restraints
- Lithium-Ion Supply Concentration:Battery cell production concentrates in East Asian manufacturing clusters. European and North American integrators face extended lead times and input cost volatility for mobile robot power systems.
- EU MDR Technical Documentation Burden:The expanded clinical evidence requirements for software-as-a-medical-device create regulatory friction. Small platform vendors struggle to resource the notified body engagement costs.
- Manual Disinfection Protocol Persistence:Environmental services departments in budget-constrained facilities maintain ultraviolet-C tower and chemical fogging workflows. These established substitutes delay capital conversion to autonomous systems.
Strategic Opportunities
- Japan's PMDA Elder-Care Fast Track:The streamlined approval pathway for patient monitoring and mobility assistance robots creates regulatory tailwind. Domestic manufacturers are expanding production capacity for aging facility deployment.
- LiDAR-Computer Vision Convergence:Sensor fusion architectures enable navigation in dynamic, clutter-rich environments without facility retrofit. This technology pairing opens nursing home segments previously excluded by infrastructure limitations.
- China's NMPA Cybersecurity Mandates:The tightened network security standards for AI-enabled medical devices create compliance service demand. Third-party validation providers are establishing specialized practices for connected robot platforms.
Industry Challenges
- Clinical Engineering Talent Scarcity:Health systems lack sufficient biomedical technicians trained in autonomous system maintenance. This skill gap extends mean time to repair and strains existing clinical engineering departments.
- Legacy HIS Integration Complexity:Hospital information system architectures vary widely across installed bases. Robot fleet management software requires custom middleware development for each major electronic health record vendor.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Service Robots Market |
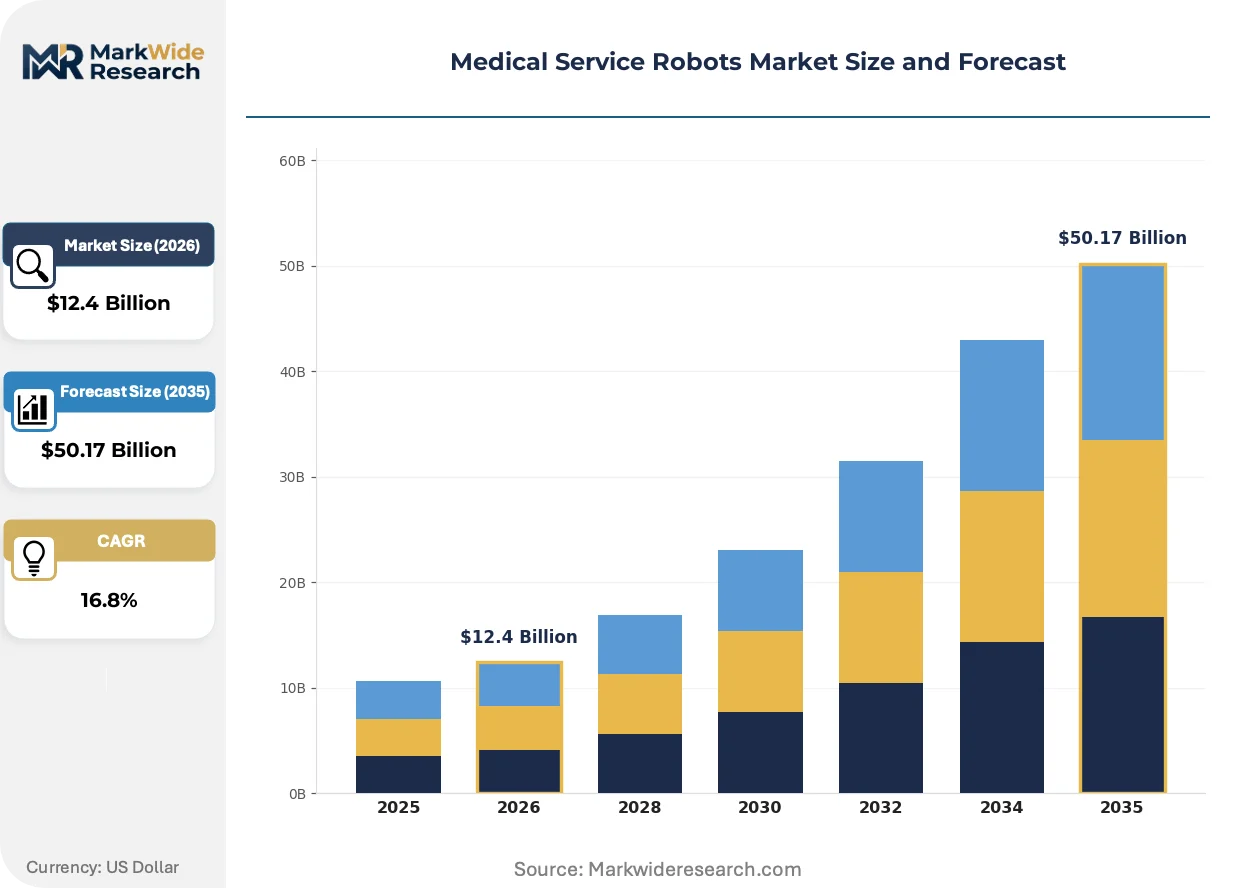
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $50.17 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Robots, Rehabilitation Robots, Telepresence Robots, Disinfection Robots End User: Hospitals, Nursing Homes, Rehabilitation Centers, Home Care Providers Technology: Artificial Intelligence, Machine Learning, Robotics Process Automation, Sensor Technology Application: Surgery Assistance, Patient Monitoring, Medication Delivery, Environmental Cleaning |
| Companies Covered | Toyota Motor Corp., Panasonic, Aethon, Nordson Corp., Blue Ocean Robotics, Xenex Disinfection Services, InTouch Health, Nuro, Inc., Diligent Robotics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Service Robots Market Strategic Shifts & Innovations
Autonomous navigation architectures are migrating from infrastructure-dependent beacon systems to infrastructure-free simultaneous localization and mapping. This shift is collapsing deployment timelines and expanding addressable facility types.
Semiconductor-based solid-state LiDAR is supplanting mechanical spinning sensors in hospital logistics robots. The technology eliminates moving parts, reducing failure rates in continuous-use environments. United States health systems are specifying solid-state configurations in fleet procurement tenders. The transition is compressing maintenance contract pricing and extending robot service intervals.
The EU AI Act's risk classification framework for machine learning in medical devices imposes conformity assessment obligations on autonomous decision systems. Robot manufacturers must document algorithmic transparency and human oversight protocols. Telepresence platforms with diagnostic suggestion features face heightened scrutiny in German and French regulatory submissions. Vendors are restructuring product architectures to isolate high-risk AI components from core navigation systems.
Leasing structures are displacing capital purchase models in North American hospital procurement. Health systems conserve balance sheet capacity while accessing latest-generation disinfection and logistics platforms. Robot-as-a-service providers assume residual value risk and lifecycle maintenance obligations. This financing innovation is most visible in United States integrated delivery networks with constrained capital budgets and high bed-turnover pressure.
Medical Service Robots Market Segmentation
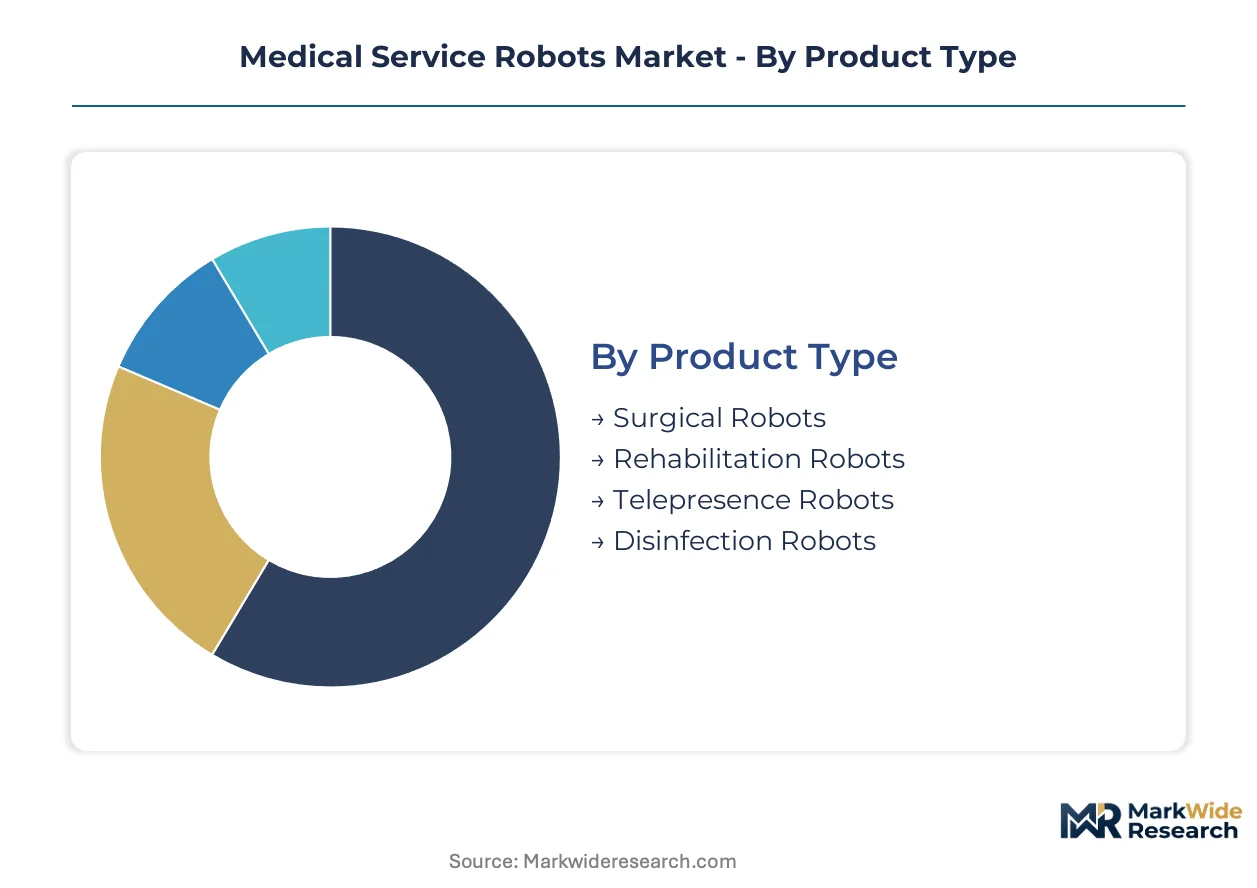
Segmentation in medical service robotics reveals how regulatory pathways, reimbursement codes, and facility infrastructure shape procurement patterns across distinct product categories and deployment settings. Understanding these divides enables manufacturers to sequence market entry and align technical specifications with buyer readiness.
Product Type:
FDA 510(k) clearance timelines vary dramatically across product categories, with surgical systems facing the most extensive clinical evidence requirements while disinfection platforms benefit from streamlined predicates.
- Surgical Robots:These systems integrate multi-arm manipulators with haptic feedback and real-time imaging for minimally invasive procedures. Demand concentrates in United States academic medical centers where bundled payment models reward reduced complication rates. Da Vinci's installed base creates high switching costs for competing platforms.
- Rehabilitation Robots:Exoskeleton and end-effector devices deliver automated physical therapy with quantifiable range-of-motion metrics. German rehabilitation clinics drive procurement where statutory health insurance reimbursement codes have stabilized for stroke and spinal cord indications. Patient throughput improvements justify capital outlays.
- Telepresence Robots:Mobile platforms with audiovisual links enable remote specialist consultation in rural and understaffed facilities.
- Disinfection Robots:Autonomous ultraviolet-C and hydrogen peroxide vapor systems target hospital-acquired infection reduction.
Established volume favors surgical robots; emerging adoption favors disinfection robots.
End User:
Capital availability and purchasing authority fragmentation create tiered market access, with centralized hospital procurement contrasting sharply with decentralized nursing home decision-making.
- Hospitals:Integrated delivery networks in the United States deploy fleet-scale logistics and disinfection robots to address staffing shortages. Value analysis committees evaluate total cost of ownership including training and maintenance infrastructure.
- Nursing Homes:These facilities represent the most underserved segment due to thin operating margins and lack of dedicated clinical engineering staff. Japan's PMDA fast-track approvals for elder-care platforms are unlocking demand in municipally funded facilities.
- Rehabilitation Centers:Specialized outpatient and inpatient facilities prioritize functional outcome measurement capabilities.
- Home Care Providers:Distributed care models create deployment complexity for mobile platforms requiring reliable connectivity.
Procurement sophistication peaks in hospitals; penetration potential concentrates in nursing homes.
Technology:
Software validation burdens under EU MDR and FDA software-as-a-medical-device guidance are reshaping R&D allocation between algorithmic innovation and regulatory documentation.
- Artificial Intelligence:Diagnostic suggestion and autonomous decision modules face heightened scrutiny under EU AI Act risk classification frameworks. German notified bodies require algorithmic transparency documentation that extends development timelines.
- Machine Learning:Adaptive navigation systems trained on facility-specific floor plans reduce deployment customization. United States health systems specify continuous learning capabilities in logistics robot tenders.
- Robotics Process Automation:Structured workflow automation for medication and supply delivery operates within deterministic safety parameters.
- Sensor Technology:LiDAR-computer vision fusion enables infrastructure-free navigation in cluttered clinical environments.
Regulatory burden weighs heaviest on AI; deployment flexibility favors sensor fusion.
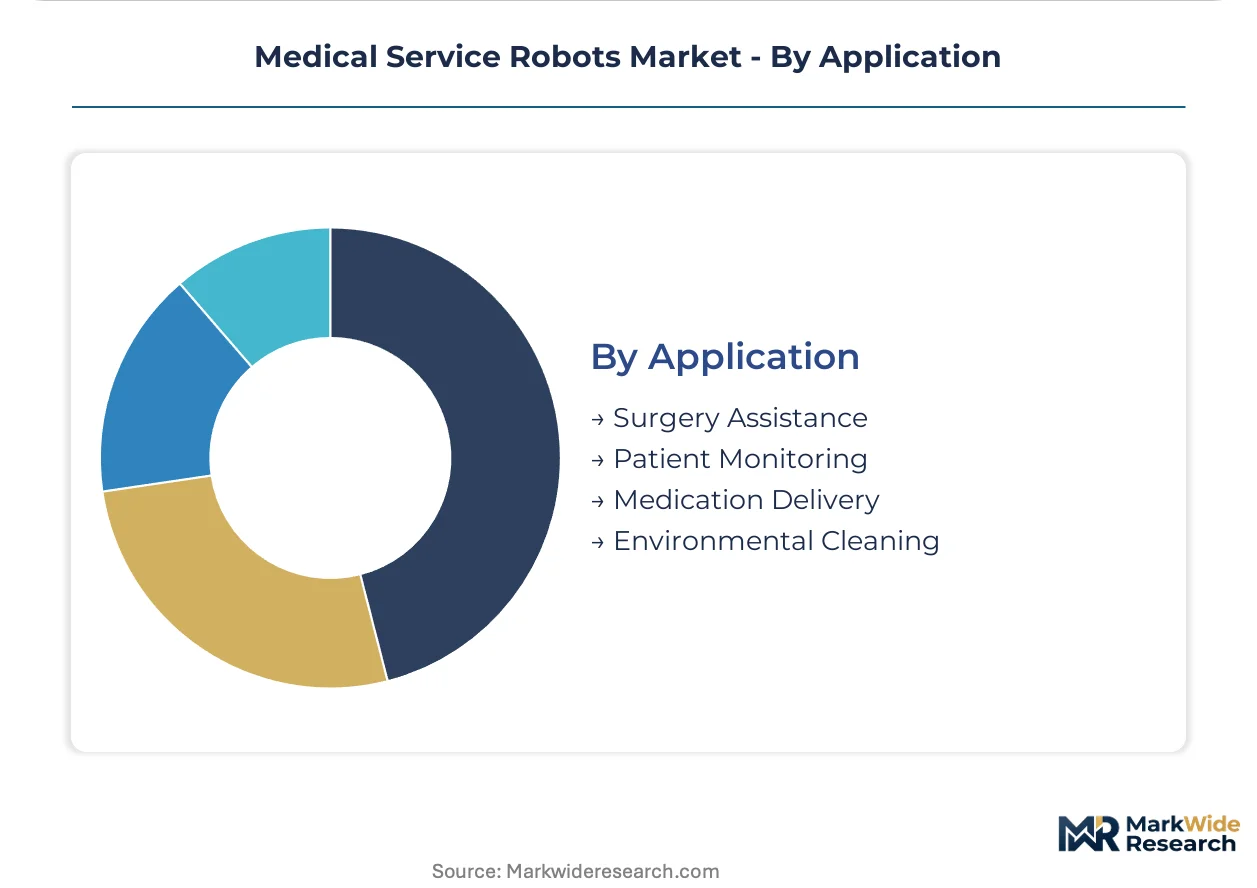
Application:
Reimbursement code availability and infection control budget allocations determine which applications convert from pilot programs to fleet-scale deployment.
- Surgery Assistance:Robotic-assisted procedures command premium reimbursement in United States commercial and Medicare Advantage plans. Hospital systems amortize capital costs across high-volume service lines including urology and gynecology.
- Patient Monitoring:Continuous vital sign and mobility tracking robots reduce falls and deterioration events in elder-care settings. Japan's regulatory fast-track accelerates domestic deployment in aging facilities.
- Medication Delivery:Autonomous mobile robots transport pharmaceuticals from central pharmacy to nursing units.
- Environmental Cleaning:Automated disinfection workflows replace manual ultraviolet-C tower placement and chemical fogging protocols.
Reimbursement stability anchors surgery assistance; pandemic-hardened budgets drive environmental cleaning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital systems in Germany and Japan demonstrate low price elasticity for surgical and disinfection platforms, while nursing homes in Italy and long-term care facilities in Canada exhibit acute capital constraints that compress procurement timelines and favor leasing structures.
United States
Integrated delivery networks in Texas and Florida deploy fleet-scale logistics robots to address acute nursing shortages in high-turnover units. FDA 510(k) pre-submission programs for autonomous mobile platforms accelerate clearance pathways for disinfection vendors. The Boston-Cambridge corridor concentrates venture-backed telepresence developers targeting rural hospital consultation gaps.
Germany
Statutory health insurance reimbursement codes for automated physical therapy stabilize demand for rehabilitation robots in Bavarian and North Rhine-Westphalian clinics. EU MDR harmonized technical documentation enables cross-border certification reciprocity for logistics platforms. The Stuttgart precision manufacturing cluster supplies compact harmonic drive actuators to global OEMs at volume scale.
Japan
Municipally funded elder-care facilities in Osaka and Nagoya expand procurement of patient monitoring and mobility assistance platforms. PMDA streamlined approval pathways for elder-care robotics compress domestic deployment timelines. The Nagoya industrial corridor hosts precision actuator manufacturers serving both automotive and medical robot supply chains.
China
Tier-one hospital systems in Shanghai and Beijing pilot AI-enabled service robots despite tightened NMPA cybersecurity documentation requirements for networked devices. The Yangtze River Delta manufacturing base concentrates battery cell production for mobile robot power systems. Domestic integrators face input cost volatility from lithium-ion supply concentration.
United Kingdom
NHS trusts in London and Manchester evaluate robot-as-a-service models to conserve capital budgets for disinfection and medication delivery platforms. MHRA alignment with EU MDR technical standards preserves cross-border market access for German and French suppliers. The Oxford-Cambridge arc hosts early-stage developers targeting surgical assistance applications.
Medical Service Robots Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in medical service robotics. Toyota Motor Corp. leverages automotive manufacturing scale to produce precision actuators at unit economics that pure-play medical firms struggle to match. Blue Ocean Robotics sustains diversified exposure across disinfection and telepresence applications, reducing single-segment concentration risk. Diligent Robotics occupies a narrow but defensible niche in autonomous hospital logistics. Competitive moves concentrate on M&A for sensor technology capabilities and strategic partnerships with health system integrators to secure fleet-scale procurement contracts.
Within the diversified industrial tier, Toyota Motor Corp. and Panasonic exemplify manufacturers leveraging adjacent sector capabilities to enter clinical automation. Among pure-play specialists, Blue Ocean Robotics and Diligent Robotics occupy positions defined by application focus rather than vertical integration depth. Xenex Disinfection Services represents the segment-specific vendor archetype targeting infection control budgets with ultraviolet-C platform specialization.
| Leading Market Players |
|---|
| Toyota Motor Corp. |
| Panasonic |
| Aethon |
| Nordson Corp. |
| Blue Ocean Robotics |
| Xenex Disinfection Services |
| InTouch Health |
| Nuro, Inc. |
| Diligent Robotics |
| Others |
Cost & Logistics Intelligence
Solid-state LiDAR substitution for mechanical spinning sensors is redrawing component sourcing maps toward Japanese and United States precision optics manufacturers while collapsing maintenance contract pricing for hospital fleet operators. This displacement simultaneously concentrates sensor supply in East Asian industrial corridors and compresses aftermarket revenue pools for legacy hardware vendors.
Pricing Analysis
Multi-year service contracts and spare parts provisioning generate lifetime value exceeding initial hardware outlays by substantial margins. Three-tier pricing structure across premium FDA-cleared platforms, standard CE-marked configurations, and economy refurbishment tiers segments buyer access. Cost compression in the economy tier is intensifying because Chinese integrators are flooding secondary markets with decommissioned hospital logistics units. Nursing homes exhibit acute price sensitivity due to thin operating margins, while United States academic medical centers prioritize clinical validation over acquisition cost.
Supply Chain Analysis
Strait of Malacca transit underwrites lithium-ion cell delivery schedules for European and North American robot assemblers, exposing fleets to maritime chokepoint risk. Battery cell production concentrates in China, South Korea, and Japan; compact harmonic drive actuators draw from German and Japanese precision manufacturing clusters. Single-source vulnerability pervades solid-state LiDAR emitter arrays, where qualified vendors number fewer than five globally. Distribution runs through hospital group purchasing organizations and regional medical equipment distributors with exclusive territory agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The medical service robots sector is experiencing high-growth disruption as FDA 510(k) pre-submission programs compress autonomous platform clearance timelines from years to months. This regulatory inflection is forcing immediate strategic repositioning across incumbent, entrant, and investor archetypes.
For Market Incumbents: Consolidate sensor technology capabilities through targeted component supplier acquisitions before Japanese precision manufacturers extend dominance into medical-grade LiDAR. Lock in hospital system fleet procurement contracts with embedded upgrade pathways that neutralize emerging software-centric platform vendors. Vertical integration into compact actuator production defends margin position against Toyota Motor Corp.'s automotive scale economics. For New Entrants and Emerging Players: Post-acute care software integration represents a service-layer gap where incumbents under-serve nursing home medication management workflows. Target Japan's municipally funded elder-care facilities where PMDA fast-track approvals compress competitive response windows. Lead with robot-as-a-service financing structures that eliminate capital committee friction in budget-constrained long-term care segments. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed telepresence developers that expanded rapidly during pandemic-era rural hospital consultation demand. Five-to-ten year viability hinges on successful navigation from pilot deployments to fleet-scale recurring revenue. Watch FDA enforcement discretion on autonomous decision systems as the inflection signal distinguishing platform-scale winners from stranded hardware investments.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Secures fleet-scale procurement contracts with integrated delivery networks in Texas and Florida. |
| FDA 510(k) Pre-Submission | Accelerates clearance pathways for autonomous disinfection platforms targeting infection control budgets. |
| Sensor Technology Acquisition | Captures solid-state LiDAR capabilities before Japanese suppliers extend medical market dominance. |
| Robot-as-a-Service Launch | Conserves hospital balance sheet capacity while locking in long-term maintenance revenue streams. |
| EU MDR Conformity Investment | Enables cross-border certification reciprocity for logistics platforms in German hospital groups. |
Research Approach
Initial hypotheses were tested against primary input from hospital purchasing committee directors, biomedical engineering managers, GPO contracts specialists, and regulatory affairs leads at autonomous platform developers, then refined against secondary validation. FDA 510(k) clearance databases, EU MDR notified body registers, hospital procurement transaction records, and CMS Medicare reimbursement code filings anchored quantitative baselines. Bottom-up facility-level deployment estimates and top-down manufacturer revenue analysis were triangulated to constrain variance.
Variance decomposition across product type, end-user facility tier, navigation technology architecture, and geographic regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from installed base growth trajectories and replacement cycle assumptions. Forecast inputs incorporated PMDA approval velocity for elder-care platforms and NMPA cybersecurity documentation burden effects on Chinese market penetration.
Forecasts assume regulatory continuity in FDA pre-submission programs, EU MDR harmonized standards, and Japan PMDA elder-care fast tracks; material policy shifts would require re-modeling. Cybersecurity standard evolution, lithium-ion supply disruption, and reimbursement code revision for automated physical therapy represent specific revision risks. Practitioners should keep alternative scenarios live as health system staffing crisis severity and AI Act enforcement discretion evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Medical Rehabilitation Robotics Market
Robotics and Automation
Robotic Coffee Bars Market
Robotics and Automation
South Korea Cloud Robotics Market
Robotics and Automation
Robotics Actuators Market
Robotics and Automation
Global Robotic Grippers Market
Robotics and Automation
Professional Service Robots Market
Robotics and Automation
Robotic Drilling Market
Robotics and Automation
Global Demolition Robots Market
Robotics and Automation
Delta Robots Market
Robotics and Automation
Italy Cloud Robotics Market
Robotics and Automation
Rehabilitation Robot Gloves Market
Robotics and Automation
Europe Underwater Robotics Market
Robotics and Automation
Modular Robotics Market
Robotics and Automation
Europe Educational Robot Market
Robotics and Automation
Robot Market
Robotics and Automation
Global All Terrain Robots Market