
 Medical Robots Market | 2026-2036
Medical Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Robots Market Analysis
Hospital procurement of surgical systems is pivoting toward integrated platforms that combine teleoperation with imaging systems. Intuitive Surgical leverages its installed base of da Vinci systems to sustain recurring instrument revenue. Stryker Corporation anchors its Mako platform in orthopedic robotics, competing directly with Zimmer Biomet Holdings in knee and hip replacement applications.
Medical robots encompass electromechanical systems with sub-millimeter positioning accuracy, force feedback resolution below 0.1 newton, and real-time imaging fusion for minimally invasive intervention. These systems serve to extend surgeon precision, reduce tissue trauma, and standardize outcomes across heterogeneous clinical settings. Surgical robots occupy the largest value pool, while disinfection robots represent the fastest-expanding segment as hospitals prioritize infection control. Rehabilitation robots command premium pricing through haptic feedback integration, whereas telepresence robots face margin compression from commoditized video-conferencing hardware.
FDA 510(k) pathways and EMA MDR compliance requirements determine market access timelines for new platforms. ISO 13485 quality management and IEC 60601 electrical safety standards govern manufacturing consistency across jurisdictions. Stakeholders must monitor reimbursement decisions by CMS and Germany's G-BA, as these directly dictate hospital capital allocation toward robotic platforms.
Market Dynamics
Hospital procurement of surgical systems is pivoting toward integrated platforms that combine teleoperation with imaging systems. This structural shift compresses vendor margins on standalone hardware while elevating recurring revenue from consumables and software subscriptions.
Growth Catalysts
- CMS Reimbursement Expansion:The Centers for Medicare and Medicaid Services in the United States has broadened coverage for robotic-assisted procedures in oncology and gynecology, directly accelerating hospital capital allocation toward surgical platforms.
- Force Feedback Resolution:Advances in haptic sensor technology enabling sub-0.1 newton precision are extending robotic applications into microsurgical domains previously restricted to manual techniques.
- Japan's Super-Aged Society:Demographic pressure in Japan is driving Ministry of Health, Labour and Welfare incentives for rehabilitation robotics to offset labor shortages in physical therapy.
Market Restraints
- Capital Equipment Intensity:Surgical robot systems require upfront investments exceeding $2 million per unit, constraining adoption to tier-one academic medical centers and excluding community hospitals.
- Supply Concentration:High-precision harmonic drive actuators for robotic arms depend on a concentrated supplier base in Germany and Japan, creating vulnerability to component shortages.
- Technical Limitation:Current teleoperation systems exhibit latency above 50 milliseconds for transcontinental procedures, limiting real-time surgical collaboration across distant geographies.
Strategic Opportunities
- Rural Hospital Penetration:Telepresence robots for specialist consultation remain underdeployed in rural United States health systems, creating whitespace for platform-as-a-service models.
- EU MDR Compliance Services:The European Union's Medical Device Regulation mandates enhanced clinical evidence for Class III devices, opening advisory revenue streams for regulatory consultancies.
- AI-Imaging Convergence:Integration of real-time computer vision with robotic control systems is enabling autonomous tissue recognition during laparoscopic procedures.
Industry Challenges
- Specialized Surgical Training:Robotic-assisted procedures require 50-100 proctored cases for competency certification, creating bottlenecks in qualified operator supply.
- Legacy System Integration:Hospital IT infrastructure fragmentation complicates data exchange between robotic platforms and electronic health record systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Robots Market |
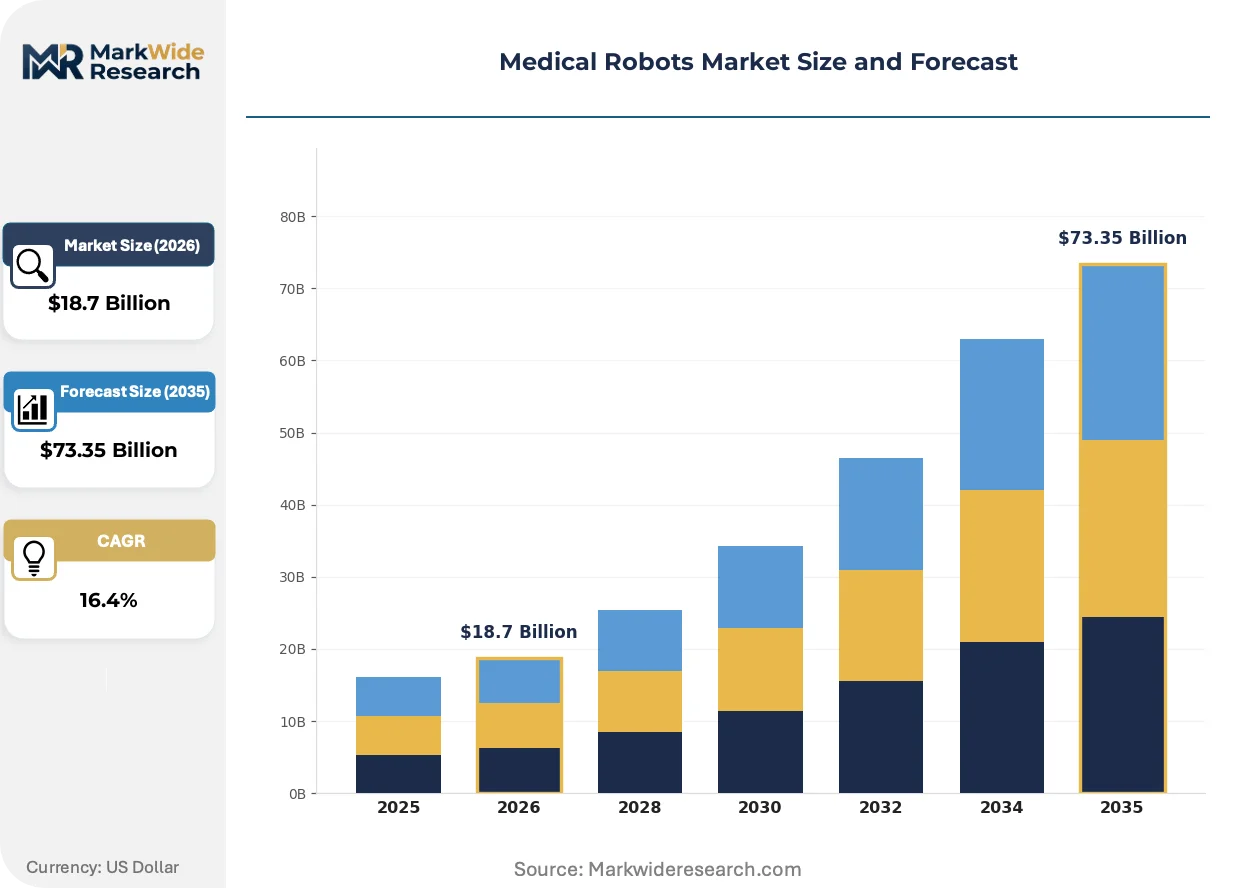
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Robots, Rehabilitation Robots, Telepresence Robots, Disinfection Robots End User: Hospitals, Clinics, Research Institutes, Home Care Application: Orthopedics, Neurosurgery, Urology, Cardiovascular Technology: AI Integration, Teleoperation, Haptic Feedback, Imaging Systems |
| Companies Covered | Intuitive Surgical, Stryker Corporation, Medtronic, Zimmer Biomet Holdings, Smith & Nephew, CMR Surgical, Accuray, Ekso Bionics Holdings, Hocoma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Robots Market Emerging Trajectories
Software-defined functionality is displacing hardware-centric design across medical robot categories. Vendors now monetize through recurring software licenses rather than one-time equipment sales, compressing traditional capital expenditure cycles into operational expenditure models.
Multi-port robotic architectures are consolidating market preference over single-port alternatives. Hospital purchasing committees favor systems enabling flexible procedure conversion without platform switching. Academic medical centers in the United States and Germany are standardizing on these configurations, forcing smaller vendors to abandon narrow-application designs or exit surgical robotics entirely.
The FDA's 510(k) clearance pathway for AI-integrated devices is tightening evidentiary requirements for machine learning-enabled surgical systems. Manufacturers must now submit algorithm training datasets and performance validation across demographic subgroups. Orthopedic robotics applications face the steepest compliance burden, with PMA-level scrutiny increasingly applied to autonomous bone-cutting features.
Hospital buying committees are unbundling after-sales service contracts from equipment procurement. Third-party technical service providers in the United States are capturing maintenance revenue previously retained by original equipment manufacturers. This disintermediation is most pronounced in disinfection robotics, where standardized components enable independent servicing.
Medical Robots Market Segmentation
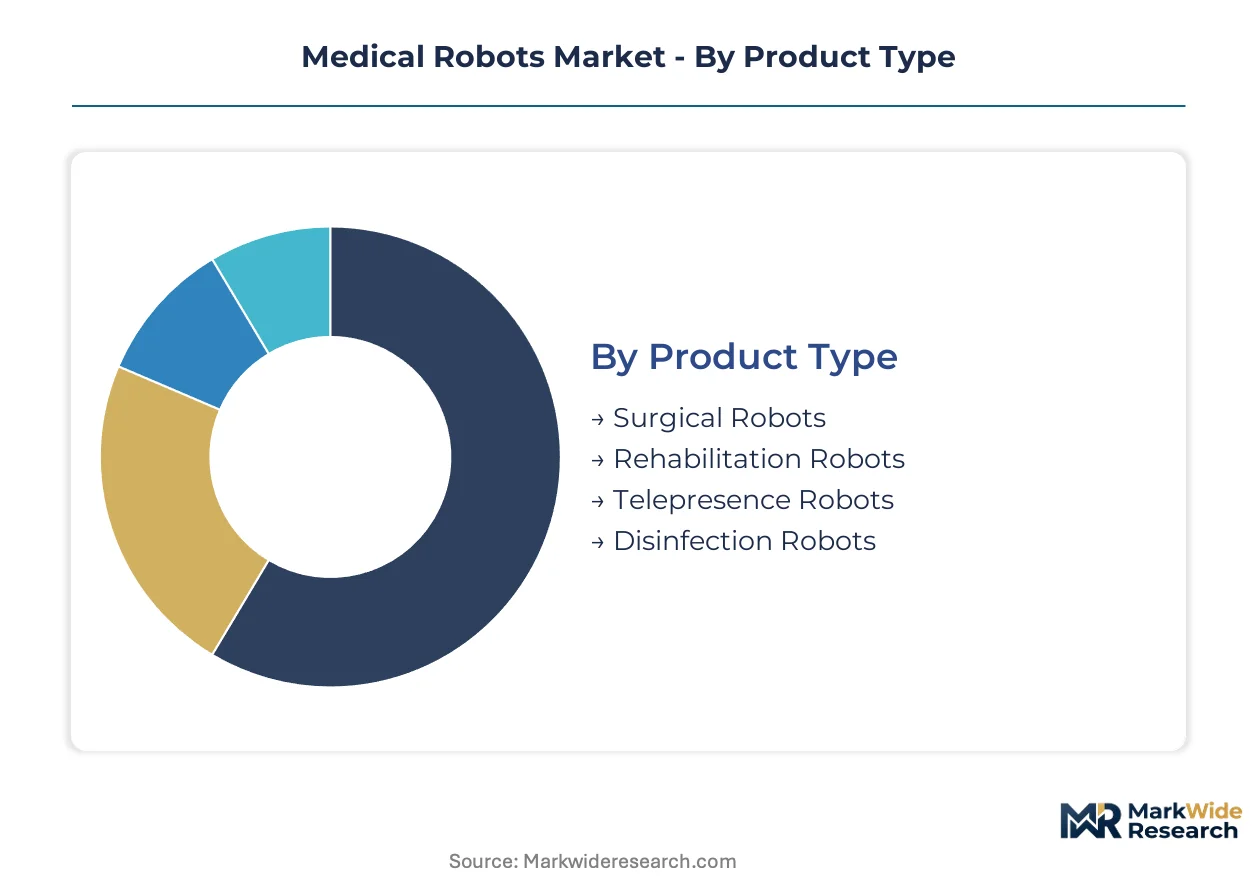
Medical robot procurement decisions fragment across four intersecting dimensions. Product architecture determines capital intensity and recurring revenue potential. End-user scale dictates service contract structures and regulatory pathways.
Product Type:
Customization intensity spans from fully configurable surgical platforms to standardized disinfection units with minimal field adjustment.
- Surgical Robots:Multi-arm electromechanical systems integrate force feedback below 0.1 newton with real-time imaging fusion. Demand concentrates in United States academic medical centers where CMS reimbursement expansion for oncology and gynecology procedures justifies $2 million-plus capital outlays.
- Rehabilitation Robots:Exoskeleton and end-effector devices incorporate haptic feedback for motor relearning protocols. Japan's Ministry of Health, Labour and Welfare incentives are accelerating deployment in super-aged society care settings facing physical therapist shortages.
- Telepresence Robots:Mobile video-conferencing platforms enable remote specialist consultation with commoditized hardware margins.
- Disinfection Robots:UV-C and hydrogen peroxide vapor autonomous units target hospital-acquired infection reduction with fastest-expanding deployment trajectories.
Most installed capacity flows through Surgical Robots. Expansion is steepest in Disinfection Robots.
End User:
Customer scale determines procurement modality, from centralized health system tenders to individual physician practice leases.
- Hospitals:Integrated delivery networks negotiate enterprise-wide platform contracts bundling hardware, software, and training. United States tier-one academic centers anchor procurement volume for multi-port surgical systems.
- Clinics:Ambulatory surgical centers favor compact single-procedure platforms with lower capital thresholds and faster depreciation cycles.
- Research Institutes:Preclinical validation sites drive early-stage protocol development for FDA 510(k) and EMA MDR submission pathways.
- Home Care:Direct-to-patient rehabilitation devices face reimbursement fragmentation but expanding remote monitoring integration.
Hospital procurement dominates capital deployment. Home Care is gaining share fastest as wearable rehabilitation form factors mature.
Application:
Clinical specificity ranges from standardized joint replacement workflows to patient-specific neurovascular interventions.
- Orthopedics:Knee and hip arthroplasty platforms incorporate preoperative CT-based planning with intraoperative navigation. Stryker's Mako and Zimmer Biomet systems compete directly in United States and German markets where G-BA reimbursement decisions shape adoption.
- Neurosurgery:Stereotactic frames and endoscopic platforms require sub-millimeter accuracy for deep brain stimulation and tumor resection.
- Urology:Radical prostatectomy represented the first mass-market robotic procedure; procedure volumes now plateau in mature markets.
- Cardiovascular:Percutaneous coronary intervention and electrophysiology mapping systems face stringent PMA-level FDA scrutiny for autonomous catheter control.
Orthopedics commands the largest procedure volume. Cardiovascular is climbing the fastest as structural heart interventions expand.
Technology:
Intellectual property intensity varies from commoditized teleoperation protocols to proprietary AI training datasets.
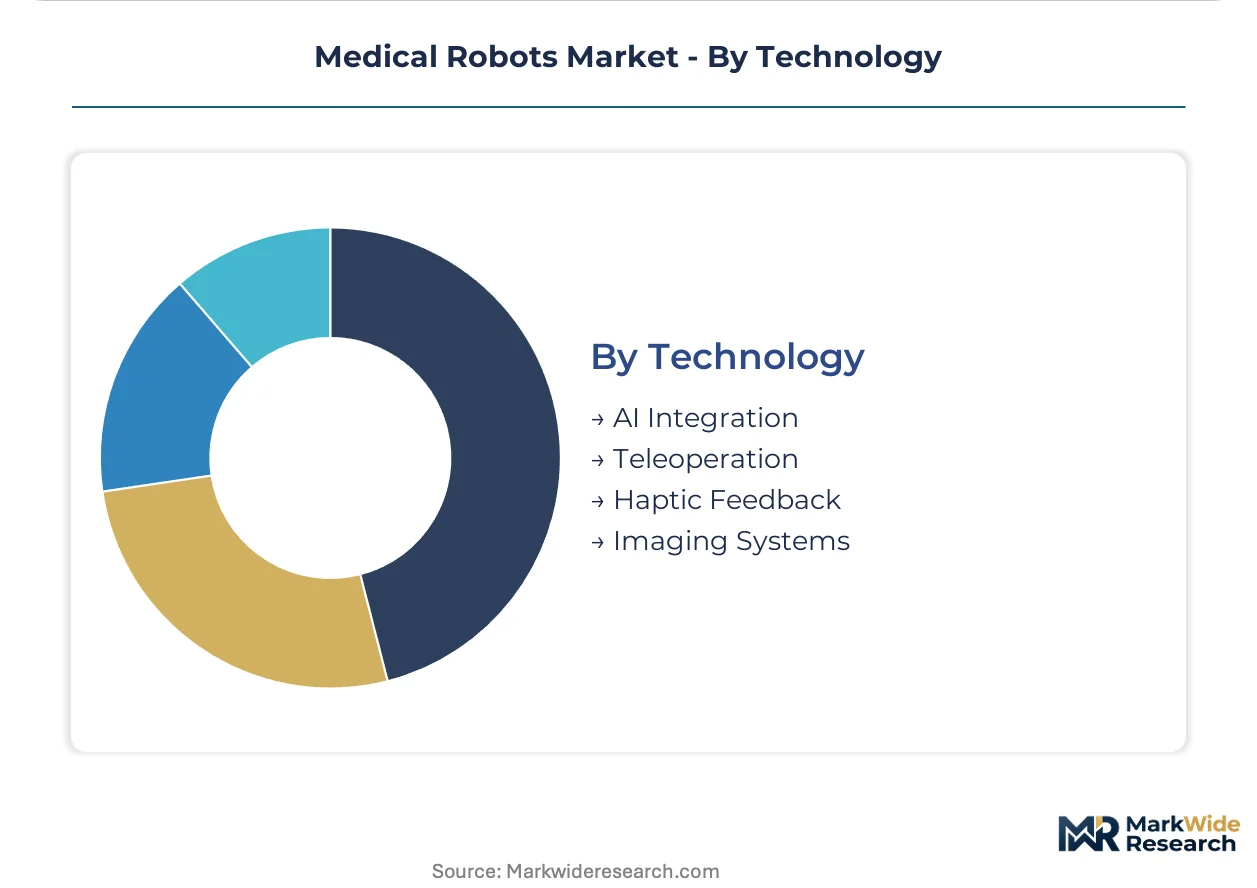
- AI Integration:Machine learning algorithms for tissue recognition and autonomous suturing face tightened FDA evidentiary requirements including demographic subgroup validation.
- Teleoperation:Master-slave architectures with 50-millisecond latency floors constrain transcontinental real-time collaboration.
- Haptic Feedback:Force sensor arrays enabling tissue compliance discrimination command premium pricing in microsurgical applications.
- Imaging Systems:Intraoperative fluorescence and OCT fusion are becoming standard configuration in new platform tenders.
Imaging Systems anchor current procurement specifications. AI Integration shows steepest R&D allocation growth as autonomous features advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan deploys rehabilitation robotics at scale to offset demographic collapse, while Germany concentrates surgical platform manufacturing around precision actuator supply chains. Both markets illustrate how regulatory frameworks and industrial policy reshape procurement geography.
United States
FDA 510(k) clearance volumes for AI-integrated surgical systems outpace other jurisdictions, with CMS reimbursement expansion for oncology and gynecology procedures accelerating hospital capital allocation. The FDA's tightened evidentiary requirements for machine learning-enabled devices now mandate demographic subgroup validation. Academic medical centers in Boston and the San Francisco Bay Area anchor multi-port surgical system standardization.
Germany
G-BA reimbursement decisions for robotic-assisted orthopedic procedures directly dictate hospital procurement timelines, with knee and hip arthroplasty platforms commanding premium positioning. EMA MDR compliance requirements for Class III devices extend market access timelines but elevate manufacturing quality benchmarks. The Stuttgart and Munich industrial clusters host concentrated harmonic drive actuator production for robotic arm precision.
Japan
Ministry of Health, Labour and Welfare incentives target rehabilitation robotics deployment to address physical therapist shortages in super-aged care settings. METI industrial policy supports domestic manufacturing of haptic feedback systems for motor relearning protocols. The Tokyo-Osaka corridor concentrates exoskeleton development facilities serving both clinical and home care applications.
China
NMPA regulatory pathways for surgical robots are converging toward international standards, accelerating domestic platform development for laparoscopic and orthopedic applications. Hospital procurement in tier-one cities prioritizes integrated imaging-teleoperation systems over standalone hardware. The Yangtze River Delta manufacturing base is scaling precision actuator production to reduce import dependency.
United Kingdom
NHS England specialized commissioning frameworks determine robotic surgery access thresholds, concentrating deployment in designated cancer centers and academic hospitals. MHRA post-Brexit regulatory autonomy is diverging from EMA timelines for AI-integrated device approvals. The Cambridge and Oxford clusters host preclinical validation sites for FDA 510(k) and EMA MDR submission pathways.
Medical Robots Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across medical robot categories, creating a tiered market structure where scale advantages clash with application-specific agility. The vendor base organizes around three strategic archetypes: integrated surgical platform providers, orthopedic navigation specialists, and rehabilitation exoskeleton developers. M&A activity concentrates on imaging-robotics convergence capabilities, while geographic expansion targets CMS-reimbursed procedures in United States academic centers and G-BA-covered applications in German hospitals.
Within the integrated surgical platform tier, Intuitive Surgical and Stryker Corporation exemplify contrasting diversification strategies. Intuitive Surgical anchors recurring revenue models through installed base expansion, while Stryker Corporation occupies orthopedic robotics positioning through platform-specific navigation systems. Medtronic represents the diversified conglomerate archetype, spanning multiple intervention categories through portfolio breadth rather than single-application depth.
| Leading Market Players |
|---|
| Intuitive Surgical |
| Stryker Corporation |
| Medtronic |
| Zimmer Biomet Holdings |
| Smith & Nephew |
| CMR Surgical |
| Accuray |
| Ekso Bionics Holdings |
| Hocoma |
| Others |
Supply Flow & Price Mechanics
Software-defined functionality is displacing hardware-centric design across medical robot categories, simultaneously compressing upfront capital expenditure cycles into operational expenditure models and concentrating value capture among vendors with recurring revenue platforms. This transition elevates pricing power for integrated system providers while eroding margins on standalone hardware producers.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for precision actuator components. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA 510(k) clearance tier and ISO 13485 certification status. Cost compression in telepresence hardware is intensifying because video-conferencing component commoditization accelerates. Ambulatory surgical centers exhibit highest price sensitivity; academic medical centers with CMS reimbursement coverage show lowest.
Supply Chain Analysis
Domestic-content mandates in China's NMPA regulatory framework are reshaping sourcing patterns for surgical platform manufacturers. High-precision harmonic drive actuators draw from concentrated production in Germany, Japan, and emerging Chinese capacity. Supply chain risk centers on single-source vulnerability for sub-0.1 newton force feedback sensors. Distribution runs through integrated delivery network procurement committees and GPO contracts in United States hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Medical Robots Market reads as a late-cycle quality story where hospital procurement committees now prioritize integrated imaging-teleoperation platforms over standalone hardware, elevating vendors with software subscription capabilities.
For Market Incumbents: Anchor recurring revenue models through installed base expansion of multi-port surgical systems while defending against emerging pure-play AI-imaging convergence specialists. Deepen backward integration into haptic feedback sensor production to offset supply concentration risk in German and Japanese actuator suppliers. Prioritize ISO 13485 quality management certification maintenance as EMA MDR compliance timelines extend. For New Entrants and Emerging Players: Launch via platform-as-a-service models targeting rural United States hospital systems where telepresence specialist consultation remains underdeployed. Exploit whitespace in EU MDR compliance advisory services as Class III device evidentiary requirements tighten. Pursue home care rehabilitation robotics where wearable form factors face reimbursement fragmentation but remote monitoring integration expands addressable demand. For Investors and Strategic Acquirers: Roll-up economics work for orthopedic navigation specialists because G-BA reimbursement decisions in Germany and CMS expansion in the United States create predictable hospital capital allocation toward knee and hip arthroplasty platforms. Target acquisition profiles emphasizing AI training dataset proprietary access and demographic subgroup validation capabilities. Watch FDA PMA-level scrutiny intensity for autonomous bone-cutting features as inflection indicator for orthopedic robotics compliance burden trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Clearance volumes for AI-integrated devices outpace other jurisdictions, mandating demographic subgroup validation. |
| Hospital System Partnership | Integrated delivery networks negotiate enterprise-wide platform contracts bundling hardware, software, and training. |
| CE Marking Pathway | EMA MDR compliance requirements for Class III devices extend market access timelines but elevate quality benchmarks. |
| Software Companion Development | Recurring software licenses displace one-time equipment sales, compressing capital expenditure into operational expenditure models. |
| Reimbursement Strategy | CMS coverage expansion for oncology and gynecology procedures directly accelerates hospital capital allocation. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and regulatory affairs specialists with secondary validation against FDA 510(k) filings, EMA MDR submission databases, CMS Medicare reimbursement data, and hospital procurement records. Bottom-up segment sizing and top-down market triangulation cross-verified volume and value estimates.
Segment-weighting approaches modeled surgical robots, rehabilitation robots, telepresence robots, and disinfection robots across product architecture, end-user scale, clinical application, and technology integration dimensions. CAGRs were derived from procedure volume trajectories, reimbursement expansion schedules, and capital expenditure cycle analysis across the projection horizon. Force feedback resolution benchmarks and AI training dataset availability served as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under NMPA regulatory pathway convergence delays or harmonic drive actuator supply disruptions. Forecasts reflect documented assumptions regarding CMS reimbursement continuity and EMA MDR implementation timelines. A small set of named triggers—including FDA PMA-level scrutiny intensity for autonomous surgical features and Japan's Ministry of Health, Labour and Welfare incentive program extensions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Agricultural Robots and Mechatronics Market
Robotics and Automation
Europe AUV Market
Robotics and Automation
Mobile Stabilizer Market
Robotics and Automation
Robotics Technology Market
Robotics and Automation
Global Robot Software Market
Robotics and Automation
Global Soldering Robot Market
Robotics and Automation
Robotics for NDT Market
Robotics and Automation
Delta Robots Market
Robotics and Automation
Human-Robot Collaborative Picking Optimization Platforms Market
Robotics and Automation
Global Soft Robotics Market
Robotics and Automation
Global Robot Teach Pendant Market
Robotics and Automation
UV-C Disinfection Robots Market
Robotics and Automation
Gantry (Cartesian) Robot Market
Robotics and Automation
Humanoid Robot Market
Robotics and Automation
Intelligent Vending Machines Market
Robotics and Automation
Europe Automated Liquid Handling Market