
 Global Position Tracking System Market | 2026-2036
Global Position Tracking System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Position Tracking System Market Foresight
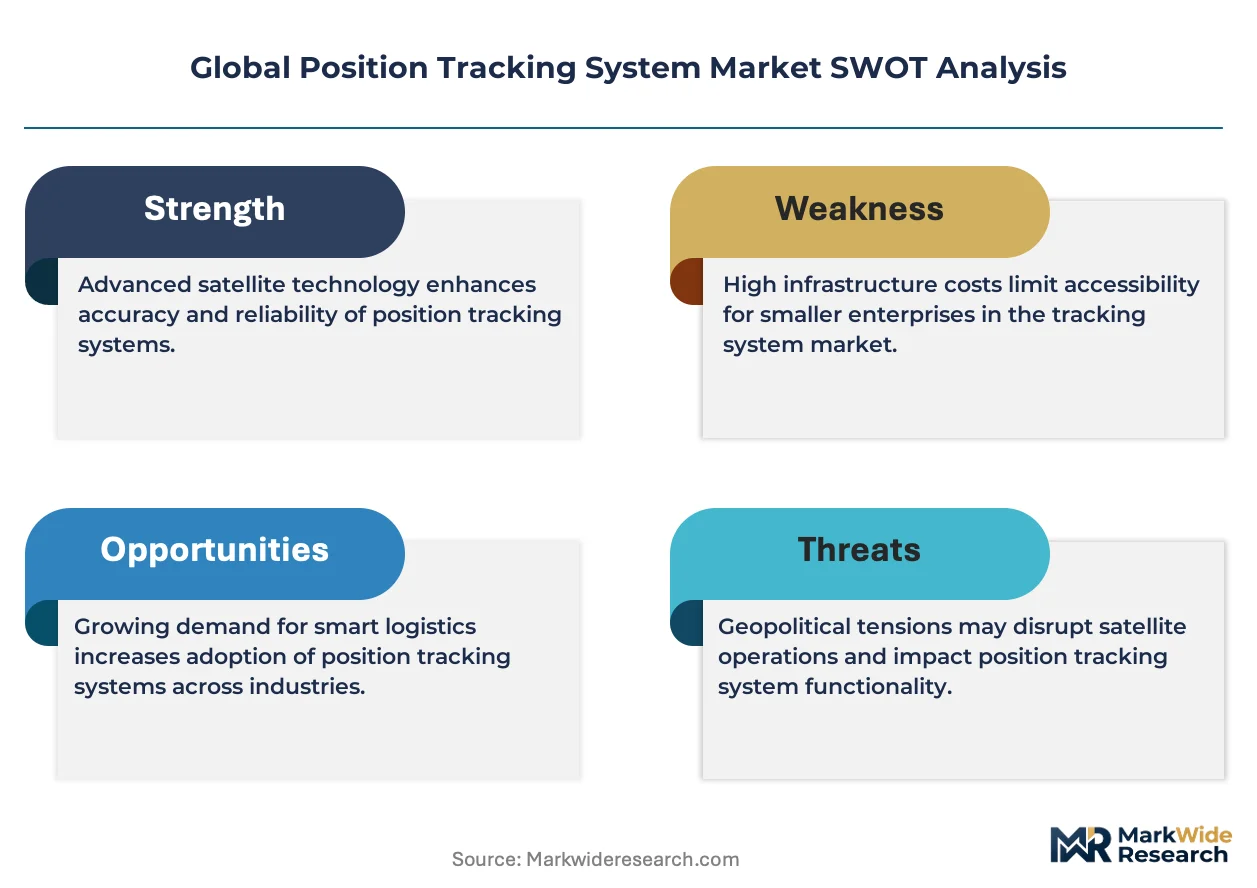
The gap between precision-grade multi-constellation systems and basic single-band trackers is expanding across industrial deployments. Garmin Ltd. leverages its vertical integration in wearable and aviation-grade receivers to sustain premium pricing power. Trimble Inc. anchors construction and geospatial workflows with centimeter-accurate RTK correction services. Qualcomm Technologies, Inc. competes in the automotive tier-one supply chain by embedding multi-frequency GNSS directly into connected vehicle chipsets.
A position tracking system comprises hardware and software modules that calculate geographic coordinates by receiving and processing signals from satellite constellations, with multi-constellation units typically achieving sub-meter accuracy through simultaneous GPS, GLONASS, Galileo, and BeiDou reception. These systems serve commercial purposes ranging from fleet dispatch optimization to wildlife migration mapping and athlete biomechanics analysis. Multi-constellation systems command the strongest margin pools as defense and autonomous vehicle programs mandate interference-resistant positioning. Satellite-based navigation technology leads in installed base, while UWB systems represent the fastest-expanding segment for indoor asset tracking in warehouses and manufacturing floors. Cellular triangulation remains mature and cost-driven, dominating personal tracking devices where meter-level precision suffices.
The U.S. Federal Communications Commission shapes device certification timelines for GNSS-enabled hardware, while the EU's Radio Equipment Directive mandates CE marking for all position tracking systems sold across member states. Japan's Ministry of Internal Affairs and Communications enforces spectrum allocation rules that directly impact dual-band receiver designs for the Asia-Pacific supply chain. Stakeholders must monitor evolving frequency band auctions and cross-border data localization mandates to align product roadmaps with diverging national compliance frameworks.
Market Dynamics
Multi-constellation receiver architectures are forcing a recalibration of competitive positioning across the position tracking value chain, as precision requirements from autonomous vehicle programs and defense procurement compress margins for single-band hardware suppliers.
Growth Catalysts
- EU AI Act compliance mandates:European fleet operators are retrofitting tracking infrastructure to meet algorithmic transparency requirements for location-based decision systems, expanding upgrade cycles for installed base hardware.
- Automotive OEM integration:Connected vehicle platforms in Germany and Japan are embedding multi-frequency GNSS chipsets as standard equipment for lane-level navigation and V2X coordination.
- RTK correction network densification:Commercial augmentation services are extending centimeter-accurate coverage to agricultural automation corridors across the US Midwest and Australian wheat belts.
Market Restraints
- Semiconductor foundry concentration:Advanced RF front-end fabrication for dual-band receivers depends on Taiwan-based capacity, exposing lead times to geopolitical supply disruptions.
- GDPR data localization friction:Cross-border fleet operations face architectural constraints on cloud-hosted position histories, forcing redundant regional infrastructure deployment.
- UWB spectrum allocation delays:Indoor asset tracking adoption in Japanese manufacturing facilities remains gated by Ministry of Internal Affairs and Communications licensing timelines for 6-8.5 GHz operation.
Strategic Opportunities
- India logistics corridor modernization:Dedicated freight highways and port automation projects under the PLI scheme are creating first-mover openings for precision tracking vendors in container yard management.
- Cellular-GNSS convergence:5G positioning reference signals integrated with satellite constellations are enabling seamless indoor-outdoor tracking for warehouse robotics and last-mile delivery optimization.
- Brazil agricultural automation:ANVISA regulatory clarity on drone-mounted spraying systems is accelerating demand for centimeter-accurate field mapping in soybean and sugarcane operations.
Industry Challenges
- RF interference mitigation engineering:Dense urban deployments in Seoul and Singapore require specialized multipath rejection algorithms that strain in-house DSP development teams.
- CE marking certification velocity:EU Radio Equipment Directive testing bottlenecks at notified bodies are extending product launch timelines for multi-constellation receivers by four to six months.
- Legacy fleet integration complexity:Retrofitting CAN bus interfaces to decade-old commercial vehicles for telematics upgrades demands custom harness engineering that erodes project margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Position Tracking System Market |
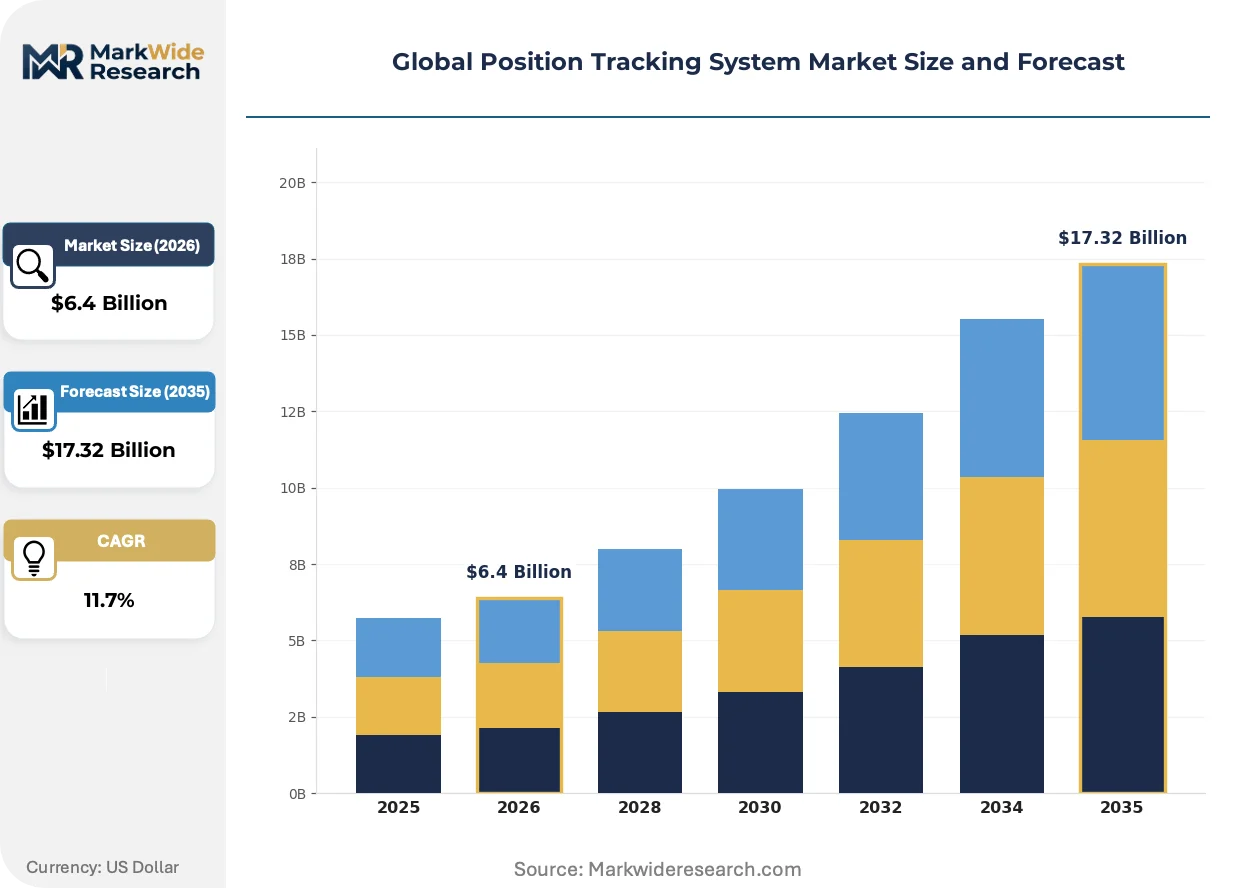
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $17.32 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: GPS Receivers, GLONASS Devices, Galileo Modules, BeiDou Units, Multi-Constellation Systems, Others Application: Fleet Management, Asset Monitoring, Personal Tracking, Wildlife Conservation, Sports Analytics, Inventory Control Technology: Cellular Triangulation, Satellite-Based Navigation, Bluetooth Low Energy, Wi-Fi Positioning, RFID Tracking, UWB Systems End User: Logistics Providers, Construction Firms, Emergency Response Teams, Sports Organizations, Research Institutions, Transportation Operators |
| Companies Covered | Garmin Ltd., Trimble Inc., Qualcomm Technologies, Inc., TomTom International BV, Broadcom Inc., Hexagon AB, Texas Instruments Incorporated, Sierra Wireless, Quectel Wireless Solutions Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Position Tracking System Market Shifts & Advancements
Signal fusion architectures and regulatory pressure on data sovereignty are compressing traditional hardware-software boundaries, while procurement patterns shift toward integrated platform subscriptions.
Dual-band RTK receivers with inertial measurement unit fusion are electrifying precision agriculture and construction workflows by maintaining sub-10 centimeter accuracy during temporary satellite occlusion. John Deere and Caterpillar are deploying these units across autonomous tractor and motor grader fleets in North American and European markets. The technology is compressing the addressable market for standalone correction services by embedding real-time kinematics directly into OEM equipment packages.
The EU AI Act's risk classification framework for biometric and behavioral tracking systems is mandating algorithmic audit trails for fleet management software processing driver location histories. Logistics operators must now maintain explainable decision records for route optimization engines, forcing architectural redesigns of cloud-based dispatch platforms. German and French fleet software vendors are responding by partitioning inference workloads between edge devices and regional data centers.
Subscription-based hardware-as-a-service models are displacing capital expenditure procurement in mid-size logistics fleets across Australia and the UK. Leasing providers bundle device provisioning, cellular connectivity, and software licenses into per-vehicle monthly fees that align costs with utilization. This shift is most visible in temperature-controlled transport segments where asset turnover and compliance documentation requirements favor operational flexibility over ownership.
Global Position Tracking System Market Segmentation
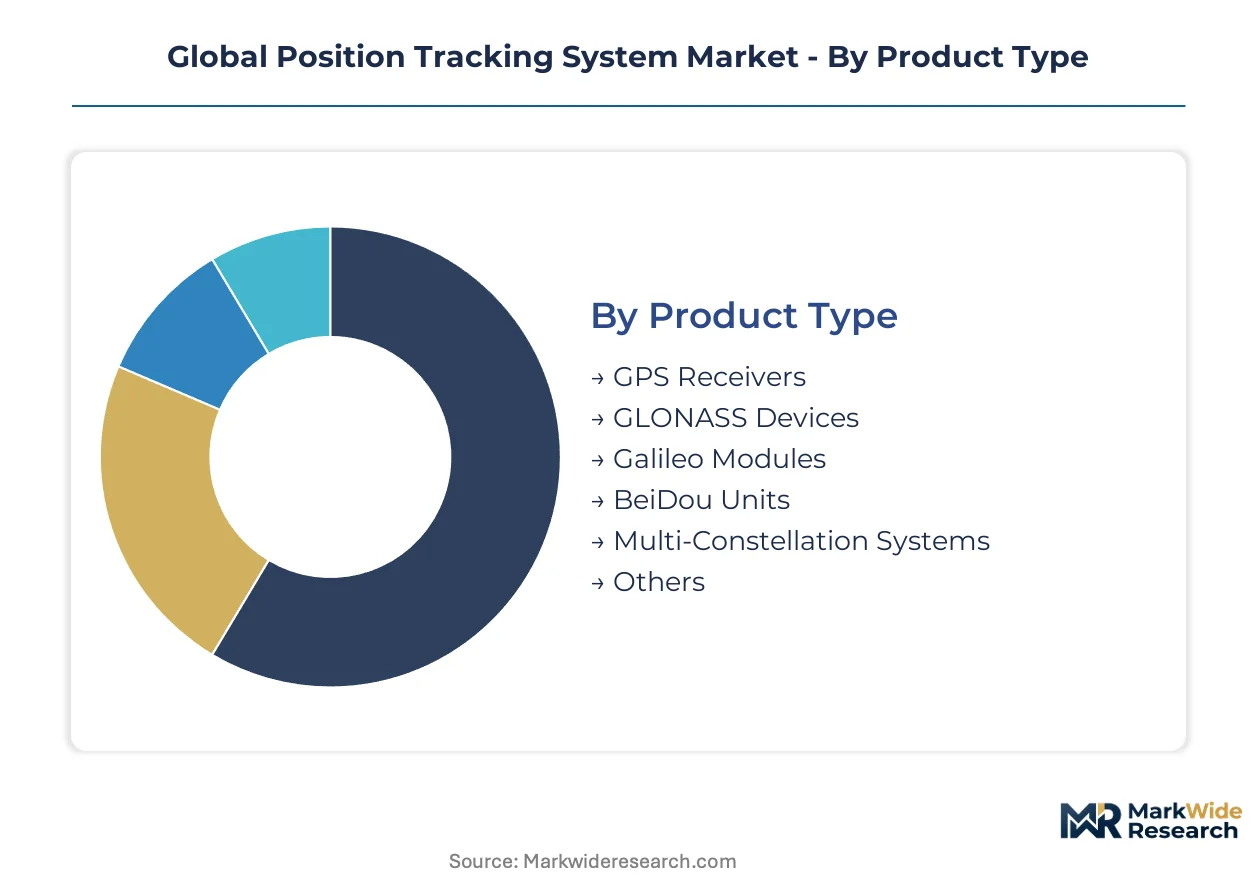
Position tracking system segmentation reveals how precision requirements, regulatory frameworks, and infrastructure maturity create divergent margin structures across hardware and service tiers. Certification burdens and constellation interoperability standards fragment competitive dynamics within each category.
Product Type:
CE marking under the EU Radio Equipment Directive applies universally, while FCC Part 15 certification governs US-bound hardware and Japan's Technical Standards Conformity Mark shapes Asia-Pacific export requirements.
- Multi-Constellation Systems:Simultaneous GPS, GLONASS, Galileo, and BeiDou reception enables sub-meter accuracy through signal diversity. German automotive OEMs and US defense contractors mandate these units for autonomous vehicle testing corridors and interference-resistant navigation.
- GPS Receivers:Single-constellation architecture dominates legacy fleet installations and consumer-grade applications. Cost-sensitive logistics operators in India and Brazil continue procuring these units for basic route verification where meter-level precision satisfies operational requirements.
- GLONASS Devices:Russian constellation-specific hardware retains niche demand in CIS-bordering logistics corridors.
- Galileo Modules:European GNSS infrastructure drives adoption for public-sector fleet compliance in EU member states.
- BeiDou Units:Chinese constellation hardware dominates domestic deployments and Belt and Road infrastructure projects.
- Others:Regional augmentation systems and proprietary correction services fill specialized surveying and maritime applications.
Leading the category by volume: GPS Receivers. Growing fastest: Multi-Constellation Systems.
Application:
Application segmentation tracks how precision thresholds and data sovereignty requirements reshape procurement patterns across commercial and institutional buyers.
- Fleet Management:Real-time vehicle location, route optimization, and fuel consumption analytics form the core value proposition. EU AI Act compliance mandates are forcing German and French operators to upgrade cloud-hosted dispatch platforms for algorithmic audit trails.
- Asset Monitoring:Container yard management and high-value equipment tracking drive demand for ruggedized hardware with extended battery life. Australian mining operators and Singapore port authorities are deploying these systems for theft prevention and utilization optimization.
- Personal Tracking:Elderly care and lone-worker safety applications favor compact, low-power devices with cellular fallback.
- Wildlife Conservation:Migration pattern research and anti-poaching programs in Kenya and Tanzania utilize solar-powered satellite collars.
- Sports Analytics:Athlete biomechanics and performance optimization in professional leagues demand high-frequency sampling rates.
- Inventory Control:Warehouse robotics and automated storage systems integrate UWB and RFID for centimeter-level indoor positioning.
Fleet Management generates the largest revenue pool. Inventory Control is climbing the fastest as warehouse automation accelerates.
Technology:
Technology choice reflects the trade-off between coverage ubiquity, precision grade, and infrastructure deployment cost.
- Satellite-Based Navigation:GNSS constellations provide outdoor coverage without terrestrial infrastructure investment. RTK correction network densification across the US Midwest and Australian wheat belts is extending centimeter-accurate service to agricultural automation.
- UWB Systems:Ultra-wideband enables 10-centimeter precision for indoor asset tracking in manufacturing floors and distribution centers. Japanese deployment remains gated by Ministry of Internal Affairs and Communications spectrum licensing timelines for 6-8.5 GHz operation.
- Cellular Triangulation:Mature, cost-driven technology dominates personal tracking devices where meter-level precision suffices.
- Bluetooth Low Energy:Beacon-based proximity detection serves retail analytics and indoor wayfinding applications.
- Wi-Fi Positioning:Fingerprinting techniques leverage existing infrastructure for indoor location in office complexes and hospitals.
- RFID Tracking:Passive and active radio-frequency identification dominates supply chain visibility at pallet and item level.
Satellite-Based Navigation holds the widest installed base. UWB Systems are gaining share fastest as warehouse robotics adoption intensifies.
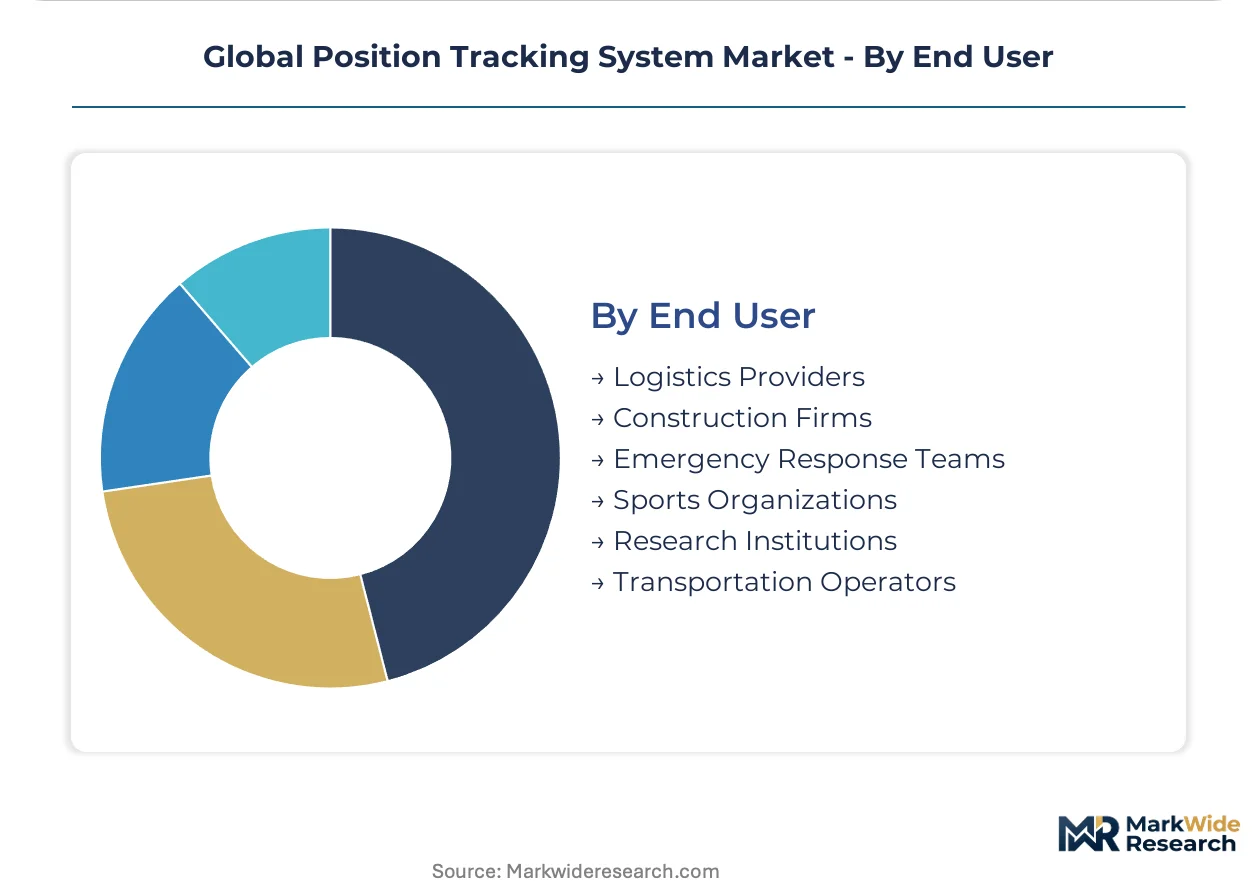
End User:
End user segmentation captures how operational tempo, regulatory exposure, and capital availability differentiate procurement behavior.
- Logistics Providers:Temperature-controlled transport and last-mile delivery operations demand real-time visibility with proof-of-compliance documentation. UK and Australian mid-size fleets are shifting toward subscription-based hardware-as-a-service models to align costs with utilization.
- Construction Firms:Motor grader and excavator automation requires centimeter-accurate machine guidance. Caterpillar and John Deere are embedding RTK-capable receivers directly into OEM equipment packages across North American and European markets.
- Emergency Response Teams:Disaster relief and search-and-rescue operations prioritize ruggedized, multi-constellation units with inertial backup.
- Sports Organizations:Professional leagues and training facilities invest in high-frequency athlete tracking for tactical analysis.
- Research Institutions:Geoscience and climate studies utilize precision-grade equipment for crustal deformation monitoring.
- Transportation Operators:Public transit and rail networks integrate tracking for schedule adherence and passenger information systems.
Logistics Providers represent the largest addressable demand. Construction Firms show the steepest expansion trajectory as equipment automation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors precision tracking demand through German automotive OEM integration of multi-frequency GNSS into autonomous vehicle testing corridors. Fleet operators across the city are retrofitting infrastructure to meet EU AI Act algorithmic transparency mandates. The concentration of Tier-1 suppliers in Baden-Württemberg accelerates chipset procurement cycles for connected vehicle platforms.
United States
Midwest agricultural automation corridors drive RTK correction network densification across Iowa and Illinois wheat belts. The FCC shapes device certification timelines for GNSS-enabled hardware through Part 15 regulations. Dallas-Fort Worth logistics hubs deploy subscription-based hardware-as-a-service models for temperature-controlled transport fleets.
China
Belt and Road infrastructure projects generate concentrated demand for BeiDou constellation hardware in port automation and container yard management. MIIT spectrum allocation rules govern dual-band receiver designs across the Asia-Pacific supply chain. Shenzhen manufacturing clusters produce RF front-end components for export markets.
Japan
Ministry of Internal Affairs and Communications licensing timelines for 6-8.5 GHz UWB operation gate indoor asset tracking adoption in Osaka manufacturing facilities. Connected vehicle platforms embed multi-frequency GNSS chipsets as standard equipment for V2X coordination. Nagoya automotive clusters integrate precision tracking into lane-level navigation systems.
Australia
Mining operators in Western Australia deploy ruggedized asset monitoring systems for theft prevention and utilization optimization. The country's national communications regulator enforces spectrum rules impacting receiver designs. Sydney and Melbourne mid-size logistics fleets shift toward operational expenditure models aligning tracking costs with vehicle utilization.
Global Position Tracking System Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the position tracking value chain, with semiconductor foundry concentration in Taiwan exposing lead times to supply disruptions. The vendor base stratifies between integrated OEM equipment providers, modular chipset suppliers, and correction service operators. Three archetypes dominate: aviation-grade precision specialists, construction workflow anchors, and automotive tier-one embedders. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure RF front-end fabrication allocation.
Within the precision-tier segment, Garmin Ltd. and Trimble Inc. occupy positions exemplifying vertical integration strategies across hardware and service layers. Qualcomm Technologies, Inc. anchors the automotive-embedded vector, representing the tier-one supply chain approach to multi-frequency GNSS integration.
| Leading Market Players |
|---|
| Garmin Ltd. |
| Trimble Inc. |
| Qualcomm Technologies, Inc. |
| TomTom International BV |
| Broadcom Inc. |
| Hexagon AB |
| Texas Instruments Incorporated |
| Sierra Wireless |
| Quectel Wireless Solutions Co., Ltd. |
| Others |
Supply & Pricing Matrix
RF front-end engineering talent concentration in Taiwan and South Korea widens pricing-tier spreads between precision-grade multi-constellation units and basic GPS receivers. Labor-cost differentials in RF fabrication clusters translate directly into margin compression for single-band hardware suppliers competing against vertically integrated rivals.
Pricing Analysis
Outcome-based subscription pricing anchored to fleet uptime metrics dominates logistics provider procurement. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked multi-constellation systems from FCC-certified single-band units and uncertified gray-market alternatives. Price differentiation hinges on RTK correction service bundling and algorithmic audit-trail compliance under EU AI Act mandates. Cost compression in economy-tier GPS receivers is intensifying because Indian and Brazilian logistics operators prioritize basic route verification over centimeter accuracy. Small fleet operators in Southeast Asia exhibit highest price sensitivity; defense contractors and German automotive OEMs show lowest.
Supply Chain Analysis
Dual-sourcing requirements from Tier-1 automotive suppliers mandate multi-supplier qualification for RF front-end components across Taiwan, South Korea, and Japan. Advanced receiver architectures draw from Taiwan-based foundry capacity, Japanese dual-band filter designs, and Chinese BeiDou baseband silicon. Single-source vulnerability in Taiwan semiconductor fabrication exposes lead times to geopolitical disruption. Distribution runs through authorized distributor networks serving OEM equipment channels, direct enterprise sales for fleet management platforms, and cellular carrier partnerships for consumer-grade personal trackers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Position Tracking System Market functions as a cost-of-compliance story where EU AI Act algorithmic transparency mandates erect barrier-to-entry moats for vendors with pre-certified audit-trail architectures.
For Market Incumbents: To counter margin erosion from subscription-based hardware-as-a-service models, deepen backward integration into RTK correction network infrastructure and secure captive supply of dual-band RF front-ends through long-term foundry allocation agreements. Prioritize CE marking velocity investments to compress EU Radio Equipment Directive testing bottlenecks at notified bodies. For New Entrants and Emerging Players: The mid-tier price-point gap between premium multi-constellation systems and economy GPS receivers offers white-space entry through cellular-GNSS convergence modules targeting warehouse robotics in Australian and UK logistics corridors. Brazil agricultural automation presents the most penetrable geography given ANVISA regulatory clarity on drone-mounted spraying systems. Pursue platform integration partnerships with existing fleet management software vendors rather than direct hardware competition. For Investors and Strategic Acquirers: Re-rating potential sits with RTK correction service operators given densification catalysts across US Midwest and Australian wheat belt agricultural corridors. Long-term viability favors asset-light correction network providers over capital-heavy receiver manufacturers facing foundry concentration risk. Monitor Ministry of Internal Affairs and Communications UWB spectrum licensing timelines as inflection indicator for indoor asset tracking segment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| RTK Correction Network Densification | Extends centimeter-accurate coverage to Iowa and Illinois agricultural automation corridors. |
| Multi-Constellation Chipset Integration | Qualcomm embeds GPS, GLONASS, Galileo, and BeiDou into automotive tier-one supply chains. |
| EU AI Act Compliance Certification | CE marking with algorithmic audit trails creates procurement preference in German fleet operators. |
| Hardware-as-a-Service Platform Launch | Subscription models align tracking costs with utilization for UK temperature-controlled transport fleets. |
| Cellular-GNSS Convergence Development | 5G positioning reference signals enable seamless indoor-outdoor warehouse robotics tracking. |
Research Methodology
SEC filings, ETSI technical standards documentation, and FCC equipment authorization databases formed the secondary backbone of this analysis. Primary interviews with fleet management software architects, automotive Tier-1 supplier procurement leads, RF front-end design engineers, and cellular carrier IoT platform directors combined with secondary validation. Bottom-up and top-down triangulation cross-referenced shipment data from receiver manufacturers against carrier activation records and correction service subscriber counts.
Bottom-up modeling aggregated unit economics across hardware tiers, software licensing, and service subscriptions. Segmentation dimensions included constellation architecture, precision grade, application vertical, and regional regulatory cluster. CAGRs were derived from installed base growth rates and average revenue per unit trajectories. Forecast inputs incorporated RTK network coverage expansion timelines and EU AI Act implementation schedules.
Inputs from automotive OEM procurement systems and fleet operator dispatch platforms were available through the study window; gaps in defense contractor program-level demand introduce uncertainty bands around autonomous vehicle testing corridor projections. Deviation in Taiwan semiconductor foundry capacity allocation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
North America Eye Tracking Solutions Market
Sensors
Lidar in Construction Market
Sensors
Wireless Synchronized Clocks Market
Sensors
Wireless Sensor Nodes for Monitoring Exterior Panel Fatigue Market
Sensors
Wireless Occupancy Sensors Market
Sensors
Global Radio Frequency Identification (RFID) Smart Cabinet Market
Sensors
Asia Pacific RFID Market
Sensors
Global Heat Stress Monitor (HSM) Market
Sensors
Global Smart Leak Detection Solutions Market
Sensors
Mobile Mapping Systems Market
Sensors
Global Load Monitoring System (LMS) Market
Sensors
Global RFID Market
Sensors
In-Counter Barcode Scanners Market
Sensors
Smart Mat Market
Sensors
Body Area Network Market
Sensors
Europe Remote Sensing Technology Market