
 Active Noise and Vibration Control (ANVC) Systems Market | 2026-2036
Active Noise and Vibration Control (ANVC) Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Active Noise and Vibration Control (ANVC) Systems Market Outlook
Digital signal processing integration with electromechanical actuators is narrowing the performance gap between active and passive noise attenuation architectures. LORD Corporation leverages its materials science heritage to anchor defense and aerospace contracts with hybrid active-passive solutions. Moog Inc. competes through precision motion control expertise applied to adaptive vibration cancellation in commercial aviation. Parker-Hannifin Corporation sustains industrial machinery penetration through channel density in hydraulics distribution networks.
Active Noise and Vibration Control (ANVC) Systems deploy real-time sensor arrays, digital controllers, and electromechanical actuators to generate anti-phase waveforms that cancel unwanted acoustic or mechanical oscillations, typically operating across 20 Hz to 20 kHz frequency bands with millisecond latency requirements. The primary commercial purpose spans occupant comfort enhancement in transportation platforms, precision manufacturing protection, and structural fatigue reduction in rotating equipment. Aerospace end-user demand leads absolute revenue contribution due to stringent cabin quietness specifications and regulatory certification thresholds, while adaptive control solutions represent the fastest-expanding technology segment as machine learning algorithms enable real-time parameter adjustment without manual calibration. Consumer electronics application volume remains concentrated in premium headphone tiers where feedforward control architectures dominate.
FAA airworthiness standards for cabin noise exposure and EPA occupational noise limits for industrial workplaces shape product certification requirements and end-market access conditions in the United States. EASA CS-25 cabin noise specifications and EU Machinery Directive vibration exposure thresholds create parallel compliance frameworks across European aviation and manufacturing sectors. Stakeholders must monitor evolving UNECE automotive noise regulations and the trajectory of smart materials standardization under ISO mechanical vibration protocols to anticipate specification shifts that will reshape competitive positioning.
Market Dynamics
Automotive electrification is eliminating internal combustion engine masking noise, exposing cabin acoustic deficiencies that ANVC systems must now address. This structural vacuum in powertrain sound signatures forces OEMs to integrate active cancellation architectures earlier in vehicle development cycles, reshaping supplier engagement models and specification timelines.
Growth Catalysts
- UNECE Regulation 51:Stricter EU vehicle noise directives mandate compliance-driven system integration across passenger car and commercial vehicle platforms, accelerating OEM procurement cycles.
- Machine learning algorithms:Adaptive control architectures enable real-time parameter adjustment without manual calibration, reducing deployment costs and expanding addressable applications in precision manufacturing.
- German manufacturing clusters:Premium automotive and aerospace supply chain density in Baden-Württemberg and Bavaria concentrate specification intensity and drive technology validation at scale.
Market Restraints
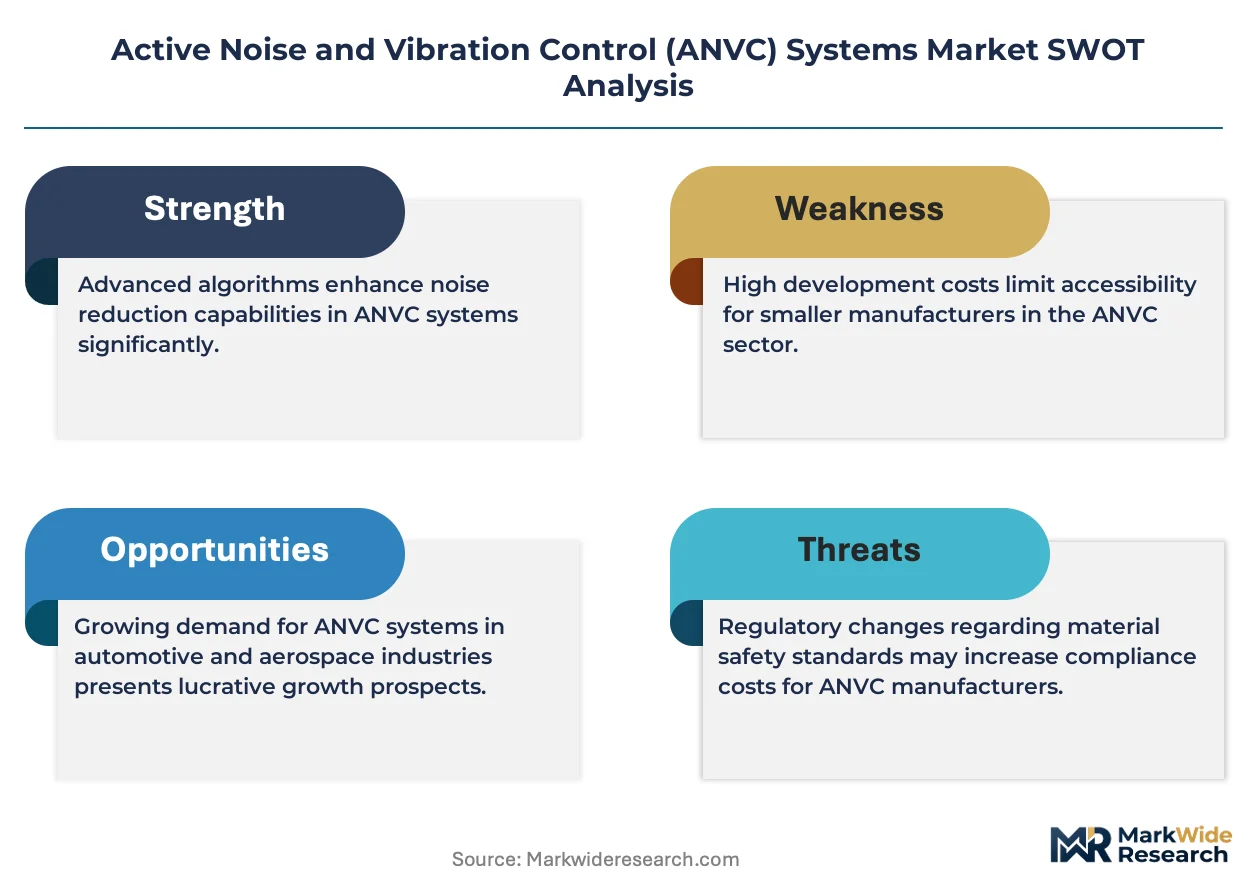
- Rare earth magnet supply concentration:Electromechanical actuator production depends on neodymium supply chains concentrated in Chinese processing facilities, creating input cost volatility and geopolitical exposure.
- High-fidelity sensor costs:Microelectromechanical microphone arrays and accelerometer networks required for broadband cancellation remain structurally expensive, compressing margins in price-sensitive industrial segments.
- Passive acoustic treatment substitution:Advanced porous materials and tuned mass dampers continue improving, limiting ANVC penetration in applications where absolute performance outweighs adaptive flexibility.
Strategic Opportunities
- Indian automotive manufacturing:Domestic EV production scaling under the PLI scheme creates first-mover positioning for ANVC suppliers establishing local engineering centers and tier-2 partnerships.
- ISO 2631-1 vibration standard convergence:Harmonized mechanical vibration exposure protocols across industrial sectors enable platform standardization, reducing certification overhead and accelerating cross-vertical deployment.
- Edge computing integration:Convergence of embedded DSP architectures with 5G-enabled predictive maintenance networks opens service-revenue models in rotating equipment monitoring and structural health management.
Industry Challenges
- Control systems engineering scarcity:Specialized expertise in adaptive filter algorithms and real-time embedded software remains concentrated among defense-aerospace talent pools, constraining vendor scaling.
- FAA/EASA certification timelines:Commercial aviation system validation requires extensive flight-test documentation and failure-mode analysis, extending program development cycles and locking working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Active Noise and Vibration Control (ANVC) Systems Market |
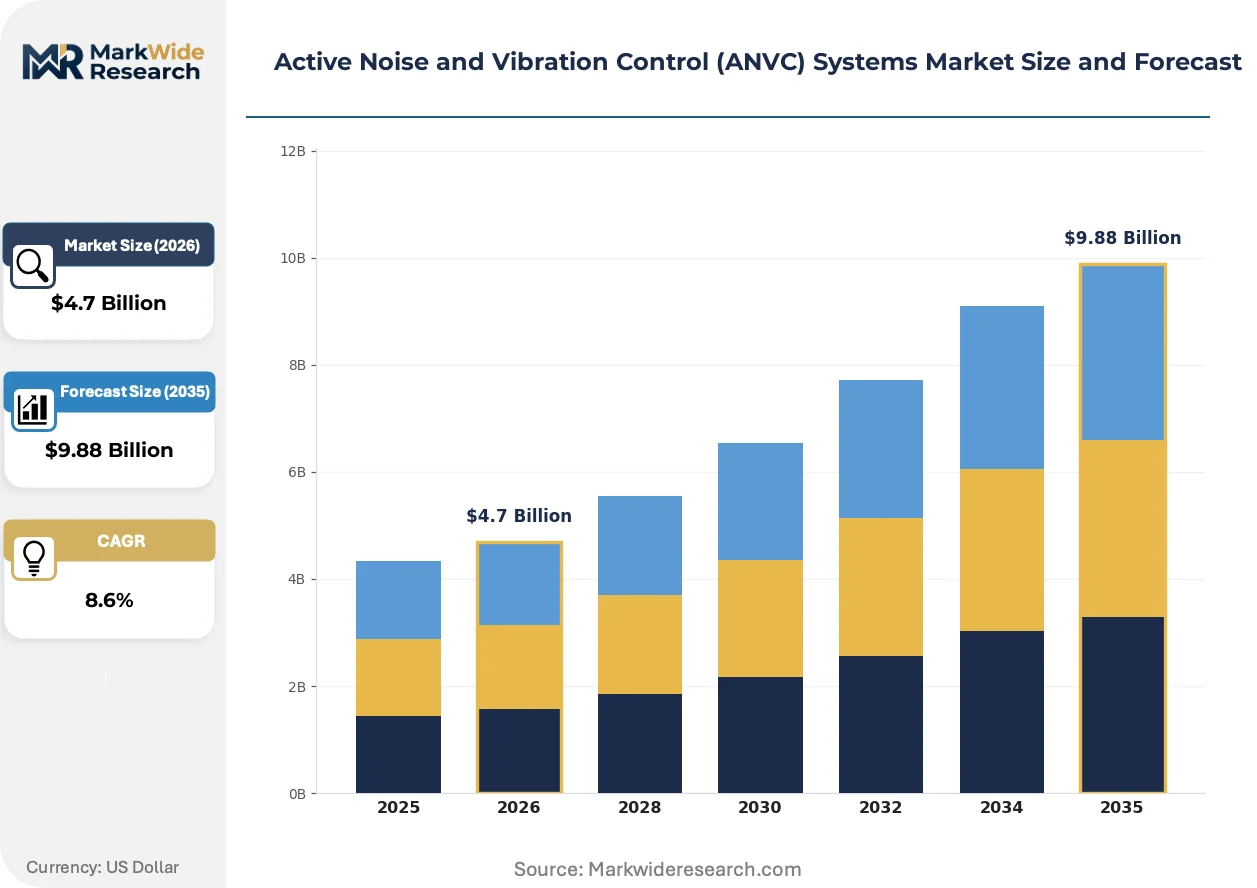
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $9.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Noise Control, Vibration Control Systems, Adaptive Control Solutions, Hybrid Systems End User: Aerospace, Automotive, Industrial Machinery, Marine Technology: Feedback Control, Feedforward Control, Smart Materials, Digital Signal Processing Application: Consumer Electronics, Commercial Vehicles, HVAC Systems, Aerospace Interiors |
| Companies Covered | LORD Corporation, Moog Inc., Ultra Electronics Holdings plc, Bosch General Aviation Technology GmbH, Hutchinson SA, Terma A/S, Creo Dynamics AB, Wolfe Aviation, Parker-Hannifin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Active Noise and Vibration Control (ANVC) Systems Market Strategic Shifts
Digital twin methodologies are compressing development cycles by enabling virtual acoustic environment simulation before physical prototyping. This shift is redistributing R&D expenditure toward software and sensor fusion while reducing hardware iteration costs.
Model-based reference architectures are virtualizing traditional hardware-dependent control loops. Automotive Tier-1 suppliers deploy these frameworks to validate cabin acoustic performance across multiple vehicle platforms simultaneously. The approach is virtualizing the need for platform-specific analog controller redesign, collapsing development timelines from months to weeks.
EPA occupational noise limits and OSHA hearing conservation standards are tightening enforcement across US manufacturing facilities. Industrial operators face penalty exposure and workers' compensation liability, redirecting capital toward active vibration cancellation in metalworking and material handling equipment. Midwest heavy machinery producers now specify integrated ANVC as standard configuration rather than optional upgrade.
Aftermarket service unbundling is fragmenting traditional bundled maintenance contracts. Aviation MRO providers now sell acoustic performance monitoring as standalone subscription services, decoupled from hardware warranty terms. This pattern concentrates in North American commercial fleet operators seeking operational expenditure predictability over capital-heavy system replacement cycles.
Active Noise and Vibration Control (ANVC) Systems Market Segmentation
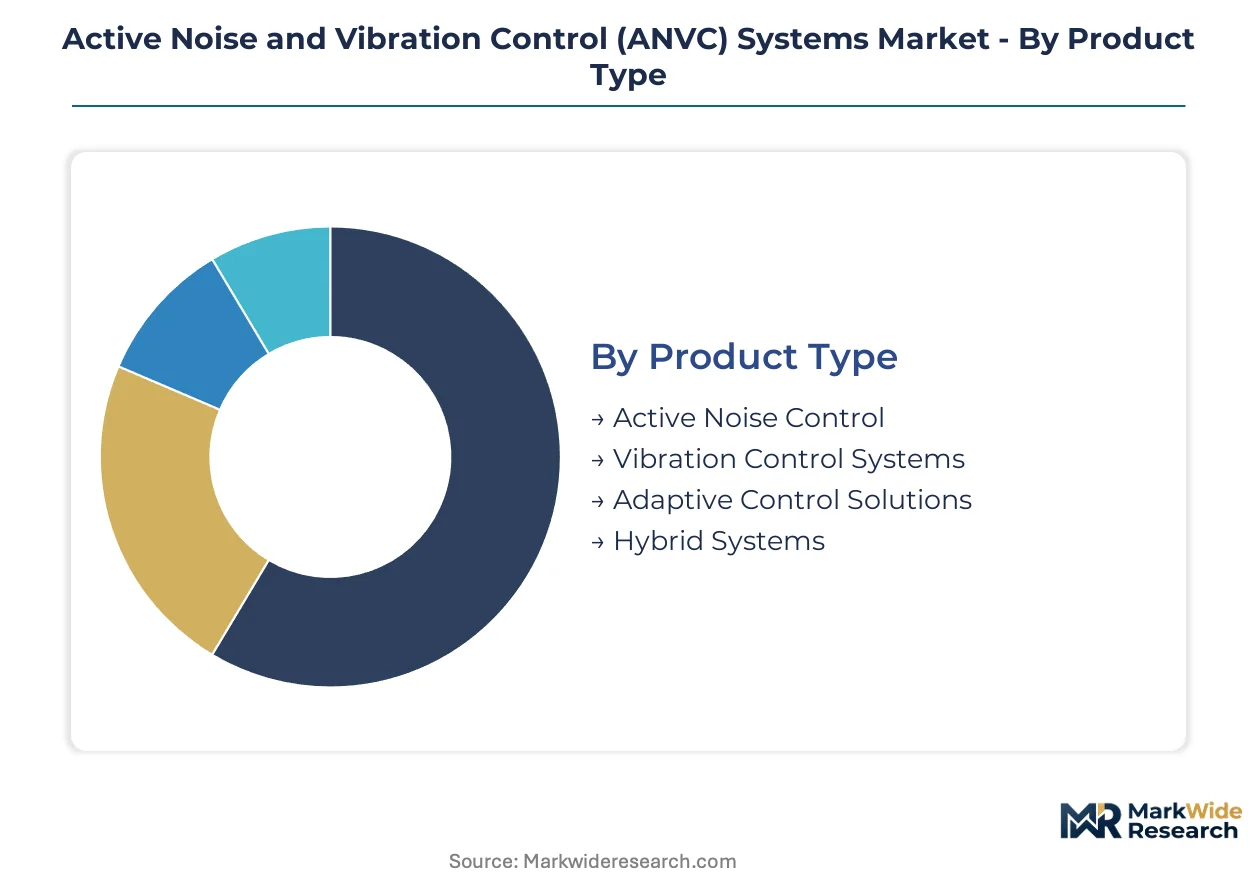
ANVC system configurations vary dramatically in service lifecycle requirements, with aerospace installations demanding continuous calibration support while consumer electronics prioritize minimal touchpoints. Understanding these segment-specific maintenance intensities shapes supplier resource allocation and margin architecture across the value chain.
Product Type:
After-sales service intensity diverges sharply across product architectures, with adaptive and hybrid systems requiring ongoing algorithm tuning while fixed-feedback installations operate with minimal intervention.
- Active Noise Control:Fixed-filter architectures generate anti-phase acoustic waveforms through predetermined DSP coefficients without real-time environmental adaptation. Demand concentrates in automotive cabin applications across German OEM platforms where UNECE Regulation 51 compliance deadlines compress procurement timelines.
- Vibration Control Systems:Electromechanical actuator networks mounted on rotating machinery counteract mechanical oscillations through tuned mass cancellation. Industrial operators in Baden-Württemberg manufacturing clusters specify these for precision machine tool protection under tightening EU Machinery Directive vibration exposure thresholds.
- Adaptive Control Solutions:Machine learning-enabled parameter adjustment eliminates manual recalibration requirements.
- Hybrid Systems:Combined active-passive architectures integrate porous materials with electromechanical cancellation.
By volume, Vibration Control Systems leads. By growth pace, Adaptive Control Solutions is ahead.
End User:
Customer procurement sophistication spans defense-aerospace specification rigor at one extreme and industrial machinery price sensitivity at the other, with margin structures tracking accordingly.
- Aerospace:FAA and EASA certification mandates drive extensive flight-test documentation and failure-mode analysis requirements. Commercial aviation cabin quietness specifications concentrate demand around long-haul fleet operators seeking passenger comfort differentiation on transatlantic routes.
- Automotive:Electrification eliminates ICE masking noise, exposing cabin acoustic deficiencies that force earlier ANVC integration in vehicle development cycles. German premium OEMs in Bavaria anchor specification intensity as EV platform launches accelerate.
- Industrial Machinery:EPA and OSHA enforcement tightening redirects capital toward active vibration cancellation in metalworking equipment.
- Marine:Vessel engine compartment and passenger cabin applications face salt-corrosion durability requirements.
By absolute revenue contribution, Aerospace leads. By expansion trajectory, Automotive is climbing the fastest.
Technology:
Development cost tiers separate legacy analog architectures from software-defined control loops, with R&D resource allocation shifting toward sensor fusion and embedded intelligence.
- Digital Signal Processing:Software-defined control loops virtualize hardware-dependent architectures, enabling multi-platform validation without analog controller redesign. Automotive Tier-1 suppliers deploy these frameworks to collapse development timelines from months to weeks across vehicle programs.
- Smart Materials:Piezoelectric and magnetostrictive compounds enable solid-state vibration cancellation without moving mechanical components. Aerospace structural health monitoring applications concentrate demand where mass reduction outweighs material cost premiums.
- Feedback Control:Error-signal-based adaptation loops respond to residual noise after cancellation.
- Feedforward Control:Reference-signal architectures anticipate disturbance before it reaches the target zone.
By installed base, Feedback Control leads. By technology transition velocity, Digital Signal Processing is gaining share fastest.
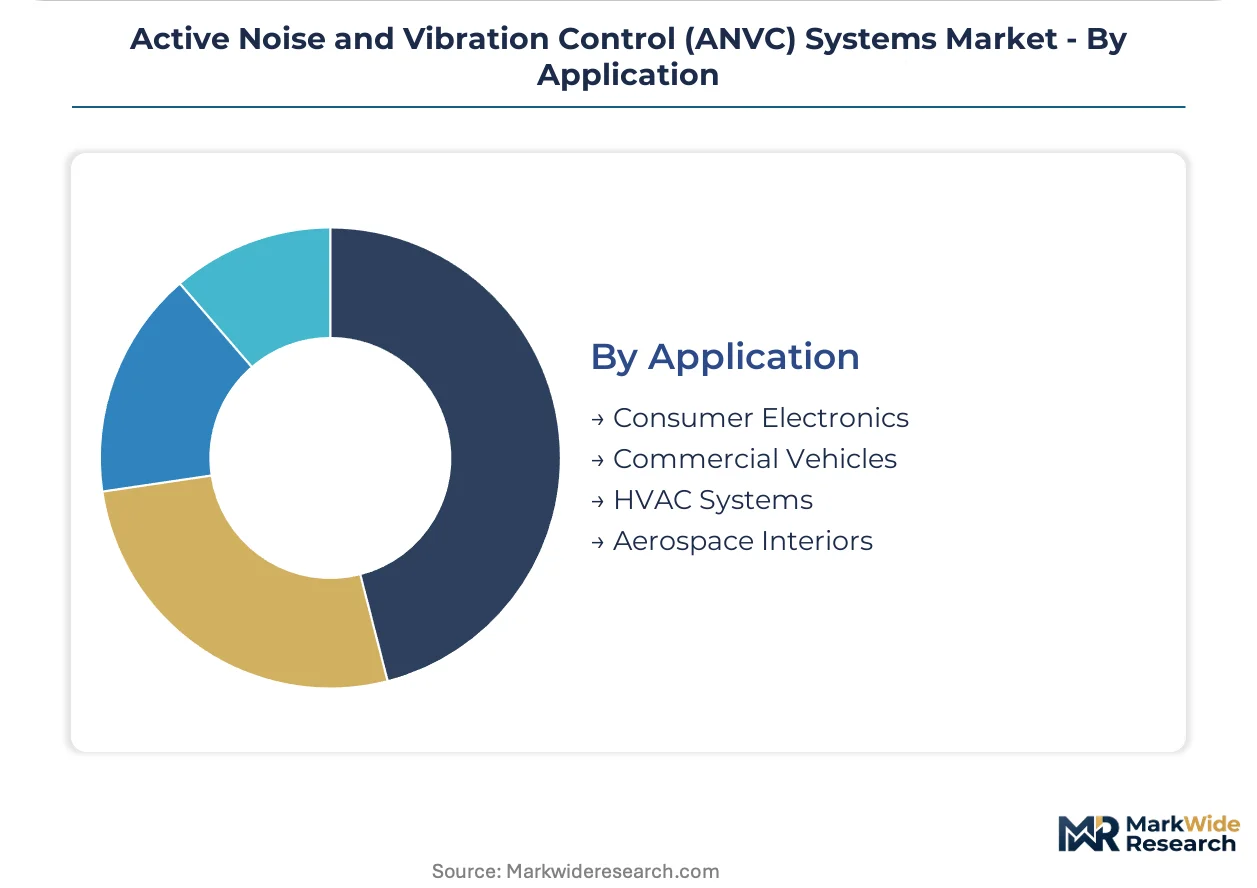
Application:
Volume scale and performance requirements create distinct commercial profiles, with consumer electronics prioritizing unit economics and aerospace interiors demanding certification rigor.
- Aerospace Interiors:Cabin quietness specifications under EASA CS-25 and FAA Part 25 drive extensive acoustic validation testing. Long-haul commercial fleet operators specify integrated ANVC as standard configuration rather than optional upgrade to secure passenger comfort ratings.
- Commercial Vehicles: Heavy-duty truck cabin and powertrain mounting applications face UNECE noise directive compliance deadlines.
- Consumer Electronics:Premium headphone tiers concentrate volume where feedforward architectures dominate.
- HVAC Systems:Building mechanical noise cancellation targets compressor and ductwork acoustic emissions.
By unit volume, Consumer Electronics leads. By specification intensity, Aerospace Interiors is ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German ANVC system exports flow predominantly to aerospace manufacturers in France and the United Kingdom, while U.S. defense contractors source precision vibration control components from Japanese suppliers serving the Tokyo-Osaka industrial corridor.
United States
FAA Part 25 cabin noise specifications and OSHA hearing conservation standards drive specification intensity across commercial aviation and industrial machinery segments. The EPA enforces occupational noise limits that redirect capital toward active vibration cancellation in metalworking equipment. Midwest heavy machinery producers in Michigan and Ohio now specify integrated ANVC as standard configuration.
Germany
Premium automotive OEMs and aerospace supply chains in Bavaria and Baden-Württemberg anchor European demand concentration. UNECE Regulation 51 compliance deadlines compress procurement timelines for passenger car and commercial vehicle platforms. Stuttgart and Munich manufacturing clusters validate adaptive control technologies at scale for deployment across EU markets.
China
Domestic EV production scaling under MIIT industrial policy creates procurement volume for cabin acoustic systems. GB standards for vehicle noise emissions tighten compliance thresholds for local manufacturers. Yangtze River Delta automotive clusters in Shanghai and Jiangsu province concentrate specification activity for export-oriented platforms.
Japan
METI carbon neutrality roadmaps accelerate electrification across commercial vehicle fleets, exposing cabin acoustic deficiencies. JIS vibration measurement protocols standardize performance validation for industrial machinery applications. Nagoya aerospace suppliers and Tokyo precision equipment manufacturers integrate hybrid active-passive architectures for regional defense contracts.
India
Domestic automotive production scaling under the PLI scheme creates first-mover positioning for ANVC suppliers establishing local engineering partnerships. BIS automotive noise standards converge with UNECE frameworks for export market access. Tamil Nadu and Maharashtra manufacturing corridors concentrate tier-2 supplier development for EV platform integration.
Active Noise and Vibration Control (ANVC) Systems Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered market strata. The vendor base organizes around three archetypes: diversified industrial conglomerates with hydraulics distribution networks, precision motion control specialists with aerospace heritage, and adaptive algorithm developers with machine learning capabilities. Consolidation pressure intensifies as automotive electrification compresses specification timelines and defense-aerospace certification requirements extend program development cycles.
Within the diversified industrial tier, Parker-Hannifin Corporation exemplifies channel density strategies anchored in hydraulics distribution networks. LORD Corporation and Moog Inc. occupy positions among precision motion control specialists leveraging materials science and adaptive filter expertise respectively. These three entities represent contrasting competitive vectors: one scaling through industrial aftermarket reach, the others through defense-aerospace specification intensity and real-time embedded software capabilities.
| Leading Market Players |
|---|
| LORD Corporation |
| Moog Inc. |
| Ultra Electronics Holdings plc |
| Bosch General Aviation Technology GmbH |
| Hutchinson SA |
| Terma A/S |
| Creo Dynamics AB |
| Wolfe Aviation |
| Parker-Hannifin Corporation |
| Others |
Value Chain & Pricing Dynamics
Neodymium processing concentration in Chinese facilities anchors cost volatility for electromechanical actuators, compressing margins at the system-integrator tier while concentrating pricing power with rare-earth traders and magnet manufacturers. This upstream chokepoint forces ANVC vendors to absorb input fluctuations or pass them through to aerospace and automotive OEMs with long-term contract leverage.
Pricing Analysis
Fixed-feedback architectures trade at commodity-equivalent levels while adaptive DSP-enabled systems command certification-linked premiums. Three-tier pricing structure across premium, standard, and economy levels separates FAA-validated aerospace installations from industrial machinery retrofits and consumer headphone components. Cost compression in the industrial tier stems from accelerometer network expenses and price-sensitive plant-engineer procurement committees. Aerospace buyers exhibit lowest price sensitivity due to passenger-comfort differentiation mandates and regulatory non-compliance penalties.
Supply Chain Analysis
Neodymium magnet feedstock draws from Chinese separation and refining facilities, with Japanese sintering operations and German magnet-assembly plants completing the value chain. MEMS microphone arrays source from Taiwanese foundries, while DSP chip fabrication concentrates in South Korean and U.S. facilities. Single-source vulnerability in Chinese rare-earth processing creates tariff-exposure and geopolitical disruption risk. Distribution runs through hydraulics-focused industrial distributors for machinery applications and direct OEM engineering engagement for aerospace and automotive platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ANVC system demand tracks automotive production cycles and commercial aviation fleet renewal waves, with electrification-driven cabin-acoustic investment now lifting the cycle from trough conditions.
For Market Incumbents: Harden algorithm IP protection against machine-learning-enabled entrants from adjacent sensor-fusion markets. Deepen captive magnet sourcing through offtake agreements with Australian and Canadian rare-earth developers to offset Chinese supply concentration. Lock in multi-platform automotive contracts before Tier-1 suppliers internalize adaptive control competencies.
For New Entrants and Emerging Players: Pursue Indian EV platform integration through Tamil Nadu engineering partnerships and PLI-scheme qualification. Industrial machinery aftermarket service contracts present the most penetrable white-space, with Midwest metalworking operators seeking subscription-based vibration monitoring decoupled from hardware sales. Lead with edge-computing-enabled predictive maintenance to bypass incumbent certification timelines.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision motion control specialists carrying defense-aerospace contract backlogs but limited adaptive algorithm capabilities. Long-term viability hinges on software-defined control transition velocity over hardware-dependent legacy architectures. Watch FAA Part 25 certification queue lengths as inflection indicator for vendor working-capital stress and forced divestiture opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Adaptive Algorithm Acquisition | Machine-learning expertise from adjacent sensing markets accelerates DSP-enabled product transitions. |
| Rare-Earth Supply Diversification | Australian and Canadian magnet feedstock agreements reduce Chinese processing dependency. |
| Indian Engineering Center Establishment | Tamil Nadu and Maharashtra partnerships capture PLI-scheme EV platform procurement. |
| Digital Twin Capability Buildout | Virtual acoustic simulation compresses development cycles and reduces hardware iteration costs. |
| Aftermarket Service Unbundling | Standalone acoustic performance subscriptions attract North American fleet operators seeking OpEx predictability. |
Study Parameters
A spread of perspectives from aerospace procurement directors, automotive platform engineers, industrial maintenance managers, and MEMS sensor suppliers converged on the working assumptions. Primary fieldwork combined structured interviews with Tier-1 supplier executives and aftermarket service heads with secondary validation against FAA certification databases, EASA CS-25 documentation, SEC 10-K filings from precision motion control vendors, and UNECE Regulation 51 compliance timelines. Bottom-up segment sizing triangulated against top-down automotive production and commercial aviation delivery forecasts.
Demand-supply balance modeling tracked electromechanical actuator capacity against aerospace fleet renewal and EV platform launch schedules across the projection horizon. Segmentation dimensions spanned product architecture, end-user industry, control technology generation, and regional regulatory cluster. CAGRs derived from regression analysis of historical certification-to-deployment lags and technology substitution elasticities, with inputs from rare-earth price indices and DSP semiconductor capacity announcements.
Sensitivities concentrate around FAA/EASA certification timeline extensions, Chinese rare-earth export policy shifts, and automotive OEM vertical integration into adaptive control software. Cross-checking against IHS Markit vehicle production data and Cirium commercial aviation fleet forecasts is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Robot Sensor Market
Sensors
Safety Motion Control System Market
Sensors
Automated Weather Observation System Market
Sensors
Handheld GPS Units Market
Sensors
Heat Stress Meter Market
Sensors
Global Tunnel Monitoring System Market
Sensors
Location-Based Ambient Intelligence Market
Sensors
Global Heat Stress Monitor (HSM) Market
Sensors
IO Link Market
Sensors
Smart Pest Monitoring Management System Market
Sensors
Terrestrial Laser Scanning System Market
Sensors
Sensor Landscape in Robotics and ADAS Vehicle Market
Sensors
Temperature Data Loggers Market
Sensors
In-Counter Barcode Scanners Market
Sensors
Beacon Technology Market
Sensors
Cloud Camera Market