
 High-Precision Truss Robot Market | 2026-2036
High-Precision Truss Robot Market Size, Share, and Industry Trends Forecast 2026-2036
High-Precision Truss Robot Market Insights
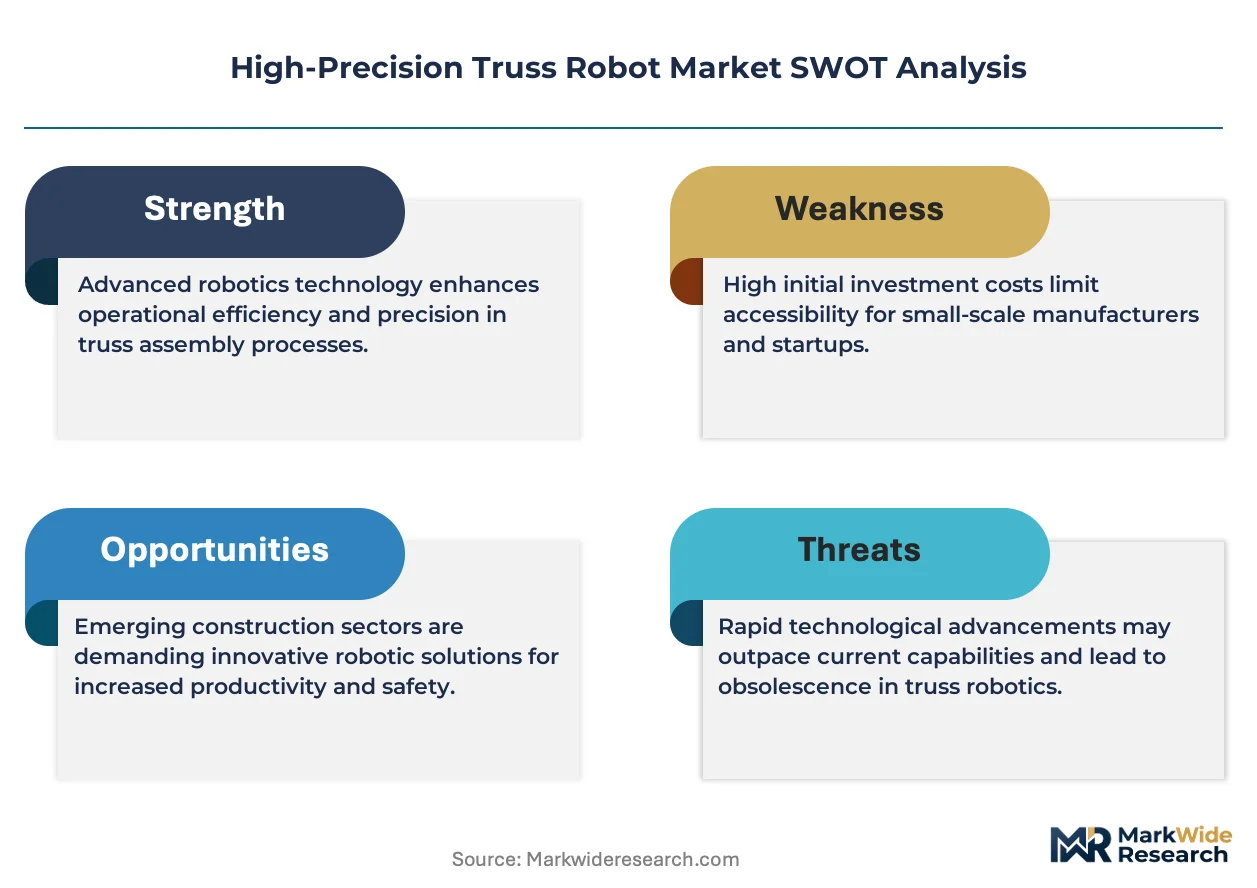
EU machinery safety directives and CE marking is expanding compliance burdens for truss robot OEMs entering European assembly lines. KUKA leverages its Stuttgart manufacturing base to sustain integrated control system production. FANUC anchors high-repeatability servo architectures across Japanese and North American electronics fabs. Güdel Group specializes in heavy-payload gantry configurations for automotive powertrain handling.
High-precision truss robots are multi-axis Cartesian or gantry systems built from extruded aluminum or steel lattice frameworks, achieving positional accuracy below ±0.05 millimeter through linear motor or ball-screw drive trains; they execute coordinated pick-place, transfer, and machining operations across extended factory footprints. Gantry robots dominate margin pools in heavy-material handling for aerospace engineering, where span lengths exceed fifteen meters and rigidity requirements command premium pricing. Vision systems penetration is accelerating fastest among technology segments, displacing legacy proximity arrays in quality inspection cells across pharmaceutical production lines. Delta robots retain mature share in food processing pick-and-place, though cycle-time limits constrain expansion into precision electronics assembly.
FDA validation requirements for pharmaceutical production equipment shape truss robot material selection and cleanroom washdown protocols in US installations. EMA and MDR frameworks in Europe enforce traceable calibration cycles for robotic systems deployed in medical device handling. China's SAMR and GB standards mandate energy efficiency disclosures for servo-driven automation sold domestically. Stakeholders must weigh regional certification roadmaps against platform standardization targets when allocating R&D across product architectures.
Market Dynamics
Electronics fabs in Taiwan, South Korea, and Germany are consolidating wafer-handling automation around single-source gantry platforms, compressing vendor qualification cycles and reshaping competitive positioning across precision Cartesian systems.
Growth Catalysts
- MIIT Dual Carbon Mandates:China's efficiency standards for servo motors are accelerating replacement of legacy pneumatic actuators with electric linear drives in domestic assembly plants.
- Semiconductor Fabs:Wafer transport automation below ±0.05 millimeter tolerance is pulling gantry architectures into 300mm and 450mm fab designs across East Asian manufacturing clusters.
- EU Machinery Safety Directives:CE marking requirements for collaborative robot integration are expanding addressable market for certified truss systems in European automotive powertrain lines.
Market Restraints
- Rare Earth Magnet Volatility:Neodymium price swings in Chinese export markets are compressing margins on permanent-magnet linear motor configurations.
- Ball Screw Supply Concentration:Precision ground screw production concentrates in Japan and Germany, creating lead-time vulnerability for mid-tier OEMs outside these geographies.
- Delta Robot Substitution:Parallel kinematic systems retain cost advantage in food packaging pick-place cycles above 200 parts per minute, limiting truss robot penetration in high-speed material handling.
Strategic Opportunities
- India PLI Scheme:Production-linked incentives for electronics manufacturing are creating greenfield demand for precision automation in Noida and Sriperumbudur industrial corridors.
- Vision-Gantry Convergence:Integration of 3D time-of-flight sensors with Cartesian positioning is opening inspection-cell applications in pharmaceutical blister packaging.
- F-Gas Regulation Tailwind:EU restrictions on fluorinated greenhouse gases are accelerating electric actuator adoption over pneumatic systems in temperature-controlled logistics automation.
Industry Challenges
- Mechatronics Talent Scarcity:Shortage of engineers proficient in both servo tuning and structural finite element analysis is extending commissioning timelines for multi-axis gantry deployments.
- FDA Validation Burden:Pharmaceutical equipment qualification protocols are stretching deployment cycles for cleanroom-rated truss systems in US generic drug manufacturing.
- Legacy PLC Integration Friction:Proprietary fieldbus architectures in brownfield automotive plants are forcing costly gateway development for new Ethernet-based servo networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Precision Truss Robot Market |
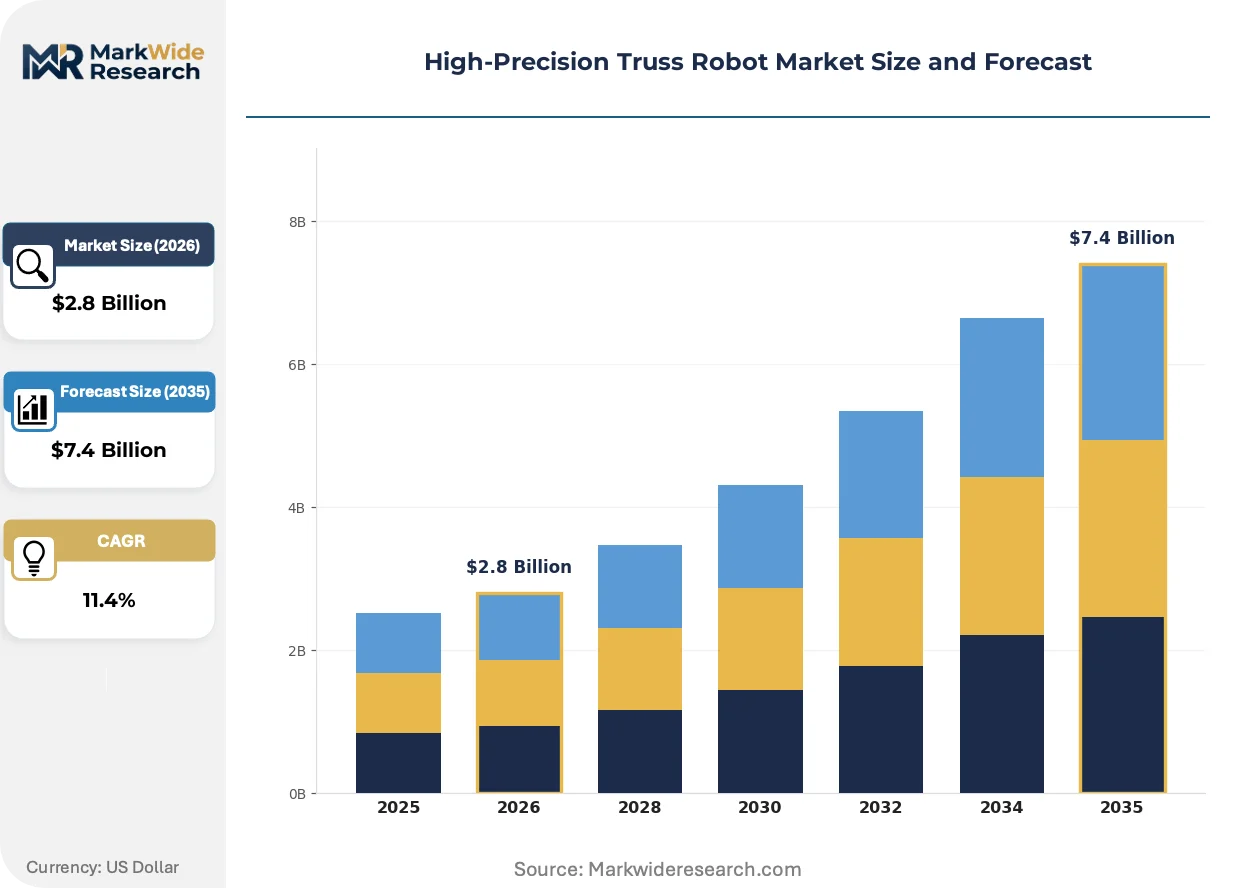
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Delta Robots, Gantry Robots, Articulated Arms, SCARA Robots, Cartesian Robots Technology: Lidar, Infrared Sensors, Optical Encoders, Force Sensors, Vision Systems Application: Assembly, Material Handling, Quality Inspection, Packaging, Welding End User Industry: Electronics Manufacturing, Aerospace Engineering, Logistics Providers, Pharmaceutical Production, Food Processing |
| Companies Covered | KUKA, FANUC, Güdel Group, SIASUN Robot & Automation, Liebherr-International, Felsomat, FLT Automation, Qingdao Kingerobot, Anhui Hengtong Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Precision Truss Robot Market Trends and Innovations
Linear motor drive trains are overtaking ball-screw architectures in precision-critical applications, while regulatory pressure on energy efficiency and cleanroom protocols is reshaping material selection and control system design across major manufacturing geographies.
Ironless linear motors with zero cogging torque are overtaking ball-screw drives in semiconductor wafer-handling applications requiring sub-10-micron following error. Taiwanese and South Korean memory fabs are standardizing on direct-drive gantries for 300mm wafer transport. This shift is compressing maintenance intervals and enabling continuous-duty operation in 24/7 cleanroom environments.
REACH restrictions on hexavalent chromium surface treatments are forcing European truss robot manufacturers to migrate from traditional steel corrosion protection to aluminum extrusion or specialized coating systems. The regulation's industrial consequence extends to aerospace gantry applications where span rigidity requirements previously favored chromated steel lattice structures. German automotive suppliers are responding by qualifying aluminum-heavy configurations for powertrain assembly lines.
Consolidated procurement of automation platforms by multinational electronics contract manufacturers is displacing regional system integrator relationships in favor of direct OEM partnerships with volume pricing and global service coverage. Foxconn and Luxshare are centralizing truss robot sourcing through frame agreements spanning multiple production sites. This concentration is most visible in China's Pearl River Delta, where single-source gantry standardization is reducing spare parts inventory complexity across dispersed fab networks.
High-Precision Truss Robot Market Segmentation
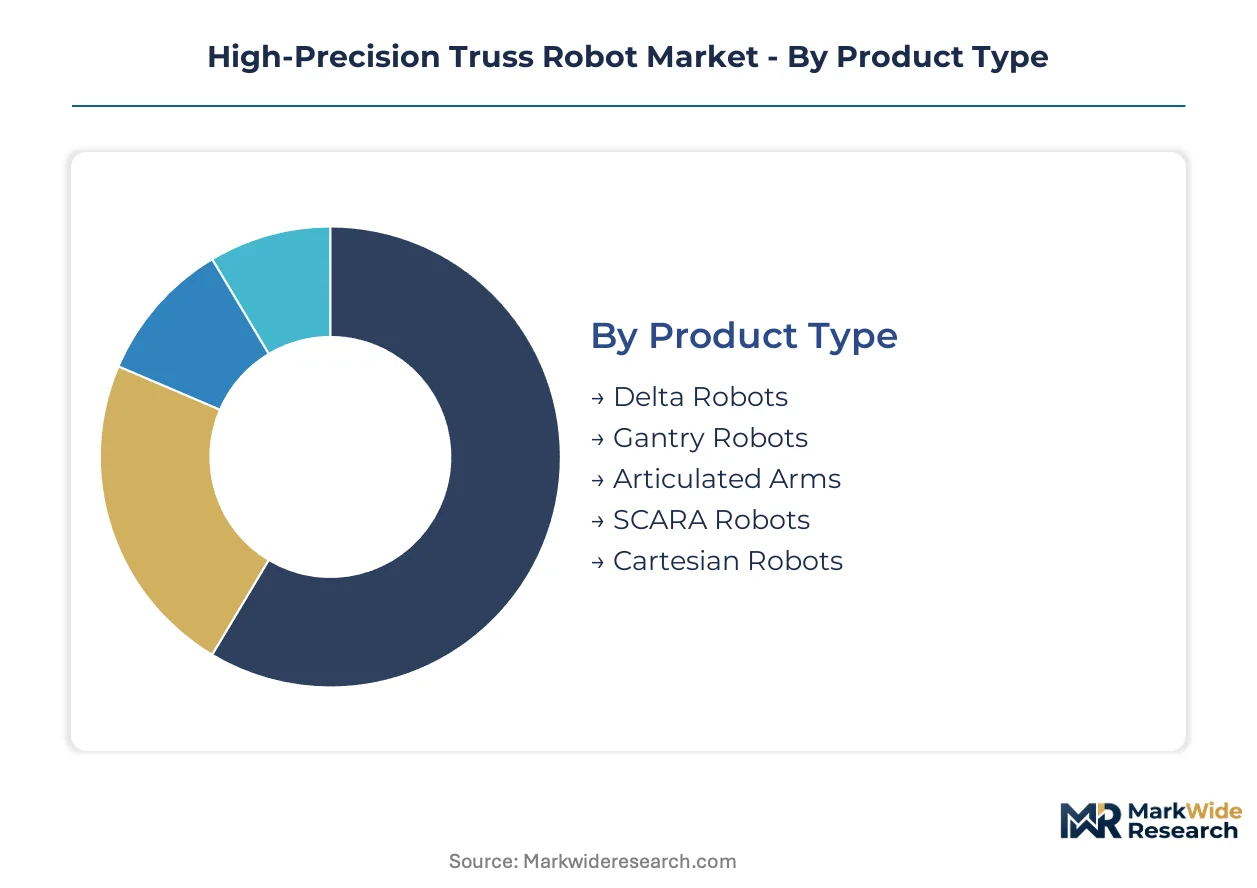
Segmentation in high-precision truss robots reveals how technical specifications, sensing architectures, and end-use constraints fragment procurement patterns across manufacturing verticals. Each dimension carries distinct margin profiles and qualification barriers that shape vendor strategy.
Product Type:
Supply concentration in linear motor manufacturing favors architectures that leverage direct-drive efficiency over mechanical transmission systems.
- Gantry Robots:Steel or aluminum lattice frameworks spanning extended factory footprints achieve positional accuracy below ±0.05 millimeter through linear motor or ball-screw drives. Demand concentrates in Germany's automotive belt around Stuttgart and Munich, where powertrain handling requires heavy-payload configurations with rigidity premiums.
- Cartesian Robots:Three-axis linear motion systems built from extruded aluminum profiles execute pick-place and transfer operations across semiconductor fabs. Taiwanese and South Korean memory manufacturers standardize on these architectures for 300mm wafer transport, compressing vendor qualification cycles.
- Delta Robots:Parallel kinematic systems with three arms connected to a common base retain cost advantage in food packaging pick-place cycles above 200 parts per minute.
- SCARA Robots:Selective compliance assembly robot arms combine rotational and vertical linear motion for electronics assembly tasks requiring speed over extended reach.
- Articulated Arms:Six-axis configurations with rotary joints access confined spaces in aerospace component finishing where gantry spans prove impractical.
Today's leader: Gantry Robots. Tomorrow's challenger: Cartesian Robots.
Technology:
Cost tier stratification separates premium sensing stacks from commodity proximity arrays in quality inspection cells.
- Vision Systems:3D time-of-flight sensors integrated with Cartesian positioning enable inspection-cell applications in pharmaceutical blister packaging. Penetration accelerates fastest among technology segments, displacing legacy proximity arrays across production lines.
- Optical Encoders:High-resolution position feedback devices with sub-micron accuracy mount directly to linear motor stages for semiconductor wafer-handling applications requiring sub-10-micron following error.
- Lidar:Time-of-flight laser ranging systems provide environmental mapping for collaborative gantry deployments in shared human-robot workspaces.
- Force Sensors:Strain-gauge or piezoelectric load cells enable compliant motion control in delicate assembly tasks across electronics manufacturing.
- Infrared Sensors:Non-contact temperature monitoring supports thermal management in welding applications and cleanroom environments.
Vision Systems command premium pricing tiers. Optical Encoders scale fastest in fab automation.
Application:
Volume concentration in electronics contract manufacturing pulls automation procurement toward standardized platform architectures.
- Assembly:Coordinated multi-axis positioning for component placement and fastening operations dominates electronics fab automation, with precision requirements below ±0.05 millimeter driving gantry specification.
- Material Handling:Wafer transport automation in 300mm and 450mm fab designs across East Asian manufacturing clusters anchors demand for cleanroom-rated linear motor configurations.
- Quality Inspection:Vision-guided dimensional verification and defect detection expands addressable market in pharmaceutical production lines subject to FDA validation protocols.
- Packaging:High-speed pick-place cycles in food processing retain delta robot preference due to cycle-time constraints on truss architectures.
- Welding:Articulated arm dominance persists in automotive body-in-white applications where joint access complexity exceeds gantry reach.
Assembly commands current procurement volumes. Quality Inspection offers steepest expansion trajectory.
End User Industry:
Margin maturity varies sharply across regulated versus unregulated manufacturing environments.
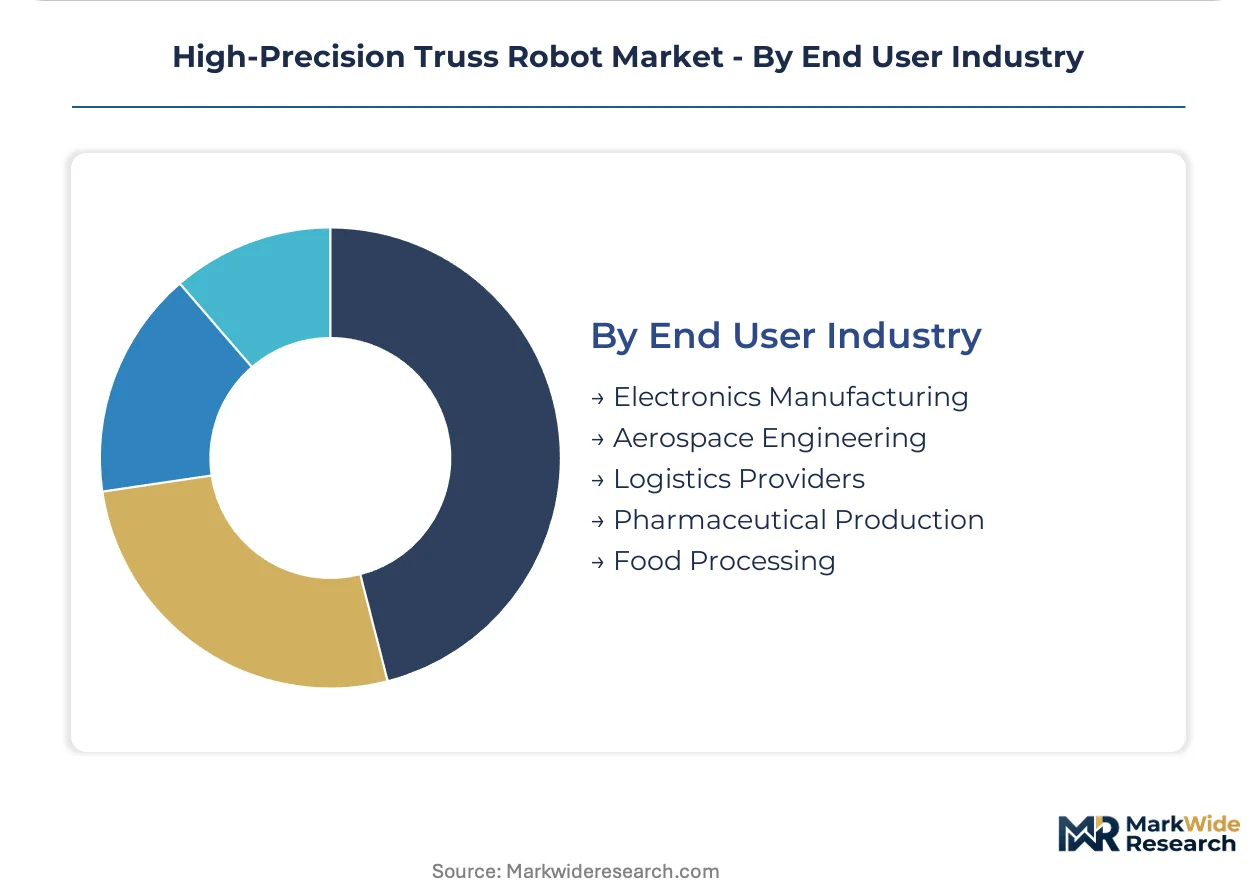
- Electronics Manufacturing:Wafer-handling automation and precision assembly in Taiwan, South Korea, and Germany consolidate around single-source gantry platforms. Foxconn and Luxshare centralize truss robot sourcing through frame agreements spanning multiple production sites.
- Pharmaceutical Production:FDA validation requirements for equipment qualification shape material selection and cleanroom washdown protocols in US installations, stretching deployment cycles for generic drug manufacturing.
- Aerospace Engineering:Heavy-material handling applications where span lengths exceed fifteen meters command premium pricing for rigidity-optimized steel lattice structures.
- Logistics Providers:Temperature-controlled automation accelerates electric actuator adoption over pneumatic systems under EU F-Gas Regulation restrictions.
- Food Processing:Delta robots retain mature share in pick-and-place operations, though cycle-time limits constrain truss robot penetration.
Electronics Manufacturing anchors revenue concentration. Pharmaceutical Production offers premium margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-precision truss robot manufacturing originated in German and Japanese machine tool traditions before scaling through East Asian electronics clusters. The technology diffused from Stuttgart's automotive belt to Taiwan's semiconductor fabs and China's Pearl River Delta contract manufacturers. Today, national industrial policies and regional specialization patterns determine competitive positioning across major manufacturing geographies.
Germany
Automotive powertrain automation around Stuttgart and Munich sustains demand for heavy-payload gantry configurations with rigidity premiums. CE marking requirements under EU machinery safety directives expand compliance burdens for OEMs serving European assembly lines. KUKA leverages its Stuttgart manufacturing base to sustain integrated control system production for regional automotive suppliers.
China
MIIT dual carbon goals and GB standards push servo motor efficiency mandates across domestic assembly plants. SAMR energy efficiency disclosures reshape procurement criteria for electric linear drives. Foxconn and Luxshare centralize truss robot sourcing through frame agreements spanning multiple production sites in the Pearl River Delta, reducing spare parts inventory complexity.
Japan
Memory fab automation in Yokkaichi and Hiroshima anchors demand for sub-10-micron following error in wafer-handling applications. METI industrial policy supports precision equipment exports through JIS standards alignment. Ball-screw supply concentration in Nagoya and Osaka creates lead-time advantages for domestic OEMs over mid-tier competitors outside these geographies.
South Korea
Samsung and SK Hynix fabs in Giheung and Icheon standardize on direct-drive gantries for 300mm wafer transport. MFDS pharmaceutical equipment frameworks shape cleanroom validation protocols for medical device handling applications. Busan-Ulsan industrial corridor demand concentrates in heavy-material handling for shipbuilding and offshore engineering.
United States
FDA validation requirements for pharmaceutical production equipment stretch deployment cycles for cleanroom-rated truss systems in generic drug manufacturing. EPA and OSHA frameworks govern material selection and worker safety in shared human-robot workspaces. Austin and Phoenix semiconductor clusters pull gantry architectures into new fab designs as Intel and TSMC expand domestic capacity.
High-Precision Truss Robot Market Competitive Landscape
The competitive structure tilts toward diversified industrial automation conglomerates with captive control system capabilities. Consolidation around single-source gantry platforms in electronics contract manufacturing compresses vendor qualification cycles and raises barriers for regional system integrators. Two strategic archetypes dominate: integrated motion control specialists with proprietary servo architectures, and heavy-payload gantry fabricators with structural engineering heritage. Competitive moves concentrate on geographic expansion through direct OEM partnerships and technology licensing for Ethernet-based servo networks.
Among German-based fabricators, KUKA and Güdel Group exemplify divergent specialization patterns within the precision automation space. FANUC anchors the Japanese contingent with scale advantages in high-repeatability servo architectures. Chinese competition intensifies through SIASUN Robot & Automation and emerging regional specialists in the Yangtze and Pearl River Delta manufacturing belts.
| Leading Market Players |
|---|
| KUKA |
| FANUC |
| Güdel Group |
| SIASUN Robot & Automation |
| Liebherr-International |
| Felsomat |
| FLT Automation |
| Qingdao Kingerobot |
| Anhui Hengtong Group |
| Others |
Pricing and Supply Chain Analysis
Ironless linear motor adoption in semiconductor wafer-handling applications simultaneously compresses maintenance economics and concentrates sourcing leverage among Japanese and German drive-train specialists. This technology transition elevates premium pricing for zero-cogging configurations while exposing mid-tier OEMs to supply bottlenecks in precision ground ball-screw alternatives.
Pricing Analysis
Hardware-software bundling splits the market between integrated control system packages and unbundled mechanical frames requiring third-party servo integration. Three-tier pricing structure across premium, standard, and economy levels separates CE-certified cleanroom configurations from uncertified material handling variants. Cost compression in economy-tier Cartesian systems intensifies because Chinese domestic OEMs scale aluminum extrusion capabilities. Contract electronics manufacturers exhibit lowest price sensitivity due to frame agreement standardization, while regional system integrators face acute margin pressure from consolidated procurement.
Supply Chain Analysis
Mechatronics talent scarcity in Taiwan, Germany, and Japan extends commissioning timelines and inflates field service premiums for multi-axis gantry deployments. Precision ground ball-screw production concentrates in Nagoya and Osaka, while rare earth magnet processing feeds from Chinese export channels. Single-source vulnerability in neodymium supply chains threatens permanent-magnet linear motor cost stability. Distribution runs through direct OEM partnerships with multinational electronics contract manufacturers, displacing traditional regional integrator networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder, with semiconductor fab automation sustaining predictable replacement cycles and efficiency-driven servo motor upgrades.
For Market Incumbents: Hedge against delta robot substitution in food packaging by accelerating vision-gantry convergence for pharmaceutical inspection cells. Deepen backward integration into ironless linear motor manufacturing to offset rare earth magnet volatility. Prioritize CE marking certification investments to defend European automotive powertrain positioning against emerging Chinese competition. For New Entrants and Emerging Players: India's PLI scheme for electronics manufacturing opens a window for precision automation penetration in Noida and Sriperumbudur corridors. Target cleanroom-rated Cartesian systems for generic drug manufacturing, where FDA validation burdens stretch incumbent deployment cycles. Pursue technology licensing partnerships for Ethernet-based servo networks to bypass proprietary fieldbus integration friction in brownfield automotive plants. For Investors and Strategic Acquirers: Valuations sit cheapest among heavy-payload gantry fabricators with structural engineering heritage and captive aerospace certifications. Long-term viability centers on platform standardization capabilities spanning 300mm to 450mm wafer transport architectures. Watch for single-source gantry consolidation announcements from Foxconn or Luxshare as inflection indicators for vendor qualification cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| Vision-Gantry Integration | 3D time-of-flight sensor fusion opens pharmaceutical blister packaging inspection revenue pools. |
| Backward Integration into Linear Motors | Captive ironless motor production insulates margins from rare earth magnet price volatility. |
| CE Marking Acceleration | EU machinery safety directive compliance expands addressable market in Stuttgart automotive belt. |
| Direct OEM Partnership Expansion | Frame agreements with contract electronics manufacturers reduce spare parts inventory complexity. |
| Cleanroom Certification Investment | FDA validation protocols for generic drug manufacturing stretch deployment cycles for unprepared competitors. |
Research Methodology
Coverage spans East Asian semiconductor clusters, German automotive manufacturing belts, and Chinese Pearl River Delta contract manufacturing zones, with primary inputs from each. Primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and mechatronics integration specialists combined with secondary validation from SEC filings, customs trade data, and GB standards disclosure databases. Bottom-up unit economics triangulated against top-down industry absorption rates.
Rate-of-change decomposition across the analysis window separates volume growth from mix-shift and pricing dynamics. Segmentation dimensions modeled include product architecture, sensing technology tier, end-use application, and regional regulatory cluster. CAGRs derived from installed base replacement cycles and greenfield fab automation intensity. Forecast inputs incorporate MIIT dual carbon mandate compliance timelines and semiconductor wafer diameter transition trajectories.
Revisions become necessary when rare earth export restrictions materialize, when FDA validation protocols for pharmaceutical equipment shift, or when single-source gantry standardization by major contract manufacturers accelerates vendor consolidation. Forecasts reflect documented assumptions about servo motor efficiency improvement rates and cleanroom protocol harmonization across regulatory jurisdictions. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Personal Robots Market
Robotics and Automation
Global Smart Robots Market
Robotics and Automation
Long-Range Drone Package Delivery Market
Robotics and Automation
Asia-Pacific Robotics Technology Market
Robotics and Automation
South Korea Cloud Robotics Market
Robotics and Automation
Robotic Drilling Market
Robotics and Automation
Soft Exoskeleton Market
Robotics and Automation
Household Robots Market
Robotics and Automation
Global Entertainment Robots Market
Robotics and Automation
Robot Market
Robotics and Automation
Middle East and Africa Warehouse Robotics Market
Robotics and Automation
India Cloud Robotics Market
Robotics and Automation
Robotic Process Automation in BFSI Market
Robotics and Automation
Mobile Robotics Market
Robotics and Automation
Global Indoor Robots Market
Robotics and Automation
Smart Sweeper Market