
 Gantry Industrial Robots Market | 2026-2036
Gantry Industrial Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Gantry Industrial Robots Market Intelligence
High-precision linear positioning tiers is unwinding legacy cost-performance trade-offs across factory floors. Yamaha Motor Co., Ltd. leverages its servo motor integration to dominate compact electronics assembly lines. FANUC Corporation anchors heavy-payload automotive welding cells with proprietary multi-axis controllers. ABB Ltd. competes through modular custom configurations that slash commissioning cycles for tier-one suppliers.
Gantry industrial robots are Cartesian-coordinate manipulators built on rigid linear rail frameworks, typically achieving positional repeatability below ±0.05 millimeter through ball-screw or linear-motor drives, and they execute pick-place, dispensing, and assembly tasks across extended work envelopes. Servo motor technology leads installed value due to closed-loop torque control and energy recuperation, while pneumatic actuators retain share in cost-sensitive food packaging where explosive environments preclude electric drives. Multi-axis configurations capture the fastest structural expansion as semiconductor and battery manufacturers demand synchronized six-degree-of-freedom motion within single-gantry footprints.
OSHA machine guarding standards and ISO 10218 robot safety codes shape North American procurement by mandating collaborative speed limits and force-sensing peripheries, while CE marking under the EU Machinery Directive gates European market access through third-party conformity assessment. The EU AI Act introduces emerging compliance burdens for vision-guided gantry systems with embedded learning algorithms. Stakeholders must monitor how regional safety codes diverge on autonomous operation thresholds before committing to platform architectures.
Market Dynamics
Electric vehicle battery gigafactories are forcing gantry robot architectures toward multi-axis synchronized motion systems that compress factory footprints while handling heavier payloads per linear meter of rail.
Growth Catalysts
- OSHA machine guarding retrofits:North American automotive plants face mandated upgrades of legacy Cartesian systems to force-sensing peripheries, creating replacement demand across Michigan and Ohio assembly corridors.
- Semiconductor wafer handling:Taiwan and South Korea foundries deploy six-degree-of-freedom gantries for sub-micron positioning in advanced packaging lines, pulling precision-engineered linear motor configurations.
- Germany's precision-engineering clusters:Stuttgart and Munich automotive OEMs anchor European procurement through modular gantry specifications that slash commissioning cycles for tier-one suppliers.
Market Restraints
- Ball-screw supply concentration:Japanese and German precision component suppliers control critical linear drive manufacturing, exposing buyers to extended lead times during capacity constraints.
- Pneumatic actuator substitution limits:Explosive food packaging environments preclude electric servo adoption, locking cost-sensitive segments into lower-performance pneumatic systems.
- ISO 10218 compliance friction:Third-party conformity assessment for collaborative speed limits adds certification delays and consulting costs to North American deployments.
Strategic Opportunities
- India's PLI scheme for manufacturing:Production-linked incentives for electronics and automotive assembly create first-mover positioning for gantry suppliers establishing local commissioning support.
- Battery module handling convergence:Vision-guided systems with embedded learning algorithms intersect with EU AI Act compliance frameworks, creating premium-tier differentiation for algorithm-augmented positioning.
- Direct OEM channel bypass:Tier-one suppliers in Germany and Japan are procuring modular gantry configurations directly from subsystem integrators, compressing traditional distributor margins.
Industry Challenges
- Multi-axis synchronization expertise:Battery and semiconductor manufacturers struggle to source controls engineers capable of programming six-degree-of-freedom motion within single-gantry footprints.
- Legacy system integration complexity:Automotive welding cells require proprietary controller bridges to mesh new FANUC and ABB gantries with existing PLC architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gantry Industrial Robots Market |
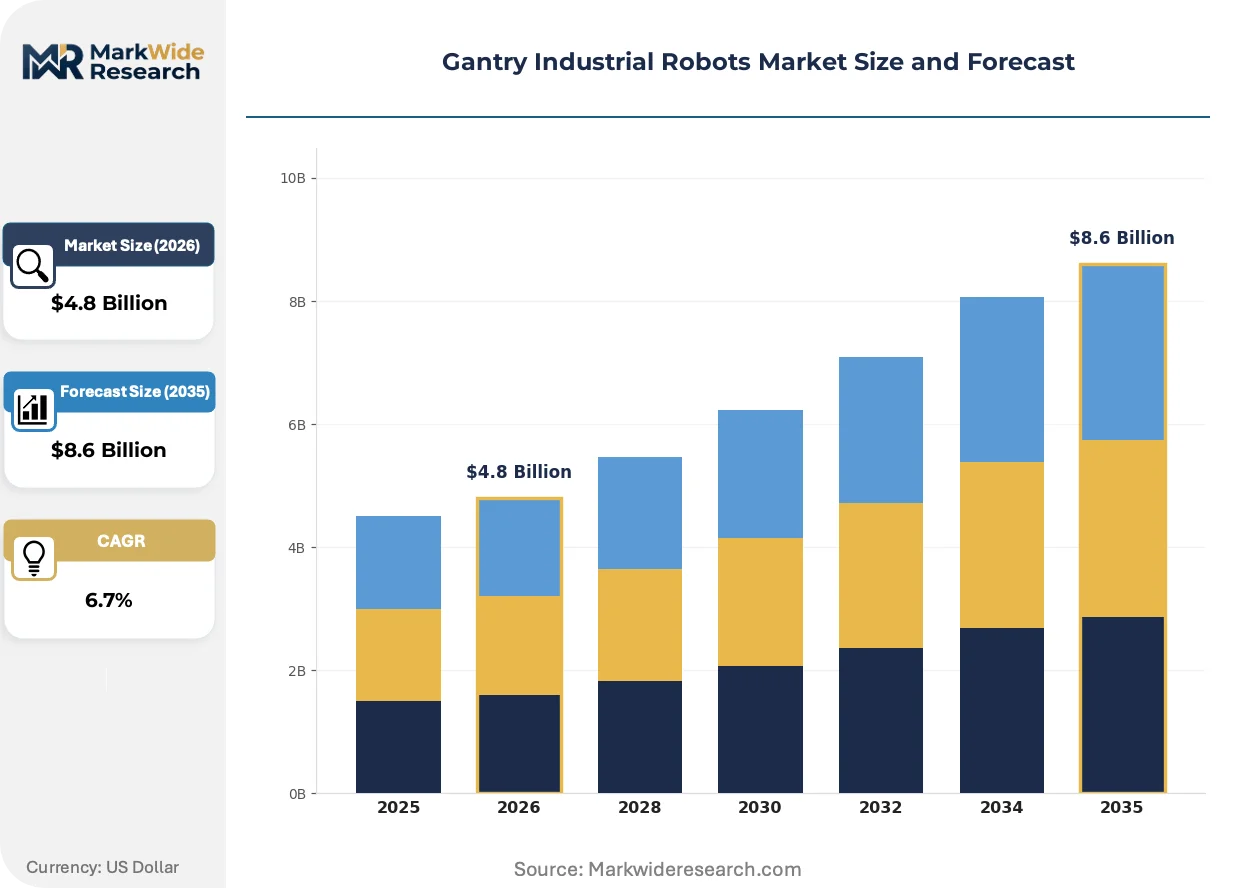
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Axis, Dual-Axis, Three-Axis, Multi-Axis, Custom Configuration Technology: Servo Motors, Pneumatic Actuators, Stepper Motors, Hydraulic Drives, Linear Actuators Application: Material Handling, Automated Assembly, Welding Operations, Packaging Automation, Inspection & Quality Control End User: Electronics Manufacturing, Automotive Assembly Plants, Aerospace Fabrication, Consumer Goods Production, Food Processing Units |
| Companies Covered | Yamaha Motor Co., Ltd., Yaskawa Electric Corporation, FANUC Corporation, Mitsubishi Electric Corporation, Liebherr, ABB Ltd., Toshiba Machine Co., Ltd., Kawasaki Heavy Industries, Ltd., KUKA AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gantry Industrial Robots Market Strategic Shifts & Innovations
Linear motor drives are actively compressing the cost-performance boundary that has historically separated precision semiconductor applications from standard industrial handling.
Linear motor technology replaces ball-screw mechanisms in high-throughput battery assembly lines. Korean and Taiwanese battery manufacturers adopt these systems for sub-50-micron repeatability at speeds exceeding 3 meters per second. This is displacing traditional rack-and-pinion configurations from applications previously considered cost-prohibitive for linear motor economics.
The EU AI Act introduces conformity obligations for vision-guided gantry systems with embedded learning algorithms. Industrial robot OEMs must now document algorithmic decision transparency and human oversight protocols for European market access. Semiconductor and battery manufacturers in Germany and the Netherlands face the steepest compliance ramps as early adopters of AI-augmented positioning.
Automotive tier-one suppliers now unbundle after-sales service contracts from initial hardware procurement. German and Japanese OEMs negotiate separate multi-year maintenance agreements with regional service integrators rather than accepting captive OEM service bundles. This channel fragmentation is most visible in Stuttgart and Nagoya manufacturing corridors where supplier consolidation has concentrated buyer leverage.
Gantry Industrial Robots Market Segmentation
Gantry robot buyers face distinct trade-offs between precision, payload capacity, and commissioning complexity across factory floors. Segmentation reveals how battery gigafactories, semiconductor foundries, and automotive welding cells pull demand toward divergent technical specifications.
Product Type:
Single-axis and dual-axis configurations dominate domestic procurement for simple pick-place operations, while multi-axis and custom systems anchor export-led demand from precision manufacturing clusters in Germany, Taiwan, and South Korea.
- Single-Axis:Ball-screw-driven linear modules achieve ±0.1 millimeter repeatability for basic material transfer along one Cartesian plane. Food processing units in the United States deploy these for cost-sensitive packaging lines where pneumatic actuation suffices.
- Multi-Axis:Synchronized six-degree-of-freedom gantries compress factory footprints through integrated linear motor drives. Taiwan Semiconductor Manufacturing Company and Samsung SDI battery lines pull these configurations for sub-50-micron positioning at speeds exceeding 3 meters per second.
- Dual-Axis:XY planar systems serve electronics assembly with moderate precision requirements.
- Three-Axis:XYZ configurations bridge standard handling and precision applications.
- Custom Configuration:Modular architectures from ABB and FANUC enable rapid commissioning for tier-one automotive suppliers.
Single-axis configurations hold the largest share; momentum sits with multi-axis systems as battery and semiconductor manufacturers demand synchronized motion within compressed footprints.
Technology:
Cost tier stratification separates precision applications from commodity handling, with closed-loop electric systems commanding premium positioning against pneumatic alternatives locked into explosive-environment constraints.
- Servo Motors:Closed-loop torque control with energy recuperation dominates high-value installations. FANUC Corporation anchors automotive welding cells with proprietary multi-axis controllers leveraging this technology.
- Pneumatic Actuators:Compressed-air drives retain share in cost-sensitive food packaging where OSHA explosive atmosphere classifications preclude electric servo adoption. Performance ceilings constrain expansion beyond simple pick-place operations.
- Stepper Motors:Open-loop positioning suits low-cost electronics assembly with moderate repeatability needs.
- Hydraulic Drives:High-force applications in heavy fabrication tolerate fluid power maintenance overhead.
- Linear Actuators:Direct-drive linear motors displace ball-screw mechanisms in Korean and Taiwanese battery assembly lines.
Servo motors capture the dominant value position; linear actuators are expanding most quickly as linear motor economics compress cost-performance boundaries.
Application:
Volume concentration in material handling reflects broad deployment across factory floors, while margin expansion concentrates in inspection and quality control as vision-guided systems integrate EU AI Act compliance requirements.
- Material Handling:Extended work envelope pick-place operations span automotive battery module transfer and electronics component feeding. Michigan and Ohio assembly corridors generate replacement demand as OSHA mandates force-sensing periphery retrofits.
- Inspection & Quality Control:Vision-guided gantries with embedded learning algorithms face emerging EU AI Act conformity obligations for algorithmic transparency. Semiconductor manufacturers in Germany and the Netherlands encounter steepest compliance ramps as early adopters.
- Automated Assembly:Precision component placement drives modular gantry specifications.
- Welding Operations:Heavy-payload automotive cells require proprietary controller bridges for PLC integration.
- Packaging Automation:Food processing units balance pneumatic cost advantages against electric precision.
Material handling commands the greatest installed base; inspection and quality control offers the steepest expansion trajectory as AI-augmented positioning creates premium-tier differentiation.
End User:
Customer type maturity varies sharply, with automotive assembly plants driving standardization through tier-one supplier consolidation while aerospace fabrication demands bespoke engineering with extended commissioning cycles.
- Automotive Assembly Plants:Electric vehicle battery gigafactories force architectures toward synchronized multi-axis systems handling heavier payloads per linear meter. Stuttgart and Munich OEMs anchor European procurement through modular specifications.
- Electronics Manufacturing:Compact assembly lines favor Yamaha Motor servo-integrated configurations for sub-millimeter repeatability in high-volume consumer device production.
- Aerospace Fabrication:Large-envelope composite handling requires custom engineering with extended lead times.
- Consumer Goods Production:Cost-sensitive packaging lines balance pneumatic and electric trade-offs.
- Food Processing Units:Explosive environment constraints lock segments into pneumatic actuator limitations.
Automotive assembly plants represent the largest demand concentration; electronics manufacturing is gaining share fastest as semiconductor packaging investments accelerate in Taiwan and South Korea.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-heavy precision engineering clusters in Germany and Japan generate substantial gantry robot trade surpluses, while import-dependent battery gigafactories in South Korea and Taiwan drive cross-border procurement of linear motor configurations. The United States maintains a structural deficit in high-precision linear drive components, sourcing critical ball-screw assemblies from Japanese and German suppliers.
United States
Automotive battery module handling and OSHA-mandated safety retrofits dominate procurement across Michigan and Ohio assembly corridors. The Department of Labor enforces machine guarding standards that compel force-sensing periphery upgrades in legacy Cartesian systems. Detroit-area OEMs anchor replacement demand as tier-one suppliers consolidate gantry specifications for electric vehicle production.
Germany
Stuttgart and Munich automotive clusters drive modular gantry specifications that compress commissioning cycles for tier-one suppliers. CE marking under the EU Machinery Directive gates market access through third-party conformity assessment for collaborative speed limits. Bavarian precision-engineering firms supply linear motor drives to domestic battery manufacturers and export to Dutch semiconductor foundries.
Japan
Ball-screw and linear motor component manufacturing concentrates under METI industrial policy support for precision machinery exports. JIS standards govern repeatability certifications for sub-50-micron positioning systems. Nagoya manufacturing corridors host servo motor integrators serving domestic automotive welding cells and Taiwanese electronics assembly lines.
South Korea
Samsung SDI battery lines and semiconductor packaging operations pull six-degree-of-freedom gantries for synchronized multi-axis motion. The Ministry of Trade, Industry and Energy channels support toward domestic linear motor adoption in gigafactory automation. Busan-Ulsan industrial complexes concentrate demand for high-throughput material handling at speeds exceeding 3 meters per second.
Taiwan
TSMC advanced packaging lines deploy precision gantries for sub-micron wafer positioning in semiconductor fabrication. The National Development Council prioritizes automation equipment procurement under technology upgrade programs. Hsinchu Science Park anchors foundry demand for linear motor configurations that displace legacy rack-and-pinion systems.
Gantry Industrial Robots Market Key Industry Players
Listed leaders compete with private specialists across servo motor integration and multi-axis controller architectures. The vendor base stratifies into three tiers: diversified industrial conglomerates with captive robotics divisions, pure-play automation specialists with modular configuration capabilities, and regional subsystem integrators serving localized commissioning needs. Strategic moves concentrate on backward integration into linear drive manufacturing and direct OEM channel establishment that compresses traditional distribution margins.
Within the diversified industrial tier, FANUC Corporation and ABB Ltd. exemplify contrasting approaches to controller architecture and geographic footprint. Yamaha Motor Co., Ltd. occupies a specialist position in compact servo-integrated configurations for electronics assembly. KUKA AG represents European precision-engineering origins through its German corporate structure.
| Leading Market Players |
|---|
| Yamaha Motor Co., Ltd. |
| Yaskawa Electric Corporation |
| FANUC Corporation |
| Mitsubishi Electric Corporation |
| Liebherr |
| ABB Ltd. |
| Toshiba Machine Co., Ltd. |
| Kawasaki Heavy Industries, Ltd. |
| KUKA AG |
| Others |
Cost & Logistics Intelligence
Fourteen-to-eighteen-week lead times for Japanese ball-screw assemblies concentrate pricing power among Stuttgart and Nagoya precision component suppliers, while German linear motor manufacturers extract premiums through captive integration of servo controllers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with FANUC and ABB commanding brand premiums for proprietary multi-axis controllers. Price differentiation hinges on ISO 10218 certification tier and after-sales service bundling, though German tier-one suppliers increasingly unbundle maintenance contracts to compress distributor margins. Pricing pressure stems from Korean battery manufacturers demanding linear motor economics at ball-screw price points. Food processing units exhibit highest price sensitivity, locked into pneumatic systems by OSHA explosive atmosphere classifications.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes amplify inbound logistics costs for Taiwanese foundries sourcing German linear motor drives. Component manufacturing concentrates in Japan, Germany, and South Korea, with ball-screw precision grinding and servo motor winding anchoring regional specialization. The supply chain draws from rare-earth magnet feedstock, high-grade steel rail stock, and ceramic bearing elements. Single-source vulnerability persists for sub-50-micron linear encoders. Distribution runs through tier-one automotive supplier consolidation in Stuttgart and Nagoya corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tier-one automotive supplier consolidation across Michigan and Ohio assembly corridors has shifted bargaining power toward buyers capable of mandating modular gantry specifications across multi-year procurement frameworks.
For Market Incumbents: Secure backward integration into linear drive manufacturing to defend against Korean and Taiwanese battery manufacturers bypassing traditional distributor channels. Capture proprietary controller bridge technology for legacy PLC integration in automotive welding cells. METI-supported Japanese component suppliers pose substitution threats through JIS-certified precision grinding capacity. For New Entrants and Emerging Players: Lead with commissioning support capabilities in India's PLI scheme corridors, where electronics and automotive assembly incentives outpace local gantry integration expertise. Target semiconductor packaging applications in Hsinchu Science Park, where TSMC's advanced packaging lines demand sub-micron positioning without incumbent service entrenchment. Establish direct OEM relationships with tier-one suppliers to circumvent established distributor margins. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming robotics divisions, particularly those lacking servo motor integration or multi-axis controller development. Long-term viability centers on algorithm-augmented positioning capabilities intersecting with EU AI Act compliance frameworks. Watch for inflection when battery gigafactory automation capex accelerates in Busan-Ulsan industrial complexes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Linear Drive Manufacturing | FANUC and ABB reduce dependency on Japanese ball-screw suppliers during capacity constraints. |
| Direct OEM Channel Establishment | German tier-one suppliers in Stuttgart corridors bypass traditional distributor margins through subsystem integrator relationships. |
| EU AI Act Compliance Documentation | Vision-guided gantry OEMs in Germany and Netherlands secure market access through algorithmic transparency protocols. |
| Modular Configuration Capability Investment | ABB compresses commissioning cycles for tier-one automotive suppliers through rapid deployment architectures. |
| Regional Service Integrator Acquisition | Yamaha Motor strengthens electronics assembly support in Taiwan and South Korea packaging lines. |
Research Approach
The analysis maps single-axis pick-place modules, multi-axis synchronized systems, and custom automotive welding configurations, each validated through plant engineers, OEM procurement teams, aftermarket service heads, and linear drive component suppliers. Primary fieldwork combined with secondary validation from SEC filings of listed automation conglomerates, METI precision machinery export statistics, and EU Machinery Directive conformity assessment databases. Bottom-up installation tracking across Michigan, Ohio, Stuttgart, and Nagoya manufacturing corridors triangulates against top-down OEM capex disclosures.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled product type, technology tier, application intensity, and end-user maturity dimensions. CAGRs derived from battery gigafactory automation intensity curves and semiconductor packaging equipment replacement cycles, with cross-reference to OSHA machine guarding retrofit mandates and EU AI Act implementation timelines.
The analysis sits within stated boundaries; outcomes outside sustained electric vehicle production scaling, linear motor cost compression trajectories, or regulatory harmonization on collaborative robot speed limits would require recalibration. Forecasts reflect documented assumptions about tier-one supplier consolidation patterns and precision component manufacturing capacity expansion. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Global K-12 Robotic Toolkits Market
Robotics and Automation
AGV Software Market
Robotics and Automation
Robotics in Shipbuilding Market
Robotics and Automation
Underwater Drone Market
Robotics and Automation
Commercial Robotics Market
Robotics and Automation
High-Precision Truss Robot Market
Robotics and Automation
Retail Robotics Market
Robotics and Automation
US Cloud Robotics Market
Robotics and Automation
Biaxial Mobile Phone Stabilizer Market
Robotics and Automation
Commercial Service Robotics Market
Robotics and Automation
Drone-Based NDT Inspection Systems for Energy and Infrastructure Assets Market
Robotics and Automation
Middle East and Africa Warehouse Robotics Market
Robotics and Automation
Agricultural Robots Market
Robotics and Automation
Asia-Pacific Data Center Robotics Market
Robotics and Automation
Robotic Flexible Washer Market
Robotics and Automation
Top Robotics Market