
 Canada Commercial Construction Market | 2026-2036
Canada Commercial Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Commercial Construction Market Insights
Modular prefabrication is fragmenting traditional project delivery timelines across Canadian commercial sites. PCL Construction leverages its national fabrication network to compress schedules for healthcare and institutional clients. EllisDon Corporation anchors its position through integrated design-build contracts that span Ontario and Western Canada. Aecon Group Inc. competes on civil-commercial crossover expertise, particularly in transit-adjacent developments.
Canada commercial construction encompasses the planning, erection, and finishing of non-residential structures using steel framing, cast-in-place concrete, engineered wood products, and high-performance glazing systems designed to meet seismic and climatic load requirements. Office buildings and warehouses command the largest share of current project value, though sustainable construction methods are capturing disproportionate attention from institutional investors seeking carbon-reduction credentials. Steel and concrete retain material dominance, yet mass timber is carving a structural niche in mid-rise commercial buildings through updated National Building Code provisions.
Health Canada, the National Research Council, and provincial building authorities collectively enforce the National Building Code and energy efficiency standards that dictate envelope performance and mechanical system specifications. These codes shape demand by mandating stepped efficiency improvements that elevate upfront capital requirements while reducing operational energy exposure. Stakeholders must track how provincial adoption timelines for the next code cycle alter project pro formas and financing structures.
Market Dynamics
The National Building Code of Canada's tiered energy efficiency mandates are compressing project timelines while elevating upfront capital requirements. This regulatory architecture is redirecting contractor capabilities toward envelope performance optimization and mechanical system integration.
Growth Catalysts
- Healthcare Infrastructure Mandates:Provincial health authorities are accelerating hospital expansion and long-term care facility construction. Federal infrastructure commitments are unlocking institutional capital pools for acute care and ambulatory projects.
- Mass Timber Code Recognition:Updated National Building Code provisions now permit mid-rise commercial structures using engineered wood products. This material shift is opening structural alternatives to steel and concrete in Ontario and British Columbia developments.
- Transit-Oriented Development Corridors:Municipal zoning reforms across the Greater Toronto Area are densifying nodes around subway and light rail extensions. Mixed-use commercial towers are concentrating demand within 800-meter radii of station infrastructure.
Market Restraints
- Steel Input Volatility:North American steel pricing fluctuations are compressing margin visibility for structural framing contractors. Tariff exposure on imported rebar and structural sections is elevating contingency reserves in project pro formas.
- Skilled Trades Concentration:Regional labor pools for commercial glazing and high-performance envelope installation are thinning in Atlantic Canada. Migration patterns are favoring Ontario and Alberta markets, leaving eastern provinces exposed to wage inflation.
- Seismic Design Complexity:British Columbia's seismic zone requirements are elevating engineering costs for high-rise commercial structures. Foundation and lateral system specifications are consuming disproportionate design phase resources.
Strategic Opportunities
- Indigenous Partnership Models:Federal procurement mandates are creating set-aside volumes for First Nations joint ventures on federal building projects. Saskatchewan and Manitoba are seeing elevated contract flow to Indigenous-led construction entities.
- Deep Energy Retrofit Incentives:The Canada Greener Homes Loan program and provincial efficiency utilities are unlocking capital for commercial building envelope and mechanical system overhauls. Existing office stock in Calgary and Edmonton represents underpenetrated retrofit volume.
- Modular-Permanent Hybrid Delivery:Prefabricated volumetric units are migrating from temporary applications into permanent commercial structures. Quebec manufacturers are capturing institutional demand through accelerated schedule guarantees.
Industry Challenges
- Building Envelope Commissioning Bottlenecks:Certified envelope specialists are scarce relative to code-mandated testing protocols. Project handover timelines are extending as thermal bridging verification and air tightness testing queues lengthen.
- Cross-Trade Coordination Complexity:Mechanical-electrical-plumbing integration with mass timber structural systems demands sequencing precision that general contractors are building through trial on early projects. Design-phase clash detection is consuming additional pre-construction resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Commercial Construction Market |
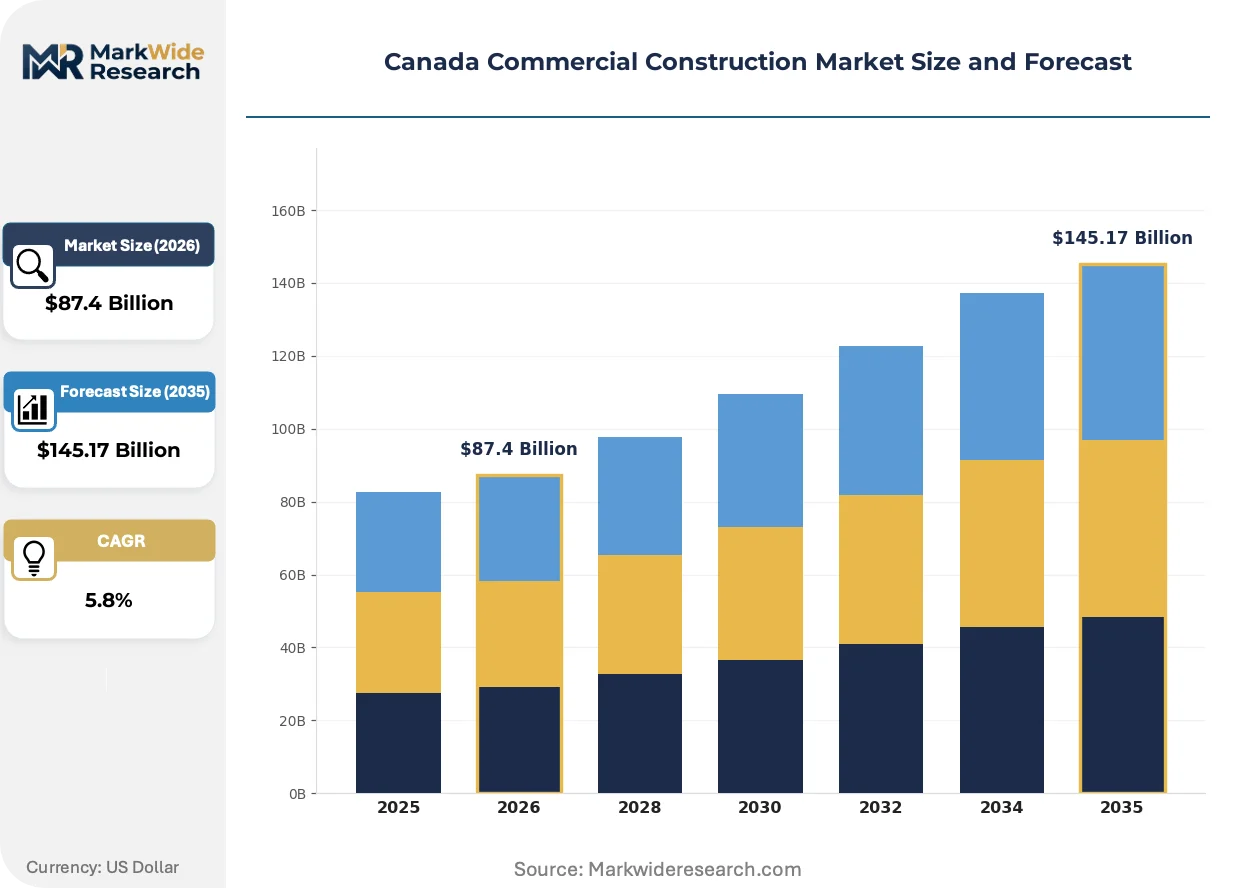
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $145.17 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Office Buildings, Retail Spaces, Warehouses, Hospitality Facilities Materials Used: Steel, Concrete, Wood, Glass Construction Method: Traditional, Modular, Renovation, Sustainable Client Type: Government, Corporations, Developers, Investors |
| Companies Covered | PCL Construction, EllisDon Corporation, Pomerleau, Aecon Group Inc., Graham Construction, Ledcor Group of Companies, Kiewit Canada Group Inc., Broccolini, Bird Construction Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Commercial Construction Market Trends and Innovations
Digital fabrication and performance-based code compliance are compressing traditional design-bid-build cycles. Contractors are reconfiguring pre-construction workflows around building information modeling and offsite component production.
Cross-laminated timber and glue-laminated beams are migrating from niche applications into structural systems for six-to-twelve story commercial buildings. Institutional developers in British Columbia and Quebec are specifying mass timber for carbon accounting advantages. The technology is migrating from demonstration projects into repeat client portfolios as insurance and financing structures standardize.
Health Canada's stepped energy efficiency tiers are mandating performance thresholds that exceed previous prescriptive code cycles. Envelope U-value and mechanical system coefficients are tightening on three-year intervals. Ontario and British Columbia adoption timelines are running ahead of prairie provinces, creating uneven compliance landscapes across contractor operating territories.
Institutional buyers are consolidating procurement around design-build and construction management at-risk contracts. Traditional hard-bid tendering is retreating to standardized warehouse and distribution facilities. Healthcare and post-secondary clients in the Greater Toronto Area are favoring single-point accountability models that transfer risk to integrated delivery teams.
Canada Commercial Construction Market Segmentation
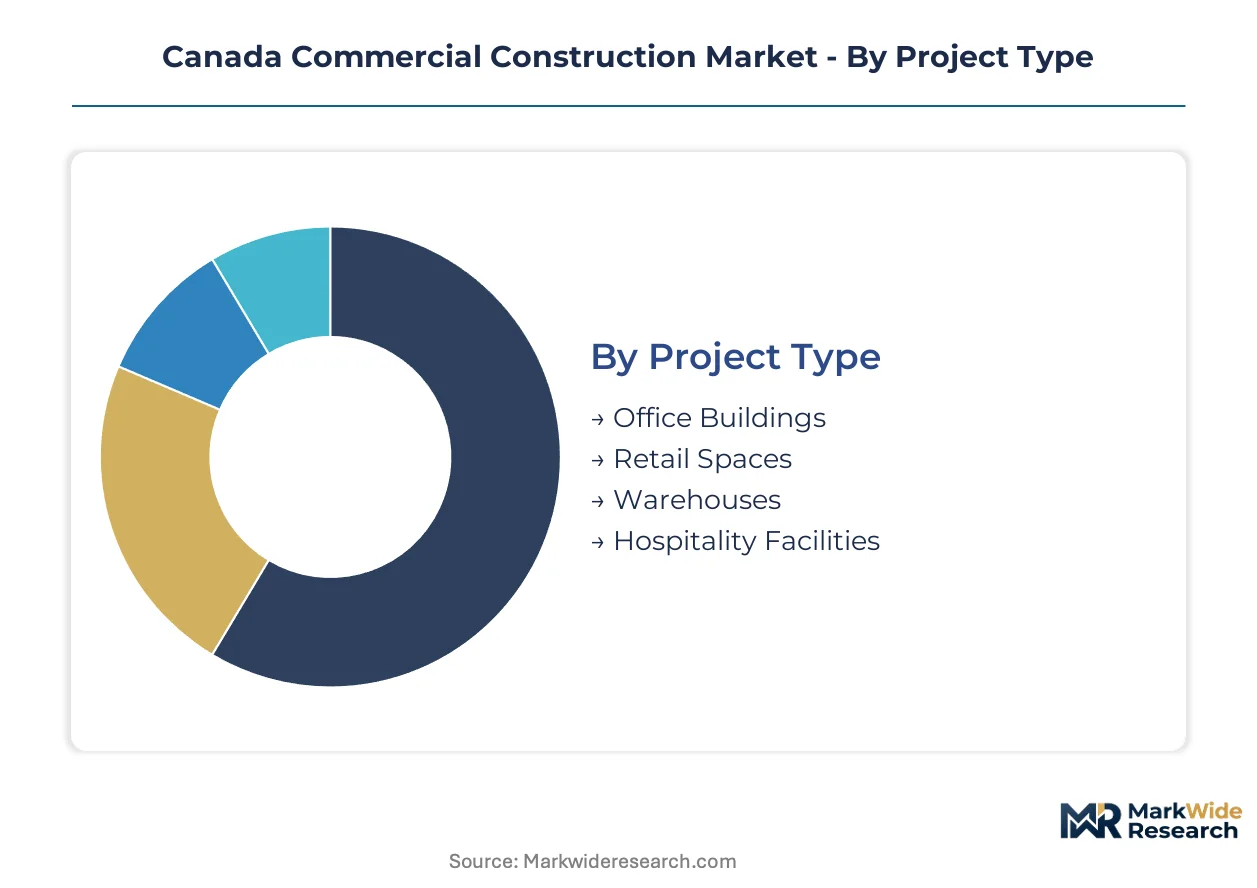
Canada's commercial construction market fragments across project scale, material systems, delivery methods, and capital sources. Each segmentation dimension reveals distinct procurement patterns, risk allocation structures, and regulatory compliance pathways that shape contractor positioning and client decision frameworks.
Project Type:
Development pipelines span speculative income-producing assets, purpose-built institutional facilities, and logistics infrastructure serving e-commerce fulfillment networks.
- Office Buildings:Class A towers in Toronto and Vancouver command premium rents through high-performance envelopes and transit adjacency. Institutional investors anchor pre-leasing commitments before construction mobilization.
- Retail Spaces:Strip centers and enclosed malls face obsolescence pressure; mixed-use podium retail integrated with residential towers captures redevelopment capital. Grocery-anchored neighborhood centers retain financing availability in secondary markets.
- Warehouses:Distribution facilities near Highway 401 corridors and Calgary's logistics hub attract pension fund capital. Clear-height specifications and cross-dock configurations dominate tenant requirements.
- Hospitality Facilities:Full-service hotels concentrate in Toronto's downtown core; limited-service properties expand along Quebec autoroute interchanges. Franchise agreements dictate prototype compliance.
Established volume favors warehouses; emerging adoption favors office-to-residential conversions.
Materials Used:
Structural material selection balances seismic load requirements, carbon accounting mandates, and supply chain reliability across provincial building code jurisdictions.
- Steel:Wide-flange sections and composite deck systems dominate high-rise commercial cores in Toronto and Calgary. Tariff exposure on imported structural shapes is elevating domestic mill premiums.
- Concrete:Cast-in-place and precast systems anchor podium structures and parking garages. British Columbia's seismic zone demands ductile moment frame detailing that consumes disproportionate engineering resources.
- Wood:Mass timber code recognition permits six-to-twelve story commercial structures in Ontario and British Columbia. Cross-laminated panels reduce embodied carbon for institutional clients with net-zero commitments.
- Glass:High-performance curtainwall systems with triple-glazed units meet National Building Code energy tiers. Thermal bridging mitigation at spandrel conditions drives fabrication complexity.
Structural dominance remains with steel and concrete; mass timber represents the steepest expansion trajectory among material alternatives.
Construction Method:
Delivery model selection depends on schedule compression requirements, design certainty at procurement, and client risk tolerance for cost escalation.
- Traditional:Design-bid-build sequencing persists for standardized warehouse and retail pad developments. Hard-bid tendering transfers construction risk to lowest-compliant bidders.
- Modular:Volumetric prefabrication accelerates healthcare and institutional schedules through factory-controlled quality. Quebec manufacturers capture repeat demand from provincial health authorities.
- Renovation:Deep energy retrofits of Calgary and Edmonton office stock access Canada Greener Homes financing. Envelope commissioning bottlenecks extend project handover timelines.
- Sustainable:Integrated design-build contracts incorporate LEED and Zero Carbon Building standards. Performance-based energy modeling precedes construction documentation.
Traditional methods retain volume leadership; modular delivery is gaining share fastest among institutional clients.
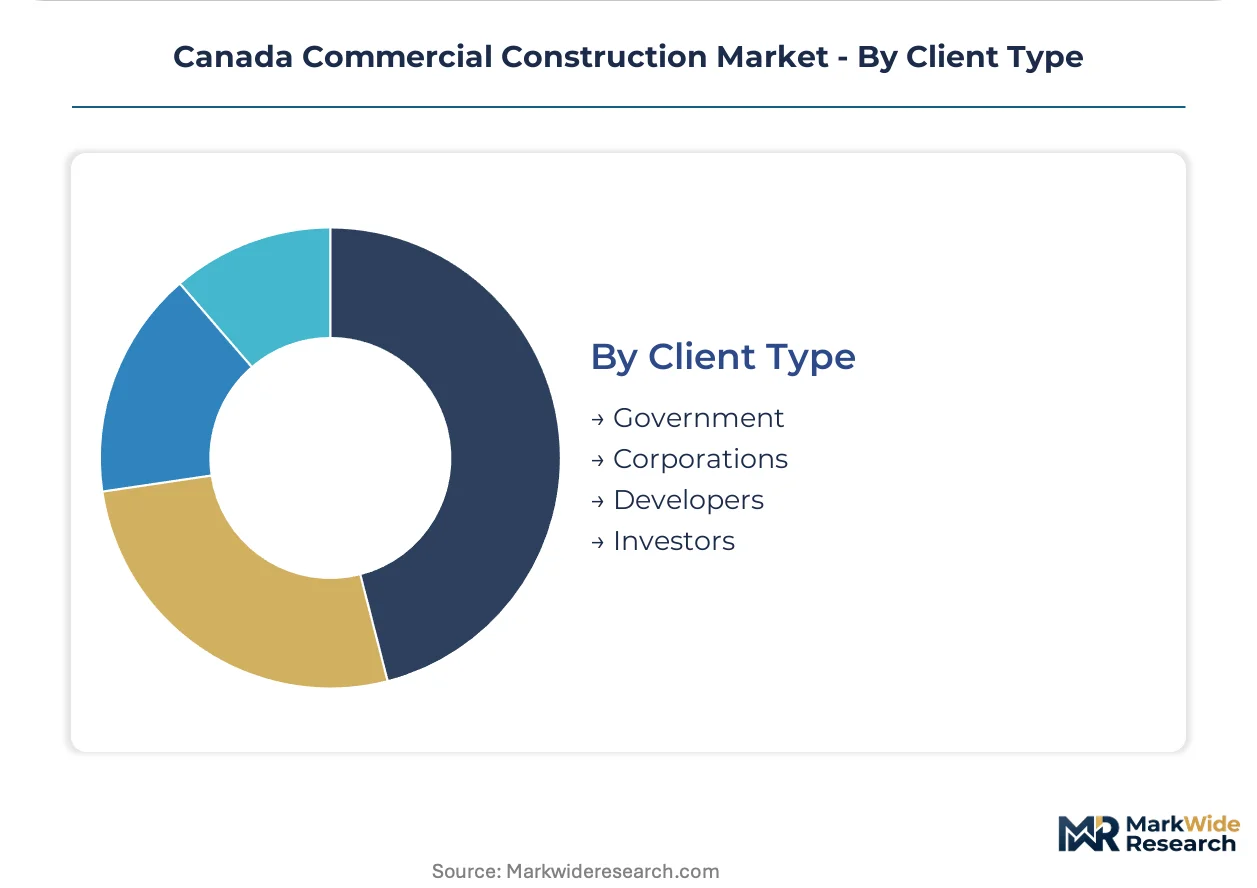
Client Type:
Capital source determines procurement sophistication, contract form selection, and stakeholder alignment mechanisms throughout project lifecycles.
- Government:Federal procurement mandates reserve contract flow for Indigenous joint ventures in Saskatchewan and Manitoba. P3 structures transfer operational risk for healthcare and transit facilities.
- Corporations:Owner-occupied headquarters concentrate design-build accountability with single-point responsibility. Technology and financial services firms anchor Class A pre-leasing in Toronto.
- Developers:Speculative commercial towers in the Greater Toronto Area secure construction financing against pre-leasing thresholds. Equity partners demand carbon-risk disclosure for institutional capital access.
- Investors:Pension funds and REITs consolidate logistics asset portfolios near Vancouver port infrastructure and Calgary distribution corridors. Yield compression is elevating development-to-core strategies.
Institutional investors anchor the largest transaction volumes; government procurement is expanding most quickly through infrastructure commitments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada exports commercial construction expertise and prefabricated components primarily to United States border markets, with Ontario and Quebec fabricators supplying volumetric modules for healthcare and institutional projects across the Great Lakes and Northeast corridors.
Ontario
The Greater Toronto Area concentrates mixed-use commercial tower development within 800-meter radii of subway and light rail extensions. Health Canada energy efficiency tier adoption runs ahead of national timelines, compressing project pro formas. PCL Construction and EllisDon Corporation anchor design-build procurement for healthcare and post-secondary clients across Toronto and Ottawa corridors.
Quebec
Provincial health authorities drive hospital expansion and long-term care facility construction through accelerated procurement schedules. The National Building Code energy provisions apply with Quebec-specific amendments to envelope performance standards. Montreal manufacturers capture institutional demand for modular volumetric units through factory-controlled quality guarantees.
Alberta
Calgary and Edmonton office stock represents underpenetrated volume for deep energy retrofits accessing Canada Greener Homes financing. Provincial building authorities enforce stepped efficiency improvements that elevate upfront capital requirements. Distribution facilities near Calgary logistics hubs attract pension fund capital for e-commerce fulfillment infrastructure.
British Columbia
Seismic zone requirements elevate engineering costs for high-rise commercial structures in Vancouver and Victoria. Updated National Building Code provisions permit mid-rise mass timber construction for institutional clients with net-zero commitments. Transit-oriented densification concentrates mixed-use development around SkyTrain extensions in Burnaby and Surrey.
Atlantic Canada
Regional labor pools for commercial glazing and high-performance envelope installation are thinning, exposing projects to wage inflation. Federal procurement mandates create set-aside volumes for First Nations joint ventures on federal building projects in Nova Scotia and New Brunswick. Healthcare infrastructure mandates from provincial health authorities accelerate hospital expansion in Halifax.
Canada Commercial Construction Market Competitive Landscape
On the supply side, the industry is consolidating around integrated delivery capabilities that compress project timelines and transfer risk to single-point accountability structures. National contractors with fabrication networks and regional specialists with geographic density form a tiered competitive architecture. Three archetypes dominate: scale-driven national generalists, mid-sized integrated design-build specialists, and Indigenous-led joint venture entities. M&A activity targets envelope commissioning capabilities, while strategic partnerships secure mass timber fabrication capacity.
Among national-scale contractors, PCL Construction exemplifies the integrated delivery archetype through its national fabrication network, while EllisDon Corporation occupies a position within the design-build specialist tier. Aecon Group Inc. anchors the civil-commercial crossover segment. These three entities collectively represent the competitive positioning spectrum: scale-driven vertical integration, integrated project delivery expertise, and infrastructure-adjacent commercial development capability.
| Leading Market Players |
|---|
| PCL Construction |
| EllisDon Corporation |
| Pomerleau |
| Aecon Group Inc. |
| Graham Construction |
| Ledcor Group of Companies |
| Kiewit Canada Group Inc. |
| Broccolini |
| Bird Construction Inc. |
| Others |
Pricing and Supply Chain Analysis
Tariff exposure on imported structural steel sections determines both the premium spread between domestic and foreign-sourced framing packages and the geographic clustering of fabrication capacity around Ontario and Quebec mill networks. Contractors are absorbing margin compression through contingency reserves while redirecting procurement toward captive domestic supply.
Pricing Analysis
Current-generation high-performance envelope systems command substantial premiums over prior-generation double-glazed assemblies, while next-generation carbon-capture concrete remains pre-commercial. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and geographic delivery cost differentials. Cost compression in mid-rise structural packages is intensifying because mass timber code recognition is displacing conventional steel framing in Ontario and British Columbia. Institutional developers with net-zero mandates show the least price sensitivity; speculative warehouse developers exhibit the most.
Supply Chain Analysis
Upstream feedstock for structural materials draws from Canadian domestic steel mills, US rebar producers, and engineered wood manufacturers concentrated in British Columbia and Quebec. Cross-laminated timber panels, high-strength concrete admixtures, and triple-glazed curtainwall units anchor material dependencies. Single-source vulnerability concentrates in specialized envelope commissioning specialists relative to project demand. Distribution runs through national general contractor procurement desks with regional fabricator networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among pension funds and institutional investors consolidating logistics and healthcare portfolios, compressing contractor margins and elevating single-point accountability demands.
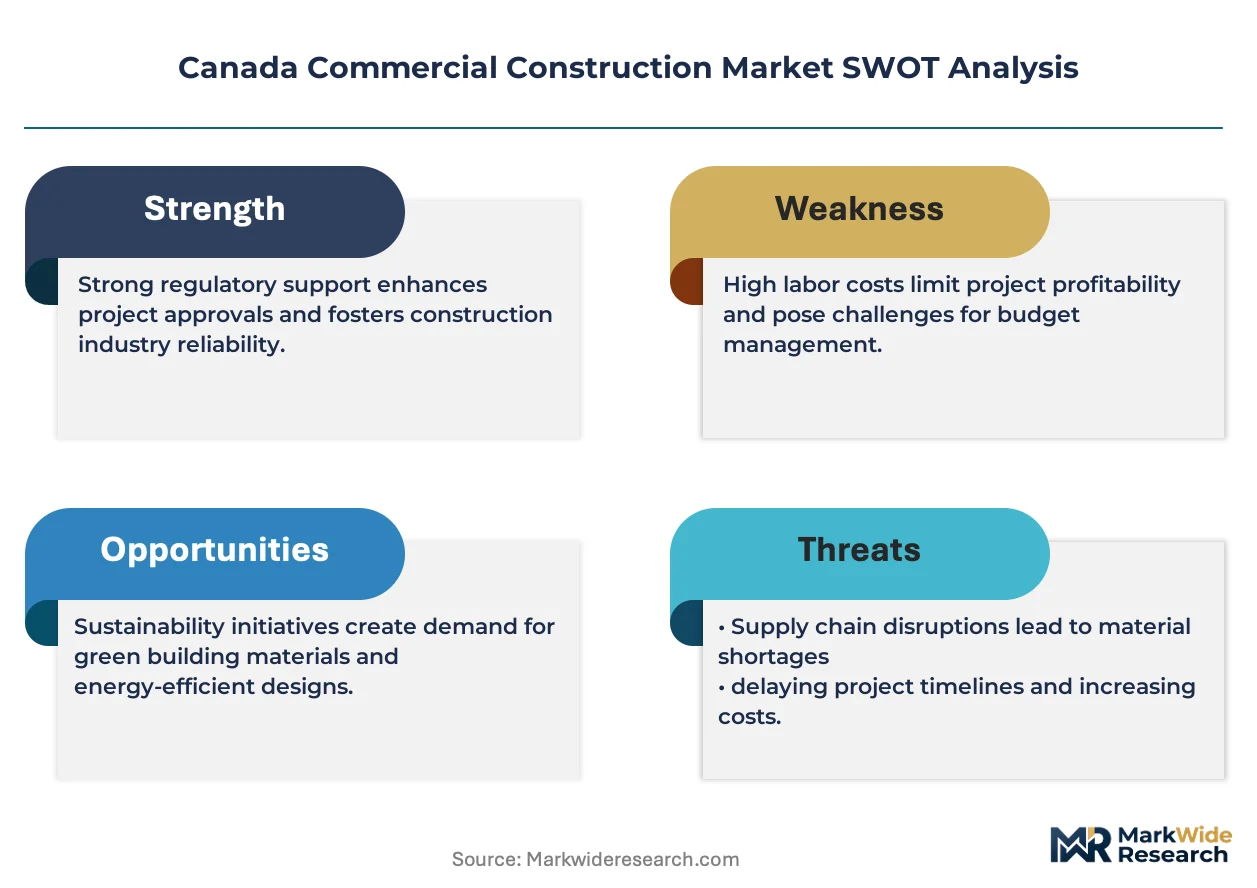
For Market Incumbents: Pre-empt margin erosion by securing captive mass timber fabrication capacity in British Columbia and Quebec before regional supply tightens. Anchor design-build procurement relationships with provincial health authorities through accelerated schedule guarantees. Certify envelope commissioning capabilities to capture bottleneck premiums. For New Entrants and Emerging Players: Build out Indigenous joint venture structures to access federal procurement set-asides in Saskatchewan and Manitoba. Target deep energy retrofit volume in Calgary and Edmonton office stock where incumbent presence thins. Lead with Canada Greener Homes financing navigation as the go-to-market wedge. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors envelope commissioning specialists and modular fabrication assets. Long-term viability hinges on regulatory compliance capabilities across stepped National Building Code energy tiers. Watch provincial adoption timelines for the next code cycle as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Mass Timber Fabrication Capacity Expansion | Captures code-enabled structural alternatives in Ontario and British Columbia institutional pipelines. |
| Envelope Commissioning Specialist Acquisition | Resolves certified specialist scarcity relative to Health Canada testing protocol mandates. |
| Indigenous Joint Venture Structuring | Unlocks federal procurement set-asides in Saskatchewan and Manitoba healthcare infrastructure. |
| Deep Energy Retrofit Service Line Buildout | Accesses underpenetrated Calgary and Edmonton office stock through Canada Greener Homes financing. |
| Modular-Permanent Hybrid Delivery Investment | Compresses healthcare and institutional schedules through Quebec factory-controlled production. |
Research Methodology
A standing panel of general contractor procurement directors, provincial health authority facility planners, mass timber fabricator operations managers, and pension fund real estate investment heads provided ongoing calibration. Primary interviews combined with secondary validation from National Research Council code development records, provincial building authority adoption timelines, and Canadian construction trade customs data. Bottom-up project pipeline aggregation and top-down capital flow analysis enabled triangulation across the analysis window.
Scenario-bracketing anchored projections across material cost volatility, regulatory adoption pace, and labor migration patterns. Segmentation dimensions modeled include project type, structural material system, delivery method, and client capital source. CAGRs derived from historical construction value flows and forward infrastructure commitment trajectories. Industry-specific inputs incorporated National Building Code tier adoption schedules and federal procurement mandate enforcement intensity.
Sensitivities concentrate around steel tariff regime shifts, provincial code adoption timeline divergence, and skilled trades migration patterns. Forecasts reflect documented assumptions regarding infrastructure commitment durability and institutional capital allocation preferences. Material shifts in federal procurement mandate scope or National Building Code energy tier stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
Road & Highway Infrastructure Market
Infrastructure Construction
Utility System Construction Market
Infrastructure Construction
Philippines Data Center Construction Market
Infrastructure Construction
China Infrastructure Market
Infrastructure Construction
Singapore Transportation Infrastructure Construction Market
Infrastructure Construction
North America Pipeline Maintenance Market
Infrastructure Construction
Global Rail Infrastructure Market
Infrastructure Construction
Netherlands Transportation Infrastructure Construction Market
Infrastructure Construction
Vietnam Infrastructure Market
Infrastructure Construction
Japan Transportation Infrastructure Construction Market
Infrastructure Construction
Denmark Data Center Construction Market
Infrastructure Construction
Cofferdam Market
Infrastructure Construction
Docks Market
Infrastructure Construction
APAC Data Center Construction Market
Infrastructure Construction
Thailand Data Center Construction Market
Infrastructure Construction
New Zealand Infrastructure Market